
 Brazil Agricultural Tractors Market | 2026-2036
Brazil Agricultural Tractors Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Agricultural Tractors Market Outlook
Aftermarket service revenue is rewriting profit structures across the Brazil Agricultural Tractors Market. John Deere Brasil Ltda leverages its dealer network density to capture recurring parts and maintenance income across the Cerrado belt. Mahindra & Mahindra Ltd anchors its position through cost-competitive utility tractor lines tailored to mid-size farms in Minas Gerais and São Paulo. AGCO do Brasil competes via localized assembly and brand diversification across Valtra and Massey Ferguson portfolios.
Agricultural tractors are self-propelled vehicles engineered primarily to deliver mechanical power for traction, typically rated by engine horsepower, drawbar pull capacity, and hydraulic flow rates measured in liters per minute. Their core industrial purpose centers on soil preparation, crop establishment, and field logistics across arable and plantation farming systems. 4WD tractors dominate volume and value given their necessity for heavy tillage and planter duty in Brazil's clay-rich Cerrado soils. Smart tractors represent the fastest-expanding technology segment as telematics and autosteer systems reduce input overlap and satisfy financier requirements for operational traceability. Compact tractors occupy a mature niche concentrated in horticulture zones near São Paulo and Paraná, where smaller landholdings limit horsepower requirements.
ANVISA oversees operator safety and emissions-related component standards, while INMETRO certification governs fuel efficiency labeling and engine performance claims for equipment sold domestically. Brazil's PROCONVE P-8 equivalent standards and state-level environmental licensing shape manufacturer product planning and import timing. Stakeholders must monitor the interplay between federal credit programs through Banco do Brasil and evolving RenovaBio compliance thresholds to anticipate fleet renewal timing and technology specification shifts.
Market Dynamics
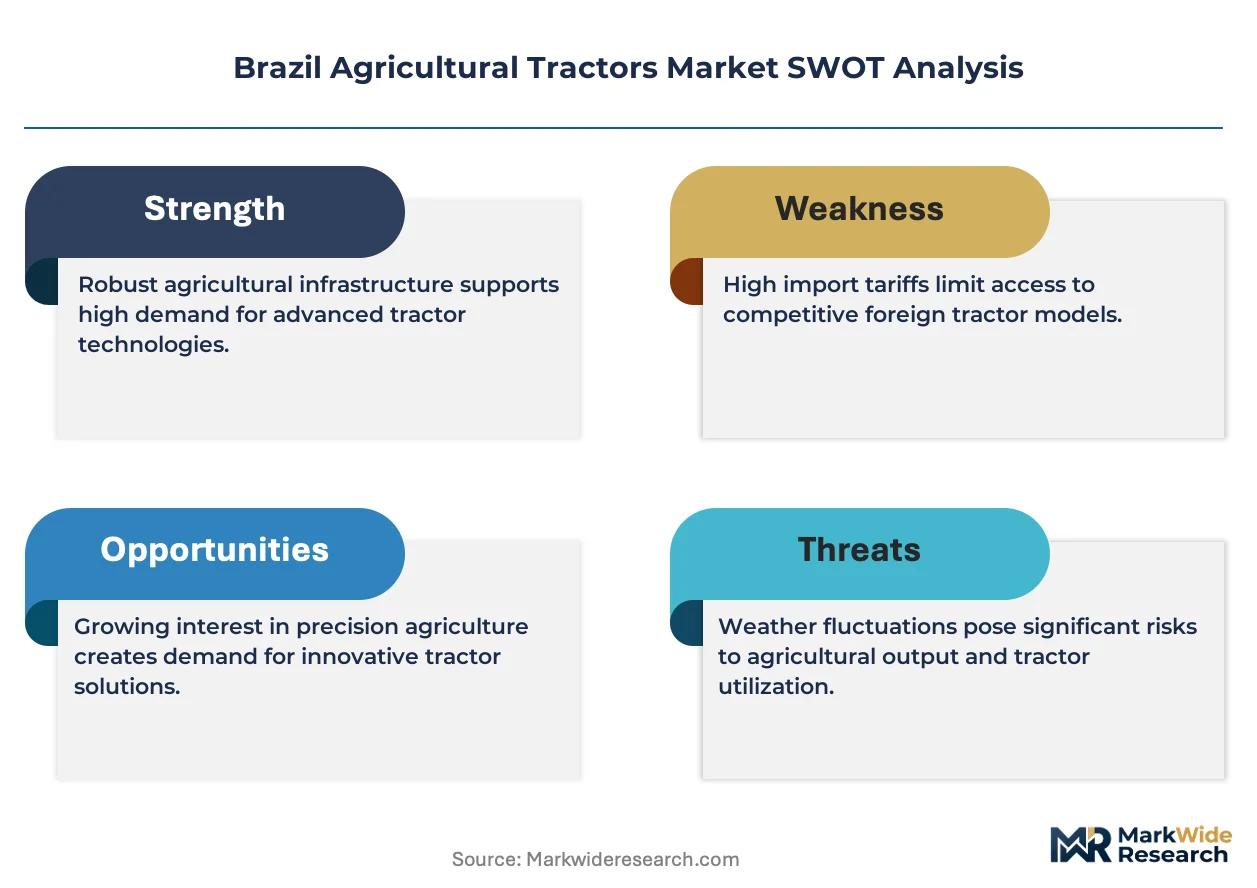
Precision agriculture telemetry and autosteer systems are compressing replacement cycles across Brazil's Center-West soybean belt, as financiers mandate operational traceability for credit access under federal agricultural lending programs.
Growth Catalysts
- RenovaBio compliance thresholds:Biofuel blending mandates under Brazil's national carbon reduction framework are accelerating fleet turnover toward higher-horsepower, emissions-optimized configurations in Mato Grosso corn-soy operations.
- Double-cropping intensity:Sequential soybean-corn planting windows in Goiás and Mato Grosso do Sul are forcing mechanized speed upgrades to complete tillage and planting within narrow seasonal windows.
- Telematics penetration:Real-time fuel monitoring and input-overlap reduction through GPS-guided autosteer is virtualizing fleet management decisions for 500+ hectare operations.
Market Restraints
- Import dependency for powertrain components:Domestic assembly relies on captive supply of Tier 4-compliant engines from North American and European suppliers, exposing margins to currency volatility and shipping congestion at Santos port.
- Credit access stratification:Banco do Brasil's FINAME rural credit lines favor established producers with collateralized land titles, excluding mid-tier operators in Paraná's fragmented dairy-horticulture transition zones.
- Soil compaction trade-offs:Heavier 4WD configurations required for Cerrado clay tillage accelerate subsoil degradation, triggering regulatory scrutiny from state environmental licensing boards in Tocantins expansion frontiers.
Strategic Opportunities
- Aftermarket service unbundling:Remote diagnostics and predictive maintenance contracts are creating recurring revenue streams independent of equipment sales cycles across dealer networks in Rondonia's emerging soybean districts.
- Utility tractor electrification:Battery-electric compact configurations for São Paulo's peri-urban vegetable cooperatives align with municipal air quality ordinances and noise restrictions in high-density horticulture zones.
- Second-hand export channels:Depreciated 150-200 HP units from Center-West consolidation are finding resale demand in Paraguay's Alto Paraná and Bolivia's Santa Cruz soybean frontiers.
Industry Challenges
- Precision agriculture technician scarcity:Telematics calibration and variable-rate application programming require skills absent from traditional mechanical training pipelines in rural technical schools.
- Legacy fleet integration friction:Retrofitting autosteer and yield monitoring to 2010-2015 model-year tractors demands proprietary adapter kits with limited backward compatibility.
- INMETRO certification timelines:Fuel efficiency labeling verification for imported engine variants creates 4-6 month product launch delays during critical pre-planting procurement windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Agricultural Tractors Market |
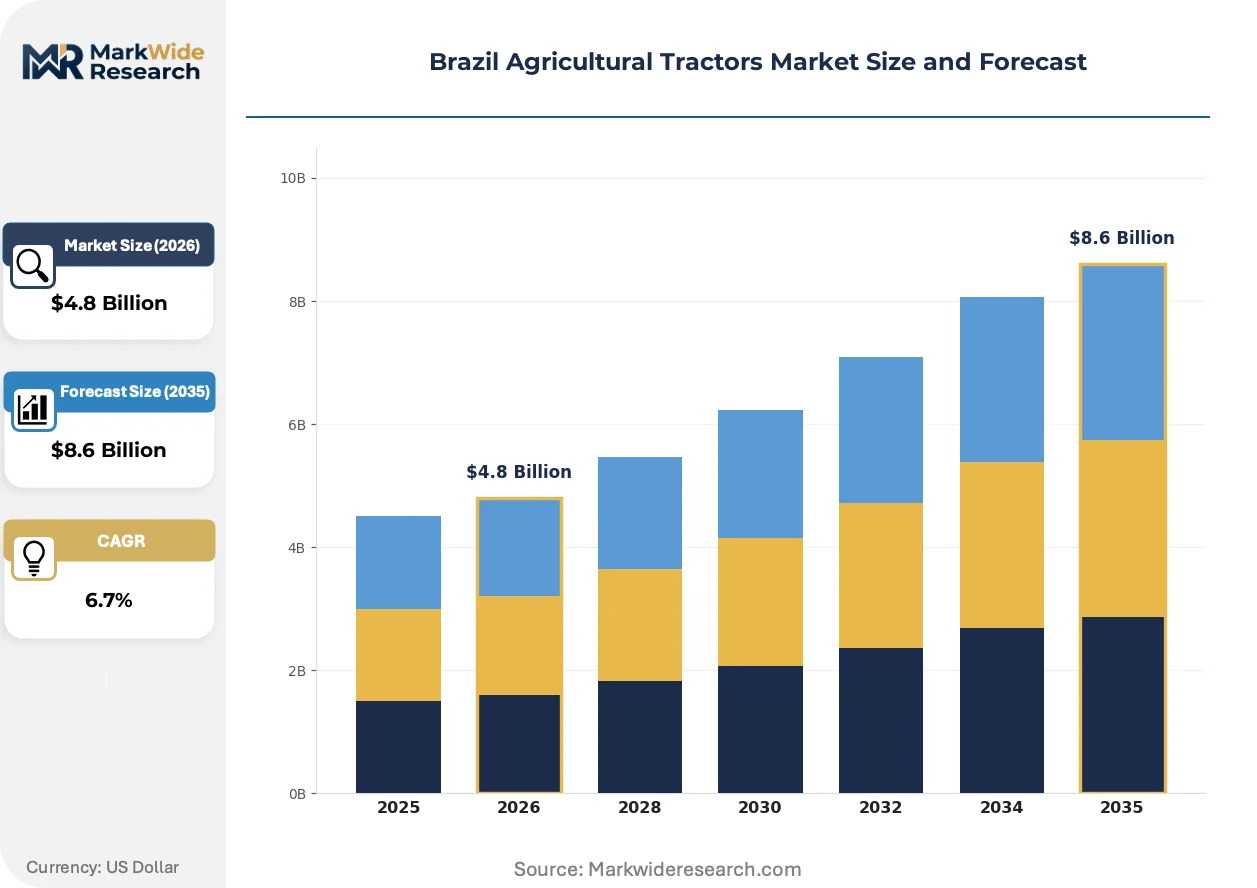
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 4WD Tractors, 2WD Tractors, Compact Tractors, Utility Tractors End User: Farmers, Agricultural Cooperatives, Contractors, Government Technology: Smart Tractors, Diesel Tractors, Electric Tractors, Hybrid Tractors Application: Tillage, Planting, Harvesting, Fertilization |
| Companies Covered | New Holland Agriculture, Mahindra & Mahindra Ltd, John Deere Brasil Ltda, Stara S/A, Tractors and Farm Equipment Limited, CNH Industrial Brasil Ltda, Kubota Agricultural Machinery, Valtra, AGCO do Brasil, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Agricultural Tractors Market Strategic Shifts
Digital agriculture platforms are collapsing the information asymmetry between equipment operators and financiers, reshaping how tractor specifications are validated and how residual value is calculated across Brazil's agricultural credit markets.
Telematics-enabled fleet management software is virtualizing operator supervision across dispersed landholdings. Large-scale producers in Mato Grosso are deploying centralized control rooms to monitor fuel consumption, engine diagnostics, and field coverage rates across 50+ unit fleets in real time. This compression of managerial oversight is reducing per-hectare labor costs while satisfying Banco do Brasil's documentation requirements for operational traceability.
ANVISA and INMETRO are tightening concurrent enforcement of operator safety standards and fuel efficiency claims under PROCONVE P-8 equivalent thresholds. Manufacturers must now submit consolidated emissions and performance data for entire product families rather than individual SKUs, extending pre-market certification timelines. The Center-West states, where fleet turnover concentrates, are experiencing the most pronounced compliance-driven specification shifts toward Tier 4 Final and Stage V equivalent engines.
Equipment-as-a-service contracting is displacing traditional ownership models among mid-scale operators in Minas Gerais dairy and coffee systems. Hourly-rate leasing with bundled maintenance and telemetry access reduces capital commitment while guaranteeing uptime during critical harvest windows. This procurement evolution is most visible in São Paulo's sugarcane renovation cycles, where mills prefer operational expenditure treatment for seasonal tractor deployments over balance-sheet asset accumulation.
Brazil Agricultural Tractors Market Segmentation
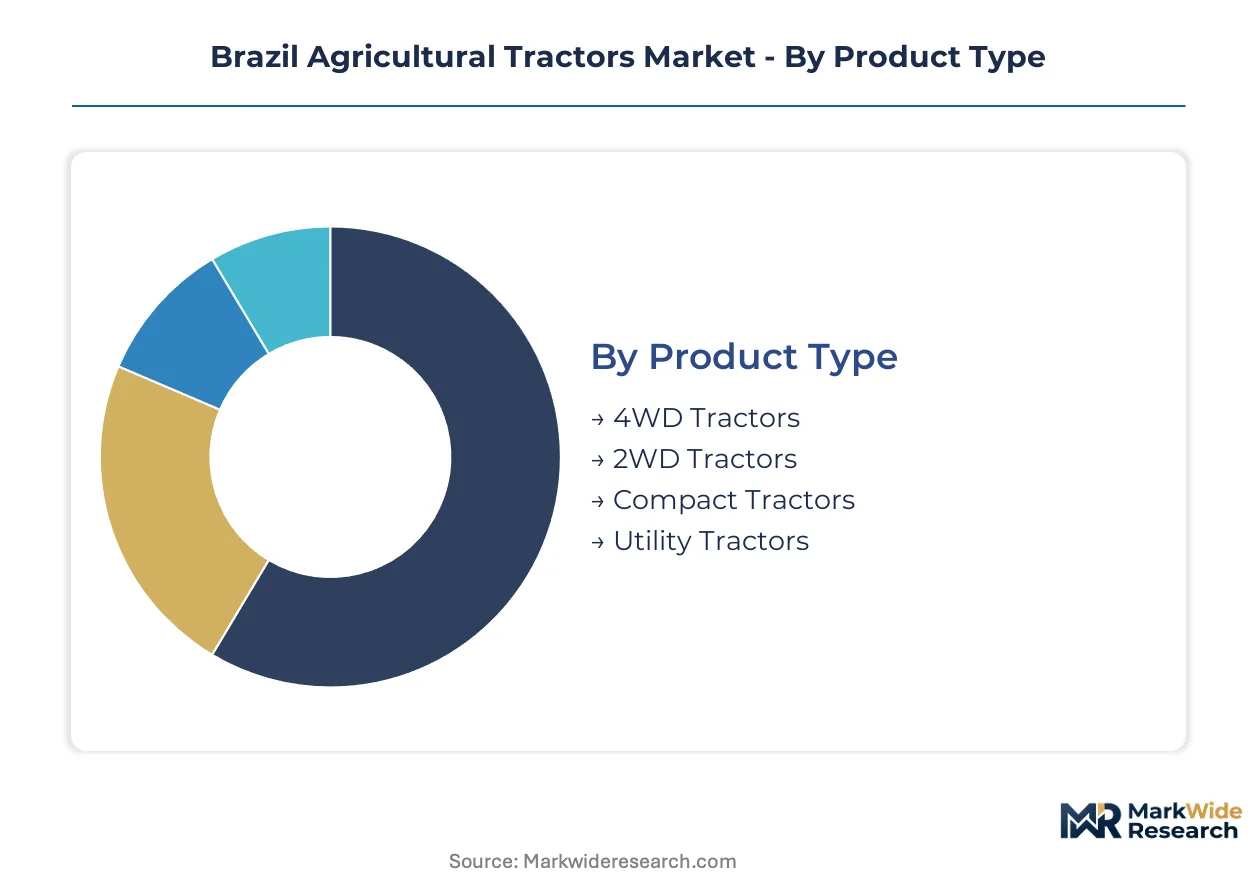
Equipment specification choices in Brazil's agricultural tractor market directly determine aftermarket service revenue potential and dealer network profitability. Segmentation reveals how horsepower ratings, technology integration levels, and end-user scale reshape procurement patterns across the Cerrado belt and southern farming systems.
Product Type:
After-sales service intensity varies dramatically by drivetrain configuration, with 4WD platforms generating three to five times the parts revenue over their lifecycle compared to compact alternatives due to hydraulic complexity and tillage stress loads.
- 4WD Tractors:Articulated-frame or rigid-frame designs with power delivery to all four wheels, typically rated above 150 HP for heavy primary tillage and planter duty. Demand clusters in Mato Grosso's soybean-corn double-cropping operations where clay-rich Cerrado soils mandate maximum traction and ballast weight. ANVISA safety certifications and INMETRO fuel efficiency labeling apply most stringently to this high-volume category.
- 2WD Tractors:Rear-wheel-drive configurations optimized for lighter tillage and transport tasks on established farms with improved soil structure. Mature demand in Paraná's dairy-horticulture transition zones and São Paulo's sugarcane renovation cycles where capital constraints favor lower acquisition cost over traction performance.
- Compact Tractors:Sub-50 HP machines with three-point hitch and PTO for specialty crop operations. Peri-urban vegetable cooperatives near Campinas and Curitiba deploy these for precision bed preparation in high-density horticulture.
- Utility Tractors:Mid-range 50-100 HP platforms bridging field and yard duty. Minas Gerais coffee and dairy systems favor this segment for equipment fleet flexibility across seasonal task variations.
By volume, 4WD Tractors leads. By growth pace, Compact Tractors is ahead.
End User:
Customer scale dictates financing access through Banco do Brasil's FINAME rural credit lines and determines telemetry adoption thresholds.
- Farmers:Individual owner-operators managing landholdings from 50 to 5,000 hectares. Center-West soybean producers above 500 hectares drive replacement cycles for precision agriculture-enabled fleets.
- Agricultural Cooperatives:Member-owned entities pooling equipment across multiple farms. Rio Grande do Sul's grain cooperatives concentrate demand for high-hour utilization machines with shared maintenance contracts.
- Contractors:Third-party service providers offering tillage, planting, or harvesting on fee-per-hectare terms. Goiás and Mato Grosso do Sul host expanding contractor fleets serving absentee landowners.
- Government:Federal and state procurement for research stations, settlement projects, and extension services. EMBRAPA research units and PRONAF settlement programs specify domestic assembly requirements.
Equipment-as-a-service contracting is reshaping how Contractors acquire fleet capacity while Farmers retain ownership concentration in high-horsepower categories.
Technology:
Telematics penetration rates diverge sharply by power class and end-user sophistication, with financier traceability requirements accelerating specification shifts.
- Smart Tractors:GPS-guided autosteer, real-time fuel monitoring, and ISOBUS-compatible implement control. Large-scale Mato Grosso operations deploy centralized control rooms to manage 50+ unit fleets remotely.
- Diesel Tractors:Conventional mechanical-hydraulic platforms with Tier 3 or Tier 4 Final emissions compliance. Dominates replacement demand in credit-constrained segments across Paraná and Rio Grande do Sul.
- Electric Tractors:Battery-electric powertrains for zero-emission operation. São Paulo municipal air quality ordinances drive pilot deployments in peri-urban vegetable production.
- Hybrid Tractors:Diesel-electric architectures optimizing fuel consumption across variable load cycles. Emerging specification for sugarcane loader applications in São Paulo's renovation zones.
Smart Tractors commands the steepest expansion trajectory as RenovaBio compliance and operational traceability harden into credit prerequisites.
Application:
Task-specific duty cycles determine hydraulic flow requirements, ballast configurations, and seasonal utilization rates that feed into residual value calculations.
- Tillage:Primary and secondary soil preparation requiring maximum drawbar pull and implement lift capacity. Heavy disc and subsoiler duty in Tocantins expansion frontiers drives 4WD specification.
- Planting:Precision seed and fertilizer placement with GPS guidance and variable-rate control. Double-cropping intensity in Goiás compresses planting windows and demands high-speed planter compatibility.
- Harvesting:Support logistics including grain cart operation and field transport. Secondary tractor deployment during soybean and corn harvest peaks in Mato Grosso.
- Fertilization:Solid and liquid nutrient application with boom or pneumatic spreader integration. Lime incorporation in Brazil's acid soil correction programs sustains steady demand.
Tillage absorbs the largest equipment investment per hectare, while Planting shows the fastest technology upgrade cycles as precision agriculture specifications advance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Assembly plants cluster in São Paulo and Rio Grande do Sul, with component sourcing stretching through Paraná's metalworking corridor. This supply-side geography shapes regional demand patterns and dealer network density across Brazil's agricultural heartland.
São Paulo
Sugarcane renovation cycles and peri-urban vegetable cooperatives sustain demand for mid-range utility configurations. Municipal air quality ordinances in Campinas and surrounding metros accelerate interest in battery-electric compact platforms for high-density horticulture zones.
Minas Gerais
Coffee and dairy systems favor flexible 50-100 HP utility tractors across seasonal task variations. Equipment-as-a-service contracting is displacing traditional ownership among mid-scale operators, with hourly-rate leasing reducing capital commitment during critical harvest windows.
Mato Grosso
Soybean-corn double-cropping operations drive replacement cycles for precision agriculture-enabled fleets above 500 hectares. FINAME rural credit access concentrates here, with Banco do Brasil traceability requirements mandating telemetry integration for fleet renewal approvals.
Goiás
Sequential planting windows compress mechanized speed requirements to complete tillage within narrow seasonal thresholds. Expanding contractor fleets serve absentee landowners, creating demand for high-hour utilization machines with shared maintenance contracts.
Rio Grande do Sul
Grain cooperatives pool equipment across multiple farms, concentrating demand for standardized platforms with centralized parts inventories. Legacy fleet integration challenges emerge as cooperatives retrofit autosteer systems to 2010-2015 model-year tractors.
Brazil Agricultural Tractors Market Competitive Environment
Full-line manufacturers and specialized regional assemblers split the market across distinct capability tiers. The vendor base organizes around three strategic archetypes: integrated global equipment systems houses, emerging-market cost leaders, and domestic-focused utility specialists. Consolidation pressure intensifies as telematics standardization raises R&D minimums, while portfolio diversification into precision agriculture software creates defensive moats against pure-play hardware competitors.
Within the integrated systems tier, John Deere Brasil Ltda and AGCO do Brasil anchor positions through dealer network density and aftermarket service unbundling. Mahindra & Mahindra Ltd occupies a distinct cost-leadership vector targeting mid-size farm segments. These three exemplify how geographic origin and corporate structure shape competitive positioning: the Brazilian subsidiaries of North American parents leverage localized assembly, while the Indian multinational exploits scale economies in utility configurations.
| Leading Market Players |
|---|
| New Holland Agriculture |
| Mahindra & Mahindra Ltd |
| John Deere Brasil Ltda |
| Stara S/A |
| Tractors and Farm Equipment Limited |
| CNH Industrial Brasil Ltda |
| Kubota Agricultural Machinery |
| Valtra |
| AGCO do Brasil |
| Others |
Value Chain & Pricing Dynamics
Captive supply of Tier 4-compliant engines from North American and European Tier 1 suppliers concentrates upstream margin capture, while Brazilian assemblers compete downstream through localized kitting and dealer network density across the Cerrado belt. This structural asymmetry funnels pricing power toward powertrain importers and squeezes assembly margins during currency volatility episodes.
Pricing Analysis
INMETRO fuel efficiency labeling dictates the pricing tier structure across premium telemetry-enabled configurations, standard mechanical-hydraulic platforms, and economy 2WD alternatives. Price differentiation hinges on PROCONVE P-8 equivalent certification grade and after-sales service bundling intensity. Cost compression in the standard tier is intensifying because credit-constrained mid-size operators in Paraná defer replacement cycles. Farmers above 500 hectares show lowest price sensitivity due to FINAME rural credit access, while peri-urban horticulture cooperatives exhibit acute cost consciousness.
Supply Chain Analysis
Steel castings and precision-machined transmission housings feed from foundry clusters in Germany, the United States, and Japan. Domestic assembly draws from these inputs alongside hydraulic pumps from Italy and electronic control modules from Taiwan. Single-source vulnerability concentrates in Tier 4 Final engine supply from two North American parents. Distribution runs through captive dealer networks anchored in Mato Grosso and São Paulo, with parts inventories staged at regional hubs to compress field repair timelines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Telematics standardization and RenovaBio compliance thresholds are compressing technology refresh cycles, creating a high-growth disruption window for precision agriculture equipment. The regulatory inflection toward operational traceability as a credit prerequisite is restructuring procurement authority away from traditional owner-operators toward financier-specified configurations.
For Market Incumbents: Pre-empt margin erosion in the utility tractor segment by deepening captive supply of electronic control modules through backward integration into Tier 2 component sourcing. Lock in dealer exclusivity clauses for telemetry calibration services to defend against emerging equipment-as-a-service entrants. The threat of hourly-rate leasing models from contractor fleets demands accelerated predictive maintenance platform deployment.
For New Entrants and Emerging Players: Rondonia's emerging soybean districts present underpenetrated terrain for aftermarket service unbundling, with dealer network gaps exceeding 200 kilometers in frontier municipalities. Battery-electric compact configurations for São Paulo peri-urban zones offer a regulatory-aligned entry vector with lower capital intensity than full-line competition. A cooperative-partnership go-to-market model bypasses FINAME collateral requirements through pooled procurement structures.
For Investors and Strategic Acquirers: Capital is best deployed toward precision agriculture software specialists with ISOBUS-compatible platform architectures and recurring telemetry revenue streams. Long-term viability across the analysis window favors asset-light service unbundling over manufacturing scale. The signal to watch is Banco do Brasil's traceability mandate expansion beyond the Center-West into Paraná and Rio Grande do Sul, which would accelerate specification shifts and consolidate procurement authority.
| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Platform Integration | ISOBUS-compatible systems satisfy Banco do Brasil traceability requirements for FINAME credit access. |
| Aftermarket Service Unbundling | Predictive maintenance contracts generate recurring revenue independent of equipment sales cycles. |
| Localized Assembly Expansion | Domestic kitting compresses INMETRO certification timelines and reduces currency exposure. |
| Battery-Electric Compact Development | Zero-emission configurations align with São Paulo municipal air quality ordinances. |
| Dealer Network Density Investment | Parts inventory staging in Mato Grosso and Goiás reduces field repair response times. |
Study Parameters
A standing panel of agricultural equipment procurement managers, precision agriculture technicians, dealer network operators, and Banco do Brasil rural credit officers provided ongoing calibration throughout the study. Primary interviews combined with secondary validation against ANVISA regulatory filings, INMETRO certification databases, EMBRAPA machinery utilization surveys, and FINAME disbursement records. Bottom-up unit shipment modeling triangulated against top-down agricultural GDP and mechanization intensity benchmarks.
Scenario bracketing anchored the analytical framework across conservative, baseline, and expansion trajectories over the projection horizon. Segmentation dimensions modeled include drivetrain configuration, horsepower tier, technology integration level, end-user scale, and regional credit access intensity. CAGRs derived from fitted growth curves applied to replacement cycle timing and fleet expansion patterns. Industry-specific forecast inputs incorporated RenovaBio compliance threshold evolution and telemetry penetration assumptions by farm size class.
The forecast holds incumbent behavior within observed patterns; aggressive moves by battery-electric specialists or precision agriculture software entrants would shift outcomes beyond modeled ranges. Specific risk factors include PROCONVE P-8 equivalent standard acceleration, Santos port logistics disruption, and credit program eligibility restriction. Cross-checking against EMBRAPA agricultural machinery census data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Machinery
Mexico Agricultural Machinery Market
Agricultural Machinery
United States Agricultural Tractor Market
Agricultural Machinery
Asia-Pacific Utility Tractor Market
Agricultural Machinery
Global Tractor Market
Agricultural Machinery
Asia-Pacific Agricultural Tractors Market
Agricultural Machinery
Sickle Bar Mower Market
Agricultural Machinery
Two Wheel Walking Tractor Market
Agricultural Machinery
Garden and Orchard Tractors Market
Agricultural Machinery
Electric Farm Tractor Market
Agricultural Machinery
Europe Utility Tractor Market
Agricultural Machinery
Vietnam Combine Harvester Market
Agricultural Machinery
Global Autopilot Agricultural Vehicle Market
Agricultural Machinery
Turkey Agricultural Tractor Market
Agricultural Machinery
Agricultural Forestry Machinery Market
Agricultural Machinery
Two-Wheeler Tractors Market
Agricultural Machinery
Agricultural Electric Tractor Market