
 Italy Agricultural Machinery Market | 2026-2036
Italy Agricultural Machinery Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Agricultural Machinery Market Foresight
Italian tractor manufacturing capacity is shifting toward higher-horsepower segments and precision-ready platforms. CNH Industrial leverages its Raven precision technology division to anchor premium positioning in autonomous-ready equipment. Deere & Company sustains brand loyalty through its extensive dealer network across northern Italy's machinery belts. Argo Tractors specializes in compact and specialized tractors suited to the country's fragmented hillside vineyards and orchards.
Agricultural machinery encompasses powered and towed equipment engineered for soil preparation, planting, cultivation, harvesting, and post-harvest processing, with power ratings ranging from sub-20 hp vineyard units to 400+ hp arable tractors. Tractors occupy the dominant revenue position given their universal deployment across all farm scales and crop types. Precision Farming technology within the equipment segment attracts disproportionate investment as Italian cooperatives seek yield optimization and input cost control. Combine Harvesters represent a mature replacement-driven category where margin pools concentrate in aftermarket parts and service contracts rather than initial unit sales.
Italy's Ministry of Agriculture (MIPAAF) administers PNRR subsidies tied to digital and green transition benchmarks, while BIS certification requirements govern machinery safety standards for domestic sale and export eligibility. EU F-Gas Regulation and Stage V emission standards from the European Commission constrain engine architecture choices and filter technology costs for manufacturers serving Italian buyers. Stakeholders must monitor how subsidy disbursement timelines and evolving emission thresholds reshape equipment replacement cycles and supplier R&D allocation.
Market Dynamics
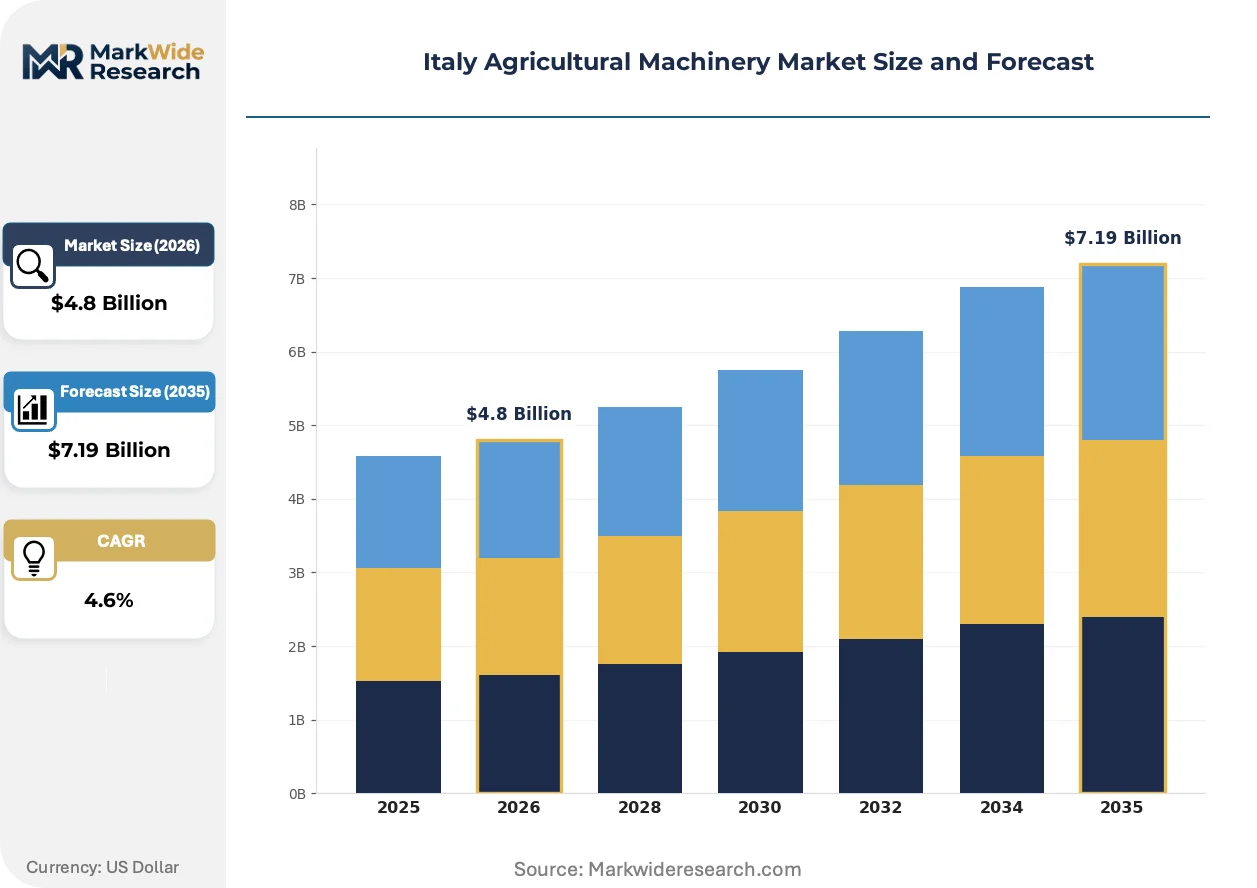
Italy's agricultural machinery sector is being restructured by the National Recovery and Resilience Plan's precision agriculture subsidies, which are compressing replacement cycles and forcing manufacturers to reconfigure product portfolios toward telemetry-ready platforms before 2026 disbursement deadlines.
Growth Catalysts
- PNRR digital transition subsidies:MIPAAF's benchmark-tied disbursements accelerate cooperative fleet upgrades in Emilia-Romagna and Lombardy.
- Specialty crop mechanization:Po Valley viticulture and orchard operators invest in narrow-track tractors and sensor-integrated harvesters.
- Stage V compliance pre-buying:Anticipatory purchasing ahead of stricter EU emission thresholds pulls forward equipment demand in northern machinery belts.
Market Restraints
- Steel and semiconductor input volatility:Filter technology and engine component costs fluctuate with raw material availability, squeezing margin pools on sub-100 hp tractors.
- Dealer network concentration:Northern Italy's machinery distribution clusters around Bologna and Verona, creating geographic supply vulnerability for southern growers.
- F-Gas refrigeration constraints:EU F-Gas Regulation limits climate-control options for cab-equipped tractors, complicating operator comfort specifications in Mediterranean heat zones.
Strategic Opportunities
- Sicilian and Apulian underpenetration:Southern Italy's fragmented smallholdings remain below national mechanization averages, presenting compact equipment demand.
- Autonomous-ready platform leasing:Raven and Trimble telemetry integration enables subscription-based precision farming access for capital-constrained cooperatives.
- BIS certification arbitrage:Dual domestic-export safety compliance positions Italian manufacturers for North African and Balkan market entry.
Industry Challenges
- Telemetry technician scarcity:Dealer service departments lack sufficient ISOBUS and CAN bus diagnostic capability to support precision agriculture rollouts.
- Legacy fleet interoperability:Retrofitting 1990s-era tractors with GPS guidance and variable-rate controllers creates firmware compatibility failures.
- Subsidy disbursement timeline compression:MIPAAF's accelerated PNRR spending deadlines strain manufacturer order-to-delivery capacity during peak agricultural windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Agricultural Machinery Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tractors, Combine Harvesters, Plows, Seeders End User: Commercial Farms, Cooperatives, Government Agencies, Research Institutions Distribution Channel: Direct Sales, Retail Stores, Online Platforms, Auctions Technology: Precision Farming, GPS Guidance, Autonomous Equipment, IoT Integration |
| Companies Covered | Deere & Company, Argo Tractors, CNH Industrial, Maschio Gaspardo, CLAAS KGaA mbH, SDF Group, Antonio Carraro, BCS S.p.A., AGCO Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Agricultural Machinery Market Shifts & Advancements
Italian agricultural equipment is undergoing a platform shift where mechanical reliability becomes table stakes and data infrastructure determines vendor selection. Three forces are restructuring competitive positioning.
ISOBUS universal protocol implementation is converging with cloud-based farm management software to create seamless implement-to-tractor communication. Emilia-Romagna's large-scale cooperatives are adopting these integrated stacks fastest, consolidating their procurement around vendors offering end-to-end telemetry rather than standalone hardware. This convergence is compressing margins for equipment-only suppliers while expanding recurring revenue pools for software-anchored manufacturers.
EU Stage V emission standards from the European Commission are forcing engine architecture redesigns across the 75-200 hp tractor segment. Manufacturers serving Italian buyers must integrate diesel particulate filters and selective catalytic reduction systems, adding cost and maintenance complexity. The regulation hits compact vineyard tractors hardest, where engine compartment space constraints limit aftertreatment packaging options.
Service contract unbundling is disrupting traditional dealer revenue models in northern Italy's machinery belts. Buyers in Lombardy and Veneto increasingly separate equipment purchase from maintenance agreements, sourcing aftermarket parts through independent channels. This pattern is most visible among large arable cooperatives with in-house mechanical capability, who treat dealer networks as parts depots rather than full-service partners.
Italy Agricultural Machinery Market Segmentation
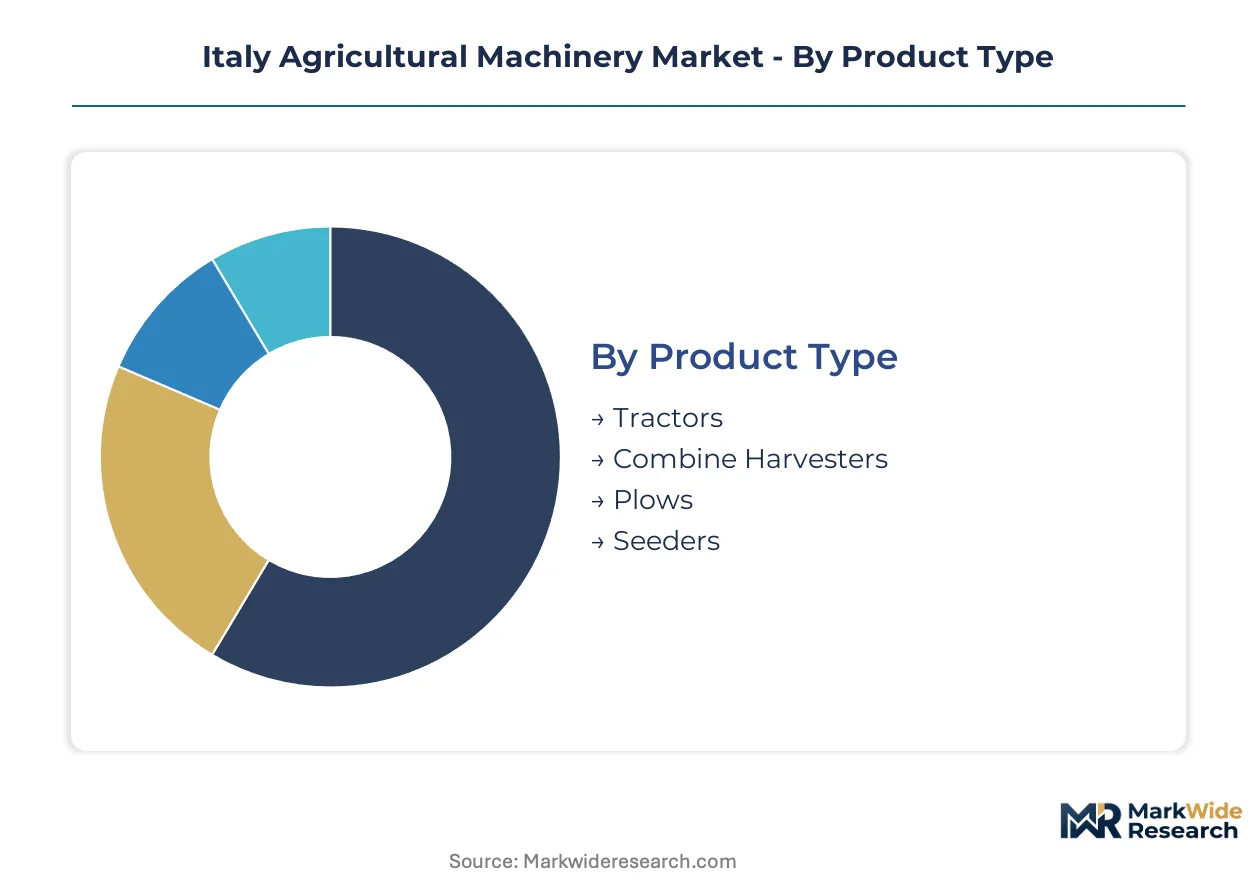
Italy's agricultural machinery segmentation reflects divergent certification burdens across product categories. MIPAAF subsidy eligibility and BIS safety standards create distinct compliance thresholds that reshape procurement patterns among Po Valley cooperatives and southern smallholders.
Product Type:
Certification intensity varies sharply across equipment categories. Tractors and combine harvesters face BIS machinery safety mandates plus Stage V emission compliance, while implements navigate lighter regulatory frameworks.
- Tractors:Power platforms ranging from sub-20 hp vineyard units to 400+ hp arable machines. Demand clusters around Emilia-Romagna's cooperative sector, where telemetry-ready specifications unlock PNRR digital transition subsidies. Stage V aftertreatment requirements compress margin pools on compact models.
- Combine Harvesters:Self-propelled grain and specialty crop harvesting systems with integrated threshing and cleaning mechanisms. Replacement cycles in Lombardy and Veneto concentrate around aftermarket service contracts rather than initial unit sales, as large arable operators extend machine lifespans through component refurbishment.
- Plows:Soil inversion implements ranging from mounted reversible units to semi-mounted deep tillage systems. Argo Tractors and CNH Industrial dominate supply to Apulian wheat producers seeking F-Gas-compliant cab integration.
- Seeders:Mechanical and pneumatic planting equipment for cereals, oilseeds, and specialty crops. Narrow-track configurations serve Sicilian citrus and olive operators with fragmented hillside holdings.
Leading the category by volume: Tractors. Growing fastest: Precision-ready tractor platforms.
End User:
Procurement scale determines technology access tiers. Large-scale operators command volume discounts and dedicated service agreements unavailable to fragmented southern smallholders.
- Commercial Farms:Privately held arable and specialty crop operations exceeding 200 hectares. Northern Italian belt operations from Bologna to Verona drive demand for autonomous-ready platforms with Raven and Trimble telemetry integration.
- Cooperatives:Federated farming enterprises consolidating equipment procurement across member holdings. Emilia-Romagna's cooperative sector anchors national precision agriculture adoption rates through PNRR-subsidized fleet upgrades.
- Government Agencies:State and regional agricultural extension services managing demonstration fleets and rental pools. MIPAAF-directed machinery procurement prioritizes ISOBUS-compatible equipment for training and subsidy program administration.
- Research Institutions:University and CNR-affiliated agricultural experiment stations. Field robotics testing at Bologna and Milan campuses shapes pre-commercial validation protocols for autonomous equipment.
Cooperatives dominate absolute equipment expenditure. Commercial farms are expanding most quickly into subscription-based precision farming access.
Distribution Channel:
Channel selection reflects buyer technical sophistication and capital constraints. Direct manufacturer relationships favor large fleets, while fragmented southern demand routes through auction and independent retail.
- Direct Sales:Manufacturer-to-fleet transactions bypassing dealer networks. CNH Industrial and Deere & Company deploy direct account teams for Emilia-Romagna cooperative procurement exceeding 50-unit annual volumes.
- Retail Stores:Authorized dealer showrooms with service bay integration. Bologna and Verona machinery belt concentration creates geographic supply vulnerability for Calabrian and Sicilian growers.
- Online Platforms:Digital equipment marketplaces and manufacturer configurator portals. Younger cooperative managers in Lombardy leverage online specification tools before negotiating direct purchase terms.
- Auctions:Secondary market clearing for legacy fleet disposal. Southern Italian smallholders source 1990s-era tractors through regional auction houses, creating retrofit compatibility challenges for GPS guidance installation.
Retail stores capture the largest transaction count. Online platforms are gaining share fastest among digitally native procurement officers.
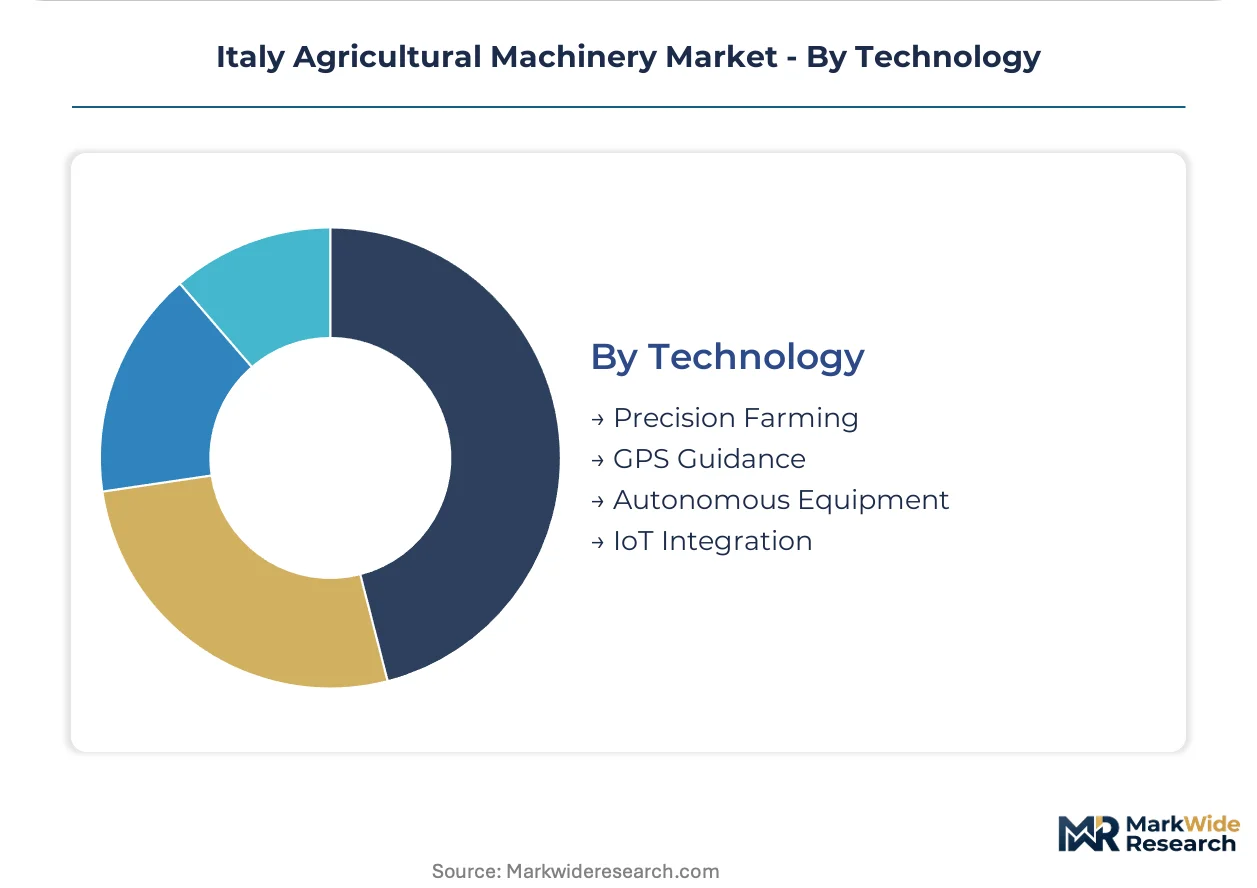
Technology:
Technology tier determines subsidy eligibility and residual value. PNRR disbursement deadlines accelerate cooperative migration toward telemetry-integrated platforms.
- Precision Farming:Variable-rate input application and yield mapping systems. Po Valley viticulture operators invest in sensor-integrated harvesters for real-time quality sorting and input cost control.
- GPS Guidance:Satellite-based steering assistance with sub-inch accuracy. Retrofit installations on legacy tractors face firmware interoperability failures, constraining adoption among auction-dependent southern smallholders.
- Autonomous Equipment:Operator-less tractors and implements with obstacle detection and path planning. Raven division integration anchors CNH Industrial premium positioning in pre-commercial trials across Veneto arable operations.
- IoT Integration:Machine-to-cloud telemetry for predictive maintenance and fleet optimization. Dealer service departments lack sufficient ISOBUS and CAN bus diagnostic capability to support rollout timelines.
Precision Farming leads technology expenditure. Autonomous Equipment is climbing the fastest, though from a smaller installed base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Steel from Taranto's Ilva complex and precision components from Milan's manufacturing corridor anchor Italian agricultural machinery production. Emilia-Romagna's cooperative farming belt concentrates demand for telemetry-integrated tractors. Southern smallholders in Sicily and Apulia remain below national mechanization averages.
Emilia-Romagna
Large-scale cooperative farming drives precision agriculture adoption across Bologna and Modena provinces. MIPAAF's PNRR digital transition subsidies accelerate fleet upgrades exceeding 50-unit annual volumes. Raven-equipped platforms from CNH Industrial dominate procurement at Federazione Italiana Consorzi Agrari consolidation points.
Lombardy
Arable operations in the Po Valley flatlands generate replacement demand for 200+ hp tractors with Stage V aftertreatment. BIS certification requirements govern machinery safety standards for domestic sale and export eligibility to North African markets. Bergamo and Brescia machinery clusters host Deere & Company direct account teams.
Veneto
Viticulture mechanization investments concentrate in Verona and Treviso hillside vineyards requiring narrow-track configurations. EU F-Gas Regulation constrains climate-control specifications for cab-equipped tractors in Mediterranean heat zones. Trimble telemetry integration trials proceed at Veneto Agricoltura demonstration farms.
Piedmont
Specialty crop producers in Turin's hinterland expand sensor-integrated harvester procurement for real-time quality sorting. Stage V emission standards from the European Commission force diesel particulate filter integration across the 75-150 hp segment. Cuneo and Asti dealer networks face telemetry technician scarcity for ISOBUS diagnostic support.
Sicily
Fragmented citrus and olive smallholdings below national mechanization averages present compact equipment demand. Auction-dependent procurement of 1990s-era tractors creates GPS guidance retrofit compatibility failures. Catania and Palermo independent retailers source narrow-track seeders for hillside cultivation.
Italy Agricultural Machinery Market Competitive Landscape
Global majors compete with regional champions across precision technology integration and cooperative procurement relationships. The vendor base stratifies into three tiers: multinational full-line suppliers with telemetry divisions, Italian-headquartered specialists in compact vineyard equipment, and component-focused implement manufacturers. Two dominant competitive moves reshape positioning: autonomous-ready platform leasing subscriptions and BIS certification arbitrage for North African export access.
Within the precision-technology tier, Deere & Company and CNH Industrial occupy positions as telemetry-anchored full-line suppliers. Argo Tractors exemplifies the Italian specialist archetype focused on compact configurations. Maschio Gaspardo represents the implement-manufacturer segment concentrating on soil preparation and seeding equipment.
| Leading Market Players |
|---|
| Deere & Company |
| Argo Tractors |
| CNH Industrial |
| Maschio Gaspardo |
| CLAAS KGaA mbH |
| SDF Group |
| Antonio Carraro |
| BCS S.p.A. |
| AGCO Corporation |
| Others |
Supply & Pricing Matrix
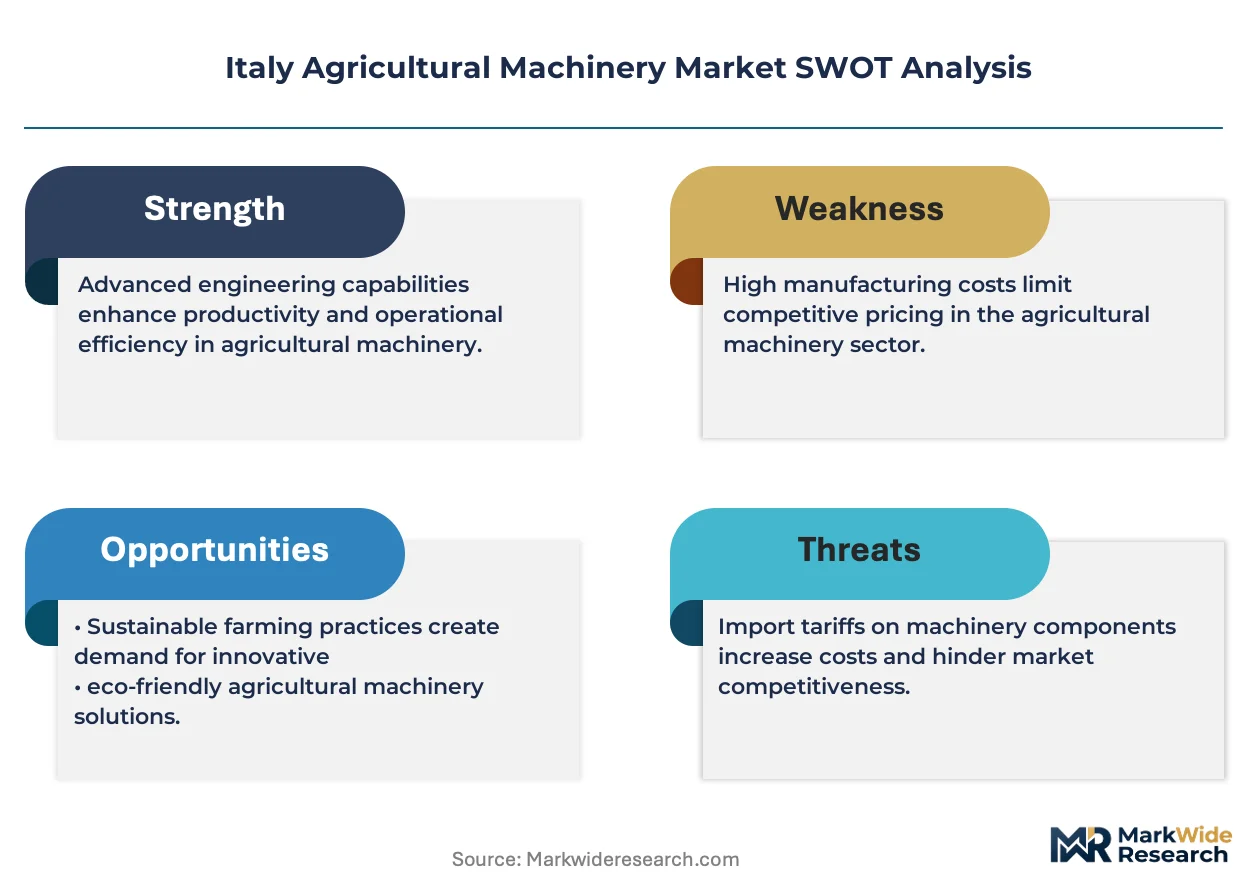
Captive integration of Stage V aftertreatment systems by CNH Industrial and Deere & Company anchors premium pricing power across northern Italy's machinery belts, while outsourced filter technology procurement squeezes margin pools for compact tractor specialists serving southern smallholders.
Pricing Analysis
Warranty and service-bundling unbundling distinguishes northern cooperative procurement from southern auction-dependent buying. Three-tier pricing structure across premium, standard, and economy levels separates telemetry-integrated platforms with Raven division technology from ISOBUS-ready mid-tier units and legacy mechanical configurations. Price differentiation hinges on PNRR subsidy eligibility and Stage V certification tier. Cost compression in sub-100 hp segments is intensifying because semiconductor and steel input volatility feeds into filter technology costs. Southern Sicilian and Apulian smallholders exhibit highest price sensitivity, while Emilia-Romagna cooperatives prioritize total cost of ownership over upfront unit economics.
Supply Chain Analysis
Dual-sourcing mandates from MIPAAF-directed procurement programs require manufacturers to qualify multiple Tier 1 suppliers for diesel particulate filters and selective catalytic reduction systems. Geographic supply concentration centers on Germany, Poland, and Czech Republic for engine aftertreatment components, with steel inputs drawing from Taranto's Ilva complex and Milan's precision manufacturing corridor. Raw material dependencies rest on high-grade steel, semiconductor chips for telemetry modules, and platinum-group metals for catalytic converters. Single-source vulnerability in Raven and Trimble telemetry integration creates bottleneck risk for autonomous-ready platform rollouts. Distribution runs through Bologna and Verona machinery belt dealer networks with service bay integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Italy's agricultural machinery sector functions as a cost-of-compliance arena where EU Stage V emission standards and BIS safety certification erect durable barriers against non-compliant entrants, entrenching established players with certified product portfolios.
For Market Incumbents: Cement telemetry technician training partnerships with Bologna and Milan technical institutes to close ISOBUS diagnostic capability gaps threatening precision agriculture rollout timelines. Deepen backward integration into filter technology production to capture margin pools currently leaking to outsourced aftertreatment suppliers. Defensive positioning requires preemptive certification of next-tier emission architectures before European Commission threshold adjustments. For New Entrants and Emerging Players: The mid-tier price-point gap between Raven-equipped premium platforms and economy mechanical tractors opens white-space entry for ISOBUS-compatible mid-range configurations. Southern Sicily and Apulia's underpenetrated smallholder base offers most penetrable demand, with compact narrow-track seeders and sub-50 hp vineyard units commanding limited incumbent attention. Go-to-market execution should route through Catania and Palermo independent retailers bypassing northern dealer concentration. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by multinational full-line suppliers seeking telemetry capability augmentation and BIS certification arbitrage for North African market entry. Long-term viability favors Italian-headquartered specialists with captive compact equipment expertise and established MIPAAF subsidy program relationships. Watch telemetry integration failure rates at dealer service departments as inflection indicator for platform readiness and cooperative adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Telemetry Technician Certification Program | ISOBUS-trained service capacity unlocks PNRR-subsidized precision agriculture deployments across Emilia-Romagna cooperatives. |
| Backward Integration into Filter Technology | In-house diesel particulate filter production captures margin pools squeezed by outsourced Stage V aftertreatment procurement. |
| Southern Distribution Network Expansion | Catania and Palermo retail presence addresses geographic supply vulnerability for Sicilian citrus and olive smallholders. |
| Autonomous-Ready Platform Leasing | Subscription-based Raven telemetry access lowers capital barriers for capital-constrained cooperative fleet upgrades. |
| BIS Certification Arbitrage Investment | Dual domestic-export safety compliance positions acquisition targets for North African and Balkan market entry. |
Research Methodology
Trade association filings, MIPAAF subsidy disbursement records, and EU Stage V regulatory documentation formed the secondary backbone, supplemented by primary interviews with dealer network managers, cooperative procurement officers, and aftermarket service heads. Bottom-up and top-down triangulation validated equipment shipment data against PNRR funding allocation patterns and BIS certification registry entries.
Bottom-up modeling aggregated segment-level demand across tractor power ratings, combine harvester replacement cycles, and precision technology adoption tiers, while top-down cross-checks anchored totals to national agricultural GDP and machinery investment intensity benchmarks. Segmentation dimensions included product type, end-user scale, distribution channel, and technology tier across the projection horizon. CAGRs derived from equipment replacement cycle compression effects tied to subsidy deadlines and emission standard pre-buying behavior.
Inputs from dealer service departments and cooperative fleet managers were available through the study window; gaps in southern smallholder auction transaction records introduce uncertainty bands around retrofit compatibility failure rates. Forecasts reflect documented assumptions regarding PNRR disbursement timelines and European Commission emission threshold evolution. Deviation in MIPAAF spending acceleration or Stage V enforcement postponement would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Machinery
United States Agricultural Machinery Market
Agricultural Machinery
Germany Agricultural Tractor Machinery Market
Agricultural Machinery
Agriculture Sprayers Market
Agricultural Machinery
India Agricultural Machinery Market
Agricultural Machinery
Mexico Agricultural Machinery Market
Agricultural Machinery
France Agricultural Machinery Market
Agricultural Machinery
Autonomous Farm Equipment Market
Agricultural Machinery
US Agriculture Drone Market
Agricultural Machinery
North America Agricultural Machinery Market
Agricultural Machinery
Agricultural Spray Drone Market
Agricultural Machinery
Two-Wheeler Tractors Market
Agricultural Machinery
Agricultural Tractor Robots Market
Agricultural Machinery
North America Agricultural Tractors Market
Agricultural Machinery
Europe Utility Tractor Market
Agricultural Machinery
Canada Agricultural Machinery Market
Agricultural Machinery
Australia Agricultural Machinery Market