
 Southeast Asia Agricultural Tractors Market | 2026-2036
Southeast Asia Agricultural Tractors Market Size, Share, and Industry Trends Forecast 2026-2036
Southeast Asia Agricultural Tractors Market Analytics
Precision guidance and telematics integration is narrowing the performance gap between compact utility models and full-scale farm equipment across Southeast Asian operations. KUBOTA Corporation leverages its established Thai manufacturing base and dense dealership network to dominate sub-50 horsepower segments for rice paddy applications. Deere & Company sustains premium positioning through advanced precision agriculture suites targeted at large plantation operators in Indonesia and Malaysia. Yanmar Holdings Co. Ltd anchors its competitive stance with diesel-electric hybrid prototypes designed specifically for tropical humidity cycles and fragmented landholdings.
Agricultural tractors are self-propelled power units engineered to deliver drawbar and power-take-off torque typically ranging from 15 to 300 horsepower, configured with three-point hitch linkages and hydraulic systems for implement attachment in soil preparation, planting, and harvesting workflows. Compact tractors occupy the volume base across Southeast Asia given smallholder plot sizes averaging under two hectares, while utility tractors command expanding share as cooperative farming consolidates land and shares equipment hours across multiple growers. High horsepower tractors concentrate margin pools around Malaysian palm oil estates and Indonesian corporate agriculture ventures requiring extended daily duty cycles and heavy tillage capacity.
Thailand's Board of Investment machinery incentives, Indonesia's Ministry of Agriculture mechanization subsidy schemes, and Vietnam's national technical regulations on agricultural equipment safety standards collectively shape product homologation requirements and import duty structures across the region. These frameworks favor localized assembly operations and incentivize manufacturers to achieve domestic content thresholds that reduce landed costs for end users. Stakeholders must monitor evolving carbon intensity benchmarks and electrification roadmaps as ASEAN harmonization discussions progress, since future equipment specifications will likely integrate emissions compliance as a procurement gate for government-supported farming programs.
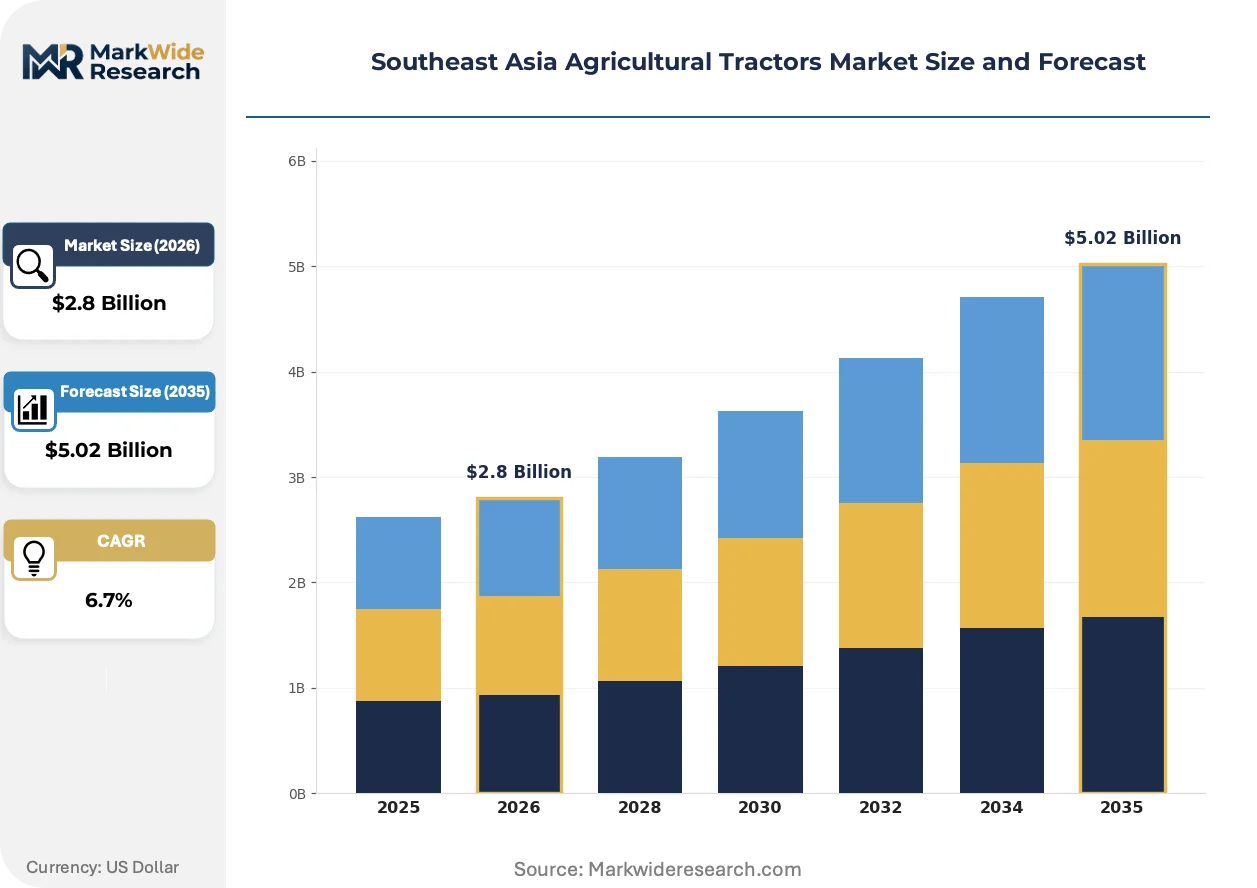
Market Dynamics
Mechanization subsidies from Indonesia's Ministry of Agriculture and Thailand's Board of Investment tax incentives are compressing adoption timelines for precision-enabled tractors across smallholder cooperatives and plantation operators.
Growth Catalysts
- Rising Labor Costs:Rural workforce shortages in Vietnam and Thailand push farming collectives toward shared equipment models that maximize tractor utilization rates across fragmented landholdings.
- Telematics Integration:Real-time monitoring systems allow cooperatives to track fuel consumption and maintenance intervals, reducing operational waste across dispersed rice paddy and palm oil operations.
- Thailand BOI Incentives:Tax holidays and import duty exemptions for localized assembly operations lower landed costs for utility tractors targeting cooperative farming ventures.
Market Restraints
- Steel Price Volatility:Input cost swings for chassis and engine components compress manufacturer margins and complicate long-term pricing commitments to distributor networks.
- Import Dependency:Powertrain and hydraulic system sourcing concentrates in Japanese and Korean supplier bases, exposing assemblers to currency fluctuation and shipping disruption risks.
- Technical Limitations:Battery-electric prototypes struggle with tropical humidity degradation and limited charging infrastructure across rural Indonesian and Philippine farming corridors.
Strategic Opportunities
- Myanmar Mechanization Gap:Sanctions relief scenarios and agricultural modernization programs could unlock first-wave tractor adoption across previously isolated farming regions.
- Diesel-Electric Hybrid Platforms:Convergence of compact diesel engines with electric assist motors addresses torque demands for wet-field rice cultivation while reducing fuel exposure.
- Digital Equipment Leasing:Fintech-enabled pay-per-use models bypass traditional credit barriers for Vietnamese smallholders lacking collateral for outright purchase.
Industry Challenges
- Telematics Technician Scarcity:Diagnostic and software calibration skills lag hardware deployment across Indonesian dealership networks, extending downtime for precision-enabled fleets.
- ASEAN Harmonization Delays:Divergent emissions testing protocols between Thailand, Indonesia, and Vietnam force manufacturers to maintain multiple product configurations, inflating homologation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Southeast Asia Agricultural Tractors Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compact Tractors, Utility Tractors, Row Crop Tractors, High Horsepower Tractors End User: Farmers, Cooperatives, Agricultural Service Providers, Landowners Technology: Conventional Tractors, Autonomous Tractors, Electric Tractors, Hybrid Tractors Distribution Channel: Direct Sales, Online Sales, Dealerships, Rental Services |
| Companies Covered | KUBOTA Corporation, Deere & Company, AGCO Corporation, CNH Industrial N.V., Yanmar Holdings Co. Ltd, Mahindra & Mahindra, CLAAS KGaA mbH, Iseki & Co., Ltd., JCB, Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Southeast Asia Agricultural Tractors Market Evolving Landscape
Automation and connectivity layers are redefining equipment specifications across Southeast Asian farming operations, compressing the functional distinction between compact utility and full-scale agricultural machinery.
Autosteering and variable-rate application systems are rendering obsolete manual guidance methods for rice transplanting and fertilizer distribution. Plantation operators in Malaysia and Indonesia now specify GPS-enabled tractors as baseline procurement requirements, forcing dealers to bundle precision packages rather than offer them as aftermarket add-ons. This capability compression is mainstreaming precision agriculture across mid-tier equipment segments previously served by mechanical-hydraulic platforms.
Indonesia's Ministry of Agriculture mechanization subsidy schemes now incorporate telematics compliance as a disbursement condition, mandating operational data reporting from beneficiary equipment. This regulatory architecture accelerates connected fleet penetration while creating technical barriers for non-compliant imports. Thai and Vietnamese regulators are observing this framework for potential regional harmonization.
Cooperative buying consortia are displacing individual smallholder purchases as the dominant transaction pattern across Java and the Mekong Delta. These aggregators negotiate volume discounts and shared maintenance contracts with authorized dealers, compressing single-unit retail margins while expanding aftermarket service attach rates. Equipment financing through agricultural cooperatives now commands significant transaction flow in Vietnam's northern rice-growing provinces.
Southeast Asia Agricultural Tractors Market Segmentation
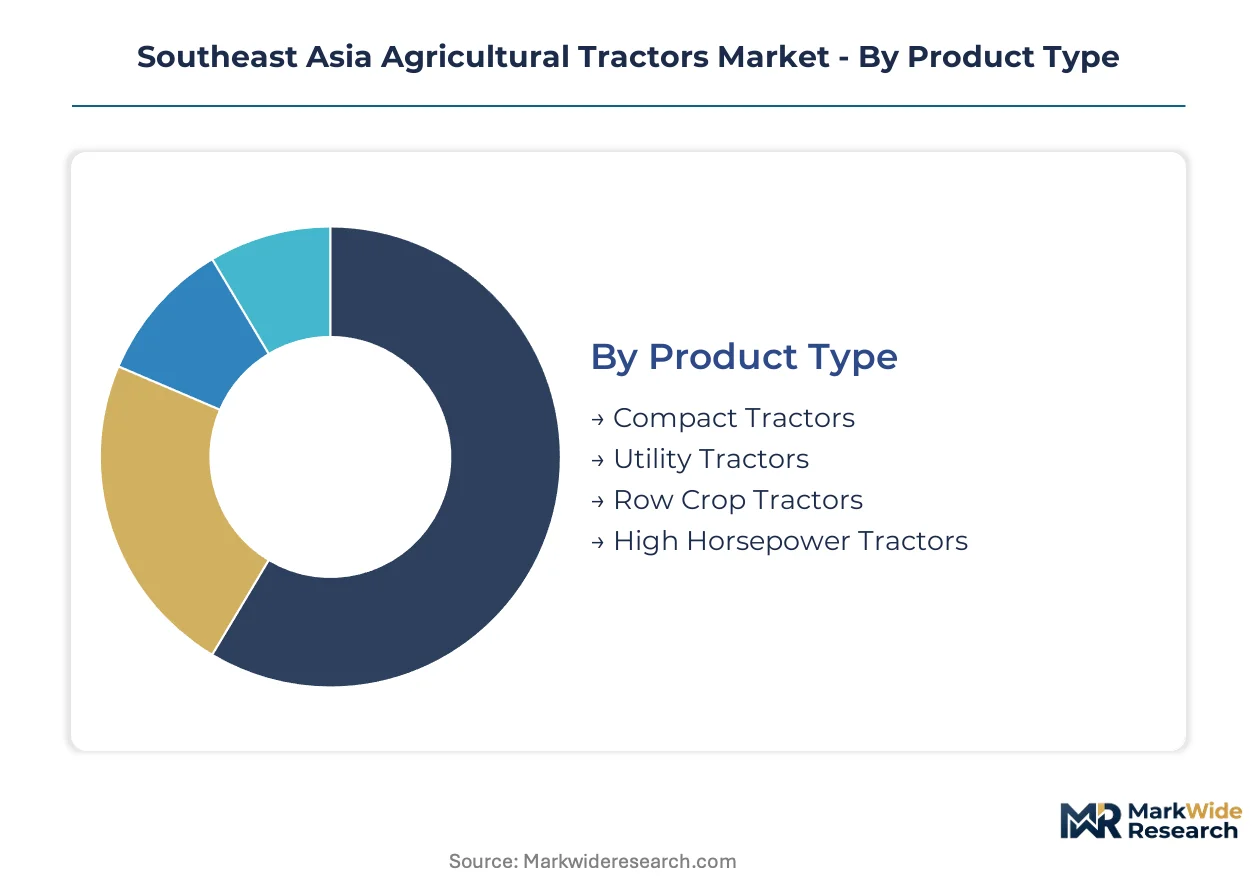
Tractor segmentation across Southeast Asia reflects the tension between smallholder plot constraints and plantation-scale mechanization. Equipment specifications diverge sharply across rice paddy operations in Vietnam, palm oil estates in Malaysia, and cooperative farming ventures in Thailand.
Product Type:
Cost tier differentiation separates entry-level mechanization from capital-intensive fleet investments across Indonesian and Thai farming operations.
- Compact Tractors:Sub-50 horsepower units dominate Vietnamese and Indonesian smallholder procurement, configured with narrow tread widths for flooded rice field navigation. Java's farming cooperatives specify these models for shared-equipment pools serving fragmented two-hectare plots.
- Utility Tractors:50-100 horsepower platforms anchor Thailand's cooperative mechanization programs, delivering three-point hitch versatility for tillage and hauling across diversified cropping systems. Board of Investment assembly incentives compress landed costs for these mid-tier units.
- Row Crop Tractors:Specialized axle configurations accommodate precise row spacing in Malaysian palm oil nurseries and Indonesian vegetable production zones.
- High Horsepower Tractors:150+ horsepower units concentrate around Sumatran palm oil processing estates and East Malaysian plantation conglomerates requiring extended daily duty cycles.
Compact tractors command the established base. The steepest expansion runs through utility tractors as cooperative farming consolidates equipment sharing arrangements.
End User:
Customer type determines financing structures and aftermarket service attach rates across the region's divergent land tenure systems.
- Farmers:Individual smallholders in Vietnam's Mekong Delta and Indonesia's Central Java rely on subsidized credit programs for compact tractor acquisition. Ministry of Agriculture disbursement conditions now mandate telematics compliance for beneficiary equipment.
- Cooperatives:Aggregated buying consortia negotiate volume discounts and shared maintenance contracts with authorized Kubota and Yanmar dealers, displacing single-unit retail transactions.
- Agricultural Service Providers:Contract tillage operators in Thailand's Chao Phraya basin maximize equipment utilization rates across multiple client farms.
- Landowners:Corporate agriculture ventures in Malaysian Sabah and Indonesian Riau specify premium precision agriculture suites as baseline procurement requirements.
Individual farmers retain volume leadership. Cooperative purchasing is gaining share fastest as credit aggregation bypasses traditional collateral barriers.
Technology:
Powertrain architecture selection hinges on tropical humidity tolerance and rural charging infrastructure availability.
- Conventional Tractors:Diesel-mechanical platforms retain dominance across Philippine and Myanmar farming corridors where dealer service networks remain sparse. Simplified hydraulic systems reduce technician dependency for maintenance intervals.
- Autonomous Tractors:GPS-guided autosteering systems are rendering manual guidance obsolete for Malaysian palm oil fertilizer distribution and Indonesian rice transplanting operations.
- Electric Tractors:Battery-electric prototypes struggle with humidity degradation and limited grid access across rural Indonesian archipelago farming zones.
- Hybrid Tractors:Diesel-electric assist configurations address torque demands for wet-field rice cultivation while reducing fuel exposure in volatile energy markets.
Conventional diesel architectures command the established base. Hybrid platforms are climbing the fastest as manufacturers prototype tropical-duty powertrains.
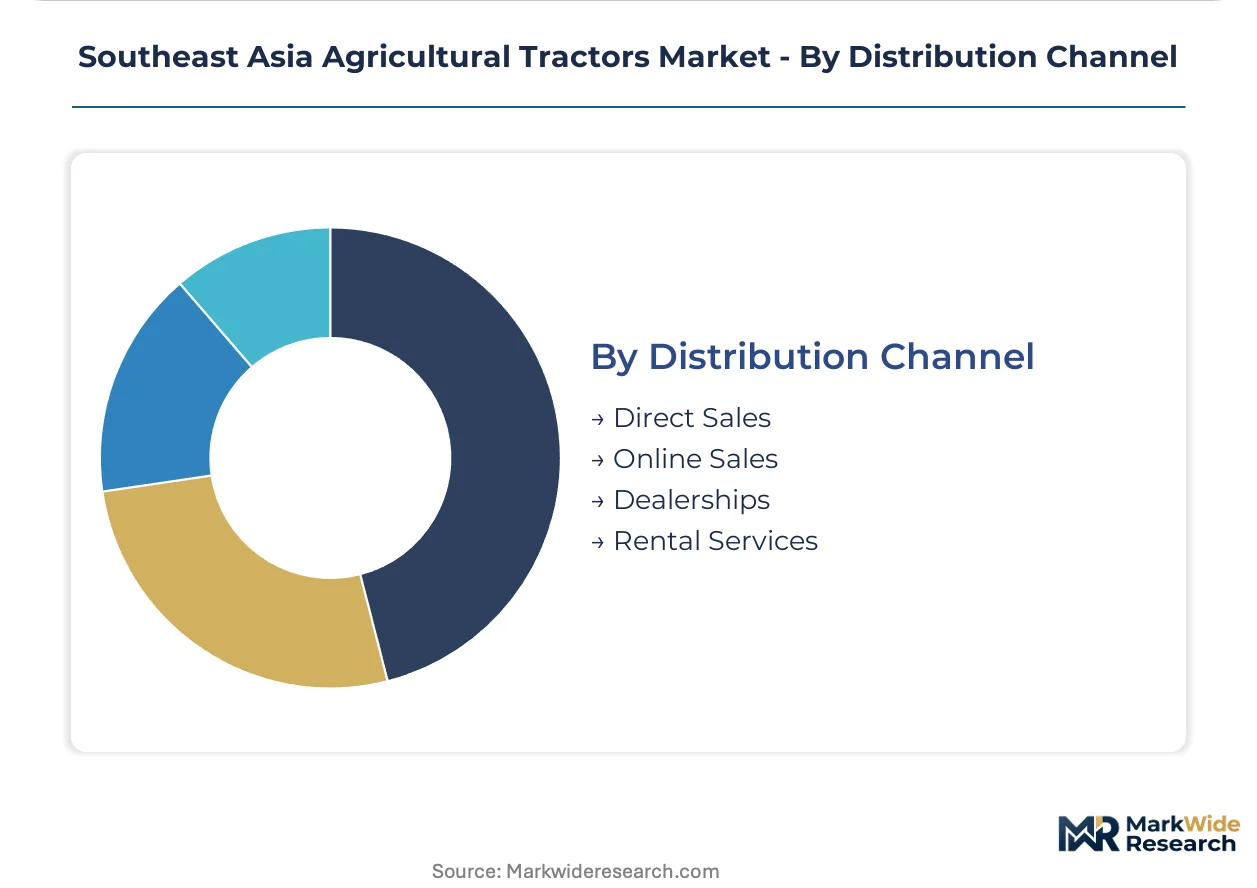
Distribution Channel:
Channel selection reflects credit access patterns and technical service requirements across divergent farming economies.
- Direct Sales:Plantation operators in Indonesian Papua and Malaysian Sarawak negotiate fleet procurement directly with manufacturer regional offices, bypassing retail margin stacking.
- Online Sales:Digital equipment configurators penetrate Vietnamese and Thai urban-proximate farming districts where smartphone penetration supports virtual specification.
- Dealerships:Dense Kubota and Deere networks across Thailand's Central Plains deliver spare parts availability and technician training for precision agriculture diagnostics.
- Rental Services:Pay-per-use models emerge in Vietnam's northern provinces where fintech platforms collateralize equipment access without traditional asset ownership.
Authorized dealerships command the established base. Rental and fintech-enabled channels are expanding most quickly among credit-constrained smallholder segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Plantation operators and cooperative farming consortia concentrate procurement power across Indonesian palm oil belts, Thai rice basins, and Vietnamese Mekong Delta corridors. Equipment specifications diverge sharply between smallholder compact tractor demand and estate-scale high-horsepower fleet investments.
Indonesia
Palm oil estate operators in Sumatra and Kalimantan drive demand for 150+ horsepower tractors with extended duty cycles. The Ministry of Agriculture's mechanization subsidy schemes now mandate telematics compliance as a disbursement condition for beneficiary equipment. Manufacturing clusters around Jakarta and Surabaya host localized assembly operations serving domestic content thresholds.
Thailand
Rice cooperative farming consortia across the Central Plains accelerate utility tractor adoption through shared-equipment pooling models. The Board of Investment grants tax holidays and import duty exemptions for agricultural machinery assembly operations meeting domestic content requirements. Dense Kubota and Yanmar dealership networks in Bangkok-proximate industrial zones deliver spare parts availability and precision agriculture technician training.
Vietnam
Mekong Delta smallholders and northern rice-growing provincial cooperatives propel compact tractor volume through aggregated buying consortia. The national technical regulations on agricultural equipment safety standards shape product homologation requirements for imported machinery. Agricultural financing through cooperative credit structures in Hai Duong and Thai Binh provinces bypasses traditional collateral barriers for equipment acquisition.
Malaysia
Sabah and Sarawak plantation conglomerates specify premium precision agriculture suites as baseline procurement requirements for large-scale palm oil operations. The country's sustainable palm oil certification frameworks increasingly incorporate mechanization efficiency metrics into compliance audits. Industrial equipment distributors in Port Klang and Johor Bahru coordinate fleet procurement directly with regional manufacturer offices.
Philippines
Luzon and Mindanao farming cooperatives rely on simplified diesel-mechanical platforms where dealer service networks remain sparse across archipelago geography. The Department of Agriculture's mechanization programs channel subsidized credit toward compact tractor acquisition for rice and corn production zones. Equipment assemblers in Cavite and Laguna provinces benefit from tariff structures favoring localized operations over fully-imported units.
Southeast Asia Agricultural Tractors Market Competitive Landscape
Channel-controlling players compete with product-specialist players across divergent access pathways to plantation operators and cooperative buyers. The market structure tiers between established Japanese manufacturers with dense dealership networks and emerging Indian and Korean challengers penetrating through price-aggressive cooperative procurement channels. Three archetypes dominate: precision-technology integrators targeting estate-scale accounts, compact-utility volume leaders serving smallholder cooperatives, and hybrid-powertrain innovators prototyping tropical-duty specifications. Competitive moves concentrate on strategic partnerships with agricultural financing platforms and backward integration into localized assembly operations.
Within the precision-technology tier, Deere & Company and AGCO Corporation exemplify equipment suppliers bundling GPS-enabled autosteering and variable-rate application systems as baseline offerings rather than aftermarket add-ons. Japanese manufacturers KUBOTA Corporation and Yanmar Holdings Co. Ltd anchor the compact-utility volume position through established Thai manufacturing bases and dense regional dealership networks. Among diversified industrial conglomerates, CNH Industrial N.V. and Mahindra & Mahindra occupy positions spanning multiple horsepower segments and geographic price points. These named entities represent archetypal competitive positions rather than exhaustive market coverage.
| Leading Market Players |
|---|
| KUBOTA Corporation |
| Deere & Company |
| AGCO Corporation |
| CNH Industrial N.V. |
| Yanmar Holdings Co. Ltd |
| Mahindra & Mahindra |
| CLAAS KGaA mbH |
| Iseki & Co., Ltd. |
| JCB |
| Others |
Value Network & Pricing Analysis
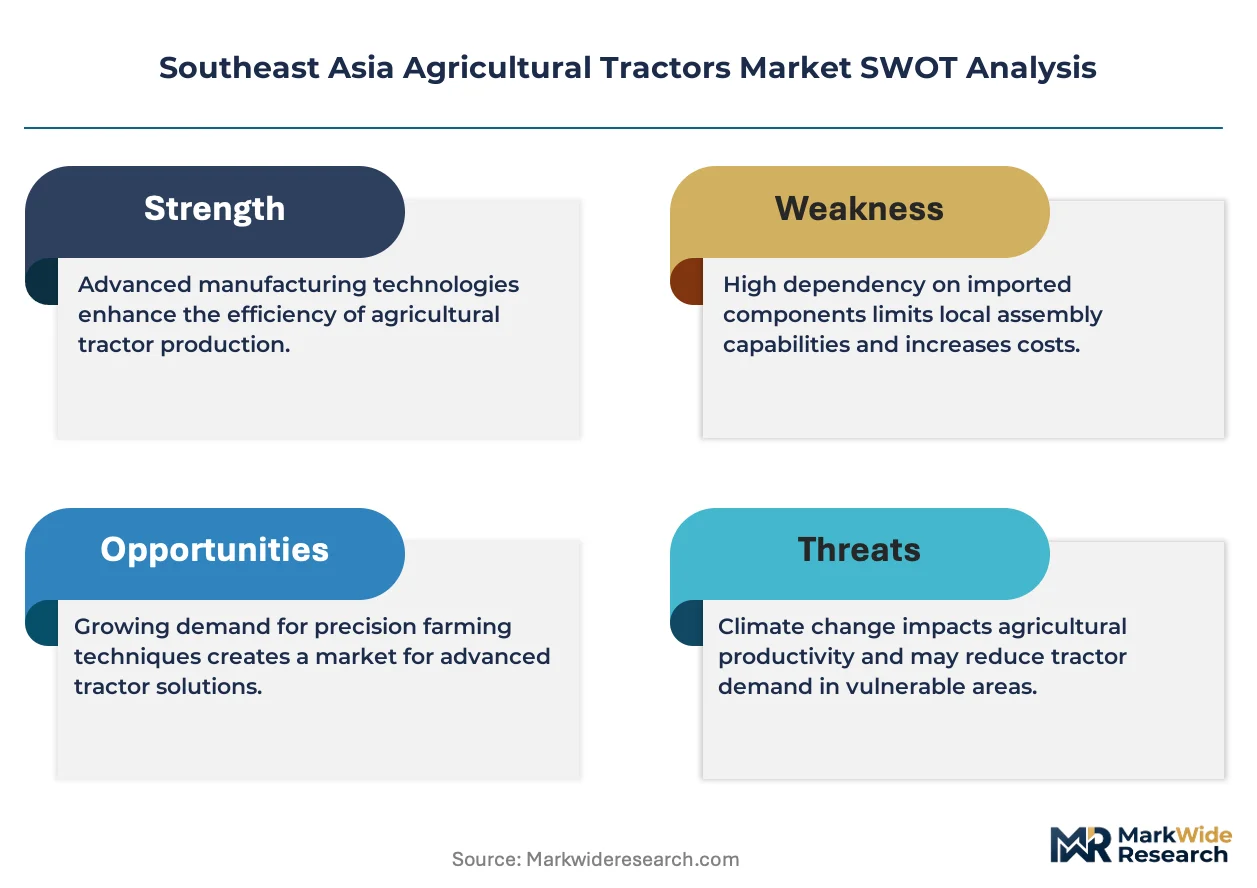
Overcapacity in Thai tractor assembly operations is compressing supplier margins while simultaneously expanding pricing flexibility for cooperative buyers negotiating volume procurement contracts. This utilization dynamic rewards localized manufacturers meeting Board of Investment domestic content thresholds with cost advantages that translate into competitive positioning against fully-imported units.
Pricing Analysis
Cost-plus contracts indexed to steel futures and engine component baskets dominate procurement agreements between Indonesian plantation operators and equipment assemblers. Pricing stratifies across premium precision-agriculture tiers, standard utility configurations, and economy compact models, with brand premium and after-sales service bundling as primary differentiation drivers. Cost compression in the economy tier is intensifying because Indian and Korean challengers are penetrating cooperative procurement channels with aggressive landed-cost positioning. Cooperative farming consortia exhibit highest price sensitivity due to aggregated credit constraints, while Malaysian estate operators demonstrate lowest sensitivity given operational efficiency imperatives.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from Japanese trading houses are stabilizing working capital for Thai and Indonesian assembly operations facing currency fluctuation exposure. Powertrain sourcing concentrates in Japan and South Korea, hydraulic system components draw from Chinese and Taiwanese supplier bases, and steel chassis materials feed from regional mills in Vietnam and Indonesia. Single-source vulnerability around precision guidance sensors creates structural risk given limited qualified suppliers for tropical-duty telematics hardware. Distribution runs through dense authorized dealership networks across Thailand's Central Plains and Vietnam's Mekong Delta, with direct manufacturer relationships serving Indonesian and Malaysian plantation accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is approaching a platform-economics inflection where telematics compliance becomes the interoperability layer connecting equipment financing, subsidy disbursement, and precision agriculture service bundling. The Indonesian Ministry of Agriculture's data-reporting mandate is accelerating this ecosystem consolidation.
For Market Incumbents: Build switching-cost moats through captive financing platforms that embed telematics compliance as a loan servicing requirement, locking cooperative borrowers into multi-year aftermarket service contracts. Deepen backward integration into localized engine assembly operations to defend margin position against Korean price aggression in the utility tractor segment. Prioritize technician certification programs addressing diagnostic scarcity in Indonesian dealership networks.
For New Entrants and Emerging Players: Pursue white-space penetration in Myanmar's mechanization gap through simplified diesel-mechanical platforms bypassing telematics complexity, targeting provincial agricultural modernization programs as anchor accounts. Vietnam's northern rice-growing provinces offer the most penetrable geography given credit-aggregated cooperative structures and limited incumbent service density. Deploy fintech-enabled equipment leasing partnerships with agricultural credit unions to bypass traditional collateral barriers.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across hybrid powertrain development as diesel-electric assist platforms achieve production scale, improving returns on R&D deployment. Acquisition targets should emphasize dealership network density in Thailand and Vietnam over manufacturing asset ownership given service-attach-rate monetization potential. Monitor ASEAN emissions harmonization negotiations as the critical signal for product configuration standardization and homologation cost reduction.
| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Platform Integration | Indonesian subsidy compliance mandates are rendering connected fleets a procurement gate for government-supported programs. |
| Localized Assembly Expansion | Thailand Board of Investment incentives reward domestic content thresholds with tax holidays compressing landed costs. |
| Hybrid Powertrain Development | Diesel-electric assist configurations address wet-field rice torque demands while reducing fuel exposure in volatile energy markets. |
| Cooperative Financing Partnerships | Fintech-enabled pay-per-use models bypass traditional collateral barriers for Vietnamese smallholders lacking asset ownership. |
| Aftermarket Service Network Densification | Technician training investments address diagnostic scarcity extending downtime for precision-enabled fleets across Indonesian archipelago operations. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with plantation operations managers, cooperative equipment pooling coordinators, agricultural financing officers, dealership service technicians, and Ministry of Agriculture mechanization program administrators. Secondary validation drew from customs and trade flow databases, ASEAN technical regulation filings, Board of Investment incentive disclosure records, and equipment registration statistics. Bottom-up unit demand estimates were triangulated against top-down agricultural mechanization spending projections.
Calibration against historical subsidy disbursement patterns and cooperative formation rates anchored the analytical framework across the projection horizon. Segmentation modeling incorporated horsepower tier, end-user archetype, powertrain architecture, and distribution channel dimensions. CAGRs were derived from fitted trend extrapolation moderated by regulatory inflection assumptions. Forecast inputs included labor cost trajectories in Vietnamese and Thai agricultural sectors and palm oil estate capital expenditure cycles.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Indian price-aggressive entrants or accelerated ASEAN harmonization would shift outcomes beyond modeled ranges. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Machinery
Two Wheel Walking Tractor Market
Agricultural Machinery
Autonomous Agricultural Machinery Market
Agricultural Machinery
Europe Utility Tractor Market
Agricultural Machinery
Rotary Tiller Market
Agricultural Machinery
Rice Mill Machine Market
Agricultural Machinery
Orchard Tractor Market
Agricultural Machinery
Crawler Tractors Market
Agricultural Machinery
Europe Agricultural Sprayer Market
Agricultural Machinery
Mini Tractors Market
Agricultural Machinery
Mexico Agricultural Machinery Market
Agricultural Machinery
Power Tiller Market
Agricultural Machinery
Agriculture Sprayers Market
Agricultural Machinery
Automated Turf Harvester Market
Agricultural Machinery
Compact Tractor Market
Agricultural Machinery
India Agricultural Machinery Market
Agricultural Machinery
Canada Agricultural Machinery Market