
 US Lawn Mowers Market | 2026-2036
US Lawn Mowers Market Size, Share, and Industry Trends Forecast 2026-2036
US Lawn Mowers Market Insights
Premium battery specifications is bifurcating the US Lawn Mowers Market into performance tiers that reward engineering depth. Deere & Company leverages its vertical integration into powertrain components to sustain margin capture across commercial and residential lines. Husqvarna Group differentiates through robotic navigation patents and connected fleet management for professional landscapers. The Toro Company anchors its position in golf and sports turf applications where precision cutting tolerances command premium pricing.
A lawn mower is a motorized or human-propelled turf maintenance machine utilizing rotary or reel cutting decks with blade speeds typically ranging from 2,800 to 3,200 RPM to sever grass at controlled heights for aesthetic and horticultural purposes. Gas Lawn Mowers retain volume leadership in extra-large lawn categories and commercial fleets where runtime and torque requirements exceed current battery density, though Electric Lawn Mowers capture fastest growth in residential small-to-medium lawn segments as lithium-ion pack costs decline. Robotic Lawn Mowers represent an emerging margin pool concentrated among tech-forward households with bounded property perimeters and Wi-Fi coverage.
EPA emissions regulations under the Clean Air Act constrain small spark-ignition engine designs and push manufacturers toward electrification or catalytic after-treatment investments. OSHA noise exposure standards and state-level California Air Resources Board zero-emission equipment mandates reshape product portfolios and distribution priorities. Stakeholders must monitor battery supply chain localization under the Inflation Reduction Act and assess whether captive cell production or supplier partnerships better secure cost positions as electrification accelerates.
Market Dynamics
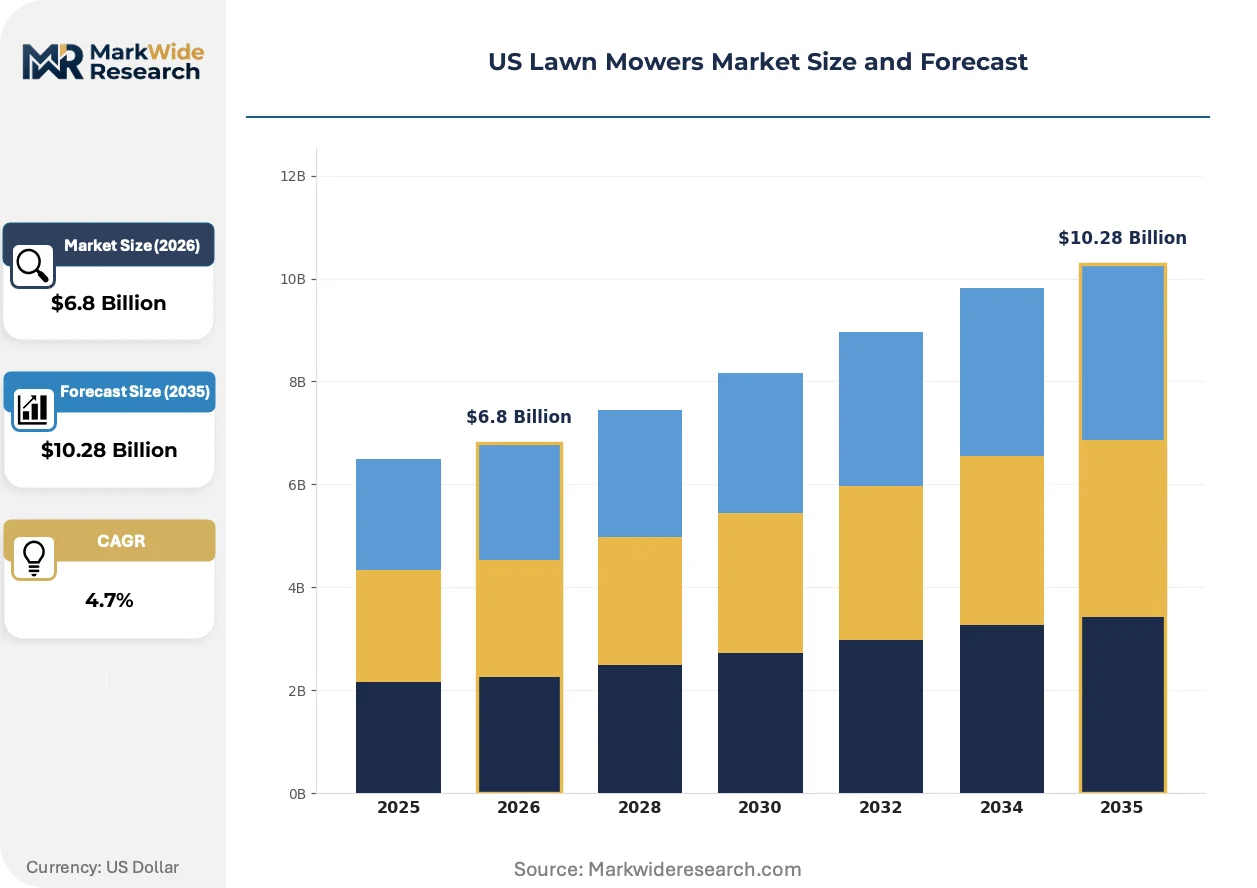
EPA emissions standards under the Clean Air Act are decomposing gas-engine product lines as manufacturers redirect R&D toward electrification and catalytic after-treatment systems. The regulatory pressure is compressing traditional powertrain margins while creating asymmetric rewards for battery-pack engineering depth.
Growth Catalysts
- California Air Resources Board zero-emission mandates:State-level equipment bans are accelerating fleet turnover among commercial landscapers in the Southeast and residential buyers in suburban Texas.
- Lithium-ion pack cost curves:Declining cell prices are unlocking battery-powered viability for medium-lawn residential segments previously dominated by gas engines.
- Tech-adopting households:Wi-Fi coverage expansion in bounded California and Northeast properties is enabling robotic mower penetration among time-constrained professionals.
Market Restraints
- Cobalt and lithium supply concentration:Battery raw material sourcing from concentrated overseas suppliers exposes manufacturers to geopolitical disruption and price volatility.
- Energy density limitations:Current lithium-ion chemistry cannot match gas-engine runtime for extra-large lawn categories and commercial zero-turn applications.
- OSHA noise exposure compliance:Hearing conservation program requirements add operational friction for landscaping contractors maintaining mixed gas-electric fleets.
Strategic Opportunities
- Inflation Reduction Act localization incentives:Battery supply chain onshoring credits reward domestic cell production or strategic supplier partnerships.
- Connected fleet management:Telematics integration is opening recurring revenue streams among professional landscaping operations in Florida and Georgia.
- Golf and sports turf precision cutting:Specialized reel-mower tolerances command premium pricing in municipal and private course maintenance contracts.
Industry Challenges
- Powertrain engineering talent scarcity:The shift from small spark-ignition engines to electric drivetrains requires retraining mechanical engineering workforces concentrated in Midwest manufacturing hubs.
- Dual certification complexity:Simultaneous EPA compliance for remaining gas models and UL safety validation for electric platforms stretches quality assurance timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Lawn Mowers Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.28 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gas Lawn Mowers, Electric Lawn Mowers, Robotic Lawn Mowers, Manual Push Mowers End User: Residential Users, Commercial Landscapers, Government Agencies, Agricultural Sector Technology: Battery-Powered, Hybrid, Zero-Turn, Walk-Behind Size: Small Lawns, Medium Lawns, Large Lawns, Extra-Large Lawns |
| Companies Covered | Deere & Company, Husqvarna Group, The Toro Company, Honda, Kubota Corporation, MTD Products, AriensCo, Stanley Black & Decker, Robert Bosch, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Lawn Mowers Market Trends and Innovations
Electrification is fragmenting the competitive landscape into distinct engineering-capability tiers rather than brand-loyalty segments. Manufacturers must now compete on battery thermal management and motor control algorithms alongside traditional cutting performance.
Solid-state battery prototyping is decomposing the runtime-performance tradeoff that has protected gas-engine incumbency in commercial applications. Professional landscapers in Arizona and Nevada are piloting early packs for all-day cutting operations. The technology is decomposing the traditional segmentation between residential electric and commercial gas product lines.
EPA Tier 4 and CARB small off-road engine regulations are forcing catalytic converter integration or complete platform abandonment. Engineering teams face redesign costs for remaining gas models while accelerating electric transitions. The Southeast commercial fleet channel bears the highest compliance burden as contractors delay capital replacement cycles.
Subscription-based equipment access is displacing outright ownership among cash-flow-sensitive landscaping startups. Dealer networks in Texas and Florida are unbundling maintenance from hardware sales to capture recurring revenue. The model is compressing traditional three-to-five-year replacement cycles into shorter-term refresh decisions tied to software feature releases.
US Lawn Mowers Market Segmentation
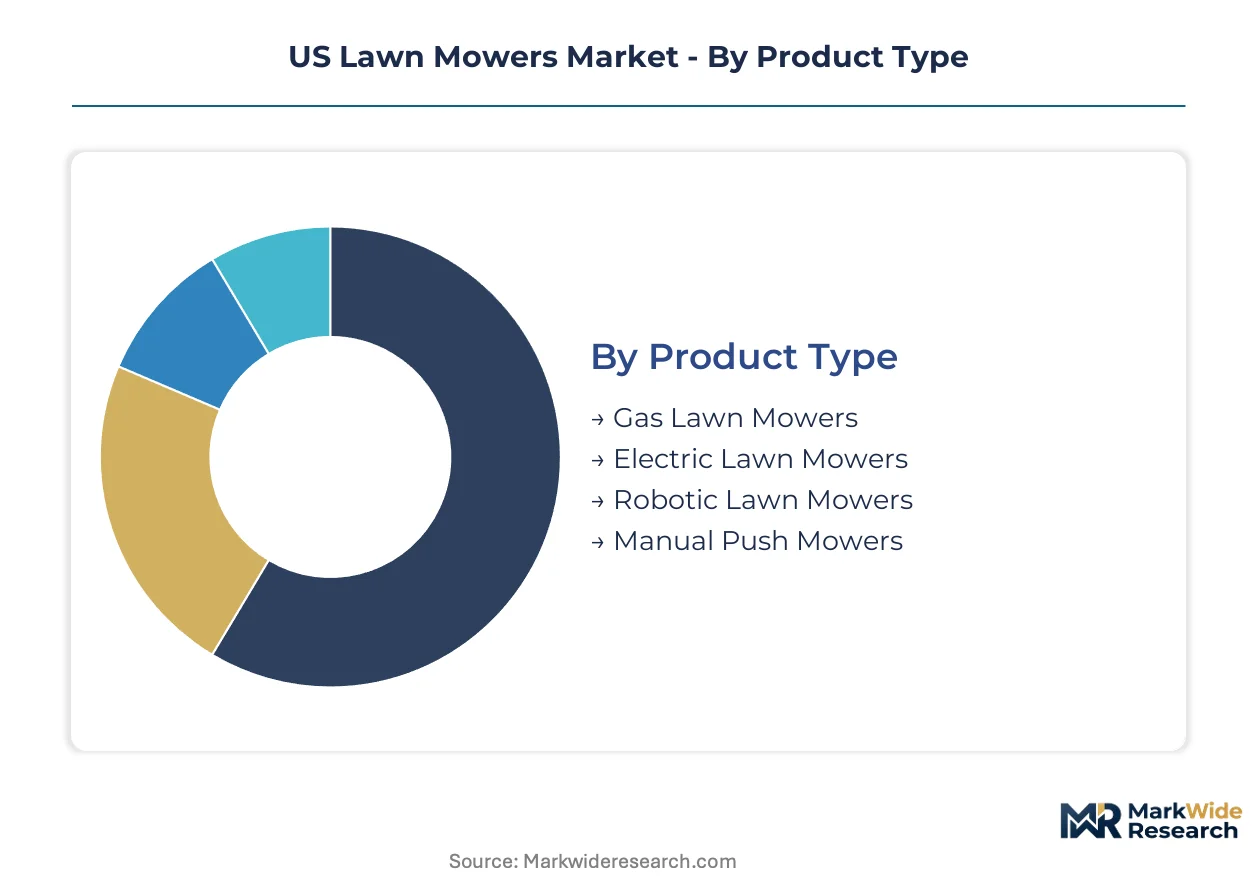
Segmentation in the US Lawn Mowers Market reveals distinct procurement patterns across powertrain technologies and property scales. Channel strategies diverge sharply between big-box retail for residential electric units and dealer-direct networks for commercial zero-turn fleets.
Product Type:
Dealer networks and mass retail channels bifurcate sharply around powertrain technology, with gas models flowing through independent servicing dealers while electric units concentrate in home improvement chains.
- Gas Lawn Mowers:Small spark-ignition engines deliver 2,800-3,200 RPM blade speeds with catalytic after-treatment for EPA Tier 4 compliance. Demand concentrates among commercial landscapers in Florida and Texas where runtime requirements exceed current battery density.
- Electric Lawn Mowers:Lithium-ion packs power brushless motors with thermal management systems for residential cutting cycles. Suburban households in California and the Northeast are upgrading as CARB zero-emission mandates tighten and pack costs decline.
- Robotic Lawn Mowers:Autonomous navigation systems with boundary wire or GPS-RTK positioning for bounded properties.
- Manual Push Mowers:Human-propelled reel cutting for small urban lawns and sustainability-focused consumers.
By volume, Gas Lawn Mowers leads. By growth pace, Electric Lawn Mowers is ahead.
End User:
Customer type determines service bundling intensity, with commercial accounts requiring fleet telematics and maintenance contracts unavailable to residential purchasers.
- Residential Users:Homeowners maintaining single properties with seasonal cutting cycles. Battery-powered walk-behind units dominate suburban Texas and Florida upgrades as emissions standards tighten.
- Commercial Landscapers:Fleet operators serving multiple properties with daily runtime demands. Zero-turn riders anchor Southeast contractor purchases where OSHA noise compliance adds operational friction for mixed fleets.
- Government Agencies:Municipal parks departments with procurement governed by public bidding rules.
- Agricultural Sector:Ranch and rural property maintenance with acreage-scale cutting requirements.
Commercial Landscapers command the highest average transaction values. Residential Users are expanding most quickly in electrified segments.
Technology:
Engineering architecture separates premium pricing tiers, with thermal management sophistication determining margin capture across battery platforms.
- Battery-Powered:Lithium-ion chemistry with cell balancing and regenerative braking for runtime optimization. Pack cost curves are unlocking medium-lawn viability previously reserved for gas engines.
- Hybrid:Combined combustion-electric powertrains for extended range applications.
- Zero-Turn:Dual hydrostatic drive systems enabling pivot steering for professional productivity. Demand clusters among Southeast commercial fleets where maneuverability accelerates job completion.
- Walk-Behind:Operator-propelled or self-propelled decks for residential precision.
Walk-Behind units ship the highest absolute volumes. Zero-Turn configurations claim the steepest expansion trajectory in commercial channels.
Size:
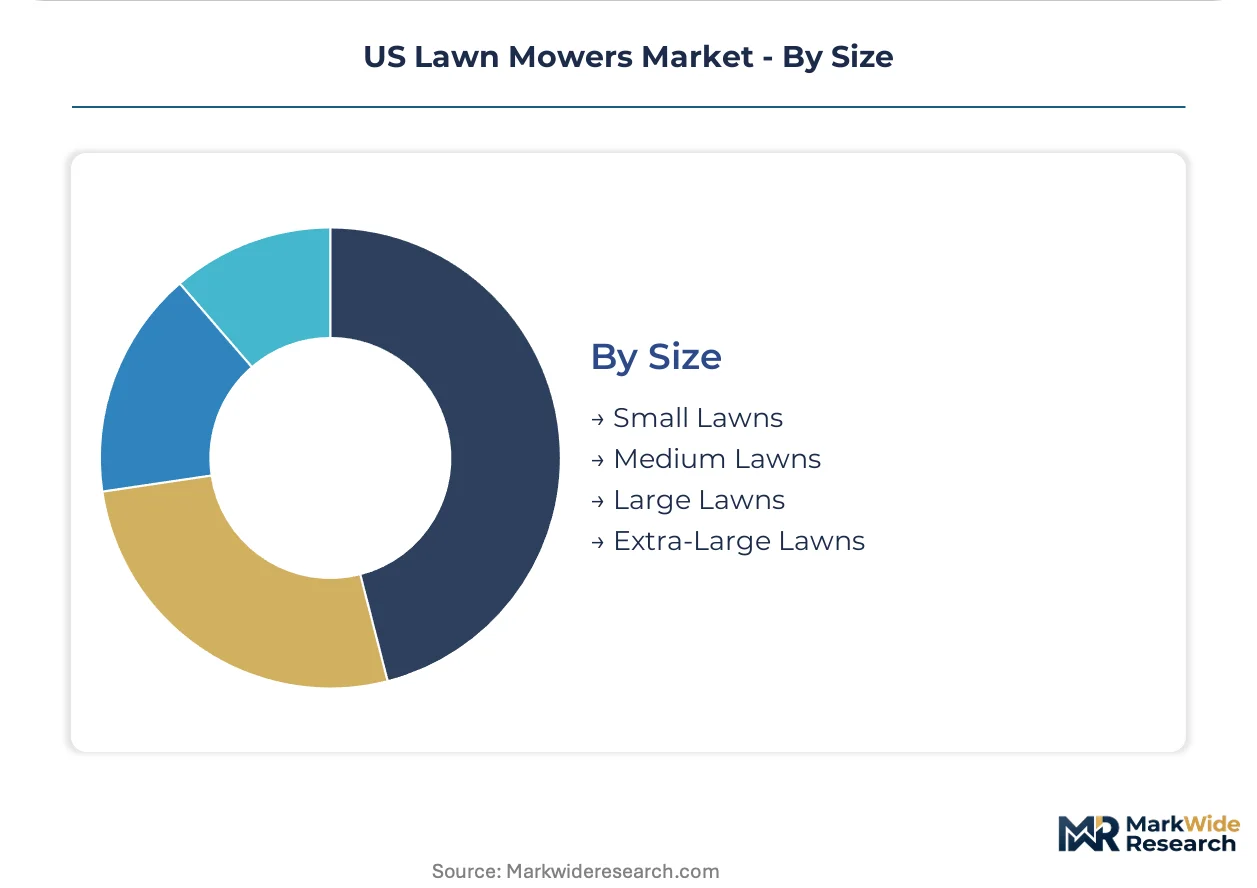
Property acreage dictates deck width and powertrain selection, with cutoff points determining electric viability against gas-engine incumbency.
- Small Lawns:Sub-0.25 acre properties suitable for robotic or compact electric units. Tech-forward households in California bounded properties are piloting autonomous navigation.
- Medium Lawns:0.25-0.75 acre suburban lots where battery-powered walk-behinds now compete with entry gas models. Lithium-ion cost declines are accelerating segment conversion.
- Large Lawns:0.75-2 acre estates requiring riding platforms or extended-runtime batteries.
- Extra-Large Lawns:2+ acre rural properties and commercial grounds where gas-engine torque and refueling speed maintain dominance.
Medium Lawns represents the largest addressable population. Small Lawns is gaining share fastest as robotic penetration advances.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US lawn mower market operates as a net importer of battery cells and powertrain components, with domestic assembly concentrated in Midwest manufacturing corridors and coastal distribution hubs serving distinct climatic demand patterns.
California
Tech-forward households in Silicon Valley and Los Angeles suburbs are piloting robotic navigation systems for bounded properties under 0.25 acres. CARB zero-emission equipment mandates are compressing gas-engine sales channels and redirecting inventory toward battery-powered walk-behind units. The Sacramento Central Valley corridor hosts testing facilities for solid-state battery prototypes targeting commercial runtime thresholds.
Texas
Suburban Houston and Dallas-Fort Worth homeowners are upgrading to battery-powered models as EPA emissions standards tighten, though extra-large rural properties maintain gas-engine demand. The state energy regulator's grid reliability programs intersect with residential electrification timelines. Austin's tech corridor is emerging as a robotic mower early-adoption cluster with dense Wi-Fi coverage enabling autonomous deployment.
Florida
Commercial landscaping fleets in Miami-Dade and Orlando concentrate demand for zero-turn riders where OSHA noise compliance adds operational friction for mixed powertrain operations. Year-round cutting cycles accelerate equipment depreciation and replacement frequency. The Tampa Bay region anchors dealer-direct distribution networks serving Southeast contractor procurement patterns.
Southeast
Atlanta and Charlotte metropolitan areas are witnessing fleet turnover among professional landscapers responding to tightening emissions enforcement. Georgia's logistics infrastructure supports inbound component flows for regional assembly operations. The Research Triangle in North Carolina hosts engineering talent pools transitioning from small spark-ignition expertise toward electric drivetrain development.
Northeast
Massachusetts and Connecticut municipalities are deploying battery-powered units for parks maintenance under state-level clean equipment procurement rules. Dense suburban Boston and New York Metro properties favor compact electric and robotic platforms. The Erie Canal corridor retains legacy manufacturing footprints now repurposing for battery pack assembly under Inflation Reduction Act incentives.
US Lawn Mowers Market Competitive Landscape
Concentration sits with diversified machinery conglomerates possessing captive powertrain engineering capabilities. The vendor base stratifies across three capability tiers: integrated manufacturers controlling upstream cell supply, specialist robotics developers with navigation IP, and regional assemblers sourcing commodity drivetrains. Strategic moves center on battery supply chain partnerships and telematics platform development for fleet management recurring revenue.
Among Midwest-anchored machinery manufacturers, Deere & Company and The Toro Company exemplify integrated engineering depth spanning commercial and residential lines. Husqvarna Group represents the robotics-specialist archetype with European origins and autonomous navigation positioning. These three entities anchor the competitive structure while smaller fabricators occupy price-sensitive segments through distributor relationships.
| Leading Market Players |
|---|
| Deere & Company |
| Husqvarna Group |
| The Toro Company |
| Honda |
| Kubota Corporation |
| MTD Products |
| AriensCo |
| Stanley Black & Decker |
| Robert Bosch |
| Others |
Pricing and Supply Chain Analysis
Midwest assembly capacity utilization above eighty percent is compressing margin flexibility for domestic manufacturers while amplifying pricing power among integrated producers with captive battery engineering. This scale asymmetry stratifies the market into three performance tiers where thermal management sophistication determines price floors and procurement access.
Pricing Analysis
Commercial landscaping fleets anchor pricing stratification across premium, standard, and economy tiers differentiated by battery chemistry grade and UL certification level. Price erosion runs through entry-level residential walk-behinds as Chinese cell imports compress pack costs, while professional zero-turn configurations maintain premium positioning due to OSHA noise compliance bundling. Residential homeowners in suburban Texas exhibit highest price sensitivity, whereas municipal golf course contracts show lowest elasticity due to precision-tolerance specifications.
Supply Chain Analysis
China, South Korea, and Japan anchor lithium-ion cell production for US lawn mower battery packs, with cathode active material processing concentrated in Fujian province and nickel refining in Indonesia. Domestic assembly draws from cobalt hydroxide shipments through Long Beach port corridors, exposing manufacturers to tariff volatility under Section 301 enforcement. Distribution runs through independent dealer networks for commercial zero-turn fleets and big-box retail channels for residential electric units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electrification engineering talent scarcity constrains product development timelines across the competitive landscape, with battery thermal management expertise particularly concentrated among Midwest machinery conglomerates and West Coast robotics specialists.
For Market Incumbents: Compound defensive positioning through backward integration into powertrain components and captive cell supply partnerships that lock in cost positions against emerging robotics entrants. Prioritize UL safety certification investments for electric platforms to accelerate EPA dual-compliance timelines and compress quality assurance cycles. For New Entrants and Emerging Players: CARB fast-track certification pathways for zero-emission equipment open procurement access to California municipal contracts and Southeast commercial fleet turnover. Target medium-lawn residential segments in suburban Texas where lithium-ion cost curves have unlocked battery viability against gas-engine incumbency, deploying direct-to-consumer subscription models that displace dealer-dependent distribution. For Investors and Strategic Acquirers: Specialist robotics developers with autonomous navigation IP and bounded-property positioning algorithms represent priority acquisition archetypes as solid-state battery prototyping decomposes runtime-performance tradeoffs. Monitor solid-state pilot deployments among Arizona and Nevada commercial landscapers as inflection signal for technology-readiness timelines and platform consolidation windows.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Chain Localization | IRA domestic content credits reward Midwest cell production or strategic Korean supplier partnerships. |
| Connected Fleet Management Platform | Telematics integration captures recurring revenue from Florida and Georgia landscaping contractors. |
| Robotic Navigation Patent Acquisition | Autonomous positioning IP secures bounded-property market share against European robotics specialists. |
| Solid-State Battery Pilot Partnership | Early pack deployment with Arizona commercial fleets accelerates all-day runtime viability. |
| Dealer Network Maintenance Unbundling | Subscription-based service contracts compress replacement cycles and capture software refresh revenue. |
Research Methodology
A standing panel of commercial landscaping fleet managers, residential dealer network owners, battery procurement leads at Midwest OEMs, and EPA compliance officers provided ongoing calibration across primary fieldwork. Secondary validation drew from EPA Clean Air Act filings, CARB equipment certification databases, SEC 10-K disclosures from listed machinery manufacturers, and customs import records for lithium-ion cell shipments. Bottom-up unit shipment modeling triangulated against top-down revenue estimates from distributor channel audits.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation modeling incorporated powertrain technology, end-user category, property size tier, and regional regulatory cluster dimensions. CAGRs derived from historical shipment trajectories adjusted for lithium-ion cost curve slopes and CARB mandate implementation timelines. Industry-specific inputs included battery pack watt-hour pricing trends and commercial fleet replacement cycle surveys.
The analysis sits within stated boundaries; outcomes outside sustained IRA incentive continuity or cobalt supply stability would require recalibration. Forecasts reflect assumptions regarding EPA Tier 4 enforcement intensity and solid-state battery prototyping schedules. Recalibration cycles align with material shifts in CARB mandate expansion or lithium-ion cell import tariff adjustments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Machinery
Hydrogen Powered Tractor Market
Agricultural Machinery
Global Crop Harvesting Robots Market
Agricultural Machinery
Asia-Pacific Agricultural Machinery Market
Agricultural Machinery
Orchard Type Tractors Market
Agricultural Machinery
Europe Agricultural Machinery Market
Agricultural Machinery
Agricultural Haying and Forage Machinery Market
Agricultural Machinery
South America Agricultural Sprayers Market
Agricultural Machinery
Agriculture Sprayers Market
Agricultural Machinery
North America Agricultural Tractors Machinery Market
Agricultural Machinery
Farm Tractor Market
Agricultural Machinery
South America Agricultural Machinery Market
Agricultural Machinery
Brazil Agricultural Tractors Market
Agricultural Machinery
Agriculture Tire Market
Agricultural Machinery
Europe Utility Tractor Market
Agricultural Machinery
Garden and Orchard Tractors Market
Agricultural Machinery
North America Agricultural Sprayers Market