
 United States Grain Storage Silos Market | 2026-2036
United States Grain Storage Silos Market Size, Share, and Industry Trends Forecast 2026-2036
United States Grain Storage Silos Market Insights
OSHA grain handling standards compliance is bifurcating the competitive landscape between certified national suppliers and regional fabricators. AGI leverages its vertical integration across handling equipment and storage systems to sustain pricing power across the Midwest. Sukup Manufacturing anchors its position through deep manufacturing scale in Sheffield, Iowa, while Brock Grain Systems differentiates via engineered solutions for large commercial elevators.
Grain storage silos are cylindrical or rectangular structures designed to protect harvested cereals from moisture, pests, and temperature fluctuation, typically fabricated from galvanized steel with aeration floors and temperature monitoring systems to preserve germination quality and food-grade integrity. Steel vertical silos dominate the installed base due to their structural efficiency and compatibility with automated loading systems, while modular silo configurations represent the fastest-expanding category as mid-size farms retrofit existing operations without greenfield construction. Concrete bunker silos retain share in feed-grain applications where anaerobic preservation of high-moisture corn drives specifications.
OSHA, the USDA, and the EPA collectively govern worker safety, commodity reserve programs, and environmental permitting for silo construction and fumigation practices, with OSHA's grain handling standards directly mandating confined-space protocols that elevate equipment specification requirements. The USDA's Farm Service Agency storage facility loans shape producer capital deployment cycles by subsidizing on-farm capacity additions. Stakeholders must monitor evolving EPA air-quality permits for fumigant emissions as regulatory stringency tightens around phosphine and sulfuryl fluoride application protocols in commercial facilities.
Market Dynamics
OSHA grain handling standards compliance is bifurcating the competitive landscape between certified national suppliers and regional fabricators. The USDA's conservation programs and Farm Bill storage incentives are reshaping producer investment timelines across the Corn Belt.
Growth Catalysts
- USDA Farm Service Agency storage facility loans:Subsidized on-farm capacity additions accelerate capital deployment cycles for mid-size agricultural producers in Iowa and Illinois.
- Commercial elevator consolidation:Large-scale grain handlers in Nebraska and Kansas are expanding steel silo capacity to capture economies of scale in corn and soybean logistics.
- Galvanized steel aeration systems:Temperature monitoring integration preserves germination quality and extends storage windows for food-grade cereals.
Market Restraints
- Zinc-coated steel price volatility:Input cost fluctuations compress margins for fabricators dependent on galvanized sheet metal supply chains.
- EPA air-quality permitting delays:Fumigant emission restrictions around phosphine and sulfuryl fluoride extend project approval timelines for commercial facilities.
- Concrete bunker silo substitution:Anaerobic preservation systems retain share in feed-grain applications where high-moisture corn specifications dominate.
Strategic Opportunities
- Modular silo configurations:Retrofit-ready designs enable mid-size farms to expand capacity without greenfield construction across Minnesota and Indiana.
- Automated loading system integration:Robotics convergence with vertical steel silos reduces labor dependency and elevates throughput for commercial elevators.
- Conservation Reserve Program incentives:Environmental set-aside policies create storage infrastructure demand in buffer zones surrounding protected acreage.
Industry Challenges
- Confined-space safety certification:OSHA-mandated worker training programs create talent pipeline constraints for installation and maintenance crews.
- Legacy concrete silo integration:Hybrid system architectures complicate temperature monitoring standardization across multi-vendor installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Grain Storage Silos Market |
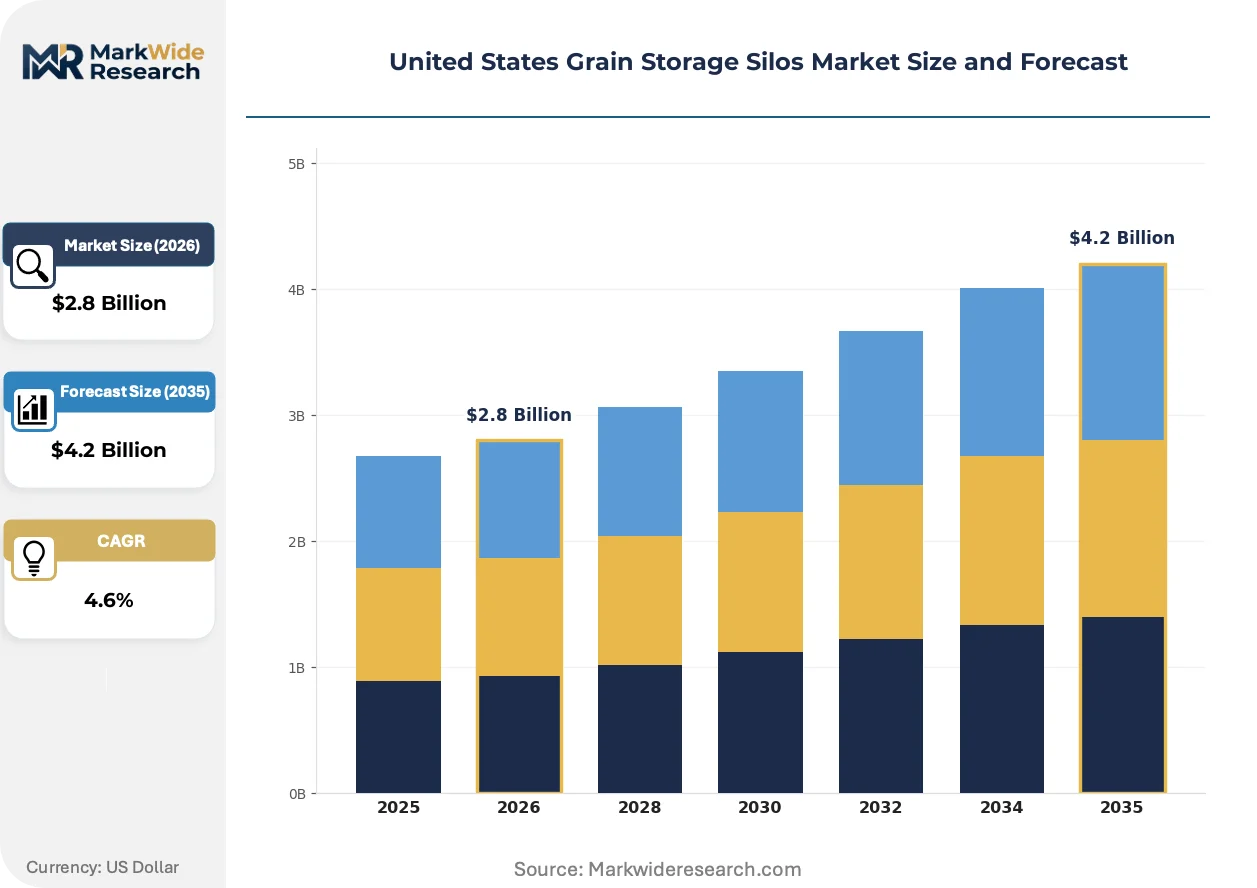
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.2 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vertical Silos, Horizontal Silos, Bunker Silos, Modular Silos Material: Steel, Concrete, Plastic, Fiberglass Storage Capacity: Small Scale, Medium Scale, Large Scale, Custom Size End User: Agricultural Producers, Grain Merchants, Food Processors, Exporters |
| Companies Covered | AGI (Ag Growth International Inc.), GSI (Grain Systems, Inc. – a brand of AGCO Corporation), Sukup Manufacturing Co., Brock Grain Systems (CTB, Inc.), Meridian Manufacturing Inc., Behlen Manufacturing Company, Chief Industries, Inc., SCAFCO Grain Systems Co., Sioux Steel Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Grain Storage Silos Market Trends and Innovations
Digital sensor networks and predictive maintenance platforms are transforming how grain handlers manage moisture and temperature risk across distributed storage assets.
Wireless grain condition monitoring systems with cloud-based analytics are displacing manual probing and periodic inspection routines. Commercial elevators in Iowa and Illinois are adopting these platforms fastest, driven by insurance premium reductions and quality-loss prevention. The technology is displacing legacy thermocouple installations that require physical cable runs through silo walls.
OSHA's updated grain handling standards mandate continuous atmosphere monitoring inside confined spaces. The regulation forces capital upgrades to ventilation and gas detection equipment across facilities built before 2010. Smaller regional fabricators in the Dakotas face the steepest compliance burden relative to their technical service capacity.
Service unbundling separates equipment supply from installation and multi-year maintenance contracts. Large agricultural producers in Nebraska now procure steel silos directly from manufacturers while contracting specialized rigging firms for erection. This pattern concentrates most visibly among operations exceeding 5,000 acres of corn and soybean cultivation.
United States Grain Storage Silos Market Segmentation
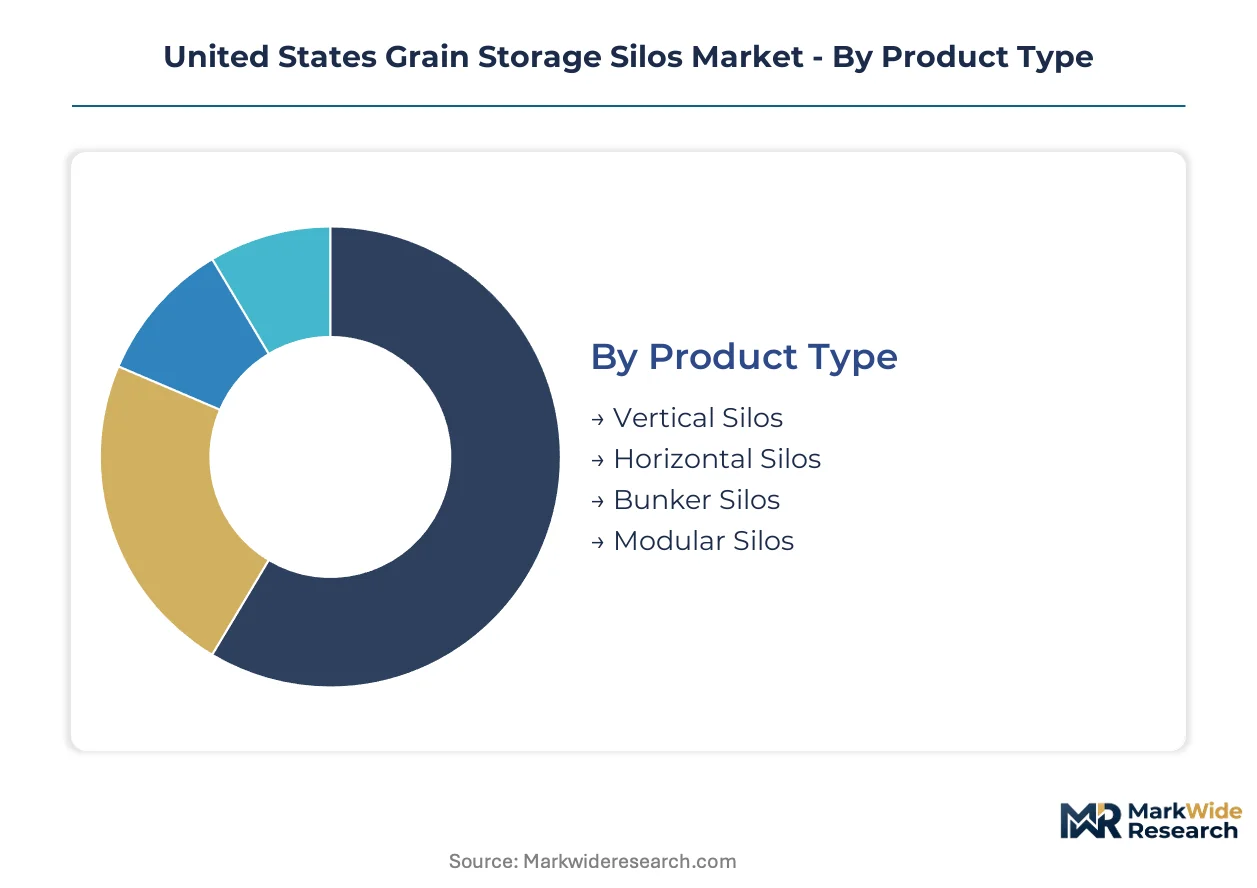
Grain storage silo procurement patterns diverge sharply between domestic Corn Belt operations and export-oriented Gulf Coast facilities. Each segment category carries distinct geographic signatures that reshape supplier go-to-market strategies across the Midwest.
Product Type:
Domestic grain handlers favor vertical configurations for space efficiency, while export terminals prioritize throughput-optimized horizontal systems.
- Vertical Silos:Galvanized steel cylindrical structures dominate the installed base across Iowa and Illinois farm operations. Corn Belt elevators specify these for automated loading compatibility and structural efficiency in high-wind zones.
- Horizontal Silos:Low-profile concrete or steel configurations serve feed-grain operations in Nebraska and Kansas where high-moisture corn preservation demands anaerobic conditions. Gulf Coast export terminals specify these for rapid vessel loading.
- Bunker Silos:Earth-banked concrete wall systems retain share in dairy-dense Wisconsin and Minnesota regions.
- Modular Silos:Prefabricated bolted-steel units enable retrofit expansion without greenfield permitting delays.
Vertical silos hold the largest share; momentum sits with modular configurations.
Material:
Cost tiers separate premium corrosion-resistant specifications from commodity-grade alternatives in producer procurement decisions.
- Steel:Zinc-coated galvanized sheet metal constitutes the dominant fabrication material across commercial elevators. Nebraska and Iowa fabricators source from domestic steel mills to hedge import price volatility.
- Concrete:Cast-in-place or precast systems anchor permanent installations where 30-year depreciation schedules justify higher upfront capital. Dairy operations in Wisconsin specify concrete for bunker silo walls.
- Plastic:Polyethylene tanks serve specialty seed storage and small-scale organic operations.
- Fiberglass:Corrosion-resistant composite materials penetrate coastal applications with salt-air exposure.
Steel dominates volume; fiberglass posts the steepest expansion trajectory in corrosion-critical environments.
Storage Capacity:
Farm scale dictates capacity selection, with USDA loan thresholds bifurcating mid-size from large-scale producer segments.
- Small Scale:Sub-5,000 bushel units serve specialty crop producers and organic operations in Minnesota's Red River Valley. These configurations bypass commercial elevator fees but require on-farm handling equipment.
- Medium Scale:5,000 to 50,000 bushel systems capture the fastest expansion among Corn Belt farms consolidating from 1,000 to 3,000 acres. USDA Farm Service Agency storage facility loans accelerate adoption in this tier.
- Large Scale:Commercial elevator specifications exceed 500,000 bushel single-site capacity.
- Custom Size:Engineered configurations address irregular site constraints or hybrid grain-livestock operations.
Medium scale commands the fastest growth; large scale retains the revenue concentration.
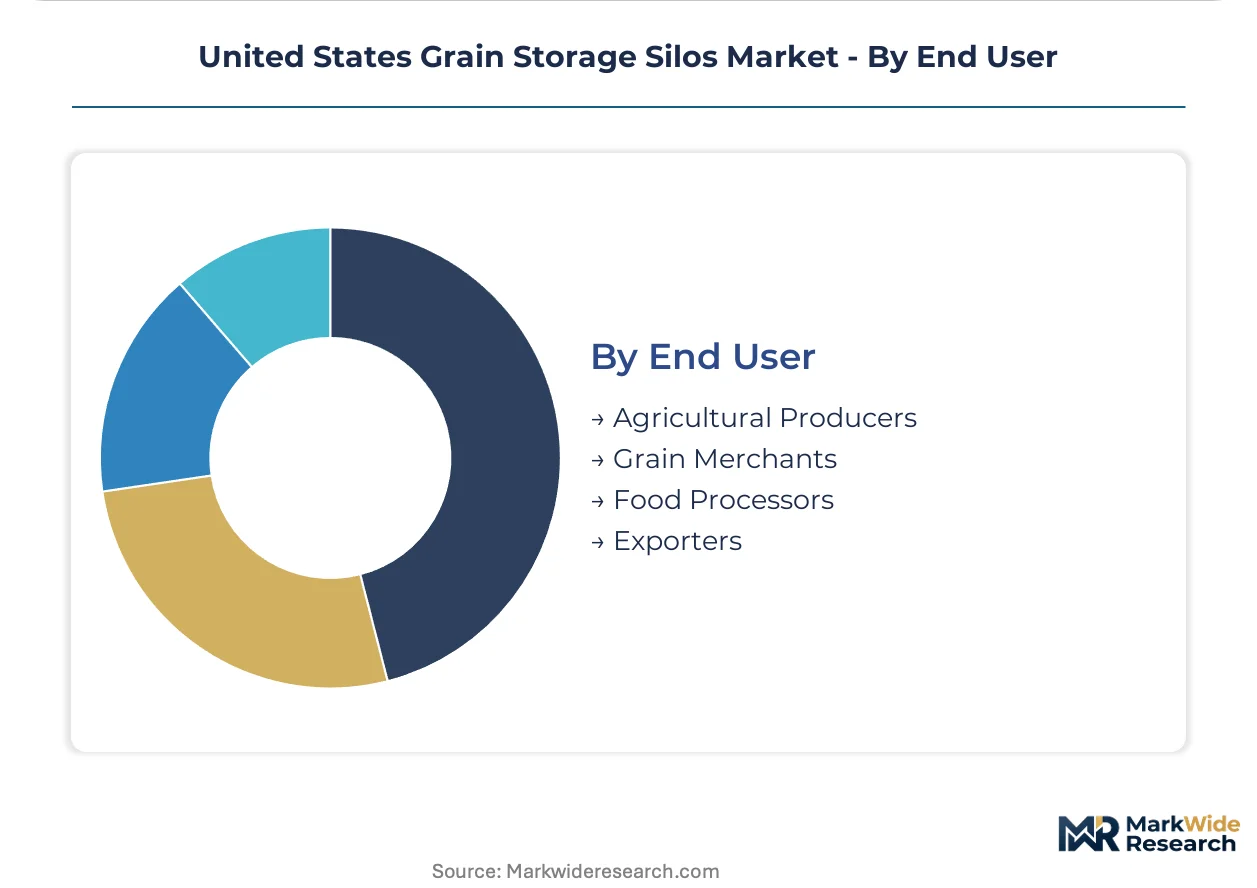
End User:
Customer type determines specification rigor, with food-grade exporters imposing certification standards far exceeding on-farm storage requirements.
- Agricultural Producers:Corn and soybean growers across Iowa, Illinois, and Nebraska invest in on-farm capacity to capture basis improvements and marketing flexibility. These operators prioritize aeration systems and temperature monitoring over structural complexity.
- Grain Merchants:Independent elevator operators in Kansas and the Dakotas consolidate origination volume for rail shipment to Gulf and Pacific Northwest export terminals. Their specifications emphasize throughput velocity and fumigation compatibility.
- Food Processors:Milling operations impose food-grade integrity standards with traceability documentation.
- Exporters:Gulf Coast and Pacific Northwest terminal operators specify maximum single-site capacity with vessel-loading automation.
Agricultural producers represent the volume anchor; exporters drive specification escalation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The USDA's Farm Service Agency storage facility loans are accelerating capital deployment across the Corn Belt, reshaping regional investment patterns in Iowa, Illinois, and Nebraska where elevator consolidation and on-farm expansion coincide.
Iowa
Corn and soybean basis improvements drive on-farm storage investment across 1,000-3,000 acre operations. USDA conservation programs incentivize capacity additions in buffer zones surrounding protected acreage. Sheffield anchors manufacturing concentration where deep fabrication scale supports regional supply chains.
Illinois
Commercial elevator operators consolidate origination volume for rail shipment to Gulf export terminals. OSHA grain handling standards elevate equipment specification requirements for facilities built before 2010. Peoria and Decatur clusters concentrate food-grade milling operations with traceability documentation demands.
Nebraska
Large-scale grain handlers expand steel silo capacity to capture economies of scale in corn and soybean logistics. Farm Bill storage incentives compress producer investment timelines across the western Corn Belt. Omaha and Lincoln metro areas anchor distribution networks for modular retrofit configurations.
Kansas
Independent elevator operators prioritize throughput velocity and fumigation compatibility for Pacific Northwest export corridors. EPA air-quality permitting delays around phosphine emissions extend project approval timelines. Wichita serves as a procurement hub for mid-size farms transitioning to automated loading systems.
Minnesota
Dairy-dense regions retain concrete bunker silo share for anaerobic high-moisture corn preservation. Red River Valley specialty crop producers deploy sub-5,000 bushel units to bypass commercial elevator fees. Twin Cities logistics clusters support service unbundling between equipment supply and specialized rigging contractors.
United States Grain Storage Silos Market Competitive Landscape
Player mix skews toward vertically integrated national suppliers and specialized regional fabricators. OSHA certification requirements bifurcate the competitive landscape, elevating compliance burdens for smaller Dakotas-based operators. Three strategic archetypes dominate: full-system integrators with handling equipment portfolios, manufacturing-scale specialists with captive fabrication assets, and engineering-driven providers of large commercial elevator solutions. Capacity expansion and service unbundling represent the dominant competitive moves, with producers above 5,000 acres increasingly procuring directly from manufacturers while contracting specialized erection firms.
Among Iowa-based manufacturers, Sukup Manufacturing Co. anchors the manufacturing-scale specialist archetype through its Sheffield concentration. AGI (Ag Growth International Inc.) represents the full-system integrator model with vertical integration across handling equipment and storage systems. Brock Grain Systems (CTB, Inc.) occupies a position exemplifying the engineering-driven commercial elevator segment. These three entities illustrate the competitive structure without exhausting its composition.
| Leading Market Players |
|---|
| AGI (Ag Growth International Inc.) |
| GSI (Grain Systems, Inc. – a brand of AGCO Corporation) |
| Sukup Manufacturing Co. |
| Brock Grain Systems (CTB, Inc.) |
| Meridian Manufacturing Inc. |
| Behlen Manufacturing Company |
| Chief Industries, Inc. |
| SCAFCO Grain Systems Co. |
| Sioux Steel Company |
| Others |
Pricing and Supply Chain Analysis
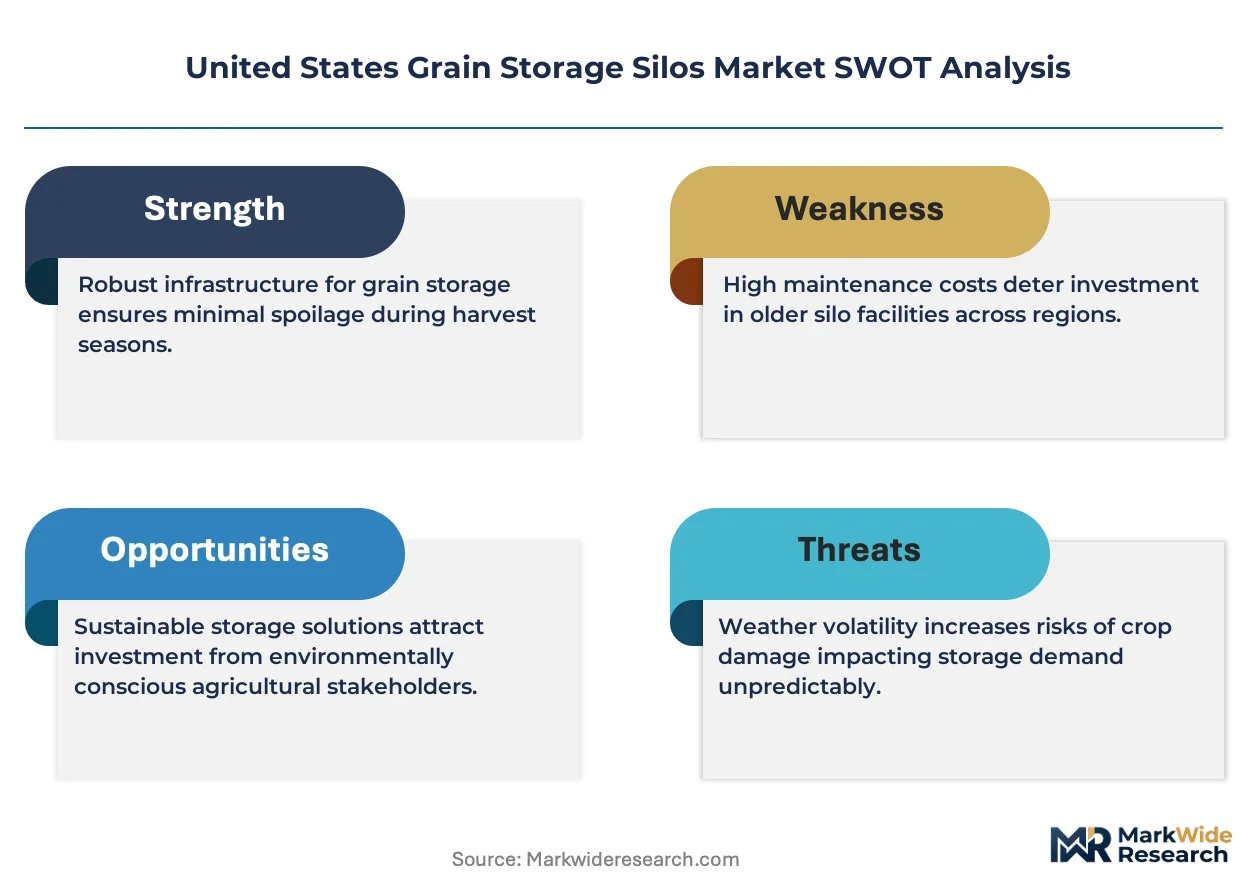
OSHA grain handling standards certification gates both supplier qualification and price differentiation simultaneously across the US grain storage silos market, bifurcating fabricators into OSHA-compliant national suppliers commanding premium positioning versus uncertified regional operators competing on raw material cost.
Pricing Analysis
Certification level (OSHA-compliant versus non-compliant) creates the primary spread between premium and economy tiers across the installed base. Pricing stratifies across three levels: OSHA-certified systems with continuous atmosphere monitoring, standard galvanized configurations with basic aeration, and economy bolted-steel units without integrated sensors. Cost compression in the economy tier is intensifying because zinc-coated steel price volatility compresses fabricator margins. Mid-size agricultural producers in Iowa and Illinois exhibit the highest price sensitivity, while Gulf Coast export terminals prioritize specification compliance over unit cost.
Supply Chain Analysis
Domestic steel mills in Indiana, Ohio, and Pennsylvania anchor galvanized sheet metal supply for Corn Belt fabricators. Raw material flows draw from zinc mining operations in Alaska and Tennessee, plus hot-rolled coil production centered on the Great Lakes region. Single-source vulnerability concentrates in specialized aeration floor components sourced from limited Midwest metalworking clusters. Distribution runs through manufacturer-direct channels for large producers above 5,000 acres, while regional dealer networks serve smaller farm operations across Minnesota and Wisconsin.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US grain storage silos market is entering a cyclical recovery phase as USDA Farm Service Agency storage facility loans compress producer investment timelines and accelerate capital deployment across the Corn Belt.
For Market Incumbents: Consolidate manufacturing scale in Sheffield, Iowa and adjacent Corn Belt fabrication clusters to defend against modular silo entrants from regional metalworking shops. Deepen backward integration into galvanized steel coil supply through captive relationships with Indiana and Ohio mills. Prioritize OSHA certification maintenance as a barrier against uncertified Dakotas-based competitors facing compliance burden escalation. For New Entrants and Emerging Players: Lead with wireless grain condition monitoring system integration as a differentiated service layer atop commodity bolted-steel hardware. Target Minnesota and Wisconsin dairy operations where concrete bunker silo substitution creates retrofit white space. Pursue service unbundling contracts with specialized rigging firms to bypass captive installation capabilities of incumbent manufacturers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across modular silo configurations as prefabrication reduces field labor dependency. Long-term viability favors manufacturers with captive fabrication assets and established OSHA compliance infrastructure rather than pure-play technology licensors. Monitor EPA air-quality permitting velocity around phosphine fumigant restrictions as the signal indicating regulatory-driven consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Configuration Expansion | Enables mid-size farms to retrofit capacity without greenfield construction delays across Indiana. |
| Automated Loading System Integration | Reduces labor dependency for Nebraska commercial elevators facing OSHA confined-space training constraints. |
| Wireless Monitoring Platform Deployment | Displaces legacy thermocouple installations while capturing insurance premium reductions for Iowa handlers. |
| Galvanized Steel Supply Backward Integration | Hedges zinc-coated sheet metal price volatility through captive relationships with Great Lakes mills. |
| OSHA Certification Maintenance Investment | Preserves pricing power against uncertified regional fabricators in the Dakotas facing compliance burden. |
Research Methodology
The analysis maps vertical silo, horizontal silo, bunker silo, and modular silo sub-sectors, each validated through elevator operations managers, agricultural producer procurement officers, and grain merchant logistics directors. Primary interviews with USDA Farm Service Agency lending officers, OSHA compliance consultants, and galvanized steel procurement leads at Midwest fabricators combined with secondary validation from USDA commodity reports, EPA air-quality permit databases, and SEC filings from publicly traded handling equipment manufacturers. Bottom-up capacity installation tallies triangulated against top-down Farm Bill incentive allocation estimates.
External benchmark consistency checks validated volume and value outputs against USDA grain storage capacity surveys and state-level agricultural census data across the projection horizon. Segmentation dimensions modeled include product type, material specification, storage capacity tier, and end-user category with geographic clustering by Corn Belt state. CAGRs derived from historical capacity addition patterns correlated with Farm Bill funding cycle phasing and corn-soybean basis improvement trajectories.
Forecasts assume regulatory continuity in OSHA grain handling standards and EPA fumigant emission protocols; material policy shifts would require re-modeling. Specific risks that could revise projections include accelerated phosphine restriction implementation, galvanized steel tariff adjustments, and Farm Bill storage incentive cancellation. Recalibration cycles align with material shifts in USDA conservation program funding and OSHA enforcement priority announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Equipment
Cordless Sprayer Market
Agricultural Equipment
Food Bucket Elevators Market
Agricultural Equipment
Flexible Silos Market
Agricultural Equipment
Billhook Market
Agricultural Equipment
Oil Expellers Market
Agricultural Equipment
Global Yield Monitoring Devices Market
Agricultural Equipment
Pre-Harvest Equipment Market
Agricultural Equipment
Tree Transplanters Market
Agricultural Equipment
Floating Covers Market
Agricultural Equipment
Fishing Net Market
Agricultural Equipment
Smart Rice Transplanter Market
Agricultural Equipment
Gardening Tools Market
Agricultural Equipment
India Color Sorter Market
Agricultural Equipment
Tree Trimmers Market
Agricultural Equipment
Battery Powered Sprayer Market
Agricultural Equipment
Bulk Reception Feeder Market