
 Forage Market | 2026-2036
Forage Market Size, Share, and Industry Trends Forecast 2026-2036
Forage Market Intelligence
The EU Green Deal's Farm to Fork Strategy is expanding compliance requirements for livestock feed sourcing across European dairy supply chains. Cargill Incorporated leverages its grain-forage procurement networks to secure contracted acreage in the Upper Midwest. DLF Pickseed specializes in perennial ryegrass and alfalfa breeding programs that sustain varietal performance under drought stress.
Forage encompasses preserved and fresh plant material—primarily grasses, legumes, and cereal crops harvested at optimal moisture and nutritional stages for ruminant consumption. The feedstuff typically contains 15-25% crude protein in legume varieties and 8-12% in grass types, with acid detergent fiber levels determining digestibility and energy availability for dairy and beef production. Silage dominates value capture due to anaerobic fermentation requirements and capital-intensive storage infrastructure, while legume mixtures command margin premiums from organic dairy cooperatives seeking non-GMO protein sources. Hay retains volume leadership in equine and small ruminant channels where long-stem fiber supports digestive health.
The USDA's Natural Resources Conservation Service shapes forage demand through Environmental Quality Incentives Program payments for cover crop-to-forage transitions. EPA nutrient management rules and state-level confined animal feeding operation permits constrain manure-to-forage nutrient cycling practices. Stakeholders must monitor evolving carbon credit protocols for perennial pasture systems and their interaction with existing conservation program structures.
Market Dynamics
The EU Green Deal's Farm to Fork Strategy is compressing input-intensive crop systems and accelerating certified grass-legume mixture adoption across European dairy supply chains. Processor sustainability audits now mandate documented pasture-based feeding ratios, restructuring procurement relationships between livestock operations and forage suppliers.
Growth Catalysts
- Environmental Quality Incentives Program:USDA's Natural Resources Conservation Service incentivizes cover crop-to-forage transitions across the United States Corn Belt, expanding perennial pasture acreage.
- Organic dairy cooperatives:Non-GMO protein sourcing mandates from certified organic processors create margin premiums for legume mixture producers meeting varietal purity standards.
- Silage infrastructure investment:Capital-intensive anaerobic fermentation and storage systems capture value through reduced dry matter loss and extended feed availability windows.
Market Restraints
- Input cost volatility:Fertilizer and fuel price swings compress margins for grass hay producers dependent on diesel-dependent mowing and baling operations.
- Supply concentration risk:Seed genetics for drought-tolerant alfalfa varieties concentrate among narrow breeding program pipelines, creating varietal vulnerability.
- Regulatory friction:EPA nutrient management rules constrain manure-to-forage nutrient cycling on confined animal feeding operations, limiting closed-loop efficiency.
Strategic Opportunities
- Carbon credit protocols:Emerging verification frameworks for perennial pasture systems enable new revenue streams from soil carbon sequestration.
- Integrated livestock-crop operations:Silage-to-feed ratio optimization creates captive demand channels bypassing commodity hay markets.
- Equine nutrition segment:Long-stem fiber requirements for digestive health sustain premium pricing outside ruminant commodity channels.
Industry Challenges
- Agronomic skill scarcity:Optimal harvest timing for moisture and nutritional stages requires specialized knowledge in short weather windows.
- Certification timeline compression:Organic and non-GMO verification processes delay market access during peak seasonal demand periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Forage Market |
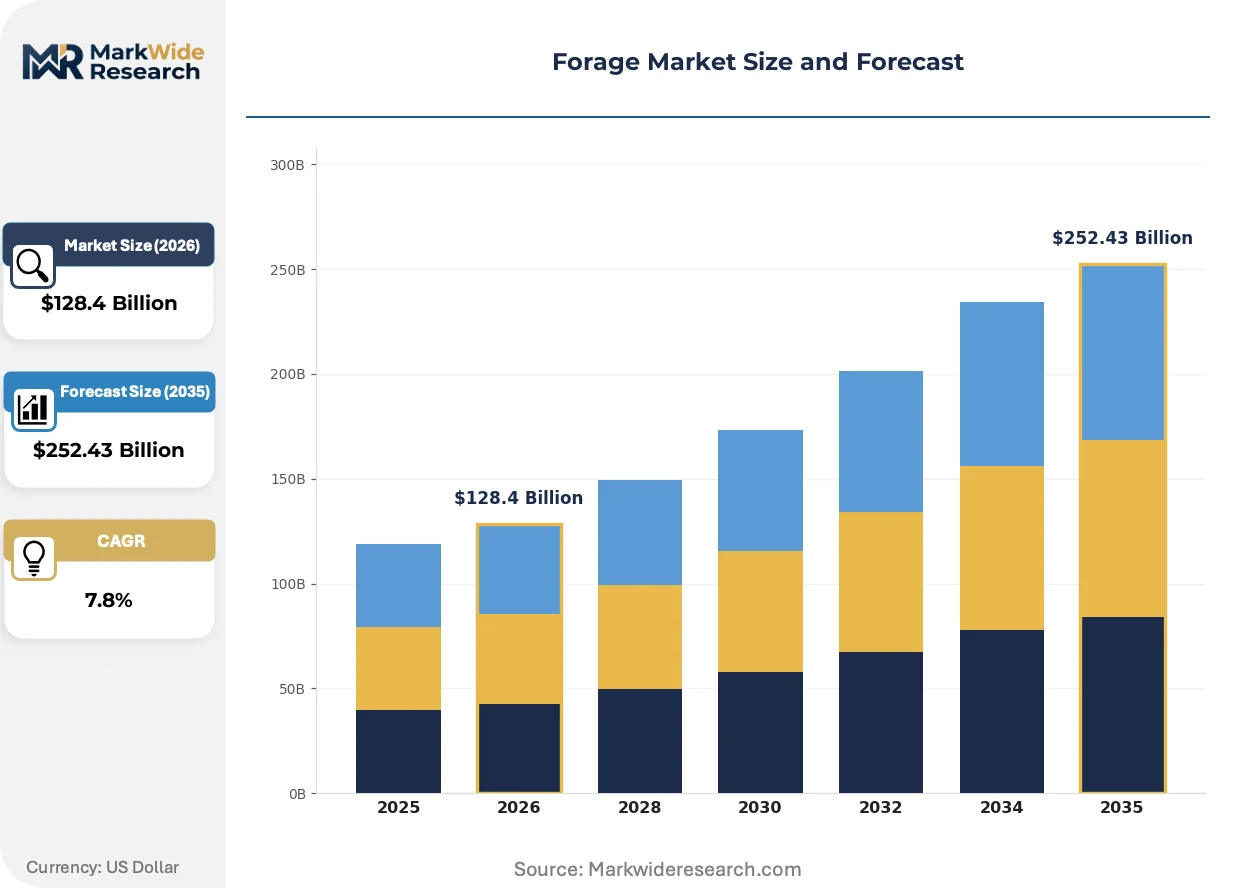
| Market Size in 2026 | $128.4 Billion |
| Market Size in 2035 | $252.43 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Grass, Legume, Silage, Hay Use Case: Dairy Cattle, Beef Cattle, Sheep, Goats Distribution Channel: Direct Sales, Retail, Online, Wholesale Packaging Type: Bales, Bags, Bulk, Pellets |
| Companies Covered | Cargill Incorporated, Land O'Lakes, Inc., Corteva Inc., Forage Genetics International LLC, Barenbrug USA, Standlee Premium Products LLC, DLF Pickseed, BrettYoung, King's Agriseeds Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Forage Market Strategic Shifts & Innovations
Precision fermentation monitoring and near-infrared spectroscopy are compressing quality variance in silage production. Breeders now select for drought-stress tolerance and protein stability under shifting precipitation patterns.
Near-infrared spectroscopy platforms for real-time moisture and nutritional analysis during harvest operations are consolidating quality control into fewer, larger forage operations. Dairy cooperatives in the Upper Midwest deploy these systems to enforce contracted protein specifications. The technology is consolidating regional supplier bases by disqualifying small-scale producers lacking capital for spectral verification equipment.
EU Green Deal compliance deadlines are forcing rapid reconfiguration of crop input registries across member state agricultural ministries. The Farm to Fork Strategy's 50% pesticide reduction target accelerates legume mixture substitution for nitrogen-intensive grass monocultures. French and German dairy processors now require documented legume percentages in contracted forage volumes, reshaping seed procurement patterns.
Long-term contracting between integrated livestock-crop operations and dairy processors is displacing spot-market hay transactions. Wisconsin and Minnesota operations lock in three-to-five-year silage supply agreements with protein floors and moisture penalties. This shift is most visible in the United States Corn Belt, where processor sustainability audits demand traceable feed sourcing documentation.
Forage Market Segmentation
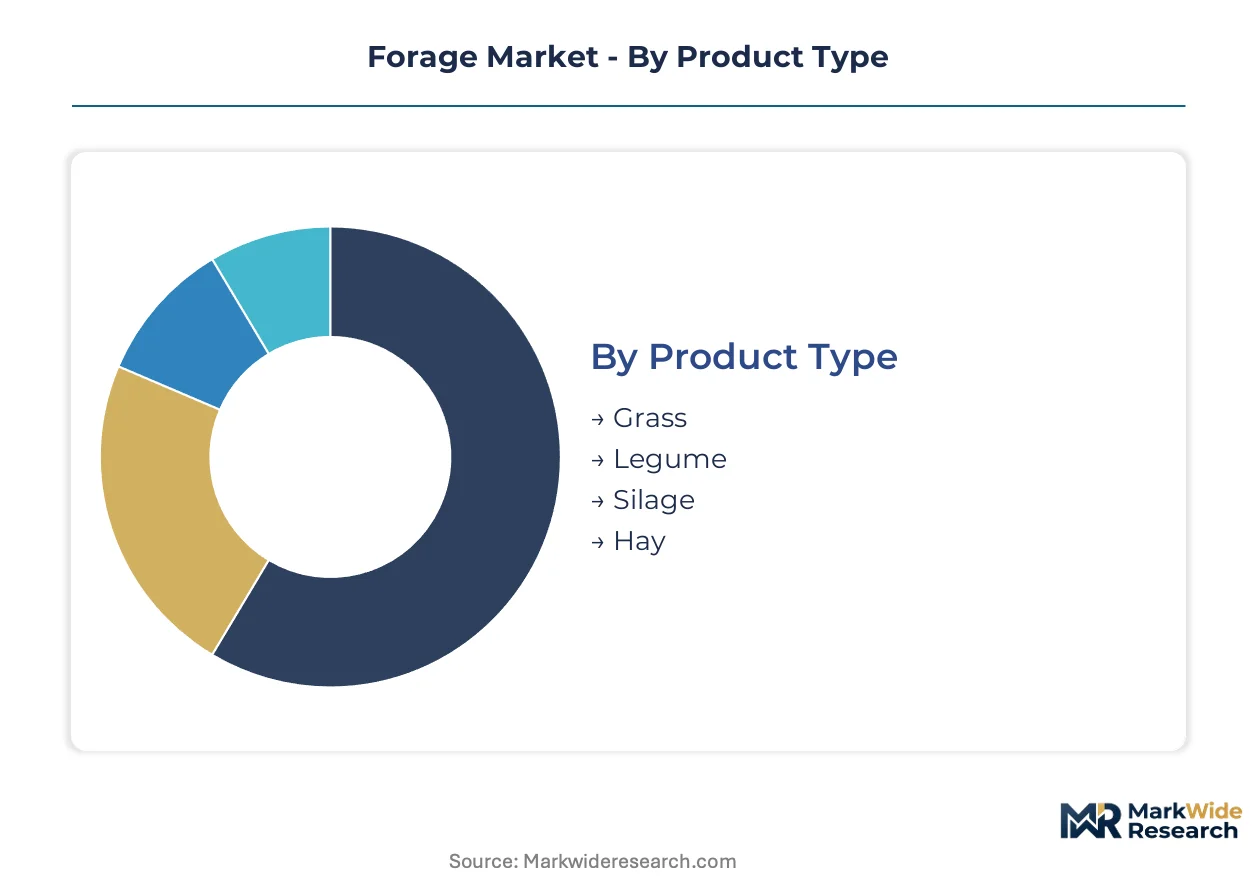
Forage purchasing decisions hinge on nutritional specifications, storage infrastructure, and livestock category requirements. Dairy processors enforce protein thresholds that reshape supplier segmentation. Each dimension reveals distinct margin structures and captive demand channels.
Product Type:
Buyers prioritize crude protein content and acid detergent fiber levels when selecting feedstock for specific ruminant classes.
- Grass:Delivers 8-12% crude protein with higher fiber content suited to maintenance rations. Beef cattle finishing operations in the United States Corn Belt source Timothy and orchard grass varieties for cost-efficient weight gain protocols.
- Legume:Alfalfa and clover mixtures achieve 15-25% crude protein with superior digestibility. Organic dairy cooperatives in Wisconsin and Minnesota mandate documented legume percentages for non-GMO protein verification.
- Silage:Anaerobic fermentation preserves moisture and nutritional value for extended feed windows. Capital-intensive bunker silos and oxygen-limiting structures dominate value capture in integrated livestock-crop operations.
- Hay:Dried long-stem fiber supports equine digestive health and small ruminant maintenance. Premium pricing persists outside commodity dairy channels where stem length determines palatability.
Volume sits with Grass; growth tilts toward Legume.
Use Case:
Species-specific nutritional requirements and processor audit standards segment demand by livestock category.
- Dairy Cattle:High-producing herds require 16-18% dietary protein from legume-dominant mixtures. EU Green Deal Farm to Fork compliance deadlines force rapid pasture-based feeding ratio documentation across French and German processor supply chains.
- Beef Cattle:Finishing operations optimize silage-to-grain ratios for marbling and feed conversion efficiency. Upper Midwest feedlots contract directly with corn-soybean operations for integrated forage sourcing.
- Sheep:Smaller rumen capacity demands higher-quality fiber with lower moisture content. Flock operations in New Zealand and Australia concentrate demand for compressed hay exports.
- Goats:Browsing behavior and copper sensitivity require tailored mineral supplementation. Niche producers in Texas and California sustain premium pricing for browse-compatible legume mixtures.
Revenue concentrates in Dairy Cattle; margin expansion favors Beef Cattle.
Distribution Channel:
Supply chain configuration determines price realization and quality verification capabilities.
- Direct Sales:Long-term contracting between integrated operations and processors eliminates intermediary margins. Wisconsin dairies lock in three-to-five-year silage agreements with protein floors and moisture penalties.
- Retail:Farm supply cooperatives and agricultural merchants serve small-scale producers lacking procurement scale. Storefront presence enables tactile quality assessment for hay buyers.
- Online:Digital platforms aggregate regional supply for equine and hobby farm segments. Spectral verification data accompanies listings to reduce quality uncertainty.
- Wholesale:Volume aggregators supply export markets and large confinement operations. Containerized logistics and phytosanitary certification dominate international shipment protocols.
Transaction volume flows through Wholesale; channel innovation centers on Direct Sales.
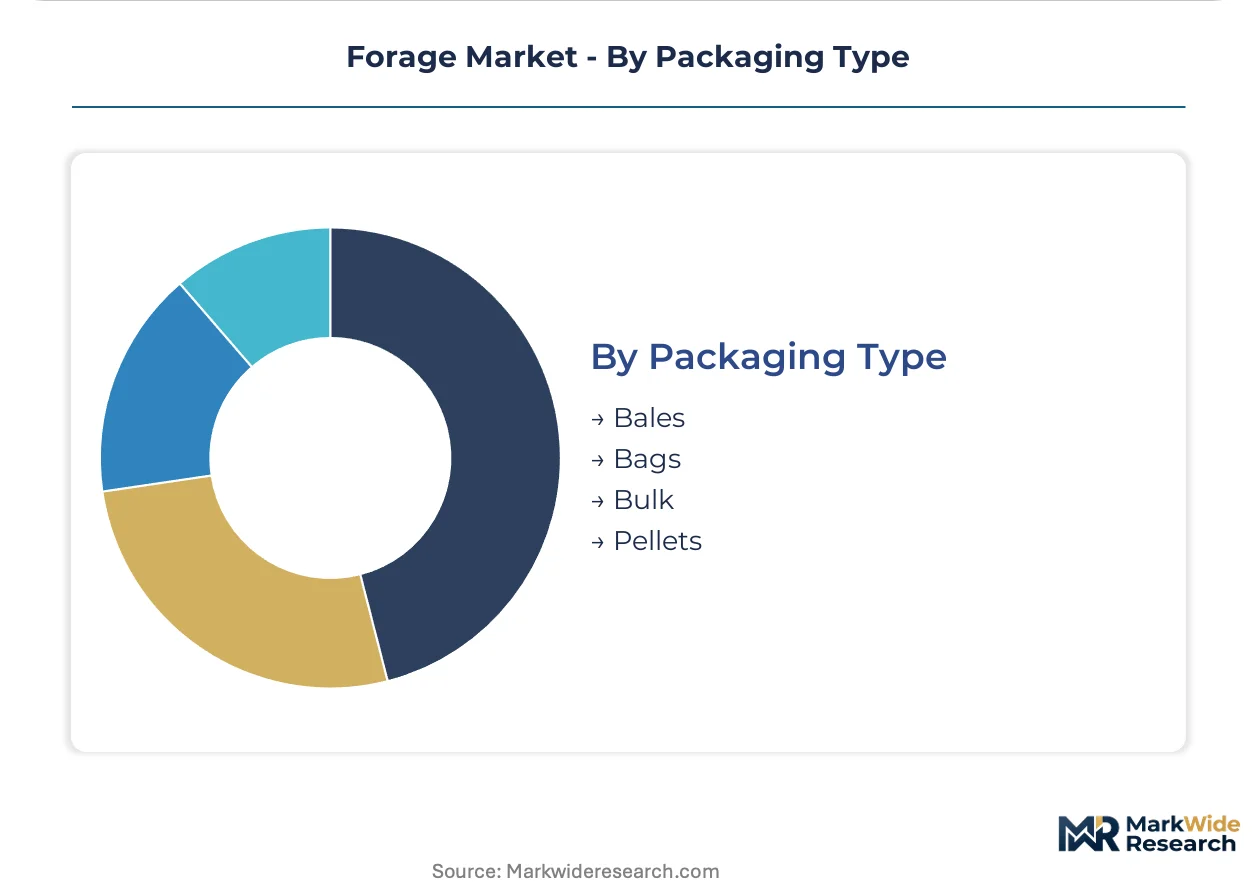
Packaging Type:
Handling equipment compatibility and storage constraints drive format selection.
- Bales:Small square and large round formats suit mechanical handling systems on mid-scale operations. Weather exposure risk necessitates covered storage investment.
- Bags:Compressed and chopped products enable precise ration mixing in automated feeding systems. Dairy operations in the Netherlands and Denmark favor bagged silage for robotic barn compatibility.
- Bulk:Loose delivery minimizes packaging cost for on-farm silage pits and bunker storage. Proximity requirements limit sourcing radius to 50-mile haul zones.
- Pellets:Densified format reduces transportation cost and enables mechanized feeding. Equine nutrition specialists in Kentucky and Florida specify pellet diameter for choke prevention.
Shipment volume favors Bulk; value per ton climbs fastest in Pellets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wisconsin's Fox River Valley anchors North American forage processing capacity, where integrated dairy cooperatives contract directly with corn-soybean operations for silage supply. European demand concentrates in the Netherlands' Gelderland province, where robotic barn systems drive bagged forage adoption. Australian exports flow through Melbourne's port infrastructure to Southeast Asian dairy markets.
United States
Integrated livestock-crop operations in Wisconsin and Minnesota lock in three-to-five-year silage agreements with protein floors and moisture penalties. The USDA's Environmental Quality Incentives Program incentivizes cover crop-to-forage transitions across the Corn Belt. Wisconsin's Fox River Valley hosts the densest concentration of anaerobic fermentation facilities serving Upper Midwest dairy processors.
Germany
French and German dairy processors now require documented legume percentages in contracted forage volumes under EU Green Deal compliance deadlines. The Farm to Fork Strategy's pesticide reduction targets accelerate legume mixture substitution for nitrogen-intensive grass monocultures. Bavaria's Allgäu region sustains premium hay production for equine export markets through specialized drying infrastructure.
Netherlands
Dairy operations in Gelderland and Overijssel provinces favor bagged silage for robotic barn compatibility and precise ration mixing. The country's national agricultural regulator enforces strict nutrient management protocols that constrain manure-to-forage cycling on intensive operations. Friesland's cooperative processing network demands spectral-verified protein specifications from contracted suppliers.
Australia
Flock operations in Victoria and New South Wales concentrate demand for compressed hay exports to Southeast Asian markets. The country's national biosecurity regulator mandates phytosanitary certification for all international forage shipments. Melbourne's port infrastructure handles containerized legume hay bound for dairy operations in Japan and South Korea.
France
Organic dairy cooperatives in Normandy mandate documented legume percentages for non-GMO protein verification under processor audit standards. The EU Green Deal's Farm to Fork Strategy compresses input-intensive crop systems across the Brittany dairy basin. The country's national agricultural ministry maintains crop input registries that accelerate certified grass-legume mixture adoption.
Forage Market Key Industry Players
Premium-margin players sit above commodity-margin players across seed genetics and processing infrastructure dimensions. The vendor base stratifies into three tiers: multinational grain traders with procurement networks, specialized seed breeders with varietal pipelines, and regional processors with storage assets. Strategic moves concentrate on long-term contracting structures and spectral verification technology deployment that disqualify small-scale suppliers.
Within the multinational trading tier, Cargill Incorporated and Land O'Lakes, Inc. occupy positions defined by grain-forage procurement scale and integrated livestock-crop relationships. Among specialized seed breeders, DLF Pickseed and Forage Genetics International LLC exemplify drought-tolerance breeding program concentration. These named entities represent archetypes rather than exhaustive market coverage.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Land O'Lakes, Inc. |
| Corteva Inc. |
| Forage Genetics International LLC |
| Barenbrug USA |
| Standlee Premium Products LLC |
| DLF Pickseed |
| BrettYoung |
| King's Agriseeds Inc. |
| Others |
Cost & Logistics Intelligence
Integrated livestock-crop operations in Wisconsin and Minnesota anchor pricing power through long-term silage contracting with protein floors and moisture penalties, displacing spot-market transactions across the Upper Midwest. This buyer concentration forces suppliers toward spectral verification investments that disqualify small-scale hay producers lacking capital for near-infrared spectroscopy platforms.
Pricing Analysis
Yield-linked protein premiums anchor value-based pricing for legume mixtures sold to organic dairy cooperatives. Three-tier pricing structure across premium, standard, and economy levels separates certified non-GMO legume blends from conventional grass hay and unverified bulk silage. Pricing pressure stems from fertilizer and fuel cost volatility compressing margins for diesel-dependent mowing and baling operations. Small-scale equine hay buyers exhibit highest price sensitivity, while robotic dairy barn operators in the Netherlands accept premium bagged silage rates for ration precision.
Supply Chain Analysis
Seed genetics for drought-tolerant alfalfa varieties rests on narrow breeding program pipelines concentrated in the United States, Denmark, and New Zealand. Propagation materials, specialized drying infrastructure, and phytosanitary certification capacity feed from regional agricultural equipment networks and cooperative processing facilities. Single-source vulnerability concentrates in proprietary perennial ryegrass germplasm controlled by limited breeders. Distribution runs through long-term contracting channels that bypass wholesale hay markets in favor of direct processor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The forage sector sits in a technology-transition phase where near-infrared spectroscopy and precision fermentation monitoring displace visual quality assessment and manual moisture testing. Legacy harvest timing decisions based on weather windows and field experience yield to real-time nutritional analytics that consolidate supplier bases.
For Market Incumbents: Deploy spectral verification technology as a competitive moat. Cargill Incorporated and Land O'Lakes leverage grain-forage procurement scale to lock in three-to-five-year silage agreements with protein floors, while DLF Pickseed accelerates drought-stress breeding programs to offset climate volatility threatening varietal performance. Incumbents must absorb certification timeline compression costs that delay organic and non-GMO market access during peak seasonal demand periods. For New Entrants and Emerging Players: The EU Green Deal's Farm to Fork Strategy in Europe opens a window for certified grass-legume mixture specialists. White-space targets include robotic barn-compatible bagged silage for Dutch and Danish dairy operations, and carbon credit protocol verification services for perennial pasture systems in France and Germany. Go-to-market positioning should emphasize documented legume percentages and traceable feed sourcing documentation demanded by processor sustainability audits. For Investors and Strategic Acquirers: The window for entry favors regional processors with storage assets and spectral verification capabilities. Long-term viability hinges on captive demand channels through integrated livestock-crop relationships rather than commodity hay exposure. Watch for carbon credit protocol maturation as an inflection indicator that would revalue perennial pasture acreage and reshape seed procurement patterns.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement | Three-to-five-year silage contracts with protein floors lock in Wisconsin and Minnesota dairy processor demand. |
| Backward Integration | Seed breeding programs for drought-tolerant alfalfa reduce varietal vulnerability to climate stress. |
| Technology Licensing | Near-infrared spectroscopy platforms consolidate regional supplier bases by disqualifying unverified producers. |
| Geographic Expansion | Upper Midwest storage asset deployment captures Environmental Quality Incentives Program cover crop-to-forage transitions. |
| Green Certification Program | Organic and non-GMO verification enables margin premiums from certified dairy cooperatives. |
Research Approach
Multi-period observation of silage infrastructure investment, seed breeding program pipelines, and processor sustainability audit requirements anchored the trend analysis, supplemented by interviews with dairy cooperative procurement managers, alfalfa seed breeders, robotic barn system integrators, and USDA Natural Resources Conservation Service program officers. Secondary validation drew from USDA Environmental Quality Incentives Program payment records, EU Farm to Fork Strategy implementation documents, SEC 10-K filings of listed agricultural companies, and customs data on compressed hay exports. Bottom-up acreage and volume estimates triangulated against top-down processor demand projections.
Segment-weighting across product type, use case, distribution channel, and packaging type dimensions structured the analytical framework over the projection horizon. CAGRs derived from fitted growth curves applied to historical acreage transitions, protein premium trajectories, and infrastructure investment cycles. Modeled inputs included silage-to-feed ratio optimization trends, robotic barn adoption rates in the Netherlands and Denmark, and EU pesticide reduction compliance timelines.
Caveats apply where EPA nutrient management rule revisions, carbon credit protocol verification delays, or seed genetics pipeline disruptions could materially shift the outlook. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Alfalfa Pellets Market
Agriculture and Agri Products
South Africa Alfalfa Hay Market
Agriculture and Agri Products
Kenya Floriculture Market
Agriculture and Agri Products
Beet Pulp Market
Agriculture and Agri Products
Asia-Pacific Poultry Meat Market
Agriculture and Agri Products
France Compound Feed Market
Agriculture and Agri Products
Canada Bamboos Market
Agriculture and Agri Products
Netherlands Floriculture Market
Agriculture and Agri Products
Sorghum by-Products Market
Agriculture and Agri Products
Taro Market
Agriculture and Agri Products
Algae-Based Animal Feed Market
Agriculture and Agri Products
Organic Farming Market
Agriculture and Agri Products
Global Vermicompost Market
Agriculture and Agri Products
LAMEA Rapeseed Oil Market
Agriculture and Agri Products
Alfalfa Hay Market
Agriculture and Agri Products
Forage Feed Market