
 Brazil Tractors Market | 2026-2036
Brazil Tractors Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Tractors Market Insights
Market Context
The Brazil tractors market is rebalancing between premium precision-agriculture platforms and commodity utility machines serving mid-size farms. Deere & Company leverages its integrated precision farming ecosystem to command the high-horsepower segment. CNH Industrial anchors its position through extensive dealer coverage across Brazil's interior states. AGCO competes via specialized row-crop configurations tailored to soybean-corn rotation systems.
Technical Definition and Segments
A tractor is a self-propelled power unit with a diesel or alternative-fuel engine generating torque through a drivetrain to pull or power agricultural implements, typically rated by engine horsepower and hydraulic lift capacity. Utility tractors and agricultural tractors dominate Brazil's volume base, though compact tractors serving diversified smallholdings in the South represent the fastest-expanding margin pool. Engine power segmentation shows medium-power units absorbing the bulk of replacement demand, while extra high power models concentrate in Mato Grosso and Goiás where field sizes exceed 500 hectares.
Regulatory Framework
ANVISA oversees operator safety standards and emissions compliance for agricultural machinery sold in Brazil, while the National Petroleum Agency regulates biofuel blending mandates that directly affect tractor engine calibration requirements. The Brazilian Institute of Environment and Renewable Natural Resources shapes deforestation monitoring protocols that influence mechanization patterns in frontier agricultural zones. Stakeholders must track how PROCONVE emission tier advancements and RenovaBio credit mechanisms will alter engine technology roadmaps and total cost of ownership calculations across Brazil's distinct farming regions.
Market Dynamics
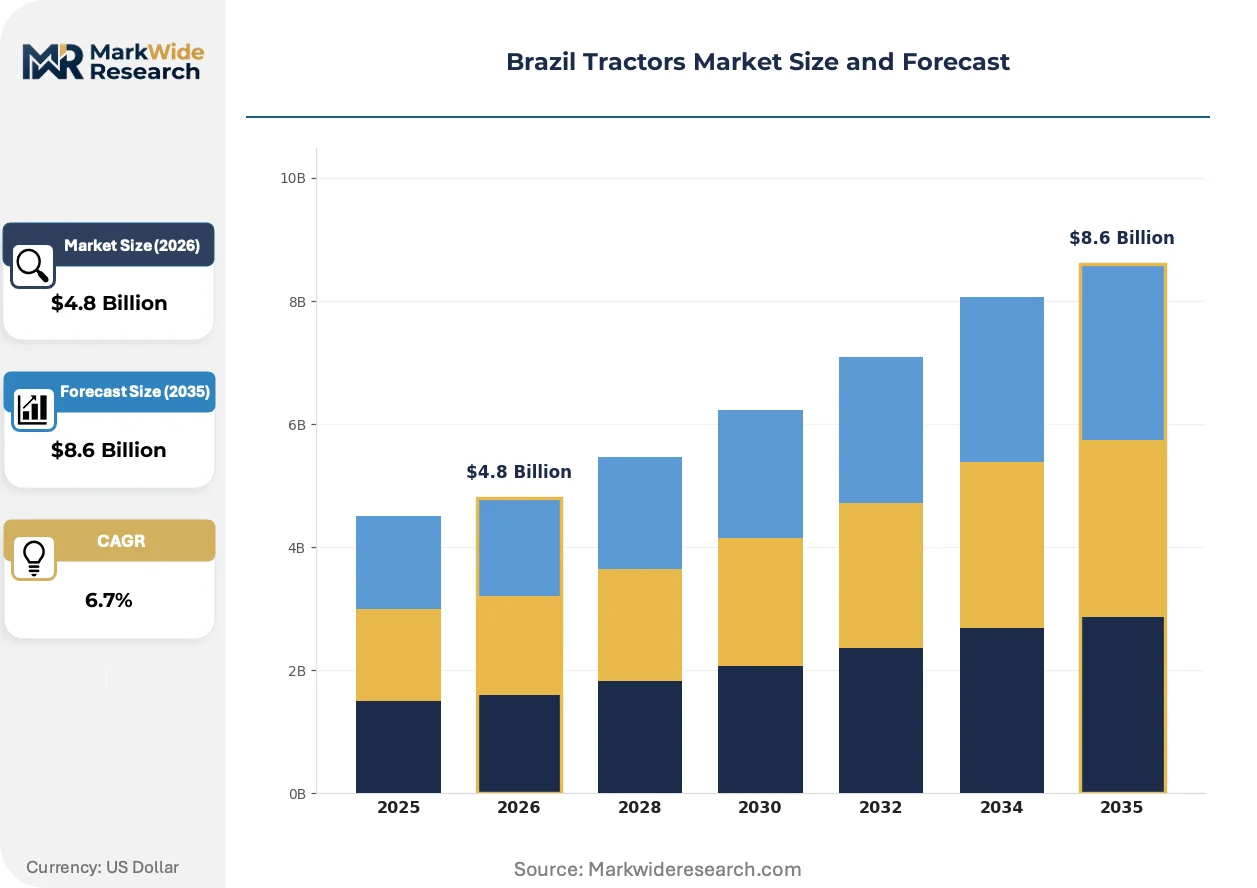
Brazil's tractor market is reconfiguring around RenovaBio compliance costs and the Central-West's consolidation into thousand-hectare soy-corn operations. Engine calibration for higher ethanol blends now drives R&D allocation more than horsepower wars.
Growth Catalysts
- RenovaBio credit mechanisms:ANVISA-aligned flex-fuel engine platforms earn carbon credits that offset total ownership costs for fleet operators in Mato Grosso.
- Precision planting systems:Variable-rate seeding and section control technology cut input waste on soybean monocultures, justifying premium equipment upgrades.
- MATOPIBA frontier expansion:Mechanized row-crop conversion in western Bahia and Tocantins generates first-time tractor demand from newly consolidated landholdings.
Market Restraints
- Steel and semiconductor input volatility:Hydraulic component costs fluctuate with global metallurgical coal prices, compressing assembler margins on mid-power units.
- Dealer network concentration:After-sales service capacity clusters in São Paulo and Paraná, leaving remote Goiás and Piauí operations exposed to downtime risk.
- PROCONVE tier lag:Emission enforcement gaps between Brazil and EU markets delay technology transfer for cleaner combustion architectures.
Strategic Opportunities
- Remote diagnostics platforms:Cellular-enabled telematics modules allow assemblers to unbundle predictive maintenance from physical dealer presence in the North region.
- Smallholder cooperative procurement:Rio Grande do Sul's dairy and poultry associations aggregate compact tractor demand, creating volume pools for specialized configurations.
- Biomass-powered stationary units:Sugarcane bagasse gasification engines open a parallel product line for irrigation pump sets in Minas Gerais.
Industry Challenges
- Mechatronics technician scarcity:CAN bus diagnostics and hydraulic-electronic integration repair skills lag fleet expansion in frontier states.
- Multi-brand fleet interoperability:Proprietary ISOBUS implementations complicate implement-swapping across Deere, CNH, and AGCO machines during peak planting windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Tractors Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compact Tractors, Utility Tractors, Agricultural Tractors, Specialty Tractors Engine Power: Low Power, Medium Power, High Power, Extra High Power Fuel Type: Diesel, Gasoline, Electric, Hybrid End User: Agriculture, Construction, Forestry, Landscaping |
| Companies Covered | Deere & Company, CNH Industrial, AGCO, Kubota Corporation, Mahindra & Mahindra Ltd., LS Mtron, TAFE, Agrale, Yanmar, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Tractors Market Trends and Innovations
Autonomous guidance and engine hybridization are compressing the traditional replacement cycle while forcing assemblers to choose between precision-ag premium positioning and utility volume defense.
Telematics-enabled fleet management is absorbing operator decision-making into centralized control rooms. Large-scale soy producers in Mato Grosso deploy machine-to-machine coordination across 40-plus-unit fleets, reducing per-hectare labor hours by consolidating supervision. This technology is absorbing the traditional role of field supervisors, shifting talent requirements toward data analysts and remote diagnostics technicians.
ANVISA is tightening rollover protective structure certification timelines for imported chassis, forcing assemblers to maintain parallel homologation tracks for Brazilian and export specifications. The regulatory friction most affects extra-high-power imports from EU and US manufacturing bases, prompting localized welding and assembly investments in São Paulo state to bypass complete-knockdown delays.
Leasing penetration is accelerating among mid-size grain operations unable to deploy capital against commodity price uncertainty. Traditional equipment finance through Banco do Brasil and regional cooperatives now competes with manufacturer-captive leasing arms offering bundled maintenance and residual value guarantees. This shift is most pronounced in Goiás, where soybean price volatility has compressed equipment payback assumptions from seven to four years.
Brazil Tractors Market Segmentation
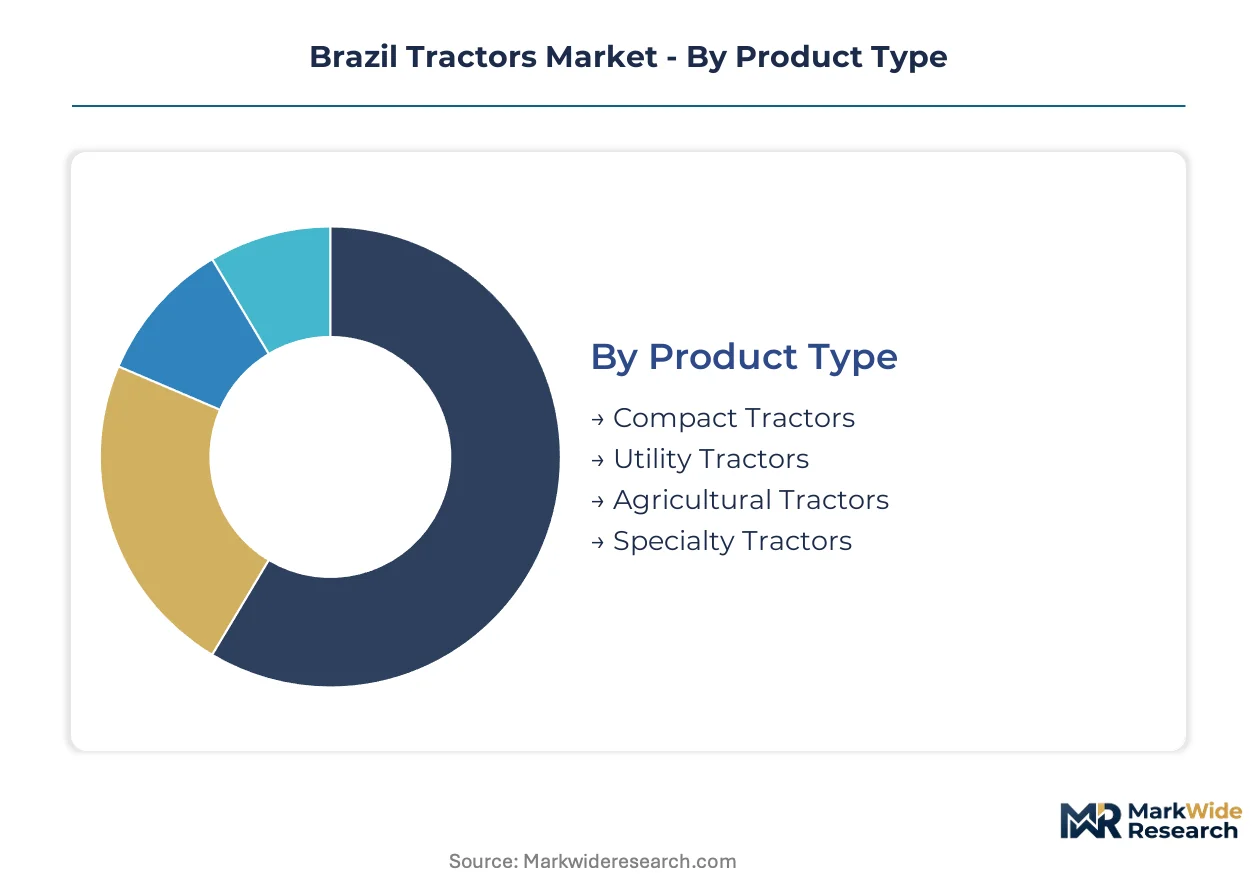
Segmentation in Brazil's tractor market reveals how regulatory pressure and farm scale interact to reshape procurement patterns. ANVISA certification requirements and RenovaBio compliance costs create divergent total ownership calculations across equipment categories, forcing buyers to match technical specifications to operational scale and fuel access.
Product Type:
ANVISA rollover protective structure certification timelines vary sharply by chassis configuration, with imported extra-high-power units facing the longest homologation delays while domestically assembled compact platforms clear approval fastest.
- Compact Tractors:These sub-50 horsepower units serve diversified smallholdings in Rio Grande do Sul and Santa Catarina with specialized dairy and poultry configurations. Demand concentrates among cooperative procurement pools in the South, where RenovaBio credit mechanisms offer limited offset value due to smaller fleet scales.
- Utility Tractors:Mid-range power units dominate replacement cycles across Brazil's interior states with versatile three-point hitch configurations for mixed operations. Mato Grosso grain operations favor these for transport and light fieldwork, though precision-ag upgrade rates lag larger agricultural platforms.
- Agricultural Tractors:Row-crop optimized machines with high-clearance frames and precision hydraulics anchor soybean-corn rotation systems in the Central-West belt.
- Specialty Tractors:Narrow-profile vineyard and orchard configurations serve São Paulo state citrus and coffee estates with specialized turning radii.
Utility tractors sit at the top of the volume ranking, with compact tractors climbing the fastest.
Engine Power:
Power tier selection tracks field size distribution, with thousand-hectare operations in Goiás and Mato Grosso absorbing the upper segments while fragmented landholdings in the South concentrate procurement at the lower end.
- Low Power:Sub-40 horsepower engines serve smallholder vegetable and dairy operations with mechanical transmission simplicity. Rio Grande do Sul's poultry associations aggregate demand for these units, creating volume pools that offset individual buyer credit constraints.
- Medium Power:The 40-100 horsepower band absorbs the bulk of replacement demand across Brazil's grain belt with proven hydraulic-electronic integration. Goiás mid-size soybean operations favor this tier for equipment payback assumptions compressed to four years by price volatility.
- High Power:100-200 horsepower platforms command premium positioning through ISOBUS-compatible precision planting systems in western Bahia MATOPIBA expansion zones.
- Extra High Power:200-plus horsepower units concentrate in Mato Grosso where field sizes exceed 500 hectares and fleet coordination across 40-plus machines justifies centralized telematics investment.
Medium power units dominate absolute shipments, though extra high power platforms are expanding most quickly in frontier consolidation zones.
Fuel Type:
RenovaBio credit mechanisms and PROCONVE tier advancement create divergent technology roadmaps, with ethanol-blend calibration requirements pushing R&D allocation toward flex-fuel architectures while electric platforms remain confined to niche applications.
- Diesel:Compression-ignition engines with established supply chains and technician familiarity anchor the installed base across all power tiers. ANVISA emission enforcement gaps versus EU markets delay cleaner combustion technology transfer, preserving diesel's cost advantage in remote Goiás and Piauí operations.
- Gasoline:Spark-ignition platforms with lower first-cost positioning serve entry-level compact tractor buyers in the South, though fuel price volatility erodes total ownership advantages against flex-fuel alternatives.
- Electric:Battery-electric drivetrains with limited range and charging infrastructure dependence confine deployment to peri-urban landscaping and municipal applications near São Paulo.
- Hybrid:Parallel hybrid architectures combining diesel prime movers with electric boost systems emerge in high-power precision-ag platforms for variable-load field operations.
Diesel retains the dominant share position, with hybrid configurations gaining share fastest as assemblers balance RenovaBio compliance against performance requirements.
End User:
End-use concentration determines financing channel selection, with agricultural buyers accessing Banco do Brasil equipment credit and manufacturer-captive leasing while construction and forestry procurement runs through commercial banking relationships with shorter tenor structures.
- Agriculture:Soybean-corn rotation systems and sugarcane operations drive 70-plus percent of tractor demand with seasonal utilization peaks dictating fleet sizing. Mato Grosso large-scale producers deploy machine-to-machine coordination across integrated operations, consolidating supervision roles into remote control rooms.
- Construction:Earthmoving and material handling applications in São Paulo state infrastructure projects absorb utility tractor variants with reinforced frames and loader packages.
- Forestry:Eucalyptus and pine plantation management in Minas Gerais and Paraná requires specialized high-flotation tire configurations and protective cab structures for rugged terrain access.
- Landscaping:Municipal parks maintenance and golf course operations in metropolitan belts favor compact zero-turn platforms with mower deck integration.
Agriculture commands the volume apex, with forestry applications expanding most quickly on plantation mechanization trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil concentrates Latin American tractor demand while Argentina and Mexico represent smaller but strategically distinct procurement patterns shaped by their own agricultural structures and regulatory environments.
São Paulo
Southeastern industrial infrastructure anchors domestic tractor assembly with localized welding investments bypassing complete-knockdown delays. ANVISA homologation timelines tighten for imported chassis, prompting manufacturers to maintain parallel certification tracks. The Sorocaba and Piracicaba manufacturing clusters absorb flex-fuel R&D allocation as RenovaBio compliance costs reshape engine technology roadmaps.
Mato Grosso
Thousand-hectare soy-corn operations drive extra-high-power tractor absorption with fleet coordination across 40-plus-unit deployments. The state's National Petroleum Agency biofuel blending mandates calibrate engine platforms for higher ethanol blends. Rondonópolis and Lucas do Rio Verde serve as mechanization hubs where centralized telematics investment consolidates field supervision into remote control rooms.
Rio Grande do Sul
Diversified smallholdings with dairy and poultry operations aggregate compact tractor demand through cooperative procurement pools. ANVISA operator safety standards apply across sub-50 horsepower configurations with faster certification timelines than imported extra-high-power units. The Passo Fundo and Erechim clusters specialize in poultry association volume contracts offsetting individual buyer credit constraints.
Goiás
Mid-size soybean operations favor medium-power tractors with equipment payback assumptions compressed to four years by commodity price volatility. PROCONVE emission tier enforcement gaps versus EU markets delay cleaner combustion technology transfer, preserving diesel's cost advantage. The Rio Verde and Catalão sub-regions concentrate replacement demand as frontier consolidation accelerates.
Minas Gerais
Sugarcane operations and eucalyptus plantations generate demand for specialized high-flotation configurations and protective cab structures. The Brazilian Institute of Environment and Renewable Natural Resources shapes deforestation monitoring protocols influencing mechanization patterns. The Triângulo Mineiro and Zona da Mata clusters absorb biomass-powered stationary units for irrigation pump sets.
Brazil Tractors Market Competitive Landscape
Top-tier vendors anchor the precision-agriculture premium segment, while mid-tier assemblers compete on utility volume and regional dealer coverage. The market structures around integrated technology ecosystems versus specialized row-crop configurations. Three archetypes dominate: multinational full-line manufacturers with captive financing arms, regional specialists with cooperative procurement relationships, and emerging flex-fuel technology developers. Competitive moves center on telematics platform unbundling and localized assembly investments to circumvent import homologation delays.
Among the established multinational tier, Deere & Company, CNH Industrial, and AGCO occupy positions defined by their respective precision farming ecosystem integration, interior state dealer network density, and specialized soybean-corn rotation configurations. These manufacturers exemplify divergent strategic postures toward RenovaBio compliance—integrated carbon credit capture versus volume-driven flex-fuel platform standardization versus precision-hydraulic specialization for high-clearance row-crop frames.
| Leading Market Players |
|---|
| Deere & Company |
| CNH Industrial |
| AGCO |
| Kubota Corporation |
| Mahindra & Mahindra Ltd. |
| LS Mtron |
| TAFE |
| Agrale |
| Yanmar |
| Others |
Pricing and Supply Chain Analysis
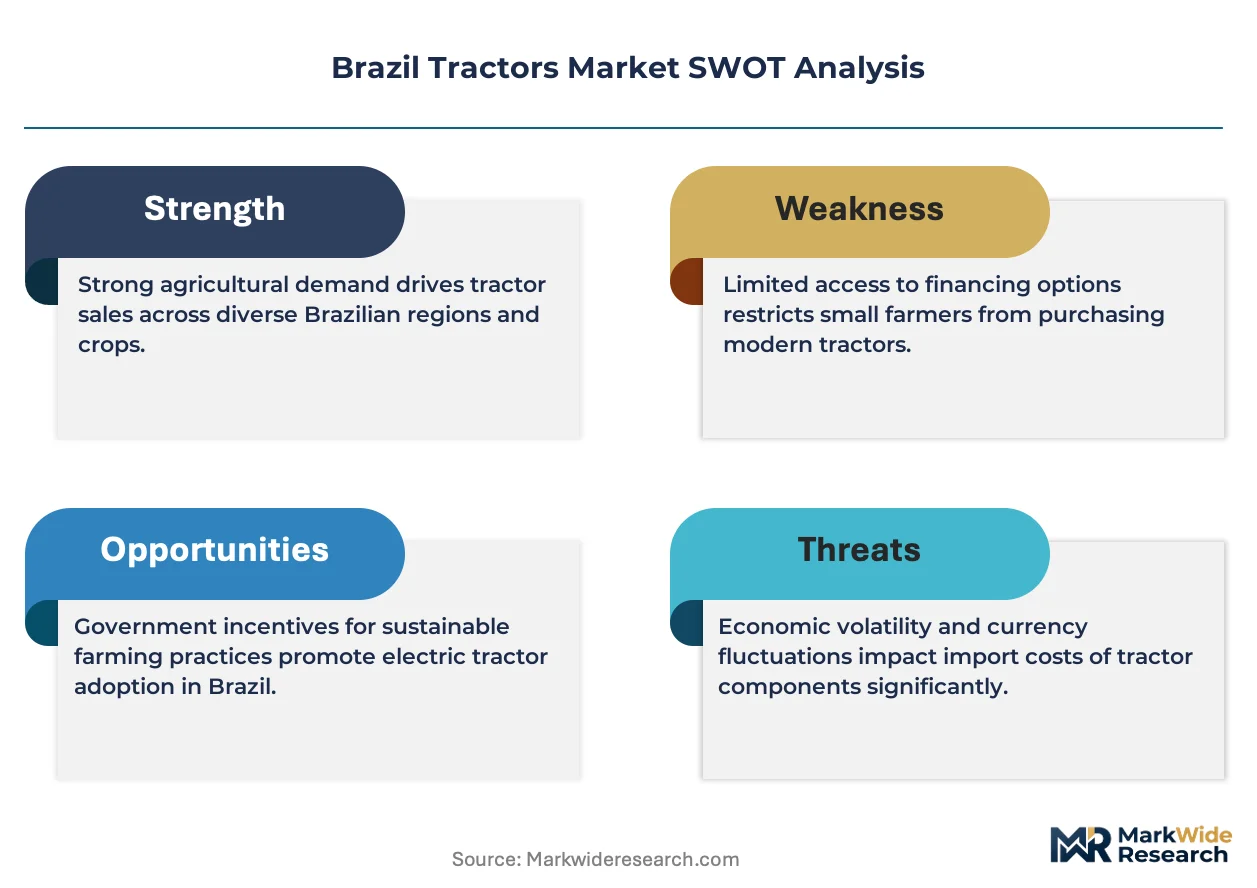
Metallurgical coal prices transmit directly through hydraulic component costs, pressing assembler margins on mid-power utility tractors while São Paulo welding clusters absorb localized assembly investments to bypass ANVISA homologation delays for extra-high-power imports.
Pricing Analysis
Capacity additions in São Paulo state are reshaping price floors for domestically assembled compact and utility tiers. Three-tier pricing structure across premium precision-ag, standard row-crop, and economy utility levels stratifies by ISOBUS compatibility and telematics bundling. Cost compression in mid-power segments intensifies because steel and semiconductor input volatility squeezes margin buffers. Cooperative procurement pools in Rio Grande do Sul exhibit highest price sensitivity, while Mato Grosso fleet operators prioritize total ownership cost optimization through RenovaBio credit capture.
Supply Chain Analysis
Inland freight costs from São Paulo assembly clusters to Mato Grosso and Goiás operations absorb 8-12% of landed equipment value, favoring regional welding investments over complete-knockdown imports. Brazil draws cast iron engine blocks and precision hydraulic pumps from China, electronic control modules from Germany, and high-strength steel from Argentina. Single-source vulnerability concentrates in EU-sourced emission control systems facing PROCONVE tier lag delays. Distribution runs through manufacturer-captive dealer networks in grain belts and cooperative procurement channels in southern dairy regions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazil's tractor market functions as a geographic-arbitrage play where RenovaBio compliance costs in Mato Grosso diverge sharply from PROCONVE enforcement gaps preserving diesel cost advantages in remote Goiás operations.
For Market Incumbents: Deploy telematics platform unbundling to decouple predictive maintenance revenue from physical dealer presence in frontier North region states. Consolidate flex-fuel R&D allocation around ANVISA-aligned carbon credit capture mechanisms. Counter Mahindra and Agrale volume pressure through captive leasing arms offering residual value guarantees compressed to four-year payback assumptions. For New Entrants and Emerging Players: Launch via cooperative procurement aggregation in Rio Grande do Sul dairy and poultry associations where compact tractor demand pools offset individual credit constraints. Target MATOPIBA frontier expansion zones in western Bahia with first-time mechanization demand from newly consolidated thousand-hectare soy operations. Pursue biomass-powered stationary unit specialization for Minas Gerais sugarcane irrigation pump sets. For Investors and Strategic Acquirers: Consolidation pressure builds where mechatronics technician scarcity in frontier states outpaces fleet expansion, creating acquisition opportunities for remote diagnostics platform developers. Long-term viability hinges on flex-fuel technology roadmaps aligned with National Petroleum Agency biofuel blending mandate acceleration. Monitor ANVISA rollover protective structure certification timeline tightening as inflection signal for localized assembly investment returns.| Strategic Initiative | Industry Significance |
|---|---|
| Flex-Fuel Engine Platform Standardization | RenovaBio credit mechanisms offset ownership costs for Mato Grosso fleet operators. |
| Telematics-Enabled Predictive Maintenance | Cellular modules reduce downtime risk in remote Goiás and Piauí grain operations. |
| Localized Welding and Assembly Investment | São Paulo clusters bypass ANVISA homologation delays for extra-high-power chassis. |
| Cooperative Procurement Channel Development | Rio Grande do Sul poultry associations aggregate compact tractor volume pools. |
| Biomass Gasification Engine Development | Sugarcane bagasse-powered units serve Minas Gerais irrigation pump set demand. |
Research Methodology
Direct dialogue with tractor assembler product managers, ANVISA certification specialists, Mato Grosso fleet operations directors, and Banco do Brasil agricultural credit officers grounded qualitative findings in operational reality. Secondary validation drew from ANVISA regulatory filings, National Petroleum Agency biofuel blending mandate documentation, Brazilian Institute of Environment deforestation monitoring protocols, and SEC 10-K disclosures from listed equipment manufacturers. Bottom-up shipment data from state-level farm machinery registrations triangulated against top-down macroeconomic indicators across the analysis window.
Top-down macroeconomic modeling anchored demand projections to soybean-corn rotation acreage expansion and RenovaBio credit mechanism adoption curves. Segmentation dimensions spanned product type, engine power tier, fuel architecture, and end-use concentration with regional adoption patterns calibrated to state-level field size distribution. CAGRs derived from equipment replacement cycle compression and frontier mechanization penetration rates. Key inputs included PROCONVE tier advancement timelines and ethanol blend calibration R&D allocation trends.
Several conditions sit outside the modeled scope, including abrupt PROCONVE enforcement acceleration, ANVISA certification timeline reversals, and commodity price volatility outside historical bands. Forecasts reflect assumptions about cooperative procurement pool stability and telematics infrastructure rollout pace. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Machinery
Brazil Agricultural Machinery Market
Agricultural Machinery
Brazil Agricultural Tractors Market
Agricultural Machinery
Agricultural Electric Tractor Market
Agricultural Machinery
Agricultural Spray Drone Market
Agricultural Machinery
South America Agricultural Machinery Market
Agricultural Machinery
Agricultural Haying and Forage Machinery Market
Agricultural Machinery
Global Autonomous Tractor Market
Agricultural Machinery
Global Tractor Market
Agricultural Machinery
Agriculture and Farm Machinery Market
Agricultural Machinery
France Agricultural Machinery Market
Agricultural Machinery
Agricultural Drum Mowers Market
Agricultural Machinery
North America Agricultural Tractors Market
Agricultural Machinery
Crop Sprayers Market
Agricultural Machinery
Electric Tractors Market
Agricultural Machinery
Autonomous Agricultural Machinery Market
Agricultural Machinery
United Kingdom Agricultural Machinery Market