
 Forestry Machinery Market | 2026-2036
Forestry Machinery Market Size, Share, and Industry Trends Forecast 2026-2036
Forestry Machinery Market Analysis
Multi-source component procurement is repositioning supply economics across the forestry machinery sector. Deere & Company leverages its captive dealer network to control aftermarket parts flows in North America. Ponsse Plc anchors its competitiveness through deep vertical integration into cut-to-length harvester manufacturing in Finland. Komatsu Ltd. competes via scale advantages in crawler-based extraction systems for steep terrain.
Forestry machinery encompasses self-propelled equipment engineered for felling, processing, forwarding, and site preparation, typically operating at engine outputs from 100 kW to 300 kW and incorporating hydraulic boom systems with reach envelopes exceeding 10 meters. Harvesters command the largest installed base among product types due to mechanized cut-to-length dominance in Nordic and Central European logging operations. Forwarders represent the fastest-expanding segment as contractors adopt longer-distance extraction to access remote stands. GPS technology integration is reshaping precision forestry workflows, while fuel-efficient engines face margin pressure from electrification roadmaps.
The EPA governs off-road diesel emissions in the United States, compelling engine recertification cycles that directly shape product development budgets. The EU F-Gas Regulation and REACH framework restrict hydraulic fluid chemistries and refrigerants in European-sold equipment, filtering through to global design standards. Stakeholders must track how carbon border adjustments and battery supply chain localization will alter total cost of ownership calculations for fleet operators.
Market Dynamics
EU F-Gas Regulation compliance deadlines are compressing powertrain development cycles across the forestry machinery sector, forcing OEMs to accelerate electrification roadmaps while maintaining hydraulic system performance in cut-to-length harvesters.
Growth Catalysts
- Mechanized harvesting mandates:Nordic forestry cooperatives in Finland and Sweden are requiring full mechanization for state-leased concessions, eliminating manual felling contracts.
- EU F-Gas Regulation:The 2024 refrigerant phase-down is accelerating R&D investment in electric auxiliary systems for harvester cabs and processors.
- Precision forestry adoption:GPS-guided boom control systems are enabling single-operator efficiency gains in Estonian and Latvian contractor fleets.
Market Restraints
- Steel and hydraulic component volatility:Boom cylinder and high-pressure hose input costs fluctuate with Nordic steel mill output schedules.
- Engine certification concentration:EPA Tier 4 Final and Stage V recertification cycles concentrate compliant powertrain supply among three European engine builders.
- Battery energy density limits:Lithium-ion pack weight-to-output ratios constrain all-electric forwarder range in steep-terrain extraction.
Strategic Opportunities
- Baltic contractor expansion:Underpenetrated private woodland in Lithuania and Poland offers first-mover positioning for cut-to-length system lessors.
- Hybrid powertrain convergence:Diesel-electric architectures paired with supercapacitor buffers are opening mid-duty harvester segments previously reserved for conventional engines.
- Direct fleet financing channels:Manufacturer-captive finance arms are bypassing traditional agricultural lending networks in Nordic markets.
Industry Challenges
- Mechatronics technician scarcity:Hydraulic-electric system integration expertise lags machine deployment rates in Finnish service territories.
- Stage V compliance timelines:Exhaust after-treatment packaging conflicts with harvester frame geometry constraints, extending prototype validation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Forestry Machinery Market |
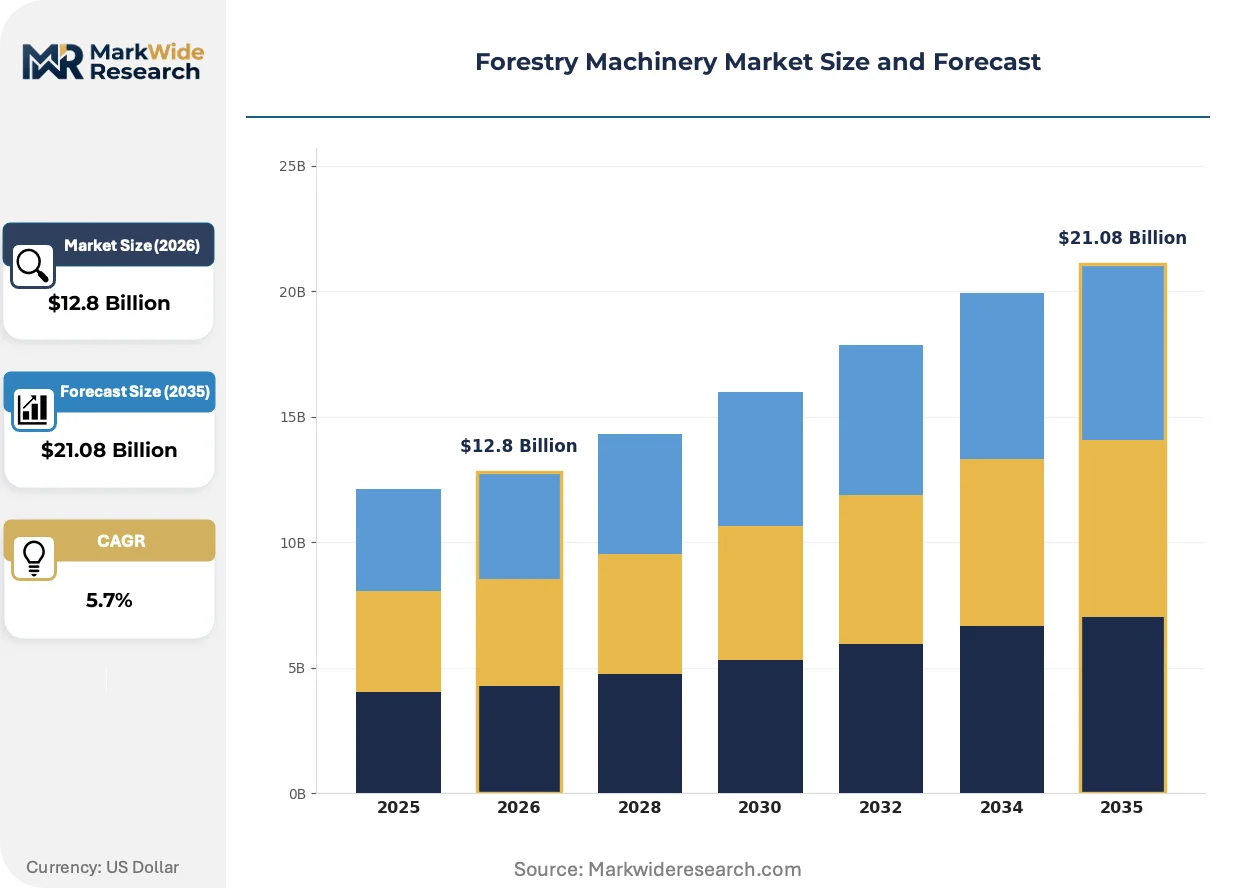
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $21.08 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Harvesters, Forwarders, Chippers, Log Skidders Application: Logging Operations, Land Clearing, Biomass Production, Urban Forestry End User: Private Contractors, Government Agencies, Timber Companies, Eco-Friendly Organizations Technology: Hydraulic Systems, Automated Control, GPS Technology, Fuel-efficient Engines |
| Companies Covered | Ponsse Plc, Husqvarna Group, Deere & Company, Hitachi Construction Machinery, STIHL Group, Komatsu Ltd., Tigercat International Inc., Volvo Construction Equipment, Caterpillar Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Forestry Machinery Market Emerging Trajectories
Telematics-enabled predictive maintenance is rewiring aftermarket revenue models across Nordic contractor fleets. Equipment intelligence layers are shifting value capture from hardware sales to uptime guarantees.
Machine-to-machine coordination protocols are decentralizing harvester-forwarder pairing decisions in Finnish logging operations. Contractors operating Ponsse and Komatsu mixed fleets are adopting open CAN-bus standards to synchronize boom cycles and payload routing. Real-time terrain mapping is compressing stand-level planning from days to hours.
EU F-Gas Regulation refrigerant quotas are forcing hydraulic system redesigns in harvester climate systems. OEMs are substituting CO2 heat pumps for conventional R134a circuits, adding compressor load to auxiliary power units. Nordic manufacturers are lobbying Brussels for forestry equipment exemptions during the 2027 phase-down review.
Contractor procurement patterns are fragmenting across equipment lifecycle stages. Estonian and Latvian mid-size operators are unbundling machine purchases from service contracts, sourcing maintenance through independent hydraulic specialists rather than dealer networks. This disintermediation concentrates in regions with dense second-hand machine liquidity.
Forestry Machinery Market Segmentation
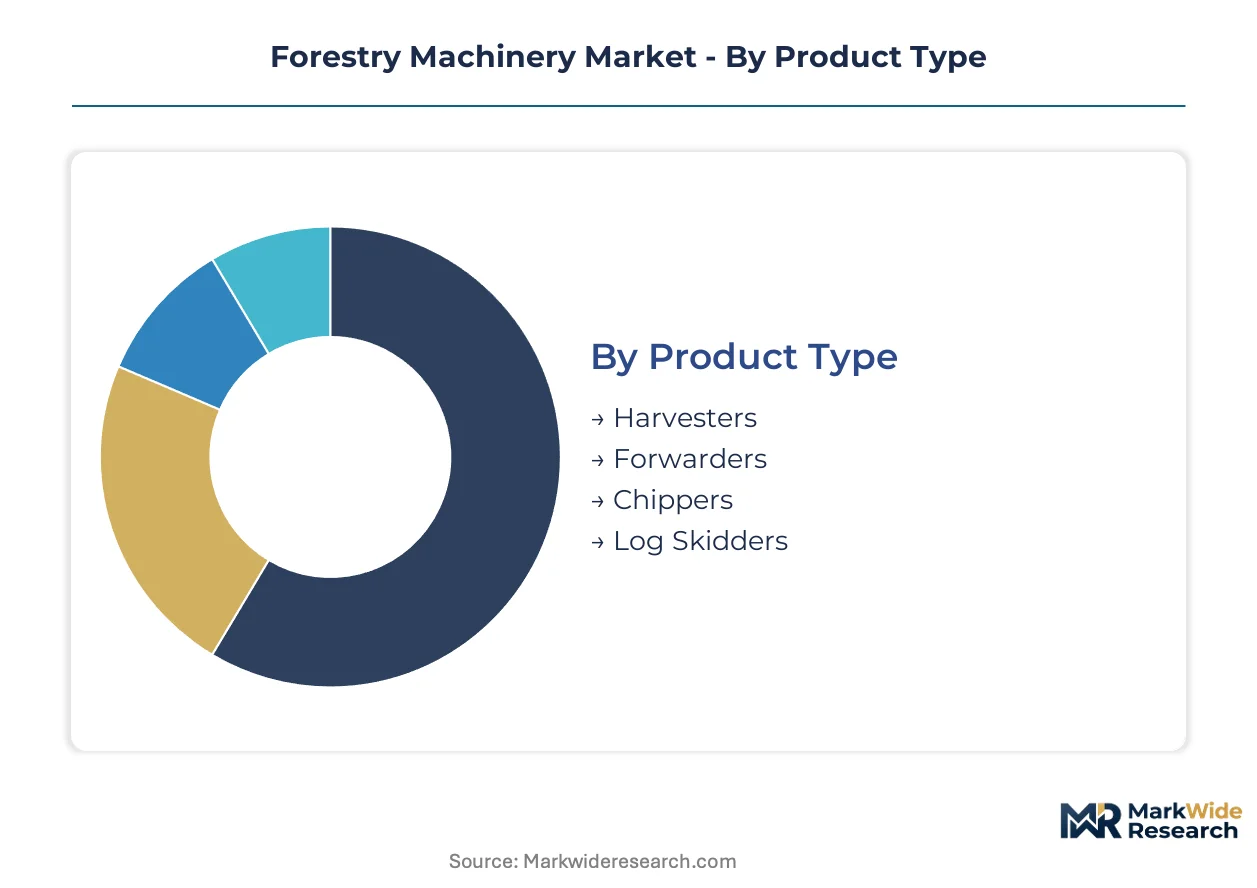
Forestry machinery segmentation reflects divergent certification burdens across powertrain architectures and operating environments. Equipment buyers face distinct compliance pathways depending on whether machines deploy conventional diesel, hybrid-electric, or fully electric auxiliary systems.
Product Type:
EPA Tier 4 Final and EU Stage V certification requirements concentrate most heavily on high-displacement harvester engines, while smaller forwarder powertrains face lighter documentation loads. Chippers and skidders occupy intermediate regulatory tiers based on engine output classes.
- Harvesters:Self-propelled cut-to-length machines integrating felling heads with boom-mounted processing units, typically rated at 150-300 kW engine output. Demand concentrates among Finnish and Swedish contractor fleets facing mechanized harvesting mandates for state-leased concessions, with F-Gas Regulation compliance adding auxiliary system redesign costs.
- Forwarders:Wheeled or tracked carriers equipped with hydraulic cranes and bunk systems for log extraction over distances exceeding 500 meters. Estonian and Latvian operators are expanding fleet capacity fastest as contractors adopt longer-distance extraction to access remote stands, though battery energy density limits constrain all-electric range in steep terrain.
- Chippers:Mobile or stationary units reducing logging residue and roundwood to biomass fuel specifications, subject to noise ordinances in urban forestry zones.
- Log Skidders:Cable or grapple-based dragline extractors for steep-slope operations, common in North American cable-yarding systems.
Leading the category by volume: Harvesters. Growing fastest: Forwarders.
Application:
Cost tier stratification separates high-investment logging operations from lower-capital land clearing contracts, with biomass production occupying a mid-tier position sensitive to energy subsidy regimes.
- Logging Operations:Industrial-scale timber harvesting requiring coordinated harvester-forwarder fleets, GPS-guided boom control, and real-time terrain mapping. Nordic cooperatives in Finland demand full mechanization compliance, while Baltic contractors in Lithuania and Poland present first-mover expansion opportunities for cut-to-length system lessors.
- Land Clearing:Site preparation for construction, agriculture, or wildfire mitigation, typically employing lower-specification chippers and skidders with shorter depreciation schedules.
- Biomass Production:Dedicated feedstock supply for district heating plants and power generation, concentrated in Swedish and Estonian energy clusters.
- Urban Forestry:Municipal tree maintenance and storm damage response, governed by local noise and emissions ordinances favoring electric auxiliary systems.
Dominant by revenue: Logging Operations. Expanding most quickly: Biomass Production.
End User:
Customer type determines financing channel access and service contract bundling preferences, with private contractors fragmenting procurement patterns most aggressively.
- Private Contractors:Independent operators owning 5-25 machine fleets, increasingly unbundling equipment purchases from maintenance contracts. Estonian and Latvian mid-size operators source hydraulic service through independent specialists rather than dealer networks.
- Government Agencies:State forest administrations in Finland and Sweden leasing concessions with mechanization mandates, procuring through tender processes with extended warranty requirements.
- Timber Companies:Vertically integrated pulp and sawmill operators with captive maintenance infrastructure.
- Eco-Friendly Organizations:Conservation NGOs and certified sustainable forestry groups prioritizing low-emission powertrains for demonstration stands.
Highest fleet turnover: Private Contractors. Fastest contract volume growth: Government Agencies.
Technology:
Margin structure varies sharply across technology tiers, with GPS-enabled precision systems commanding premium positioning while fuel-efficient engines face electrification-driven margin compression.
- Hydraulic Systems:High-pressure boom circuits and drive transmissions, core to cut-to-length harvester functionality. REACH framework restrictions on hydraulic fluid chemistries filter through to global design standards.
- Automated Control:Machine-to-machine coordination protocols and open CAN-bus standards enabling mixed-fleet synchronization between Ponsse and Komatsu equipment in Finnish operations.
- GPS Technology:Real-time kinematic positioning for boom automation and stand-level planning, compressing harvest planning from days to hours.
- Fuel-efficient Engines:Diesel powertrains optimized for Tier 4 Final and Stage V compliance, facing development cycle compression from F-Gas Regulation deadlines and electrification roadmaps.
Widest installed base: Hydraulic Systems. Steepest expansion trajectory: GPS Technology.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boreal timber reserves and Nordic steel mill proximity anchor regional production economics. Mechanized harvesting mandates and F-Gas Regulation compliance timelines concentrate investment across specific national markets.
Finland
State-leased concession mechanization mandates drive fleet replacement cycles among private contractors. The EU F-Gas Regulation refrigerant phase-down forces auxiliary system redesigns in harvester climate controls. Machine-building clusters around Tampere and Joensuu concentrate cut-to-length harvester production and hydraulic component supply chains.
Sweden
Forestry cooperative procurement standards require GPS-guided boom systems for tender eligibility. REACH framework restrictions on hydraulic fluid chemistries filter through to domestic equipment specifications. Biomass production energy clusters in southern counties sustain dedicated chipper and residue processing equipment demand.
Germany
Stage V exhaust after-treatment compliance compresses development cycles for mid-size forwarder engines. The country's national environmental regulator enforces strict noise ordinances in urban forestry zones favoring electric auxiliary systems. Industrial machinery expertise in Baden-Württemberg supports precision hydraulics and automated control subsystem supply.
United States
EPA Tier 4 Final recertification cycles shape product development budgets for crawler-based extraction systems. Steep-slope cable-yarding operations in Pacific Northwest and Appalachian regions sustain specialized skidder demand. Dealer network concentration in timber-producing states controls aftermarket parts flows and service contract penetration.
Estonia
Private woodland underpenetration offers first-mover positioning for cut-to-length system lessors expanding from Nordic bases. GPS-guided boom control adoption enables single-operator efficiency gains in mid-size contractor fleets. Proximity to Finnish manufacturing clusters reduces spare parts lead times for Baltic operators unbundling procurement from traditional dealer networks.
Forestry Machinery Market Vendor Landscape
Global majors compete with regional champions across powertrain certification and aftermarket service density. The vendor base organizes around three tiers: integrated full-line producers, specialized harvester-forwarder builders, and component-focused subsystem suppliers. Two strategic archetypes dominate—captive dealer network operators leveraging parts flow control, and vertically integrated specialists anchoring competitiveness through in-house production of cut-to-length systems. Competitive moves concentrate on hybrid powertrain convergence and direct fleet financing channel expansion bypassing traditional agricultural lending.
Among Nordic-based integrated specialists, Ponsse Plc and Komatsu Ltd. occupy positions exemplifying contrasting scale approaches to mechanized harvesting. Deere & Company anchors the captive distribution archetype through aftermarket parts flow management. These three represent distinct competitive vectors: regional manufacturing depth, crawler-based extraction scale, and dealer network control.
| Leading Market Players |
|---|
| Ponsse Plc |
| Husqvarna Group |
| Deere & Company |
| Hitachi Construction Machinery |
| STIHL Group |
| Komatsu Ltd. |
| Tigercat International Inc. |
| Volvo Construction Equipment |
| Caterpillar Inc. |
| Others |
Supply Flow & Price Mechanics
EU F-Gas Regulation refrigerant phase-down deadlines gate qualified supply for harvester climate system retrofits, restricting premium-tier pricing access to OEMs with certified CO2 heat pump architectures and compliant auxiliary power units. Finnish and Swedish contractors face compressed procurement timelines as state-leased concession mechanization mandates collide with auxiliary system redesign costs, concentrating pricing power among vertically integrated manufacturers with captive component supply.
Pricing Analysis
Warranty and service contract bundling separates Nordic dealer network pricing from unbundled procurement patterns emerging among Estonian and Latvian mid-size operators. Three-tier pricing structure across premium, standard, and economy levels reflects Stage V certification grade, geographic delivery cost from Tampere manufacturing clusters, and after-sales service density. Pricing pressure stems from battery energy density constraints limiting all-electric forwarder range, forcing hybrid premiums in steep-terrain segments. Private contractors exhibit highest price sensitivity, while government agencies with extended warranty tender requirements show lowest.
Supply Chain Analysis
Regional distribution centers around Joensuu and Tampere anchor hub-and-spoke patterns serving Finnish domestic demand and Baltic export markets. Component supply concentrates in Finland, Sweden, and Germany, with hydraulic boom cylinders and high-pressure hose assemblies drawing from Nordic steel mill output schedules. Raw material dependencies include specialty steel grades, lithium-ion cell packs, and precision hydraulic seals. Single-source vulnerability concentrates in Stage V-compliant engine supply among three European builders. Distribution runs through captive dealer networks in North America and independent hydraulic specialists in fragmented Baltic territories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified mechatronics technician scarcity props pricing for maintenance-capable OEMs, creating supply-constrained conditions where service infrastructure availability limits fleet expansion rates across Finnish and Swedish contractor territories.
For Market Incumbents: Hedge against electrification-driven margin compression by accelerating hybrid powertrain convergence in mid-duty harvester segments. Deepen backward integration into hydraulic-electric system integration capabilities to offset mechatronics technician scarcity threatening service revenue capture. Prioritize certification investment in CO2 heat pump architectures ahead of 2027 F-Gas Regulation phase-down review exemptions. For New Entrants and Emerging Players: Begin with underpenetrated private woodland in Lithuania and Poland where cut-to-length system lessors face limited incumbent service density. Target first-mover positioning through direct fleet financing channels bypassing traditional agricultural lending networks concentrated in Nordic markets. Emphasize GPS-guided boom control adoption as single-operator efficiency value proposition for Estonian and Latvian mid-size contractors. For Investors and Strategic Acquirers: EU F-Gas Regulation refrigerant quota allocation announcements are the leading indicator that auxiliary system redesign investment cycles will concentrate market share among compliant OEMs. Five-to-ten year viability favors vertically integrated specialists with captive cut-to-length manufacturing depth over assembly-dependent challengers. Watch Nordic manufacturer lobbying outcomes for forestry equipment exemptions during 2027 phase-down review as inflection signal for competitive positioning stability.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Powertrain Convergence | Diesel-electric architectures paired with supercapacitor buffers open mid-duty harvester segments previously reserved for conventional engines. |
| Direct Fleet Financing Expansion | Manufacturer-captive finance arms bypass traditional agricultural lending networks concentrated in Nordic cooperative procurement channels. |
| CO2 Heat Pump Certification | Compliant auxiliary climate systems secure premium-tier positioning ahead of F-Gas Regulation phase-down deadlines. |
| Mechatronics Training Infrastructure | Service capability expansion addresses technician scarcity limiting fleet uptime guarantees in Finnish territories. |
| Baltic Distribution Localization | Regional spare parts positioning reduces lead times for contractors unbundling procurement from traditional dealer networks. |
Methodological Framework
Multi-period observation of harvester-forwarder fleet deployment rates, F-Gas Regulation compliance timelines, and mechanic certification pipeline outputs anchored the trend analysis, supplemented by interviews with equipment procurement managers at Finnish forestry cooperatives, maintenance directors at Swedish timber companies, hydraulic service specialists in Estonia and Latvia, and platform engineers at Nordic OEMs. Secondary validation drew from EPA Tier 4 Final certification databases, EU Stage V type-approval registries, customs trade data for forestry machinery imports, and SEC filings of listed equipment manufacturers. Bottom-up unit economics triangulated against top-down market sizing across powertrain technology tiers.
Input-output matrix modeling connected powertrain architecture adoption curves to segment-level revenue flows across the projection horizon. Segmentation dimensions included product type, application intensity, end-user financing channel access, and technology integration depth. CAGRs derived from logistic diffusion curves fitted to mechanized harvesting mandate implementation schedules and battery energy density improvement trajectories. Industry-specific forecast inputs incorporated Nordic steel mill capacity utilization rates and lithium-ion cell pack cost evolution assumptions.
Underlying measurement precision varies by segment; GPS-enabled precision systems and hybrid powertrain categories carry tighter precision than conventional diesel tiers due to more visible deployment data. Forecasts reflect documented assumptions regarding regulatory timeline adherence and commodity input cost stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Machinery
South America Utility Tractor Market
Agricultural Machinery
South America Agricultural Sprayers Market
Agricultural Machinery
Two Wheel Walking Tractor Market
Agricultural Machinery
Brazil Tractors Market
Agricultural Machinery
Europe Agricultural Tractors Market
Agricultural Machinery
Agriculture Drones Market
Agricultural Machinery
Crawler Tractors Market
Agricultural Machinery
Southeast Asia Agricultural Tractors Market
Agricultural Machinery
Asia-Pacific Agricultural Machinery Market
Agricultural Machinery
Canada Robotic Fruit Picker Market
Agricultural Machinery
Europe Utility Tractor Market
Agricultural Machinery
India Agricultural Tractor Market
Agricultural Machinery
United Kingdom Agricultural Machinery Market
Agricultural Machinery
Milking Robots Market
Agricultural Machinery
Hydrogen Powered Tractor Market
Agricultural Machinery
Wheat Milling Machine Market