
 Cattle Head Catch Market | 2026-2036
Cattle Head Catch Market Size, Share, and Industry Trends Forecast 2026-2036
Cattle Head Catch Market Outlook
Beef production is consolidating its share of cattle head catch equipment procurement as feedlot operators replace manual restraint methods with hydraulic and squeeze chute systems. Arrowquip dominates the premium automated segment through its Canadian manufacturing base and direct-to-ranch distribution network. Schulte CattleQuip anchors the mid-market with standardized designs that compete aggressively on replacement part availability. Priefert Manufacturing leverages its Texas steel fabrication heritage to sustain long-standing relationships with large-scale cattle operations across the southern United States.
A cattle head catch is a mechanical restraint device designed to secure a bovine animal's head during veterinary procedures, weighing, tagging, or transport preparation, typically constructed from galvanized steel tubing with adjustable width settings between 15 and 30 centimeters to accommodate varying breed sizes. The device functions as a critical safety interface between livestock handlers and animals, reducing injury risk while enabling single-operator efficiency in high-throughput environments. Steel-framed clamp designs occupy the largest installed base due to durability under corrosive conditions, while polypropylene rope variants represent the fastest-growing material category among smallholder dairy operations seeking portable, low-capital alternatives. Dairy farming applications generate the most consistent replacement demand cycle, whereas livestock auction applications concentrate margin pools in heavy-duty configurations rated for continuous daily use.
USDA guidelines under the Humane Methods of Livestock Slaughter Act and OSHA workplace safety standards shape head catch design requirements around handler protection and animal stress minimization. ISO 10954 standards for agricultural equipment safety influence export market access for manufacturers seeking placement in European Union and Australian distribution channels. Stakeholders must monitor evolving state-level animal welfare legislation in Nebraska, Kansas, and Texas, where proposed handling facility audit requirements could accelerate equipment replacement timelines and redefine minimum specification thresholds for new installations.
Market Dynamics
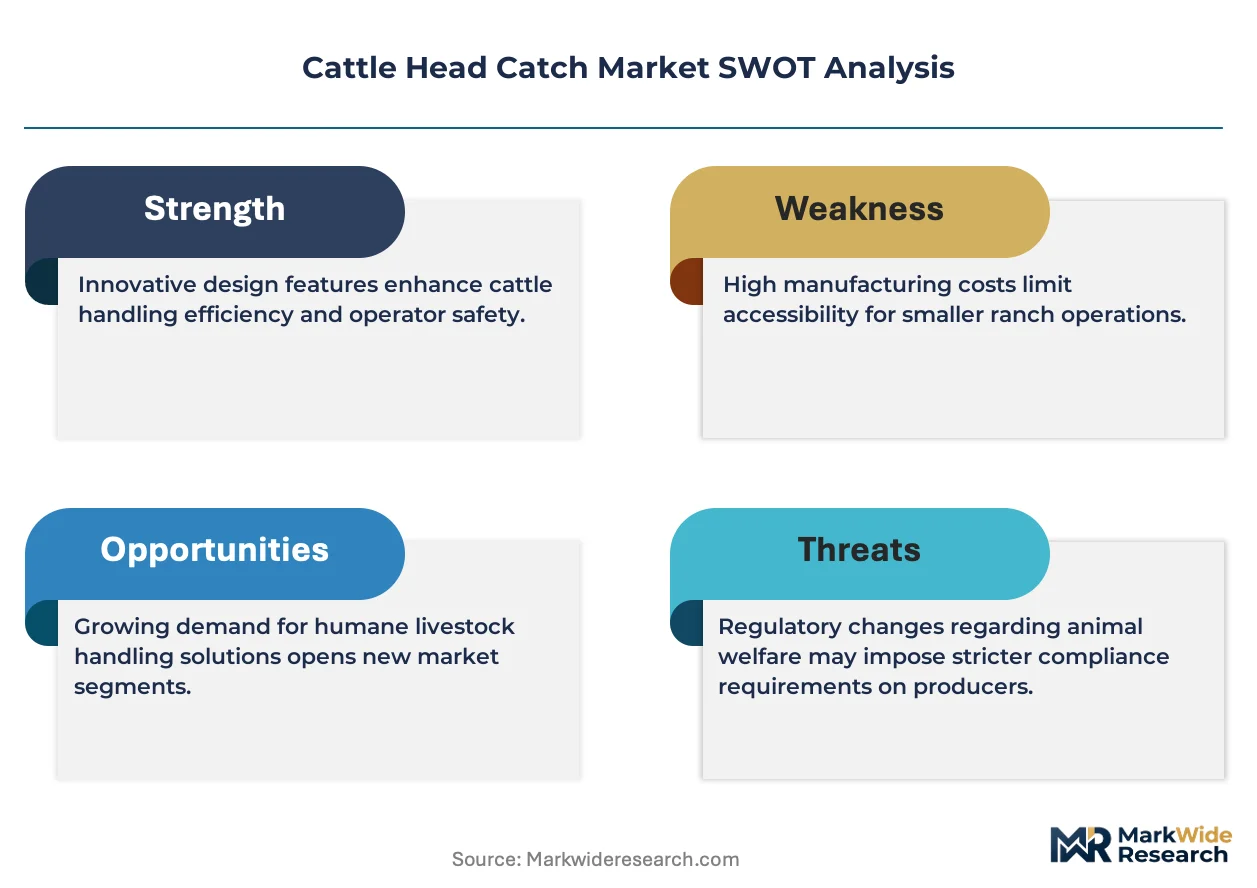
Automated hydraulic squeeze chute systems are displacing manual restraint methods across commercial beef operations, concentrating procurement decisions among fewer large-scale feedlot operators who prioritize throughput efficiency and handler safety metrics over upfront capital expenditure.
Growth Catalysts
- USDA Livestock Handling Guidelines:Federal mandates under the Humane Methods of Livestock Slaughter Act compel feedlot operators to upgrade restraint infrastructure, creating replacement demand cycles for certified equipment.
- Steel Framing Durability:Galvanized tubular construction withstands corrosive feedlot environments for 15-plus year service intervals, reducing total cost of ownership versus wooden alternatives.
- Australian Pastoral Consolidation:Large-scale cattle stations in Queensland and Northern Territory are standardizing permanent handling infrastructure to meet export certification requirements for Asian beef markets.
Market Restraints
- Steel Price Volatility:Fluctuations in hot-rolled coil pricing directly compress fabrication margins for equipment manufacturers dependent on North American steel supply.
- Canadian Manufacturing Concentration:Premium automated segment production clusters in Alberta and Manitoba, creating geographic supply risk and extended lead times for southern hemisphere buyers.
- Polypropylene Rope Substitution:Smallholder dairy operations in developing markets favor portable rope restraints that undercut capital investment requirements for permanent chute systems.
Strategic Opportunities
- Brazilian Export Certification:Evolving animal welfare audit requirements for European Union beef access create upgrade mandates for Amazon basin feedlot infrastructure.
- Sensor-Integrated Restraint Systems:Convergence of load cell weighing technology with hydraulic chute controls enables real-time data capture for individual animal management protocols.
- Veterinary Service Bundling:Mobile chute rental networks are emerging in Texas and Nebraska, offering per-head pricing that lowers barrier to entry for mid-scale operators.
Industry Challenges
- Hydraulic System Maintenance Expertise:Rural feedlots face acute shortages of technicians certified to service high-pressure hydraulic circuits, extending equipment downtime.
- ISO 10954 Compliance Timelines:Agricultural equipment safety certification for European Union market access requires 18-to-24 month validation cycles that delay revenue recognition.
- Legacy Corral Integration:New automated chute systems demand concrete pad specifications and electrical supply upgrades that conflict with existing dirt-floor handling facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cattle Head Catch Market |
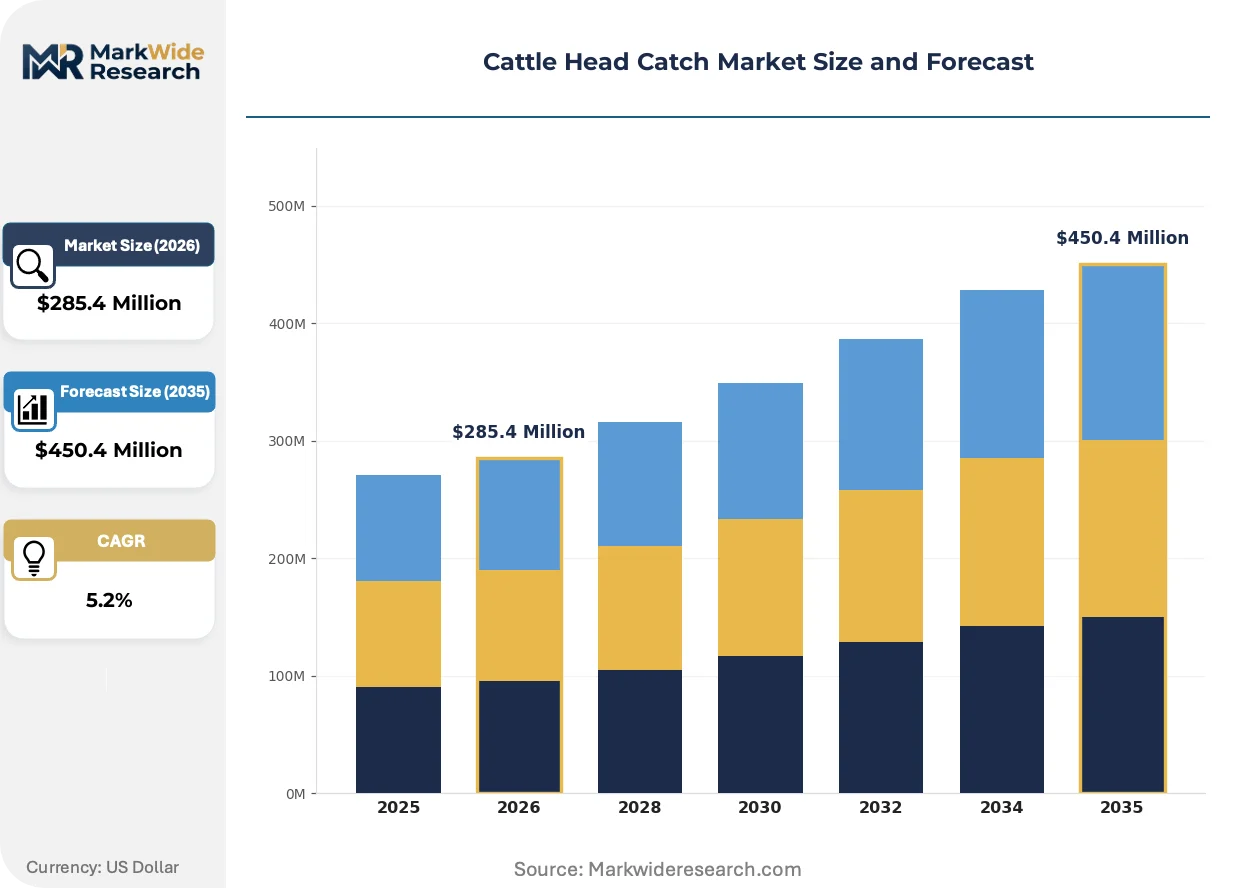
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $450.4 Million |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rope, Loop, Clamp, Net Material: Steel, Polypropylene, Nylon, Rubber Application: Dairy Farming, Beef Production, Veterinary Clinics, Livestock Auctions End User: Farmers, Veterinarians, Livestock Handlers, Agricultural Cooperatives |
| Companies Covered | Mid Valley Manufacturing Ltd., Schulte CattleQuip, Priefert Manufacturing, Arrowquip, Powder River, WW Manufacturing, Tarter Farm and Ranch Equipment, Behlen Manufacturing, Lakeland Farm and Ranch Direct, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cattle Head Catch Market Strategic Shifts
Equipment intelligence and material science advances are compressing the functional gap between premium automated systems and mid-market alternatives, while regulatory audit requirements are hardwiring compliance features into baseline product specifications.
Sensor-enabled hydraulic chutes with integrated weight capture and electronic identification scanning are rewriting operational workflows in large-scale feedlots. Operators in Kansas and Nebraska are retrofitting existing squeeze chutes with bolt-on load cell arrays and RFID antennae to eliminate separate handling passes for data collection. This convergence is compressing labor requirements per head from three operators to one, fundamentally altering staffing models for commercial yards processing over fifty thousand cattle annually.
OSHA workplace safety standards and state-level handler protection mandates in Texas are tightening guardrail specifications and emergency release mechanisms. Equipment fabricators must now engineer panic-bar systems and anti-kick side panels as standard rather than optional features. The regulatory burden falls heaviest on mid-market manufacturers who lack in-house compliance engineering teams, forcing partnerships with third-party certification consultants to maintain market access.
After-sales service contracts are unbundling from equipment purchase agreements as feedlot operators seek predictable maintenance budgeting. Texas-based distributors now offer tiered service subscriptions covering hydraulic fluid analysis, seal replacement schedules, and emergency call-out response. This shift is most visible in the southern United States where large-scale operators run chutes on three-shift schedules and cannot tolerate unplanned downtime during peak processing windows.
Cattle Head Catch Market Segmentation
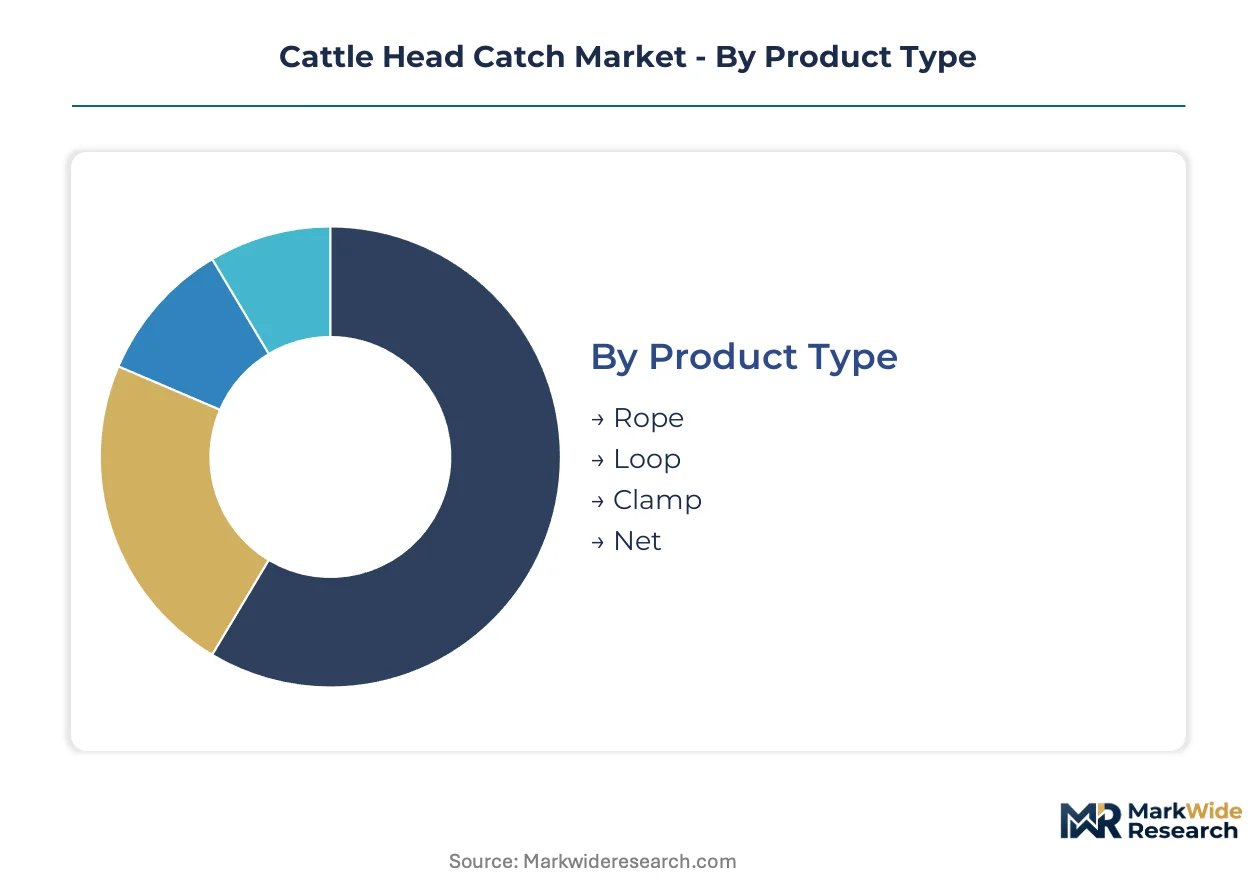
Cattle head catch procurement splits sharply between permanent infrastructure investments and portable restraint solutions. Buyers weigh capital recovery periods against throughput requirements, with material durability and application intensity driving specification choices across the four core segmentation dimensions.
Product Type:
Buyers prioritize restraint security against animal stress metrics when selecting catch mechanisms, with throughput volume dictating mechanical complexity.
- Clamp:Hydraulic or manual steel-framed mechanisms deliver adjustable width settings from 15 to 30 centimeters for breed accommodation. Feedlot operators in Kansas and Texas specify clamp systems for processing over fifty thousand head annually, where single-operator efficiency justifies capital deployment.
- Rope:Braided polypropylene or natural fiber loops enable rapid deployment without fixed infrastructure. Smallholder dairy operations in developing markets favor rope variants for their sub-hundred-dollar entry cost and field-portable characteristics.
- Loop:Continuous-cable designs with sliding lock mechanisms provide intermediate restraint security for mid-scale operations. These systems balance portability against mechanical reliability in veterinary field service applications.
- Net:Mesh restraint systems distribute pressure across broader surface areas for specialized handling of horned breeds or fractious animals. Net configurations see concentrated demand in European Union-certified facilities emphasizing animal welfare audit scores.
Clamp systems lead on scale; rope configurations lead on momentum.
Material:
Corrosive exposure duration and capital recovery horizons determine material specification, with service life expectations ranging from two years to fifteen-plus years.
- Steel:Galvanized tubular construction withstands ammonia-rich feedlot environments and repeated pressure cycling without deformation. USDA-certified facilities mandate steel framing for permanent installations under Humane Methods of Livestock Slaughter Act guidelines.
- Polypropylene:Synthetic rope offers complete corrosion immunity and sub-five-kilogram transport weight for mobile veterinary units. Dairy cooperatives in Brazil's Minas Gerais state specify polypropylene for rotational grazing systems lacking concrete handling infrastructure.
- Nylon:Higher tensile strength than polypropylene with superior UV resistance for outdoor storage conditions. Nylon sees preference in Australian pastoral zones with extreme solar exposure.
- Rubber:Elastomer coatings and inserts reduce noise transmission and thermal conductivity for temperature-sensitive handling. Rubber components integrate as wear surfaces in premium hydraulic chute systems.
Steel dominates installed value; polypropylene climbs the fastest.
Application:
Handling frequency and regulatory scrutiny intensity create divergent specification requirements across end-use environments.
- Beef Production:High-throughput feedlot operations demand automated hydraulic squeeze chutes with integrated weighing and identification scanning. Nebraska and Kansas yards processing three-shift schedules specify heavy-duty configurations rated for continuous daily use.
- Dairy Farming:Routine veterinary procedures and breeding management generate consistent replacement demand cycles. Dairy operations prioritize low-stress restraint designs to maintain milk production trajectories.
- Veterinary Clinics:Mixed-practice facilities require adjustable systems accommodating cattle, horses, and small ruminants. Clinics favor portable chute units with rapid species conversion capabilities.
- Livestock Auctions:High-turnover environments concentrate margin pools in extreme-duty configurations with accelerated cycle times. Auction yards prioritize throughput velocity over individual animal comfort metrics.
Beef production commands capital deployment; dairy farming sustains replacement volume.
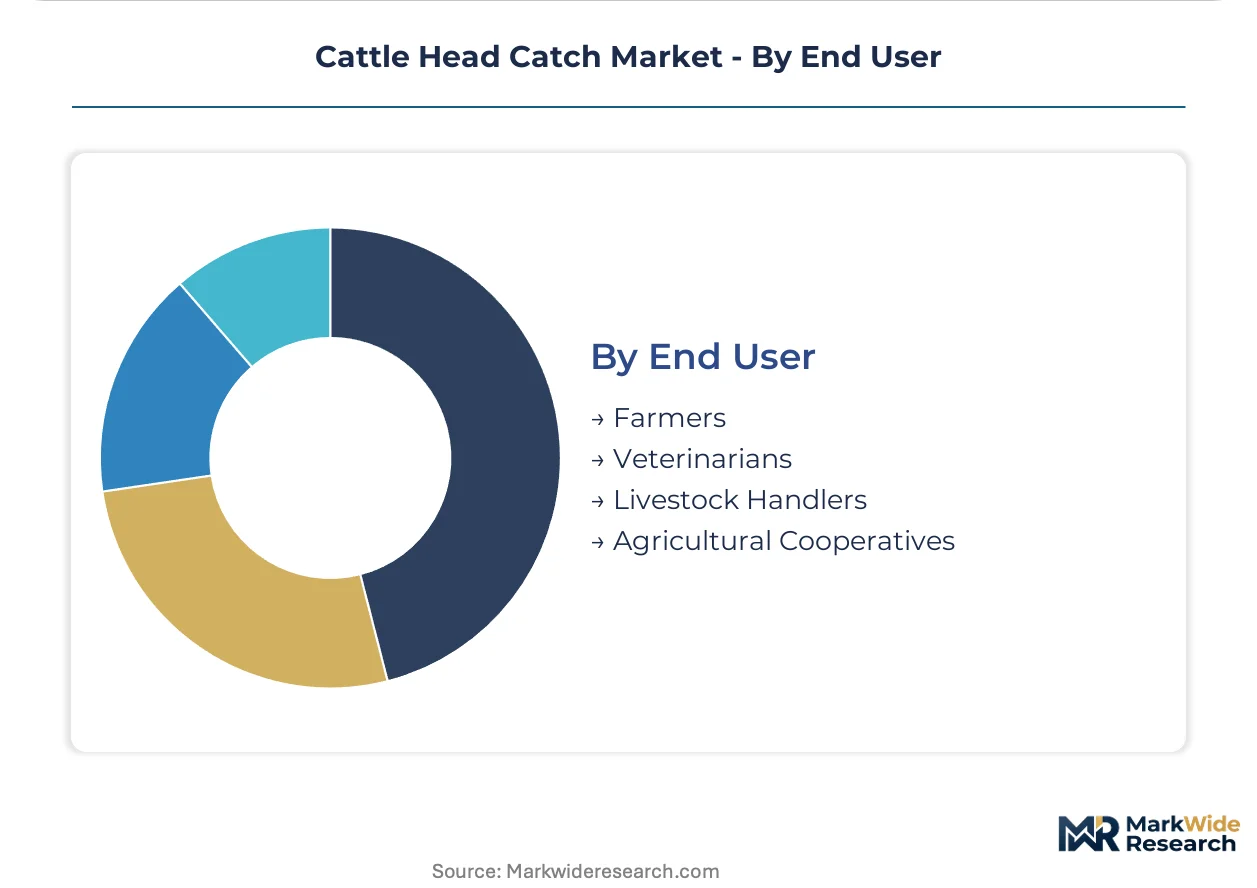
End User:
Procurement authority and technical service access shape buying behavior across operator categories with divergent capital constraints.
- Farmers:Owner-operators weigh equipment financing against tax depreciation schedules and seasonal cash flow patterns. Individual ranchers in Texas and Oklahoma prioritize distributor proximity for emergency parts availability.
- Veterinarians:Mobile practitioners demand lightweight, rapid-deployment systems for field service efficiency. Veterinarians specify equipment with standardized hitch mounting for pickup truck compatibility.
- Livestock Handlers:Professional processing crews prioritize ergonomic design and emergency release mechanisms under OSHA workplace safety standards. Handler safety incident liability drives specification of guardrail-equipped systems.
- Agricultural Cooperatives:Pooled procurement enables volume pricing and shared maintenance infrastructure. Cooperatives in Australia's Queensland standardize equipment fleets to reduce spare parts inventory complexity.
Farmers anchor unit volume; agricultural cooperatives concentrate contract value.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping equipment procurement patterns as Brazilian and Australian operators invest ahead of European Union animal welfare audit requirements while US feedlots absorb stricter OSHA workplace safety mandates. Cost-of-compliance gaps between jurisdictions are accelerating cross-border sourcing of certified hydraulic systems.
United States
Nebraska and Kansas feedlots processing three-shift schedules drive demand for heavy-duty hydraulic squeeze chutes with integrated weighing systems. OSHA workplace safety standards and state-level handler protection mandates in Texas tighten guardrail specifications and emergency release mechanisms. The Texas Panhandle and Oklahoma corridor concentrates large-scale cattle operations replacing legacy manual restraint infrastructure.
Brazil
Amazon basin feedlot operators face upgrade mandates tied to European Union beef export certification requirements under evolving animal welfare audit protocols. ANVISA and Ministry of Agriculture regulations increasingly align with international standards for humane handling equipment. São Paulo and Minas Gerais states host the largest concentration of dairy cooperatives standardizing permanent handling infrastructure.
Australia
Queensland and Northern Territory pastoral stations are consolidating permanent handling infrastructure to meet Asian export market certification requirements. TGA and state-level livestock welfare regulations enforce equipment standards for facilities supplying beef to China and Japan. The Darling Downs region anchors the heaviest concentration of capital investment in automated chute systems.
Canada
Alberta and Manitoba manufacturing clusters supply premium automated segments to North American and southern hemisphere buyers. Health Canada guidelines and provincial animal welfare codes shape product specifications for domestic feedlot operators. The Calgary-Edmonton corridor hosts specialized fabricators serving large-scale ranching operations across the Prairie Provinces.
Germany
Dairy farming cooperatives in Bavaria and Lower Saxony specify low-stress restraint designs to maintain milk production trajectories during routine veterinary procedures. EU Green Deal sustainability criteria and national animal welfare regulations under the Animal Welfare Act drive replacement cycles for older equipment. The Münsterland region concentrates specialized veterinary equipment distributors serving mixed-practice facilities.
Cattle Head Catch Market Competitive Environment
Strategic partnerships dominate the current landscape as fabricators align with hydraulic component suppliers and certification consultants to accelerate compliance timelines. The vendor base splits between premium automated system specialists and mid-market standardized manufacturers competing on replacement part availability. Three archetypes anchor competitive positioning: Canadian premium automated specialists, Texas-based steel fabrication heritage players, and mid-market distributors emphasizing service network density. Geographic expansion into Brazilian and Australian certification-driven markets and technology licensing for sensor-integrated restraint systems represent the dominant competitive moves.
Within the premium automated tier, Arrowquip and Priefert Manufacturing exemplify divergent geographic anchoring strategies. Arrowquip occupies a position tied to Canadian manufacturing concentration and direct-to-ranch distribution networks. Priefert Manufacturing represents Texas steel fabrication heritage sustained through long-standing relationships with large-scale southern US cattle operations. Schulte CattleQuip sits within the mid-market archetype, competing aggressively on standardized designs and replacement part availability rather than automation complexity.
| Leading Market Players |
|---|
| Mid Valley Manufacturing Ltd. |
| Schulte CattleQuip |
| Priefert Manufacturing |
| Arrowquip |
| Powder River |
| WW Manufacturing |
| Tarter Farm and Ranch Equipment |
| Behlen Manufacturing |
| Lakeland Farm and Ranch Direct |
| Others |
Value Chain & Pricing Dynamics
Certified hydraulic technician concentration in Alberta and Manitoba creates labor-cost differentials that widen pricing-tier spreads between premium automated systems and mid-market alternatives. Feedlot operators absorbing extended lead times for southern hemisphere delivery face steeper total cost equations than buyers proximate to Canadian manufacturing clusters.
Pricing Analysis
Distributor margin layers absorb 18-25 points between factory gate and ranch delivery, compressing as direct-to-operator digital channels gain share. Three-tier pricing structure across premium, standard, and economy levels separates sensor-integrated hydraulic systems from manual clamp designs and polypropylene rope variants. Cost compression in the steel-framed mid-market is intensifying because hot-rolled coil volatility passes through fabrication contracts with 90-day lag structures. Smallholder dairy operations exhibit highest price sensitivity, while Nebraska and Kansas feedlot operators prioritize throughput efficiency metrics over capital expenditure minimization.
Supply Chain Analysis
Dual-sourcing requirements from Queensland pastoral stations and Texas Panhandle feedlots mandate multi-supplier qualification across Canadian and US fabrication bases. Geographic supply concentration centers on Canada, the United States, and Australia for finished equipment, with steel tubing drawing from domestic North American mills and hydraulic components sourcing from established industrial distribution networks. Single-source vulnerability persists in high-pressure hydraulic circuit certification, where qualified technician scarcity extends service response windows. Distribution runs through specialized agricultural equipment dealers with captive service territories, supplemented by direct-to-ranch digital channels for standardized configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cattle head catch market functions as a stable compounder anchored by regulatory upgrade mandates that refresh installed bases on predictable cycles regardless of commodity price volatility.
For Market Incumbents: Lock in after-sales service contract penetration across existing installed bases before mobile chute rental networks achieve critical density. Defensive consolidation through backward integration into hydraulic component supply secures margin control against steel price volatility. Certification engineering partnerships with third-party consultants maintain ISO 10954 compliance timelines as a competitive moat against mid-market fabricators lacking in-house regulatory capacity.
For New Entrants and Emerging Players: Direct-to-ranch e-commerce routes bypass established dealer territories and capture price-sensitive mid-scale operators in Texas and Oklahoma. White-space concentration in Brazilian Amazon basin feedlot infrastructure upgrade cycles offers penetrable entry before European Union audit requirements harden specification thresholds. Mobile veterinary service bundling with per-head pricing models lowers barrier to entry for dairy cooperatives in Minas Gerais state.
For Investors and Strategic Acquirers: Agricultural equipment distributors with captive service networks are the most active acquirer in this space, seeking geographic footprint expansion and technician workforce consolidation. Long-term viability over a 5-10 year window rests on sensor-integrated system penetration rates and regulatory audit stringency trajectories. Acquisition target archetypes include mid-market fabricators with standardized design platforms and dense replacement parts distribution. The signal to watch is state-level animal welfare legislation progression in Nebraska, Kansas, and Texas, where handling facility audit requirements would accelerate equipment replacement timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Sensor-Integrated System Development | Convergence of load cell weighing with hydraulic controls enables real-time data capture for individual animal management protocols. |
| Certification Engineering Partnership | Third-party consultant alliances compress ISO 10954 validation cycles for European Union and Australian market access. |
| After-Sales Service Unbundling | Tiered maintenance subscriptions covering hydraulic fluid analysis and seal replacement generate predictable recurring revenue streams. |
| Mobile Chute Rental Network | Per-head pricing models lower capital barriers for mid-scale operators while capturing margin from seasonal processing peaks. |
| Backward Integration into Hydraulics | In-house production of high-pressure circuit components insulates fabrication margins from supplier concentration risk. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with feedlot operations managers, veterinary equipment procurement officers, hydraulic systems maintenance directors, and agricultural cooperative purchasing committees with secondary validation. Secondary sources encompassed USDA livestock handling guideline publications, OSHA workplace safety standard filings, ISO 10954 certification documentation, and customs trade data for agricultural equipment imports. Bottom-up unit demand modeling and top-down market sizing triangulated volume estimates across the analysis window.
Segment-weighting approaches distributed value projections across product type, material specification, application intensity, and end-user procurement authority dimensions. CAGRs derived from historical replacement cycle analysis and regulatory mandate implementation timelines. Industry-specific forecast inputs incorporated feedlot consolidation rates in the United States and Australian pastoral station infrastructure investment patterns.
The model assumes a particular technology adoption path; alternative pathways for sensor-integrated restraint systems would alter the outlook if veterinary data management platform interoperability delays materialize. Forecasts reflect assumptions regarding regulatory audit stringency progression and steel price volatility moderation. Deviation in Brazilian European Union export certification timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Livestock Management
Layer Breeding System Market
Livestock Management
Africa Ruminant Feed Premix Market
Livestock Management
Wild Birds Products Market
Livestock Management
Colombia Animal Feed Market
Livestock Management
Morocco Poultry Market
Livestock Management
South America Ruminant Feed Market
Livestock Management
Cattle Management Software Market
Livestock Management
Digital Livestock Farming Market
Livestock Management
Wagyu Beef Market
Livestock Management
Cattle Feeder Market
Livestock Management
Herd Management Software Market
Livestock Management
Animal Identification Market
Livestock Management
Africa Alfalfa Hay Market
Livestock Management
Europe Ruminant Feed Premix Market
Livestock Management
Smart Feeding Systems Market
Livestock Management
Roughage Feed Market