
 US Agriculture Drone Market | 2026-2036
US Agriculture Drone Market Size, Share, and Industry Trends Forecast 2026-2036
US Agriculture Drone Market Insights
NDVI-grade multispectral imaging is reorganizing competitive positioning across the US agriculture drone landscape. AgEagle Aerial Systems specializes in fixed-wing platforms engineered for broad-acre coverage. Trimble Inc. leverages its precision agriculture software ecosystem to anchor recurring revenue streams. Sentera differentiates through integrated sensor payloads calibrated for crop health analytics.
Agriculture drones are unmanned aerial vehicles equipped with multispectral cameras, LiDAR, or thermal sensors operating at altitudes below 400 feet, designed to capture field-level data for variable-rate input management and yield optimization. Multirotor drones dominate the current installed base due to lower capital requirements and vertical takeoff flexibility, while spraying drones represent the fastest-expanding product category as chemical application regulations evolve. Crop monitoring applications command the largest revenue share, though irrigation management is gaining traction in water-stressed regions of the Central Valley and High Plains.
FAA Part 107 certification requirements and evolving beyond-visual-line-of-sight waiver protocols shape operator density and service model viability across state lines. EPA pesticide application guidelines intersect with drone spraying approvals, creating compliance complexity for equipment manufacturers and aerial applicators. Stakeholders must track state-level agricultural aviation statutes and FAA reauthorization language to anticipate operational freedom and liability frameworks.
Market Dynamics
FAA Part 107 certification expansion and evolving beyond-visual-line-of-sight waiver protocols are compressing operator onboarding timelines and expanding serviceable acreage per pilot across the Midwest Corn Belt.
Growth Catalysts
- NDVI-grade multispectral imaging:Large-scale corn and soybean operations in Iowa, Illinois, and Nebraska deploy calibrated sensor payloads for variable-rate nitrogen management, compressing input waste.
- FAA Part 107 remote pilot certification:Streamlined commercial operator access reduces regulatory friction for aerial applicator service expansion across state lines.
- Water-stressed region demand:Irrigation management applications gain traction in California's Central Valley and the High Plains as groundwater constraints intensify.
Market Restraints
- LiDAR sensor cost concentration:Precision agriculture-grade LiDAR modules remain concentrated among Japanese and German component suppliers, inflating platform BOM costs.
- Beyond-visual-line-of-sight waiver friction:FAA case-by-case BVLOS approval timelines create operational uncertainty for broad-acre coverage providers.
- Manned aerial applicator substitution:Fixed-wing crop dusters retain cost advantages for ultra-large field complexes above 2,000 acres.
Strategic Opportunities
- EPA drone spraying guideline evolution:Chemical application regulation alignment creates white space for purpose-built spraying drone OEMs.
- Software ecosystem convergence:Precision agriculture platforms integrating drone data with variable-rate prescription tools capture recurring revenue.
- Nebraska-Iowa service corridor:Underpenetrated mid-sized operations between 500-1,500 acres lack dedicated drone service provider density.
Industry Challenges
- Part 107 pilot skill gaps:Commercial operators struggle to recruit certified remote pilots with agronomic interpretation capabilities.
- Multispectral data integration:Legacy farm management information systems lack native APIs for real-time NDVI feed ingestion.
- State agricultural aviation statute fragmentation:Liability frameworks and insurance requirements vary across Illinois, Iowa, and Nebraska, complicating multi-state service scaling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Agriculture Drone Market |
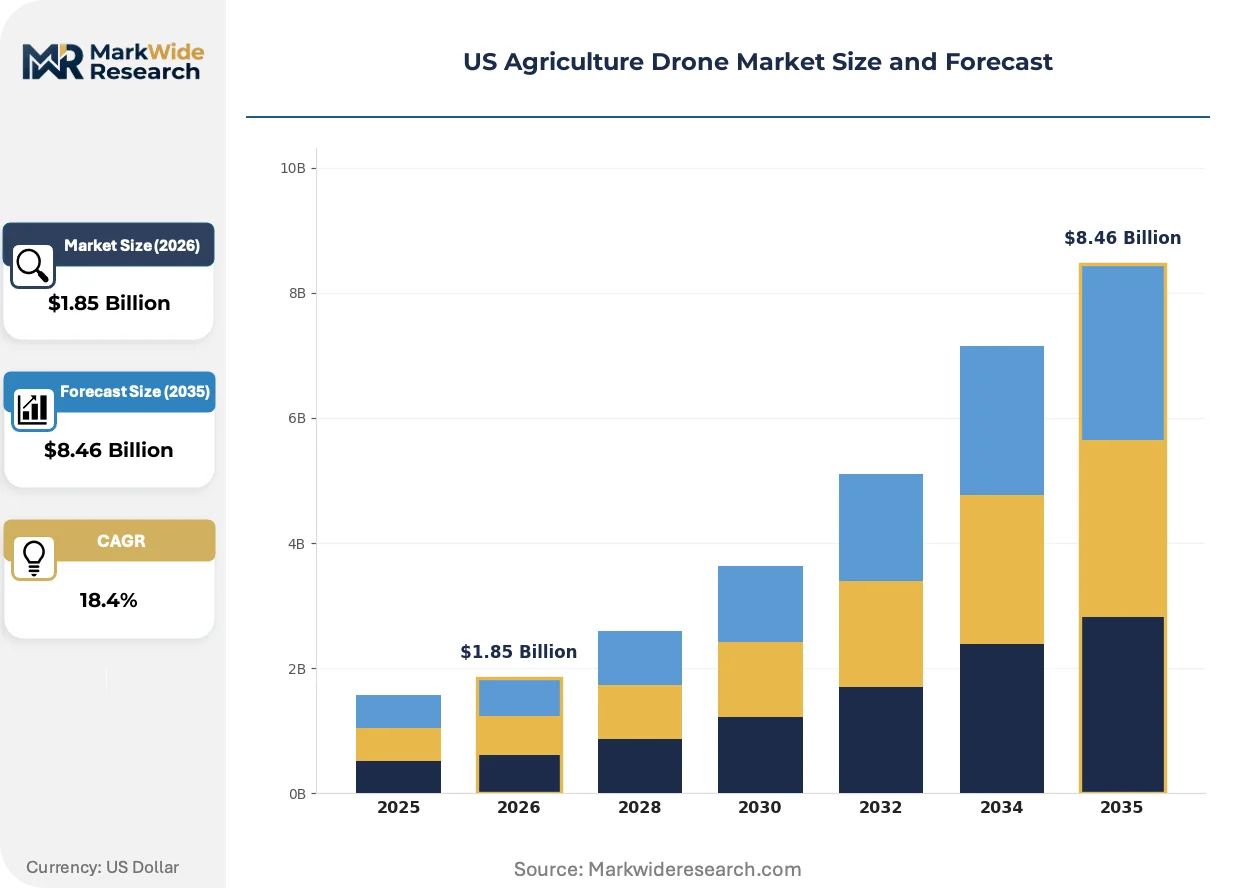
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $8.46 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Multirotor Drones, Fixed-Wing Drones, Hybrid Drones, Spraying Drones Application: Crop Monitoring, Soil Analysis, Pest Control, Irrigation Management End User: Farmers, Agricultural Cooperatives, Research Institutions, Agronomy Consultants Technology: Remote Sensing, Aerial Imaging, GIS Integration, Autonomous Navigation |
| Companies Covered | Trimble Inc., AgEagle Aerial Systems Inc., DroneDeploy, AeroVironment, Inc., PrecisionHawk, Inc., Hylio, Sentera, 3D Robotics, American Robotics, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Agriculture Drone Market Trends and Innovations
Spray-capable platforms and autonomous flight systems are compressing the labor-intensity of precision agriculture while regulatory frameworks race to keep pace with operational expansion.
Autonomous swarm coordination software is displacing single-pilot single-drone operations as the dominant service model. Aerial applicator cooperatives in the Corn Belt deploy coordinated multi-UAV fleets for chemical application, reducing per-acre labor hours by over half. This operational compression is forcing smaller independent operators into equipment-sharing networks or exit.
FAA reauthorization language under Congressional review proposes standardized BVLOS corridors for agricultural operations below 400 feet. The regulatory shift would eliminate waiver-by-waiver processing delays that currently throttle service scalability. Midwestern states with established unmanned aircraft test ranges stand to capture disproportionate operator licensing density.
Cooperative procurement consortia among mid-scale growers are consolidating equipment purchasing power and displacing individual farm ownership models. These buyer groups negotiate fleet leasing terms with regional service providers, unbundling hardware capital risk from operational execution. The pattern is most visible in Illinois where grain handling cooperatives extend into aerial input application services.
US Agriculture Drone Market Segmentation
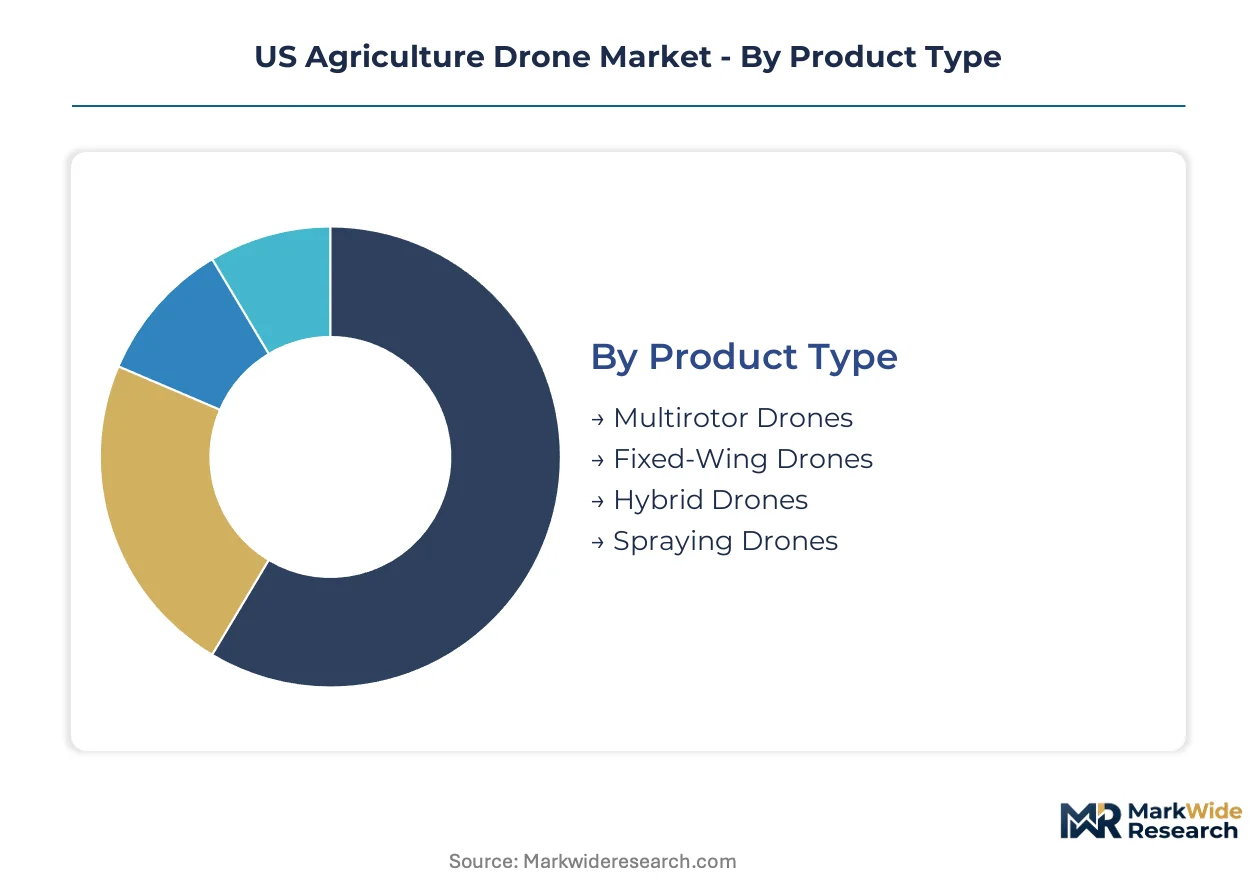
Segmentation in the US agriculture drone market reveals distinct operational profiles across product architectures and use cases. Each category reflects divergent capital intensity, regulatory exposure, and service scalability requirements that shape vendor positioning.
Product Type:
Domestic demand concentrates in multirotor and fixed-wing platforms serving Midwest row-crop operations, while spraying drones face export-oriented component sourcing from Asian sensor suppliers.
- Multirotor Drones:Vertical takeoff capability and sub-$15,000 entry pricing dominate the installed base across Iowa and Illinois corn operations. Demand clusters with certified Part 107 pilots serving 500-1,500 acre farms lacking dedicated aerial applicator contracts.
- Fixed-Wing Drones:Extended endurance above 90 minutes and broad-acre coverage efficiency position these platforms for Nebraska's ultra-large field complexes. FAA BVLOS waiver limitations currently constrain operational radius despite superior per-acre economics.
- Hybrid Drones:VTOL-range combinations address Central Valley orchard topography where runway access is limited.
- Spraying Drones:EPA guideline alignment for chemical application drives equipment certification timelines and OEM R&D concentration.
Multirotor drones hold the largest share; momentum sits with spraying drones as regulatory frameworks mature.
Application:
Cost tier differentiation separates subscription-based monitoring services from capital-intensive spraying contracts, with mid-tier soil analytics gaining traction among precision agriculture adopters.
- Crop Monitoring:NDVI-grade multispectral imaging enables variable-rate nitrogen prescription across Corn Belt operations. Iowa and Illinois growers deploy weekly overflight schedules during critical growth stages to compress input waste.
- Irrigation Management:Thermal sensor payloads identify moisture stress patterns in California's Central Valley and High Plains groundwater districts. Water allocation constraints intensify ROI calculations for precision irrigation scheduling.
- Soil Analysis:LiDAR-equipped platforms generate elevation and compaction maps for pre-planting tillage optimization.
- Pest Control:Early-season scouting applications concentrate in integrated pest management programs for specialty crop regions.
Crop monitoring commands the largest revenue base; irrigation management is climbing the fastest as water stress intensifies across western producing regions.
End User:
Customer type determines procurement modality, with cooperatives consolidating fleet purchasing power against individual farm ownership models.
- Farmers:Individual operators below 1,000 acres favor leasing arrangements and per-acre service contracts to avoid capital risk concentration. Equipment-sharing networks in Illinois reduce idle time through coordinated scheduling.
- Agricultural Cooperatives:Grain handling cooperatives extending into aerial application services leverage existing member relationships and seasonal labor pools. These entities negotiate volume discounts with regional service providers.
- Agronomy Consultants:Independent advisors bundle drone data interpretation with variable-rate prescription services.
- Research Institutions:University extension programs drive calibration standards for sensor payload accuracy.
Agricultural cooperatives hold the largest share; momentum sits with agronomy consultants as data integration complexity rises.
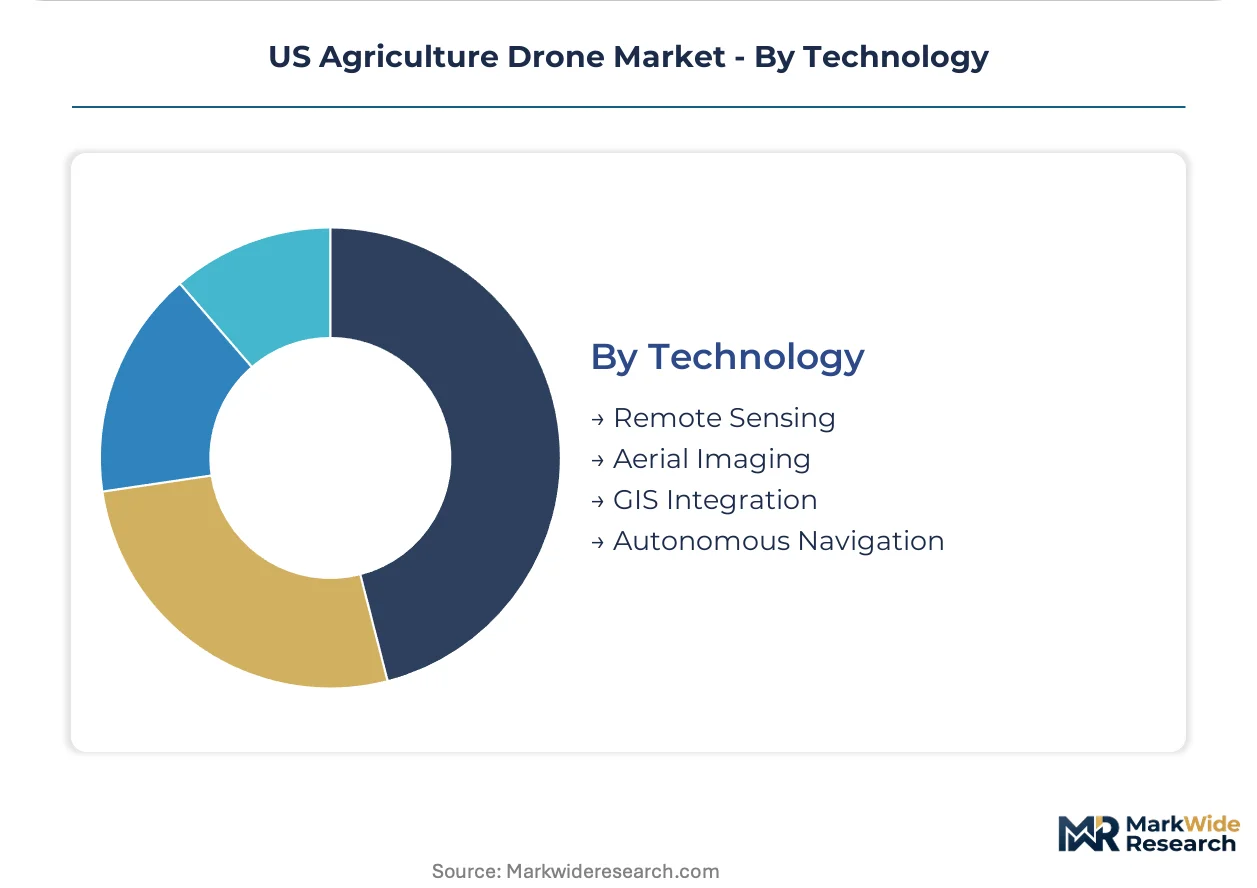
Technology:
Supply concentration in imaging hardware versus distributed software development creates divergent margin structures across the technology stack.
- Remote Sensing:Multispectral and thermal sensor modules from Japanese and German suppliers anchor platform BOM costs. Calibration drift issues in high-dust field environments drive recurring service revenue for sensor maintenance.
- Autonomous Navigation:Swarm coordination software displaces single-pilot operations as Corn Belt aerial applicator cooperatives deploy coordinated multi-UAV fleets. Labor hour compression exceeds 50% versus conventional piloted approaches.
- Aerial Imaging:Real-time NDVI feed ingestion requires API development for legacy farm management information systems.
- GIS Integration:Precision agriculture software ecosystems anchor recurring revenue through subscription-based prescription tools.
Remote sensing holds the largest share; autonomous navigation is expanding most quickly as labor constraints intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US agriculture drone market exhibits pronounced regional concentration patterns shaped by crop mix density, water stress severity, and FAA regulatory infrastructure maturity. Export intensity remains minimal given the service-oriented nature of domestic aerial application, while component import dependency concentrates in multispectral sensor modules from Japanese and German suppliers.
Iowa
Corn and soybean operations exceeding 1,000 acres drive multispectral imaging adoption for variable-rate nitrogen management. The FAA's Des Moines Flight Standards District Office processes Part 107 certifications at above-national rates. The Ames-Des Moines corridor hosts equipment-sharing networks that coordinate drone scheduling across mid-sized farms lacking dedicated aerial applicator contracts.
Illinois
Grain handling cooperatives extending into aerial application services leverage existing member relationships for fleet purchasing power consolidation. State agricultural aviation statutes require liability insurance minimums that exceed neighboring jurisdictions, complicating multi-state operator scaling. The Champaign-Urbana research cluster drives sensor payload calibration standards through University of Illinois extension programs.
Nebraska
Ultra-large field complexes above 2,000 acres favor fixed-wing platforms for broad-acre coverage efficiency despite BVLOS waiver constraints. Groundwater management district regulations intensify irrigation management demand as allocation constraints tighten. The Lincoln-Omaha corridor anchors autonomous swarm coordination software development for aerial applicator cooperatives deploying multi-UAV fleets.
California
Central Valley specialty crop regions deploy thermal sensor payloads for moisture stress identification as surface water deliveries contract. EPA pesticide application guidelines intersect with state agricultural aviation statutes to create compliance complexity for spraying drone operators. The Fresno-Bakersfield axis concentrates LiDAR-equipped soil analysis services for pre-planting tillage optimization in orchard topography.
US Agriculture Drone Market Competitive Landscape
Listed leaders compete with private specialists across platform architecture and software ecosystem dimensions. The vendor base separates into three tiers: publicly traded precision agriculture conglomerates with integrated software-hardware stacks, venture-backed specialists in fixed-wing or spraying configurations, and regional service providers operating leased equipment fleets. Strategic moves concentrate on M&A for sensor payload capabilities and strategic partnerships for BVLOS corridor access.
Within the precision agriculture software tier, Trimble Inc. and DroneDeploy occupy positions anchored to recurring revenue models through variable-rate prescription tool integration. AgEagle Aerial Systems exemplifies the fixed-wing specialist archetype with broad-acre coverage positioning. Sentera sits within the integrated sensor payload segment, representing the crop health analytics calibration approach that differentiates beyond commodity hardware.
| Leading Market Players |
|---|
| Trimble Inc. |
| AgEagle Aerial Systems Inc. |
| DroneDeploy |
| AeroVironment, Inc. |
| PrecisionHawk, Inc. |
| Hylio |
| Sentera |
| 3D Robotics |
| American Robotics, Inc. |
| Others |
Pricing and Supply Chain Analysis
Per-acre service contracts with multi-season lock-ins anchor pricing visibility for Midwest corn and soybean operators while tethering equipment utilization rates to seasonal weather windows and FAA flight authorization timelines. These agreements compress capital risk for farms below 1,500 acres and concentrate pricing power with regional aerial applicator cooperatives holding certified Part 107 pilot pools.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in the US agriculture drone market. Premium tiers bundle NDVI-grade multispectral calibration with EPA-compliant spraying certification, while standard tiers target crop monitoring without chemical application rights. Cost compression in the economy tier stems from Asian-sourced multirotor platforms flooding the sub-$10,000 entry segment. Price differentiation separates sensor-integrated bundles from bare hardware, with agronomic software subscriptions extracting recurring revenue. Cooperative buyers exhibit lowest price sensitivity due to consolidated fleet purchasing power, whereas individual farmers below 500 acres face acute budget constraints.
Supply Chain Analysis
Strategic stockpile preferences concentrate among fixed-wing specialists buffering against Japanese and German LiDAR sensor lead times, while multirotor assemblers operate on just-in-time component flows from Chinese motor and battery suppliers. Geographic supply concentration centers on China for lithium-polymer batteries and carbon fiber airframes, Japan for precision multispectral imagers, and Germany for agriculture-grade LiDAR modules. Raw material dependencies include rare earth magnets for brushless motors, high-purity silicon for imaging sensors, and aerospace-grade composites for airframe durability. Single-source vulnerability in EPA-certified spraying nozzle assemblies creates procurement bottlenecks for chemical application platforms. Distribution runs through regional equipment dealers and direct-to-cooperative fleet leasing arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified remote pilots with simultaneous agronomic interpretation capabilities represent the critical bottleneck constraining service scalability across the Corn Belt, with FAA Part 107 issuance rates lagging behind cooperative fleet expansion timelines. This capability gap rewards vendors who bundle training with hardware deployment.
For Market Incumbents: Shield recurring revenue streams by deepening software ecosystem integration with legacy farm management information systems, countering the threat of modular sensor specialists unbundling hardware from data analytics. Prioritize backward integration into EPA-certified spraying nozzle production to capture margin from chemical application regulatory alignment. Channel control through exclusive dealer networks in Iowa and Illinois defends against price erosion from direct-import Asian platforms. For New Entrants and Emerging Players: Lead with autonomous swarm coordination software targeting aerial applicator cooperatives in the Nebraska-Iowa corridor, where labor hour compression demands exceed current vendor fulfillment. The most penetrable segment sits with mid-sized operations between 500-1,500 acres lacking dedicated service provider density. A per-acre outcome-based pricing model with guaranteed input waste reduction metrics accelerates land-grab velocity against incumbent capital-sale approaches. For Investors and Strategic Acquirers: Capital is best deployed toward integrated sensor payload specialists with established EPA calibration protocols and existing relationships with University of Illinois extension programs. Long-term viability over the next decade hinges on BVLOS regulatory maturation enabling broad-acre coverage economics. The signal to watch is FAA reauthorization language standardizing agricultural flight corridors below 400 feet, which would trigger step-function demand inflection for fixed-wing platform operators.| Strategic Initiative | Industry Significance |
|---|---|
| EPA Spraying Certification Investment | Unlocks chemical application revenue streams as drone-specific pesticide guidelines align with aerial applicator licensing frameworks. |
| BVLOS Corridor Partnership | Secures operational scalability for Nebraska fixed-wing operators awaiting FAA waiver standardization. |
| Cooperative Fleet Leasing Expansion | Captures consolidated purchasing power of Illinois grain handling cooperatives extending into aerial services. |
| Sensor Payload Calibration Acquisition | Integrates University of Illinois extension relationships and NDVI-grade imaging standards into hardware offerings. |
| Autonomous Swarm Software Development | Compresses labor hours below 50% of single-pilot operations for Corn Belt aerial applicator cooperatives. |
Research Methodology
Operator-level perspectives from Part 107 certified remote pilots, aerial applicator cooperative managers, agronomy consultants, and EPA compliance officers anchored the qualitative base for this analysis. Primary interviews with equipment-sharing network coordinators in Iowa and Illinois supplemented field-level operational data. Secondary validation drew from FAA certification issuance databases, USDA National Agricultural Statistics Service crop acreage reports, EPA pesticide application guideline dockets, and SEC filings of publicly traded precision agriculture vendors. Bottom-up triangulation across state-level agricultural aviation statutes merged with top-down demand modeling from corn and soybean planted acreage trends.
Sensitivity analysis tested forecast robustness against BVLOS regulatory acceleration scenarios, LiDAR sensor cost deflation curves, and cooperative procurement consolidation rates across the projection horizon. Segmentation dimensions modeled include product architecture, application use case, end-user procurement modality, and technology stack layer. CAGRs derived from installed base expansion rates, replacement cycle compression, and service revenue per acre trajectories. Industry-specific inputs encompassed FAA Part 107 certification velocity, groundwater management district regulation tightening in Nebraska, and Central Valley surface water allocation constraints.
The analysis sits within stated boundaries; outcomes outside sustained FAA regulatory streamlining and EPA guideline alignment timelines would require recalibration. Forecasts reflect documented assumptions regarding sensor cost trajectories and cooperative fleet adoption curves. Revision becomes warranted when BVLOS waiver approval velocity crosses thresholds that enable fixed-wing platform economics at scale.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Machinery
Germany Agricultural Tractor Machinery Market
Agricultural Machinery
Global Autopilot Agricultural Vehicle Market
Agricultural Machinery
Milking Robots Market
Agricultural Machinery
Europe Agricultural Sprayer Market
Agricultural Machinery
Tiller Machine Market
Agricultural Machinery
Agriculture Sprayers Market
Agricultural Machinery
Agricultural Tractor Market
Agricultural Machinery
United States Agricultural Tractor Market
Agricultural Machinery
Tractor Implements Market
Agricultural Machinery
Agricultural Machinery Market
Agricultural Machinery
United States Agricultural Machinery Market
Agricultural Machinery
United States Haying and Forage Machinery Market
Agricultural Machinery
Autonomous Farm Equipment Market
Agricultural Machinery
Southeast Asia Agricultural Tractors Market
Agricultural Machinery
Vietnam Agricultural Machinery Market
Agricultural Machinery
Garden Tractor Market