
 Agricultural Forestry Machinery Market | 2026-2036
Agricultural Forestry Machinery Market Size, Share, and Industry Trends Forecast 2026-2036
Agricultural Forestry Machinery Market Intelligence
The capital-intensity divergence between full-line manufacturers and specialized forestry equipment producers is collapsing as telemetry and autonomous systems become table stakes. Deere & Company leverages its precision agriculture ecosystem to extend control over fleet management software across both farm and forest applications. AGCO Corporation anchors its competitive stance through deep specialization in harvesting mechanics, while Kubota Corporation dominates compact tractor segments across Asian and European distribution networks.
Agricultural forestry machinery encompasses self-propelled and towed equipment engineered for soil cultivation, timber extraction, and crop harvesting, typically featuring hydraulic power outputs exceeding 100 kW and operating weights ranging from 3 to 30 tonnes depending on application intensity. Tractors and harvesters constitute the largest installed base, though margin pools increasingly concentrate in autonomous systems and GPS guidance technologies where software recurring revenue offsets hardware cyclicality. Forwarders and skidders retain steady replacement demand in mature Nordic and North American forestry markets, while feller bunchers see accelerated uptake in mechanized tropical logging concessions.
EPA Tier 4 Final and EU Stage V emissions frameworks have forced engine architecture redesigns, elevating development costs and consolidating supplier tiers around compliant powertrain partners. OSHA machinery guarding standards and ISO 12100 safety protocols further shape product configuration for North American and European market access. Stakeholders must weigh the pace of autonomous regulatory certification against the operational savings these systems promise in labor-constrained harvesting environments.
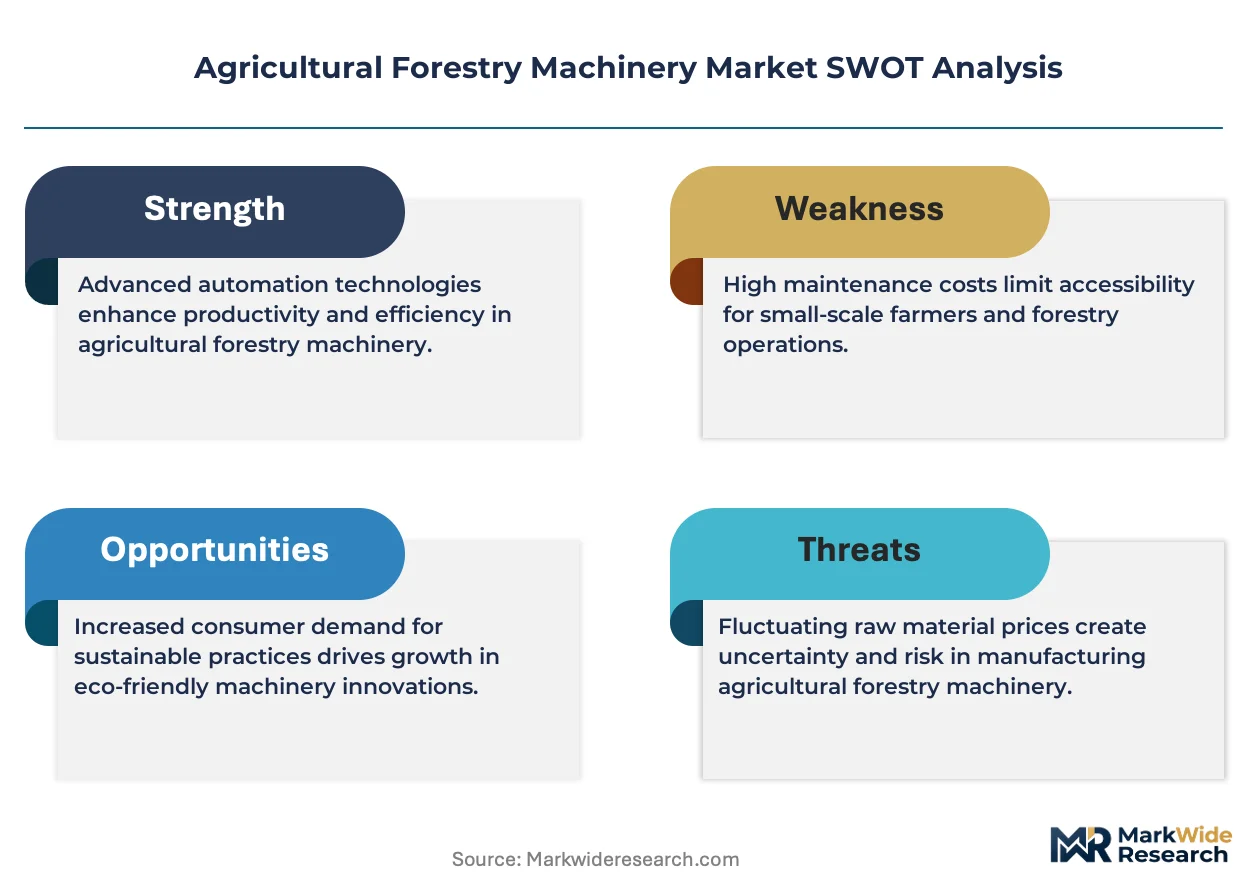
Market Dynamics
Precision forestry platforms are consolidating control over equipment fleets as telemetry integration becomes mandatory for contractor qualification in mechanized harvesting concessions.
Growth Catalysts
- EU F-Gas Regulation:Tightened emissions standards for hydraulic systems are forcing fleet modernization across Scandinavian forestry contractors, accelerating replacement cycles for legacy harvesters and forwarders.
- Mato Grosso mechanization:Brazilian agribusiness operators are replacing aging equipment with precision-capable platforms to maintain productivity in large-scale soy-corn-timber rotation systems.
- GPS guidance integration:Autonomous path-planning systems are reducing operator skill requirements and enabling 24-hour harvesting operations in Nordic softwood concessions.
Market Restraints
- High-alloy steel volatility:Boom and stick fabrication depends on specialized wear-resistant plate grades subject to supply concentration from Nordic mills.
- Tier 4 Final compliance costs:EPA-mandated aftertreatment systems add substantial capital burden to sub-100 kW equipment categories where margins are thinnest.
- Electrification physics:Battery energy density limitations prevent meaningful substitution in high-draw feller buncher and skidder applications requiring sustained hydraulic output.
Strategic Opportunities
- Indonesian concession digitization:Tropical logging operators lack telemetry infrastructure, creating first-mover advantage for integrated platform providers.
- Carbon credit verification:ISO 14064-aligned biomass tracking creates recurring software revenue from harvest monitoring in EU-managed forests.
- Remanufacturing ecosystems:Component rebuild programs anchored in Alberta and Wisconsin extend asset life while capturing service revenue from price-sensitive owner-operators.
Industry Challenges
- Autonomous certification timelines:ISO 12100 safety protocols lack harmonized interpretation across national forestry inspectorates, delaying unmanned forwarder deployment.
- Legacy hydraulic integration:Retrofitting 1990s-era skidders with telematics requires proprietary CAN bus adapters that fragment fleet management software compatibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Agricultural Forestry Machinery Market |
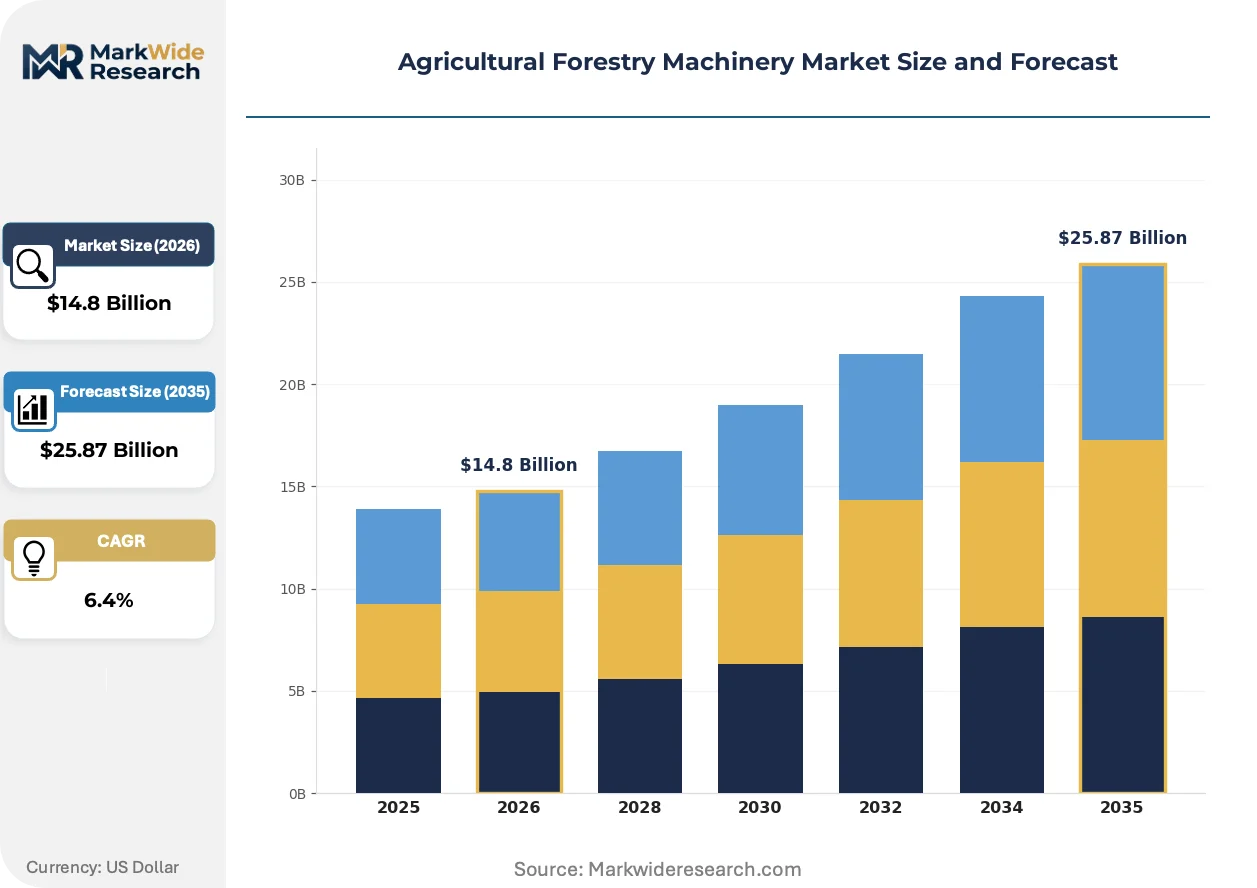
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $25.87 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tractors, Harvesters, Forwarders, Skidders, Feller Bunchers Technology: GPS Guidance, Autonomous Systems, Telemetry, Precision Farming, Remote Sensing Application: Cultivation, Timber Extraction, Land Preparation, Crop Harvesting, Soil Management End User: Farmers, Forestry Contractors, Landowners, Agricultural Cooperatives, Timber Processors |
| Companies Covered | Komatsu Ltd, AGCO Corporation, Deere & Company, Hitachi Construction Machinery, Kubota Corporation, CNH Industrial, AB Volvo, Doosan Infracore, Caterpillar Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Agricultural Forestry Machinery Market Strategic Shifts & Innovations
Telematics penetration is redefining equipment value propositions as hardware margins compress and recurring software revenue becomes the primary profit engine.
Electro-hydraulic valve architectures are supplanting mechanical linkages in harvester head control systems. Large-scale contractors in Finland and Sweden are specifying these platforms for new fleet acquisitions. The shift is compressing aftermarket parts revenue for traditional hydraulic component suppliers while enabling real-time pressure diagnostics.
EPA Tier 4 Final and EU Stage V frameworks have forced complete engine architecture redesigns across the 130-250 kW power band. Development cost escalation has consolidated supplier tiers around compliant powertrain partners with captive aftertreatment capabilities. North American forwarder manufacturers are absorbing compliance costs through extended depreciation schedules rather than price increases.
Outcome-based maintenance contracts are displacing traditional time-and-materials service arrangements in Nordic forestry operations. Equipment-as-a-service providers in Norway and Sweden bundle telemetry, consumables, and uptime guarantees into per-cubic-meter harvesting fees. This model concentrates purchasing authority with fleet management platforms and marginalizes independent dealer networks.
Agricultural Forestry Machinery Market Segmentation
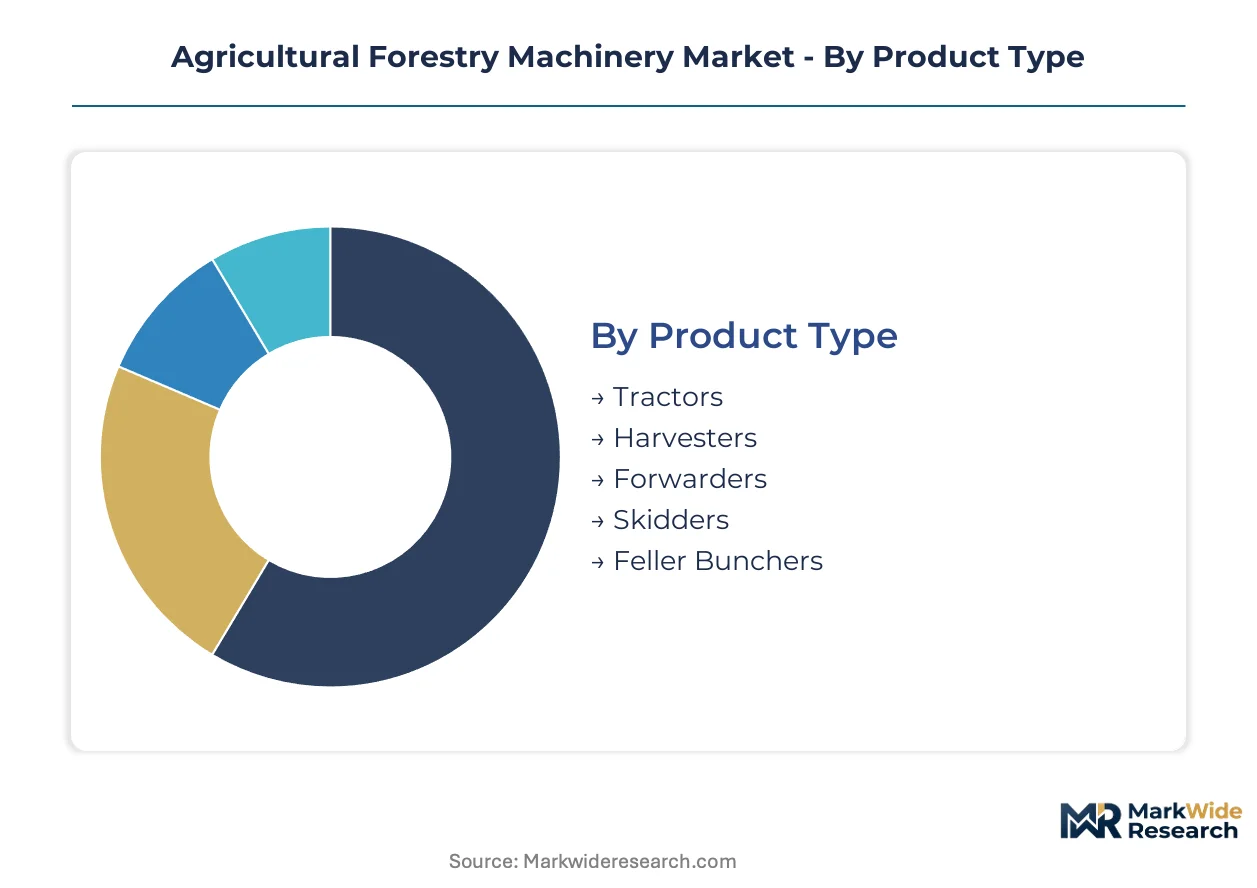
Segmentation in agricultural forestry machinery determines equipment specification, financing terms, and aftermarket revenue potential. Product architecture, technology integration level, and end-user scale each create distinct margin profiles and replacement cycle dynamics.
Product Type:
EPA Tier 4 Final and EU Stage V emissions standards impose divergent compliance costs across power bands, reshaping manufacturer product mix priorities.
- Tractors:Self-propelled platforms with hydraulic outputs exceeding 100 kW anchor the installed base in cultivation and towing applications. Demand concentrates in Brazil's Mato Grosso region where large-scale agribusiness operators replace aging fleets with precision-capable models to maintain productivity in soy-corn-timber rotations.
- Harvesters:Mechanized felling and processing heads mounted on tracked or wheeled carriers dominate Nordic softwood concessions. Scandinavian forestry contractors are expanding mechanized harvesting fleets as EU F-Gas Regulation tightens emissions standards for hydraulic systems, accelerating replacement cycles for legacy units.
- Forwarders:Load-carrying platforms with articulated steering and hydraulic cranes retain steady replacement demand in mature Nordic and North American forestry markets.
- Skidders:Cable and grapple configurations for timber extraction face retrofitting challenges when integrating telemetry due to proprietary CAN bus adapter fragmentation.
- Feller Bunchers:High-draw hydraulic systems for sustained felling operations see accelerated uptake in mechanized tropical logging concessions despite battery energy density limitations preventing meaningful electrification.
Established volume favors Tractors; emerging adoption favors Feller Bunchers.
Technology:
Cost tier differentiation separates premium integrated platforms from retrofit add-ons, with recurring software revenue offsetting hardware cyclicality.
- GPS Guidance:Autonomous path-planning systems reduce operator skill requirements and enable 24-hour harvesting operations in Nordic softwood concessions.
- Autonomous Systems:Unmanned forwarder deployment faces delays as ISO 12100 safety protocols lack harmonized interpretation across national forestry inspectorates.
- Telemetry:Real-time equipment monitoring consolidates control over equipment fleets as integration becomes mandatory for contractor qualification in mechanized harvesting concessions.
- Precision Farming:Variable-rate application technologies extend from agriculture into plantation forestry for optimized nutrient delivery.
- Remote Sensing:Satellite and aerial biomass assessment tools support carbon credit verification under ISO 14064-aligned tracking protocols.
Telemetry captures the steepest expansion trajectory; Precision Farming holds the deepest untapped penetration in tropical concessions.
Application:
Customer type determines equipment duty cycle intensity and financing structure, from owner-operator cash purchases to fleet-as-a-service arrangements.
- Cultivation:Soil preparation and tillage operations using tractors with 3-30 tonne operating weights depending on application intensity.
- Timber Extraction:Forwarders and skidders retain steady replacement demand in mature Nordic and North American forestry markets.
- Land Preparation:Site clearing and stump removal equipment faces seasonal utilization patterns in plantation establishment cycles.
- Crop Harvesting:Combine and forage platforms overlap with agricultural machinery in mixed farming-forestry operations.
- Soil Management:Subsoiling and drainage installation equipment supports long-rotation timber productivity.
Timber Extraction commands the highest equipment specialization; Land Preparation offers the broadest cross-application flexibility.
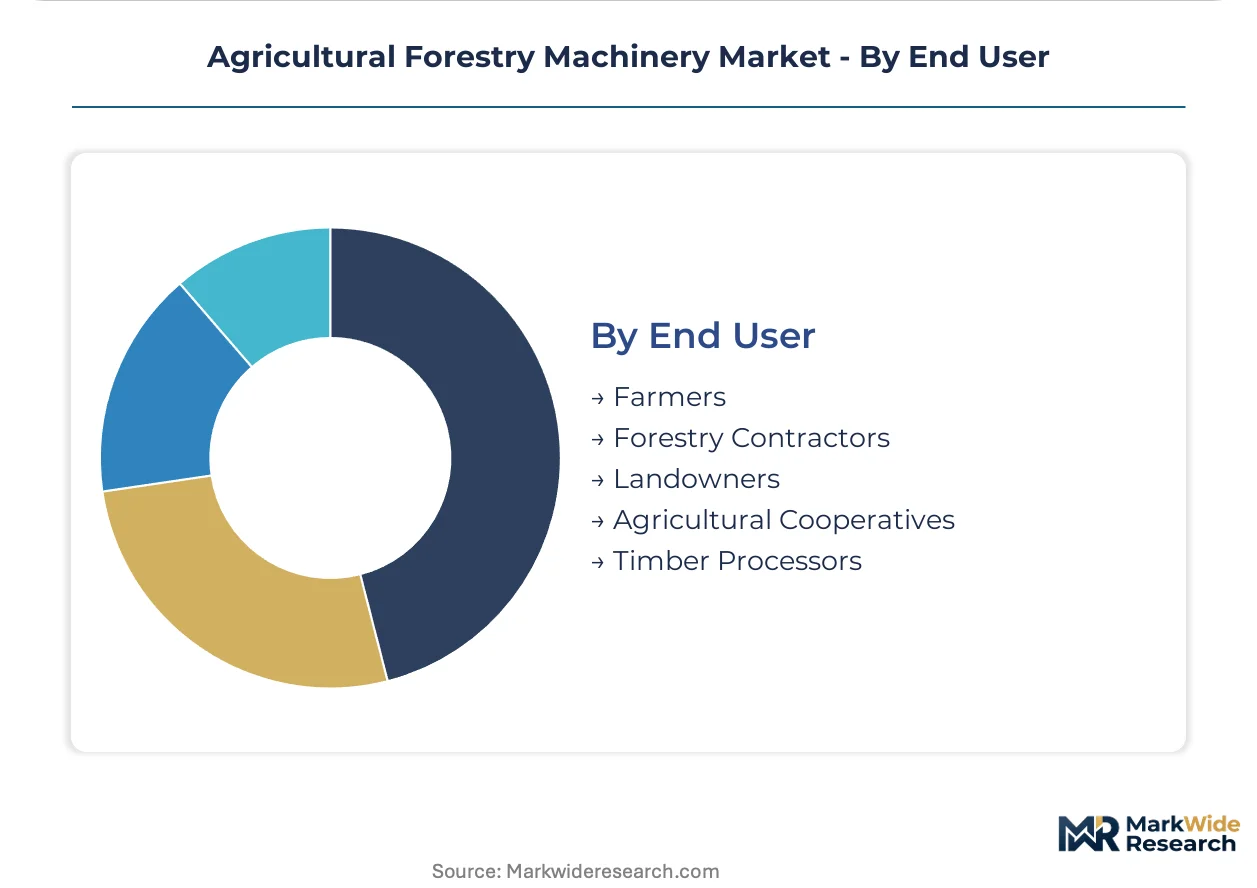
End User:
Procurement scale separates price-sensitive independents from integrated fleet operators demanding outcome-based contracts.
- Farmers:Owner-operators in mixed agricultural-forestry systems prioritize equipment versatility across crop and timber cycles.
- Forestry Contractors:Mechanized harvesting specialists in Scandinavia are expanding fleets as EU F-Gas Regulation tightens emissions standards for hydraulic systems.
- Landowners:Non-industrial private forest holders represent fragmented demand captured by dealer service networks.
- Agricultural Cooperatives:Pooled equipment purchasing concentrates negotiating leverage for precision technology bundles.
- Timber Processors:Vertically integrated mill operators specify harvesting equipment aligned with log dimension and species requirements.
Forestry Contractors drive telemetry adoption fastest; Agricultural Cooperatives concentrate price negotiation leverage most effectively.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Forestry contractors in Brazil absorb steep equipment premiums with limited negotiation leverage, while Nordic operators command outcome-based contracts that shift capital risk to manufacturers. This demand-elasticity divide separates price-tolerant plantation markets from service-integrated mature forestry regions.
United States
Timberland investment trusts in the Pacific Northwest and Southeast are modernizing forwarder fleets to meet OSHA machinery guarding standards. EPA Tier 4 Final compliance costs concentrate equipment purchasing decisions among larger integrated operators. Wisconsin and Alberta anchor remanufacturing ecosystems that extend asset life for price-sensitive owner-operators.
Brazil
Agribusiness operators in Mato Grosso replace aging harvesters with precision-capable platforms to maintain productivity across soy-corn-timber rotations. ANVISA equipment certification requirements shape import timelines for European and Asian manufacturers. São Paulo-based financing consortia structure lease arrangements that concentrate fleet ownership among integrated plantation groups.
Sweden
Mechanized harvesting contractors expand fleet capacity as EU F-Gas Regulation tightens emissions standards for hydraulic systems. The Swedish Forestry Agency mandates telemetry integration for concession qualification, accelerating replacement cycles for legacy harvesters. Västerbotten and Norrbotten counties concentrate autonomous forwarder trials under ISO 12100 safety protocol pilots.
Germany
Precision agriculture specialists extend control software into plantation forestry applications across Baden-Württemberg and Bavaria. KBA certification requirements for autonomous systems delay unmanned forwarder deployment timelines. Stuttgart industrial clusters develop electro-hydraulic valve architectures that supplant mechanical linkages in harvester head control systems.
Finland
Outcome-based maintenance contracts displace time-and-materials service arrangements among Nordic forestry cooperatives. The Finnish Transport and Communications Agency Traficom oversees autonomous vehicle testing protocols for unmanned harvesting equipment. Oulu and Tampere regions concentrate equipment-as-a-service providers bundling telemetry and uptime guarantees into per-cubic-meter harvesting fees.
Agricultural Forestry Machinery Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with capital-intensity divergence collapsing as telemetry becomes mandatory across contractor qualification frameworks. Full-line manufacturers leverage precision agriculture ecosystems to extend fleet management software control across both farm and forest applications. Specialist harvester mechanics producers anchor competitive positioning through deep application expertise. Dominant competitive moves include strategic partnerships for compliant powertrain access and geographic expansion into telemetry-underserved tropical concessions.
Within the integrated full-line tier, Deere & Company and AGCO Corporation exemplify divergent strategic positioning. Deere leverages its precision agriculture ecosystem to extend software control across forest applications, while AGCO anchors its stance through deep specialization in harvesting mechanics. Kubota Corporation occupies a distinct position dominating compact tractor segments across Asian and European distribution networks. Komatsu Ltd represents the construction-equipment crossover archetype applying excavator platform expertise to forestry carrier applications.
| Leading Market Players |
|---|
| Komatsu Ltd |
| AGCO Corporation |
| Deere & Company |
| Hitachi Construction Machinery |
| Kubota Corporation |
| CNH Industrial |
| AB Volvo |
| Doosan Infracore |
| Caterpillar Inc. |
| Others |
Cost & Logistics Intelligence
Capacity utilization at Nordic specialty steel mills anchors cost floors for boom and stick fabrication, concentrating supply power among a handful of wear-resistant plate producers while compressing margin headroom for harvester head manufacturers. This scale concentration simultaneously elevates minimum efficient scale for new forging entrants and hardens price resistance among Brazilian plantation operators already absorbing steep equipment premiums.
Pricing Analysis
After-sales service contracts and telemetry subscriptions now drive lifetime value capture, displacing transactional equipment margins as the dominant profit engine. Three-tier pricing structure across premium integrated platforms, mid-range precision-capable models, and economy legacy equipment reflects certification grade differentiation under EPA Tier 4 Final and EU Stage V frameworks. Pricing pressure stems from compliance cost absorption in sub-100 kW categories where hardware margins are thinnest. Forestry contractors in Scandinavia show least price sensitivity due to outcome-based contract structures, while owner-operators in North American remanufacturing hubs exhibit highest elasticity.
Supply Chain Analysis
Baltic Sea port congestion and specialized heavy-lift vessel availability chokepoint equipment delivery schedules for oversized harvester carriers bound for Mato Grosso. High-alloy steel fabrication draws from Swedish and Finnish specialty mills, while hydraulic component sourcing rests on German and Japanese precision valve manufacturers. Single-source vulnerability concentrates in compliant powertrain partners with captive aftertreatment capabilities following EPA Tier 4 Final consolidation. Distribution runs through manufacturer-direct fleet management platforms in Nordic markets and dealer networks serving fragmented North American landowners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Telemetry penetration is expanding recurring software revenue faster than hardware sales, transforming agricultural forestry machinery from capital goods into service-attach businesses where uptime guarantees and per-cubic-meter harvesting fees dominate contractor relationships.
For Market Incumbents: Compound software ecosystem control by embedding fleet management platforms deeper into contractor qualification frameworks, while capturing compliant powertrain capacity through exclusive supplier arrangements before Tier 4 Final consolidation completes. Electrification physics limitations in high-draw applications create defensive moats against battery substitution threats, though electro-hydraulic valve architectures require R&D investment to maintain harvester head control leadership. For New Entrants and Emerging Players: Telemetry infrastructure gaps in Indonesian and Malaysian tropical concessions offer first-mover positioning where integrated platform providers currently under-serve. Carbon credit verification software aligned with ISO 14064 protocols represents the most penetrable application layer, with biomass tracking bundled into harvesting equipment sales as the go-to-market angle against hardware-centric incumbents. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision agriculture software specialists with proven forestry adaptation capability over pure-play equipment manufacturers facing hardware cyclicality. Five-to-ten year viability hinges on recurring revenue ratio expansion rather than installed base growth alone. Watch autonomous forwarder certification harmonization across national forestry inspectorates as the inflection signal for unmanned deployment scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Telemetry Platform Integration | Mandatory contractor qualification in Swedish concessions consolidates fleet control under integrated providers. |
| Compliant Powertrain Partnership | EPA Tier 4 Final consolidation limits supplier tiers to manufacturers with captive aftertreatment capabilities. |
| Carbon Credit Verification Software | ISO 14064-aligned biomass tracking creates recurring revenue from EU-managed forest harvest monitoring. |
| Remanufacturing Ecosystem Expansion | Alberta and Wisconsin rebuild programs extend asset life while capturing service revenue from price-sensitive operators. |
| Electro-Hydraulic Architecture Transition | Real-time pressure diagnostics in harvester heads displace mechanical linkage aftermarket parts revenue. |
Research Approach
Initial hypotheses were tested against primary input from forestry contractor operations managers, OEM aftermarket service heads, and plantation fleet procurement directors, then refined through secondary validation against SEC 10-K filings, equipment registration databases, and customs trade records. Bottom-up triangulation across regional production volumes and top-down reconciliation with macroeconomic indicators anchored value estimates.
Variance decomposition across product type, technology integration level, application intensity, and end-user scale dimensions structured the analytical framework over the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion. Electro-hydraulic adoption curves and autonomous certification timelines served as machinery-specific forecast inputs.
Underlying assumptions cover EPA Tier 4 Final compliance cost trajectories and EU F-Gas Regulation enforcement intensity, with deviation risk concentrated in battery energy density breakthroughs and tropical concession digitization pace. Practitioners should keep alternative scenarios live as autonomous safety protocol harmonization and carbon credit market liquidity evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Machinery
Autonomous Farm Equipment Market
Agricultural Machinery
Wheat Milling Machine Market
Agricultural Machinery
Argentina Agricultural Machinery Market
Agricultural Machinery
Garden Tractor Market
Agricultural Machinery
Asia-Pacific Agricultural Machinery Market
Agricultural Machinery
France Agricultural Machinery Market
Agricultural Machinery
Agricultural Harvester Market
Agricultural Machinery
Vietnam Agricultural Machinery Market
Agricultural Machinery
South America Agricultural Tractors Market
Agricultural Machinery
United States Agricultural Tractor Market
Agricultural Machinery
Driverless Tractor Market
Agricultural Machinery
Forestry Machinery Market
Agricultural Machinery
Southeast Asia Agricultural Tractors Market
Agricultural Machinery
Electric Farm Tractor Market
Agricultural Machinery
Germany Agricultural Tractor Machinery Market
Agricultural Machinery
Global Autopilot Agricultural Vehicle Market