
 Global Autopilot Agricultural Vehicle Market | 2026-2036
Global Autopilot Agricultural Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
Global Autopilot Agricultural Vehicle Market Intelligence
The scarcity of skilled agricultural operators and the concurrent rise of data science expertise is reorganizing farm management priorities. Deere & Company leverages its extensive dealer network and technology stack to dominate the large-scale farm segment. Trimble Inc. specializes in high-precision GPS and guidance systems, serving as a critical technology supplier. Kubota Corporation competes by offering automated solutions tailored for smaller and specialized farming operations.
Autopilot agricultural vehicles are farm machinery equipped with systems for autonomous or semi-autonomous operation. These systems rely on technologies like Real-Time Kinematic (RTK) GPS to achieve centimeter-level accuracy for tasks such as planting and spraying. Within the technology stack, GPS guidance remains foundational, while LiDAR sensors enable enhanced obstacle detection and field mapping. Application focus is shifting from basic soil preparation towards more complex tasks like selective harvesting and pest control.
Manufacturers must navigate a complex regulatory environment, including EPA emissions standards in the United States and CE marking for machinery safety in Europe. The forthcoming EU AI Act will introduce new compliance obligations for the algorithms governing autonomous operations. The primary strategic decision for equipment manufacturers and farm operators now revolves around data ownership and platform interoperability.
Market Dynamics
The acute shortage of skilled agricultural operators is the central structural force shaping the market. This labor gap, combined with the integration of data science into farm management, elevates precision automation to a core requirement for maintaining yield and operational continuity.
Growth Catalysts
- RTK GPS Accuracy:Real-Time Kinematic GPS enables centimeter-level precision, reducing input waste and boosting crop yields for commercial growers.
- Large-Scale Farming Economics:Commercial operations in the United States and Brazil seek higher yields and operational efficiency, driving demand for automated systems.
- EU Agricultural Policy:The EU's Common Agricultural Policy incentivizes technologies that reduce environmental impact, including precision spraying and planting systems.
Market Restraints
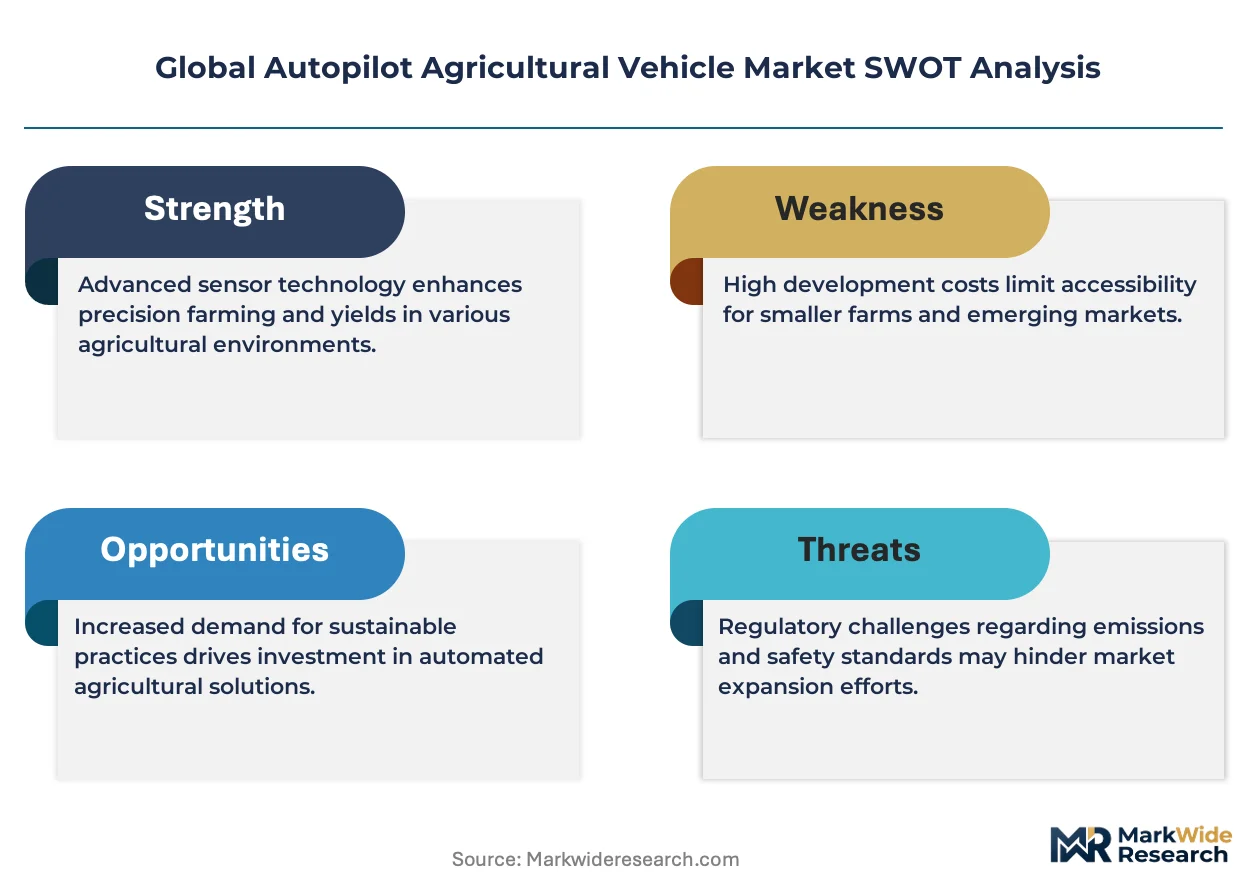
- High Capital Investment:The substantial upfront cost of autonomous vehicles and related technology presents a significant barrier for small and mid-sized farm operations.
- Platform Interoperability:A lack of data standards between equipment from different manufacturers creates integration challenges for farmers operating mixed fleets.
- Complex Regulatory Approvals:Navigating disparate regulations like Europe’s CE marking and state-level US laws for autonomous operation creates compliance delays.
Strategic Opportunities
- Selective Harvesting Automation:Developing systems for high-value, labor-intensive tasks like fruit and vegetable harvesting opens markets beyond broadacre crops.
- Small Farm Solutions:Offering affordable, compact autopilot systems for specialized farms in geographies like Japan creates a new customer segment.
- AI-Driven Pest Control:Integrating AI with LiDAR data enables real-time pest identification and targeted micro-spraying, a high-value application.
Industry Challenges
- Data Science Skill Gap:Farms and equipment dealers face a shortage of personnel with the data science and agronomy expertise needed to manage and interpret data from autonomous systems.
- Legacy System Integration:Integrating new autonomous machinery with existing, non-autonomous farm equipment and legacy farm management software presents significant technical and operational hurdles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Autopilot Agricultural Vehicle Market |
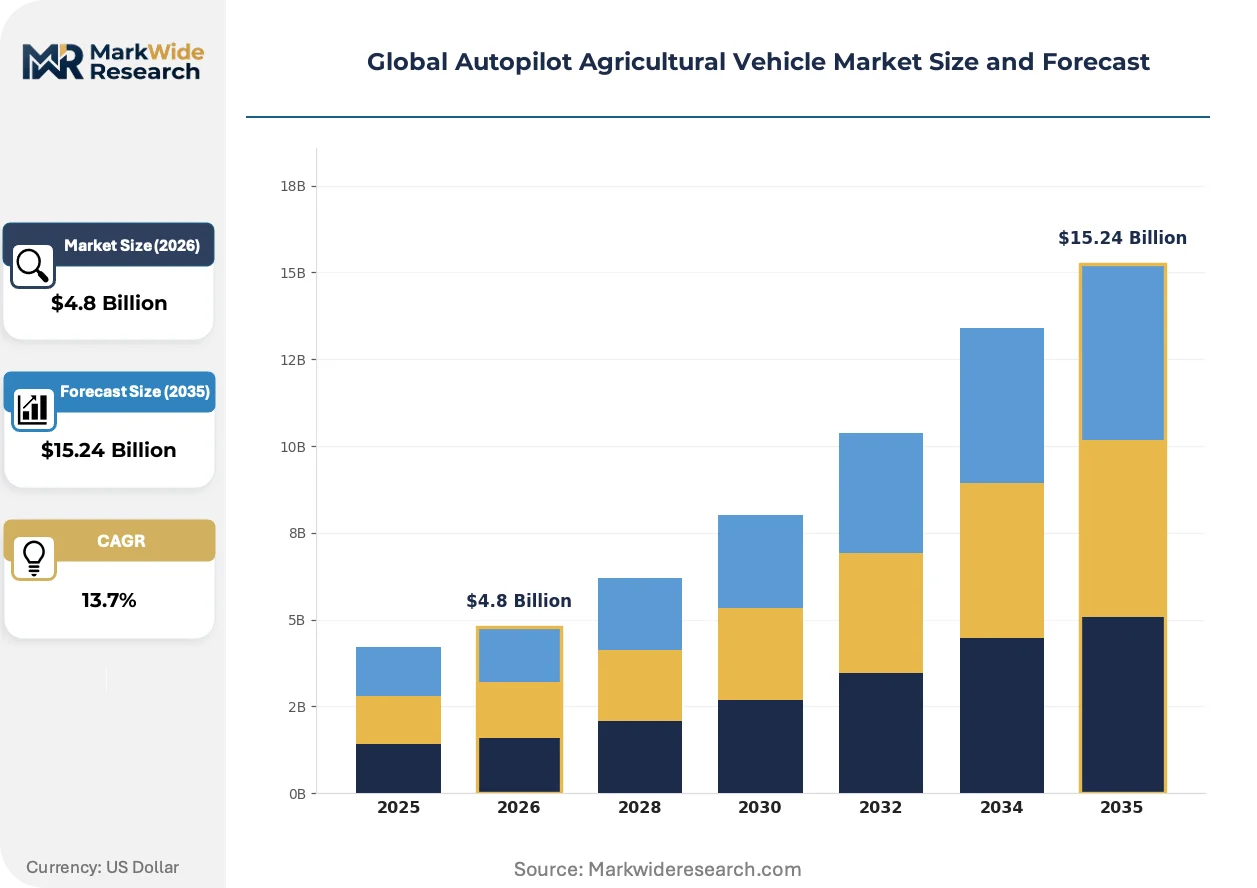
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.24 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tractors, Combine Harvesters, Planters, Sprayers, Tillers Technology: GPS Guidance, LiDAR Sensors, Machine Vision, Ultrasonic Sensors, IMU Systems Application: Soil Preparation, Seeding, Crop Monitoring, Harvesting, Pest Control End User: Family Farms, Commercial Growers, Agricultural Cooperatives, Contract Farmers, Research Institutions |
| Companies Covered | Trimble Inc., Kubota Corporation, Deere & Company, Monarch Tractor, Yanmar, CNH Industrial, Autonomous Solutions, Inc., Topcon Positioning Systems, AGCO Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Autopilot Agricultural Vehicle Market Strategic Shifts & Innovations
Operational focus is shifting from simple vehicle guidance to task-specific intelligence. This evolution transforms equipment into dynamic platforms for data acquisition and precision agronomic intervention, driven by software and advanced sensor fusion.
LiDAR sensors provide high-resolution, three-dimensional mapping of fields, enabling superior navigation compared to vision-only systems. Commercial growers with large, complex fields are the primary adopters, seeking to improve safety and operational uptime. Solid-state LiDAR development is miniaturizing the hardware, lowering costs and simplifying integration on smaller vehicles beyond just large tractors.
The forthcoming EU AI Act introduces a risk-based framework for artificial intelligence, classifying autonomous agricultural vehicles as potentially high-risk. This legislation will mandate rigorous conformity assessments, risk management, and data governance protocols for manufacturers. Manufacturers are embedding compliance-by-design into R&D, prioritizing algorithm transparency and data logging to ensure future access to the European market.
Farm operators are increasingly purchasing autonomous capabilities as a subscription service rather than a one-time, upfront hardware cost. This model, often called "autonomy-as-a-service," displaces the traditional equipment sales cycle and lowers the initial barrier to adoption. The trend is most visible in North America among large fleet operators managing capital expenditure.
Global Autopilot Agricultural Vehicle Market Segmentation
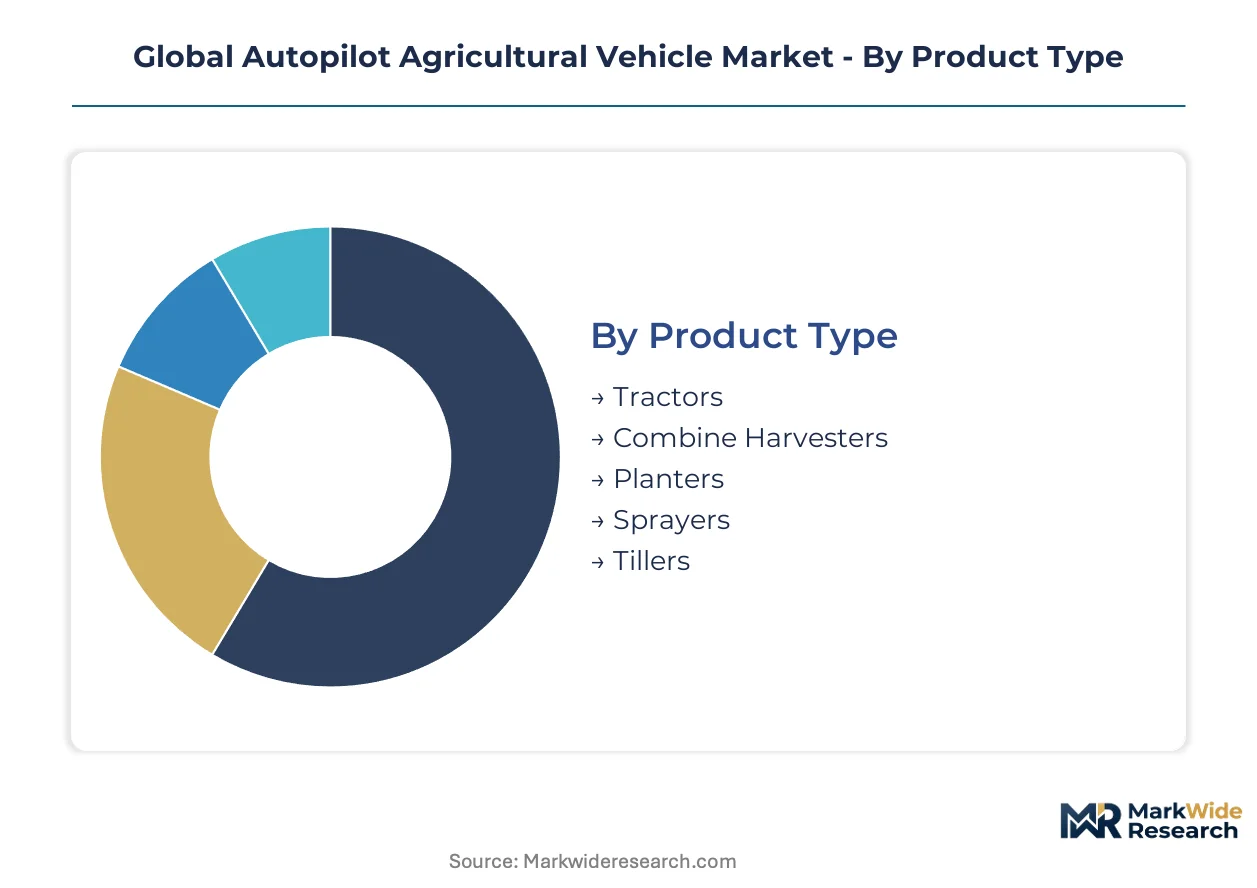
The segmentation of the global autopilot agricultural vehicle market reveals distinct patterns in product adoption, technological advancement, and end-user requirements. Understanding these segments helps manufacturers tailor solutions and navigate varying regulatory landscapes across different geographies.
Product Type:
The geographic distribution of autopilot agricultural vehicle product types varies, with some equipment types seeing higher adoption in specific regions due to farm size or crop specialization.
- Tractors:These foundational autonomous vehicles integrate RTK GPS for precise field operations like tilling and planting. Demand is high in large-scale agricultural operations across the United States, driven by the need for labor efficiency.
- Combine Harvesters:Equipped with advanced sensors for autonomous harvesting of grain crops, these machines optimize yield and reduce operational time. Commercial growers in Brazil heavily invest in these high-capacity units to manage vast fields.
- Planters:Precision planters utilize GPS guidance to accurately place seeds, minimizing waste and improving crop establishment.
- Sprayers:Autonomous sprayers apply inputs like fertilizers and pesticides with high accuracy, reducing environmental impact and chemical usage.
- Tillers:Robotic tillers prepare soil for planting, often used in smaller, specialized operations or for targeted cultivation.
Tractors hold the largest share; momentum sits with Sprayers due to precision agriculture demands.
Technology:
Technology segments for autopilot agricultural vehicles reflect varying levels of market maturity and integration complexity.
- GPS Guidance:This core technology provides positional data for autonomous navigation, enabling centimeter-level accuracy for farm machinery. It remains foundational across all autonomous agricultural applications, particularly in North American and European markets.
- LiDAR Sensors:These sensors generate high-resolution 3D maps of fields and detect obstacles, enhancing safety and navigation capabilities. Commercial growers are increasingly adopting LiDAR for complex field mapping and improved operational uptime.
- Machine Vision:Vision systems use cameras and image processing to identify crops, weeds, and harvestable produce, supporting tasks like selective spraying.
- Ultrasonic Sensors:These sensors detect nearby objects and measure distances, primarily used for short-range obstacle avoidance and row following.
- IMU Systems:Inertial Measurement Units provide data on vehicle orientation and motion, complementing GPS for robust navigation in challenging terrains.
GPS Guidance forms the bedrock of autonomous operations, while LiDAR Sensors are expanding most quickly.
Application:
The application segments reflect the increasing operational complexity and value-added tasks performed by autonomous agricultural systems.
- Harvesting:This application segment involves autonomous collection of crops, from broadacre grains to high-value specialty fruits and vegetables. Selective harvesting automation represents a significant strategic opportunity, particularly for labor-intensive crops.
- Pest Control:Autonomous systems integrate AI and sensor data for real-time pest identification and targeted micro-spraying. This high-value application reduces chemical usage and improves crop health, appealing to environmentally conscious markets like the EU.
- Soil Preparation:Autonomous vehicles perform tasks such as plowing, tilling, and harrowing with precise guidance, optimizing soil conditions.
- Seeding:Precision seeding applications ensure optimal seed placement and spacing, contributing to higher yields and reduced input costs.
- Crop Monitoring:Autonomous drones and ground vehicles collect data on crop health, growth, and stress factors, enabling data-driven agronomic decisions.
Soil Preparation represents a foundational application, but Harvesting and Pest Control are gaining significant traction.
End User:
End-user segments are differentiated by farm size and operational scale, influencing technology adoption patterns.
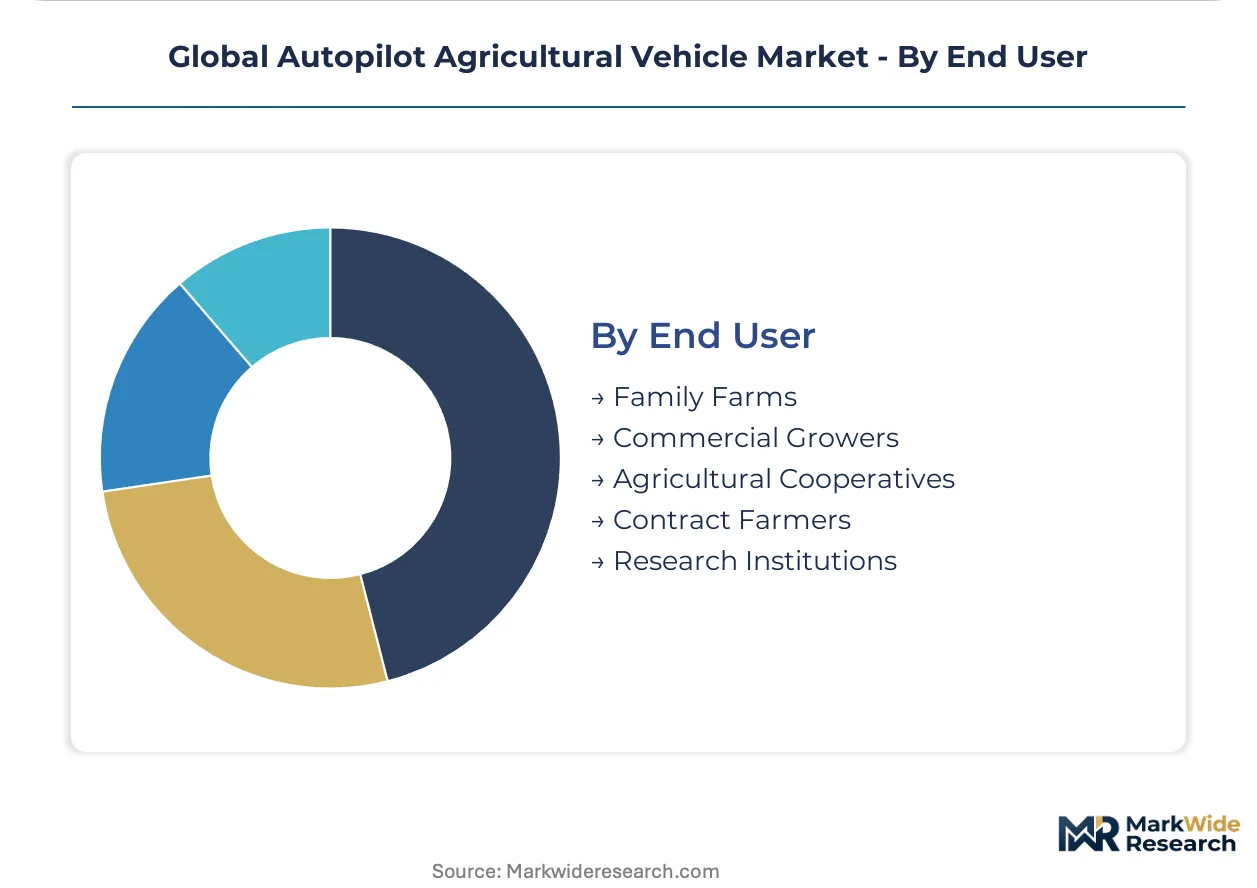
- Commercial Growers:These large-scale agricultural operations prioritize high crop yields and operational efficiency, driving demand for advanced autonomous solutions. Commercial growers in the United States and Brazil are primary adopters of autopilot agricultural vehicles.
- Agricultural Cooperatives:Member-owned organizations pool resources to invest in shared autonomous equipment, making advanced technology accessible to smaller farms. These cooperatives represent a significant collective purchasing power in regions like Europe.
- Family Farms:Smaller, often multi-generational farming operations, typically adopt compact and more affordable automated solutions.
- Contract Farmers:Businesses that provide farming services to multiple clients often leverage autonomous vehicles to maximize efficiency and service capacity.
- Research Institutions:Universities and agricultural research centers utilize autonomous vehicles for experimental farming, data collection, and technology development.
Commercial Growers represent the largest segment, with Agricultural Cooperatives demonstrating strong collective purchasing power.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power asymmetry in the global autopilot agricultural vehicle market favors regions with large-scale operations. Manufacturers often command higher prices in the United States due to advanced technology adoption. Conversely, emerging markets like China prioritize cost-effectiveness and localized solutions.
United States
Demand for autonomous tractors and combine harvesters stems from the need for labor efficiency in vast agricultural lands. The USDA's precision agriculture initiatives support technology integration and data-driven farming practices. The Midwest region, particularly states like Iowa, sees significant adoption among commercial grain growers.
Brazil
Commercial growers in Brazil heavily invest in high-capacity autonomous combine harvesters to manage extensive soybean and corn fields. ANVISA regulations ensure the safe operation and environmental impact assessment of agricultural machinery. The Mato Grosso region leads in autonomous harvesting technology deployment for its large-scale plantations.
Germany
European farmers seek precision spraying and planting systems to comply with the EU's Common Agricultural Policy's environmental goals. CE marking mandates rigorous safety and performance standards for autonomous agricultural vehicles. Bavaria's agricultural technology clusters drive innovation in specialized robotic tillers and crop monitoring systems.
Japan
The scarcity of agricultural labor and the prevalence of smaller, specialized farms drive demand for compact automated solutions. METI supports smart agriculture initiatives, promoting the development of affordable robotic tillers and planters. Hokkaido, with its larger farm sizes, serves as a testbed for compact autonomous machinery deployment.
China
China's push for agricultural modernization and food security fuels demand for automated planting and pest control systems. The Ministry of Agriculture and Rural Affairs promotes smart farming technologies and subsidies for advanced machinery. Shandong Province, a major agricultural hub, sees pilot programs for autonomous tractor fleets.
Global Autopilot Agricultural Vehicle Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the global autopilot agricultural vehicle market. The market exhibits a tiered structure, with established agricultural machinery giants competing with specialized technology providers and software developers. Strategic archetypes include full-line agricultural equipment manufacturers focusing on integrated platforms, precision technology specialists, and emerging robotics innovators targeting niche applications. Key competitive moves involve strategic partnerships for technology integration, portfolio diversification into software-as-a-service models, and geographic expansion into underserved markets.
Specialists in high-precision guidance, Trimble Inc., exemplify the technology-focused tier, providing foundational components for autonomous navigation and field mapping. This entity often serves as a critical supplier across the industry, enabling advanced precision agriculture. Meanwhile, full-line agricultural equipment manufacturers like Deere & Company represent the integrated solutions providers, offering comprehensive autonomous vehicle platforms designed for large-scale commercial operations. Kubota Corporation occupies a distinct position, catering to smaller and specialized farming operations with tailored automated solutions that prioritize affordability and ease of use.
| Leading Market Players |
|---|
| Trimble Inc. |
| Kubota Corporation |
| Deere & Company |
| Monarch Tractor |
| Yanmar |
| CNH Industrial |
| Autonomous Solutions, Inc. |
| Topcon Positioning Systems |
| AGCO Corporation |
| Others |
Cost & Logistics Intelligence
Manufacturing scale efficiencies in autonomous agricultural vehicle production directly influence supply concentration among a few large players, setting a high price floor for advanced systems. High capital expenditure for research and development and specialized components further reinforces this dynamic.
Pricing Analysis
Configured-to-order pricing for specialized autonomous agricultural solutions commands a premium over standard, pre-packaged systems. The market largely operates on a hybrid model, combining per-unit hardware sales with subscription-based autonomy-as-a-service. Price differentiation stems from precision accuracy levels, like centimeter-level RTK GPS, and comprehensive after-sales service packages. Pricing softness for basic guidance systems stems from increasing competition. Commercial growers exhibit lower price sensitivity compared to family farms.
Supply Chain Analysis
Inbound logistics costs for specialized electronic components, particularly from Asian manufacturing hubs, influence the overall supply chain for autonomous agricultural vehicles. Supply concentration for advanced sensor technology centers on China, Germany, and the United States. The industry relies on high-performance processors and LiDAR sensors. A structural risk involves single-source vulnerability for certain specialized sensor components. Distribution runs through established agricultural equipment dealer networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The global autopilot agricultural vehicle market represents a high-growth disruption, driven by the integration of AI-driven precision agriculture and the forthcoming EU AI Act's compliance mandates. This technological and regulatory inflection point reshapes operational paradigms for farm management.
For Market Incumbents: Fortify existing dealer networks by enhancing data science and agronomy training for technicians, countering the data science skill gap threat. Pursue strategic partnerships with specialized AI software developers to integrate advanced task-specific intelligence into core platforms. Invest in CE marking and EU AI Act compliance by design during research and development to maintain access to European markets. Leverage vertical integration into key sensor manufacturing to secure supply.
For New Entrants and Emerging Players: A service-layer gap exists in providing affordable, compact autopilot solutions for smaller, specialized farms, particularly in Japan. Target the selective harvesting automation segment for high-value crops, leveraging AI and LiDAR data for precision. Focus on developing modular, interoperable systems that integrate with existing legacy farm equipment, addressing platform interoperability challenges. Offer autonomy-as-a-service models to lower initial capital investment barriers for family farms.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among autonomy-as-a-service providers with strong platform interoperability and robust data analytics capabilities. Long-term viability over a 5-10 year window favors entities addressing the acute labor shortage and enhancing crop yields through precision. Acquisition targets should include specialized software developers focusing on AI-driven pest control or selective harvesting. The signal to watch is the widespread adoption rate of subscription models among mid-sized commercial growers.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop AI-driven micro-spraying systems | Reduces chemical usage and environmental impact, appealing to EU agricultural policy. |
| Expand autonomy-as-a-service offerings | Lowers initial capital investment for farm operators, accelerating technology adoption in North America. |
| Secure partnerships for RTK GPS and LiDAR integration | Ensures centimeter-level accuracy and enhanced obstacle detection for large-scale commercial operations. |
| Invest in compact, specialized robotic tillers | Addresses the labor scarcity and small farm needs in geographies like Japan. |
| Prioritize compliance-by-design for EU AI Act | Ensures future market access and builds trust for autonomous agricultural vehicle algorithms in Europe. |
Research Approach
A spread of perspectives from farm operators, equipment manufacturers, technology providers, and agricultural policy advisors converged on the working assumptions for this analysis. Primary interviews were combined with secondary validation from sources such as EPA emissions standards, CE marking documentation, and USDA reports. This approach ensured robust bottom-up and top-down triangulation of market data.
Segmentation dimensions modeled include product type, technology, application, end-user, and farm size, providing a granular view across the analysis window. The analytical framework integrated historical data and future projections to derive compound annual growth rates for each segment. Forecast inputs considered evolving crop yield data and regional agricultural labor availability trends.
Forecasts assume regulatory continuity in the US, Europe, and Brazil; material policy shifts would require re-modeling. The analysis reflects assumptions regarding technological advancements and farmer adoption rates, with unforeseen regulatory changes or significant shifts in agricultural subsidies representing key risk factors. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Machinery
Brazil Agricultural Machinery Market
Agricultural Machinery
Japan Agricultural Machinery Market
Agricultural Machinery
Driverless Tractor Market
Agricultural Machinery
Electric Farm Tractor Market
Agricultural Machinery
North America Plowing and Cultivating Machinery Market
Agricultural Machinery
North America Agricultural Tractors Market
Agricultural Machinery
Europe Agricultural Sprayer Market
Agricultural Machinery
United States Haying and Forage Machinery Market
Agricultural Machinery
US Agriculture Drone Market
Agricultural Machinery
Germany Agricultural Tractor Market
Agricultural Machinery
Autonomous Electric Tractor Market
Agricultural Machinery
Agriculture Drones Market
Agricultural Machinery
United States Agricultural Tractor Market
Agricultural Machinery
South America Agricultural Tractors Market
Agricultural Machinery
Europe Agricultural Irrigation Machinery Market
Agricultural Machinery
Utility Tractor Market