
 Fish Farming Market | 2026-2036
Fish Farming Market Size, Share, and Industry Trends Forecast 2026-2036
Fish Farming Market Intelligence
Atlantic salmon producers in Norway is restructuring output protocols after coastal zone licensing tightened. Mowi ASA leverages integrated hatchery-to-harvest operations across Scottish and Canadian sites. Grieg Seafood ASA anchors its biosecurity model on land-based smolt facilities. Charoen Pokphand Foods PCL dominates tilapia and shrimp value chains across Southeast Asian markets.
Fish farming denotes the controlled cultivation of finfish in enclosed water systems, where dissolved oxygen levels, stocking density, and feed conversion ratios determine yield efficiency and fillet quality for commercial protein supply. Salmon commands premium pricing in retail chains and foodservice channels due to longer grow-out cycles and higher omega-3 content. Recirculating aquaculture systems attract capital as land-based tank operations reduce parasite exposure and escape risks. Cage culture in coastal Norway and Chile retains scale advantages for volume supply to fish wholesalers.
Norway's Food Safety Authority enforces maximum allowable sea-lice counts per fish, while the EU's Aquaculture Regulation mandates environmental impact assessments for new licensed sites. Chile's Subsecretaría de Pesca applies area-based management rules that restrict biomass loads in salmon farming concessions. Stakeholders must monitor regulatory divergence between North Atlantic and Pacific South American jurisdictions when allocating capital across farming methods and species portfolios.
Market Dynamics
Closed-containment recirculating aquaculture systems are displacing open-net cage operations as Norway's Food Safety Authority tightens sea-lice thresholds and coastal zone licensing. This technology shift restructures capital allocation across hatchery-to-harvest value chains.
Growth Catalysts
- EU Aquaculture Regulation:Mandatory environmental impact assessments for new licensed sites accelerate investment in land-based smolt facilities and integrated biosecurity protocols.
- Omega-3 positioning:Retail chains and foodservice channels prioritize salmon fillets for longer grow-out cycles and documented fatty acid profiles, pulling premium cold-chain infrastructure buildout.
- Chile's area-based management:Biomass load restrictions in salmon farming concessions force operational efficiency gains that reduce feed conversion ratios industry-wide.
Market Restraints
- Feed input volatility:Fishmeal and fish oil price swings concentrate cost pressure on growers without backward integration into feed milling.
- Norwegian supply concentration:Coastal zone licensing scarcity limits site expansion for volume supply to Asian seafood processors.
- Technical limitation:Dissolved oxygen management in high-density RAS tanks constrains stocking density below open-water equivalents.
Strategic Opportunities
- China cold-chain segments:Premium salmon demand from seafood processors remains underpenetrated in tier-two cities lacking blast-freeze infrastructure.
- RAS-IoT convergence:Sensor networks and automated feeding systems reduce labor intensity in land-based tank operations.
- EU Green Deal alignment:Carbon accounting requirements for imported seafood create certification premiums for low-emission production methods.
Industry Challenges
- RAS engineering talent scarcity:Water chemists and mechanical systems specialists command wage premiums that inflate facility commissioning timelines.
- Sea-lice compliance certification:Norway's maximum allowable count enforcement requires weekly monitoring protocols that strain smaller operators without laboratory partnerships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fish Farming Market |
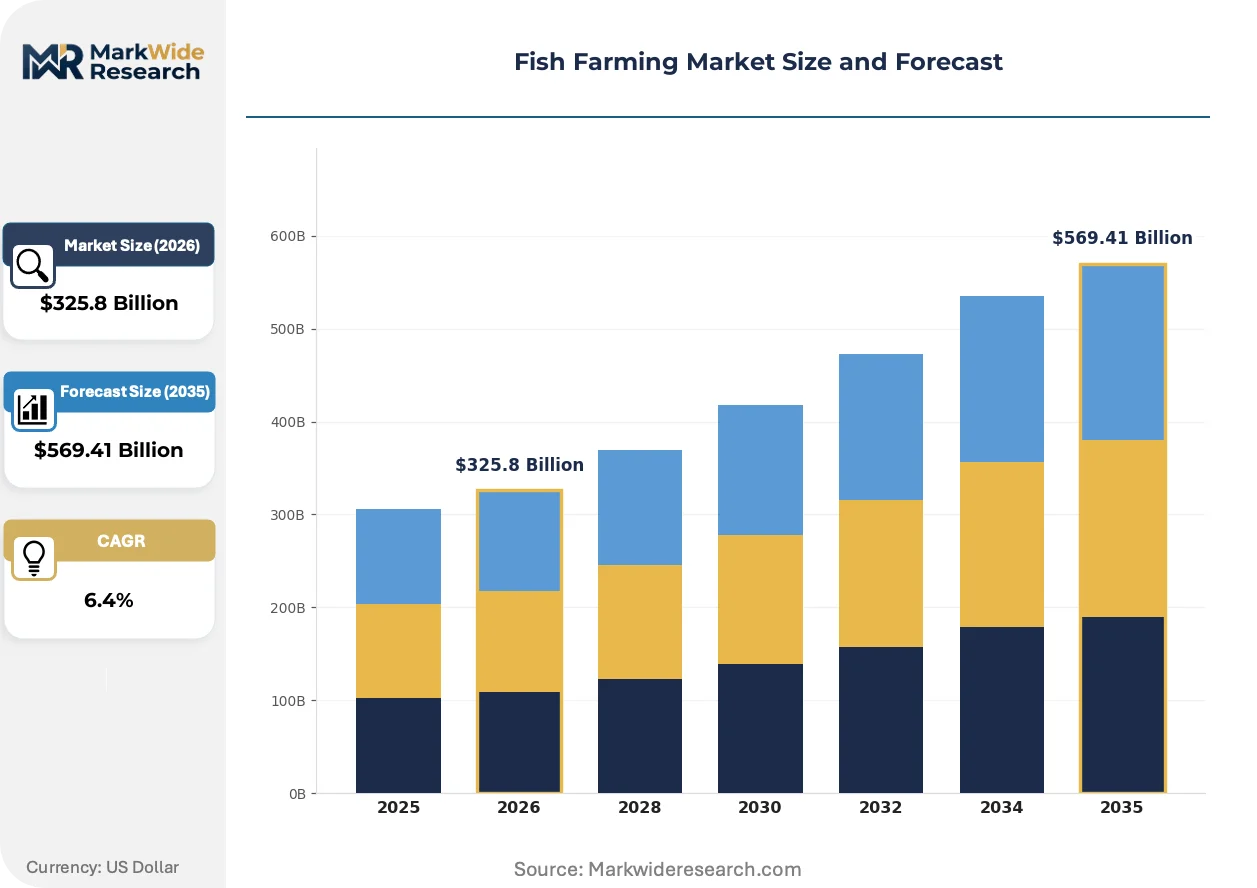
| Market Size in 2026 | $325.8 Billion |
| Market Size in 2035 | $569.41 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Species: Tilapia, Catfish, Salmon, Carp, Barramundi Farming Method: Aquaculture Ponds, Recirculating Systems, Cage Culture, Raceway Ponds, RAS Tanks Feed Type: Pellets, Flakes, Live Feed, Frozen Feed, Organic Feed End User: Seafood Processors, Fish Wholesalers, Retail Chains, Foodservice Providers |
| Companies Covered | Cermaq Group AS, Multiexport Foods S.A., Mowi ASA, Empresas AquaChile S.A., Grieg Seafood ASA, Lerøy Seafood Group ASA, Cooke Aquaculture Inc., Charoen Pokphand Foods PCL, SalMar ASA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fish Farming Market Strategic Shifts & Innovations
Digital monitoring platforms and automated feeding systems are compressing operational labor requirements while regulatory pressure on parasite management accelerates containment technology adoption across North Atlantic and Pacific South American production zones.
Recirculating aquaculture system design is modularizing around standardized tank configurations and plug-and-play filtration skids. Scottish and Canadian operators are adopting these units for smolt production to reduce coastal parasite exposure. This standardization is modularizing project finance and shortening construction timelines for multi-phase facility rollouts.
Norway's Food Safety Authority has tightened maximum allowable sea-lice counts per fish below prior thresholds. Coastal zone licensing now requires documented parasite management protocols before permit issuance. Scottish and Irish growers are accelerating closed-containment investments to preempt similar regulatory stringency.
Seafood processors in China are consolidating procurement relationships directly with Norwegian and Chilean farming groups, bypassing traditional fish wholesaler intermediaries. This disintermediation compresses margin capture for trading houses while demanding traceability documentation that smaller exporters cannot supply. Premium cold-chain segments in Shanghai and Guangzhou are the primary venues for this structural shift.
Fish Farming Market Segmentation
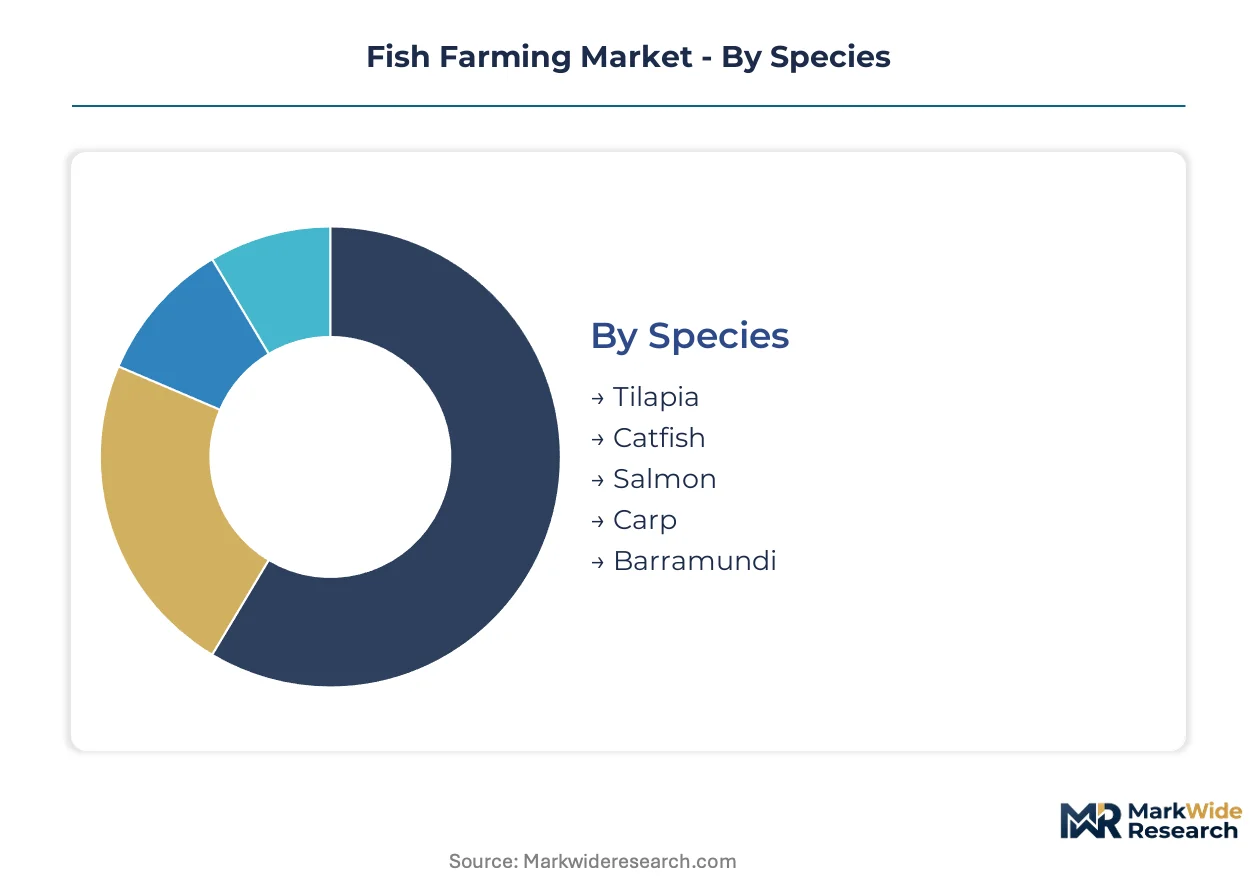
Species selection dictates capital intensity, feed conversion economics, and regulatory exposure across fish farming operations. Farming method and feed type configurations determine biosecurity risk profiles and geographic expansion feasibility for protein suppliers targeting retail and foodservice channels.
Species:
Supply concentrates in species with established hatchery infrastructure and documented omega-3 profiles that command cold-chain premiums in Asian and European markets.
- Salmon:Long grow-out cycles in temperate coastal zones yield fillets with elevated EPA and DHA content. Norwegian and Chilean farming groups dominate volume supply to seafood processors in China, where blast-freeze infrastructure gaps in tier-two cities constrain penetration.
- Tilapia:Warm-water cultivation in freshwater ponds achieves rapid biomass turnover with minimal feed protein requirements. Southeast Asian integrated producers anchor value chains serving North American retail chains demanding white-fish alternatives to cod.
- Catfish:Mississippi Delta pond operations supply US foodservice providers with consistent fillet sizing for breaded product lines.
- Carp:Central European and Chinese inland aquaculture satisfies regional consumption patterns with minimal processing infrastructure.
- Barramundi:Australian and Southeast Asian cage culture targets premium restaurant segments with firm-textured white flesh.
Today's leader: Salmon. Tomorrow's challenger: Tilapia.
Farming Method:
Cost tiers separate open-water operations with legacy licensing advantages from capital-intensive land-based systems pursuing parasite elimination and escape containment.
- Recirculating Systems:Closed-loop water treatment with mechanical and biological filtration enables inland production without coastal zone permits. Scottish smolt facilities and Norwegian post-smolt operations adopt this method to preempt sea-lice compliance costs, though dissolved oxygen management constrains stocking density below open-water equivalents.
- Cage Culture:Open-net pens in sheltered fjords and channels retain scale economies for volume harvest. Chilean concessions under area-based management rules face biomass load restrictions that force operational efficiency gains, while Norwegian coastal licensing scarcity limits site expansion.
- Aquaculture Ponds:Earthen excavation with passive water exchange dominates tilapia and catfish production in tropical and subtropical zones.
- Raceway Ponds:Concrete channels with unidirectional flow support trout and salmonid production where water rights permit continuous discharge.
- RAS Tanks:Modular standardized configurations shorten construction timelines for multi-phase facility rollouts in North American and European markets.
Today's leader: Cage Culture. Tomorrow's challenger: Recirculating Systems.
Feed Type:
Application requirements vary by species digestive physiology and farming system water quality constraints, with protein source sustainability emerging as a procurement discriminator.
- Pellets:Extruded formulations with controlled buoyancy and nutrient density dominate salmon and trout operations. Norwegian and Chilean farming groups without backward integration into feed milling face margin compression during fishmeal and fish oil price volatility.
- Live Feed:Rotifers and Artemia nauplii remain essential for larval stages of marine finfish where manufactured alternatives fail to trigger feeding responses.
- Flakes:Surface-feeding ornamental and small-scale food fish operations in Southeast Asian household ponds.
- Frozen Feed:Whole fish and chopped baitfish support broodstock conditioning in high-value breeding programs.
- Organic Feed:Plant-protein and insect-meal formulations targeting EU Green Deal alignment and certification premiums for low-emission production methods.
Today's leader: Pellets. Tomorrow's challenger: Organic Feed.
End User:
Customer type determines traceability documentation requirements, volume contracting structures, and margin capture potential across value chain intermediaries.
- Seafood Processors:Large-scale filleting, smoking, and value-added operations in China and Europe consolidate procurement directly with farming groups. This disintermediation compresses margin capture for traditional fish wholesaler intermediaries while demanding batch-level documentation that smaller exporters cannot supply.
- Retail Chains:Supermarket and hypermarket channels in Shanghai and Guangzhou prioritize salmon fillets with documented fatty acid profiles and ASC or BAP certification.
- Fish Wholesalers:Traditional auction and spot-market intermediaries face structural compression as direct contracting expands.
- Foodservice Providers:Restaurant groups and institutional caterers specify consistent portion-controlled sizing for menu standardization.
Today's leader: Seafood Processors. Tomorrow's challenger: Retail Chains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production migration tracks widening gaps in sea-lice compliance costs between jurisdictions. Norwegian coastal licensing scarcity pushes capital toward Scottish and Canadian sites where regulatory thresholds remain less stringent.
Norway
Seafood processors in Bergen and Trondheim drive demand for premium Atlantic salmon with documented fatty acid profiles. Norway's Food Safety Authority enforces maximum allowable sea-lice counts below prior thresholds. Mowi ASA and Grieg Seafood ASA operate integrated hatchery-to-harvest facilities along coastal fjords facing licensing scarcity.
Chile
Salmon demand from Chinese seafood processors concentrates export volume through Valparaíso and Puerto Montt. Chile's Subsecretaría de Pesca applies area-based management rules restricting biomass loads in farming concessions. Empresas AquaChile S.A. and Multiexport Foods S.A. anchor production clusters in Los Lagos region.
China
Retail chains in Shanghai and Guangzhou prioritize cold-chain salmon fillets for premium foodservice segments. The Ministry of Ecology and Environment enforces dual carbon goals affecting imported seafood certification requirements. Seafood processors in Qingdao and Dalian consolidate direct procurement relationships with Norwegian farming groups.
Scotland
Smolt production demand accelerates closed-containment investments to preempt Norwegian-style regulatory stringency. The UK Environment Agency mandates environmental impact assessments for new licensed sites. Cooke Aquaculture Inc. and Scottish Salmon Company operations cluster around Shetland and Orkney islands.
Canada
Atlantic salmon cultivation in British Columbia and Newfoundland targets North American retail chain contracts. Fisheries and Oceans Canada applies area-based management for Pacific aquaculture operations. Cermaq Group AS maintains integrated operations across Vancouver Island and Atlantic Canada sites.
Fish Farming Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue land-based recirculating systems and alternative species portfolios. The market structures around three tiers: integrated Norwegian-Chilean salmon groups with hatchery-to-harvest control, Southeast Asian tilapia-shrimp conglomerates with feed milling backward integration, and regional specialists in smolt production or cold-chain distribution. Consolidation pressure intensifies as direct procurement by Chinese seafood processors compresses margin capture for trading intermediaries. Competitive moves center on M&A for coastal licensing access and partnerships for RAS technology licensing.
Among Norwegian-anchored integrated producers, Mowi ASA, Grieg Seafood ASA, and SalMar ASA exemplify the capital-intensive salmon farming archetype with coastal zone licensing advantages. Charoen Pokphand Foods PCL represents the Southeast Asian diversified protein conglomerate model with captive feed supply chains. These entities occupy positions that reflect divergent strategic bets: North Atlantic salmon premiumization versus tropical whitefish volume scaling.
| Leading Market Players |
|---|
| Cermaq Group AS |
| Multiexport Foods S.A. |
| Mowi ASA |
| Empresas AquaChile S.A. |
| Grieg Seafood ASA |
| Lerøy Seafood Group ASA |
| Cooke Aquaculture Inc. |
| Charoen Pokphand Foods PCL |
| SalMar ASA |
| Others |
Cost & Logistics Intelligence
Sovereign-wealth-backed Norwegian producers anchor supply concentration along coastal fjords, translating licensing scarcity into asymmetric pricing power over Asian seafood processors while feed input volatility compresses margins for non-integrated growers.
Pricing Analysis
Direct-to-processor contracting eliminates traditional fish wholesaler markups, compressing channel margins by fifteen to twenty-five percentage points against spot-market benchmarks. Pricing stratifies across premium ASC-certified salmon, standard BAP-compliant fillets, and economy-grade unlabeled product, with differentiation driven by fatty acid documentation and cold-chain integrity. Cost compression in the economy tier is intensifying because Chinese seafood processors consolidate procurement relationships with farming groups. Retail chains in Shanghai demonstrate lowest price sensitivity, while foodservice providers in tier-two cities resist premium positioning.
Supply Chain Analysis
Fishmeal supply rests on Peruvian anchovy harvests and Southeast Asian reduction fisheries, with fish oil concentration in Norwegian and Chilean refinery operations. Key inputs include extruded feed pellets, smolt juveniles from Scottish hatcheries, and automated feeding systems from Nordic equipment specialists. Single-source vulnerability sits with coastal zone licensing scarcity that constrains Norwegian volume expansion. Distribution runs through blast-freeze terminals at Qingdao and Dalian, then onward to seafood processors bypassing traditional auction intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story, with retail chains in Chinese tier-two cities shifting procurement toward documented omega-3 profiles and ASC certification that commands sustained premium capture.
For Market Incumbents: Lock in coastal licensing access through M&A in Scottish and Canadian jurisdictions before regulatory stringency spreads. Prioritize backward integration into feed milling to neutralize fishmeal price volatility that erodes margin position. Accelerate closed-containment smolt facility rollout to preempt sea-lice compliance cost escalation. For New Entrants and Emerging Players: Launch via direct contracting relationships with Qingdao and Dalian seafood processors, bypassing fish wholesaler intermediaries that face structural compression. Target barramundi and premium whitefish segments in Australian and Southeast Asian restaurant channels where salmon incumbents hold weaker positioning. Pursue modular RAS technology licensing to shorten facility commissioning timelines. For Investors and Strategic Acquirers: Valuations sit cheapest among Scottish smolt specialists with coastal zone licensing and unexploited capacity expansion rights. Long-term viability centers on five-to-ten year regulatory divergence between North Atlantic and Pacific South American jurisdictions. Watch for Norwegian Food Safety Authority threshold tightening as inflection signal for accelerated land-based technology adoption.| Strategic Initiative | Industry Significance |
|---|---|
| Closed-Containment Facility Buildout | Reduces sea-lice compliance costs under Norway's Food Safety Authority tightening thresholds. |
| Direct Processor Contracting | Bypasses fish wholesaler intermediaries facing margin compression from Chinese consolidation. |
| Feed Milling Backward Integration | Neutralizes fishmeal and fish oil price volatility that strains non-integrated growers. |
| Cold-Chain Infrastructure Partnership | Addresses blast-freeze gaps in Chinese tier-two cities constraining premium salmon penetration. |
| ASC Certification Program | Captures retail chain premiums in Shanghai and Guangzhou requiring documented sustainability protocols. |
Research Approach
Multiple input streams — primary interviews with hatchery operations managers, seafood processor procurement directors, and feed milling technical leads; secondary validation through Norwegian Food Safety Authority licensing databases, Chile's Subsecretaría de Pesca concession records, and Chinese customs import filings — were reconciled through bottom-up volume modeling and top-down demand triangulation.
Historical production trajectories were cross-referenced against panel input from regional farming associations to anchor growth assumptions across the analysis window. Segmentation dimensions included species category, farming method technology tier, feed protein source, and end-user channel type. CAGRs were derived from iterative reconciliation of supply-side capacity additions and demand-side cold-chain infrastructure buildout. Industry-specific forecast inputs incorporated sea-lice treatment cost curves and RAS energy intensity benchmarks.
Several conditions sit outside the modeled scope, including abrupt regulatory reversals in coastal zone licensing, catastrophic fish disease outbreaks, and trade policy disruptions affecting Norwegian-Chilean export access. Forecasts reflect documented assumptions about technology adoption rates and protein substitution elasticity. A small set of named triggers — Norwegian sea-lice threshold revisions, Chinese dual carbon goal acceleration, and Peruvian anchovy quota fluctuations — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aquaculture Innovations
Qatar Fisheries and Aquaculture Market
Aquaculture Innovations
Aquaculture Water Quality and Biomass Monitoring Test Equipment Market
Aquaculture Innovations
Aquaculture Products Market
Aquaculture Innovations
Fish Breeding Tank Market
Aquaculture Innovations
Europe Aqua Feed Market
Aquaculture Innovations
Europe Organic Aquaculture Market
Aquaculture Innovations
Shrimp Feed Market
Aquaculture Innovations
Seaweed Cultivation Market
Aquaculture Innovations
Oman Aquaculture Market
Aquaculture Innovations
Global Ornamental Fish Feed Market
Aquaculture Innovations
Aquaculture Feed and Pharmaceuticals Market
Aquaculture Innovations
Smart Aquaculture Systems Market
Aquaculture Innovations
Saudi Arabia Aquaculture Market
Aquaculture Innovations
Ornamental Tropical Fish Feed Market
Aquaculture Innovations
Egypt Aquafeed Market
Aquaculture Innovations
United Arab Emirates Fisheries and Aquaculture Market