
 France Agricultural Machinery Market | 2026-2036
France Agricultural Machinery Market Size, Share, and Industry Trends Forecast 2026-2036
France Agricultural Machinery Market Foresight
Modular equipment bundling is pivoting how French farm cooperatives configure capital expenditures, shifting from standalone tractor purchases to integrated precision-farming packages. CLAAS Group leverages its dominance in combine harvester technology to anchor premium positioning in the cereal belt. Deere & Company sustains R&D intensity around autonomous guidance systems for vineyard terrain. Kuhn Group specializes in tillage and seeding equipment, occupying a defensible niche in soil preparation workflows.
Agricultural machinery encompasses self-propelled and trailed equipment engineered to mechanize crop production, soil management, and post-harvest processing, with power ratings spanning 50 to 600+ horsepower and operating weights calibrated to French field dimensions under 10 hectares average. Tractors constitute the foundational revenue pool, while GPS Guidance and Telemetry Systems represent the fastest-expanding technology layer as vineyard operators digitize spray and harvest logistics. Combine Harvesters retain mature replacement cycles tied to grain price volatility, whereas Precision Farming and Variable Rate Technology concentrate margin pools in software-enabled service contracts.
France's machinery sector operates under the EU Green Deal emissions framework, CE marking mandates, and the F-Gas Regulation governing refrigerants in climate-controlled cabs, with the national regulator enforcing conformity through market surveillance inspections. The EU AI Act introduces emerging compliance obligations for autonomous operation algorithms, reshaping product development roadmaps for OEMs. Stakeholders must monitor subsidy alignment between the Common Agricultural Policy and electrification timelines to calibrate fleet transition strategies.
Market Dynamics
The EU Green Deal emissions framework is forcing French OEMs to accelerate electrified powertrain development while vineyard operators in Bordeaux and Champagne mechanize canopy management fleets at unprecedented speed.
Growth Catalysts
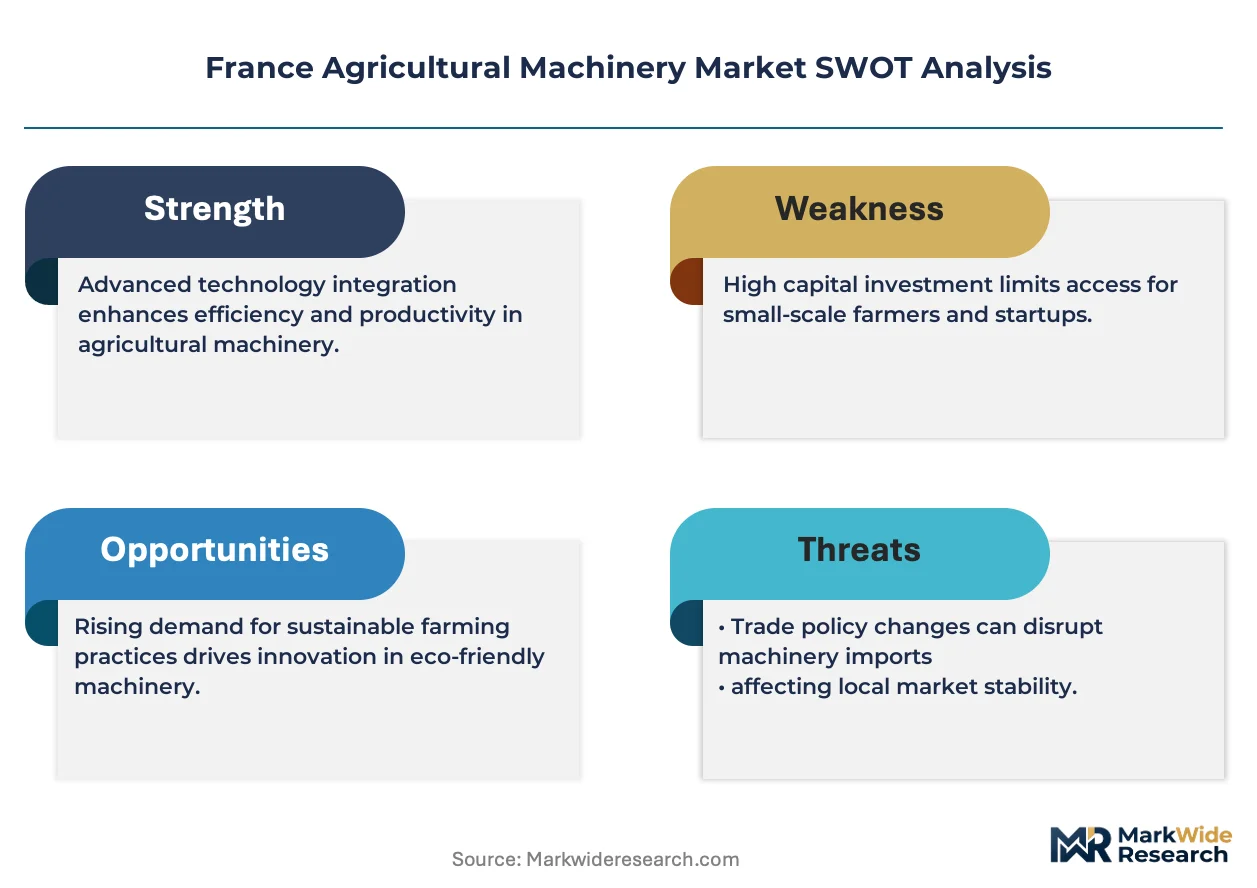
- EU Green Deal compliance deadlines:France's national agricultural regulator enforces strict emissions standards, creating replacement demand for Tier V-compliant tractors and electrified equipment across cereal cultivation zones.
- Precision viticulture digitization:Vineyard operators deploy GPS-guided sprayers and autonomous harvest logistics to address labor scarcity in Champagne and Burgundy terrains.
- Common Agricultural Policy subsidy realignment:CAP disbursements increasingly favor climate-smart machinery acquisitions, directing cooperative capital toward telemetry-enabled fleet packages.
Market Restraints
- Battery energy density limitations:Current lithium-ion configurations cannot sustain full-day field operations for high-horsepower tractors above 300 horsepower, constraining electrification timelines.
- Steel and rare earth input volatility:Permanent magnet motor supply concentrates in Asian processing facilities, exposing French OEMs to price swings in neodymium and dysprosium markets.
- CE marking conformity costs:Revised machinery safety directives impose extended testing protocols, stretching R&D budgets for specialized vineyard equipment manufacturers.
Strategic Opportunities
- Autonomous vineyard navigation:Convergence of LiDAR terrain mapping and machine vision enables single-operator management of mechanized pruning and leaf-removal workflows in steep Champagne slopes.
- Software-enabled service contracts:Variable Rate Technology providers pivot from hardware sales to subscription-based yield optimization platforms, capturing recurring revenue from Paris Basin arable farms.
- Used equipment refurbishment networks:Secondary market platforms for precision-farming components address cost barriers facing smaller Loire Valley operations.
Industry Challenges
- Mechatronics technician scarcity:French agricultural equipment dealers struggle to recruit specialists capable of diagnosing integrated hydraulic-electronic fault codes in telemetry-connected harvesters.
- EU AI Act algorithm certification:Autonomous guidance systems require conformity assessments for safety-critical decision logic, extending product launch timelines by 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Agricultural Machinery Market |
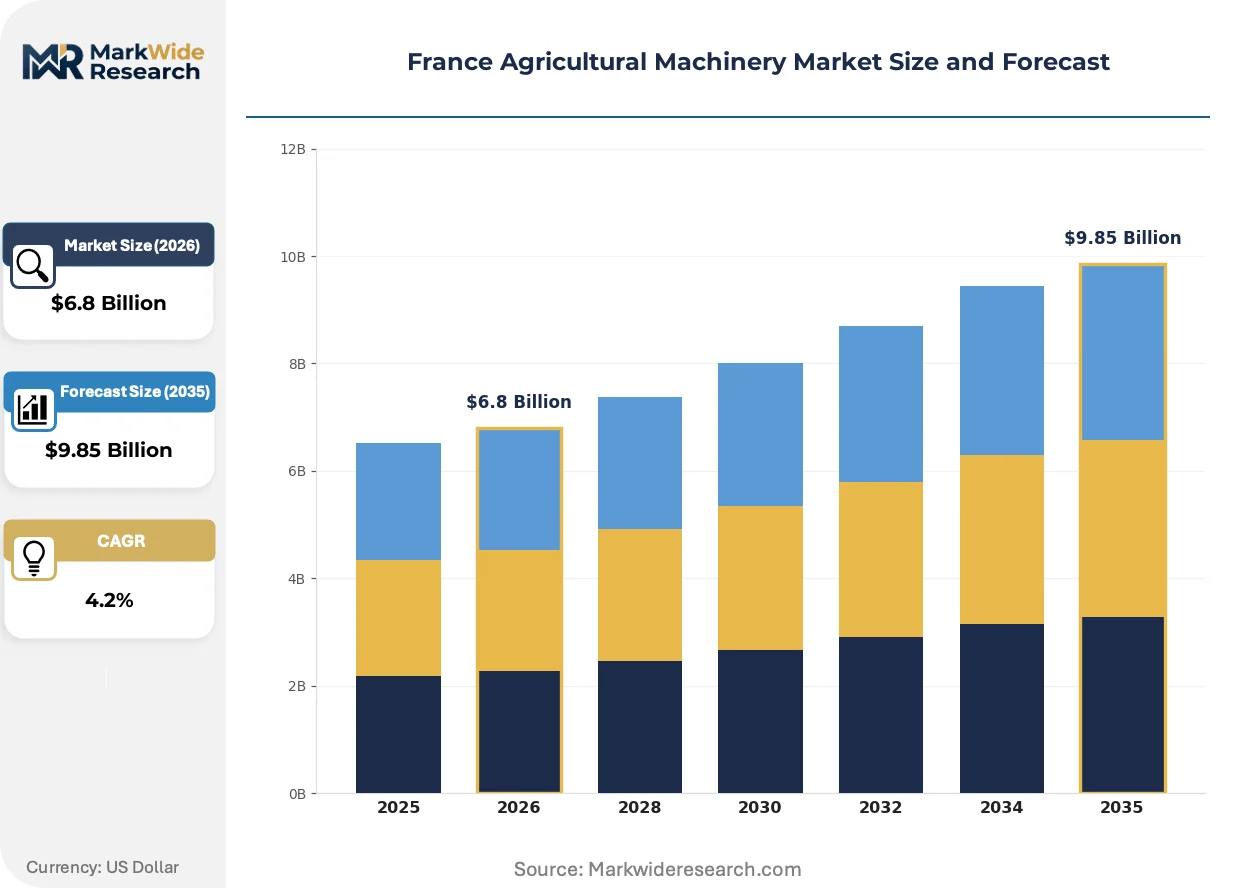
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $9.85 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tractors, Combine Harvesters, Seed Drills, Sprayers, Balers, Plows Technology: GPS Guidance, Telemetry Systems, Autonomous Operation, Precision Farming, Variable Rate Technology, Drone Integration Application: Cereal Cultivation, Viticulture, Livestock Feed Preparation, Horticulture, Soil Preparation End User: Crop Growers, Vineyard Operators, Livestock Farmers, Organic Farms, Landscape Contractors |
| Companies Covered | CLAAS Group, Same Deutz-Fahr Group, Deere & Company, Mahindra & Mahindra Ltd., Kuhn Group, AGCO Corporation, Kubota Corporation, Yanmar Co., Ltd., CNH Industrial N.V., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Agricultural Machinery Market Shifts & Advancements
Electrification and autonomy are converging to restructure how French farm cooperatives configure capital deployment, shifting procurement logic from horsepower maximization to task-specific energy efficiency metrics.
Telematics-enabled predictive maintenance is integrating real-time hydraulic pressure monitoring with cloud-based degradation models. Large-scale cereal operations in the Paris Basin adopt these systems fastest, with cooperative fleets achieving 15-20% downtime reduction. The technology is integrating dealer service departments into continuous equipment health management rather than episodic repair relationships.
The EU AI Act introduces mandatory conformity assessments for autonomous operation algorithms used in vineyard terrain navigation. French OEMs must document safety-critical decision logic and bias testing protocols before commercial deployment. Vineyard equipment manufacturers face the steepest compliance burden, as slope navigation algorithms require extensive validation across Champagne's variable topography.
Farm cooperatives now unbundle after-sales service from original equipment purchases, selecting third-party maintenance providers based on telemetry platform compatibility. This procurement fragmentation pressures traditional dealer networks to open proprietary diagnostic interfaces. The Loire Valley and Alsace regions exhibit the most pronounced shift toward independent service contracts.
France Agricultural Machinery Market Segmentation
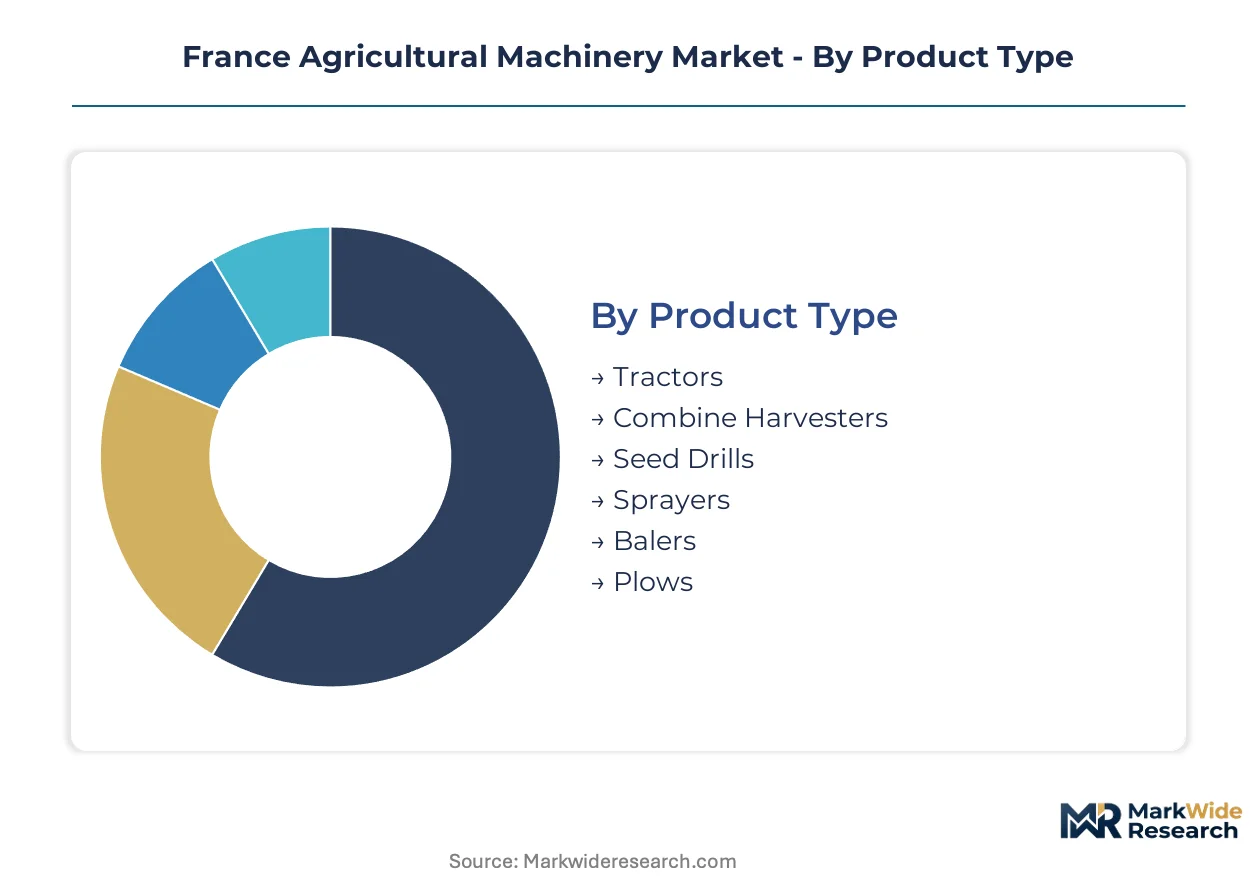
Segmentation reveals how French agricultural machinery procurement diverges across crop systems and operational scales. Equipment specifications, technology adoption rates, and replacement cycles vary sharply between Paris Basin cereal operations and Champagne vineyard terrains.
Product Type:
Replacement cycles across equipment categories track farm size and crop revenue stability, with capital deployment timing tied to subsidy windows and grain price cycles.
- Tractors:Foundational power units spanning 50-600+ horsepower configurations calibrated to French field dimensions averaging under 10 hectares. Demand concentrates in the Paris Basin cereal belt, where large-scale arable farms drive replacement cycles for high-horsepower models under EU Green Deal compliance pressure.
- Combine Harvesters:Self-propelled grain harvesting systems with operating widths matched to regional field geometries. Vineyard operators in Bordeaux and Champagne rarely deploy these units; volume concentrates in northern cereal zones where cooperative fleets prioritize throughput maximization.
- Seed Drills:Trailed and mounted precision seeding equipment for arable crop establishment.
- Sprayers:Boom and vineyard-specific configurations for crop protection application.
- Balers:Round and square hay/straw compaction systems for livestock feed operations.
- Plows:Conventional and conservation tillage implements for soil inversion and residue management.
Volume placements concentrate in Tractors; the faster expansion belongs to precision-enabled Combine Harvesters as telemetry integration accelerates.
Technology:
Technology adoption patterns split between mature precision systems with proven ROI and emerging autonomous platforms facing regulatory validation timelines.
- GPS Guidance:Satellite-based auto-steering systems reducing overlap and input waste during field operations. Deployment concentrates in cereal cultivation zones where large field geometries maximize signal stability and correction service subscriptions.
- Telemetry Systems:Real-time equipment health monitoring with cloud-based degradation modeling. Vineyard operators across Champagne and Burgundy digitize spray and harvest logistics fastest, achieving 15-20% downtime reduction through predictive maintenance protocols.
- Autonomous Operation:Self-navigating equipment with machine vision and LiDAR terrain mapping.
- Precision Farming:Integrated data-driven crop management platforms.
- Variable Rate Technology:Input application modulation based on yield mapping and soil sensing.
- Drone Integration:Aerial imaging and targeted application systems for crop monitoring.
Revenue concentration sits with GPS Guidance installations; the steepest expansion trajectory belongs to Telemetry Systems as service contract models displace hardware-only sales.
Application:
Application-specific equipment demand reflects France's agricultural geography, with mechanization intensity varying by terrain slope and crop labor requirements.
- Cereal Cultivation:Large-scale grain production systems dominating northern France. The Paris Basin drives replacement demand for high-horsepower tractors and combine harvesters, with cooperative capital favoring integrated precision-farming packages over standalone equipment purchases.
- Viticulture:Specialized vineyard operations across Champagne, Burgundy, and Bordeaux. Mechanized canopy management fleets are expanding at unprecedented speed as labor scarcity forces automation of pruning, leaf removal, and harvest logistics on steep slopes.
- Livestock Feed Preparation:Hay, silage, and mixed ration equipment for cattle and dairy operations.
- Horticulture:Protected cultivation and open-field vegetable production systems.
- Soil Preparation:Primary and secondary tillage operations for seedbed establishment.
Equipment volume concentrates in Cereal Cultivation; Viticulture commands the fastest technology upgrade cycles as digitization addresses structural labor shortages.
End User:
End-user procurement behavior diverges by scale, with cooperatives bundling precision packages and smaller operations prioritizing refurbished secondary market access.
- Crop Growers:Arable farm enterprises managing cereal and oilseed rotations. Paris Basin operations deploy capital fastest, aligning fleet renewal with CAP subsidy disbursement windows and Tier V emissions compliance deadlines.
- Vineyard Operators:Wine grape producers across France's designated appellations. Champagne terrain managers invest most aggressively in autonomous navigation and telemetry systems to enable single-operator management of mechanized workflows on variable slopes.
- Livestock Farmers:Cattle, dairy, and sheep operations requiring forage and feed handling equipment.
- Organic Farms:Certified operations with restricted input and tillage specifications.
- Landscape Contractors:Municipal and private terrain maintenance service providers.
Procurement volume concentrates among Crop Growers; Vineyard Operators are gaining share fastest as precision viticulture digitization accelerates capital deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
French agricultural machinery production clusters in the northeast industrial belt while consumption concentrates across the cereal plains and vineyard corridors. Domestic OEMs export precision tillage equipment throughout the EU single market. Import dependency runs highest for electrified powertrain components and rare earth magnet supply.
Île-de-France
The Paris Basin cereal belt drives replacement demand for high-horsepower tractors and combine harvesters. ANSM enforces CE marking conformity for telemetry-connected equipment through market surveillance inspections. Cooperative fleet operators in Beauce and Brie prioritize integrated precision-farming packages over standalone machinery purchases.
Grand Est
Champagne vineyard terrain managers invest aggressively in autonomous canopy management systems to address acute labor scarcity. The EU AI Act mandates conformity assessments for slope navigation algorithms before commercial deployment. Reims-based equipment dealers struggle to recruit mechatronics technicians capable of diagnosing integrated hydraulic-electronic fault codes.
Nouvelle-Aquitaine
Bordeaux wine producers expand mechanized pruning and leaf-removal fleets across variable hillside appellations. The F-Gas Regulation governs refrigerant specifications in climate-controlled cabs for extended harvest shifts. Cooperative purchasing syndicates in Gironde unbundle after-sales service from original equipment acquisitions.
Bourgogne-Franche-Comté
Burgundy vineyard operators digitize spray logistics through GPS-guided application systems. CAP subsidy realignment directs capital toward climate-smart machinery acquisitions with telemetry integration. Dijon-based precision agriculture startups pivot from hardware sales to subscription-based yield optimization platforms.
Hauts-de-France
Arable farms in the northern grain corridor align fleet renewal with Tier V emissions compliance deadlines under the EU Green Deal framework. Battery energy density limitations constrain electrification timelines for tractors above 300 horsepower. Lille industrial zones host refurbishment networks for secondary market precision-farming components.
France Agricultural Machinery Market Competitive Landscape
The competitive structure tilts toward diversified machinery conglomerates with full-line portfolios. European heritage brands anchor premium positioning in vineyard-specific equipment while Asian manufacturers compete on cost efficiency in utility tractor segments. Two strategic archetypes dominate: precision technology integrators and specialized tillage equipment fabricators. Consolidation pressure intensifies through strategic partnerships for electrified powertrain development and geographic expansion into Eastern European markets.
Within the diversified conglomerate tier, CLAAS Group and Deere & Company exemplify full-line positioning with integrated precision technology stacks. Kuhn Group occupies a defensible specialist position in soil preparation workflows. Among Asian-scale manufacturers, Kubota Corporation and Yanmar Co., Ltd. represent the cost-optimized utility tractor archetype. Mahindra & Mahindra Ltd. anchors emerging market penetration strategies. Same Deutz-Fahr Group and AGCO Corporation sit within the mid-tier European fabricator cluster. CNH Industrial N.V. exemplifies transnational scale with multi-brand portfolio architecture.
| Leading Market Players |
|---|
| CLAAS Group |
| Same Deutz-Fahr Group |
| Deere & Company |
| Mahindra & Mahindra Ltd. |
| Kuhn Group |
| AGCO Corporation |
| Kubota Corporation |
| Yanmar Co., Ltd. |
| CNH Industrial N.V. |
| Others |
Supply & Pricing Matrix
Mechatronics technician scarcity in Grand Est and Burgundy-Franche-Comté compresses service-labor availability, widening spreads between premium OEM-anchored contracts and third-party maintenance tiers across French vineyard equipment markets.
Pricing Analysis
Cost-down pressure on telemetry-enabled tractor packages accelerates because cooperative buyers unbundle after-sales service from hardware acquisitions. Three-tier pricing structure across premium, standard, and economy levels separates CLAAS-Deere integrated stacks from Kuhn-specialized tillage bundles and Asian utility imports. Brand premium and CE marking certification tier differentiate Paris Basin cereal operators from cost-sensitive Loire Valley cooperatives. Vineyard operators in Champagne exhibit lowest price sensitivity due to labor-scarcity urgency.
Supply Chain Analysis
EU Green Deal domestic-content mandates for electrified powertrain assembly reshape sourcing toward French and German battery pack integration facilities. Permanent magnet motors draw from Chinese and Vietnamese rare earth processing, while lithium-ion cell supply concentrates in South Korea and Japan. Single-source vulnerability in neodymium-dysprosium feedstock exposes Tier V compliance timelines. Distribution runs through Reims-based dealer networks and cooperative purchasing syndicates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The France Agricultural Machinery Market consolidates around electrified powertrain competence as EU emissions deadlines and AI Act certification burdens force smaller vineyard equipment fabricators toward strategic exit.
For Market Incumbents: Hedge battery energy density limitations by securing dual-source cell supply agreements with Korean and Japanese manufacturers while accelerating in-house production of permanent magnet motor alternatives. Channel control through proprietary telemetry platform lock-in defends against third-party service unbundling. CE marking conformity investment delays emerging competitors by 12-18 months.
For New Entrants and Emerging Players: Independent service contractors in Alsace and Loire Valley represent the fastest channel to cooperative fleet access. Secondary market refurbishment platforms for precision-farming components address cost barriers facing smaller operations. Subscription-based yield optimization software penetrates faster than hardware sales in Burgundy.
For Investors and Strategic Acquirers: The window for entry favors specialized tillage fabricators with defensible soil preparation IP and telemetry integration roadmaps. Long-term viability rests on software-enabled recurring revenue capture rather than equipment transaction margins. Watch CAP subsidy realignment timing as inflection signal for fleet replacement velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Electrified Powertrain Development | EU Green Deal Tier V compliance deadlines force accelerated R&D spend across French OEMs. |
| Autonomous Navigation Certification | EU AI Act conformity assessments extend product launch timelines for vineyard slope algorithms. |
| Telemetry Platform Integration | Predictive maintenance contracts displace hardware-only sales in Paris Basin cooperative fleets. |
| Refurbishment Network Expansion | Secondary market platforms address cost barriers facing Loire Valley precision-farming adopters. |
| Channel Partner Restructuring | Independent service contractors gain share as cooperatives unbundle after-sales from equipment purchases. |
Research Methodology
Document review covered EU regulatory filings, CAP subsidy disbursement records, and OEM technical specifications, complemented by interviews with vineyard operations managers, cereal cooperative procurement directors, agricultural equipment dealer principals, and precision agriculture software developers. Secondary validation drew from ANSM market surveillance reports, F-Gas Regulation compliance databases, and French customs machinery import records. Bottom-up equipment shipment analysis triangulated against top-down farm income and subsidy flow estimates.
Segment-level projections across tractors, combine harvesters, and precision-enabled technology stacks incorporated powertrain electrification timelines, autonomous certification delays, and cooperative capital deployment cycles. CAGRs derived from replacement cycle modeling tied to EU emissions phase-in schedules and grain price volatility assumptions. Telemetry adoption curves and software subscription conversion rates informed technology layer expansion estimates.
Several conditions sit outside the modeled scope, including unannounced EU battery standard revisions, abrupt rare earth export restrictions, and CAP subsidy suspension scenarios. Forecasts reflect documented regulatory timelines and commodity price baselines. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Machinery
United States Agricultural Machinery Market
Agricultural Machinery
Milking Robots Market
Agricultural Machinery
Africa Agricultural Tractor Market
Agricultural Machinery
United States Agricultural Tractor Market
Agricultural Machinery
Argentina Agricultural Machinery Market
Agricultural Machinery
Europe Agricultural Sprayer Market
Agricultural Machinery
Agricultural Tractor Robots Market
Agricultural Machinery
North America Agricultural Sprayers Market
Agricultural Machinery
Asia-Pacific Agricultural Tractors Market
Agricultural Machinery
Farm Tractor Market
Agricultural Machinery
Brazil Tractors Market
Agricultural Machinery
Hydrogen Powered Tractor Market
Agricultural Machinery
China Agricultural Tractors Market
Agricultural Machinery
Orchard Type Tractors Market
Agricultural Machinery
India Agricultural Tractor Market
Agricultural Machinery
North America Agricultural Tractors Machinery Market