
 Garden Tractor Market | 2026-2036
Garden Tractor Market Size, Share, and Industry Trends Forecast 2026-2036
Garden Tractor Market Intelligence
The push for lower emissions, codified by regulations like the EU's F-Gas Regulation and EPA standards in the United States, is recalibrating design priorities for engine and powertrain systems. This shift favors manufacturers investing in electric and hybrid technologies. John Deere leverages its extensive dealer network to introduce these new models to both residential and commercial buyers. Kubota Corporation specializes in reliable compact models, while CNH Industrial competes with its New Holland brand's focus on small farm and utility applications.
A garden tractor is a self-propelled machine, typically engineered with a 15 to 30 horsepower engine and a robust frame for ground-engaging attachments. Its primary function is to perform tasks beyond simple mowing, including tilling, cultivating, and hauling on properties larger than one acre. While gasoline-powered models continue to dominate sales, the electric power source segment represents the fastest-growing category. Demand from landscaping professionals and smallhold farmers is concentrating in the heavy-duty and utility product types, which offer greater versatility.
Engine design and market access are shaped by stringent emissions regulations, including the EPA's standards for small off-road engines and the EU's Stage V norms. Conformance with ISO safety standards, such as those for rollover protection structures, is also mandatory for commercial sales in many regions. Manufacturers now face a critical decision: optimizing mature gasoline engine platforms for efficiency or accelerating investment into battery-electric powertrains to meet future regulatory and consumer demands.
Market Dynamics
The garden tractor market is defined by the technological and regulatory pressure to shift from internal combustion engines to electric powertrains. This transition creates a fundamental tension between optimizing mature, cost-effective gasoline platforms and investing heavily in battery-electric systems to meet future emissions and noise standards.
Growth Catalysts
- Stricter Emissions Standards:Regulations like the EU's Stage V norms and EPA standards in the United States mandate lower exhaust emissions, compelling manufacturers to develop and market cleaner electric and advanced gasoline models.
- Commercial Landscaping Demand:Professional landscapers require quieter, low-emission equipment to comply with municipal noise ordinances and win contracts for work in noise-sensitive areas like hospitals and residential communities.
- Battery Technology Advancement:Improvements in lithium-ion battery energy density and cost reduction are making electric garden tractors more viable, offering longer runtimes and performance closer to their gasoline counterparts.
Market Restraints
- High Upfront Cost:The initial purchase price of battery-electric garden tractors remains significantly higher than comparable gasoline models, acting as a major barrier for budget-conscious residential consumers.
- Performance Gaps in Heavy-Duty Use:For ground-engaging applications like tilling or heavy hauling, current battery technology can struggle to provide the sustained torque and extended runtime of gasoline or diesel engines.
- Charging Infrastructure Limitations:The need for accessible and sufficiently fast charging solutions presents a logistical hurdle for users with very large properties or for commercial crews operating across multiple job sites.
Strategic Opportunities
- Autonomous and Robotic Systems:Integrating GPS and sensor-based autonomous navigation creates an opportunity for premium robotic mowers targeted at large commercial properties, golf courses, and high-net-worth estates.
- Fleet Electrification for Municipalities:Developing specialized electric models for municipal parks departments and public works agencies offers a new sales channel driven by public-sector sustainability mandates.
- Emerging Markets:Smallhold farms and large residential properties in developing economies in Latin America and Southeast Asia represent an underpenetrated market for utility-focused garden tractors.
Industry Challenges
- Battery Supply Chain Constraints:Competition with the electric vehicle industry for a limited supply of high-grade battery cells and semiconductor components creates production bottlenecks and input cost volatility for tractor manufacturers.
- Service Network Skill Gaps:The existing dealer and independent repair shop network requires significant training and investment in new diagnostic tools to service complex battery-electric and hybrid powertrain systems effectively.
- Lack of Charging Standardization:The absence of universal standards for battery connectors and charging protocols among different brands complicates fleet management for commercial users who own equipment from multiple manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Garden Tractor Market |
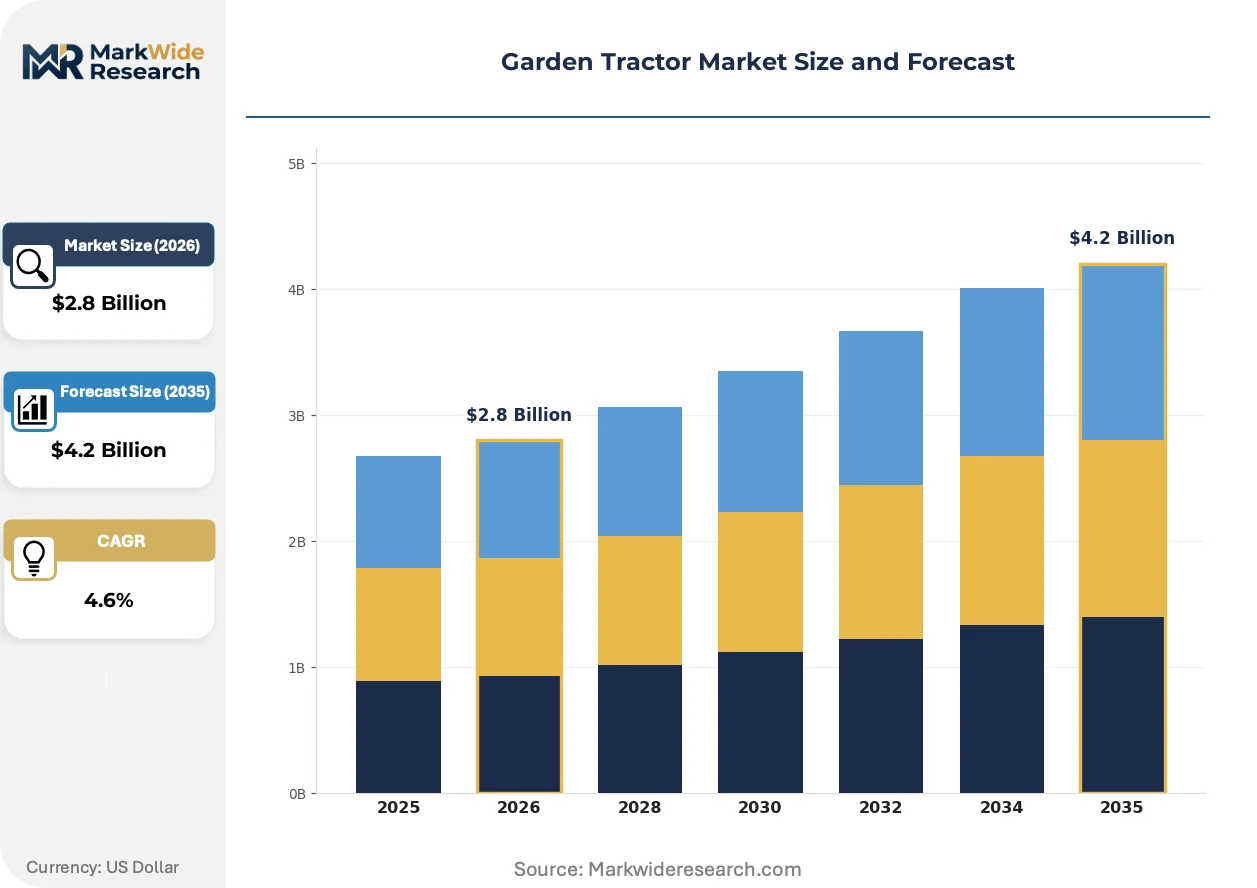
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.2 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compact, Sub-Compact, Utility, Lawn, Heavy-Duty Power Source: Gasoline, Diesel, Electric, Hybrid, Propane End User: Landscaping Professionals, Smallhold Farmers, Groundskeepers, Hobby Gardeners Distribution Channel: Specialty Dealers, Home Improvement Stores, Online Retailers, Agricultural Retailers |
| Companies Covered | CNH Industrial, New Holland, John Deere, TYM, Massey Ferguson, Kubota Corporation, Mahindra & Mahindra Ltd., Cub Cadet, AGCO Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Garden Tractor Market Strategic Shifts & Innovations
Electrification is fundamentally altering product design, moving the focus from purely mechanical performance to software-enabled features and connected services. This shift is creating new value propositions centered on operational efficiency, remote management, and regulatory compliance for both residential and commercial users.
Onboard telematics and connectivity modules are becoming standard features in premium garden tractors. Commercial fleet managers are the primary adopters, using the technology to track equipment location, monitor operating hours for maintenance scheduling, and diagnose faults remotely. This data-centric functionality is converging with battery management systems in electric models, enabling predictive alerts on cell health and optimizing charging cycles for longer battery life.
Stricter regulations, such as the California Air Resources Board (CARB) mandates aiming to phase out new small off-road engines, are accelerating the transition away from gasoline power. This regulatory pressure forces manufacturers to reallocate R&D budgets toward battery-electric platforms to ensure future market access. The utility and heavy-duty product segments are most affected, as redesigning these powerful engines for compliance is more complex and costly than developing new electric alternatives.
Subscription-based models are emerging as a new channel for high-end robotic and autonomous mowers. This disrupts the traditional dealer-based, one-time purchase by offering consumers an all-inclusive service package covering the hardware, software updates, and routine maintenance for a monthly fee. This trend is most prominent in affluent suburban markets in North America and Western Europe, where buyers prioritize convenience and access to the latest technology over asset ownership.
Garden Tractor Market Segmentation
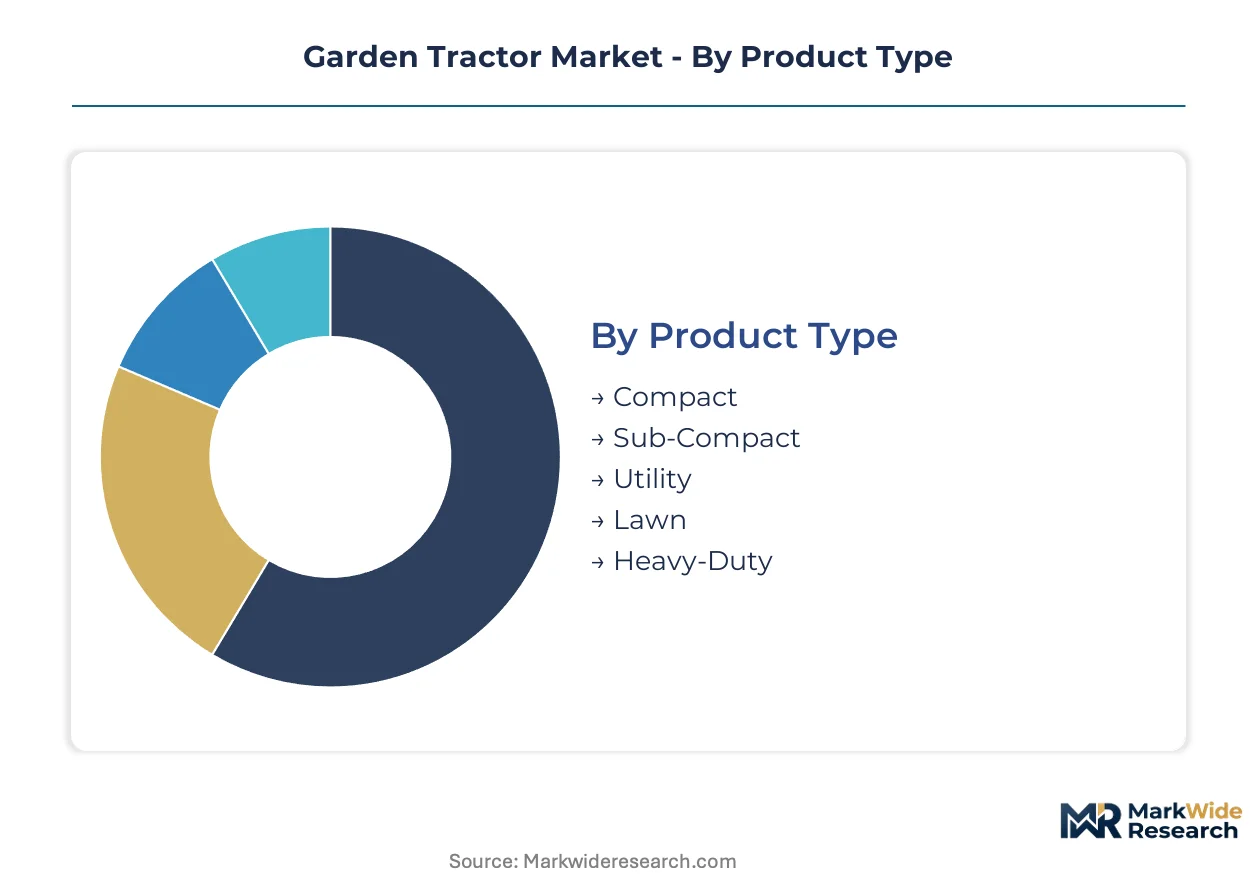
The Garden Tractor Market's segmentation provides a granular understanding of product variations, user needs, and market accessibility, which is essential for manufacturers to tailor offerings and distribution strategies effectively. Analyzing these segments reveals where innovation is concentrated and how different buyer groups prioritize features and performance.
Product Type:
The product type segmentation differentiates garden tractors based on their core functionality and capacity for integrated ground-engaging attachments, reflecting varying levels of complexity and power.
- Heavy-Duty:These machines feature robust frames and engines typically exceeding 25 horsepower, designed for demanding tasks like extensive tilling, commercial-scale hauling, and operating large implements. Demand from landscaping professionals and smallhold farmers is particularly strong, driven by the need for versatile equipment that can withstand continuous, rigorous use.
- Utility:Utility garden tractors offer a balance of power and maneuverability, commonly equipped with 20-30 horsepower engines and a range of attachment options for diverse property maintenance. Small farm operators and commercial property managers frequently procure these models, valuing their adaptability for tasks beyond simple mowing, including snow removal and material transport.
- Lawn:Primarily designed for mowing larger lawns, these tractors typically feature engines under 20 horsepower and focus on comfort and ease of use for residential users.
- Compact:Compact garden tractors are smaller, more agile machines suitable for properties with tight spaces or where lighter ground engagement is required.
- Sub-Compact:These are the smallest class, often bridging the gap between lawn tractors and full-sized utility models, serving niche applications on very small properties.
Lawn models lead volumes today; Heavy-Duty is gaining share fastest.
Power Source:
The power source segmentation reflects the varying technological maturity and environmental compliance levels across different engine types, influencing operational costs and regulatory adherence.
- Electric:These tractors operate on battery power, producing zero tailpipe emissions and significantly reduced noise, making them ideal for noise-sensitive areas and municipal fleets. Strict municipal noise ordinances and increasing sustainability mandates from public works agencies drive procurement of electric models.
- Gasoline:Gasoline-powered models utilize traditional internal combustion engines, offering familiar operation and widespread fuel availability, often at a lower initial purchase price. Residential consumers and budget-conscious buyers continue to favor gasoline tractors due to their established performance and lower upfront investment compared to electric alternatives.
- Diesel:Diesel engines provide high torque and fuel efficiency for heavy-duty applications, particularly favored in larger agricultural or commercial settings requiring sustained power.
- Hybrid:Hybrid systems combine gasoline engines with electric motors, offering improved fuel economy and reduced emissions while maintaining extended runtime capabilities.
- Propane:Propane-fueled tractors offer cleaner burning emissions than gasoline, suitable for specific indoor or enclosed environments where air quality is a concern.
Gasoline continues to dominate sales, while Electric models are expanding most quickly due to regulatory tailwinds.
End User:
The end user segmentation delineates garden tractor demand based on distinct operational requirements and purchasing motivations of different customer types.
- Landscaping Professionals:This segment requires durable, high-performance equipment capable of continuous operation across diverse terrains and weather conditions, often prioritizing efficiency and low emissions. Commercial landscaping businesses operating in urban and suburban environments increasingly invest in quieter, electric models to comply with municipal noise ordinances and secure contracts.
- Smallhold Farmers:These users seek versatile machines for a variety of agricultural tasks, including cultivation, planting, and hauling, on properties typically larger than one acre but smaller than commercial farms. Smallhold farmers prioritize ruggedness and the ability to accept multiple ground-engaging attachments to maximize productivity across diversified operations.
- Groundskeepers:Professionals managing large institutional properties like golf courses, parks, and schools require specialized equipment for precision mowing and general grounds maintenance.
- Hobby Gardeners:This segment comprises residential users who operate garden tractors for personal property maintenance, focusing on ease of use, comfort, and basic mowing or hauling capabilities.
Landscaping Professionals and Smallhold Farmers drive demand for robust equipment, while Hobby Gardeners prioritize ease of use.
Distribution Channel:
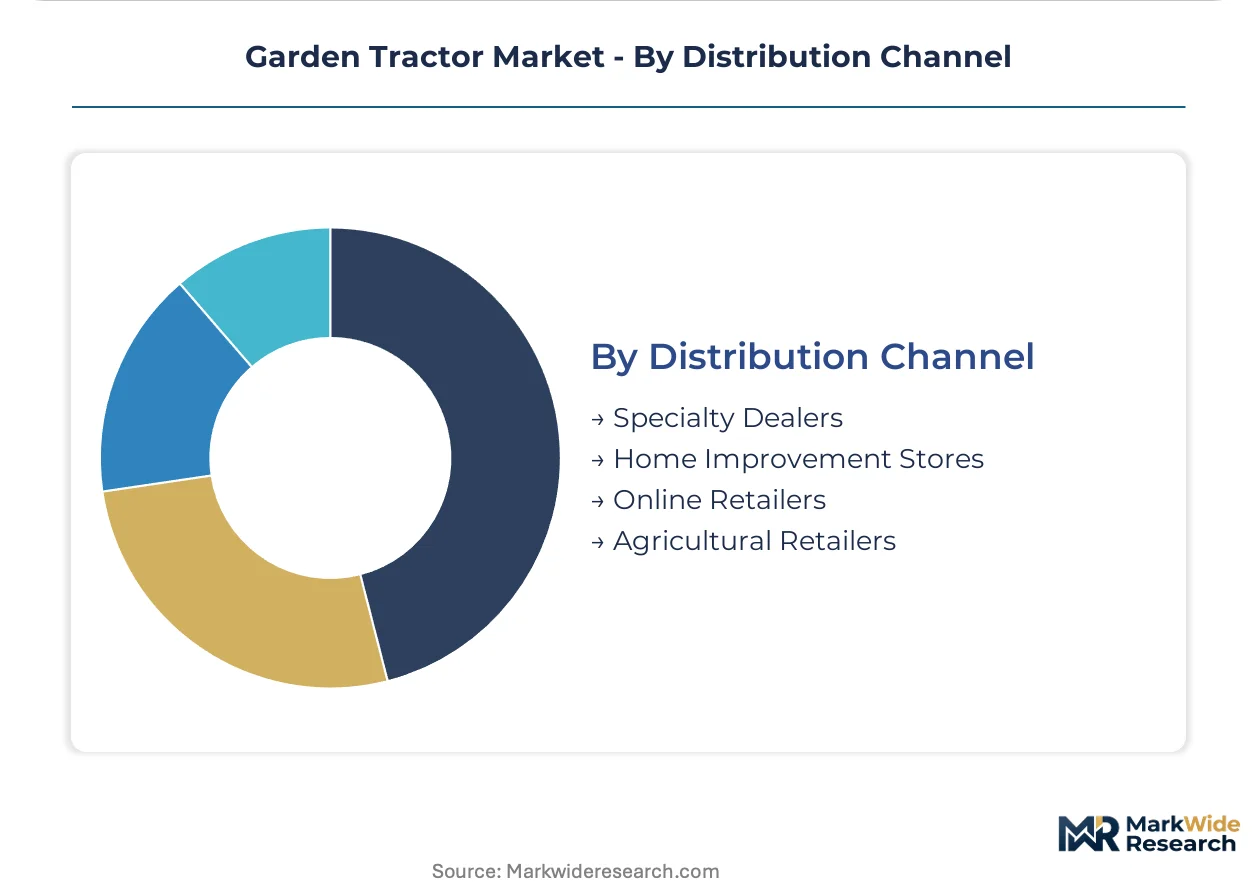
The distribution channel segmentation highlights how garden tractors reach consumers, reflecting varying levels of service integration and market access for different buyer profiles.
- Specialty Dealers:These outlets offer comprehensive sales, service, and parts support, often focusing on premium brands and complex machinery, catering to commercial and discerning residential buyers. Commercial customers and residential users seeking expert advice and dedicated after-sales support frequently purchase through specialty dealers, who provide specialized knowledge and maintenance services.
- Home Improvement Stores:These large retail chains provide accessible points of purchase for a broad range of garden tractors, particularly entry-level and mid-range models, appealing to the general residential consumer. Residential consumers and DIY enthusiasts are drawn to home improvement stores for their convenience, competitive pricing, and the ability to compare multiple brands in one location.
- Online Retailers:Digital platforms offer a wide selection and competitive pricing, facilitating direct-to-consumer sales, particularly for smaller, less complex garden tractor models.
- Agricultural Retailers:Stores specializing in farm equipment and supplies serve rural communities, offering heavy-duty and utility garden tractors alongside other farming machinery.
Specialty Dealers remain critical for complex sales, while Online Retailers are expanding their reach for simpler models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's advanced engineering talent base anchors innovation for high-performance garden tractors across Europe. This expertise drives the development of sophisticated electric and hybrid models. European manufacturers focus on meeting stringent environmental mandates.
Germany
German property management firms prioritize electric models for noise-sensitive urban environments and commercial contracts. The EU's F-Gas Regulation influences design towards zero-emission powertrains, compelling manufacturers to innovate. Manufacturers in Bavaria are actively modernizing their fleets to meet local sustainability targets and consumer preferences.
United States
United States landscaping professionals demand robust, versatile equipment for large properties and diverse tasks. EPA standards for small off-road engines accelerate the shift towards cleaner technologies. Midwest manufacturing hubs are adapting production lines for electric and hybrid garden tractor models.
Japan
Japanese smallhold farmers require compact, reliable garden tractors suited for intensive cultivation on smaller plots. METI initiatives support the development of efficient agricultural machinery, including electric variants. Manufacturers in Hokkaido specialize in durable models for varied terrain and operational needs.
India
Indian smallhold farmers drive demand for utility-focused garden tractors to enhance agricultural productivity. The PLI scheme for agricultural machinery encourages domestic production of advanced models. Manufacturing facilities in Punjab are expanding capacity for tractors with diverse attachments and power sources.
Brazil
Brazilian property owners and small farms seek durable utility tractors for land management and hauling tasks. Government agricultural support programs incentivize investment in modern farm equipment. Production centers in São Paulo state are developing models tailored for regional conditions and varied agricultural practices.
Garden Tractor Market Key Industry Players
Capital-heavy producers compete with asset-light designers across the garden tractor market. This industry features a blend of established full-line manufacturers and specialized technology providers. Strategic archetypes include integrated machinery giants, niche attachment specialists, and emerging electric powertrain innovators. Dominant competitive moves involve significant R&D investment into battery technologies and strategic partnerships for distribution network expansion.
On the full-line manufacturer vector, John Deere exemplifies a global brand leveraging an extensive dealer network for market access. Kubota Corporation represents a specialist in reliable compact models, catering to smaller-scale operations. CNH Industrial, with its New Holland brand, occupies a position focused on small farm and utility applications, emphasizing versatility for diverse tasks. These companies anchor market segments through their established reputations and product portfolios.
| Leading Market Players |
|---|
| CNH Industrial |
| New Holland |
| John Deere |
| TYM |
| Massey Ferguson |
| Kubota Corporation |
| Mahindra & Mahindra Ltd. |
| Cub Cadet |
| AGCO Corporation |
| Others |
Cost & Logistics Intelligence
Family-owned mid-cap manufacturers often anchor stable pricing strategies through controlled supply chains, prioritizing long-term customer relationships. This ownership structure influences sourcing decisions for critical components like engines and battery cells, impacting overall cost and pricing.
Pricing Analysis
The bundled-vs-unbundled service split significantly impacts garden tractor pricing, with premium models often including comprehensive maintenance packages. Pricing stratifies across premium, standard, and economy tiers, differentiated by engine horsepower and attachment compatibility. Pricing pressure stems from the higher initial cost of electric models, particularly for residential buyers. Landscaping professionals are less price-sensitive for heavy-duty electric equipment due to regulatory compliance and operational efficiency.
Supply Chain Analysis
Domestic-content mandates, particularly in the United States, reshape sourcing for garden tractor manufacturers by incentivizing local production. The supply chain draws from engine manufacturers in Japan and Germany, with battery cells primarily sourced from China and South Korea. Single-source vulnerability for advanced battery components presents a structural risk. Distribution runs through a network of specialty dealers and home improvement stores.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The garden tractor market acts as a regulatory compounder, with demand significantly amplified by mandates like the EU's F-Gas Regulation. This regulation compels manufacturers to innovate towards zero-emission powertrains, driving market evolution.
For Market Incumbents:Anchor existing dealer networks by providing extensive training on electric and hybrid powertrain diagnostics and repair. Deepen vertical integration into battery module assembly to mitigate supply chain volatility from EV competition. Invest in advanced R&D for next-generation battery technologies to counter performance gaps in heavy-duty applications. Control channel access through exclusive service agreements to fend off emerging electric-only entrants.
For New Entrants and Emerging Players:Launch via direct-to-consumer online channels, targeting residential users in affluent suburban markets with subscription-based robotic mowers. Penetrate the municipal fleet segment by offering specialized electric models that meet public-sector sustainability mandates. Focus on software-enabled features and remote management capabilities to differentiate from traditional gasoline models. Emphasize quiet operation and low emissions for noise-sensitive commercial contracts.
For Investors and Strategic Acquirers:Valuations sit cheapest among legacy gasoline-focused manufacturers needing significant capital for electrification transition. The long-term viability of the market depends on successful integration of battery-electric powertrains and autonomous capabilities. Target acquisition profiles include niche technology providers specializing in battery management systems or robotic navigation. Watch for accelerated regulatory phase-outs of small off-road engines as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| R&D in advanced battery chemistry | This initiative ensures longer runtimes and addresses performance gaps for heavy-duty electric garden tractors. |
| Comprehensive dealer training on EV service | Equipping service networks with new diagnostic skills supports the transition to complex electric powertrain systems. |
| Strategic partnerships for charging infrastructure | Collaborations with energy providers alleviate logistical hurdles for commercial fleets operating across job sites. |
| Development of autonomous navigation systems | Integrating GPS and sensor technology creates premium robotic mowers for large commercial properties. |
| Specialized electric models for public works | Tailoring equipment for municipal parks departments opens a new sales channel driven by sustainability mandates. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary insights with secondary validation. Interviews with product development executives, procurement managers, specialty dealers, and landscaping professionals informed market dynamics. Secondary sources included regulatory filings, industry association reports, and financial disclosures of public companies. A bottom-up and top-down triangulation approach ensured data consistency.
Segment weighting by product type, power source, end-user, and distribution channel formed the basis of the forecast framework. These dimensions, alongside regional regulatory shifts and battery technology advancements, were modeled across the analysis window. Compound annual growth rates were derived from historical trends and projected market drivers. Electric vehicle adoption rates and municipal sustainability budgets served as key forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under rapid shifts in battery raw material prices or unforeseen regulatory changes. Forecasts reflect assumptions documented at the time of publication. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Machinery
Forestry Machinery Market
Agricultural Machinery
China Agricultural Machinery Market
Agricultural Machinery
Mini Tractors Market
Agricultural Machinery
Global Tractor Market
Agricultural Machinery
Canada Agricultural Machinery Market
Agricultural Machinery
Spain Agricultural Machinery Market
Agricultural Machinery
Driverless Tractor Market
Agricultural Machinery
United States Agricultural Tractor Market
Agricultural Machinery
US Lawn Mowers Market
Agricultural Machinery
Japan Agricultural Machinery Market
Agricultural Machinery
Asia-Pacific Agricultural Machinery Market
Agricultural Machinery
Netherlands Hydrogen Powered Tractor Market
Agricultural Machinery
Canada Robotic Fruit Picker Market
Agricultural Machinery
Sickle Bar Mower Market
Agricultural Machinery
Two Wheel Walking Tractor Market
Agricultural Machinery
Agricultural Spray Drone Market