
 Autonomous Farm Equipment Market | 2026-2036
Autonomous Farm Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Autonomous Farm Equipment Market Analysis
Commercial farm operations is consolidating around autonomous tractor and harvester fleets as labor scarcity reshapes procurement priorities. John Deere leverages its precision-agriculture software stack to anchor North American deployment. AGCO Corporation competes through specialized seeder autonomy protocols. Kubota Corporation extends its compact-equipment dominance into Asian rice-paddy automation.
Autonomous farm equipment comprises self-guiding tractors, harvesters, seeders, and sprayers that integrate GPS positioning, LIDAR obstacle detection, computer vision, and artificial intelligence to execute planting, cultivation, and harvesting cycles without human operators; these systems typically operate at sub-inch accuracy via RTK-GPS correction and process multispectral imagery for real-time agronomic decision-making. Tractors occupy the largest installed base while harvesters capture the steepest technology premium. GPS and AI represent the fastest-growing technology pairing as manufacturers embed edge-computing modules directly into implement controllers.
The EPA, OSHA, and FAA jointly shape equipment emissions, operator-safety exemptions, and aerial-drone integration standards for unmanned agricultural systems in the United States. The EPA Tier 4 Final and emerging Tier 5 emissions thresholds force engine redesigns that favor electric-hybrid autonomous platforms. Stakeholders must monitor how FAA beyond-visual-line-of-sight rulings intersect with state-level autonomous-vehicle codes to determine where swarming drone sprayers gain legal clearance first.
Market Dynamics
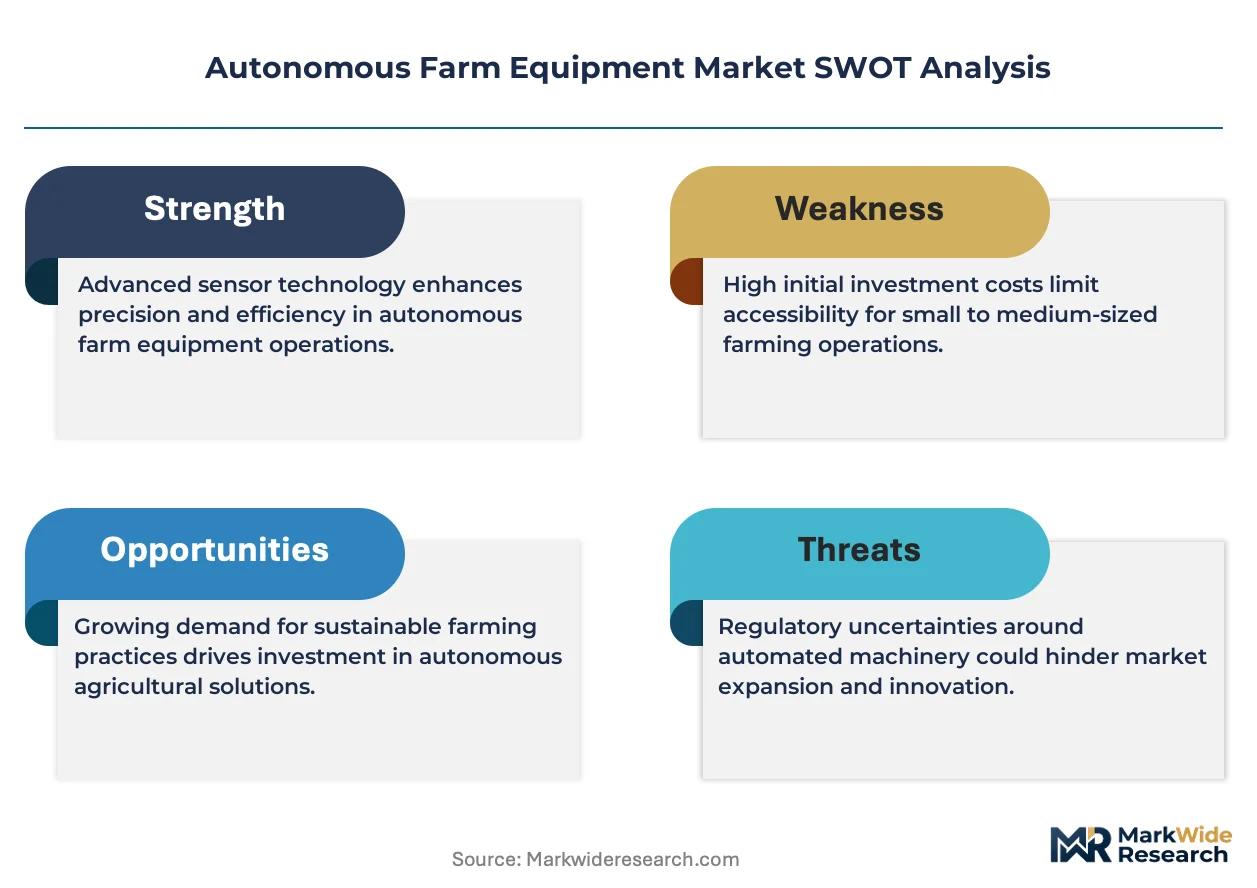
Labor scarcity across the Midwest grain belt is accelerating fleet consolidation around autonomous platforms, while EPA Tier 4 Final compliance costs compress margins for conventional diesel-powered equipment.
Growth Catalysts
- RTK-GPS Correction Networks:Sub-inch accuracy enables fully unmanned planting and harvesting cycles. Commercial grain operations in the United States are retrofitting existing fleets with these positioning modules.
- OSHA Worker-Safety Exemptions:Regulatory clarity for unmanned vehicle operation removes liability barriers. Large-scale farms now deploy autonomous sprayers without onboard supervisors.
- Computer Vision Convergence:Multispectral imaging integrates with edge-computing controllers for real-time agronomic decisions. Cotton and soybean producers capture immediate yield optimization.
Market Restraints
- Lithium-Ion Battery Supply Concentration:Cell production clusters in East Asian manufacturing hubs expose autonomous equipment makers to input volatility and geopolitical friction.
- FAA Beyond-Visual-Line-of-Sight Delays:Regulatory uncertainty for swarming aerial sprayers stalls drone-as-a-service expansion in US airspace.
- High-Precision Sensor Cost Structure:LIDAR and multispectral camera assemblies represent 35-40% of total platform cost, compressing OEM margins and limiting mid-tier farm access.
Strategic Opportunities
- Indian Rice-Paddy Automation:Small-field geometries and labor migration create demand for compact autonomous transplanters. Kubota and domestic manufacturers are localizing production.
- EU Green Deal Agricultural Subsidies:Carbon-reduction mandates favor electric-hybrid autonomous fleets. French and German cooperatives access preferential financing for zero-emission replacements.
- AI-Edge Module Convergence:Embedded inference chips enable real-time weed identification without cloud dependency. Specialty crop growers in California deploy these for precision herbicide application.
Industry Challenges
- Autonomous Systems Engineering Talent Scarcity:The intersection of robotics, agronomy, and embedded software commands premium compensation. OEMs compete with autonomous vehicle developers for limited talent pools.
- Legacy Fleet Integration Complexity:Proprietary CAN bus protocols from 1990s-era tractors resist retrofitting. Farmers face stranded asset risk when autonomous platforms cannot communicate with existing implements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Autonomous Farm Equipment Market |
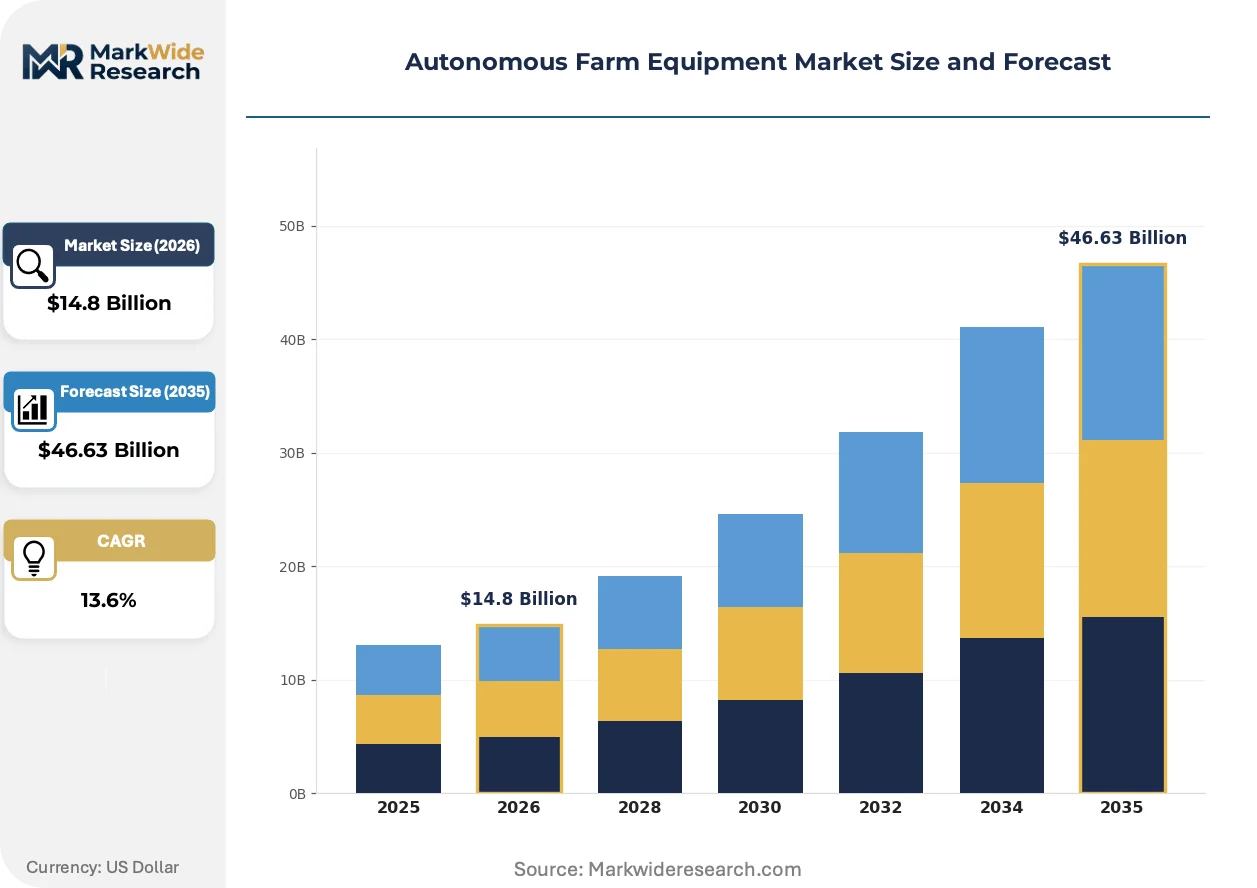
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $46.63 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tractors, Harvesters, Seeders, Sprayers Technology: GPS, LIDAR, Computer Vision, AI End User: Farmers, Agricultural Cooperatives, Commercial Farms, Research Institutions Deployment: On-Premise, Cloud-Based, Hybrid, Remote |
| Companies Covered | Kubota Corporation, New Holland Agriculture, John Deere, Autonomous Solutions Inc., Fendt, AGCO Corporation, Claas, Raven Industries, Case IH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Autonomous Farm Equipment Market Emerging Trajectories
Equipment architecture is fragmenting into interoperable subsystems as manufacturers abandon monolithic designs. This shift enables third-party autonomy retrofitting and accelerates technology refresh cycles.
Implement controllers are modularizing around standardized edge-computing footprints. Seeder and sprayer manufacturers now source autonomy modules from specialized suppliers rather than developing proprietary stacks. This compression of vertical scope allows mid-size OEMs to compete in autonomous segments without billion-dollar R&D programs.
EPA Tier 5 emissions thresholds are forcing engine platform redesigns toward electric-hybrid architectures. These powertrain shifts favor autonomous integration by eliminating mechanical transmission complexity. Harvester manufacturers in the United States are prioritizing battery-electric prototypes for 2028 compliance windows.
Service contracting is displacing equipment ownership among grain cooperatives. Midwest operators now lease autonomous capacity by acre rather than maintaining depreciating iron. This preference shift concentrates demand among fleet-scale providers and compresses distributor margins on unit sales.
Autonomous Farm Equipment Market Segmentation
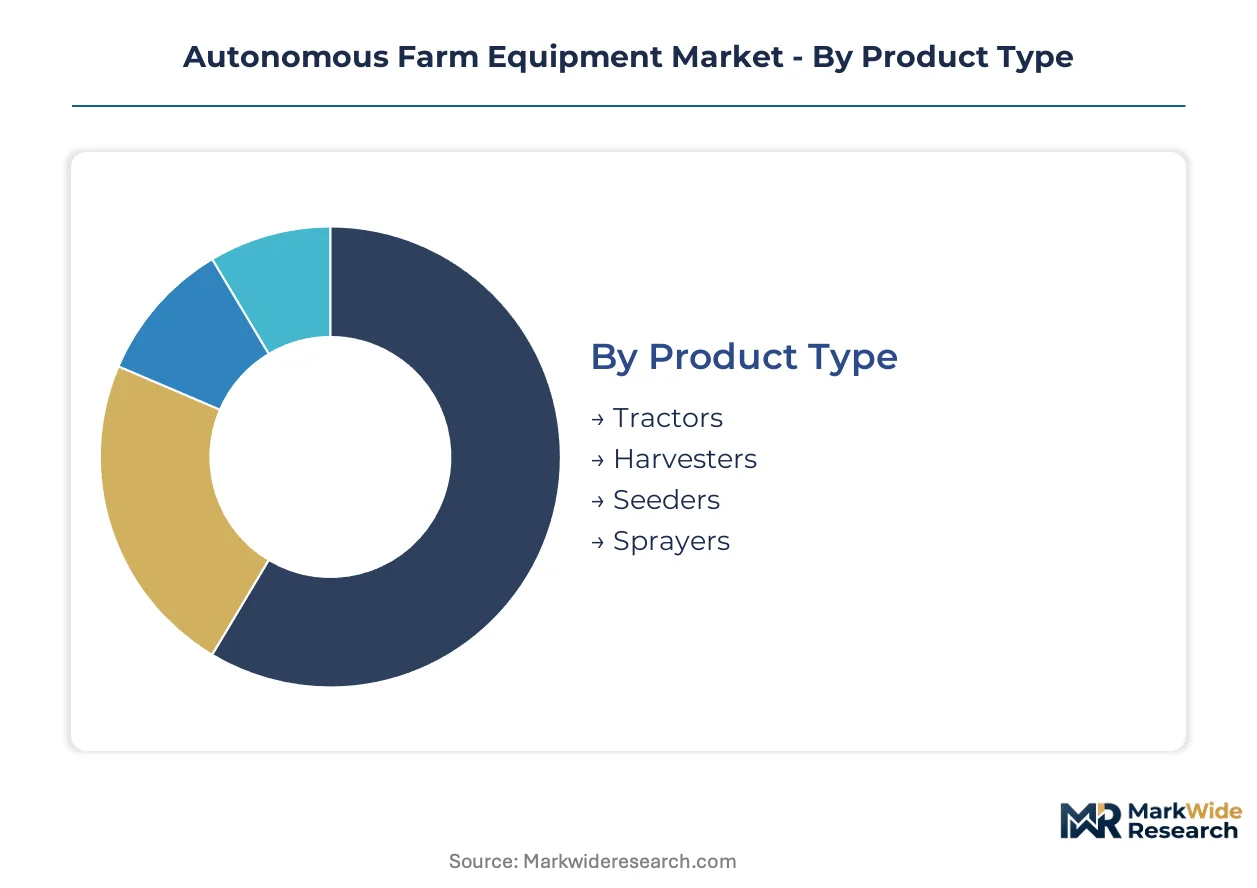
Autonomous farm equipment segmentation reveals how regulatory compliance burdens concentrate in specific product categories while technology pairings determine deployment economics. Understanding these divisions exposes where certification costs and integration complexity create barriers to adoption.
Product Type:
EPA Tier 4 Final and emerging Tier 5 emissions frameworks impose divergent certification burdens across equipment categories, with harvesters facing the steepest engine redesign requirements.
- Tractors:Self-guiding power units integrate RTK-GPS correction and implement control systems for tillage, planting, and cultivation cycles. Demand concentrates in the United States Midwest grain belt where labor scarcity drives fleet consolidation around autonomous platforms capable of 24-hour operation.
- Harvesters:Combine platforms execute grain and specialty crop collection through computer vision-guided headers and yield-mapping systems. Commercial grain operations in Iowa, Illinois, and Nebraska capture technology premiums through sub-inch accuracy during narrow harvest windows.
- Seeders:Precision planting equipment distributes seeds at variable rates based on real-time soil mapping and prescription algorithms.
- Sprayers:Autonomous application vehicles deploy herbicides and fertilizers with boom-section control and obstacle avoidance.
Tractors sit at the top of the volume ranking, with harvesters climbing the fastest as technology premiums justify replacement cycles.
Technology:
Cost tier stratification separates foundational positioning systems from premium sensing stacks, with AI modules commanding the highest per-unit investment.
- GPS:RTK-corrected positioning enables centimeter-level accuracy for boundary following and implement guidance. Commercial farms across Kansas, Nebraska, and the Dakotas retrofit existing fleets with these modules to extend equipment life.
- AI:Embedded inference processors execute real-time agronomic decisions at the edge without cloud dependency. Specialty crop growers in California deploy these systems for precision weed identification and variable-rate herbicide application.
- LIDAR:Laser-based obstacle detection creates 3D field maps for collision avoidance in unstructured environments.
- Computer Vision:Multispectral and RGB cameras capture crop health indicators and maturity signals for harvest timing.
GPS maintains the largest installed base, with AI expanding most quickly as edge-computing modules embed directly into implement controllers.
End User:
Customer type determines procurement scale and service contracting preferences, with cooperatives displacing individual ownership models.
- Commercial Farms:Large-scale operations with consolidated acreage deploy full autonomous fleets across planting, cultivation, and harvest cycles. These entities in the United States grain belt lease capacity by acre rather than maintaining depreciating equipment assets.
- Agricultural Cooperatives:Member-owned entities pool capital for shared autonomous capacity and centralized maintenance. Midwest grain cooperatives concentrate demand among fleet-scale providers and compress distributor margins on unit sales.
- Farmers:Individual owner-operators adopt autonomous technology through retrofit kits and phased implementation.
- Research Institutions:University and government agriculture departments validate autonomous protocols and train next-generation agronomists.
Commercial Farms dominate current procurement volume, with Agricultural Cooperatives gaining share fastest as service contracting displaces individual ownership.
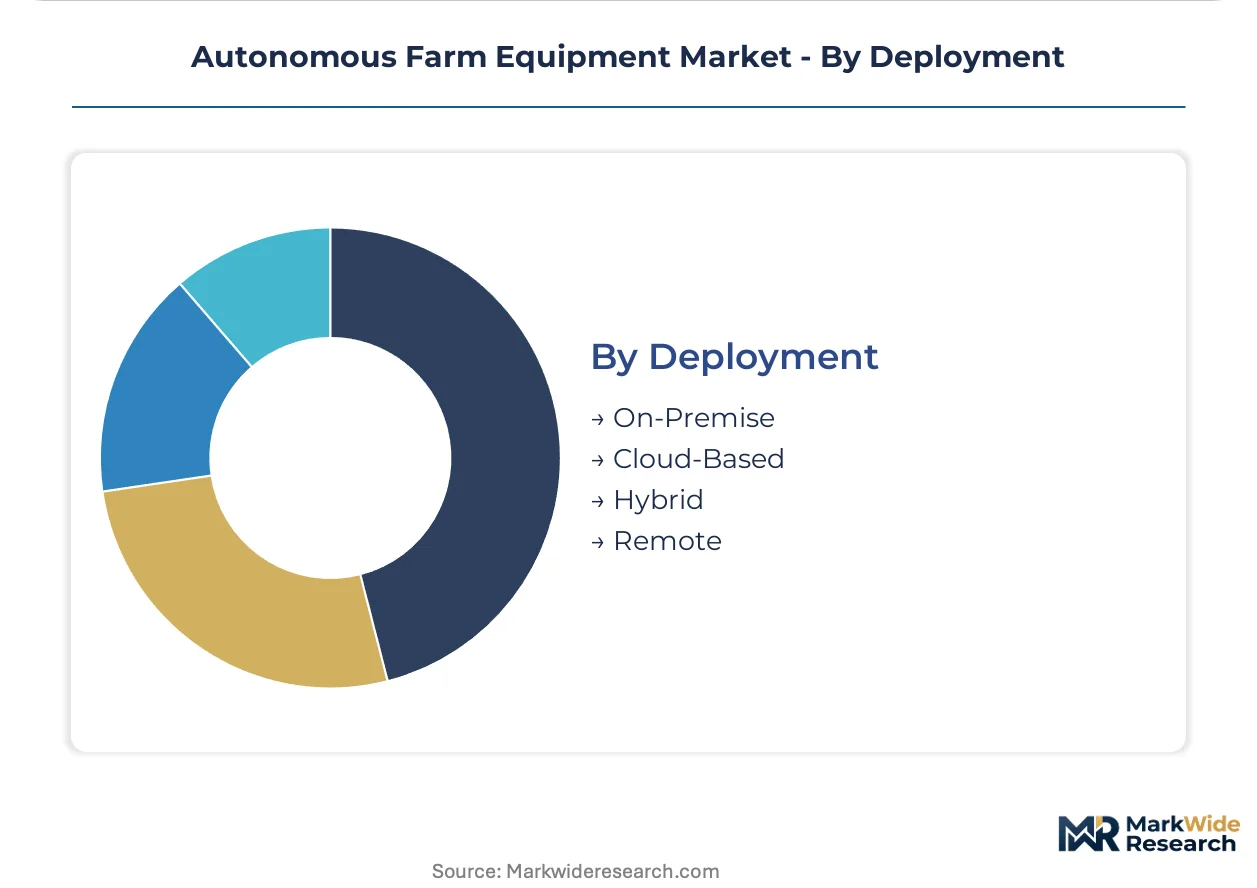
Deployment:
Maturity gradients separate established on-premise architectures from emerging cloud-dependent models, with hybrid approaches capturing intermediate positions.
- On-Premise:Edge-computing controllers process sensor data locally without network dependency for real-time vehicle control. This architecture dominates Midwest grain operations where cellular coverage gaps threaten mission-critical field operations.
- Hybrid:Split processing between edge inference and cloud analytics balances real-time control with agronomic optimization. Cotton and soybean producers in the Mississippi Delta deploy these configurations for yield mapping and prescription generation.
- Cloud-Based:Centralized processing enables fleet-wide coordination and predictive maintenance across distributed equipment.
- Remote:Teleoperation capabilities allow human intervention during edge-case scenarios beyond autonomous system training.
On-Premise retains the largest deployment base, with Hybrid configurations expanding most quickly as connectivity infrastructure improves in agricultural regions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturers are relocating final assembly and calibration facilities to jurisdictions where emissions compliance costs remain lower than in the United States and Western Europe. This regulatory arbitrage concentrates autonomous equipment production in countries with emerging agricultural automation codes but established heavy machinery ecosystems.
United States
Midwest grain belt operations in Iowa, Illinois, and Nebraska drive fleet consolidation around 24-hour autonomous platforms. EPA Tier 4 Final and emerging Tier 5 thresholds force engine redesigns favoring electric-hybrid architectures. Fargo-Moorhead and Moline-Rock Island anchor precision agriculture R&D clusters where John Deere and Case IH validate RTK-GPS guidance systems.
Germany
Carbon-reduction mandates under the EU Green Deal accelerate cooperative procurement of zero-emission autonomous fleets. REACH chemical regulations and CE marking requirements shape sprayer autonomy protocols. Stuttgart and Munich host engineering centers where Fendt and Claas integrate edge-computing modules into harvester platforms.
Japan
Compact equipment demand for rice-paddy automation responds to rural labor migration and aging farm demographics. METI standards for agricultural robotics guide safety exemption frameworks. Osaka-based manufacturers localize production of autonomous transplanters for Southeast Asian export markets.
India
Small-field geometries and seasonal labor scarcity create demand for affordable autonomous seeders and sprayers. PLI scheme incentives support domestic manufacturing of precision agriculture components. Punjab and Haryana testbeds validate computer vision systems for variable-rate fertilizer application in fragmented landholdings.
Brazil
Scale grain operations in Mato Grosso and Goiás deploy autonomous harvesters across soybean and corn mega-farms. ANVISA agrochemical regulations intersect with state-level autonomous vehicle codes for sprayer deployment. São Paulo engineering clusters adapt European autonomy stacks for tropical field conditions.
Autonomous Farm Equipment Market Vendor Landscape
Strategic partnerships dominate the current landscape as OEMs source autonomy modules from specialized suppliers rather than building proprietary stacks in-house. The vendor base organizes around three tiers: integrated equipment majors with precision agriculture software stacks, component specialists supplying edge-computing and sensor assemblies, and regional fabricators focusing on crop-specific implement autonomy. Technology licensing and backward integration into lithium-ion powertrains represent the two most active competitive vectors.
Among integrated equipment majors, John Deere, Kubota Corporation, and AGCO Corporation exemplify contrasting geographic and crop-specialization strategies. Deere anchors North American deployment through its precision agriculture ecosystem. Kubota extends compact equipment dominance into Asian rice-paddy automation. AGCO occupies a position between these archetypes through specialized seeder autonomy protocols and European cooperative relationships.
| Leading Market Players |
|---|
| Kubota Corporation |
| New Holland Agriculture |
| John Deere |
| Autonomous Solutions Inc. |
| Fendt |
| AGCO Corporation |
| Claas |
| Raven Industries |
| Case IH |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap implement manufacturers anchor tier-two supply tiers, translating generational balance-sheet discipline into stable input contracting that buffers OEMs from lithium-ion cell volatility while compressing distributor margin capture.
Pricing Analysis
Distributor margin layers in autonomous farm equipment absorb 18-22 points before reaching commercial grain operators, with direct-to-OEM volume discounts compressing this spread for fleet-scale cooperatives. Three-tier pricing structure across premium RTK-GPS integrated platforms, standard guidance-retrofit kits, and economy sensor-only configurations separates John Deere ecosystem bundles from AGCO seeder protocols and Kubota compact lines. Pricing pressure stems from EPA Tier 5 engine redesign costs forcing electric-hybrid R&D allocation, with mid-tier farmers exhibiting highest price sensitivity as LIDAR and multispectral assemblies claim 35-40% of platform cost.
Supply Chain Analysis
Refurbishment flows for 1990s-era tractors with proprietary CAN bus protocols create secondary parts markets that extend legacy fleet life, complicating autonomous retrofit demand timing. Lithium-ion cell production clusters in China, South Korea, and Japan, with edge-computing modules sourcing from Taiwan and Malaysia. Raw material dependencies span rare-earth magnets for electric motors, high-purity silicon for inference chips, and cobalt-nickel cathode formulations. Single-source vulnerability concentrates in RTK-GPS correction network infrastructure. Distribution runs through manufacturer-direct fleet contracts and agricultural equipment dealer networks serving Midwest grain belt counties.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Autonomous farm equipment functions as a late-cycle quality story where labor scarcity across Iowa, Illinois, and Nebraska accelerates demand-shift toward sub-inch accuracy specifications that command technology premiums.
For Market Incumbents: Lock in proprietary precision-agriculture software stacks through API control over third-party implement controllers, defending against modular autonomy suppliers eroding vertical scope. Deepen backward integration into lithium-ion powertrain architectures before EPA Tier 5 compliance windows tighten. Channel control through fleet-scale service contracting anchors customer retention as acre-based leasing displaces unit sales.
For New Entrants and Emerging Players: Enter via Indian rice-paddy automation where small-field geometries and PLI scheme incentives reward compact transplanter specialization over full-size grain platform competition. Target Southeast Asian export markets through Osaka-based engineering partnerships. Go-to-market leverage rests on computer vision weed-identification modules that bypass cloud dependency for cellular-coverage-constrained operations.
For Investors and Strategic Acquirers: Valuations sit cheapest among component specialists supplying edge-computing and LIDAR assemblies, where engineering talent scarcity at the robotics-agronomy-software intersection commands premium compensation. Long-term viability centers on acquisition of autonomy module suppliers with validated implement-controller footprints. FAA beyond-visual-line-of-sight rulings for swarming aerial sprayers signal regulatory inflection timing.
| Strategic Initiative | Industry Significance |
|---|---|
| RTK-GPS Network Expansion | Sub-inch accuracy unlocks fully unmanned planting cycles for Midwest grain cooperatives. |
| Electric-Hybrid Powertrain Transition | EPA Tier 5 compliance forces battery-electric harvester prototypes by 2028. |
| Edge-Computing Module Integration | Embedded inference chips enable real-time agronomic decisions without cloud latency. |
| Service Contracting Model Shift | Acre-based leasing concentrates demand among fleet-scale providers compressing distributor margins. |
| Indian Manufacturing Localization | PLI scheme incentives support domestic production of precision agriculture components for fragmented landholdings. |
Methodological Framework
Bottom-up commercial farm and cooperative procurement modeling reconciled against top-down OEM production and lithium-ion cell supply tracking forms the analytical core of this study. Primary interviews with precision agriculture software directors, fleet operations managers at grain cooperatives, agricultural equipment dealer principals, and EPA regulatory affairs specialists combined with secondary validation against SEC 10-K filings, USDA agricultural census data, FAA regulatory dockets, and customs trade records. Triangulation between demand-side adoption patterns and supply-side capacity announcements anchors volume estimates.
Historical trendline analysis of autonomous guidance system penetration rates across planting, cultivation, and harvest cycles informs projection frameworks across the modeling period. Segmentation dimensions span equipment category, technology pairing, end-user archetype, and deployment architecture, with crop-specific automation protocols modeled separately for grain versus specialty crop applications. CAGRs derive from equipment replacement cycle timing, regulatory compliance window clustering, and labor cost trajectory assumptions in key agricultural counties.
Inputs from OEM production schedules and cooperative fleet procurement announcements were available through the study window; gaps in FAA beyond-visual-line-of-sight rulemaking timelines and OSHA unmanned vehicle exemption granularity introduce uncertainty bands around aerial sprayer adoption curves. Forecasts reflect documented assumptions regarding EPA Tier 5 implementation pacing and lithium-ion cell cost trajectories. Practitioners should monitor FAA state-level autonomous vehicle code intersections and Indian PLI scheme component localization progress for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Machinery
Agricultural Forestry Machinery Market
Agricultural Machinery
Power Tiller Market
Agricultural Machinery
Southeast Asia Agricultural Tractors Market
Agricultural Machinery
Agriculture Tire Market
Agricultural Machinery
Italy Agricultural Machinery Market
Agricultural Machinery
Vietnam Agricultural Tractor Market
Agricultural Machinery
Garden and Orchard Tractors Market
Agricultural Machinery
North America Agricultural Tractors Market
Agricultural Machinery
Mini Tractors Market
Agricultural Machinery
Agricultural Drum Mowers Market
Agricultural Machinery
Electric Farm Tractor Market
Agricultural Machinery
Agricultural Harvester Market
Agricultural Machinery
Canada Agricultural Machinery Market
Agricultural Machinery
China Agricultural Machinery Market
Agricultural Machinery
South America Agricultural Tractors Market
Agricultural Machinery
Milking Robots Market