
 Electric Farm Tractor Market | 2026-2036
Electric Farm Tractor Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Farm Tractor Market Analysis
The premium-commodity split in electric farm tractors is shifting along battery capacity and autonomy integration, not horsepower alone. Deere & Company leverages its precision agriculture software stack to command premium positioning in autonomous-ready platforms. Monarch Tractor anchors the mid-tier with fully electric utility models designed for vineyard and orchard configurations. Kubota Corporation dominates compact tractor segments across Asian horticulture markets through localized manufacturing scale.
An electric farm tractor is a battery-powered or hybrid agricultural vehicle designed for soil preparation, crop management, and material handling, typically operating at 40–150 kW continuous power output with lithium-ion phosphate or solid-state battery architectures. Its primary purpose is to replace diesel combustion in field operations while enabling torque-vectoring and precision implement control. Compact tractors and utility tractors lead volume shipments, though row crop tractors concentrate margin pools where battery scaling above 100 kWh creates technical barriers. Battery electric technology occupies the dominant share, while hydrogen fuel cell variants attract R&D investment for large-scale enterprise deployments requiring rapid refueling.
The EPA tailpipe standards and EU F-Gas Regulation shape powertrain compliance timelines, while India's PLI scheme for advanced chemistry cell manufacturing redirects battery sourcing geography. The EU AI Act and emerging ISO standards for autonomous agricultural machinery will determine which OEMs retain market access across regulatory blocs. Stakeholders must monitor certification pathways for autonomous operation and battery recycling mandates as these become preconditions for fleet procurement contracts.
Market Dynamics
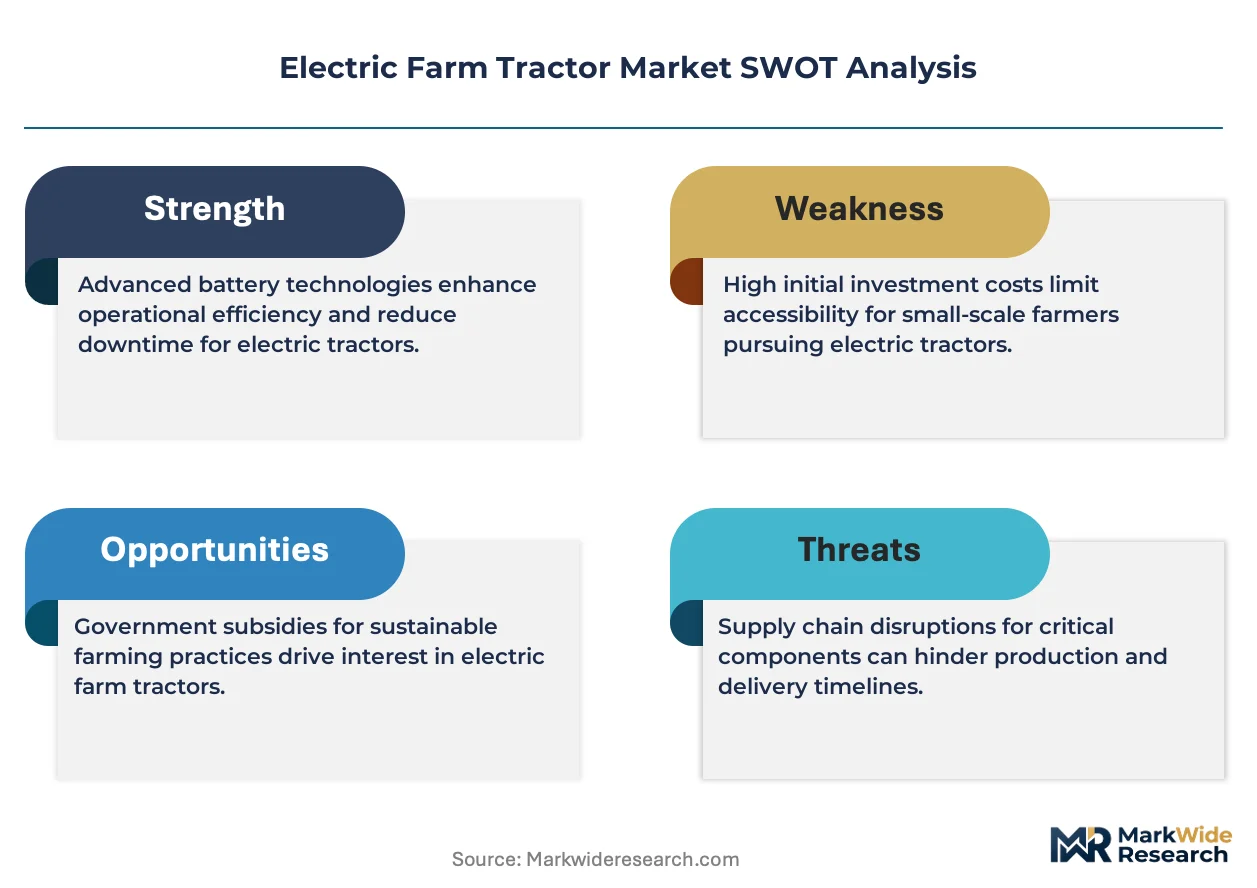
Battery energy density improvements and fast-charging protocol standardization are compressing replacement cycles while EU Green Deal subsidy timelines force fleet electrification decisions before total cost of ownership parity is achieved.
Growth Catalysts
- EU F-Gas Regulation:Stringent fluorinated gas phase-down mandates accelerate diesel tractor retirement timelines across German precision agriculture clusters, pulling forward electrified fleet procurement.
- Lithium iron phosphate chemistry:Thermal stability and cycle life improvements in battery architectures reduce fire risk premiums for insurers covering large-scale agricultural operations.
- Vineyard configurations:Narrow-track electric utility tractors penetrate high-value specialty crop segments where diesel particulate emissions damage fruit quality and worker health.
Market Restraints
- Battery raw material concentration:Cobalt and lithium refining capacity concentrates in limited jurisdictions, exposing OEMs to supply disruption and forced labor scrutiny in upstream extraction.
- Grid interconnection queues:Rural electrical infrastructure upgrade backlogs in agricultural regions delay on-farm fast-charging deployment and strand early electric tractor adopters.
- Hydrogen fuel cell substitution:Rapid refueling requirements for large-scale row crop operations sustain R&D investment in alternative zero-emission powertrains competing for capital allocation.
Strategic Opportunities
- India PLI scheme:Advanced chemistry cell manufacturing incentives redirect battery sourcing geography and create localized supply chains for Asian horticulture tractor production.
- Autonomous implement convergence:Torque-vectoring electric drivetrains integrate with precision agriculture software stacks to enable sub-inch accuracy in autonomous tillage and planting operations.
- Direct-to-grower channels:Equipment-as-a-service platforms bypass traditional dealer networks and capture recurring revenue from smallholder cooperatives in fragmented markets.
Industry Challenges
- ISO 18497 certification timelines:Autonomous agricultural machinery safety standards remain under development, creating regulatory uncertainty for OEMs pre-positioning self-driving tractor platforms.
- High-voltage technician scarcity:Rural service networks lack trained personnel for battery pack diagnostics and thermal runaway containment, extending downtime and eroding customer confidence.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Farm Tractor Market |
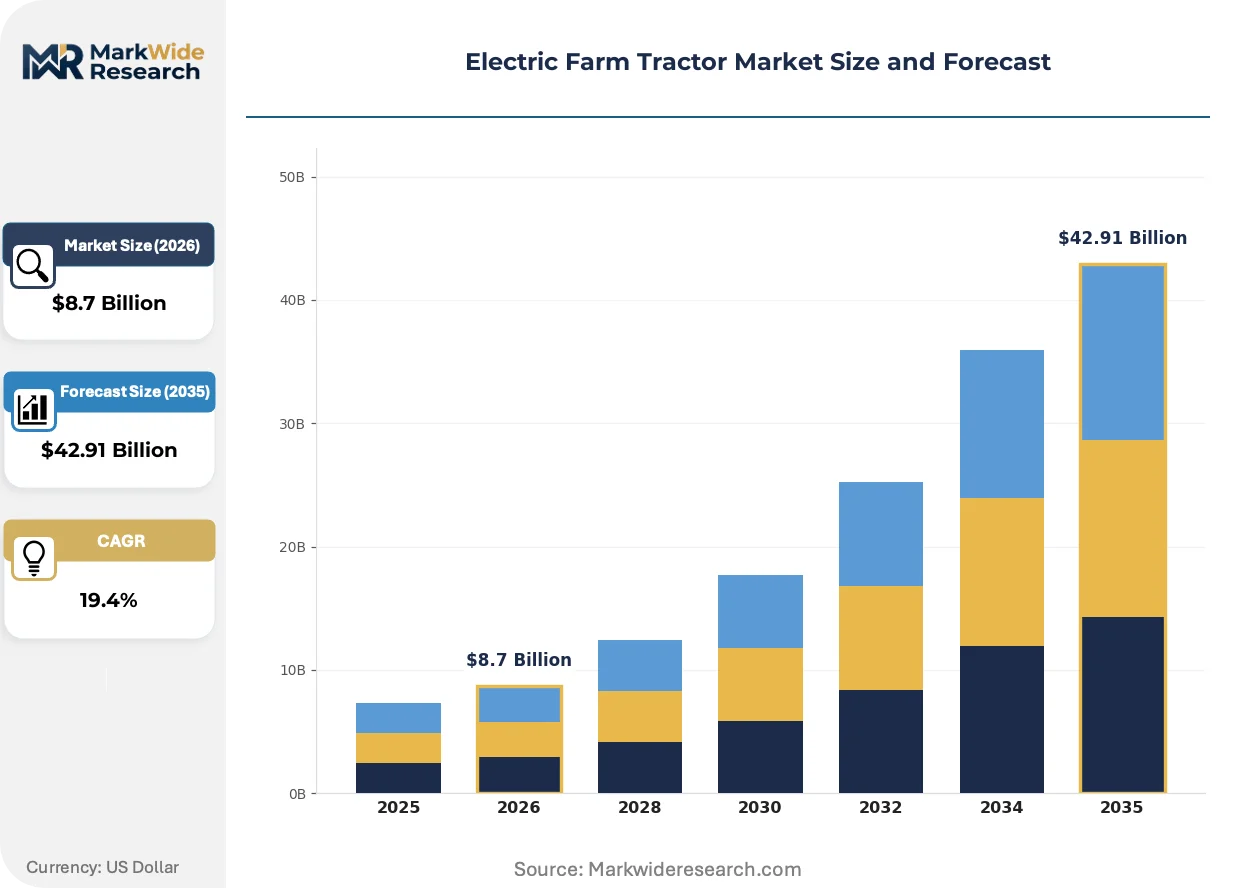
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $42.91 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compact Tractors, Utility Tractors, Row Crop Tractors, Specialty Tractors End User: Commercial Farmers, Agricultural Cooperatives, Smallholders, Large-scale Enterprises Technology: Battery Electric, Hybrid Electric, Hydrogen Fuel Cell, Solar Powered Application: Tillage, Planting, Harvesting, Irrigation |
| Companies Covered | Mahindra & Mahindra Ltd., Yanmar Holdings Co. Ltd., Deere & Company, Monarch Tractor, CLAAS KGaA mbH, CNH Industrial N.V., Kubota Corporation, Solectrac, AGCO Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Farm Tractor Market Emerging Trajectories
Solid-state battery architectures and autonomous navigation stacks are converging to redefine tractor platform economics, shifting competitive advantage from mechanical engineering to software-defined powertrain control and predictive maintenance algorithms.
Lithium metal anode solid-state batteries are absorbing the thermal management burden that constrains liquid electrolyte systems in high-ambient-temperature field conditions. Large-scale grain operations in Australia's wheat belt are piloting these architectures for harvest-season endurance requirements. The technology is absorbing margin pressure from cooling system complexity while extending operational windows into previously prohibitive heat regimes.
The EU AI Act's risk classification framework for autonomous machinery imposes conformity assessment burdens on self-driving tractor platforms above 40 kW. OEMs must demonstrate algorithmic transparency and human oversight protocols to retain market access across the regulatory bloc. German and Dutch precision agriculture clusters are responding by consolidating software validation capabilities in-house rather than outsourcing to component suppliers.
Cooperative purchasing agreements among medium-scale growers are displacing individual capital expenditure decisions with pooled fleet access models. Specialty crop producers in California's Central Valley are aggregating demand through agricultural extension networks to negotiate standardized service contracts. This collective bargaining compresses pricing dispersion and forces OEMs to unbundle hardware from software maintenance revenues.
Electric Farm Tractor Market Segmentation
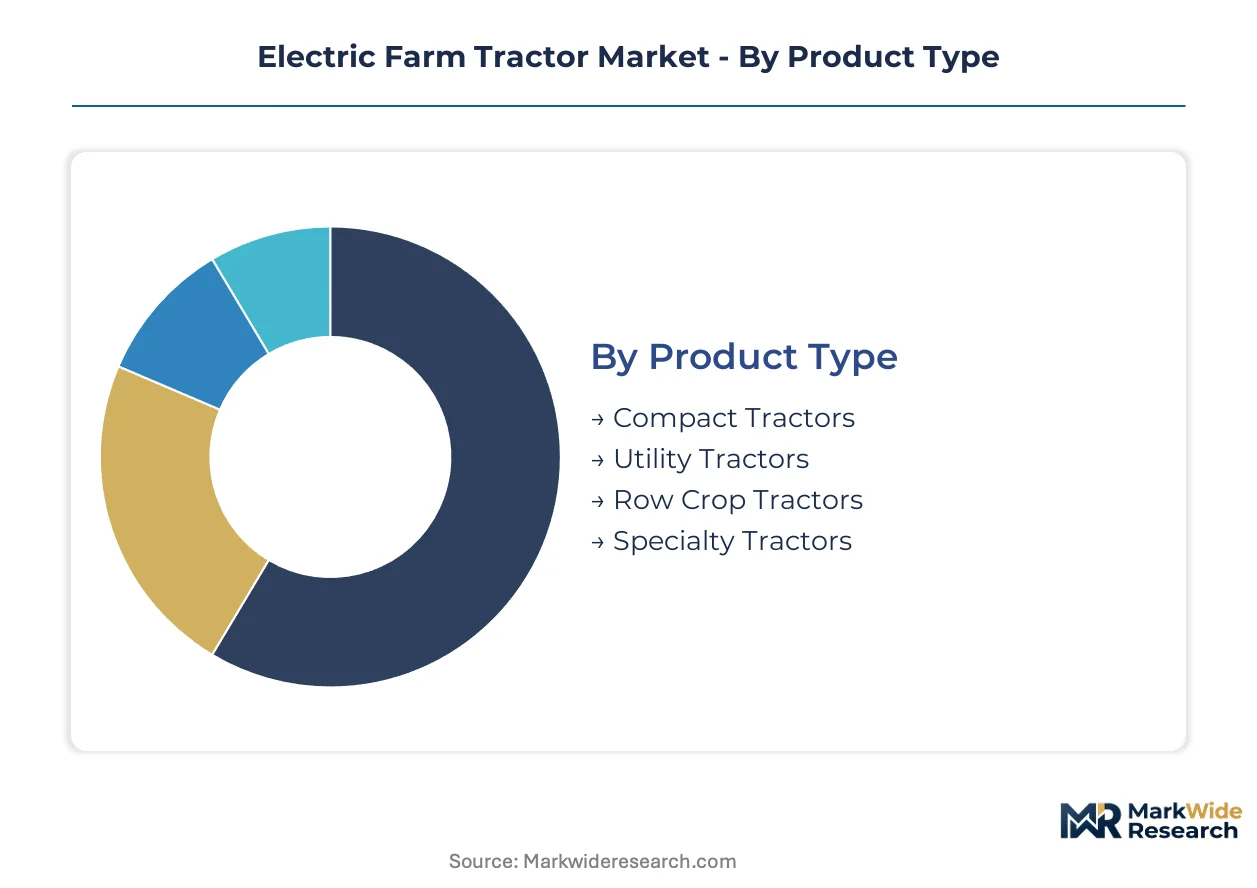
Segmentation in electric farm tractors reveals how powertrain specifications and operational intensity determine procurement budgets. Buyers sort across battery capacity thresholds and field duty cycles rather than traditional horsepower ratings alone.
Product Type:
Scale of operation and implement compatibility separate buyers in this category.
- Compact Tractors:These units operate below 50 kW continuous output with battery packs ranging 30-60 kWh, optimized for confined spaces and light tillage. Asian horticulture markets in Japan and South Korea concentrate procurement here, where terraced farming and greenhouse density favor maneuverability over raw power. India's PLI scheme for advanced chemistry cells is accelerating localized production for this segment.
- Utility Tractors:Vineyard and orchard operators in Germany's precision agriculture clusters drive specification requirements for narrow-track configurations with 60-100 kWh architectures. EU F-Gas Regulation compliance timelines pull forward fleet retirement decisions in these high-value specialty crop zones before full cost parity materializes.
- Row Crop Tractors:Battery scaling above 100 kWh creates technical barriers that concentrate margin pools in large-scale grain operations across Australia's wheat belt and Canada's prairie provinces.
- Specialty Tractors:Configured for steep-slope viticulture and rice paddy operations, these platforms integrate torque-vectoring for terrain stability in Japan's mountainous farming cooperatives.
Compact tractors lead volumes today; utility tractors are gaining share fastest.
End User:
Capital structure and fleet management sophistication determine technology absorption rates.
- Commercial Farmers:North American operations with balance sheet capacity deploy electrified units as compliance hedges against tightening EPA tailpipe standards, absorbing early-adopter premiums.
- Agricultural Cooperatives:California's Central Valley specialty crop producers aggregate demand through extension networks to negotiate standardized service contracts, compressing pricing dispersion.
- Smallholders:Equipment-as-a-service platforms bypass dealer networks for fragmented markets in India's Maharashtra and Gujarat states.
- Large-scale Enterprises:Rapid refueling requirements sustain hydrogen fuel cell R&D investment for harvest-season endurance in Australian grain operations.
Commercial farmers dominate current procurement; agricultural cooperatives show the steepest expansion trajectory.
Technology:
Energy density and refueling infrastructure availability shape powertrain selection.
- Battery Electric:Lithium iron phosphate architectures with thermal stability improvements reduce fire risk premiums for insurers covering large-scale German and Dutch operations. Solid-state battery pilots in Australia's wheat belt extend operational windows into high-ambient-temperature regimes previously prohibitive for liquid electrolyte systems.
- Hybrid Electric:Range-extender configurations bridge grid interconnection backlogs in rural US agricultural regions where fast-charging deployment lags.
- Hydrogen Fuel Cell:Rapid refueling protocols attract enterprise R&D for row crop operations requiring continuous seasonal runtime.
- Solar Powered:Supplementary panel integration reduces grid dependency for smallholder irrigation pumping in India's solar-rich western states.
Battery electric systems anchor installed base; hydrogen fuel cell variants climb the fastest in enterprise pilot programs.
Application:
Power demand profiles and seasonal intensity dictate battery sizing requirements.
- Tillage:High-torque, low-speed operations maximize regenerative braking capture and extend effective range per charge cycle in German precision agriculture clusters.
- Planting:Sub-inch accuracy requirements integrate torque-vectoring drivetrains with autonomous navigation stacks for seed placement optimization.
- Harvesting:Sustained high-power draw creates thermal management challenges that solid-state architectures are absorbing in Australian pilot deployments.
- Irrigation:Stationary pumping applications with predictable duty cycles suit solar-battery hybrid configurations in water-stressed Indian agricultural districts.
Tillage commands the largest installed base; planting applications show the most rapid technology integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's precision agriculture clusters absorb electrified fleet investments faster than Australia's wheat belt operations, where solid-state battery pilots address harvest-season thermal constraints.
United States
Commercial farmers in California's Central Valley and the Corn Belt deploy electrified units as compliance hedges against tightening EPA tailpipe standards. The Inflation Reduction Act's clean vehicle tax credits offset early-adopter premiums for large-scale operations. Iowa and Illinois grain cooperatives aggregate demand through extension networks to negotiate standardized service contracts with OEMs.
Germany
Vineyard operators in the Rhine Valley and Baden-Württemberg drive narrow-track utility tractor specifications with 60-100 kWh architectures. EU F-Gas Regulation compliance timelines pull forward fleet retirement decisions before full cost parity materializes. The EU AI Act's risk classification framework forces Munich and Stuttgart precision agriculture clusters to consolidate software validation capabilities in-house.
India
Smallholders in Maharashtra and Gujarat states access equipment-as-a-service platforms that bypass traditional dealer networks. The PLI scheme for advanced chemistry cell manufacturing redirects battery sourcing geography toward localized supply chains. Tamil Nadu's horticulture belt favors compact tractors below 50 kW for terraced farming and greenhouse density.
Australia
Large-scale grain operations across Western Australia's wheat belt pilot solid-state battery architectures for harvest-season endurance requirements. The technology extends operational windows into high-ambient-temperature regimes previously prohibitive for liquid electrolyte systems. Queensland irrigation districts deploy solar-battery hybrid configurations for stationary pumping applications.
Japan
Mountainous farming cooperatives in Nagano and Niigata prefectures integrate torque-vectoring specialty tractors for steep-slope viticulture and rice paddy stability. METI standards for agricultural machinery electrification shape domestic procurement specifications. Kansai region greenhouse operators concentrate demand for sub-50 kW compact platforms.
Electric Farm Tractor Market Vendor Landscape
Top-tier vendors anchor premium autonomous-ready platforms, while mid-tier specialists occupy vineyard and orchard configurations. The vendor base stratifies across three archetypes: legacy agricultural machinery conglomerates with precision software stacks, electric-native startups targeting specialty crop segments, and Asian manufacturers leveraging localized battery supply chains. Consolidation pressures intensify as autonomous implement convergence demands integrated hardware-software capabilities. Strategic moves concentrate on backward integration into battery cell sourcing and captive control over high-voltage service networks.
Within the legacy machinery tier, Deere & Company and CNH Industrial N.V. represent integrated platform providers combining mechanical engineering with software-defined powertrain control. Kubota Corporation anchors Asian market penetration through scale advantages in compact tractor segments. Monarch Tractor exemplifies the electric-native archetype targeting mid-tier utility configurations for high-value specialty crops.
| Leading Market Players |
|---|
| Mahindra & Mahindra Ltd. |
| Yanmar Holdings Co. Ltd. |
| Deere & Company |
| Monarch Tractor |
| CLAAS KGaA mbH |
| CNH Industrial N.V. |
| Kubota Corporation |
| Solectrac |
| AGCO Corporation |
| Others |
Supply Flow & Price Mechanics
Battery capacity bifurcation between sub-100 kWh utility configurations and 100+ kWh row crop platforms creates divergent margin structures that OEMs address through distinct supply chain footprints. Premium autonomous-ready tractors from Deere and CNH Industrial command hardware-software bundled pricing, while mid-tier vineyard specialists like Monarch Tractor compete on localized battery sourcing and stripped-down autonomy stacks.
Pricing Analysis
Capacity additions in China's lithium iron phosphate cell manufacturing are reshaping price floors for compact and utility tractor segments. Three-tier pricing structure across premium autonomous-ready, standard electric utility, and economy compact tiers separates buyers by software integration depth and battery warranty length. Cost compression in the standard tier intensifies because India's PLI scheme enables localized cell production that bypasses import duties. Agricultural cooperatives in California's Central Valley exhibit highest price sensitivity, while German precision agriculture clusters absorb premium positioning for EU F-Gas Regulation compliance.
Supply Chain Analysis
Dual-sourcing mandates from large-scale North American grain operations require OEMs to qualify battery cell suppliers across China, South Korea, and emerging Indian manufacturing under the PLI scheme. Cobalt and lithium refining capacity concentrates in the Democratic Republic of Congo and Chile, tethering cathode chemistry costs to geopolitical stability and ESG scrutiny. Single-source vulnerability in solid-state electrolyte materials constrains harvest-season deployment timelines for Australian wheat belt pilots. Distribution runs through traditional agricultural equipment dealer networks, though equipment-as-a-service platforms in India and California are disintermediating capital sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where procurement is shifting toward premium autonomous specifications that bundle precision agriculture software with torque-vectoring drivetrains.
For Market Incumbents: Anchor defensive positioning through backward integration into battery cell sourcing under India's PLI scheme and captive control over high-voltage service networks. Hydrogen fuel cell R&D investment from large-scale Australian grain enterprises threatens battery-electric dominance in row crop segments. ISO 18497 certification timelines create regulatory uncertainty that favors incumbents with in-house software validation capabilities in German precision agriculture clusters. For New Entrants and Emerging Players: Begin with specialty crop configurations in Germany's vineyard and orchard segments, where narrow-track utility tractors face less price pressure than commodity grain markets. California's Central Valley agricultural cooperatives aggregate demand through extension networks, creating pooled procurement entry points for equipment-as-a-service platforms. Direct-to-grower channels bypass entrenched dealer relationships and capture recurring software maintenance revenues from fragmented smallholder markets. For Investors and Strategic Acquirers: Consolidation pressure builds where autonomous implement convergence demands integrated hardware-software capabilities that mid-tier specialists cannot develop independently. Long-term viability over the next decade hinges on OEMs controlling battery recycling mandates and certification pathways for autonomous operation. Target acquisition profiles center on electric-native startups with validated vineyard configurations and established relationships with German precision agriculture clusters. The signal to watch is EU AI Act conformity assessment burdens that force software validation in-house rather than outsourced to component suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | PLI scheme incentives in India redirect cell sourcing geography toward localized manufacturing. |
| Autonomous Navigation Stack Development | EU AI Act risk classification forces Munich clusters to consolidate software validation capabilities. |
| High-Voltage Service Network Expansion | Rural technician scarcity in North American grain belts erodes customer confidence and extends downtime. |
| Equipment-as-a-Service Platform Launch | California Central Valley cooperatives aggregate demand through agricultural extension networks. |
| Solid-State Battery Pilot Program | Australian wheat belt operations test thermal management for harvest-season endurance requirements. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with OEM platform engineers, agricultural cooperative procurement leads, battery cell manufacturing executives, and precision agriculture software developers with secondary validation against SEC filings, EU regulatory databases, and customs trade data. Bottom-up tractor shipment modeling triangulated against top-down fleet electrification projections across the analysis window.
Segment-weighting approaches distributed value and volume across powertrain architecture, battery capacity tier, application intensity, and regional regulatory cluster. CAGRs derived from fitted growth curves incorporating technology adoption S-cycles and policy mandate timelines. Industry-specific forecast inputs included EPA tailpipe standard compliance deadlines and EU F-Gas Regulation phase-down schedules.
Several conditions sit outside the modeled scope, including breakthrough solid-state battery commercialization timelines and hydrogen fuel cell infrastructure buildout trajectories. Forecasts reflect documented assumptions about grid interconnection queue resolution and rural fast-charging deployment rates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Machinery
Compact Tractor Market
Agricultural Machinery
Germany Agricultural Machinery Market
Agricultural Machinery
Vietnam Agricultural Tractor Market
Agricultural Machinery
South America Agricultural Sprayers Market
Agricultural Machinery
China Agricultural Tractors Market
Agricultural Machinery
Cambodia Agricultural Machinery Market
Agricultural Machinery
Netherlands Hydrogen Powered Tractor Market
Agricultural Machinery
Agricultural Food Grade Rubber Conveyor Belt Market
Agricultural Machinery
Vietnam Combine Harvester Market
Agricultural Machinery
US Lawn Mowers Market
Agricultural Machinery
North America Agricultural Sprayers Market
Agricultural Machinery
Milking Robots Market
Agricultural Machinery
North America Plowing and Cultivating Machinery Market
Agricultural Machinery
Europe Agricultural Sprayer Market
Agricultural Machinery
Two-Wheeler Tractors Market
Agricultural Machinery
Crop Sprayers Market