
 Wheat Milling Machine Market | 2026-2036
Wheat Milling Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Wheat Milling Machine Market Analytics
Market Context
Modular equipment bundling is broadening buyer choice as wheat milling machine suppliers package stone mills with pneumatic separation units and automated control systems into integrated lines. Buhler Group leverages its vertical integration into optical sorting and digital process control to sustain premium positioning across industrial flour mill installations. Ocrim SpA anchors its competitive stance through specialized roller mill engineering for high-extraction applications, while Satake Corporation extends its geographic footprint with compact multi-functional mill designs tailored to emerging market bakeries.
Technical Definition and Structural Segments
A wheat milling machine is industrial equipment designed to grind wheat kernels into flour through mechanical compression, abrasion, or impact forces, with roller mills typically operating at differential speeds of 2.5:1 to 3:1 and throughput capacities ranging from 50 to 1,200 tons per day depending on configuration and sieve specification. Roller mill systems dominate commercial installations due to their precise particle size control and higher extraction rates, while automated milling technology captures expanding margin pools as flour mills retrofit legacy mechanical lines with sensor-driven process optimization. Stone mill configurations retain niche strength among artisanal bakeries and organic flour processors, though hammer mill demand concentrates in feed-grade and bran-processing applications where particle uniformity matters less than throughput volume.
Regulatory Framework
The European Union's F-Gas Regulation and CE marking requirements shape equipment design by mandating leak-tight pneumatic systems and energy efficiency disclosures for milling machinery sold within member states. India's BIS certification and Food Safety and Standards Authority of India guidelines enforce hygienic design standards and material contact safety for domestic flour processing equipment. Stakeholders must monitor evolving carbon border adjustment mechanisms and national grain reserve policies that could redirect capital toward localized milling infrastructure over export-oriented mega-mill complexes.
Market Dynamics
The wheat milling machine market is experiencing structural pressure from Europe's F-Gas Regulation, which mandates pneumatic system upgrades and accelerates capital redeployment toward low-emission milling infrastructure across industrial flour processing facilities.
Growth Catalysts
- India's Food Security Programs:Government-backed grain reserve expansion and subsidized commercial baking clusters sustain procurement volume for automated milling lines in Uttar Pradesh and Maharashtra.
- Pneumatic Separation Technology:Advances in air-classification systems enable higher extraction rates while reducing energy intensity in large-scale flour mill retrofits.
- Southeast Asia Bakery Automation:Commercial bakeries in Vietnam and Indonesia scale centralized milling capacity to serve fragmented retail bread distribution networks.
Market Restraints
- Steel and Bearing Input Volatility:Roller mill manufacturing depends on specialized alloy steel and precision bearings subject to supply chain price swings from East Asian foundries.
- CE Marking Compliance Burden:European machinery directive requirements extend certification timelines and raise engineering costs for pneumatic system redesigns.
- Hammer Mill Substitution in Feed Applications:Lower-cost impact milling technology captures bran-processing volume where particle uniformity requirements are minimal.
Strategic Opportunities
- Artisanal Stone Mill Revival:Organic flour processors and specialty bakeries in France and Italy drive demand for compact stone milling configurations with automated feed systems.
- India BIS Certification Gap:Domestic equipment suppliers lacking hygienic design accreditation face displacement as FSSAI enforcement tightens in commercial milling.
- Sensor-Driven Process Convergence:Integration of optical sorting with digital process control creates premium positioning for retrofit automation packages.
Industry Challenges
- Millwright and Automation Specialist Shortage:Roller mill maintenance and PLC programming expertise concentrates among aging technician pools in traditional milling regions.
- Legacy Mechanical Line Integration:Retrofitting pneumatic separation and sensor systems into pre-2010 milling infrastructure demands custom engineering and extended commissioning periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wheat Milling Machine Market |
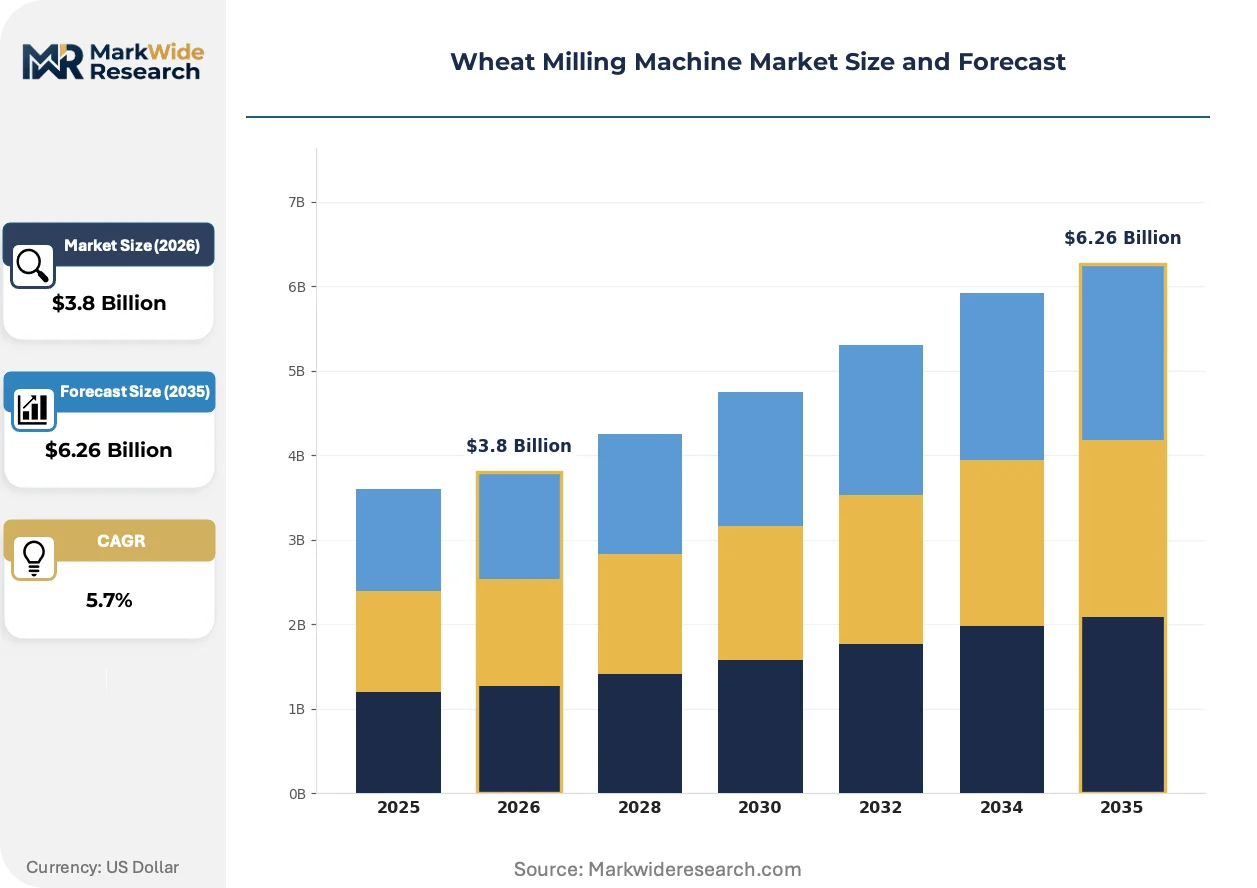
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stone Mill, Roller Mill, Hammer Mill, Multi-Functional Mill End User: Commercial Bakeries, Flour Mills, Home Users, Food Processing Plants Technology: Mechanical Milling, Pneumatic Milling, Magnetic Separation, Automated Milling Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | Buhler Group, Ocrim SpA, Satake Corporation, Alapala, Pavan Group, Golfetto Sangati, Henry Simon, Milltech, Pingle Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wheat Milling Machine Market Evolving Landscape
Digital process control and modular equipment architecture are compressing installation timelines and enabling capacity scaling without full line replacement in commercial flour milling operations.
Optical sorting technology is modularizing wheat milling workflows by embedding real-time kernel defect detection between cleaning and conditioning stages. Large-scale industrial mills in Germany and the United States adopt these systems to reduce manual inspection labor. The technology is modularizing quality control into discrete upgradeable units rather than monolithic line investments.
Europe's F-Gas Regulation is forcing leak-tight pneumatic system redesigns across roller mill installations sold within EU member states. Equipment suppliers must now certify hermetic sealing and disclose energy consumption metrics under CE marking requirements. Industrial flour mills in Poland and Spain accelerate procurement of compliant systems ahead of enforcement phase-ins.
After-sales service unbundling is fragmenting traditional maintenance contracts as mill operators seek component-specific technical support from third-party automation specialists. This pattern disrupts established supplier-captive service relationships in North American commercial baking clusters. The shift is most visible among mid-scale mills in the US Midwest pursuing flexible uptime guarantees independent of original equipment vendors.
Wheat Milling Machine Market Segmentation
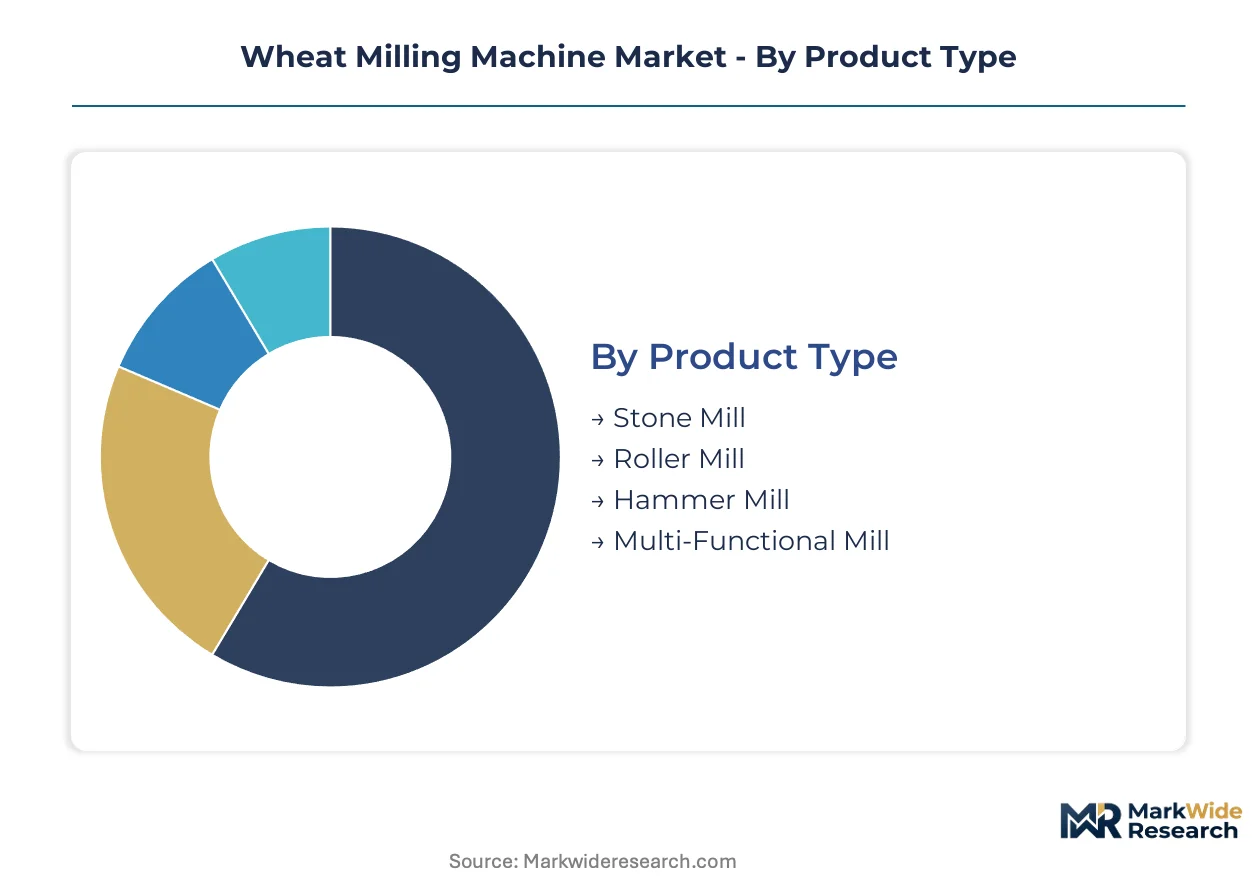
Equipment segmentation in wheat milling machinery reveals how technical specifications align with distinct operational scales and regulatory environments. Buyers select configurations based on extraction targets, energy constraints, and compliance burdens that vary sharply across artisanal, commercial, and industrial settings.
Product Type:
Supply concentration in precision roller mill manufacturing centers on German and Swiss engineering clusters, while stone mill production disperses across smaller regional fabricators.
- Roller Mill:Differential-speed compression systems operating at 2.5:1 to 3:1 ratios deliver precise particle size control for high-extraction flour production. Commercial flour mills in India and Vietnam prioritize these units for government-contracted grain processing volumes.
- Stone Mill:Abrasive grinding between stationary and rotating millstones preserves enzymatic activity preferred by organic flour processors. Artisanal bakeries in France and Italy drive procurement of compact automated feed configurations for specialty wheat varieties.
- Hammer Mill:Impact-force reduction suits bran processing and feed-grade applications where throughput outweighs uniformity requirements.
- Multi-Functional Mill:Modular designs integrate roller and stone elements for emerging market bakeries requiring operational flexibility.
Today's leader: Roller Mill. Tomorrow's challenger: Multi-Functional Mill.
End User:
Cost tier segmentation separates capital-intensive industrial installations from compact equipment serving fragmented retail baking networks.
- Flour Mills:Large-scale centralized facilities process 200 to 1,200 tons daily, deploying pneumatic separation and optical sorting for consistent extraction rates. India's FSSAI-mandated hygienic design standards are accelerating equipment replacement in Uttar Pradesh and Maharashtra commercial clusters.
- Commercial Bakeries:Mid-scale operations in Southeast Asia scale automated milling capacity to supply fragmented bread distribution networks in Vietnam and Indonesia.
- Food Processing Plants:Industrial ingredient manufacturers require certified equipment for gluten extraction and modified starch production.
- Home Users:Compact electric stone mills serve specialty baking enthusiasts in European and North American markets.
Volume concentrates in Flour Mills. Margin expansion concentrates in Commercial Bakeries.
Technology:
Application-driven technology selection reflects energy efficiency mandates and labor cost differentials across operating geographies.
- Automated Milling:Sensor-driven process control with PLC integration enables real-time extraction optimization and predictive maintenance scheduling. Retrofit demand from pre-2010 mechanical lines concentrates in Poland and Spain ahead of F-Gas Regulation enforcement.
- Pneumatic Milling:Air-classification systems reduce thermal damage while enabling higher throughput in large-scale installations. CE marking requirements for hermetic sealing extend engineering timelines for EU-bound equipment.
- Mechanical Milling:Legacy gear-driven systems dominate lower-capital installations in price-sensitive markets.
- Magnetic Separation:Ferrous contamination removal integrates into cleaning stages for food safety compliance.
Adoption is climbing the fastest in Automated Milling. Infrastructure constraints favor Pneumatic Milling in greenfield EU installations.
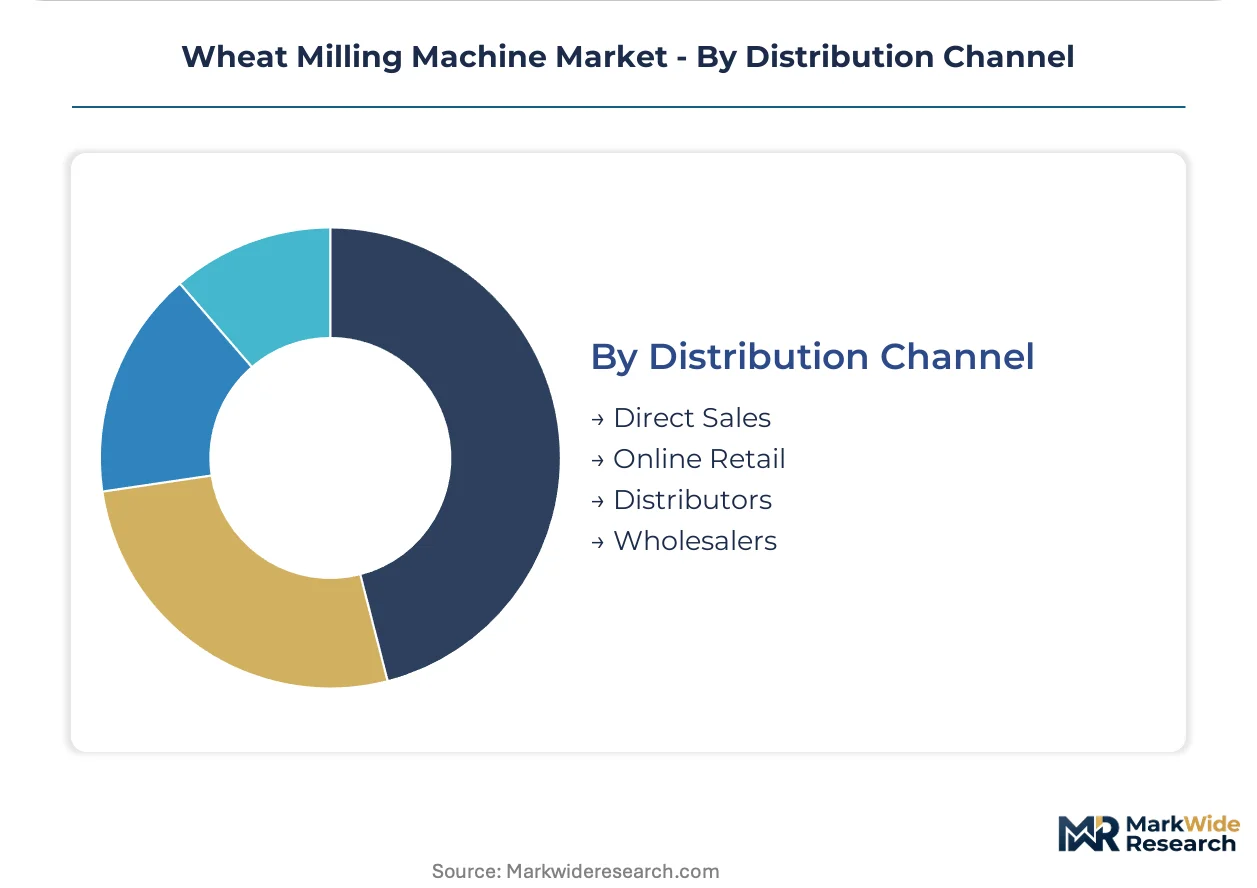
Distribution Channel:
Customer type and purchase scale determine channel selection, with direct relationships dominating industrial procurement and digital platforms capturing smaller equipment sales.
- Direct Sales:Manufacturer-led specification and commissioning for industrial flour mill projects exceeding 500-ton daily capacity. Buhler Group and Ocrim SpA maintain captive engineering teams for turnkey installation support.
- Distributors:Regional technical specialists provide localized maintenance and spare parts logistics for mid-scale commercial bakeries.
- Online Retail:Compact stone mills and home-use equipment move through specialized agricultural machinery platforms.
- Wholesalers:Bulk procurement aggregators serve equipment resellers in secondary markets with limited manufacturer presence.
Direct Sales commands industrial volume. Distributors are gaining share fastest in Southeast Asian bakery clusters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wheat milling machinery traces its industrial roots to 19th-century European engineering centers, where Swiss and German fabricators pioneered precision roller mill designs that remain foundational to modern extraction systems.
Germany
Industrial flour mills in North Rhine-Westphalia and Bavaria retrofit pneumatic separation systems to meet F-Gas Regulation leak-tightness mandates ahead of enforcement deadlines. CE marking requirements extend engineering timelines for hermetic sealing certifications. Equipment clusters around Stuttgart and Hamburg concentrate on sensor-driven process automation for large-scale milling operations.
India
Government food security programs and subsidized commercial baking clusters in Uttar Pradesh and Maharashtra sustain procurement volume for automated roller mill lines. FSSAI hygienic design standards and BIS certification requirements accelerate equipment replacement in domestic flour processing facilities. Mill fabricators in Ahmedabad and Pune scale production to serve expanding regional grain reserve infrastructure.
United States
Mid-scale commercial bakeries in the Midwest pursue flexible uptime guarantees independent of original equipment vendors through third-party automation specialists. FDA food safety compliance drives optical sorting integration between cleaning and conditioning stages. Milling equipment demand concentrates in Minnesota and Kansas grain processing corridors.
Italy
Artisanal stone mill configurations with automated feed systems gain traction among organic flour processors in Emilia-Romagna and Tuscany. France and Italy collectively drive European specialty wheat variety milling demand. Equipment suppliers in Bologna and Milan engineer compact designs for heritage grain applications.
Vietnam
Commercial bakeries scale centralized milling capacity to supply fragmented retail bread distribution networks across Ho Chi Minh City and Hanoi corridors. Southeast Asian bakery automation trends concentrate equipment procurement in Vietnamese and Indonesian urban clusters. Regional distributors gain market share through localized maintenance and spare parts logistics.
Wheat Milling Machine Market Competitive Landscape
Premium-margin players sit above commodity-margin players across engineering sophistication and after-sales service bundling in wheat milling machinery supply. The vendor base stratifies between integrated industrial solution providers and specialized component fabricators. Three archetypes dominate: full-line system integrators with captive automation capabilities, precision roller mill engineering specialists, and compact multi-functional mill designers targeting emerging market bakeries. Competitive dynamics center on backward integration into optical sorting and digital process control, alongside geographic expansion through regional distributor networks.
Among Swiss and German engineering conglomerates, Buhler Group occupies a position exemplifying integrated industrial solution architecture. Italian specialists Ocrim SpA and Pavan Group represent precision roller mill engineering archetypes with regional fabrication heritage. Japanese fabricator Satake Corporation anchors the compact multi-functional mill segment for emerging market applications. These three entities illustrate the geographic and technical stratification defining competitive positioning across industrial flour mill installations.
| Leading Market Players |
|---|
| Buhler Group |
| Ocrim SpA |
| Satake Corporation |
| Alapala |
| Pavan Group |
| Golfetto Sangati |
| Henry Simon |
| Milltech |
| Pingle Group |
| Others |
Value Network & Pricing Analysis
Specialized alloy steel and precision bearing costs cascade from East Asian foundries through three distinct pricing tiers, with pneumatic system complexity separating premium automated lines from mechanical configurations serving price-sensitive Indian grain reserve programs.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs wheat milling equipment procurement. Price differentiation separates CE-marked pneumatic systems with hermetic sealing from BIS-certified mechanical lines and uncertified compact units. Pricing pressure stems from hammer mill substitution in bran-processing applications where particle uniformity requirements relax. Commercial bakeries in Southeast Asia exhibit highest price sensitivity, while European industrial flour mills prioritize compliance-grade equipment despite premium positioning.
Supply Chain Analysis
Dual-sourcing requirements for precision roller mill components mandate qualification of German and Swiss engineering suppliers alongside Japanese fabricators for critical automation subsystems. Raw material dependencies center on specialized alloy steel from East Asian foundries, precision bearings from German manufacturing clusters, and optical sensor arrays from Japanese electronics suppliers. Supply chain risk concentrates in single-source vulnerability for high-precision roller assemblies. Distribution runs through manufacturer-direct relationships for industrial installations exceeding 500-ton capacity, with regional distributors capturing mid-scale commercial bakery procurement in Vietnam and Indonesia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in sensor-driven retrofit automation, where predictive maintenance bundling commands premium positioning against commodity mechanical lines.
For Market Incumbents: Hedge against hammer mill encroachment in feed-grade applications by deepening backward integration into optical sorting technology. Capture F-Gas Regulation compliance premiums through captive pneumatic system engineering in Stuttgart and Hamburg clusters. Prioritize aftermarket service unbundling defense against third-party automation specialists in US Midwest baking corridors. For New Entrants and Emerging Players: Direct-to-bakery digital channels enable specification bypass of established distributor networks in Vietnamese and Indonesian urban clusters. Target compact multi-functional mill white space serving emerging market bakeries requiring operational flexibility between roller and stone configurations. Pursue FSSAI hygienic design certification as mandatory entry credential for Uttar Pradesh and Maharashtra procurement programs. For Investors and Strategic Acquirers: Consolidation pressure builds where aging millwright expertise concentrates among technician pools in traditional European milling regions. Five-to-ten year viability favors acquisition targets with captive PLC programming capabilities and regional distributor footprints in Southeast Asia. Monitor BIS certification enforcement intensity as inflection indicator for domestic Indian equipment supplier displacement.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Optical Sorting | Captures premium retrofit demand from pre-2010 mechanical lines in Poland and Spain. |
| F-Gas Compliance Certification Investment | Unlocks hermetic pneumatic system procurement in North Rhine-Westphalia industrial clusters. |
| Regional Distributor Acquisition | Secures maintenance logistics for Vietnamese commercial bakery scaling corridors. |
| Sensor-Driven Process Control Launch | Enables real-time extraction optimization for India's FSSAI-mandated equipment replacement. |
| Artisanal Stone Mill Product Line Extension | Addresses organic flour processor demand in Emilia-Romagna heritage grain applications. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with flour mill engineering directors, commercial bakery procurement leads, aftermarket service heads, and pneumatic system specialists alongside secondary validation from BIS certification registries, FSSAI compliance disclosures, CE marking databases, and customs import records for milling machinery. Bottom-up equipment shipment tallies and top-down grain processing capacity estimates provided triangulation anchors.
Comparable-period anchoring tied projection models to historical installation data across the analysis window. Segmentation dimensions encompassed equipment type, end-user scale, technology tier, and geographic regulatory cluster. CAGRs derived from curve-fitting approaches applied to disclosed capacity additions and replacement cycles. Industry-specific forecast inputs included F-Gas Regulation enforcement phase-in schedules and India's grain reserve infrastructure buildout timelines.
The model assumes a particular technology adoption path; alternative pathways for pneumatic milling system penetration would alter the outlook substantially. Forecasts reflect assumptions regarding regulatory enforcement consistency and alloy steel price stability. Deviation in CE marking timeline acceleration or BIS certification stringency would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Machinery
Agricultural Tractor Market
Agricultural Machinery
Australia Agricultural Machinery Market
Agricultural Machinery
France Agricultural Machinery Market
Agricultural Machinery
Driverless Tractor Market
Agricultural Machinery
Agricultural Forestry Machinery Market
Agricultural Machinery
Autonomous Farm Equipment Market
Agricultural Machinery
Argentina Agricultural Machinery Market
Agricultural Machinery
Agriculture Drones Market
Agricultural Machinery
South America Agricultural Tractors Market
Agricultural Machinery
Orchard Type Tractors Market
Agricultural Machinery
Europe Agricultural Tractors Market
Agricultural Machinery
Milking Robots Market
Agricultural Machinery
Brazil Tractors Market
Agricultural Machinery
Power Tiller Market
Agricultural Machinery
United States Haying and Forage Machinery Market
Agricultural Machinery
North America Agricultural Tractors Machinery Market