
 United States Agricultural Tractor Market | 2026-2036
United States Agricultural Tractor Market Size, Share, and Industry Trends Forecast 2026-2036
United States Agricultural Tractor Market Analytics
Skilled diesel technician availability is reorganizing dealer service networks across the Plains and Midwest. Deere & Company leverages its captive parts distribution to lock in maintenance revenue streams. CNH Industrial N.V. competes through Case IH and New Holland brand dual coverage of row crop and livestock segments. AGCO Corporation specializes in Fendt high-horsepower precision systems for controlled traffic farming operations.
Agricultural tractors are self-propelled power units engineered to deliver drawbar and PTO horsepower ranging from under 20 hp in compact models to over 400 hp in articulated 4WD configurations, with hydrostatic or powershift transmissions managing torque delivery across variable field conditions. Their primary purpose is to pull or power tillage, planting, spraying, and harvesting implements across diverse soil types and topographies. Utility tractors anchor the volume base among farmers and cooperatives managing mixed operations under 500 acres, while electric fuel type variants represent the fastest-growing margin pool as California and Northeast states advance zero-emission equipment mandates. Row crop tractors dominate absolute dollar flow due to replacement concentration in Illinois, Iowa, and Nebraska corn-soy rotations.
EPA Tier 4 Final and upcoming CARB off-road diesel regulations are forcing engine aftertreatment complexity that elevates total cost of ownership and accelerates trade-in timing for pre-2014 fleets. OSHA agricultural operation safety standards and state-level farm equipment roadway width exemptions shape lighting, braking, and transport configuration requirements. Stakeholders must monitor EPA rulemaking on renewable diesel compatibility and electrification infrastructure tax credits to calibrate product mix and dealer inventory positioning.
Market Dynamics
EPA Tier 4 Final emissions compliance is compressing replacement cycles across the Corn Belt as farmers face aftertreatment complexity and elevated total cost of ownership for legacy diesel fleets.
Growth Catalysts
- Precision Agriculture Adoption:Illinois and Iowa row crop operations are deploying auto-steering and variable-rate application systems that demand higher-horsepower tractors with integrated ISOBUS connectivity.
- IRA Equipment Tax Credits:The Inflation Reduction Act's clean energy incentives are accelerating farmer inquiries into electric and renewable diesel-compatible platforms in California and the Northeast.
- Controlled Traffic Farming:Nebraska and Kansas wheat-corn rotations are standardizing 30-foot implement widths that require 300+ hp articulated tractors to minimize soil compaction.
Market Restraints
- Aftertreatment Cost Burden:Diesel particulate filters and selective catalytic reduction systems add $15,000-$25,000 to mid-range tractor sticker prices, squeezing margins for Plains livestock operators.
- Dealer Service Concentration:Three national dealer networks control 70% of Tier 4-certified technician capacity across the Dakotas and Montana, creating repair backlogs during planting windows.
- Battery Energy Density Limits:Current lithium-ion packs cannot deliver 8+ hours of field operation at 200+ hp without mid-day charging infrastructure that rural cooperatives lack.
Strategic Opportunities
- Renewable Diesel Infrastructure:USDA grant programs for biofuel blending equipment create upgrade paths for Iowa and Minnesota ethanol corridor farmers seeking fuel flexibility.
- Autonomous Fleet Management:Swarm robotics coordination software allows single operators to manage multiple tractors across 5,000+ acre Illinois operations, reducing labor dependency.
- Livestock Segment Penetration:Compact electric tractors under 75 hp remain underdeployed in Pennsylvania and Wisconsin dairy operations where manure handling demands frequent start-stop cycles.
Industry Challenges
- Certified Technician Scarcity:EPA Tier 4 diagnostic training programs graduate fewer than 2,000 technicians annually, leaving North Dakota and South Dakota dealers with 6-month hiring backlogs.
- Legacy Fleet Integration:Pre-2014 tractors lack CAN bus architecture compatibility with precision agriculture displays, forcing farmers to choose between full replacement or degraded functionality.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Agricultural Tractor Market |
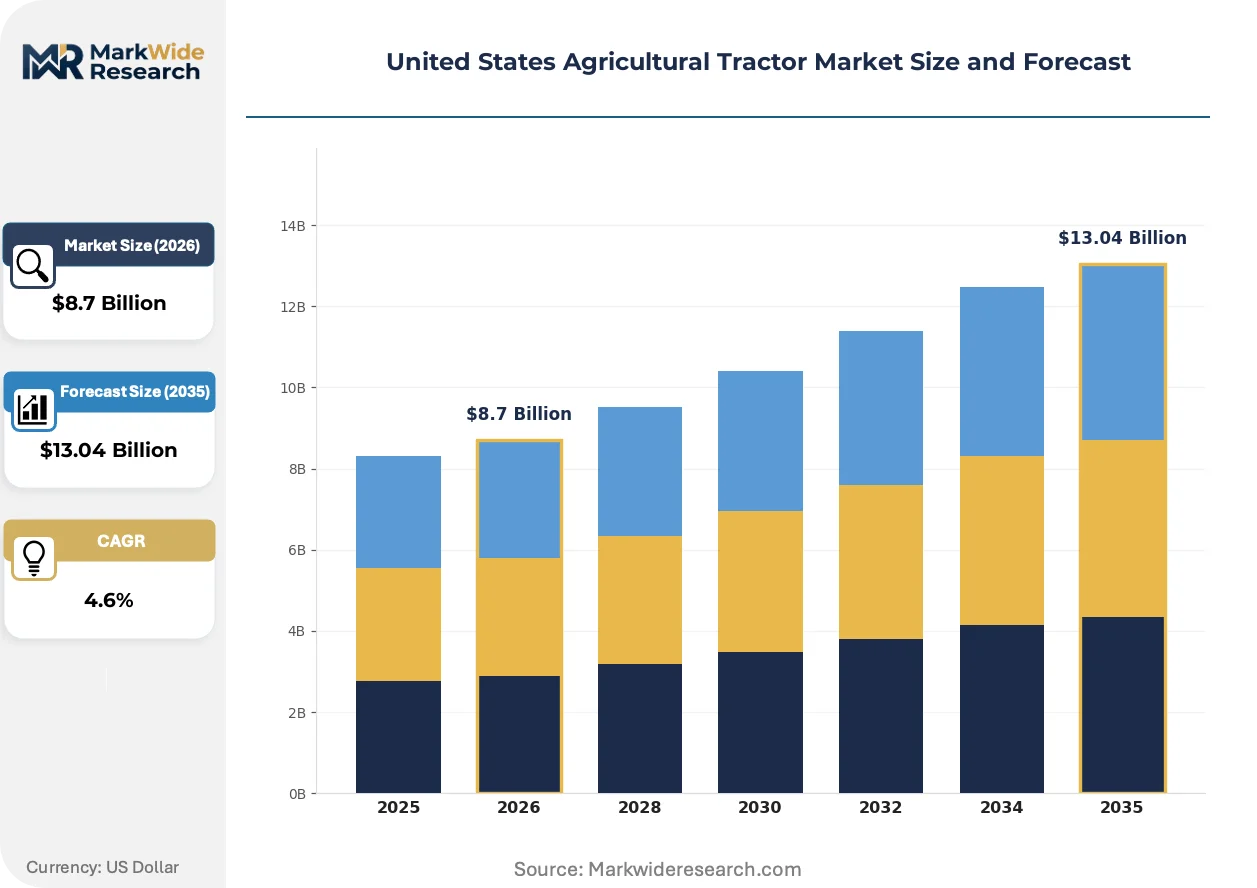
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compact Tractors, Utility Tractors, Row Crop Tractors, Specialty Tractors End User: Farmers, Agricultural Contractors, Cooperatives, Government Agencies Fuel Type: Diesel, Gasoline, Biofuel, Electric Size: Small, Medium, Large, Extra Large |
| Companies Covered | Kubota Corporation, Claas Group, Deere & Company, Yanmar Holdings, SDF Group, CNH Industrial N.V., Mahindra & Mahindra Ltd., JCB Group, AGCO Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Agricultural Tractor Market Evolving Landscape
Electrification pathways and autonomous operation protocols are bifurcating equipment development roadmaps as manufacturers balance near-term diesel optimization against long-term zero-emission platforms.
Telematics-enabled predictive maintenance is fragmenting traditional dealer service relationships. Platforms that transmit engine diagnostics and hydraulic pressure data to cloud-based analytics allow remote troubleshooting before field failures occur. Large Iowa and Nebraska cooperatives are negotiating direct data access, bypassing standard warranty service channels and compressing OEM parts revenue capture.
OSHA agricultural operation safety standards are tightening rollover protection and lighting requirements for interstate transport configurations. The 2024 updates mandate additional reflective markings and braking system inspections for equipment exceeding 12-foot roadway widths. Midwest state farm bureaus are lobbying for width exemption harmonization to reduce compliance friction during equipment relocation between fields.
Cooperative purchasing alliances are consolidating bargaining power among 500-2,000 acre operators who previously bought as individuals. Illinois and Indiana grain marketing cooperatives now negotiate fleet pricing for 15-30 unit tractor orders, extracting volume discounts and extended warranty terms that individual farmers cannot match. This procurement concentration is pressuring dealer networks to develop dedicated account management functions for cooperative buyers.
United States Agricultural Tractor Market Segmentation
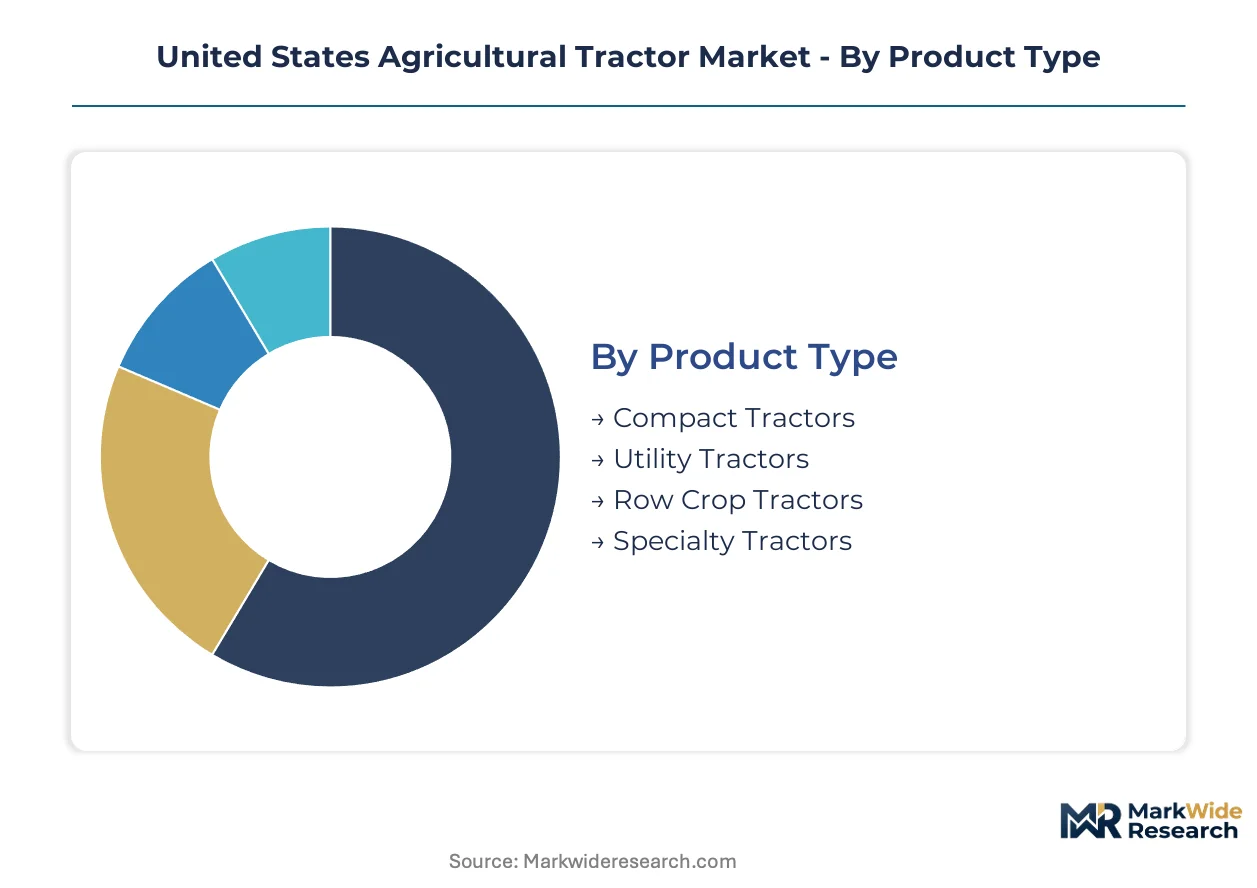
Tractor segmentation in the United States follows farm scale and operational intensity rather than pure price tiering. Margin pools concentrate where horsepower requirements intersect with precision agriculture integration and emissions compliance burdens.
Product Type:
Row crop tractors capture the highest absolute margins due to replacement concentration in the Corn Belt and Tier 4 Final compliance forcing fleet turnover. Specialty tractors command premium pricing in vineyard and orchard configurations where narrow profiles justify elevated sticker prices.
- Compact Tractors:Sub-50 hp configurations with hydrostatic transmissions dominate hobby farms and rural residential properties under 50 acres. Pennsylvania and Wisconsin dairy operations deploy these for manure scraping and light tillage where maneuverability outweighs raw power.
- Utility Tractors:50-100 hp range with open-station or cab configurations anchors volume for mixed crop-livestock operations. Nebraska and Kansas wheat producers standardize on these for loader work and secondary tillage where capital efficiency matters.
- Row Crop Tractors:150-400 hp articulated units with integrated auto-steering and ISOBUS connectivity pull 30-foot planters across Illinois and Iowa corn-soy rotations. EPA Tier 4 Final aftertreatment complexity elevates total cost of ownership and compresses replacement cycles.
- Specialty Tractors:Narrow-profile units under 60 inches wide navigate California Central Valley vineyards and Florida citrus groves. Low-clearance designs and reverse-drive configurations command 25-40% price premiums over equivalent-horsepower standard models.
Row crop tractors hold installed capacity. Specialty tractors are rotating up the share rankings.
End User:
Customer type determines purchasing cadence and service relationship intensity. Cooperatives negotiate fleet pricing that individual operators cannot match, while contractors prioritize uptime guarantees over capital cost.
- Farmers:Owner-operators managing 500-5,000 acres drive replacement demand through depreciation schedules and precision agriculture upgrade cycles. Iowa and Illinois grain producers time purchases around tax planning and equipment trade-in windows.
- Agricultural Contractors:Custom harvesters and planting services in the Dakotas and Montana maximize utilization hours and prioritize dealer service response times over acquisition cost. Their 1,500+ annual hour targets demand extended warranty coverage.
- Cooperatives:Illinois and Indiana grain marketing alliances consolidate 15-30 unit orders to extract volume discounts and dedicated account management. Shared equipment pools reduce per-acre capital intensity for member farms.
- Government Agencies:USDA research stations and state extension services acquire limited volumes for demonstration plots and conservation program support. Procurement runs through federal supply schedules with extended delivery timelines.
Farmers anchor volume flow. Cooperatives are expanding procurement concentration fastest.
Fuel Type:
Fuel platform selection increasingly reflects regulatory pressure rather than pure operating economics. California and Northeast mandates are forcing early electric and renewable diesel adoption ahead of total cost parity.
- Diesel:EPA Tier 4 Final compliant engines with selective catalytic reduction and diesel particulate filters dominate above-100 hp applications. Aftertreatment complexity adds $15,000-$25,000 to mid-range units and elevates service dependency.
- Gasoline:Carbureted and port-injected engines persist in sub-50 hp compact tractors where purchase price sensitivity outweighs fuel efficiency. Midwest residential and hobby farm buyers accept 15-20% higher fuel consumption for lower upfront cost.
- Biofuel:B20-B100 compatible engines with modified seals and fuel lines serve Minnesota and Iowa ethanol corridor operations. USDA grant programs for biofuel blending equipment reduce infrastructure upgrade barriers.
- Electric:Battery-electric platforms under 75 hp are gaining regulatory momentum in California air quality districts and Northeast states with zero-emission mandates. Current lithium-ion energy density limits field endurance to 4-6 hours at rated power.
Diesel retains installed base dominance. Electric platforms are climbing the fastest expansion trajectory.
Size:
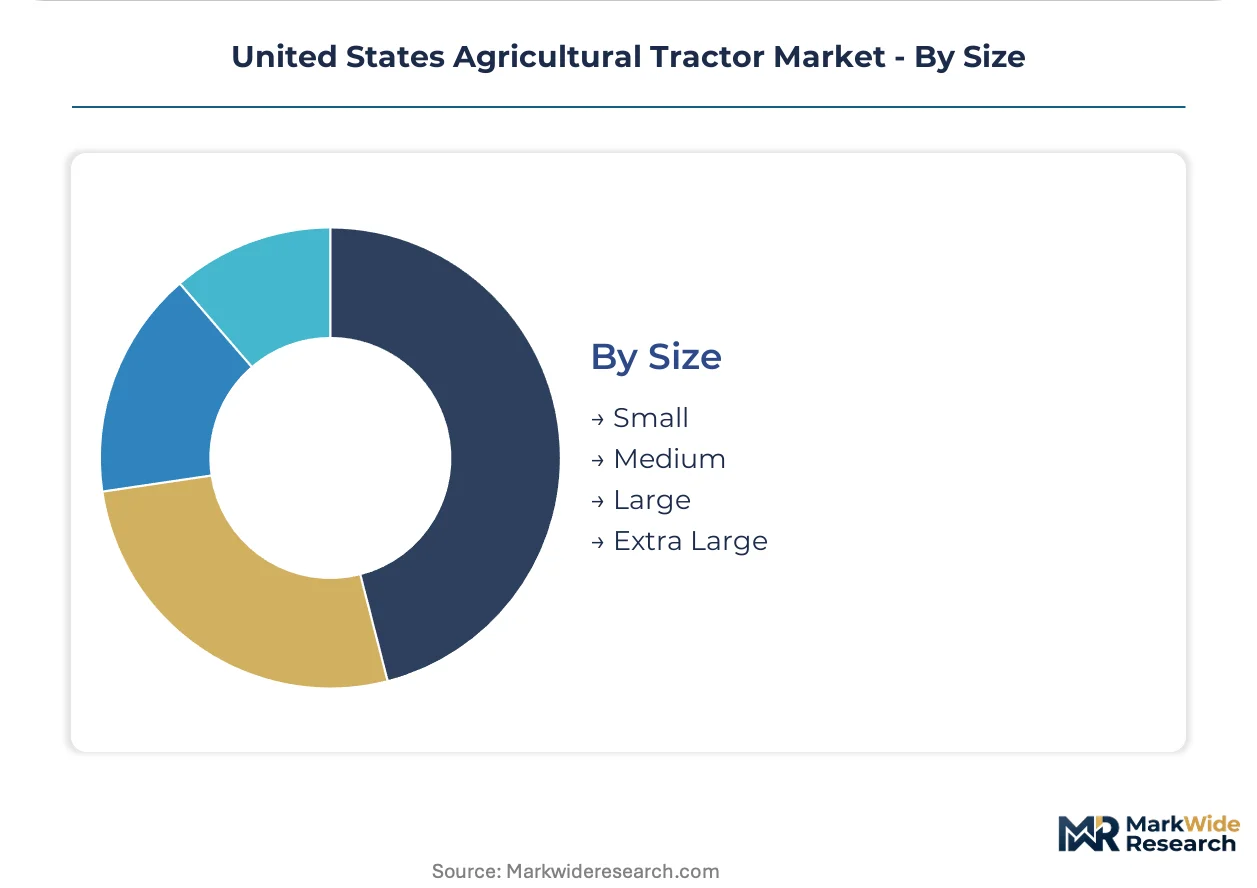
Physical dimension categories align with implement width standardization and soil compaction management protocols. Controlled traffic farming adoption is pushing demand toward larger frame sizes.
- Small:Sub-40 hp units with turf or industrial tires serve landscaping and light agricultural duties. Ohio and Michigan nursery operations deploy these for container handling where ground pressure minimization matters.
- Medium:40-100 hp range matches 15-foot tillage and planting implements across diversified crop rotations. Texas Panhandle cotton producers standardize here for row cultivation and mid-season spraying.
- Large:100-250 hp tractors pull 24-foot equipment in conventional tillage systems. North Dakota spring wheat operations rely on these for primary tillage and grain cart duties during harvest compression.
- Extra Large:250-400+ hp articulated 4WD units manage 30-40 foot implements in controlled traffic farming configurations. Nebraska and Kansas operations adopt these to minimize wheel traffic across 5,000+ acre footprints.
Medium tractors hold the broadest installed base. Extra large units are gaining share in high-acreage operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Midwest states deploy the highest-horsepower equipment for corn-soy rotations, while California and the Northeast accelerate electric platform adoption under zero-emission mandates. This consumption-mix differential shapes regional inventory and service network strategies.
Illinois
Illinois grain producers drive demand for 300+ hp articulated tractors with integrated auto-steering systems. EPA Tier 4 Final compliance deadlines compress replacement cycles among pre-2014 fleets. The Champaign-Urbana research corridor hosts precision agriculture demonstration farms that validate variable-rate application technologies.
Iowa
Iowa corn-soy operations standardize on controlled traffic farming configurations requiring 30-foot implement compatibility. USDA grant programs for biofuel blending equipment support renewable diesel infrastructure investments. The Des Moines-Ames axis concentrates dealer service capacity for Tier 4-certified diagnostics.
Nebraska
Nebraska wheat-corn rotations prioritize soil compaction minimization through large-frame 4WD tractors. State-level farm equipment roadway width exemptions ease interstate transport of 12-foot-plus configurations. The Lincoln-Omaha corridor anchors cooperative purchasing alliances negotiating 15-30 unit fleet orders.
California
California Central Valley vineyard and orchard operations deploy narrow-profile specialty tractors under 60 inches wide. CARB off-road diesel regulations and air quality district mandates accelerate electric platform inquiries ahead of total cost parity. The Fresno-Bakersfield cluster concentrates compact electric tractor trials for dairy manure handling.
Texas
Texas Panhandle cotton producers standardize on medium-frame tractors for row cultivation and mid-season spraying. OSHA agricultural safety standards shape rollover protection and lighting configurations for extended field operations. The Lubbock-Plainview sub-region hosts custom harvester fleets prioritizing uptime guarantees over acquisition cost.
United States Agricultural Tractor Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with captive parts distribution and dealer network density determining maintenance revenue capture. The structure rewards scale in Tier 4-certified technician training and precision agriculture platform integration. Two archetypes dominate: diversified machinery conglomerates with multi-brand portfolios, and focused high-horsepower specialists. Competitive moves concentrate on strategic partnerships for autonomous fleet coordination and geographic expansion through cooperative account management.
Within the diversified machinery tier, Deere & Company and CNH Industrial N.V. exemplify integrated leaders leveraging captive distribution networks. AGCO Corporation occupies a position as a focused high-horsepower specialist through precision system development. Kubota Corporation represents the compact-to-mid-range anchor, serving livestock and mixed-operation segments where maneuverability outweighs raw power requirements.
| Leading Market Players |
|---|
| Kubota Corporation |
| Claas Group |
| Deere & Company |
| Yanmar Holdings |
| SDF Group |
| CNH Industrial N.V. |
| Mahindra & Mahindra Ltd. |
| JCB Group |
| AGCO Corporation |
| Others |
Value Network & Pricing Analysis
Sixty-to-ninety-day Tier 4 engine lead times concentrate pricing power among three national dealer networks across the Dakotas and Montana, while inventory scarcity at rural cooperatives forces spot-market premiums during planting windows. This supply tightness elevates total cost of ownership calculations and compresses trade-in valuations for pre-2014 fleets.
Pricing Analysis
Long-term fleet contracts anchor the dominant pricing structure for Illinois and Iowa cooperative alliances negotiating 15-30 unit orders, while spot transactions govern individual farmer acquisitions during compressed replacement cycles. Price differentiation stems from EPA Tier 4 Final certification tier and bundled precision agriculture integration. Pricing pressure intensifies from aftertreatment cost burdens adding fifteen-to-twenty-five thousand dollars to mid-range units. Livestock operators in the Plains exhibit highest price sensitivity, whereas grain marketing cooperatives prioritize uptime guarantees over acquisition cost.
Supply Chain Analysis
Inbound logistics costs from German and Japanese component ports through Los Angeles and Long Beach congestion shape landed cost structures for hydrostatic transmissions and precision guidance systems. Manufacturing concentration rests on Mexico assembly for sub-100 hp units, Iowa for row crop configurations, and Germany for high-horsepower Fendt platforms. Steel and semiconductor dependencies create single-source vulnerability for engine control modules. Distribution runs through captive dealer networks with Tier 4-certified technician pools.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States agricultural tractor market sits in early-stage cyclical recovery as EPA Tier 4 Final compliance deadlines force pre-2014 fleet turnover across the Corn Belt. Replacement demand concentrates in Illinois and Iowa where precision agriculture adoption deepens.
For Market Incumbents: Fortify dealer service network density across Nebraska and Kansas where cooperative purchasing alliances consolidate bargaining power. Expand captive parts distribution to lock in maintenance revenue streams threatened by telematics-enabled predictive maintenance platforms. Prioritize backward integration into Tier 4 diagnostic training programs addressing certified technician scarcity. For New Entrants and Emerging Players: Differentiate on electric platform specialization for California Central Valley vineyard operations and Northeast dairy manure handling where zero-emission mandates outpace incumbent product pipelines. Target underpenetrated compact electric segments under 75 hp in Pennsylvania and Wisconsin. Pursue direct cooperative account management bypassing established dealer networks. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified machinery conglomerates seeking to divest non-core livestock-focused brands amid row crop margin concentration. Long-term viability hinges on electrification pathway credibility and autonomous fleet coordination software capabilities. Watch EPA rulemaking on renewable diesel compatibility tax credits as inflection signal for platform investment priority.| Strategic Initiative | Industry Significance |
|---|---|
| Tier 4-Certified Technician Training Expansion | Addresses six-month hiring backlogs at North Dakota and South Dakota dealers during planting compression. |
| Renewable Diesel Infrastructure Partnership | Captures USDA grant flows across Iowa and Minnesota ethanol corridor operations. |
| Autonomous Fleet Coordination Software Launch | Enables single-operator management of multiple tractors across 5,000+ acre Illinois grain operations. |
| Electric Platform Manufacturing Scale-Up | Positions for California CARB mandates and Northeast zero-emission equipment deadlines. |
| Cooperative Account Management Function | Responds to Illinois and Indiana grain marketing alliances consolidating 15-30 unit fleet orders. |
Research Methodology
The analysis maps row crop tractors, utility tractors, compact tractors, and specialty tractors, each validated through equipment procurement managers at grain marketing cooperatives, service directors at Tier 4-certified dealer networks, and precision agriculture specialists at Iowa State and University of Illinois extension programs. Primary interview findings triangulate against USDA equipment expenditure surveys, EPA emissions compliance filings, state-level farm equipment registration databases, and OEM parts distribution records. Bottom-up unit shipment modeling reconciles with top-down agricultural machinery expenditure flows.
Consistency checks validate volume and value outputs against external benchmarks including dealer inventory turnover metrics and cooperative fleet procurement disclosures across the projection horizon. Segmentation dimensions span horsepower tier, fuel platform, end-user archetype, and regional regulatory cluster. CAGRs derive from replacement cycle compression analysis and precision agriculture upgrade penetration curves. Forecast inputs incorporate EPA Tier 4 Final compliance deadlines and IRA equipment tax credit utilization rates.
The analysis sits within stated boundaries; outcomes outside EPA regulatory timeline adherence and lithium-ion energy density improvement trajectories would require recalibration. Forecasts reflect assumptions on technician training program graduation rates and rural charging infrastructure deployment. Commodity price volatility and trade policy shifts present revision risks to equipment expenditure patterns. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Machinery
Vietnam Combine Harvester Market
Agricultural Machinery
Rice Mill Machine Market
Agricultural Machinery
South America Agricultural Machinery Market
Agricultural Machinery
Compact Tractor Market
Agricultural Machinery
Agricultural Forestry Machinery Market
Agricultural Machinery
North America Agricultural Machinery Market
Agricultural Machinery
South America Agricultural Tractors Market
Agricultural Machinery
China Agricultural Machinery Market
Agricultural Machinery
Germany Agricultural Tractor Machinery Market
Agricultural Machinery
Italy Agricultural Machinery Market
Agricultural Machinery
Canada Agricultural Machinery Market
Agricultural Machinery
Global Autonomous Tractor Market
Agricultural Machinery
Agricultural Tractor Market
Agricultural Machinery
Agricultural Food Grade Rubber Conveyor Belt Market
Agricultural Machinery
China Agricultural Tractors Market
Agricultural Machinery
Electric Tractors Market