
 Germany Agricultural Tractor Machinery Market | 2026-2036
Germany Agricultural Tractor Machinery Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Agricultural Tractor Machinery Market Insights
Aftermarket service revenue is reconfiguring margin pools away from unit sales across the Germany Agricultural Tractor Machinery Market. CLAAS KGaA mbH leverages its domestic manufacturing footprint to control spare parts distribution and technical support networks. Deere & Company anchors its position through precision agriculture platforms that lock in recurring software and data-service subscriptions. AGCO Corporation differentiates via Fendt-branded high-horsepower systems that dominate contractor segments demanding maximum field efficiency.
Agricultural tractor machinery encompasses self-propelled vehicles engineered to deliver traction and power for agricultural implements, typically featuring diesel engines rated from 20 to over 600 horsepower, hydraulic three-point hitch systems, and power-take-off shafts operating at standardized 540 or 1000 rpm speeds. These machines serve as the foundational mobile power unit for tillage, planting, harvesting, and material handling operations across commercial farming enterprises. Four-wheel-drive tractors command the dominant product category due to soil compaction reduction requirements on heavy German clay soils, while compact tractors represent the fastest-growing segment as vineyard and specialty crop operators mechanize previously manual tasks. GPS guidance and precision farming technologies concentrate margin expansion potential, with autonomous driving systems emerging as the next capability frontier for large arable operations facing persistent labor constraints.
KBA enforces Stage V emissions certification for all new agricultural tractors sold in Germany, compelling manufacturers to invest in selective catalytic reduction and diesel particulate filter integration. The EU Green Deal and national Fertilizer Ordinance shape demand toward equipment compatible with reduced-input farming systems and variable-rate application technologies. Stakeholders must monitor evolving EU machinery safety standards and carbon-border adjustment mechanisms that could reshape import competitiveness for non-European suppliers.
Market Dynamics
Farm consolidation across eastern German states is compressing replacement cycles and concentrating purchasing power among large-scale arable cooperatives that demand higher-horsepower 4WD systems with integrated precision farming capabilities.
Growth Catalysts
- Stage V emissions mandates:KBA enforcement compels fleet renewal toward compliant powertrains, accelerating hardware turnover among commercial operators.
- Precision farming platforms:Variable-rate application technologies align with EU Green Deal Farm to Fork targets, creating pull-through for GPS-guided tractors in Lower Saxony.
- Eastern German consolidation:Saxony-Anhalt and Brandenburg cooperative mergers generate concentrated demand for 300+ horsepower 4WD equipment.
Market Restraints
- Powertrain cost inflation:Selective catalytic reduction and diesel particulate filter integration raises unit production costs by 15-20 percent, squeezing margin pools.
- Supply concentration risk:Hydraulic component sourcing depends on a narrow base of Tier 1 suppliers concentrated in southwestern Germany.
- Technical limitation:Battery energy density constraints block full electrification of high-horsepower tractor segments above 200 horsepower.
Strategic Opportunities
- Vineyard mechanization:Compact tractor penetration remains underdeveloped in Baden-Württemberg specialty wine regions, creating whitespace for sub-80 horsepower systems.
- Autonomous driving convergence:Lidar and computer vision integration enables operator-free field operations for large arable enterprises facing persistent labor constraints.
- Aftermarket service unbundling:Software and data-service subscriptions generate recurring revenue streams independent of unit sales cycles.
Industry Challenges
- Embedded systems engineering gap:German OEMs face acute shortages of automotive-grade software developers capable of certifying autonomous tractor platforms to EU machinery safety standards.
- Legacy fleet integration friction:Precision farming retrofits for pre-2015 tractors require proprietary CAN bus adapters that fragment data interoperability across mixed-brand operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Agricultural Tractor Machinery Market |
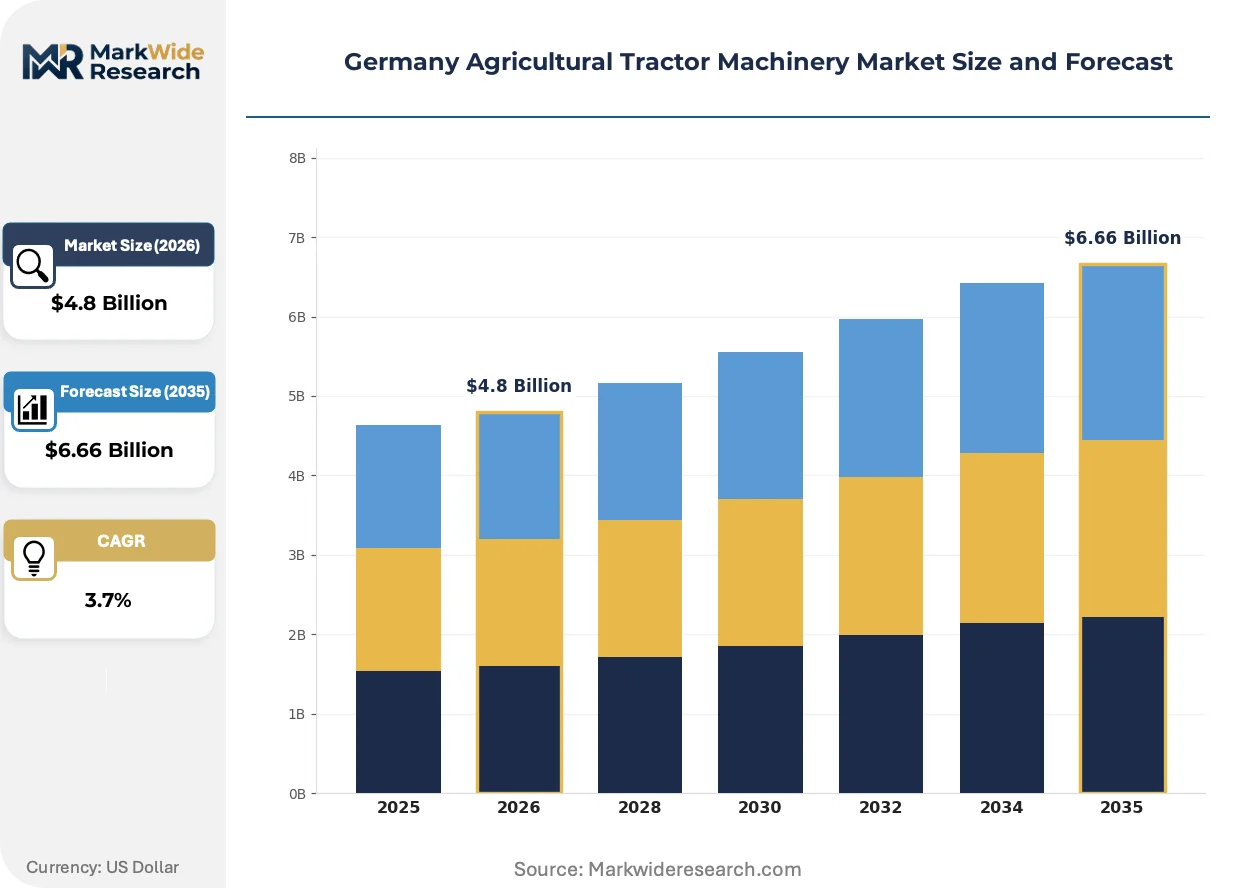
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.66 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 4WD Tractors, 2WD Tractors, Compact Tractors, Specialty Tractors Application: Crop Production, Livestock Farming, Forestry, Land Management End User: Farmers, Agricultural Co-operatives, Contractors, Government Agencies Technology: GPS Guidance, Precision Farming, Autonomous Driving, Telematics |
| Companies Covered | CLAAS KGaA mbH, Deere & Company, CNH Industrial NV, AGCO Corporation, Kubota Corporation, Yanmar Co, SAME Deutz-Fahr S.p.A., Mahindra & Mahindra Ltd., Agrale S.A., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Agricultural Tractor Machinery Market Trends and Innovations
Powertrain architecture and control systems are undergoing fundamental redesign as emissions compliance and labor scarcity force simultaneous evolution of hardware and software stacks.
Telematics-enabled predictive maintenance is migrating from premium contractor segments to mid-tier arable farms as connectivity hardware costs decline and dealer service networks consolidate diagnostic capabilities. Large cooperatives in Lower Saxony now expect remote engine monitoring and automated parts ordering as standard features. This shift compresses aftermarket revenue capture toward OEM-controlled digital platforms.
KBA Stage V certification requirements are tightening particulate matter and nitrogen oxide thresholds for all new agricultural tractors sold in Germany, forcing manufacturers to integrate selective catalytic reduction and diesel particulate filter systems as baseline equipment. The compliance burden falls heaviest on compact tractor producers serving price-sensitive vineyard and horticulture segments. Smaller OEMs are responding through shared powertrain development consortia to amortize certification costs.
Equipment procurement through operational lease structures is displacing outright purchase among eastern German cooperatives seeking to preserve balance sheet flexibility amid interest rate volatility. Dealer finance subsidiaries and captive leasing arms now capture margin pools previously held by traditional agricultural lenders. This transformation is most visible in Saxony and Brandenburg where consolidated farm enterprises prioritize cash flow predictability over asset ownership.
Germany Agricultural Tractor Machinery Market Segmentation
German tractor procurement patterns diverge sharply across operator scale and soil conditions. Equipment specifications track regional farm structures, with eastern cooperatives demanding high-horsepower systems while southwestern vineyards prioritize compact maneuverability. Technology adoption clusters geographically, concentrating precision farming investment in Lower Saxony arable belts.
Product Type:
Cost tier determines equipment specifications and margin structures across German tractor categories. Premium segments absorb emissions compliance investments while economy tiers face pricing pressure from Stage V mandates.
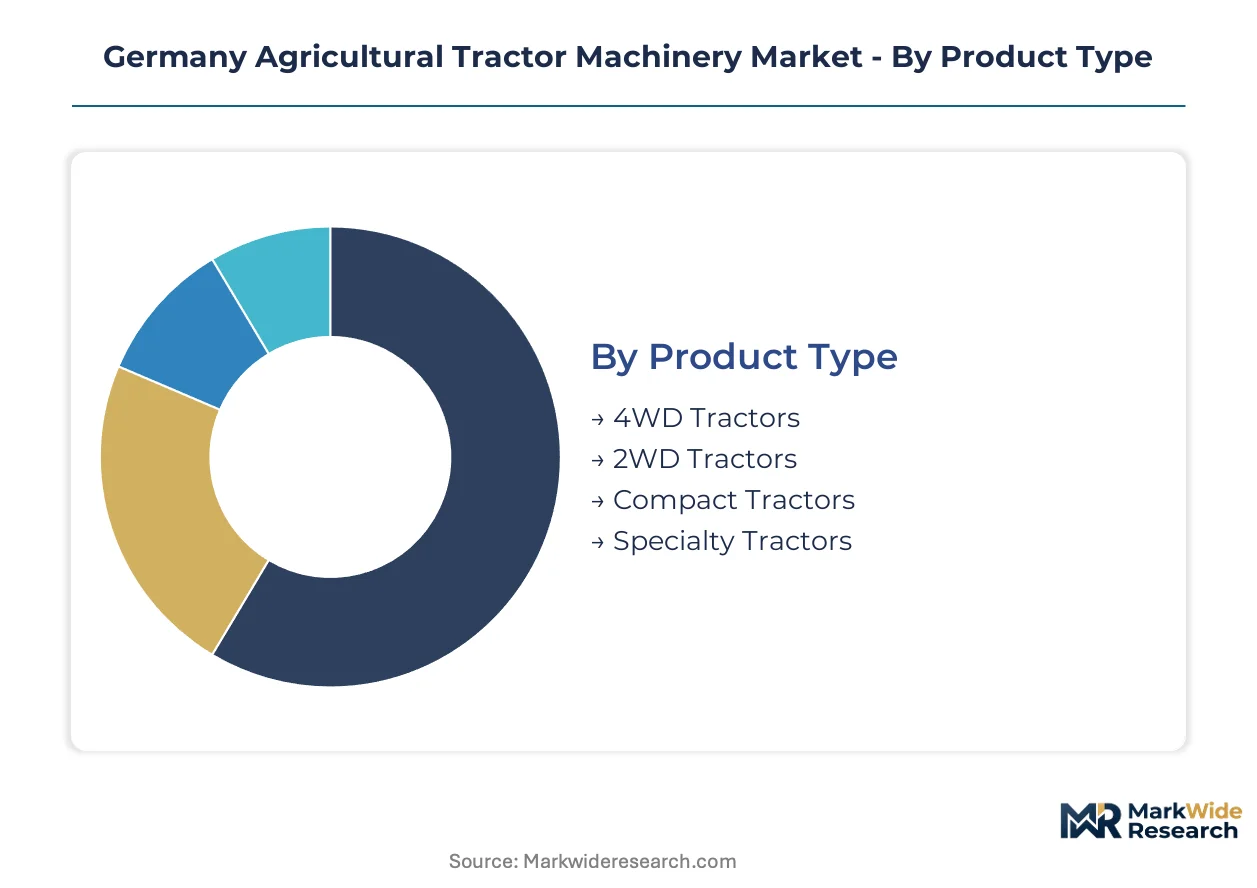
- 4WD Tractors:Four-wheel-drive systems integrate heavy-duty axles and torque-vectoring differentials rated from 150 to over 600 horsepower. Saxony-Anhalt and Brandenburg cooperatives concentrate procurement here, driven by soil compaction reduction requirements on heavy clay soils and the need to pull wide implement combinations across consolidated holdings.
- Compact Tractors:Sub-100 horsepower machines feature narrow profiles and tight turning radii engineered for vineyard rows and orchard alleys. Baden-Württemberg wine regions show concentrated uptake as labor scarcity forces mechanization of previously manual canopy management and harvest logistics.
- 2WD Tractors:Two-wheel-drive configurations serve specialized tillage and transport duties on level terrain with lower traction demands.
- Specialty Tractors:Articulated chassis and reversible operator platforms address steep-slope viticulture and municipal maintenance applications.
4WD Tractors hold installed capacity. Compact Tractors is rotating up the share rankings.
Application:
Application focus shapes hydraulic system specifications and three-point hitch configurations. Crop production demands high-flow hydraulics for implement control, while livestock operations prioritize front-loader integration and PTO versatility.
- Crop Production:Primary tillage, planting, and harvesting operations require tractors with 540/1000 rpm dual-speed PTO shafts and closed-center hydraulic systems delivering 100+ liters per minute flow rates. Lower Saxony arable belts concentrate demand, pulled by precision farming platform adoption for variable-rate seeding and fertilizer application.
- Livestock Farming:Material handling and feeding operations emphasize front-loader compatibility, cab visibility, and hydrostatic transmission for repetitive stop-start cycles. Bavarian dairy regions show concentrated investment as herd consolidation drives mechanized feed distribution and manure management.
- Forestry:Winch-equipped skidding configurations and reinforced undercarriages address timber extraction on steep terrain.
- Land Management:Municipal and conservation applications demand multi-purpose platforms with quick-attach systems for mowing, snow removal, and maintenance implements.
Crop Production dominates revenue contribution. Livestock Farming is climbing the fastest.
End User:
Customer type determines financing structures and service relationship intensity. Large cooperatives negotiate fleet pricing and embedded telematics, while individual farmers prioritize dealer proximity and parts availability.
- Agricultural Co-operatives:Consolidated eastern German enterprises operate 50+ unit fleets with centralized procurement and maintenance protocols. Saxony and Brandenburg cooperatives drive demand for 300+ horsepower 4WD systems with integrated precision agriculture subscriptions, prioritizing total cost of ownership metrics over upfront capital expenditure.
- Farmers:Family-owned operations across Lower Saxony and Bavaria select tractors based on implement compatibility and local dealer service networks. These buyers show fragmented brand loyalty, with replacement decisions influenced by trade-in valuations and seasonal financing terms.
- Contractors:Custom service providers require maximum field efficiency and rapid implement changeover capabilities.
- Government Agencies:Municipal and state procurement follows public tender regulations with extended warranty requirements.
Agricultural Co-operatives anchor volume concentration. Contractors is gaining share fastest.
Technology:
Technology tier separates price bands and creates recurring revenue attachment. Basic GPS guidance now ships standard, while autonomous systems remain premium contractor offerings.
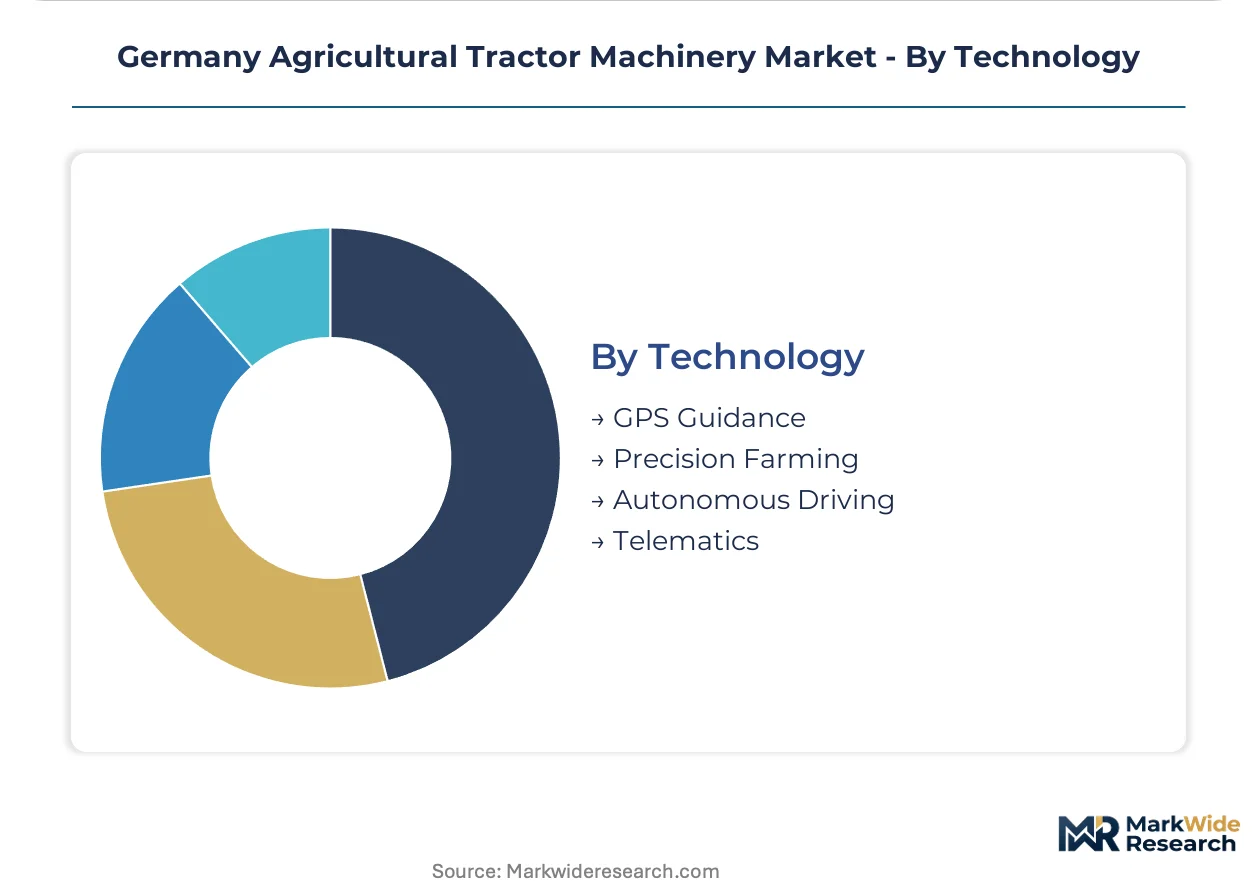
- Precision Farming:Variable-rate application systems integrate yield mapping, soil sensing, and prescription-based input control through ISOBUS-compatible displays. Lower Saxony large-scale arable operations concentrate adoption, compelled by EU Green Deal Farm to Fork targets for reduced fertilizer application and documented sustainability compliance.
- GPS Guidance:RTK-corrected auto-steering systems deliver sub-2.5 centimeter pass-to-pass accuracy for reduced overlap and input savings. These platforms have migrated from premium segments to mid-tier equipment as hardware costs declined and dealer installation networks standardized.
- Telematics:Remote engine monitoring and predictive maintenance alerts compress downtime for commercial operators.
- Autonomous Driving:Lidar and computer vision platforms enable operator-free field execution for labor-constrained enterprises.
GPS Guidance holds installed base leadership. Precision Farming is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across German tractor demand clusters. Eastern cooperatives prioritize total cost of ownership metrics, while southwestern vineyard operators remain acutely sensitive to upfront capital outlays.
Lower Saxony
Large-scale arable cooperatives drive precision farming adoption here, replacing equipment on compressed cycles. The EU Green Deal Farm to Fork strategy mandates documented fertilizer reduction, pulling GPS-guided variable-rate systems into standard procurement specifications. The Börde belt around Hanover concentrates 300+ horsepower 4WD deployments.
Saxony-Anhalt
Farm consolidation accelerates fleet standardization among merged cooperatives seeking operational uniformity. KBA Stage V emissions enforcement eliminates pre-2015 equipment from auction channels, forcing hardware turnover. The Magdeburg Börde region generates concentrated demand for high-horsepower systems pulling wide implement combinations.
Brandenburg
Operational lease structures displace outright purchase among consolidated enterprises prioritizing balance sheet flexibility. The national Fertilizer Ordinance shapes equipment specifications toward reduced-input compatibility. The Uckermark and Prignitz districts anchor eastern Germany's densest tractor replacement activity.
Baden-Württemberg
Vineyard mechanization lags arable adoption, creating whitespace for compact sub-80 horsepower systems in steep-slope viticulture. Stage V compliance costs burden price-sensitive specialty crop operators disproportionately. The Kaiserstuhl and Ortenau wine regions concentrate unmet demand for maneuverable narrow-profile equipment.
Bavaria
Livestock consolidation drives mechanized feed distribution and manure management investment across dairy regions. Front-loader compatibility and hydrostatic transmission specifications dominate procurement criteria. The Allgäu and Upper Bavaria districts concentrate mid-horsepower tractor deployment for mixed farming operations.
Germany Agricultural Tractor Machinery Market Competitive Landscape
Diversified agricultural equipment conglomerates and specialized tractor manufacturers split the market along capability and scale vectors. Consolidation pressure intensifies as emissions compliance investments favor entities with captive engineering resources and captive financing arms. Two archetypes dominate: integrated full-line suppliers controlling distribution and service networks, and focused tractor specialists leveraging manufacturing efficiency. Competitive moves cluster around precision agriculture platform integration and operational lease structure expansion.
Within the integrated supplier tier, CLAAS KGaA mbH and Deere & Company anchor positions through domestic manufacturing footprints and precision farming ecosystems. AGCO Corporation occupies a position exemplifying focused high-horsepower specialization. These three entities represent the structural poles around which mid-tier competitors and regional specialists organize their market presence.
| Leading Market Players |
|---|
| CLAAS KGaA mbH |
| Deere & Company |
| CNH Industrial NV |
| AGCO Corporation |
| Kubota Corporation |
| Yanmar Co |
| SAME Deutz-Fahr S.p.A. |
| Mahindra & Mahindra Ltd. |
| Agrale S.A. |
| Others |
Pricing and Supply Chain Analysis
Rhine-Main freight corridors carry hydraulic components from southwestern German Tier 1 clusters to eastern assembly plants, with transport cost volatility amplifying margin pressure on compact tractor producers already squeezed by KBA Stage V compliance investments. This logistics architecture concentrates pricing power among integrated OEMs controlling captive parts distribution while fragmenting margin pools for smaller manufacturers dependent on shared supplier networks.
Pricing Analysis
Aftermarket service contracts and telematics subscriptions now generate lifetime value multiples exceeding original equipment margins. Three-tier pricing structure across premium, standard, and economy levels separates Fendt-branded high-horsepower systems from mid-tier AGCO configurations and price-sensitive compact offerings. Cost compression in sub-100 horsepower segments is intensifying because Stage V catalytic reduction hardware adds fixed compliance burdens regardless of unit scale. Vineyard operators in Baden-Württemberg exhibit acute upfront price sensitivity, while eastern cooperatives prioritize total cost of ownership metrics including fuel efficiency and residual value.
Supply Chain Analysis
Tariff exposure between EU member states and third-country component sources dominates supply risk planning for German tractor assemblers. Manufacturing concentration rests on Germany, Italy, and France for complete powertrain integration, with hydraulic pumps and precision electronics drawing from specialized southwestern German suppliers. Single-source vulnerability concentrates in selective catalytic reduction substrate production. Distribution runs through captive dealer networks and consolidated agricultural finance subsidiaries displacing traditional lending channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Software and data-service subscriptions are expanding faster than hardware unit sales, transforming tractor procurement into a service-attach opportunity where recurring revenue streams decouple manufacturer fortunes from replacement cycles.
For Market Incumbents: Build switching-cost moats through precision agriculture platform integration that locks cooperatives into multi-year telemetry and variable-rate application subscriptions. Deepen backward integration into hydraulic component production to reduce southwestern supplier concentration risk. Secure embedded software engineering talent pools ahead of EU machinery safety standard evolution for autonomous certification.
For New Entrants and Emerging Players: Establish a beachhead in Baden-Württemberg vineyard mechanization where compact tractor penetration remains underdeveloped and incumbent service networks show geographic gaps. Target sub-80 horsepower narrow-profile systems compatible with steep-slope viticulture constraints. Pursue operational lease partnerships with eastern German dealer finance subsidiaries to bypass capital barrier for price-sensitive specialty crop operators.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underoptimized agricultural equipment divisions lacking precision farming software stacks. Long-term viability hinges on recurring revenue attachment rates rather than unit volume scale. Monitor KBA enforcement intensity on pre-2015 fleet retirement as inflection indicator for replacement cycle acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Agriculture Platform Integration | Locks eastern German cooperatives into multi-year telemetry subscriptions reducing churn risk. |
| Backward Integration into Hydraulics | Captures southwestern German component supplier margins and mitigates single-source vulnerability. |
| Operational Lease Structure Expansion | Aligns with Brandenburg cooperative preference for balance sheet flexibility over asset ownership. |
| Autonomous Driving Certification Investment | Addresses acute automotive-grade software developer scarcity ahead of EU machinery safety evolution. |
| Vineyard Mechanization Product Line Launch | Exploits whitespace in Baden-Württemberg steep-slope viticulture with sub-80 horsepower narrow-profile systems. |
Research Methodology
A spread of perspectives from agricultural cooperative procurement directors, OEM platform engineers, Tier 1 hydraulic component suppliers, and dealer service network managers converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation against KBA emissions certification databases, EU machinery safety directive filings, and consolidated agricultural enterprise financial disclosures. Bottom-up equipment shipment tracking and top-down macroeconomic modeling triangulated volume and value estimates.
Demand-supply-balance framing anchored the analytical approach across the analysis window, with segmentation modeled across horsepower tier, drivetrain configuration, technology attachment level, and regional farm structure. CAGRs were derived from replacement cycle compression patterns in eastern states and precision farming adoption curves in Lower Saxony. Forecast inputs incorporated KBA Stage V enforcement trajectory and EU Green Deal Farm to Fork compliance timelines.
Sensitivities concentrate around KBA regulatory enforcement intensity, battery energy density breakthroughs for high-horsepower electrification, and eastern German cooperative merger velocity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Machinery
Crop Sprayers Market
Agricultural Machinery
Europe Agricultural Irrigation Machinery Market
Agricultural Machinery
Garden Tractor Market
Agricultural Machinery
Australia Agricultural Machinery Market
Agricultural Machinery
US Lawn Mowers Market
Agricultural Machinery
Global Crop Harvesting Robots Market
Agricultural Machinery
Agricultural Electric Tractor Market
Agricultural Machinery
Vietnam Agricultural Tractor Market
Agricultural Machinery
Mexico Agricultural Machinery Market
Agricultural Machinery
Europe Agricultural Sprayer Market
Agricultural Machinery
United States Haying and Forage Machinery Market
Agricultural Machinery
North America Plowing and Cultivating Machinery Market
Agricultural Machinery
Rotary Tiller Market
Agricultural Machinery
North America Agricultural Machinery Market
Agricultural Machinery
Global Agricultural Sprayer Market
Agricultural Machinery
North America Agricultural Tractors Machinery Market