
 Age-Related Macular Degeneration Market | 2026-2036
Age-Related Macular Degeneration Market Size, Share, and Industry Trends Forecast 2026-2036
Age-Related Macular Degeneration Market Intelligence
Gene therapy and sustained-release implant platforms are narrowing the gap between chronic injection burdens and durable visual outcomes in neovascular AMD management. Regeneron Pharmaceuticals Inc. leverages its Eylea franchise to anchor North American retina practice patterns, while F. Hoffmann-La Roche Ltd competes through Port Delivery System innovations that reduce treatment frequency. Novartis AG specializes in geographic atrophy with complement inhibitor therapies, extending its ophthalmology footprint beyond anti-VEGF legacy markets.
Age-related macular degeneration constitutes a progressive retinal disorder characterized by photoreceptor degradation, drusen accumulation, and choroidal neovascularization, with diagnostic staging relying on optical coherence tomography central subfield thickness measurements and fluorescein angiography leakage patterns. Anti-VEGF agents dominate current therapeutic value, though photodynamic therapy retains niche utility in polypoidal choroidal vasculopathy subtypes where vascular morphology limits biologic response. Nutritional supplements represent a mature, margin-compressed segment anchored by the AREDS2 formulation, while intravitreal injection delivery mode commands the highest procedural reimbursement and facility fee structures across ophthalmology clinics and hospital outpatient departments.
The FDA's ophthalmic drug review division and the EMA's Committee for Medicinal Products for Human Use enforce divergent evidentiary standards for visual acuity endpoints, shaping trial design and market sequencing for developers. ISO 14155 clinical investigation standards and ICH E9 statistical principles govern multinational AMD therapy trials, with WHO International Classification of Diseases coding determining reimbursement eligibility in national health systems. Stakeholders must monitor complement pathway inhibitor readouts and biosimilar Eylea entry dynamics to anticipate portfolio repositioning requirements.
Market Dynamics
The AMD market pivots on sustained-release drug delivery platforms that compress treatment frequency from monthly to quarterly or longer intervals, fundamentally altering retina specialist practice economics and patient compliance calculus.
Growth Catalysts
- Accelerated Approval Pathways:The FDA's ophthalmic drug review division has streamlined visual acuity endpoint requirements, compressing development timelines for novel biologics targeting neovascular AMD subtypes.
- Medicare Reimbursement Structures:Facility fee differentials for hospital outpatient departments versus ambulatory surgical centers concentrate high-volume intravitreal procedures within integrated health systems.
- Complement Pathway Science:Advances in geographic atrophy pathophysiology have unlocked C3 and C5 inhibitor mechanisms, expanding addressable patient populations beyond anti-VEGF-responsive disease.
Market Restraints
- Input Cost Concentration:Recombinant protein production for anti-VEGF biologics depends on mammalian cell culture capacity concentrated in contract manufacturing organizations across Switzerland and Ireland.
- Technical Limitation:Posterior segment drug delivery faces biological barriers including vitreous clearance kinetics and retinal pigment epithelium penetration that limit sustained-release efficacy duration.
- Regulatory Friction:Divergent evidentiary standards between the FDA and EMA for visual acuity endpoints force duplicate clinical trial investments or sequential market entry strategies.
Strategic Opportunities
- Biosimilar Entry Dynamics:Patent expiry for reference anti-VEGF products creates white space for cost-competitive alternatives to capture price-sensitive segments within European national health systems.
- Gene Therapy Convergence:Adeno-associated viral vector platforms combined with sustained-release depot technologies promise functional cures that eliminate chronic injection burdens entirely.
- Diagnostic Integration:Artificial intelligence-enabled optical coherence tomography analysis streamlines treatment decision algorithms, creating channel control opportunities for platform-integrated device manufacturers.
Industry Challenges
- Specialized Injection Skill Gap:Safe intravitreal administration requires fellowship-trained retina specialists, creating bottlenecks as patient volumes expand faster than accredited training program output.
- Cold Chain Integrity Requirements:Biologic stability mandates temperature-controlled distribution infrastructure that strains last-mile logistics in emerging markets lacking specialized pharmaceutical handling capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Age-Related Macular Degeneration Market |
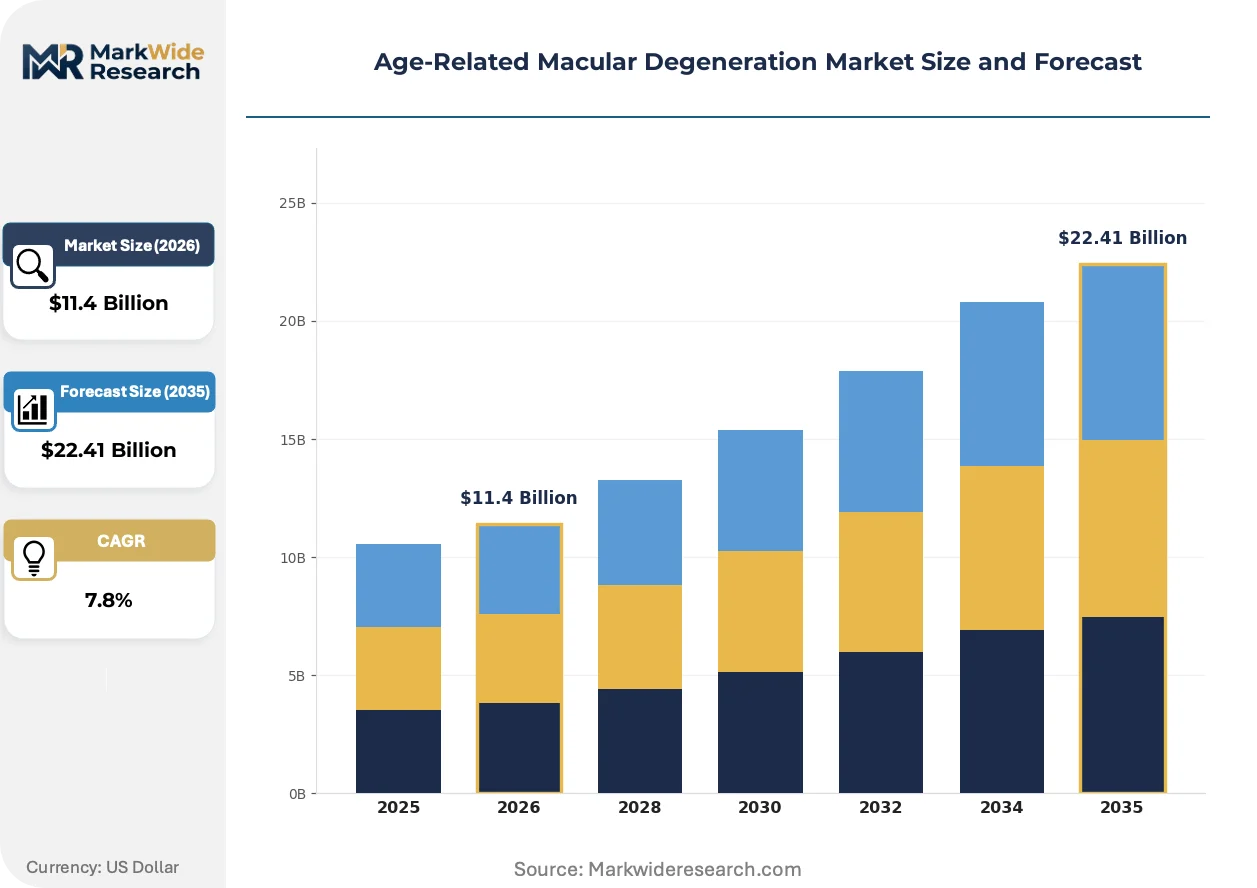
| Market Size in 2026 | $11.4 Billion |
| Market Size in 2035 | $22.41 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Anti-VEGF, Corticosteroids, Photodynamic Therapy, Nutritional Supplements End User: Hospitals, Ophthalmology Clinics, Homecare Settings, Research Institutes Treatment Stage: Early Stage, Intermediate Stage, Late Stage, Advanced Stage Delivery Mode: Intravitreal Injection, Oral, Topical, Laser Treatment |
| Companies Covered | Regeneron Pharmaceuticals Inc., F. Hoffmann-La Roche Ltd, Novartis AG, Bayer AG, Biogen Inc., Bausch Health Companies Inc., Apellis Pharmaceuticals Inc., Amgen Inc., Samsung Bioepis, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Age-Related Macular Degeneration Market Strategic Shifts & Innovations
Gene therapy vectors and sustained-release implants are converging to redefine therapeutic durability expectations, shifting competitive advantage from molecule potency to delivery platform engineering.
Sustained-release ocular implants incorporating polymeric degradation kinetics or refillable reservoir designs are rendering obsolete the chronic injection burden that has defined neovascular AMD management for two decades. Retina specialists in academic medical centers and large hospital systems are piloting these platforms to reduce clinic congestion and improve patient adherence. The structural consequence compresses practice revenue per patient while extending treatment intervals, forcing manufacturers to capture value through upfront device pricing rather than recurring drug sales.
The FDA's breakthrough therapy designation and regenerative medicine advanced therapy pathways have compressed review timelines for novel ophthalmic biologics, accelerating competitive entry against established anti-VEGF franchises. European regulators at EMA have maintained stricter visual acuity preservation standards, creating asynchronous market access that favors US-first launch strategies. Developers now sequence clinical programs to prioritize FDA approval, using US commercial traction to leverage European reimbursement negotiations.
Patient self-selection toward treatment-sparing alternatives is fragmenting the traditional monthly injection paradigm, with geographic atrophy patients particularly resistant to frequent clinic visits given their older age demographics and comorbidity burden. Specialty pharmacies and home health nursing services are capturing injection administration outside traditional retina practice settings, disintermediating specialist gatekeepers. This behavioral shift concentrates in the United States where Medicare Advantage plans experiment with value-based care models that reward reduced treatment frequency.
Age-Related Macular Degeneration Market Segmentation
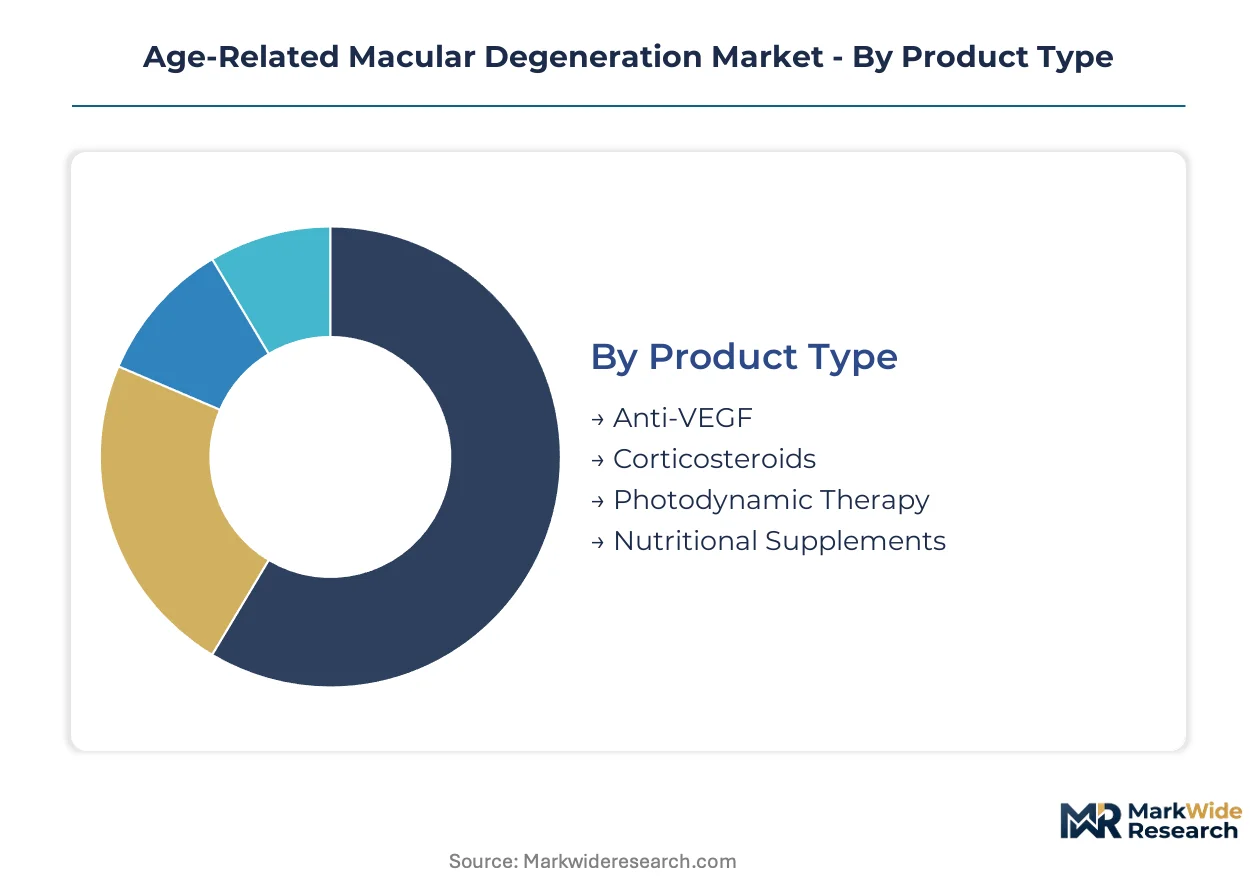
AMD therapeutic segmentation reveals distinct value capture mechanisms across intervention modalities and care settings. Product type stratification separates chronic maintenance therapies from curative-intent platforms, while delivery mode determines reimbursement tiering and specialist workforce requirements.
Product Type:
Cost tier stratification across AMD therapeutics separates premium biologics from commoditized supplements and legacy interventions.
- Anti-VEGF:Recombinant protein biologics targeting vascular endothelial growth factor signaling pathways. Demand concentrates in United States hospital outpatient departments where Medicare facility fees sustain high-volume intravitreal administration. The FDA's breakthrough therapy designation pathway accelerates novel agent entry against established franchises.
- Corticosteroids:Anti-inflammatory agents delivered via intravitreal or periocular routes for macular edema subtypes. European retina specialists in Germany and France favor these agents for pseudophakic patients where cataract progression risk diminishes.
- Photodynamic Therapy:Verteporfin-activated laser intervention for polypoidal choroidal vasculopathy.
- Nutritional Supplements:AREDS2-formulation antioxidants and minerals for intermediate dry AMD.
Anti-VEGF commands the established base. The steepest expansion runs through sustained-release formulations reducing injection frequency.
End User:
Customer type distribution across AMD care settings determines device procurement patterns and service revenue models.
- Hospitals:Integrated health systems with retina fellowship programs and surgical suites for complex cases. United States academic medical centers in Boston and Baltimore anchor clinical trial recruitment for novel biologics.
- Ophthalmology Clinics:Private practice and group settings handling routine anti-VEGF maintenance. Switzerland's Hirslanden Klinik and Germany's Helios Kliniken demonstrate European consolidation into multi-site retina networks.
- Homecare Settings:Specialty pharmacy and visiting nurse administration for mobility-limited patients.
- Research Institutes:NIH-funded centers and university hospitals conducting natural history studies and gene therapy trials.
Hospitals retain the procedural volume anchor. Homecare settings gain share fastest among Medicare Advantage populations.
Treatment Stage:
Disease severity stratification governs reimbursement eligibility and therapeutic intensity across AMD progression.
- Early Stage:Asymptomatic or mild visual impairment with drusen accumulation. Observation and nutritional supplementation dominate in United States community practice.
- Intermediate Stage:Significant drusen or pigmentary changes with preserved acuity. Complement inhibitor trials target this population before geographic atrophy develops.
- Late Stage:Neovascular conversion or extensive geographic atrophy. Anti-VEGF and emerging gene therapies concentrate clinical investment here.
- Advanced Stage:Bilateral severe vision loss with limited therapeutic options. Low-vision rehabilitation services capture residual value.
Late stage commands the established base. Intermediate stage represents the fastest-growing addressable population as diagnostic screening expands.
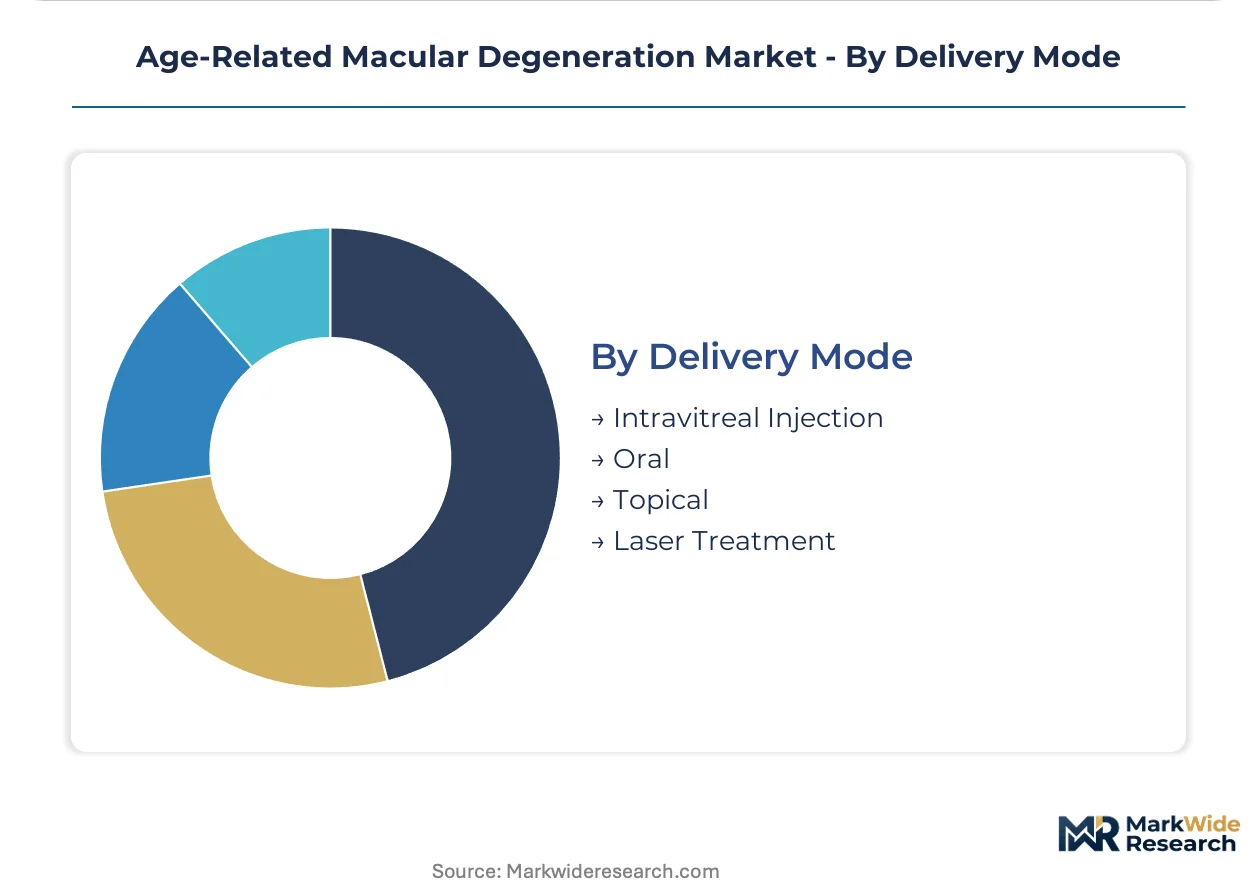
Delivery Mode:
Route of administration determines manufacturing complexity, cold chain requirements, and specialist workforce utilization.
- Intravitreal Injection:Direct vitreous cavity delivery of biologics via 30-gauge needle. Retina specialist concentration in United States metropolitan markets creates access bottlenecks as patient volumes rise.
- Oral:Systemic complement inhibitors and anti-angiogenic agents in development. Novartis and Roche oral C5 inhibitor programs target geographic atrophy with reduced injection burden.
- Topical:Eye drop formulations for anterior segment penetration with limited posterior segment efficacy.
- Laser Treatment:Photocoagulation and photodynamic modalities for selected vascular subtypes.
Intravitreal injection commands the established base. Oral delivery climbs the fastest as pharmaceutical developers pursue treatment-sparing alternatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Swiss pharmaceutical exports supply anti-VEGF biologics to hospital systems across Germany and France, while contract manufacturing organizations in Ireland feed mammalian cell culture capacity for United States market entry.
United States
Medicare facility fee structures for hospital outpatient departments sustain high-volume intravitreal injection procedures. The FDA's breakthrough therapy designation pathway compresses review timelines for novel ophthalmic biologics. Retina specialist concentration in Boston and Baltimore anchors clinical trial recruitment for sustained-release implant platforms.
Germany
Helios Kliniken and other multi-site retina networks consolidate patient volumes into centralized injection centers. The EMA's Committee for Medicinal Products for Human Use maintains stricter visual acuity preservation standards than FDA counterparts. Heidelberg's university hospital system pilots artificial intelligence-enabled optical coherence tomography analysis for treatment decision algorithms.
Switzerland
Hirslanden Klinik demonstrates European consolidation into premium ophthalmology service networks. Swissmedic enforces ISO 14155 clinical investigation standards for multinational AMD therapy trials. Basel's pharmaceutical cluster houses contract manufacturing organizations supplying recombinant protein production for anti-VEGF biologics.
Japan
PMDA accelerated approval pathways for regenerative medicine advanced therapies attract gene therapy developers. METI funding supports adeno-associated viral vector manufacturing infrastructure for domestic clinical programs. Tokyo's university hospitals lead natural history studies for geographic atrophy progression modeling.
United Kingdom
NHS England's specialized commissioning frameworks determine reimbursement eligibility for complement inhibitor therapies. The MHRA operates post-Brexit divergence from EMA evidentiary standards for visual acuity endpoints. London's Moorfields Eye Hospital anchors European clinical trial recruitment for novel biologics targeting neovascular subtypes.
Age-Related Macular Degeneration Market Key Industry Players
Channel-controlling players compete with product-specialist players across three structural tiers. Large-cap biopharmaceuticals with established retina franchises leverage Eylea-scale brand recognition and Medicare reimbursement relationships to defend position. Mid-tier specialists concentrate on sustained-release delivery engineering or complement pathway science. Emerging gene therapy platforms occupy pre-commercial development stages. Dominant competitive moves include biosimilar entry preparation and diagnostic integration partnerships.
Among North American biopharmaceuticals, Regeneron Pharmaceuticals Inc. and Apellis Pharmaceuticals Inc. exemplify contrasting archetypes. Regeneron occupies a position as the channel-controlling incumbent with established retina specialist relationships. Apellis represents the specialist tier focused on geographic atrophy through complement inhibition mechanisms. F. Hoffmann-La Roche Ltd anchors European-based competition through Port Delivery System innovations.
| Leading Market Players |
|---|
| Regeneron Pharmaceuticals Inc. |
| F. Hoffmann-La Roche Ltd |
| Novartis AG |
| Bayer AG |
| Biogen Inc. |
| Bausch Health Companies Inc. |
| Apellis Pharmaceuticals Inc. |
| Amgen Inc. |
| Samsung Bioepis |
| Others |
Cost & Logistics Intelligence
Basel's contract manufacturing cluster controls mammalian cell culture capacity for anti-VEGF biologics, concentrating upstream leverage among Swiss and Irish production sites that feed downstream pricing power to pharmaceutical developers serving United States hospital outpatient departments.
Pricing Analysis
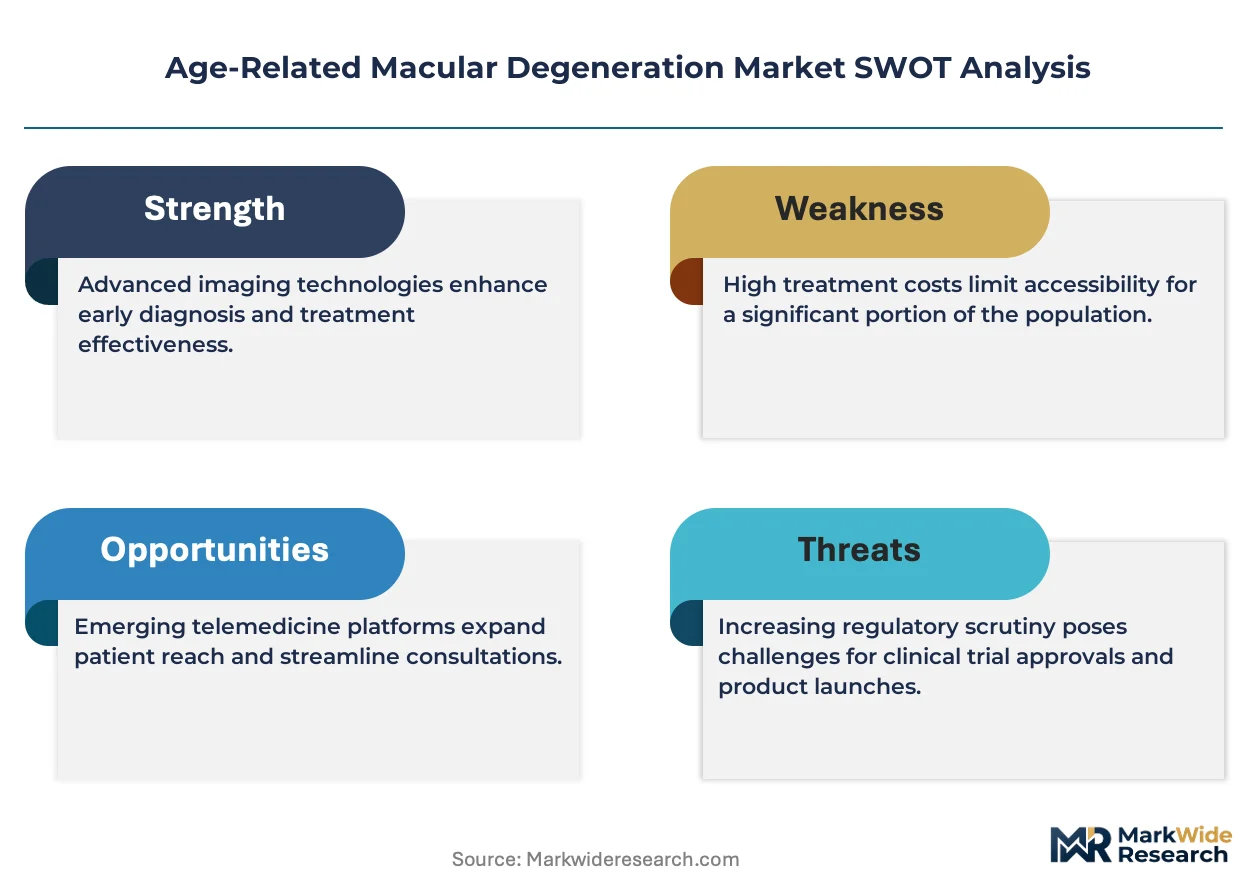
Prior-generation intravitreal injections, current sustained-release implants, and next-generation gene therapy platforms occupy distinct pricing tiers in AMD therapeutics. A three-tier pricing structure across premium biologics, standard anti-VEGF agents, and economy nutritional supplements dominates, with differentiation driven by treatment durability and Medicare reimbursement tier. Pricing pressure stems from biosimilar entry preparation as patent cliffs approach for reference products. Medicare Advantage plans exhibit highest price sensitivity through value-based care experiments, while academic medical centers remain least sensitive due to research funding insulation.
Supply Chain Analysis
Extended payment terms from Swiss and Irish contract manufacturing organizations to pharmaceutical developers strain working capital across the AMD biologics supply chain. Manufacturing concentrates in Switzerland, Ireland, and the United States, with recombinant protein production drawing from Chinese-sourced raw materials, German-engineered bioreactor systems, and Singapore-based filtration technologies. Single-source vulnerability in mammalian cell culture capacity creates structural risk. Distribution runs through cold chain logistics networks terminating at hospital outpatient departments and specialty pharmacy channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
AMD therapeutic fragmentation accelerates as patient self-selection toward treatment-sparing alternatives creates distinct niches for sustained-release platforms, oral complement inhibitors, and homecare administration models.
For Market Incumbents: Pre-empt biosimilar erosion by anchoring retina specialist relationships through sustained-release implant platforms that reduce clinic burden. Capture backward integration into refillable reservoir manufacturing to control device economics. Fortify formulary position against oral C5 inhibitor threats from complement pathway specialists by emphasizing visual acuity preservation data.
For New Entrants and Emerging Players: Build out geographic atrophy-focused portfolios targeting intermediate-stage patients before neovascular conversion, the most penetrable population with unmet need. Exploit European national health system price sensitivity through cost-competitive positioning. Pursue hospital system partnership channels that bypass established retina specialist gatekeepers through artificial intelligence-enabled diagnostic integration.
For Investors and Strategic Acquirers: Long-term, this sits as a platform-convergence play because delivery engineering expertise will displace molecular potency as the primary value driver. Target acquisition candidates with proprietary depot technologies or adeno-associated viral vector manufacturing capabilities. Monitor FDA breakthrough therapy designation awards as inflection signals for competitive repositioning requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | EMA's stricter visual acuity standards force duplicate investment or sequential market entry sequencing. |
| Regulatory Approval Pathway | FDA breakthrough therapy designation compresses review timelines for novel ophthalmic biologics. |
| Manufacturing Scale-Up | Mammalian cell culture capacity expansion in Basel and Dublin addresses recombinant protein bottlenecks. |
| Pipeline Diversification | Complement inhibitor programs extend addressable populations beyond anti-VEGF-responsive disease. |
| Strategic Partnership | Diagnostic integration with artificial intelligence-enabled OCT analysis creates channel control opportunities. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers; and secondary validation through FDA filings, EMA submissions, ClinicalTrials.gov records, and Medicare reimbursement databases. Bottom-up patient volume modeling and top-down pharmaceutical revenue triangulation anchored market sizing.
Forecast inputs span treatment stage progression, delivery mode substitution dynamics, and regional regulatory cluster adoption patterns across the projection horizon. CAGRs derive from segment-level volume trajectories and pricing evolution assumptions, incorporating intravitreal injection frequency compression, biosimilar penetration curves, and gene therapy launch sequencing as AMD-specific inputs.
Sensitivities concentrate around regulatory approval timing, reimbursement policy shifts, and manufacturing capacity constraints. Forecasts reflect documented assumptions regarding patient screening expansion and specialist workforce growth. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Global Ocular Inflammation Treatment Market
Ophthalmology
Global Automated Ophthalmic Perimeters Market
Ophthalmology
Panuveitis Treatment Market
Ophthalmology
Dacryocystitis Treatment Market
Ophthalmology
Non-Infectious Uveitis Treatment Market
Ophthalmology
Global Therapeutic Lenses Market
Ophthalmology
Diabetic Macular Edema Treatment Market
Ophthalmology
Japan Ophthalmic Devices and Drugs Market
Ophthalmology
Ptosis Treatment Market
Ophthalmology
Ophthalmic Eye Shield Market
Ophthalmology
North America Ophthalmic Devices and Drugs Market
Ophthalmology
Global Ophthalmic Knives Market
Ophthalmology
Ophthalmic Devices Market
Ophthalmology
Pseudotumor Cerebri Market
Ophthalmology
Leber Congenital Amaurosis Market
Ophthalmology
Allergy Relieving Eye Drops Market