
 Ptosis Treatment Market | 2026-2036
Ptosis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Ptosis Treatment Market Analytics
Multi-source procurement of ptosis correction devices is rebalancing toward vertically integrated suppliers with captive manufacturing capabilities. Allergan leverages its established botulinum toxin platform to address compensatory brow recruitment in ptosis patients. Merz Pharmaceuticals anchors its position through specialized injectable formulations targeting frontalis muscle overaction. Stryker Corporation competes in the surgical implant segment with precision-engineered lid elevation systems for oculoplastic surgeons.
Ptosis treatment encompasses therapeutic and surgical interventions to correct upper eyelid droop caused by levator aponeurosis dehiscence, myogenic weakness, or neurogenic pathology, with lid lift measurements typically ranging from 1-4 mm for functional correction. The primary purpose spans both visual field restoration for acquired ptosis and cosmetic symmetry improvement for congenital or involutional cases. Surgical intervention dominates value capture due to durable outcomes and higher reimbursement, while non-invasive approaches including adhesive strips and pharmacologic eye drops represent the fastest-expanding category for early-stage or contraindicated patients. Ophthalmology clinics concentrate procedure volume, though ambulatory surgical centers are capturing share through streamlined anesthesia protocols and same-day discharge pathways.
FDA 510(k) clearance requirements and EMA MDR compliance shape product development timelines and clinical evidence standards for ptosis correction devices across major markets. ISO 13485 quality management certification and adherence to IEC 60601 electrical safety standards govern manufacturing scale-up for laser and energy-based treatment platforms. The EU AI Act and GDPR frameworks increasingly influence software-enabled diagnostic tools used in preoperative lid position analysis and surgical planning. Stakeholders must monitor evolving reimbursement criteria from CMS and national health technology assessment bodies that determine access thresholds for surgical versus non-surgical ptosis management.
Market Dynamics
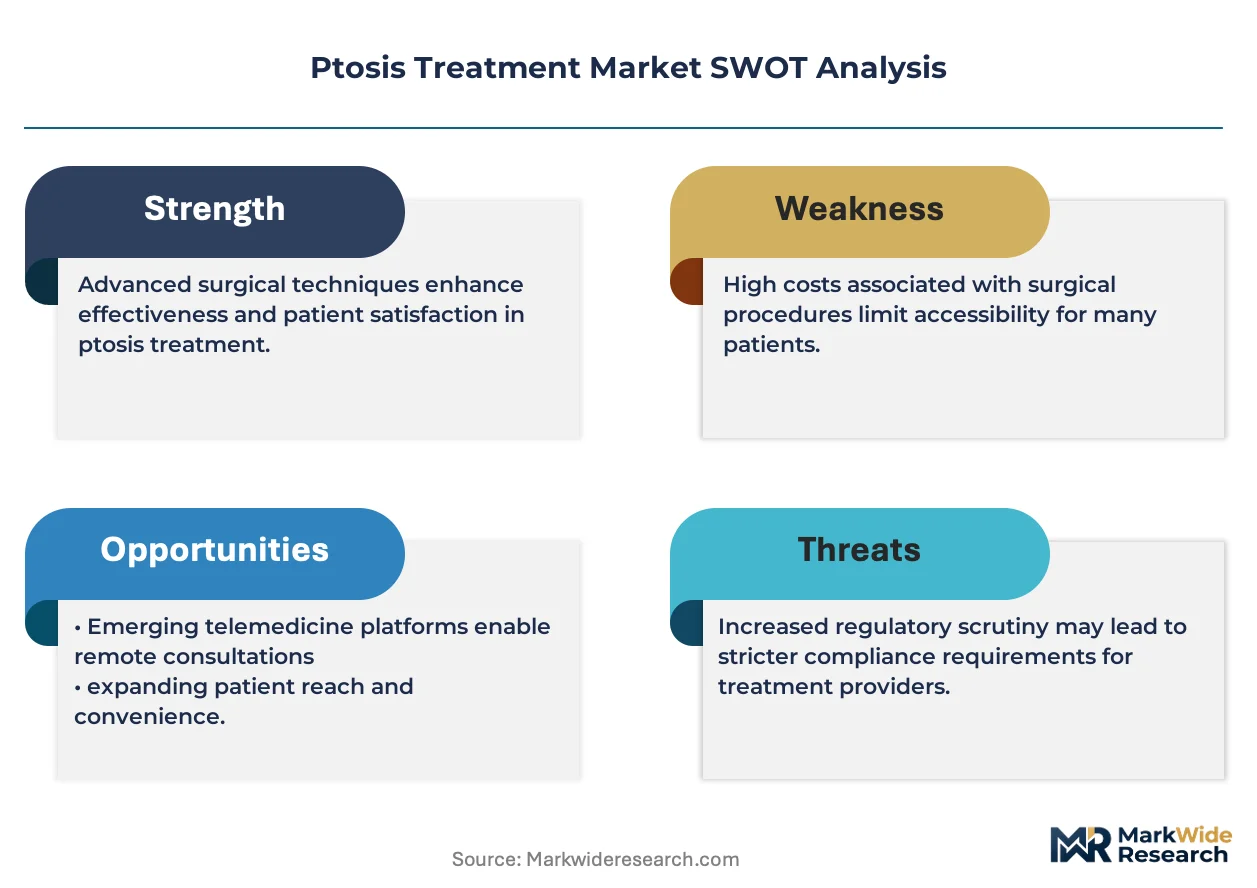
Minimally invasive blepharoptosis correction is compressing the traditional surgical pathway, forcing ophthalmology clinics to reconfigure their procedure mix and capital allocation toward suture-based and energy-assisted lid elevation techniques that reduce anesthesia requirements and same-day discharge friction.
Growth Catalysts
- Aging demographics:Japan, Germany, and the United States are experiencing surgical volume expansion as involutional ptosis prevalence rises among patients over 65, with Medicare and statutory health insurance broadening functional correction reimbursement criteria.
- EMA MDR acceleration:Streamlined conformity assessment pathways for Class IIa ptosis correction devices are compressing time-to-market for novel implantable lid elevation systems, stimulating venture investment in oculoplastic surgical platforms.
- Frontalis sling innovation:Silicone rod and fascia lata substitute materials are expanding pediatric congenital ptosis management options where levator function remains inadequate for standard aponeurotic repair.
Market Restraints
- Silicone polymer supply concentration:Medical-grade elastomer sourcing for adjustable lid elevation systems concentrates among three specialty chemical suppliers in Germany and the United States, exposing device manufacturers to input cost volatility and allocation constraints.
- FDA 510(k) evidentiary burden:Substantial equivalence demonstrations for novel energy-based ptosis correction platforms require larger clinical cohorts than historical predicate devices, extending regulatory timelines and burning capital reserves.
- Adhesive ptosis crutch substitution:Non-invasive lid support strips represent a functional substitute for surgical candidates with comorbidities, capping surgical volume growth in frail elderly populations where anesthesia risk dominates decision-making.
Strategic Opportunities
- Telemedicine preoperative screening:Digital lid position analysis tools are opening remote consultation channels for ambulatory surgical centers, capturing patients from underserved rural counties in the United States and prefectural peripheries in Japan.
- EU AI Act compliance differentiation:Software-enabled surgical planning platforms that achieve conformity with the EU's artificial intelligence liability framework will secure preferential positioning in European ophthalmology clinic procurement evaluations.
- Combination brow-ptosis protocols:Frontalis chemodenervation paired with lid elevation is creating bundled service offerings for aesthetic oculoplastic practices, expanding addressable revenue per patient encounter beyond isolated functional correction.
Industry Challenges
- Oculoplastic surgeon training pipeline:Fellowship positions in eyelid and orbital surgery remain constrained across accredited US programs, creating a bottleneck for procedure volume expansion even where capital equipment sits idle.
- ISO 13485 audit compression:Notified body backlogs for quality management system recertification are delaying manufacturing scale-up for laser-assisted ptosis platforms, forcing sponsors to maintain dual-source production arrangements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ptosis Treatment Market |
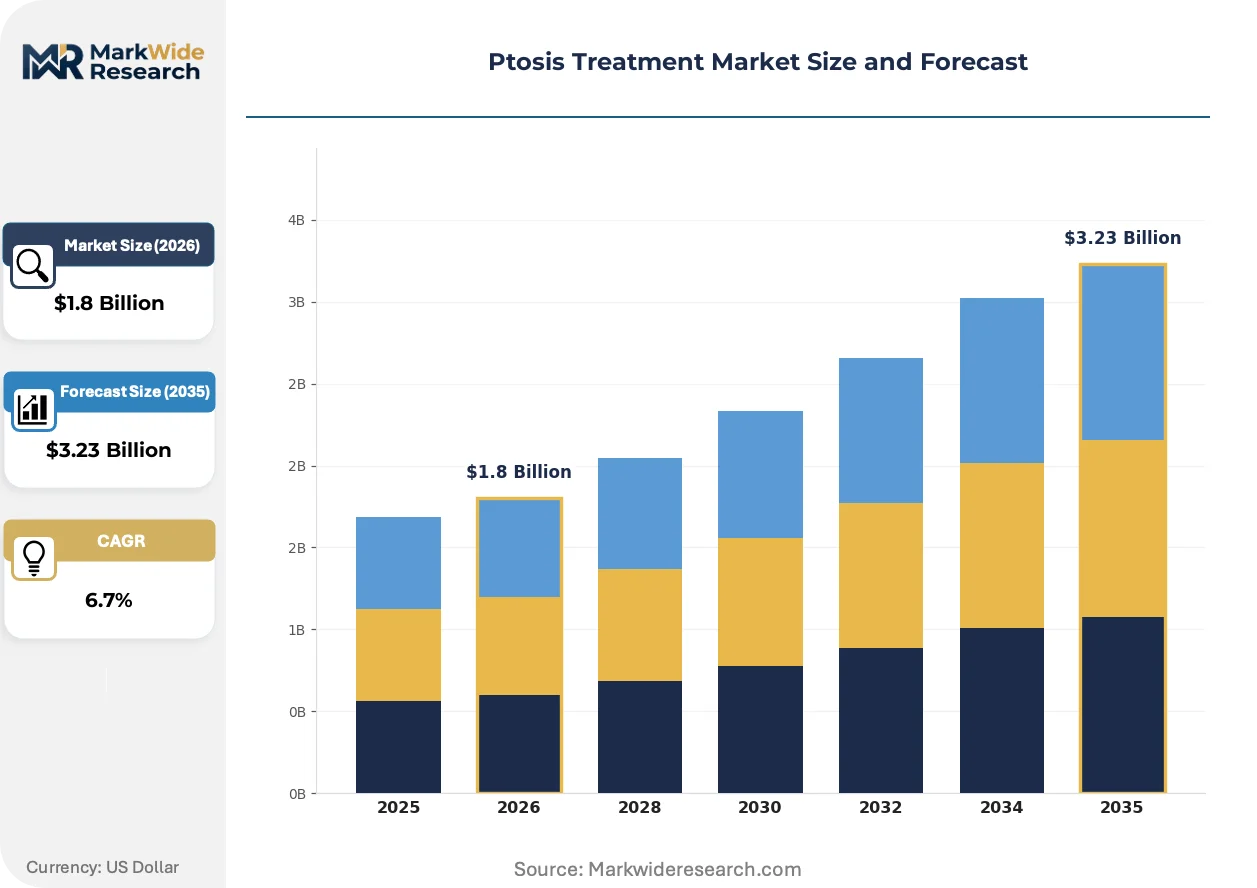
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Eye Drops, Surgical Implants, Adhesive Strips, Customized Devices Delivery Mode: Topical Application, Injectable Solutions, Surgical Intervention, Laser Treatment End User: Ophthalmology Clinics, Hospitals, Home Healthcare, Ambulatory Surgical Centers Treatment Type: Non-Invasive, Minimally Invasive, Surgical, Combined Therapy |
| Companies Covered | Allergan, Revance Therapeutics, Johnson & Johnson, Merz Pharmaceuticals, Galderma, Ipsen, Stryker Corporation, Lumenis Ltd., Bausch + Lomb, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ptosis Treatment Market Evolving Landscape
Energy-based tissue modulation and software-integrated surgical planning are converging to displace mechanical lid elevation as the default intervention pathway, compressing recovery timelines and redistributing procedure volume across care settings.
Fractional CO2 laser blepharoplasty is rewriting the functional ptosis treatment paradigm by enabling precise thermal contraction of the levator aponeurosis without incisional trauma. Outpatient ophthalmology clinics in the United States and South Korea are adopting these platforms at twice the pace of traditional surgical instrument suites. The technology is compressing the indication threshold for intervention, pulling mild-to-moderate cases away from observation protocols.
REACH Annex XIV substance restrictions are forcing medical device manufacturers to reformulate silicone-based lid elevation implants and eliminate certain phthalate plasticizers from suture materials. European oculoplastic surgeons face temporary product shortages as suppliers validate alternative polymer formulations. German and French ophthalmology clinics are prioritizing procurement from manufacturers with demonstrated SVHC substitution compliance.
Direct-to-consumer aesthetic screening is fragmenting the traditional referral pathway for involutional ptosis, with patients self-identifying lid asymmetry through smartphone-based visual field applications. Cosmetic surgery aggregators are capturing these leads and routing them to accredited ambulatory centers, bypassing general ophthalmology gatekeepers. California and Florida surgical markets exhibit the highest concentration of this channel disintermediation.
Ptosis Treatment Market Segmentation
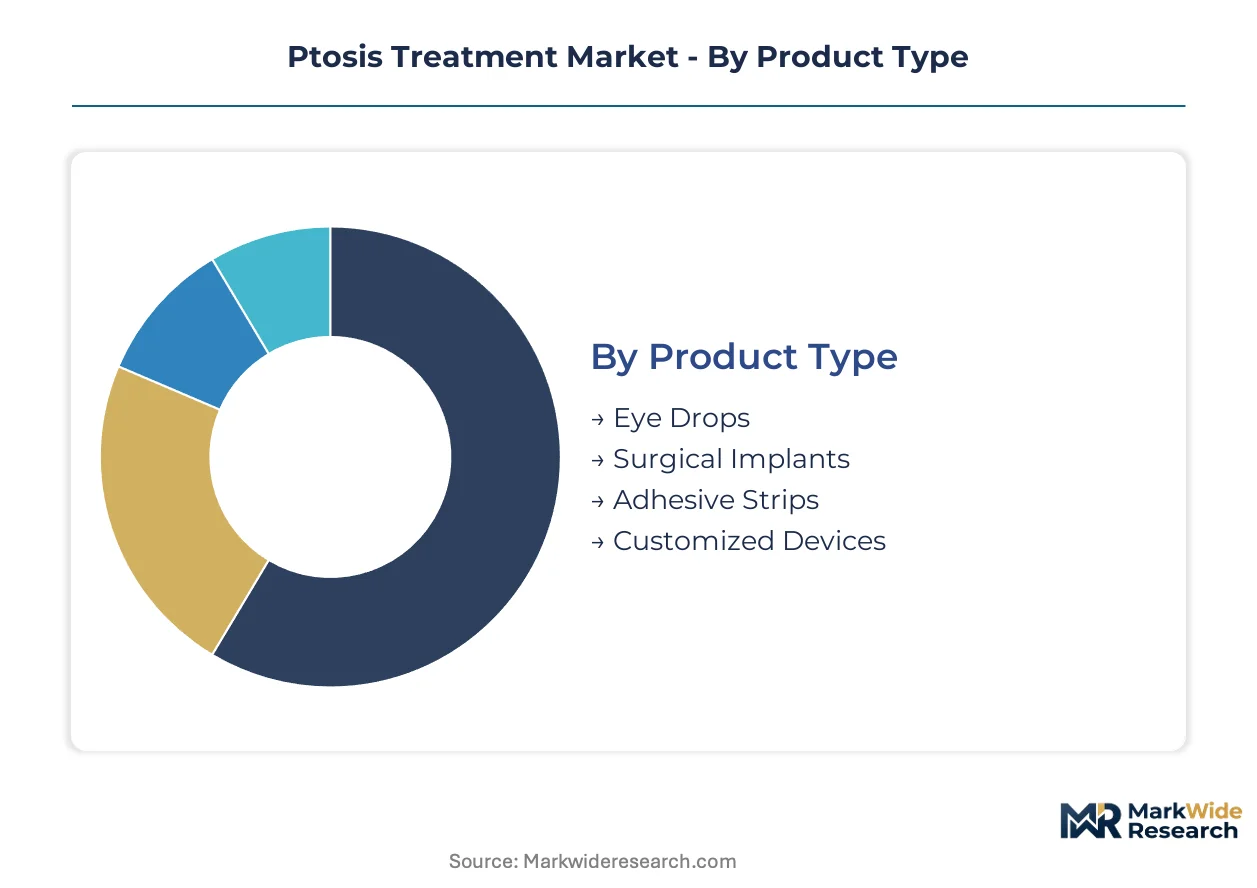
Ptosis treatment segmentation reveals how therapeutic modality, care setting, and invasiveness level determine reimbursement pathways and capital allocation across ophthalmology practices. Manufacturers configure product portfolios across these dimensions to capture volume in surgical suites while hedging against non-invasive substitution.
Product Type:
Customization intensity varies sharply across this category, from mass-produced adhesive strips to patient-matched surgical implants requiring anatomical modeling.
- Surgical Implants:Precision-engineered silicone rods, fascia lata substitutes, and adjustable lid elevation systems anchor durable functional correction. Demand concentrates in pediatric congenital cases and severe involutional presentations across Japan and Germany where statutory insurance covers implant costs.
- Eye Drops:Pharmacologic formulations targeting Müller muscle contraction or neurotransmitter modulation offer temporary lid elevation without procedural risk. United States ophthalmology clinics are piloting these for early-stage cases and surgical contraindications, though duration limits reimbursement appeal.
- Adhesive Strips:External lid crutches provide immediate mechanical support for patients declining or ineligible for surgery. Home healthcare channels in aging European markets stock these for frail elderly populations.
- Customized Devices:Patient-specific 3D-printed lid weights and molded external supports address anatomical asymmetry in complex revision cases. Oculoplastic centers in South Korea and California deploy these for aesthetic ptosis with prior surgical failure.
Leading the category by volume: Surgical Implants. Growing fastest: Eye Drops.
Delivery Mode:
Capital requirements and reimbursement intensity separate office-based applications from facility-fee-generating interventions.
- Surgical Intervention:Levator aponeurosis repair, Müllerectomy, and frontalis sling procedures under regional or general anesthesia dominate value capture. Medicare and Japanese health insurance reimburse these at premium rates, concentrating volume in hospital outpatient departments.
- Laser Treatment:Fractional CO2 and erbium-based thermal modulation of aponeurotic tissue enables incisional-sparing correction. Ambulatory surgical centers in South Korea and the United States are acquiring these platforms to compress recovery timelines and same-day discharge rates.
- Topical Application:Pharmacologic eye drops and external adhesive agents administered without clinical supervision. Home healthcare and direct-to-consumer channels in Germany and France are expanding access for mild functional cases.
- Injectable Solutions:Botulinum toxin chemodenervation of frontalis overaction and filler-based lid margin support. Aesthetic oculoplastic practices in California and Florida bundle these with surgical correction for premium service tiers.
Volume concentrates in Surgical Intervention. Steepest expansion trajectory: Laser Treatment.
End User:
Site-of-care economics and anesthesia infrastructure determine which settings can absorb specific procedure mixes.
- Ophthalmology Clinics:Dedicated oculoplastic practices with in-house surgical suites capture high-margin functional and aesthetic cases. These facilities in the United States and Japan dominate complex revision ptosis and combined brow-lid procedures.
- Ambulatory Surgical Centers:Streamlined anesthesia protocols and same-day discharge capabilities enable cost-competitive care. German and South Korean ASC networks are expanding ptosis volumes through bundled pricing contracts with statutory insurers.
- Hospitals:Academic medical centers and community hospitals manage pediatric congenital cases, trauma-related ptosis, and comorbid orbital pathology. These settings in France and the United Kingdom anchor training pipelines for fellowship-trained oculoplastic surgeons.
- Home Healthcare:External adhesive devices and patient-administered eye drops for palliative or temporary management. Aging-in-place programs in Japan and rural United States counties route these through visiting nurse services.
Procedure volume peaks in Ophthalmology Clinics. Share gains are most rapid in Ambulatory Surgical Centers.
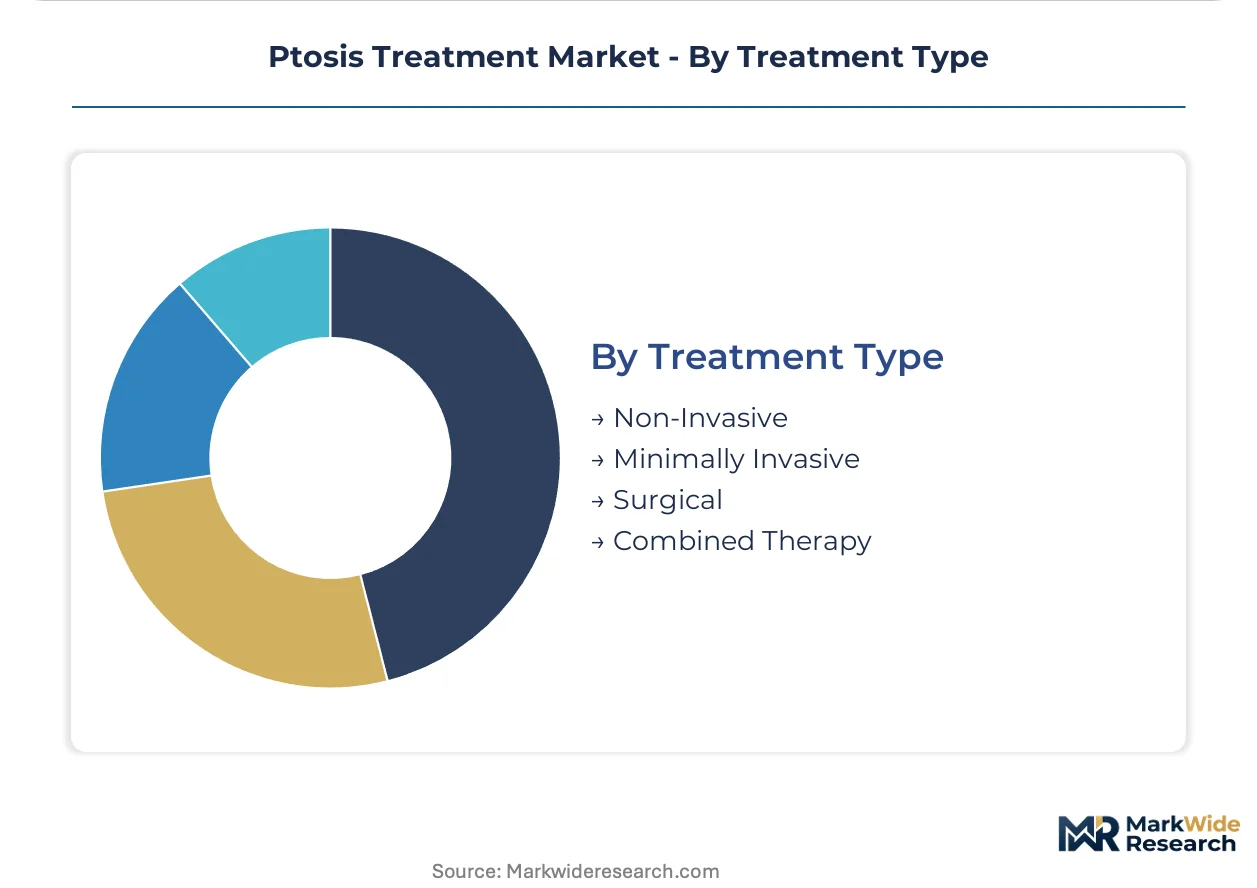
Treatment Type:
Invasiveness level dictates recovery timeline, reimbursement tier, and patient selection criteria across the care continuum.
- Surgical:Definitive mechanical correction through tissue repositioning, resection, or sling suspension. United States and German markets maintain surgical dominance due to durable outcomes and established reimbursement codes for functional visual field impairment.
- Minimally Invasive:Suture-based aponeurosis plication, energy-assisted tissue tightening, and small-incision techniques under local anesthesia. South Korean and Japanese clinics are expanding these to capture patients seeking reduced downtime.
- Non-Invasive:External mechanical support and pharmacologic modulation without tissue disruption. European markets with constrained surgical capacity and high anesthesia-risk populations are scaling these options.
- Combined Therapy:Staged or simultaneous deployment of multiple modalities—typically surgical lid elevation with chemodenervation or laser resurfacing. Premium aesthetic practices in California and Florida are standardizing these protocols for per-patient revenue optimization.
Surgical approaches command the largest volume share. Minimally Invasive methods are climbing fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medical-grade silicone polymer production concentrates in Germany and the United States, anchoring supply chains for adjustable lid elevation systems that serve aging populations across developed markets.
United States
Medicare reimbursement expansion for functional ptosis correction drives surgical volume among patients over 65. FDA 510(k) clearance pathways for energy-based devices compress regulatory timelines for novel platforms. California and Florida ambulatory surgical centers capture rising aesthetic demand through bundled brow-lid protocols.
Germany
Statutory health insurance covers implant costs for severe involutional and congenital cases, sustaining demand for precision-engineered lid elevation systems. EMA MDR streamlined conformity assessments accelerate time-to-market for Class IIa devices. Bavarian and North Rhine-Westphalian ophthalmology clinics lead adoption of suture-based minimally invasive techniques.
Japan
Super-aging demographics expand the addressable patient base for both surgical and non-invasive interventions. PMDA regulatory frameworks govern approval timelines for novel pharmacologic eye drops under development. Tokyo and Osaka metropolitan clusters concentrate oculoplastic surgeon expertise and procedure volume.
South Korea
Aesthetic medicine infrastructure supports rapid adoption of fractional CO2 laser blepharoplasty for mild-to-moderate functional cases. MFDS oversight ensures alignment with international electrical safety standards for energy-based platforms. Seoul Capital Area clinics compress recovery timelines to capture medical tourism flows from China and Southeast Asia.
United Kingdom
NHS referral pathways for visual field impairment sustain hospital-based surgical volumes for complex congenital and trauma-related cases. MHRA post-Brexit regulatory autonomy enables divergence from EMA timelines for certain device categories. London and Southeast England academic medical centers anchor fellowship training pipelines for oculoplastic specialists.
Ptosis Treatment Market Competitive Landscape
Portfolio diversification dominates the current landscape as device manufacturers and pharmaceutical sponsors hedge across surgical, minimally invasive, and non-invasive modalities. The market structure exhibits tiered consolidation: multinational conglomerates with established ophthalmology divisions occupy premium positions, mid-cap specialists concentrate on single-modality excellence, and emerging ventures pursue regulatory-first strategies for novel energy-based platforms. Strategic archetypes include vertically integrated implant manufacturers, botulinum toxin platform extenders, and laser system innovators. M&A activity and technology licensing agreements represent the dominant competitive moves as sponsors seek to fill portfolio gaps.
Among established pharmaceutical sponsors, Allergan and Merz Pharmaceuticals exemplify the toxin-platform extension archetype, leveraging frontalis muscle modulation capabilities to address compensatory brow recruitment in ptosis patients. Stryker Corporation anchors the surgical implant tier with precision-engineered mechanical systems. These three entities represent contrasting strategic positions: pharmaceutical-derived neuromodulation, specialized injectable formulations, and durable surgical hardware.
| Leading Market Players |
|---|
| Allergan |
| Revance Therapeutics |
| Johnson & Johnson |
| Merz Pharmaceuticals |
| Galderma |
| Ipsen |
| Stryker Corporation |
| Lumenis Ltd. |
| Bausch + Lomb |
| Others |
Value Network & Pricing Analysis
Certification-grade bifurcation between FDA-cleared surgical implants and unregulated adhesive strips manifests in divergent pricing architectures and procurement pathways across ophthalmology practices. Premium-tier manufacturers bundle extended warranty coverage and surgeon training programs with adjustable lid elevation systems, while economy-tier suppliers strip after-sales service to compete on unit cost for external crutches.
Pricing Analysis
Warranty and service bundling separates premium surgical implant vendors from commodity adhesive strip suppliers in contract negotiations with ophthalmology clinics. Three-tier pricing structure across premium, standard, and economy levels reflects FDA clearance status, ISO 13485 certification, and geographic delivery logistics. Pricing pressure stems from silicone polymer feedstock volatility and REACH compliance costs for European market access. Ambulatory surgical centers exhibit highest price sensitivity due to bundled reimbursement constraints, while academic medical centers prioritize clinical outcomes over unit economics.
Supply Chain Analysis
Single-source vulnerability sits with German and United States specialty chemical suppliers for medical-grade silicone elastomers used in adjustable lid elevation systems. Device manufacturing draws from polymer compounding facilities in Bavaria, precision machining operations in Switzerland, and sterile packaging operations in Ireland. Tariff exposure on Chinese-sourced titanium suture anchors creates margin compression for mid-tier implant manufacturers. Distribution runs through specialized ophthalmology distributor networks and direct hospital contracting channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ptosis treatment market operates as a cost-of-compliance story where EMA MDR conformity assessment investments create sustainable barrier-to-entry moats for established device manufacturers against undercapitalized challengers.
For Market Incumbents: Anchor market position through backward integration into medical-grade silicone polymer sourcing and captive manufacturing of laser-assisted ptosis platforms. Defensive priorities center on securing dual-source supply arrangements for REACH-compliant elastomers and accelerating FDA 510(k) predicate libraries against energy-based entrant threats.
For New Entrants and Emerging Players: Capture white-space opportunity in telemedicine-enabled preoperative lid position screening for rural United States counties and Japanese prefectural peripheries. The most penetrable segment combines pharmacologic eye drop development for early-stage involutional cases with direct-to-consumer aesthetic screening applications.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by multinational ophthalmology conglomerates seeking energy-based platform capabilities. Long-term viability favors sponsors with demonstrated EU AI Act compliance for surgical planning software and established hospital GPO contracting relationships. The signal to watch is CMS reimbursement expansion for functional ptosis correction in Medicare Advantage plans.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Pathway | Accelerated clearance timelines for energy-based devices compress competitive windows in ambulatory surgical centers. |
| CE Marking Pathway | EMA MDR streamlined assessments for Class IIa implants enable faster European market entry than predicate-era timelines. |
| Hospital System Partnership | Academic medical center alliances secure training pipeline access and fellowship program influence for novel techniques. |
| Software Companion Development | EU AI Act-compliant lid position analysis tools differentiate procurement evaluations in German and French clinics. |
| Reimbursement Strategy | CMS functional visual field impairment coding expansion drives surgical volume among Medicare-eligible populations. |
Research Methodology
FDA 510(k) filings, EMA MDR technical documentation, and hospital procurement databases formed the secondary backbone for market sizing and competitive positioning analysis. Primary fieldwork encompassed structured interviews with oculoplastic surgeons, ambulatory surgical center administrators, biomedical engineers, and GPO contracts managers across United States, German, and Japanese markets. Bottom-up procedure volume estimates triangulated against top-down manufacturer revenue disclosures.
Historical surgical volume trendlines and laser platform installation rates anchored the analytical framework across the projection horizon. Segmentation modeling incorporated treatment modality, care setting, invasiveness level, and regional regulatory cluster dimensions. CAGRs derived from fitted growth curves applied to demographic-adjusted incidence rates and reimbursement elasticity assumptions. Forecast inputs included PMDA approval timelines for pharmacologic candidates and MFDS energy-based device adoption curves.
The model holds under stable Medicare reimbursement and REACH SVHC substitution compliance; deviation in FDA evidentiary requirements or silicone supply allocation would shift volume trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Herpes Simplex Keratitis Treatment Market
Ophthalmology
Australia Ophthalmic Devices Market
Ophthalmology
Asia-Pacific Glaucoma Treatment Market
Ophthalmology
Global Photochromic Lenses Market
Ophthalmology
Ophthalmic Operating Room Microscope Market
Ophthalmology
Herpes Zoster Ophthalmicus Market
Ophthalmology
Ophthalmic Tonometers Market
Ophthalmology
Ophthalmic Lasers Therapeutic Market
Ophthalmology
Bullous Keratopathy Market
Ophthalmology
Global Tonometer Market
Ophthalmology
Retinoblastoma Treatment Market
Ophthalmology
Excimer and Femtosecond Ophthalmic Lasers Market
Ophthalmology
Macular Edema Market
Ophthalmology
Head Band Ophthalmoscopes Market
Ophthalmology
Canada Ophthalmology Drugs and Devices Market
Ophthalmology
Aesthetic Ophthalmology Device Market