
 Dacryocystitis Treatment Market | 2026-2036
Dacryocystitis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Dacryocystitis Treatment Market Outlook
The EU Medical Device Regulation (MDR) is realigning certification requirements for lacrimal drainage implants and surgical tools across European markets. Novartis AG leverages its ophthalmology franchise to sustain R&D pipelines in anti-infective therapies. Merck & Co. Inc. anchors its position through broad-spectrum antibiotic portfolios used in preoperative protocols. Pfizer Inc. competes on manufacturing scale for systemic agents administered in hospital settings.
Dacryocystitis treatment addresses infection and obstruction of the nasolacrimal sac through antimicrobial therapy, mechanical dilation, or surgical bypass procedures requiring silicone stent placement with diameters typically ranging from 0.6 mm to 1.2 mm. The primary purpose is restoring tear drainage while preventing recurrent pyogenic complications and orbital cellulitis spread. Antibiotics and Surgery together constitute the dominant treatment type pairing, with Surgery capturing higher per-procedure value due to operating room utilization and specialized instrumentation. Devices within the product type classification carry concentrated margin pools, particularly balloon dacryoplasty catheters and lacrimal intubation sets subject to stringent sterilization protocols.
FDA 510(k) clearance pathways and EMA CE marking under MDR govern market access for lacrimal surgical devices, while WHO Essential Medicines List inclusion shapes antibiotic procurement in low-resource settings. Japan's PMDA evaluates novel drug-device combinations through sakigake designation frameworks, accelerating review timelines for innovative stent designs. Stakeholders must monitor evolving reimbursement thresholds for outpatient dacryocystorhinostomy versus endonasal approaches as payers recalibrate site-of-service differentials.
Market Dynamics
Minimally invasive surgical techniques are compressing procedure times and recovery windows, forcing incumbent device manufacturers to accelerate stent miniaturization programs while defending installed base positions in tertiary ophthalmology centers.
Growth Catalysts
- Aging Demographics:Japan's super-aged population and Germany's demographic transition are expanding the chronic dacryocystitis patient pool requiring repeated intervention. Tertiary centers in Tokyo and Munich report elevated surgical volumes.
- CE Marking Under MDR:The EU Medical Device Regulation's tightened quality benchmarks for lacrimal drainage implants are filtering out marginal suppliers and consolidating procurement toward validated manufacturers.
- Balloon Dacryoplasty:This catheter-based dilation technology is replacing conventional probing in pediatric cases, reducing general anesthesia exposure and same-day discharge rates.
Market Restraints
- Silicone Polymer Feedstock Volatility:Medical-grade silicone for stent manufacturing faces price instability tied to semiconductor sector demand competition, compressing device margin pools.
- Single-Site Supply Concentration:Precision molding capabilities for 0.6-1.2 mm diameter stents concentrate in southern German industrial clusters, creating geographic vulnerability.
- Antibiotic Stewardship Mandates:WHO Essential Medicines List criteria and national antimicrobial resistance programs are restricting empirical broad-spectrum prescription patterns in preoperative protocols.
Strategic Opportunities
- Outpatient Migration:Endonasal dacryocystorhinostomy techniques are shifting procedure volume from inpatient suites to ambulatory surgery centers in the United States, opening capital-light deployment models.
- Drug-Device Convergence:Antibiotic-eluting stent coatings combining silicone matrices with sustained-release formulations represent unclaimed white space between device and pharmaceutical regulatory pathways.
- Japan's Sakigake Designation:PMDA's accelerated review framework for innovative lacrimal implants offers 50% faster market access timelines compared to standard shonin approval tracks.
Industry Challenges
- Microsurgical Skill Pipeline:Lacrimal surgery requires specialized training in endonasal anatomy and dacryoendoscopy that residency programs are shortening, creating qualified operator scarcity.
- MDR Technical Documentation Burden:European notified body backlogs for Class IIa/IIb device recertification are extending market access timelines by 12-18 months for legacy product portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dacryocystitis Treatment Market |
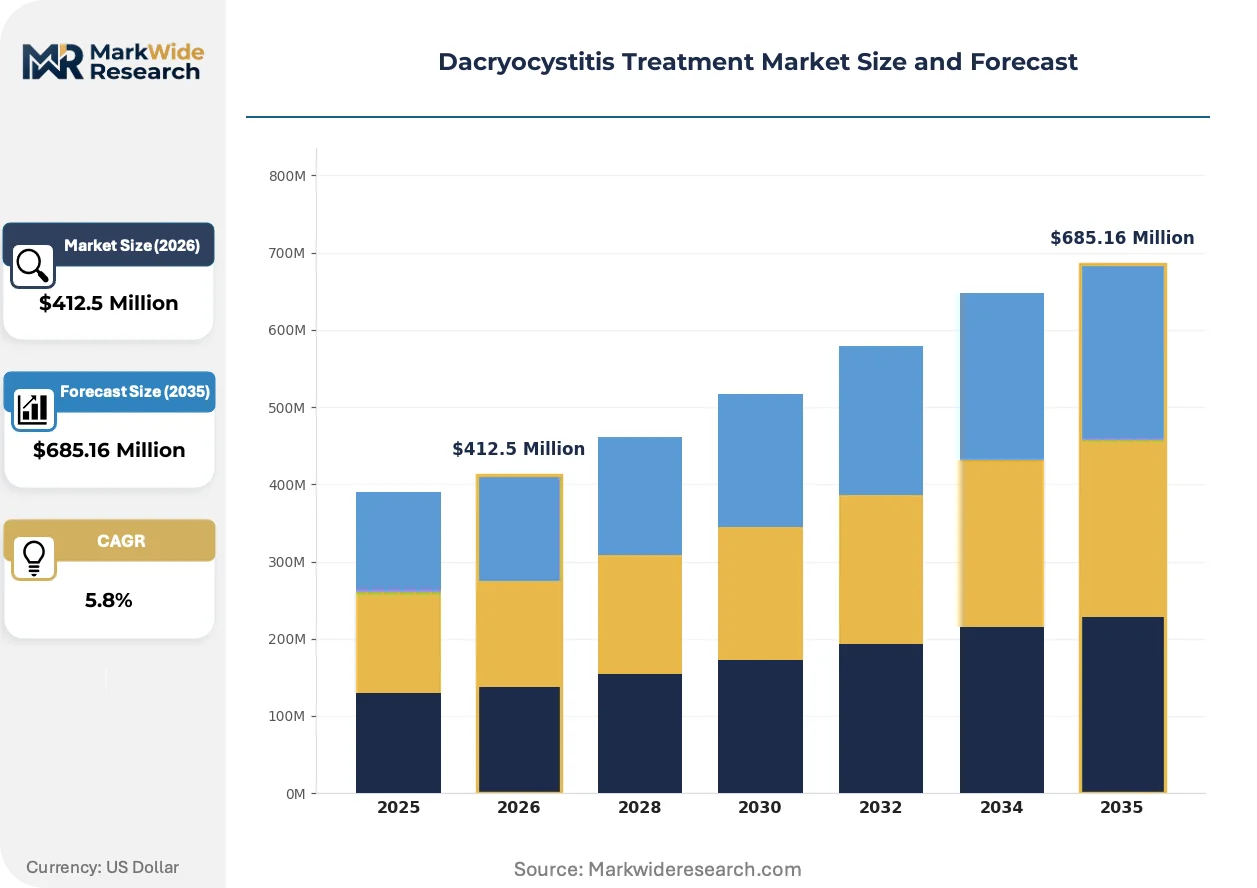
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $685.16 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Treatment Type: Antibiotics, Surgery, Punctal Plugs, Balloon Dacryoplasty End User: Hospitals, Clinics, Outpatient Surgical Centers, Home Healthcare Product Type: Devices, Medications, Surgical Instruments, Diagnostic Tools Administration Route: Topical, Oral, Intravenous, Subconjunctival |
| Companies Covered | Novartis AG, Merck & Co. Inc., Pfizer Inc., Kaneka Corp., FCI Ophthalmics, GlaxoSmithKline plc, Johnson & Johnson, Bausch Health Companies Inc., Abbott Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dacryocystitis Treatment Market Strategic Shifts
Digital navigation systems and bioresorbable materials are converging to redefine procedural workflows, while regulatory frameworks on both sides of the Atlantic are rewriting competitive entry conditions for surgical device portfolios.
Navigation-enabled dacryoendoscopy is automating anatomical landmark identification during transcanalicular procedures. Tertiary ophthalmology departments in the United States and Germany are piloting these platforms to reduce perforation risk in revision surgeries. The technology is compressing training curves for junior surgeons while standardizing outcomes documentation for payer reimbursement.
The EU Medical Device Regulation's post-market surveillance requirements are mandating systematic clinical follow-up data for lacrimal implants. Manufacturers must now maintain active implant registries and periodic safety update reports that exceed legacy MEDDEV guidelines. Mid-tier European device suppliers are outsourcing vigilance functions to specialized CROs to maintain CE marking validity.
Hospital procurement committees are consolidating supplier relationships for ophthalmic surgery sets, bundling stents, dilators, and irrigation systems under multi-year framework agreements. This concentration is displacing spot purchasing through distributor networks. The shift is most visible in German and Japanese university hospital systems where standardization protocols prioritize inventory reduction over brand flexibility.
Dacryocystitis Treatment Market Segmentation
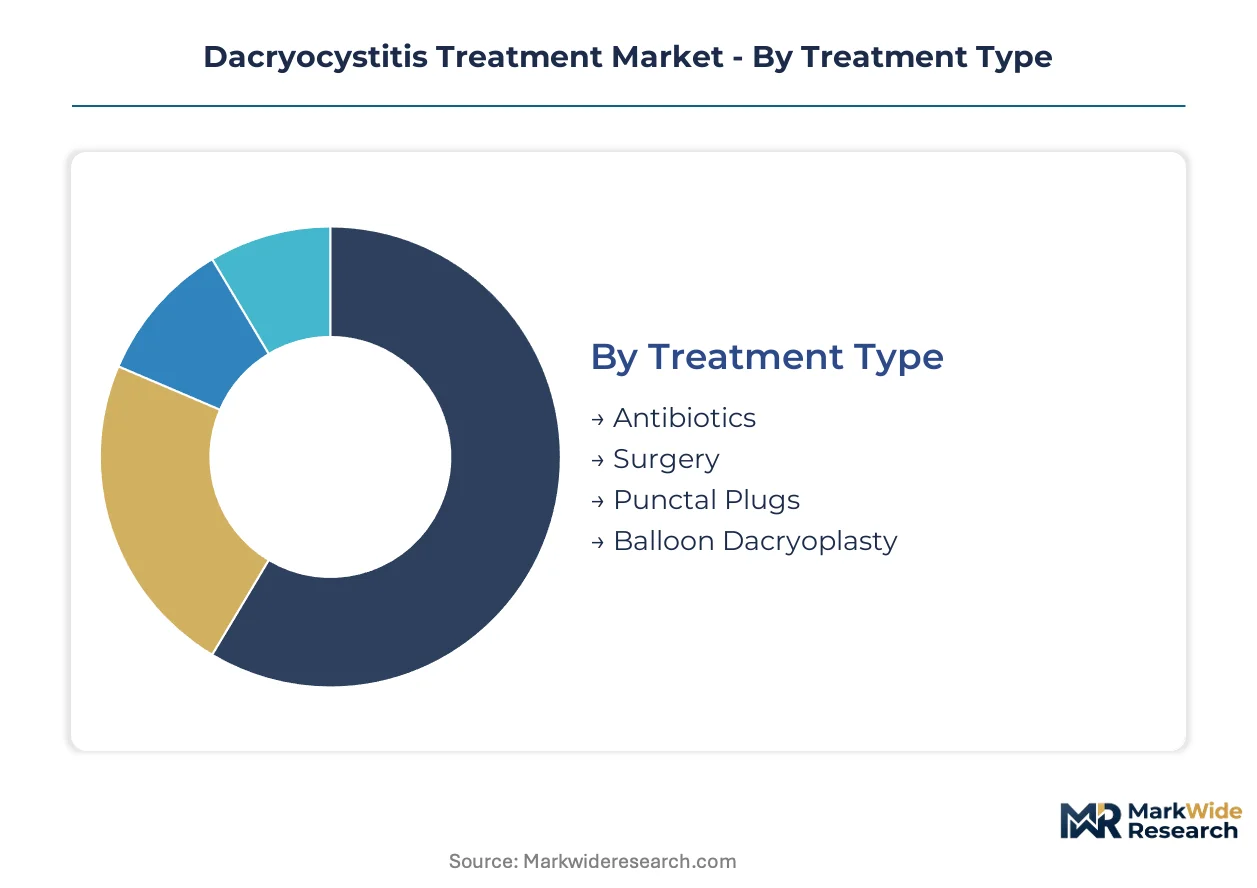
Treatment modality selection in dacryocystitis hinges on infection severity, anatomical obstruction patterns, and patient comorbidity profiles. Segmentation reveals how procedure economics and reimbursement pathways reshape competitive positioning across surgical and pharmaceutical interventions.
Treatment Type:
Clinical decision-making pivots on acute versus chronic presentation, with cost recovery timelines varying dramatically by intervention invasiveness.
- Surgery:Dacryocystorhinostomy and stenting procedures command premium reimbursement through operating room utilization and specialized instrumentation. Tertiary ophthalmology centers in Germany and Japan report elevated volumes as aging populations drive recurrent chronic cases requiring definitive mechanical correction.
- Antibiotics:Systemic and topical antimicrobial therapy addresses acute infectious presentations through broad-spectrum coverage against Staphylococcus and Streptococcus species. WHO Essential Medicines List inclusion shapes procurement in low-resource settings, though stewardship mandates are narrowing empirical prescription patterns.
- Balloon Dacryoplasty:Catheter-based dilation technology reduces general anesthesia exposure in pediatric populations.
- Punctal Plugs:Temporary occlusion devices manage tear drainage in select inflammatory presentations.
Volume sits with Antibiotics; growth tilts toward Surgery.
End User:
Site-of-service economics are redistributing procedure volume as payers recalibrate reimbursement differentials between inpatient and ambulatory settings.
- Outpatient Surgical Centers:Endonasal dacryocystorhinostomy migration is compressing capital requirements and accelerating same-day discharge protocols. United States ambulatory facilities are capturing share from hospital inpatient suites through streamlined scheduling and lower facility fees.
- Hospitals:Complex revision surgeries and orbital cellulitis complications requiring multidisciplinary management concentrate in tertiary academic medical centers with dacryoendoscopy capabilities.
- Clinics:Initial diagnostic workup and medical management of uncomplicated acute cases.
- Home Healthcare:Postoperative irrigation protocols and medication administration in select markets.
Revenue concentrates in Hospitals; share expansion is accelerating most quickly in Outpatient Surgical Centers.
Product Type:
Margin pools diverge sharply between commoditized pharmaceuticals and specialized devices subject to stringent sterilization validation.
- Devices:Silicone stents, balloon catheters, and lacrimal intubation sets carry concentrated margin pools tied to precision molding capabilities. EU MDR recertification burdens are filtering marginal suppliers and consolidating procurement toward validated manufacturers with active implant registries.
- Surgical Instruments:Microsurgical probes, dilators, and irrigation systems face bundling pressure from hospital procurement committees.
- Medications:Antibiotic formulations and anti-inflammatory drops compete on manufacturing scale.
- Diagnostic Tools:Dacryoendoscopy systems and irrigation diagnostic sets support preoperative planning.
Margin accrues to Devices; standardization pressure is reshaping Surgical Instruments procurement.
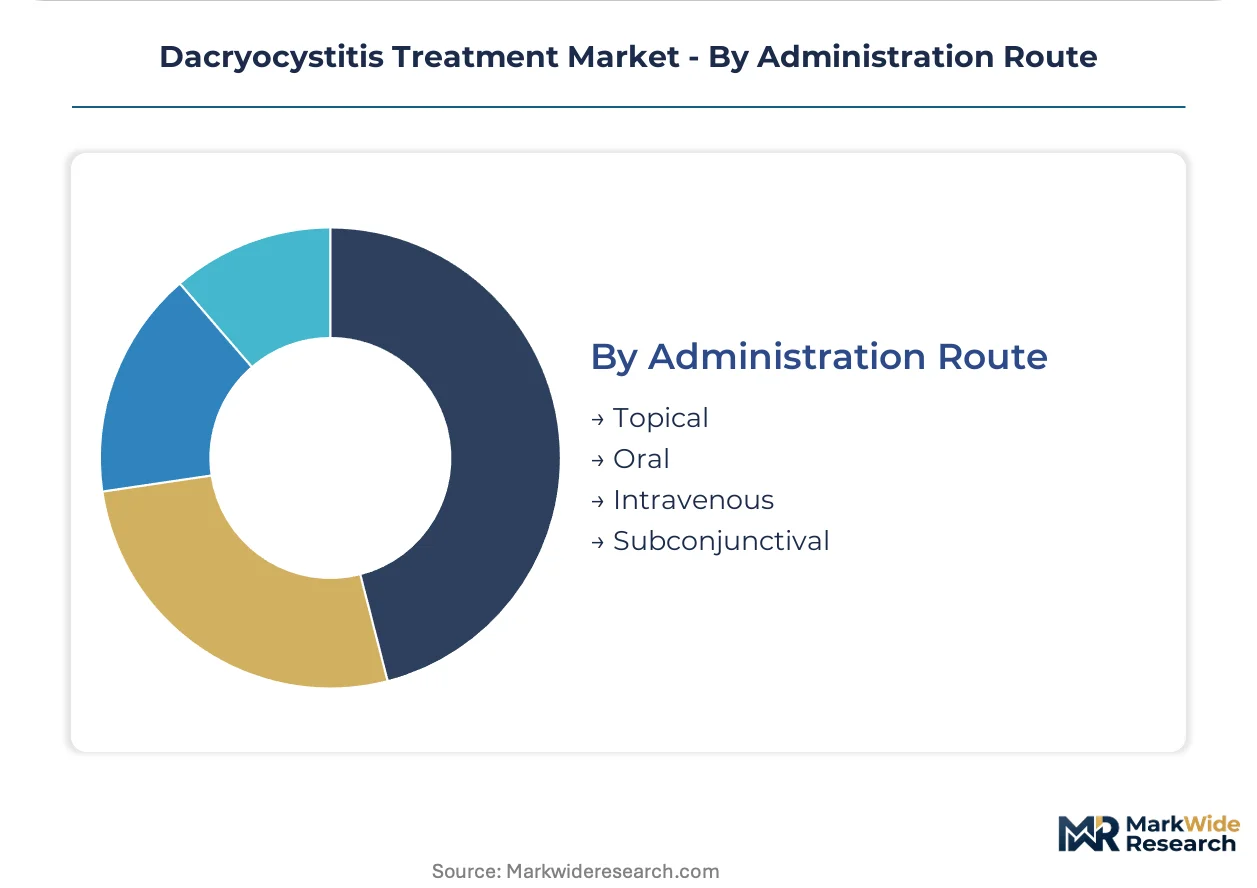
Administration Route:
Delivery pathway selection reflects infection depth, orbital involvement risk, and bioavailability requirements for target tissue penetration.
- Topical:Eye drops and ointments provide localized antimicrobial action for uncomplicated canaliculitis presentations with minimal systemic exposure.
- Intravenous:Hospital-based delivery for severe preseptal cellulitis or orbital extension requiring rapid therapeutic levels.
- Oral:Outpatient step-down therapy following initial parenteral stabilization.
- Subconjunctival:Periocular injection for targeted depot delivery in refractory cases.
Utilization clusters in Topical delivery; escalation protocols favor Intravenous for complicated presentations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Device production clusters in southern Germany and Japan's precision manufacturing corridors, while tertiary ophthalmology centers in the United States and Western Europe absorb the majority of procedural volume. This geographic split between manufacturing concentration and clinical demand shapes procurement logistics and regulatory compliance costs across the value chain.
United States
Ambulatory surgery centers in Texas and Florida are capturing endonasal dacryocystorhinostomy volume from hospital inpatient suites through streamlined scheduling protocols. FDA 510(k) clearance pathways govern market access for lacrimal stents and balloon catheters, with review timelines compressing for predicate-device submissions. Tertiary ophthalmology departments at Johns Hopkins and Bascom Palmer Eye Institute are piloting navigation-enabled dacryoendoscopy platforms to standardize revision surgery outcomes.
Germany
University hospitals in Munich and Heidelberg report elevated surgical volumes as the country's demographic transition expands the chronic dacryocystitis patient pool requiring repeated intervention. EU MDR recertification requirements for Class IIa/IIb lacrimal implants are filtering marginal suppliers and consolidating procurement toward validated manufacturers. Precision molding capabilities for 0.6-1.2 mm diameter silicone stents concentrate in Baden-Württemberg industrial clusters, creating geographic feedstock vulnerability.
Japan
Tokyo's super-aged population is driving incidence rates for chronic dacryocystitis requiring definitive surgical correction rather than repeated antimicrobial courses. PMDA's sakigake designation framework accelerates review timelines by 50% for innovative lacrimal implants compared to standard shonin approval tracks. Nagoya-based precision polymer fabricators supply medical-grade silicone to domestic device manufacturers facing semiconductor sector demand competition.
United Kingdom
NHS England's site-of-service reimbursement differentials are shifting uncomplicated cases toward outpatient settings while reserving tertiary centers for complex revisions. MHRA post-Brexit regulatory alignment with EU MDR technical documentation requirements is extending market access timelines for legacy device portfolios. Moorfields Eye Hospital in London anchors specialist training pipelines for lacrimal microsurgery that residency programs elsewhere are shortening.
India
WHO Essential Medicines List inclusion shapes antibiotic procurement patterns for acute infectious presentations in government hospital networks across Maharashtra and Tamil Nadu. CDSCO registration requirements for imported lacrimal devices create compliance friction for multinational suppliers targeting the private hospital segment. Chennai and Hyderabad are emerging as assembly locations for surgical instrument sets serving South Asian markets.
Dacryocystitis Treatment Market Competitive Environment
The competitive structure tilts toward diversified pharmaceutical conglomerates with ophthalmology franchises rather than pure-play device specialists. Market concentration is moderate, with top-tier players commanding procurement relationships in tertiary centers while mid-tier suppliers compete on price in ambulatory settings. Three archetypes dominate: broad-spectrum antibiotic manufacturers, precision silicone device fabricators, and integrated ophthalmology portfolio holders. Competitive moves center on M&A to capture drug-device convergence opportunities and strategic partnerships to secure MDR-compliant manufacturing capacity.
Within the integrated ophthalmology tier, Novartis AG and Johnson & Johnson occupy positions spanning anti-infective therapies through surgical instrumentation. Among diversified pharmaceutical manufacturers, Pfizer Inc. and Merck & Co. Inc. exemplify scale-driven systemic antibiotic production for hospital-based protocols. Kaneka Corp. represents the specialized polymer segment, with its corporate origins in Osaka suggesting Japanese precision manufacturing heritage. FCI Ophthalmics anchors the pure-play lacrimal device space.
| Leading Market Players |
|---|
| Novartis AG |
| Merck & Co. Inc. |
| Pfizer Inc. |
| Kaneka Corp. |
| FCI Ophthalmics |
| GlaxoSmithKline plc |
| Johnson & Johnson |
| Bausch Health Companies Inc. |
| Abbott Laboratories |
| Others |
Value Chain & Pricing Dynamics
Tertiary ophthalmology centers in Germany and Japan concentrate procurement power through multi-year framework agreements, anchoring contract-based pricing for silicone stent sets and balloon catheter systems. This buyer consolidation compresses spot-market premiums while rewarding validated manufacturers with volume commitments tied to EU MDR compliance tiers.
Pricing Analysis
Margin tightening in device tiers reflects medical-grade silicone feedstock competition from semiconductor sector demand. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared implant lines from CE-marked equivalents and unvalidated alternatives. Pricing pressure intensifies in balloon dacryoplasty catheters as ambulatory surgery centers in the United States negotiate bundled procedure rates. Hospital procurement committees exhibit lowest price sensitivity for revision surgery instrumentation, while outpatient clinics prioritize economy-tier options.
Supply Chain Analysis
Regional distribution centers in Baden-Württemberg and Nagoya operate hub-and-spoke patterns for lacrimal device fulfillment. Precision molding capabilities for 0.6-1.2 mm diameter stents concentrate in Germany and Japan, drawing from medical-grade silicone polymer feedstocks sourced through semiconductor industry channels. Single-site supply concentration in southern German industrial clusters creates geographic vulnerability to logistics disruption. Distribution runs through specialized ophthalmic instrument distributors serving tertiary centers and ambulatory surgery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Balloon dacryoplasty platforms are displacing conventional probing in pediatric cases, compressing general anesthesia utilization and accelerating same-day discharge protocols across tertiary networks.
For Market Incumbents: To counter antibiotic-eluting stent coatings from convergent entrants, prioritize backward integration into medical-grade silicone polymer supply and accelerate PMDA sakigake pathway submissions for navigation-enabled dacryoendoscopy platforms. Defend installed base positions in Munich and Tokyo university hospitals through active implant registry maintenance exceeding EU MDR post-market surveillance minima. For New Entrants and Emerging Players: Drug-device convergence white space in sustained-release antibiotic matrices represents the most penetrable wedge for specialty pharmaceutical fabricators lacking device heritage. Target outpatient surgical centers in Texas and Florida through capital-light balloon catheter leasing models bypassing hospital procurement committee gatekeeping. Prioritize CE marking under MDR as market access precondition. For Investors and Strategic Acquirers: Distressed-cycle entries favor precision polymer specialists in Baden-Württemberg facing MDR recertification documentation burdens. Five-to-ten year viability hinges on capturing drug-device combination regulatory expertise. Monitor PMDA sakigake designation awards as inflection signal for accelerated market access timelines.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR recertification filters marginal suppliers toward validated manufacturers with active implant registries. |
| Hospital System Partnership | Munich and Tokyo university hospitals anchor procurement consolidation through multi-year framework agreements. |
| Software Companion Development | Navigation-enabled dacryoendoscopy platforms standardize revision surgery outcomes documentation for payer reimbursement. |
| Reimbursement Strategy | Site-of-service differentials between outpatient and inpatient settings reshape procedure volume distribution. |
| Backward Integration | Captive supply of medical-grade silicone polymer buffers feedstock volatility from semiconductor sector demand competition. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs alongside primary interviews with ophthalmic surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers. FDA 510(k) clearances, EMA MDR technical documentation, and PMDA shonin submissions provided device-specific validation points. Bottom-up procedure volume estimates from tertiary centers triangulated against top-down pharmaceutical shipment data.
Segment-level granularity modeled treatment type, product category, end-user facility tier, and administration route across the projection horizon. CAGRs derived from surgical volume trajectories in super-aged demographics and antimicrobial stewardship policy impacts on pharmaceutical utilization. Industry-specific inputs incorporated EU MDR recertification timeline delays and PMDA sakigake designation acceleration effects.
Several conditions sit outside the modeled scope, including novel bioresorbable stent material clinical trial outcomes and orbital cellulitis complication rate variability. Forecasts reflect documented assumptions around demographic transition pacing and regulatory pathway stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Aesthetic Ophthalmology Device Market
Ophthalmology
Amblyopia Treatment Market
Ophthalmology
Ophthalmic Photocoagulator Market
Ophthalmology
Global Ophthalmoplegia Market
Ophthalmology
Sodium Hyaluronate Eye Drops Market
Ophthalmology
United States Dry Eye Syndrome Market
Ophthalmology
Corneal Ulcer Treatment Market
Ophthalmology
Ptosis Treatment Market
Ophthalmology
Herpes Simplex Keratitis Treatment Market
Ophthalmology
Age Related Vision Dysfunction Market
Ophthalmology
Global Diabetic Macular Edema Market
Ophthalmology
Cataract Treatment Market
Ophthalmology
Extended and Continuous Wear Lenses Market
Ophthalmology
Synoptophore Market
Ophthalmology
Herpes Zoster Ophthalmicus Market
Ophthalmology
Dacryocystitis Market