
 Anti-Inflammatory Peptides Market | 2026-2036
Anti-Inflammatory Peptides Market Size, Share, and Industry Trends Forecast 2026-2036
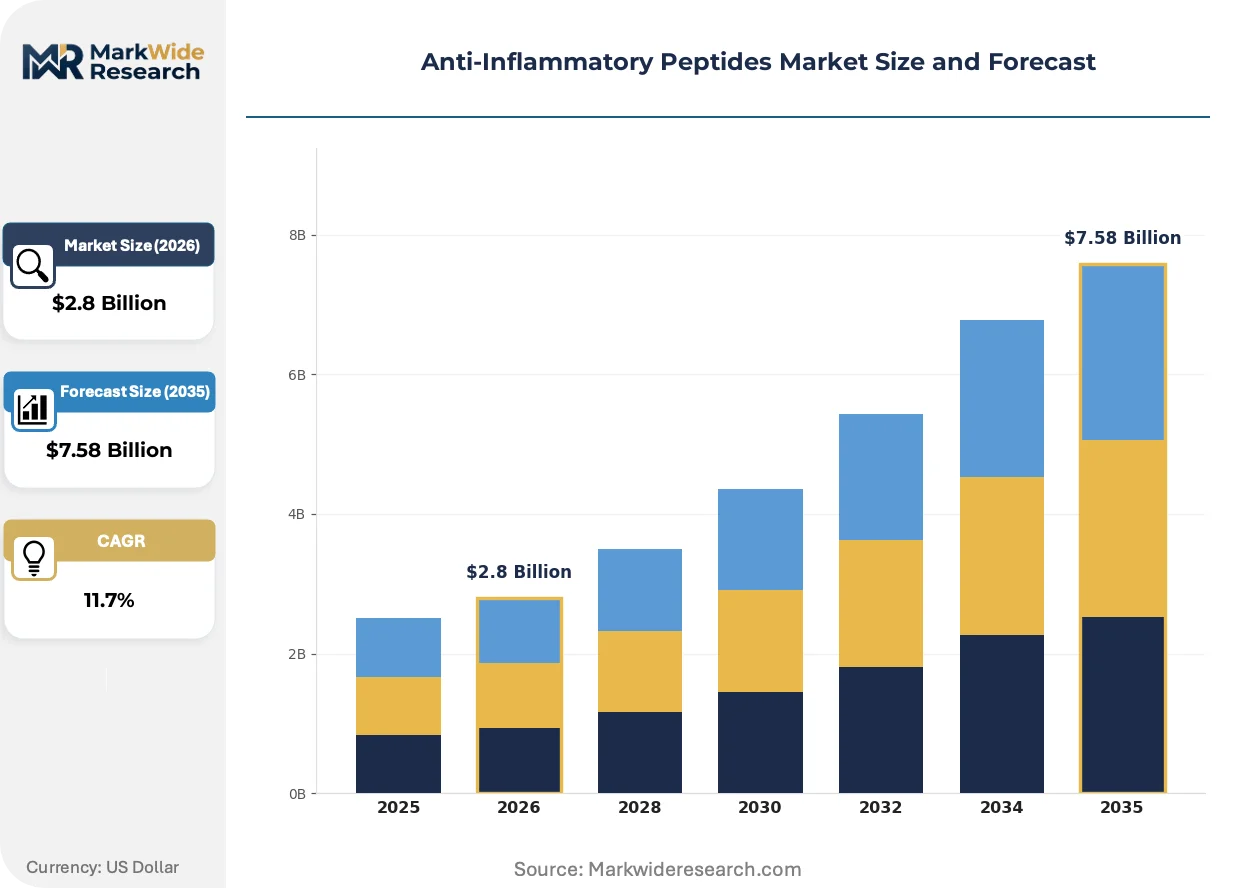
Anti-Inflammatory Peptides Market Outlook
European contract manufacturing capacity for therapeutic peptides is hardening as specialized CDMOs expand GMP-compliant production suites. Novartis AG leverages its integrated peptide synthesis platform to control quality across development stages. Boehringer Ingelheim anchors large-scale fermentation and solid-phase chemistry operations for inflammatory indications. AbbVie Corporation sustains competitive positioning through biologic pipeline diversification into peptide-based immunomodulators.
Anti-inflammatory peptides comprise short amino acid sequences, typically 2–50 residues, engineered to modulate cytokine signaling and immune cell activation through receptor-mediated pathways; they function as biologic alternatives to small-molecule NSAIDs and corticosteroids in chronic inflammatory conditions. Synthetic peptides dominate current production volumes due to reproducible manufacturing and defined impurity profiles, while modified peptides with D-amino acid substitutions or PEGylation represent the fastest-expanding category as these structural alterations enhance plasma half-life and oral bioavailability. Applications in autoimmune disorders command premium pricing relative to pain relief segments, reflecting higher unmet need and willingness to pay for disease-modifying therapy.
FDA biologics licensing requirements and EMA's MDR framework shape clinical development timelines and manufacturing standards for injectable and oral peptide formulations. ISO 13485 quality management systems and ICH Q7 GMP guidelines further constrain supplier qualification and batch release protocols. Stakeholders must monitor evolving pharmacovigilance obligations and biosimilar competition thresholds as peptide therapeutics migrate from specialty to mainstream formulary status.
Market Dynamics
Peptide manufacturing capacity is concentrating among CDMOs with integrated solid-phase synthesis and fermentation capabilities, as pharmaceutical sponsors outsource production to secure GMP-compliant supply chains for Phase III and commercial-scale inflammatory therapeutics.
Growth Catalysts
- FDA Biologics Licensing Pathway:Streamlined IND-to-BLA frameworks for peptide-based immunomodulators accelerate clinical development timelines for autoimmune indications.
- PEGylation Chemistry Advances:Site-specific conjugation technologies extend plasma half-life of anti-inflammatory peptides from hours to days, enabling weekly rather than daily dosing regimens.
- Germany:Heidelberg and Munich biotech clusters concentrate specialized peptide chemistry talent and analytical capabilities that attract multinational sponsor investment.
Market Restraints
- Amino Acid Feedstock Volatility:Prices for protected amino acids and resins fluctuate with petrochemical derivatives, compressing contract manufacturing margins.
- Single-Source Chromatography Media:Purification of therapeutic peptides depends on specialized reversed-phase and ion-exchange resins concentrated among limited qualified suppliers.
- Oral Bioavailability Ceiling:Peptide molecular weight and enzymatic degradation in the gastrointestinal tract constrain non-injectable formulation development despite patient preference for oral routes.
Strategic Opportunities
- Japan:PMDA's Sakigake designation system offers priority review and early reimbursement for innovative peptide therapeutics addressing rheumatoid arthritis and inflammatory bowel disease.
- Companion Diagnostics Integration:Biomarker-guided patient selection for peptide immunotherapy trials improves response rates and supports premium pricing in precision medicine segments.
- Continuous Flow Peptide Synthesis:Adoption of flow chemistry platforms by CDMOs reduces solvent consumption and batch-to-batch variability compared to traditional batch reactors.
Industry Challenges
- Peptide Analytical Method Development:Characterization of complex impurity profiles including diastereomers and deletion sequences requires specialized mass spectrometry expertise that outpaces current workforce supply.
- Multi-Product Facility Qualification:CDMOs face extended validation timelines when switching between peptide therapeutic campaigns due to carryover risk and cleaning verification requirements.
- ICH Q7 Interpretation Variance:Divergent national implementations of GMP guidelines for active pharmaceutical ingredients create compliance complexity for global peptide supply chains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti-Inflammatory Peptides Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.58 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Peptides, Synthetic Peptides, Modified Peptides, Therapeutic Peptides Application: Chronic Inflammation, Autoimmune Disorders, Pain Relief, Skin Conditions End User: Pharmaceutical Companies, Research Institutions, Healthcare Providers, Biotechnology Firms Delivery Mode: Injectable, Oral, Topical, Intranasal |
| Companies Covered | Novartis AG, Mylan Pharmaceuticals, Rogne Bioscience, Merck Serono, F4 Pharma, Araim Pharmaceuticals, Digna Biotech, AbbVie Corporation, Boehringer Ingelheim, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti-Inflammatory Peptides Market Strategic Shifts
Anti-inflammatory peptide development is pivoting toward multifunctional constructs that simultaneously engage multiple cytokine targets, departing from single-mechanism approaches that dominated earlier therapeutic generations.
Multivalent peptide architectures incorporating dual cytokine-binding domains are converging with advances in computational protein design to enable rational engineering of bispecific immunomodulators. Large pharmaceutical sponsors in the United States and Germany are advancing these candidates through preclinical toxicology studies at accelerated pace compared to traditional monoclonal antibody programs. This convergence is compressing early-stage development timelines and expanding the addressable patient population beyond responders to existing biologic therapies.
EMA's Medical Device Regulation framework is tightening quality management system requirements for combination products involving peptide-filled auto-injectors and prefilled syringes. Manufacturers must now demonstrate device-drug interaction stability across shelf life, adding analytical burden but reducing post-market safety incidents. Injectable peptide formulations for home administration face the steepest compliance curve, with sponsors in Switzerland and the Netherlands investing in dedicated combination product development teams.
Hospital pharmacy committees are consolidating formularies around peptide therapeutics with demonstrated disease-modifying outcomes, displacing chronic corticosteroid prescribing in rheumatology and gastroenterology departments. This preference shift favors sponsors with robust health economics evidence and patient support programs over those competing on unit cost alone. The United States and Japan exhibit the most pronounced consolidation, with integrated delivery networks negotiating outcomes-based contracts for inflammatory bowel disease peptide therapies.
Anti-Inflammatory Peptides Market Segmentation
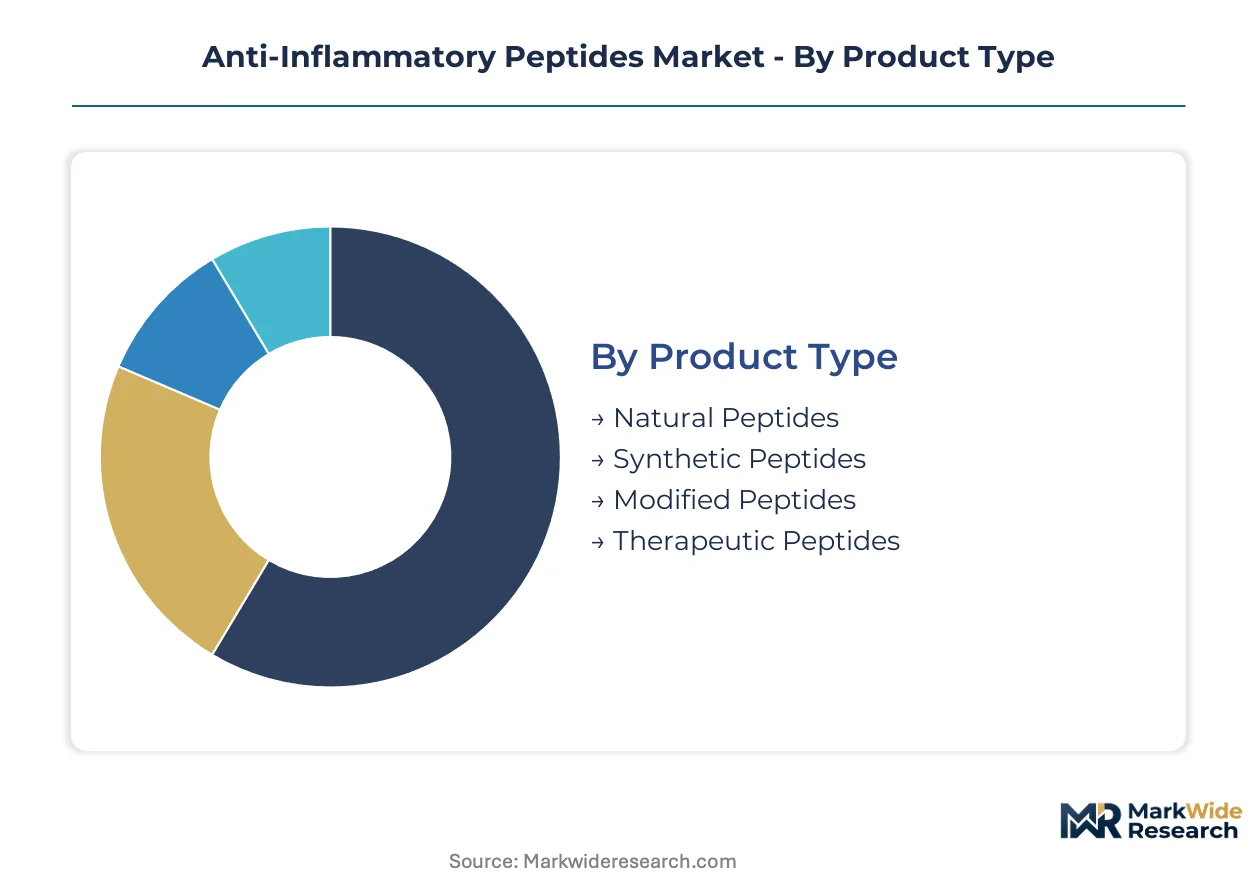
Anti-inflammatory peptide segmentation reveals distinct value pools across molecular architectures, therapeutic targets, and administration routes. Manufacturers configure production assets and regulatory strategies differently for each segment combination.
Product Type:
Natural peptides operate as standalone biologic extracts, while synthetic and modified variants embed into precision-engineered therapeutic platforms with defined impurity profiles and extended half-lives.
- Natural Peptides:Isolated from biological sources including marine organisms and plant proteins, these sequences retain native post-translational modifications. Demand concentrates in Germany and Japan where specialized extraction facilities serve nutraceutical and research applications; supply variability limits pharmaceutical-grade adoption.
- Synthetic Peptides:Solid-phase and solution-phase chemistry produce defined sequences with reproducible quality attributes. United States pharmaceutical sponsors drive volume for autoimmune disorder candidates; FDA biologics licensing pathways favor synthetic routes for IND submissions due to characterization clarity.
- Modified Peptides:Structural alterations including D-amino acid substitutions and PEGylation enhance protease resistance and plasma half-life.
- Therapeutic Peptides:Clinical-grade candidates manufactured under ICH Q7 GMP guidelines for inflammatory indications.
Volume placements concentrate in Synthetic Peptides; the faster expansion belongs to Modified Peptides.
Application:
Application segments stratify by unmet medical need intensity, with disease-modifying therapies commanding premium pricing over symptomatic relief.
- Chronic Inflammation:Long-duration conditions including rheumatoid arthritis and inflammatory bowel disease require sustained peptide modulation of cytokine cascades. United States integrated delivery networks negotiate outcomes-based contracts for these indications; hospital pharmacy committees prioritize disease-modifying evidence over corticosteroid alternatives.
- Autoimmune Disorders:Peptide immunomodulators target T-cell activation and B-cell signaling in lupus, multiple sclerosis, and type 1 diabetes. Germany's Heidelberg and Munich biotech clusters anchor preclinical development; EMA's centralized procedure accelerates market access across member states.
- Pain Relief:Short-acting peptides for acute and neuropathic pain management compete with established NSAID and opioid standards.
- Skin Conditions:Topical peptide formulations address psoriasis, atopic dermatitis, and wound healing.
Autoimmune Disorders capture the steepest pricing premiums; Chronic Inflammation maintains the broadest addressable patient base.
End User:
End user segments diverge by technical capability, with fully integrated pharmaceutical sponsors contrasting against outsourced development models.
- Pharmaceutical Companies:Large sponsors including Novartis AG and AbbVie Corporation maintain captive peptide synthesis platforms for pipeline candidates. Internal manufacturing preserves intellectual property control and accelerates Phase III timelines; these firms drive demand for multi-kilogram GMP batches.
- Research Institutions:Academic and government laboratories purchase gram-scale quantities for mechanistic studies and early proof-of-concept work. Heidelberg University and Tokyo Institute of Technology peptide chemistry groups influence downstream commercial licensing.
- Healthcare Providers:Hospital systems and specialty clinics administer approved peptide therapeutics.
- Biotechnology Firms:Venture-backed developers outsource manufacturing to CDMOs with integrated solid-phase synthesis and fermentation capabilities.
Procurement volumes cluster with Pharmaceutical Companies; Biotechnology Firms are expanding most quickly as pipeline candidates advance.
Delivery Mode:
Delivery mode selection determines formulation complexity, patient compliance economics, and competitive differentiation against oral small molecules.
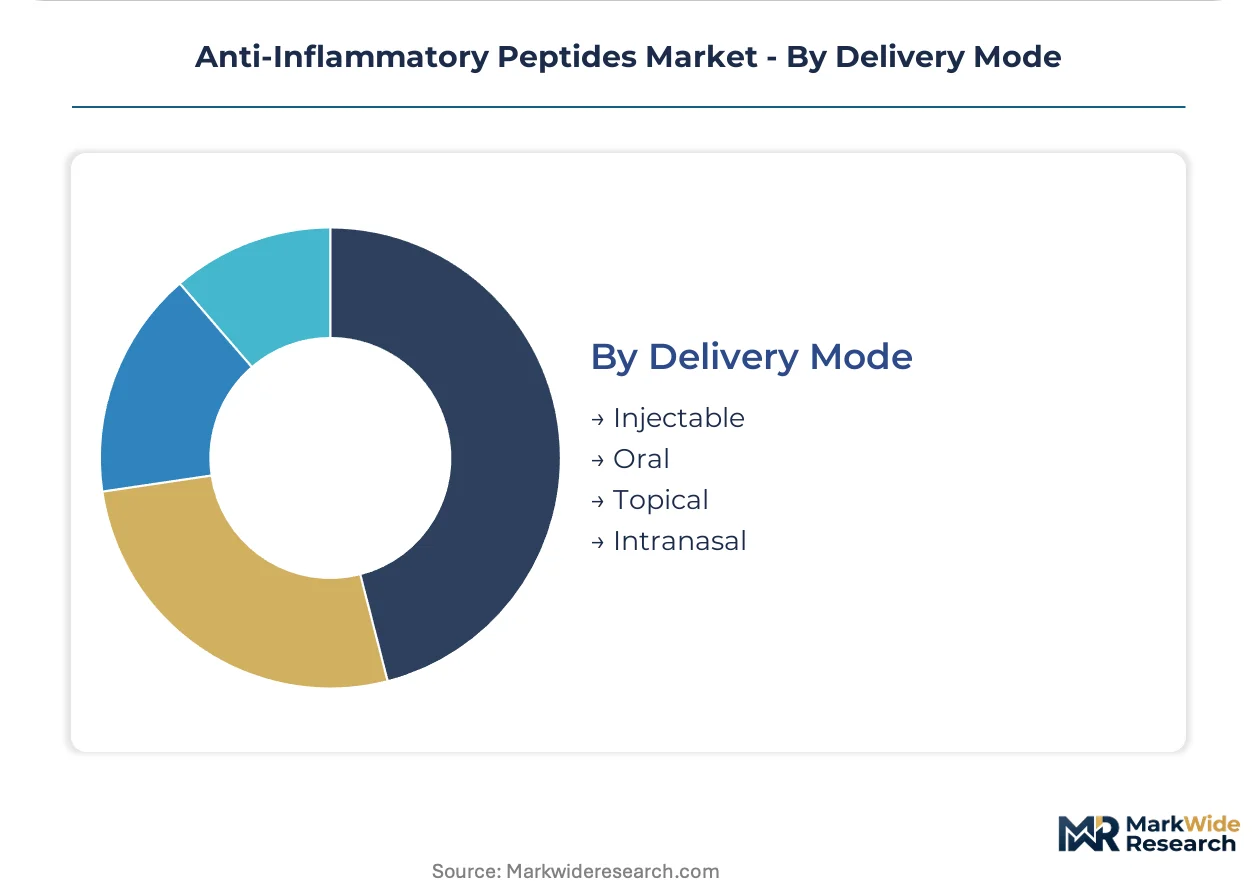
- Injectable:Subcutaneous and intravenous routes dominate current commercial peptides, bypassing gastrointestinal degradation. Prefilled syringes and auto-injector combination products face EMA MDR compliance requirements; Switzerland and Netherlands manufacturers invest in dedicated device-drug stability programs.
- Oral:Enzymatic degradation and poor permeation across intestinal epithelium constrain bioavailability. PEGylation and permeation enhancer advances in United States and Japan laboratories pursue viable enteric formulations; patient preference sustains development investment despite technical barriers.
- Topical:Dermal and transdermal administration targets localized inflammation with reduced systemic exposure.
- Intranasal:Mucosal delivery offers rapid systemic absorption and potential central nervous system access.
Injectable formulations retain dominant volume share; Oral delivery is gaining share fastest as formulation science advances.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Protected amino acid suppliers in Germany and Japan anchor the upstream peptide synthesis supply chain, while downstream formulation capacity clusters around FDA-regulated sites in the United States and PMDA-authorized facilities in Japan.
United States
FDA biologics licensing pathways accelerate IND-to-BLA timelines for autoimmune disorder candidates, drawing sponsor investment toward Boston and San Francisco biotech corridors. Integrated delivery networks in these metropolitan areas negotiate outcomes-based contracts for inflammatory bowel disease therapies, prioritizing disease-modifying evidence over corticosteroid alternatives.
Germany
Heidelberg and Munich biotech clusters concentrate specialized peptide chemistry talent and analytical capabilities that attract multinational sponsor investment. EMA's centralized procedure accelerates market access across member states, while Baden-Württemberg-based CDMOs expand GMP-compliant solid-phase synthesis capacity for Phase III candidates.
Japan
PMDA's Sakigake designation system offers priority review and early reimbursement for innovative peptide therapeutics addressing rheumatoid arthritis and inflammatory bowel disease. Tokyo and Osaka pharmaceutical sponsors leverage this regulatory pathway to compress development timelines, with Kanto-region manufacturing sites specializing in PEGylation chemistry for extended half-life formulations.
Switzerland
Swissmedic oversees combination product approvals for peptide-filled auto-injectors and prefilled syringes, with Basel-area manufacturers investing in dedicated device-drug stability programs. The country's precision engineering heritage supports advanced formulation development for subcutaneous administration routes.
Netherlands
Amsterdam and Rotterdam CDMOs specialize in continuous flow peptide synthesis platforms that reduce solvent consumption and batch-to-batch variability compared to traditional batch reactors. EMA MDR framework compliance for injectable formulations drives investment in analytical method development capabilities across Dutch manufacturing sites.
Anti-Inflammatory Peptides Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue modified peptide architectures with enhanced protease resistance and plasma half-life extension. The market structures around three tiers: integrated pharmaceutical sponsors with captive synthesis platforms, specialized CDMOs with multi-kilogram GMP capacity, and venture-backed biotechnology firms outsourcing manufacturing. Competitive dynamics center on capacity expansion for solid-phase synthesis and fermentation capabilities, alongside strategic partnerships to secure qualified chromatography media supply.
Among Swiss and German integrated sponsors, Novartis AG and Boehringer Ingelheim occupy positions representing the captive manufacturing archetype, while AbbVie Corporation exemplifies the biologic pipeline diversification strategy into peptide-based immunomodulators. These entities anchor the premium tier through control of quality across development stages, with their geographic concentration reflecting the historical depth of European peptide chemistry expertise.
| Leading Market Players |
|---|
| Novartis AG |
| Mylan Pharmaceuticals |
| Rogne Bioscience |
| Merck Serono |
| F4 Pharma |
| Araim Pharmaceuticals |
| Digna Biotech |
| AbbVie Corporation |
| Boehringer Ingelheim |
| Others |
Value Chain & Pricing Dynamics
EMA MDR sustainability mandates for combination product packaging gate qualified supplier status and premium-tier pricing access for peptide-filled auto-injectors, compressing margins for manufacturers lacking validated device-drug stability programs while rewarding Swiss and Netherlands sponsors with dedicated analytical teams.
Pricing Analysis
Service bundling separates peptide therapeutic pricing tiers, with United States integrated delivery networks negotiating outcomes-based contracts that wrap patient support programs and biomarker testing into premium autoimmune disorder therapies. Three-tier pricing structure across premium, standard, and economy levels stratifies by GMP certification grade and PEGylation complexity. Pricing pressure stems from amino acid feedstock volatility and single-source chromatography resin dependencies. Biotechnology firms outsourcing to CDMOs exhibit highest price sensitivity; captive manufacturing sponsors at Novartis AG and Boehringer Ingelheim command lowest.
Supply Chain Analysis
Specialized peptide chemistry workforce scarcity in Heidelberg and Munich constrains Baden-Württemberg CDMO expansion timelines for multi-kilogram GMP batches. Protected amino acid supply concentrates in Germany and Japan; reversed-phase chromatography media draws from limited qualified vendors. Single-source resin vulnerability creates regulatory restriction exposure for global peptide supply chains. Distribution runs through pharmaceutical sponsor captive platforms and specialized CDMO direct-to-sponsor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Anti-inflammatory peptide manufacturing capacity is supply-constrained by analytical method development workforce shortages, propping pricing power for sponsors with in-house mass spectrometry expertise.
For Market Incumbents: Extend captive synthesis platform coverage into PEGylation chemistry to defend against emerging modified peptide specialists. Secure long-term chromatography media supply agreements to offset single-source resin vulnerability. Add continuous flow manufacturing capacity in Netherlands or Switzerland to reduce batch variability and sustain premium positioning. For New Entrants and Emerging Players: Computational protein design capabilities offer entry wedge into bispecific immunomodulator development, where large pharmaceutical sponsors compress timelines. Target oral bioavailability formulation partnerships in United States and Japan laboratories as the most penetrable white space. Pursue PMDA Sakigake designation pathway for rheumatoid arthritis candidates to accelerate reimbursement access. For Investors and Strategic Acquirers: CDMO acquisition announcements from pharmaceutical sponsors is the leading indicator that manufacturing capacity scarcity is reaching inflection. Five-to-ten year viability favors platforms combining solid-phase synthesis with device-drug combination expertise. Monitor EMA MDR compliance certification timelines as signal for qualified supply scarcity premium.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Multi-kilogram GMP capacity expansion at Heidelberg CDMOs accelerates Phase III peptide supply. |
| Regulatory Approval Pathway | PMDA Sakigake designation compresses rheumatoid arthritis peptide development timelines in Japan. |
| Backward Integration | Captive protected amino acid synthesis insulates Novartis AG from petrochemical feedstock volatility. |
| Strategic Partnership | Companion diagnostic collaborations improve autoimmune disorder trial response rates and pricing power. |
| Pipeline Diversification | AbbVie Corporation's peptide immunomodulator expansion reduces corticosteroid displacement risk. |
Study Parameters
Multi-period observation of FDA biologics licensing submission volumes and EMA centralized procedure approval timelines anchored the trend analysis, supplemented by interviews with peptide chemistry group directors at Heidelberg University and Tokyo Institute of Technology, regulatory affairs leads at Swissmedic, formulary directors at United States integrated delivery networks, and CDMO procurement managers at Baden-Württemberg manufacturing sites. Secondary validation drew from FDA IND and BLA filings, EMA scientific advice outcomes, ClinicalTrials.gov peptide immunotherapy entries, and ICH Q7 GMP inspection observations. Bottom-up patient population modeling and top-down pharmaceutical sponsor pipeline valuation triangulated market sizing.
Segment-weighting across product type, application, end user, and delivery mode dimensions shaped the analytical framework over the projection horizon. CAGRs derived from therapeutic peptide volume trajectories, pricing elasticity by autoimmune indication severity, and PEGylation chemistry adoption curves. Modeled inputs included PMDA Sakigake designation success rates and continuous flow synthesis platform penetration at Netherlands CDMOs.
Several conditions sit outside the modeled scope, including biosimilar competition thresholds for peptide therapeutics and pharmacovigilance obligation expansion beyond current FDA and EMA frameworks. Forecasts reflect assumptions about regulatory pathway stability and amino acid feedstock pricing normalization. Material deviation in chromatography media supply consolidation or ICH Q7 interpretation variance warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutraceuticals
Phosphatidylserine Market
Nutraceuticals
Europe Nutricosmetics Market
Nutraceuticals
Healthy Care Coenzyme Q10 Market
Nutraceuticals
US and China Glucose Market
Nutraceuticals
Pycnogenol Market
Nutraceuticals
Piracetam Market
Nutraceuticals
Immunostimulants Market
Nutraceuticals
High Potency Apis Market
Nutraceuticals
Native Collagen Market
Nutraceuticals
Cordyceps Sinensis and Militaris Market
Nutraceuticals
PMS and Menstrual Health Supplements Market
Nutraceuticals
Levocarnitine Market
Nutraceuticals
North America Nutraceuticals Market
Nutraceuticals
Eggshell Membrane Market
Nutraceuticals
Europe Collagen Peptide Products Market
Nutraceuticals
Magtein Market