
 Diabetic Macular Edema Treatment Market | 2026-2036
Diabetic Macular Edema Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Diabetic Macular Edema Treatment Market Analysis
The EU Green Deal is pivoting pharmaceutical manufacturing toward lower-carbon active pharmaceutical ingredient production, and this sustainability mandate is reshaping supplier qualification for retinal therapies. Novartis AG leverages its integrated biologics manufacturing network to sustain corticosteroid supply security across European markets. Regeneron Pharmaceuticals anchors its competitive position through specialized anti-VEGF research infrastructure in the United States. Bayer AG competes on manufacturing scale for sustained-release ophthalmic implants, while EyePoint Pharmaceuticals differentiates through proprietary micro-insert technology for extended drug delivery.
Diabetic macular edema treatment encompasses pharmacological and procedural interventions targeting vascular endothelial growth factor-mediated blood-retinal barrier breakdown, with intravitreal anti-VEGF agents requiring monthly or bimonthly 0.05 mL injections into the vitreous cavity to reduce central retinal thickness. The primary purpose is preserving visual acuity in diabetic patients by suppressing macular fluid accumulation and preventing irreversible photoreceptor damage. Anti-VEGF biologics dominate value generation due to first-line guideline positioning, yet sustained-release corticosteroid delivery through intravitreal injection is capturing faster growth as physicians seek reduced treatment burden. Hospitals occupy the largest end-user share because of required optical coherence tomography infrastructure and sterile compounding capabilities, while ambulatory surgical centers are expanding fastest as office-based surgical licensure broadens.
The FDA maintains stringent ophthalmic biologics approval standards through its Center for Drug Evaluation and Research, while the EMA's MDR framework governs intraocular device safety profiles across European markets. Japan's PMDA imposes additional local clinical trial requirements that shape product launch sequencing and market access timelines for novel sustained-release formulations. Stakeholders must monitor biosimilar entry timelines and evolving real-world evidence requirements that will determine reimbursement positioning for next-generation combination therapies.
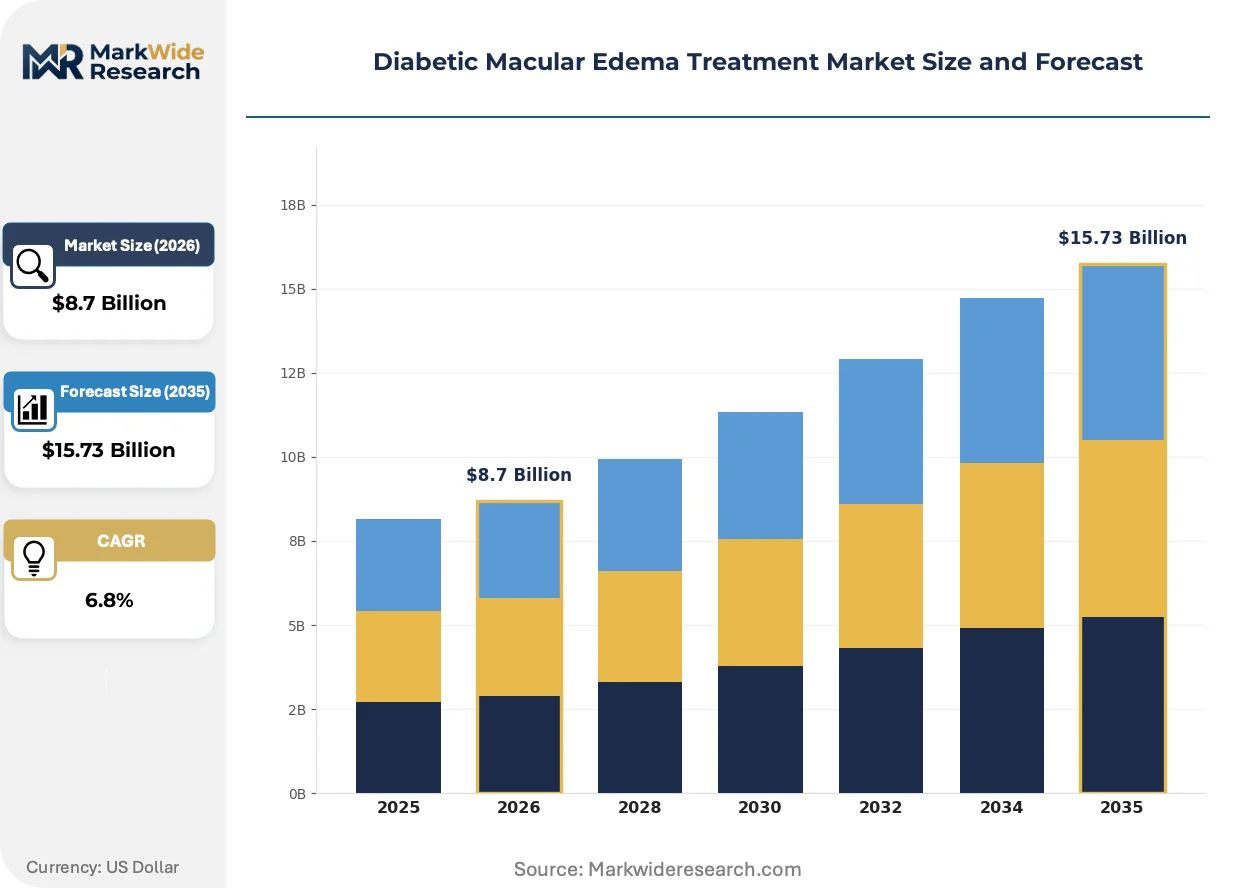
Market Dynamics
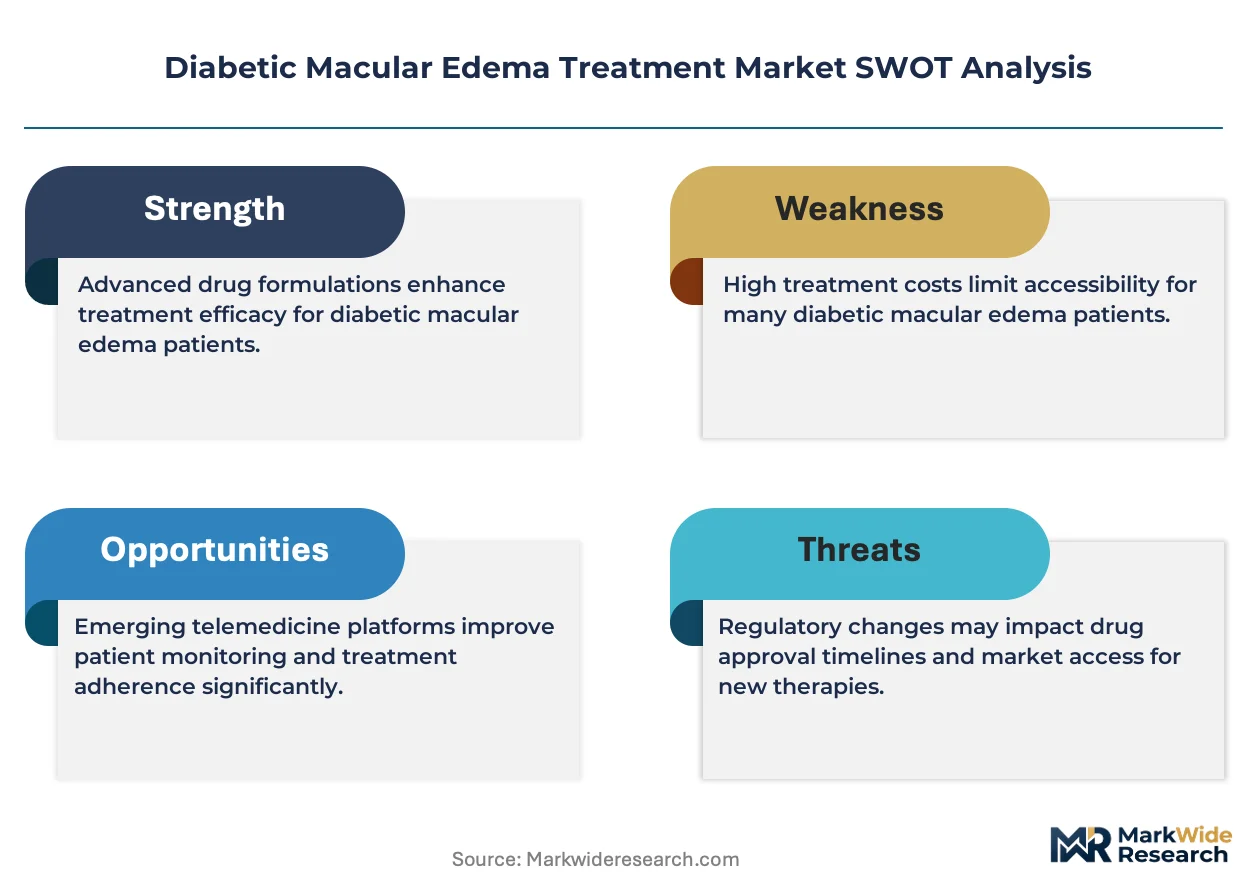
Anti-VEGF therapy's monthly injection burden is driving physician preference toward sustained-release alternatives, compressing treatment frequency while expanding addressable patient pools through improved adherence.
Growth Catalysts
- EU Green Deal sustainability mandates:The EU Green Deal is accelerating low-carbon active pharmaceutical ingredient production qualification, opening procurement pathways for European manufacturers meeting carbon-intensity thresholds.
- Ambulatory surgical center licensure expansion:Office-based surgical licensure broadening across United States states is shifting intravitreal injection capacity from hospital settings, reducing overhead and patient travel friction.
- Optical coherence tomography infrastructure:Hospital-based ophthalmology departments are expanding diagnostic throughput, enabling earlier DME detection and expanding treatable case volumes.
Market Restraints
- Corticosteroid supply concentration:European manufacturing networks for sustained-release implants face single-source dependencies, creating vulnerability to EMA inspection-driven supply interruptions.
- Intravitreal injection technical limitation:The 0.05 mL dosing precision requirement and sterile compounding complexity limit compounding pharmacy participation, constraining point-of-care flexibility.
- Biosimilar regulatory friction:FDA ophthalmic biologics approval standards and EMA MDR framework divergence create dual-track development costs, delaying market entry for follow-on anti-VEGF products.
Strategic Opportunities
- Japan local clinical trial requirements:PMDA's additional trial mandates, while lengthening launch timelines, create first-mover data advantages for sustained-release formulations completing Japanese development.
- Extended drug delivery technology convergence:Proprietary micro-insert platforms combined with anti-VEGF biologics offer combination therapy pathways beyond monotherapy guidelines.
- Real-world evidence reimbursement positioning:Evolving payer requirements for next-generation combination therapies create opportunity for manufacturers investing in post-market outcome databases.
Industry Challenges
- Vitreoretinal surgeon training pipeline:The specialized skill set for pars plana injection technique faces generational shortage, constraining treatment capacity expansion regardless of facility infrastructure investment.
- MDR certification timeline compression:European intraocular device safety profile documentation requirements are extending conformity assessment durations, delaying product refresh cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Diabetic Macular Edema Treatment Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Anti-VEGF, Corticosteroids, Laser Surgery, Other Therapies Delivery Mode: Intravitreal Injection, Oral, Topical, Others End User: Hospitals, Clinics, Ambulatory Surgical Centers, Homecare Settings Therapy Area: Ophthalmology, General Medicine, Palliative Care, Geriatrics |
| Companies Covered | Novartis AG, F. Hoffmann-La Roche AG, Regeneron Pharmaceuticals, Bayer AG, EyePoint Pharmaceuticals, Oculis, Oxurion, Alimera Sciences, Kodiak Sciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Diabetic Macular Edema Treatment Market Emerging Trajectories
Sustained-release drug delivery platforms are compressing the treatment burden paradigm while regulatory divergence between FDA and EMA pathways is reshaping development sequencing priorities.
Port delivery systems with refillable reservoirs are automating anti-VEGF administration intervals, extending from monthly to semi-annual maintenance. Retina specialists in high-volume United States practices are piloting these implants at accelerating pace. The technology is automating patient adherence management while reducing clinic injection capacity constraints.
EMA's MDR framework for intraocular device safety profiles is tightening post-market surveillance requirements across European markets. Manufacturers must now maintain active implant registries beyond initial CE marking. Sustained-release corticosteroid categories face the steepest compliance cost escalation, favoring larger players with dedicated regulatory affairs infrastructure.
After-sales service unbundling is separating diagnostic imaging from therapeutic administration in German and Japanese reimbursement structures. Ambulatory surgical centers are capturing the procedural revenue while hospital ophthalmology departments retain optical coherence tomography interpretation. United States Medicare Advantage plans are piloting similar carve-outs, compressing integrated service margins.
Diabetic Macular Edema Treatment Market Segmentation
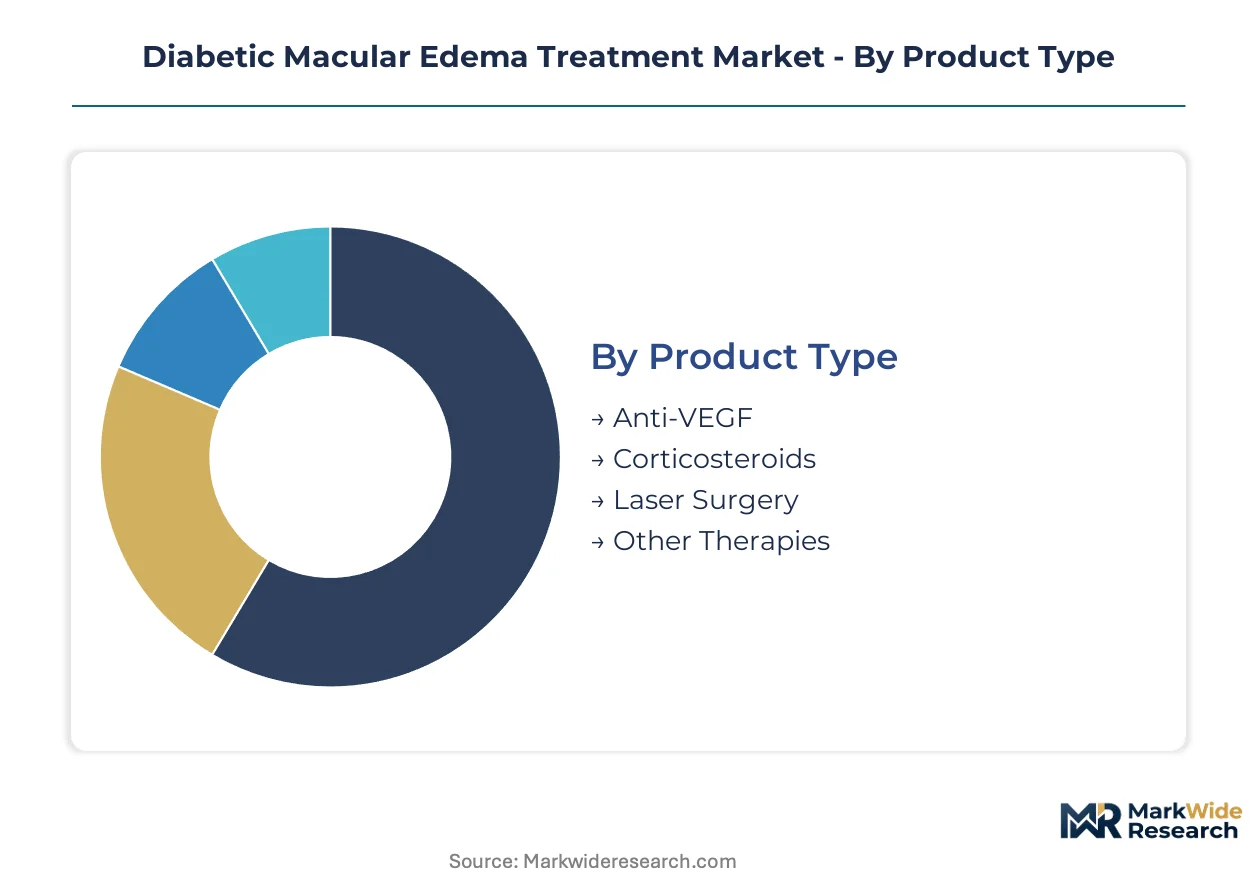
Treatment modality selection in diabetic macular edema hinges on vascular leakage severity, patient injection tolerance, and reimbursement tier positioning across institutional settings. Segmentation reveals how anti-VEGF dominance coexists with sustained-release alternatives gaining procedural share, while site-of-care economics reshape channel distribution.
Product Type:
Mechanism of action determines reimbursement tiering and treatment frequency economics in physician practice patterns.
- Anti-VEGF:Intravitreal biologics targeting vascular endothelial growth factor-A suppress pathological neovascularization and reduce central retinal thickness through monthly or bimonthly 0.05 mL injections. United States retina specialists anchor first-line prescribing around ranibizumab and aflibercept protocols, though biosimilar entry is compressing originator pricing power in Medicare Part B reimbursement.
- Corticosteroids:Sustained-release dexamethasone and fluocinolone acetonide implants deliver corticosteroid to the vitreous cavity over 3-36 month intervals, addressing treatment burden fatigue in injection-averse patient populations. German statutory health insurance frameworks have matured reimbursement for implantable sustained-release categories faster than Southern European markets.
- Laser Surgery:Focal and grid photocoagulation ablates leaking microaneurysms through thermal energy application, retaining utility in pseudophakic patients with contraindications to pharmacotherapy.
- Other Therapies:Investigational neuroprotective agents and anti-inflammatory modulators occupy pipeline positioning ahead of pivotal trial readouts.
Anti-VEGF leads on scale; corticosteroids lead on momentum.
Delivery Mode:
Route of administration dictates sterile infrastructure requirements and point-of-care economics across treatment settings.
- Intravitreal Injection:Direct 0.05 mL delivery into the vitreous cavity via pars plana puncture demands optical coherence tomography guidance, sterile compounding, and vitreoretinal surgical training. Japanese ambulatory surgical centers are expanding injection capacity faster than hospital ophthalmology departments as PMDA streamlines office-based surgical licensure.
- Oral:Systemic anti-VEGF and corticosteroid formulations remain investigational, with bioavailability challenges limiting clinical translation despite patient preference for non-invasive routes.
- Topical:Eye drop formulations targeting blood-retinal barrier permeability are advancing through early-phase trials in United States academic medical centers.
- Others:Periocular and sub-Tenon's injection methods offer intermediate invasiveness profiles for selected patient subgroups.
Intravitreal injection commands volume concentration; oral routes represent the steepest expansion trajectory contingent on bioavailability breakthroughs.
End User:
Facility type determines capital equipment thresholds, sterile processing capacity, and reimbursement rate differentials in site-of-care selection.
- Hospitals:Integrated optical coherence tomography infrastructure, emergency ophthalmology coverage, and complex case referral networks position hospital ophthalmology departments as the default setting for treatment-naive DME patients. United States Medicare fee-for-service reimburses hospital outpatient department injections at higher rates than competing sites.
- Clinics:Office-based retina practices with optical coherence tomography ownership capture stable patient follow-up volumes, though sterile compounding partnerships limit on-site injection autonomy.
- Ambulatory Surgical Centers:Dedicated ophthalmology ASCs in Florida and Texas are expanding intravitreal injection capacity through streamlined licensure, capturing procedural margin from hospital divestiture.
- Homecare Settings:Self-administered topical regimens and remote monitoring protocols remain experimental, with regulatory barriers to home injection administration.
Hospitals retain volume leadership; ambulatory surgical centers are climbing the fastest through site-of-care migration incentives.
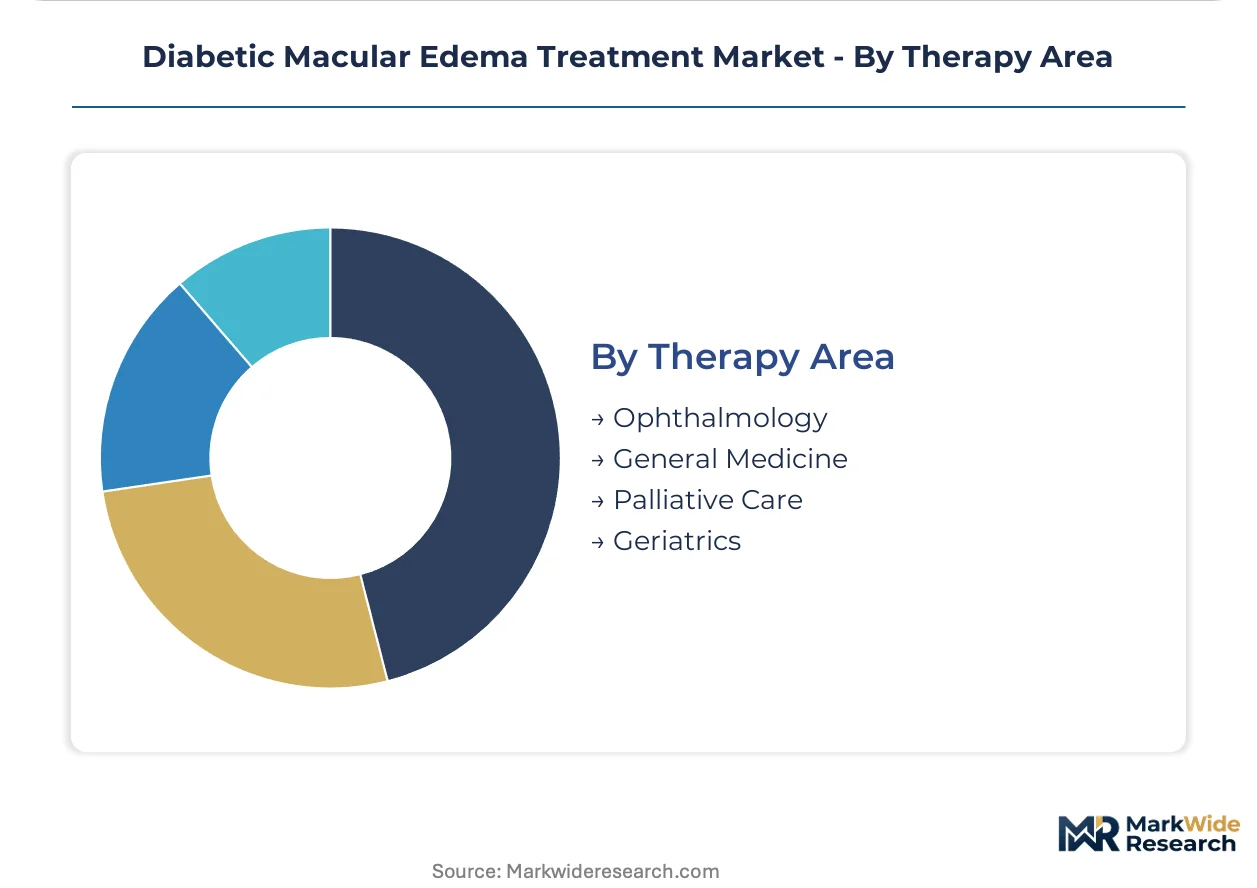
Therapy Area:
Specialist versus generalist prescribing authority shapes patient access velocity and treatment algorithm adherence.
- Ophthalmology:Vitreoretinal specialists and comprehensive ophthalmologists control intravitreal injection access, with fellowship-trained retina specialists capturing complex case referrals and sustained-release implant placement. German office-based ophthalmologists maintain broader injection privileges than United States counterparts.
- General Medicine:Primary care physicians and endocrinologists drive DME screening and referral generation, though therapeutic administration remains outside scope.
- Palliative Care:Comfort-focused visual preservation in advanced diabetic patients with limited life expectancy emphasizes low-burden treatment intervals.
- Geriatrics:Multimorbidity management in elderly diabetic populations prioritizes injection frequency reduction and transportation burden minimization.
Ophthalmology concentrates therapeutic decision authority; geriatrics is gaining share fastest through aging demographic tailwinds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Intravitreal anti-VEGF therapy originated in United States academic medical centers during the early 2000s, with German and Japanese hospital networks subsequently scaling optical coherence tomography-guided injection protocols. Regulatory divergence between FDA, EMA, and PMDA pathways now shapes commercial sequencing across major markets.
United States
Medicare Part B reimbursement anchors anti-VEGF prescribing volume, with retina specialists clustering in Florida and Texas ambulatory surgical centers. FDA's Center for Drug Evaluation and Research maintains stringent ophthalmic biologics approval standards that delay biosimilar entry. The Greater Boston corridor hosts specialized anti-VEGF research infrastructure driving sustained-release formulation innovation.
Germany
Statutory health insurance frameworks matured reimbursement for sustained-release corticosteroid implants faster than Southern European counterparts, expanding treatable case volumes in treatment-averse populations. EMA's MDR framework governs intraocular device safety documentation requirements, extending conformity assessment timelines. The Rhine-Ruhr metropolitan region concentrates hospital ophthalmology department investment in sterile compounding capacity.
Japan
PMDA's additional local clinical trial requirements shape product launch sequencing, creating first-mover data advantages for sustained-release formulations completing Japanese development. Aging demographic tailwinds expand geriatric ophthalmology demand in Kanto and Kansai regions. Tokyo-based vitreoretinal specialists pilot port delivery systems with refillable reservoirs at accelerating pace.
United Kingdom
NICE technology appraisals compress anti-VEGF pricing power through structured cost-effectiveness thresholds, shifting physician preference toward injection frequency reduction. MHRA post-Brexit regulatory autonomy enables divergence from EMA ophthalmic device timelines. London and Southeast England concentrate private ophthalmology clinic investment in optical coherence tomography infrastructure.
India
CDSCO streamlined biosimilar approval pathways accelerate follow-on anti-VEGF market entry, expanding access in price-sensitive patient populations. Maharashtra and Gujarat host expanding hospital ophthalmology department networks investing in intravitreal injection training programs. Mumbai-based retina specialists drive adoption of sustained-release alternatives among injection-burdened diabetic populations.
Diabetic Macular Edema Treatment Market Vendor Landscape
Capital-heavy integrated biologics manufacturers compete with asset-light formulation specialists in diabetic macular edema treatment supply. The market structure concentrates value generation among three strategic archetypes: diversified pharmaceutical conglomerates with captive manufacturing networks, mid-cap ophthalmology-focused developers with proprietary delivery platforms, and emerging biotechs advancing novel mechanism candidates. Competitive dynamics center on M&A activity capturing sustained-release technology assets and strategic partnerships securing optical coherence tomography diagnostic integration.
Within the diversified pharmaceutical tier, Novartis AG and Bayer AG occupy positions anchored by integrated manufacturing scale and European supply security. Regeneron Pharmaceuticals exemplifies the specialized biotech archetype with United States-based anti-VEGF research infrastructure. EyePoint Pharmaceuticals represents the delivery technology specialist segment, differentiated through micro-insert platform development for extended drug release applications.
| Leading Market Players |
|---|
| Novartis AG |
| F. Hoffmann-La Roche AG |
| Regeneron Pharmaceuticals |
| Bayer AG |
| EyePoint Pharmaceuticals |
| Oculis |
| Oxurion |
| Alimera Sciences |
| Kodiak Sciences |
| Others |
Supply Flow & Price Mechanics
EU Green Deal carbon-intensity thresholds gate qualified supply for sustained-release corticosteroid implants, with manufacturers meeting lower-carbon active pharmaceutical ingredient production standards commanding premium-tier pricing access across European markets while non-compliant suppliers face procurement exclusion.
Pricing Analysis
Three-tier pricing structure across originator biologics, biosimilars, and sustained-release implants segments the diabetic macular edema treatment market by reimbursement tier and treatment frequency economics. Price differentiation hinges on FDA approval pathway positioning and optical coherence tomography diagnostic bundling in hospital outpatient settings. Cost compression in the biosimilar tier is intensifying because Medicare Part B reimbursement parity erodes originator margin protection. Ambulatory surgical centers exhibit highest price sensitivity due to carve-out reimbursement rates, while hospital ophthalmology departments retain lowest sensitivity through integrated service margins.
Supply Chain Analysis
Vitreoretinal surgeon training pipeline constraints in United States, German, and Japanese manufacturing geographies limit sterile compounding capacity expansion regardless of facility infrastructure investment. Active pharmaceutical ingredient production draws from Swiss and Irish chemical manufacturing networks, while finished dose formulation rests on Italian and German sterile fill-finish capabilities. Single-source dependencies for dexamethasone implant polymers create vulnerability to EMA inspection-driven supply interruptions. Distribution runs through hospital pharmacy procurement and ambulatory surgical center direct purchasing channels with diverging contract structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The diabetic macular edema treatment market compounds steadily as aging diabetic populations expand addressable patient pools across developed economies. Anti-VEGF therapy's monthly injection burden sustains demand for sustained-release alternatives with superior adherence profiles.
For Market Incumbents: Extend manufacturing scale advantages in corticosteroid implant categories through backward integration into polymer reservoir production, securing supply continuity against EMA MDR certification delays. Deepen optical coherence tomography diagnostic partnerships with hospital ophthalmology departments to anchor referral capture against ambulatory surgical center site-of-care migration. Prioritize real-world evidence database investment to defend reimbursement positioning against biosimilar pricing pressure. For New Entrants and Emerging Players: Capture white-space opportunity in Japanese sustained-release formulation development, where PMDA local clinical trial requirements create first-mover data advantages for completing registrational studies. Target geriatric ophthalmology segments in Kanto and Kansai regions where aging demographics concentrate injection-burdened patient populations. Pursue port delivery system licensing partnerships with Tokyo-based vitreoretinal specialists to accelerate clinical validation. For Investors and Strategic Acquirers: Roll-up economics work for delivery technology specialists because proprietary micro-insert platforms command scarcity premiums in extended drug release applications where large pharmaceutical manufacturers lack internal capabilities. Five-to-ten year viability frames around sustained-release convergence with anti-VEGF biologics for combination therapy positioning. Monitor biosimilar entry timelines as inflection indicator for originator pricing power erosion and sustained-release alternative acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA ophthalmic biologics standards delay biosimilar entry, extending originator exclusivity windows. |
| Manufacturing Scale-Up | EMA MDR framework compliance favors larger players with dedicated regulatory affairs infrastructure. |
| Strategic Partnership | Optical coherence tomography diagnostic integration anchors hospital referral capture against site migration. |
| Pipeline Diversification | Extended drug delivery technology convergence opens combination therapy pathways beyond monotherapy guidelines. |
| Reimbursement Strategy | Real-world evidence investment determines payer positioning for next-generation combination therapies. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with vitreoretinal surgeons, hospital pharmacy directors, regulatory affairs specialists at EMA-notified bodies, and payer access managers with secondary validation through FDA 510(k) filings, EMA marketing authorization applications, ClinicalTrials.gov registry data, and Medicare Part B claims databases. Bottom-up patient volume modeling and top-down manufacturer revenue triangulation anchored market size estimation.
Segment-weighting approaches distributed value across anti-VEGF biologics, corticosteroid implants, and laser surgery modalities by treatment line, administration route, and regional regulatory cluster over the projection horizon. CAGRs derived from procedure volume trajectories and pricing evolution assumptions. Forecast inputs incorporated optical coherence tomography infrastructure expansion rates and ambulatory surgical center licensure policy changes across United States state jurisdictions.
Underlying measurement precision varies by segment; anti-VEGF biologics carry tighter precision than emerging sustained-release categories where product launch timing uncertainty persists. Forecasts reflect documented assumptions regarding biosimilar entry velocity and reimbursement tier stability. Material deviation in PMDA trial requirement enforcement or EMA MDR certification timeline compression warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Vitreous Detachment Treatment Market
Ophthalmology
North America Ophthalmic Devices and Drugs Market
Ophthalmology
Optic Nerve Glioma Market
Ophthalmology
Corneal Ulcer Treatment Market
Ophthalmology
Macular Edema and Macular Degeneration Market
Ophthalmology
Global Fundus Cameras Market
Ophthalmology
Europe Dry Eye Syndrome Market
Ophthalmology
Blepharitis Treatment Market
Ophthalmology
Head Band Ophthalmoscopes Market
Ophthalmology
Coloured Contact Lenses Market
Ophthalmology
Global Diabetic Macular Edema Market
Ophthalmology
Global Macular Degeneration Treatment Market
Ophthalmology
India Ophthalmology Devices Market
Ophthalmology
Choroidal Neovascularization Market
Ophthalmology
Non-Infectious Uveitis Treatment Market
Ophthalmology
Pseudotumor Cerebri Market