
 Pseudotumor Cerebri Market | 2026-2036
Pseudotumor Cerebri Market Size, Share, and Industry Trends Forecast 2026-2036
Pseudotumor Cerebri Market Outlook
Hospital procurement for pseudotumor cerebri care is narrowing around integrated neurology-ophthalmology service lines. Teva Pharmaceutical Industries leverages its generic acetazolamide portfolio to sustain volume leadership in oral diuretic therapy. Integra LifeSciences Corporation specializes in cerebrospinal fluid shunt systems that anchor its position in invasive surgical intervention. Johnson & Johnson competes across the care continuum through its Ethicon and Acclarent divisions.
Pseudotumor cerebri, or idiopathic intracranial hypertension, involves elevated intracranial pressure without mass lesion, typically presenting with papilledema and headache in obese women of childbearing age. Diagnostic confirmation requires lumbar puncture with elevated opening pressure plus neuroimaging to exclude secondary causes, with the primary clinical purpose being prevention of permanent vision loss through pressure reduction. Medications dominate current therapy expenditure due to first-line acetazolamide prescribing, while surgical treatments command premium positioning where rapid visual decline demands shunt placement or optic nerve sheath fenestration. Diagnostic devices represent the fastest-expanding segment as optical coherence tomography for retinal nerve fiber layer assessment displaces subjective fundoscopy in monitoring protocols.
The FDA oversees pharmaceutical approvals and medical device clearances through its Center for Drug Evaluation and Research and Center for Devices and Radiological Health, with orphan drug incentives shaping development economics for this low-prevalence indication. The EMA's parallel framework in Europe creates dual-jurisdiction complexity for sponsors pursuing transatlantic trials, while HIPAA governs real-world evidence collection that increasingly supports post-market surveillance. Stakeholders must monitor whether pressure from payers for outpatient management redirects investment toward homecare-compatible monitoring technologies.
Market Dynamics
Hospital neuro-ophthalmology departments are consolidating diagnostic workflows around optical coherence tomography, compressing subjective fundoscopy protocols and reshaping equipment procurement patterns across tertiary care networks.
Growth Catalysts
- Orphan Drug Incentives:The FDA's accelerated approval pathway reduces development timelines for low-prevalence neurological indications, attracting sponsor investment into novel intracranial pressure modulators.
- Optical Coherence Tomography:Retinal nerve fiber layer assessment technology is displacing manual papilledema grading in academic medical centers, standardizing disease monitoring protocols.
- Specialized Headache Centers:United States urban clusters are concentrating diagnostic volumes and creating referral networks that drive procedure standardization.
Market Restraints
- Acetazolamide Supply Concentration:Generic diuretic manufacturing concentrates among limited API suppliers, exposing oral therapy to price volatility and shortage risk.
- Shunt Revision Burden:Cerebrospinal fluid diversion devices require repeat surgical intervention in substantial patient cohorts, limiting long-term therapy economics.
- Diagnostic Access Disparities:Lumbar puncture with manometry demands specialized neurology infrastructure unavailable in community hospital settings.
Strategic Opportunities
- Home Intracranial Pressure Monitoring:Telemedicine-compatible wearable sensors create ambulatory measurement protocols that reduce hospital dependency for chronic patients.
- EMA Parallel Pathways:European Medicines Agency orphan designation incentives offer dual-jurisdiction trial efficiency for sponsors pursuing transatlantic development.
- Optic Nerve Sheath Fenestration:Minimally invasive endoscopic approaches expand surgical candidacy beyond traditional shunt-dependent populations.
Industry Challenges
- Neuro-Ophthalmology Workforce Scarcity:Fellowship-trained specialists remain concentrated at academic institutions, constraining diagnostic capacity expansion.
- Real-World Evidence Collection:HIPAA compliance requirements complicate multi-site patient registry assembly for post-market surveillance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pseudotumor Cerebri Market |
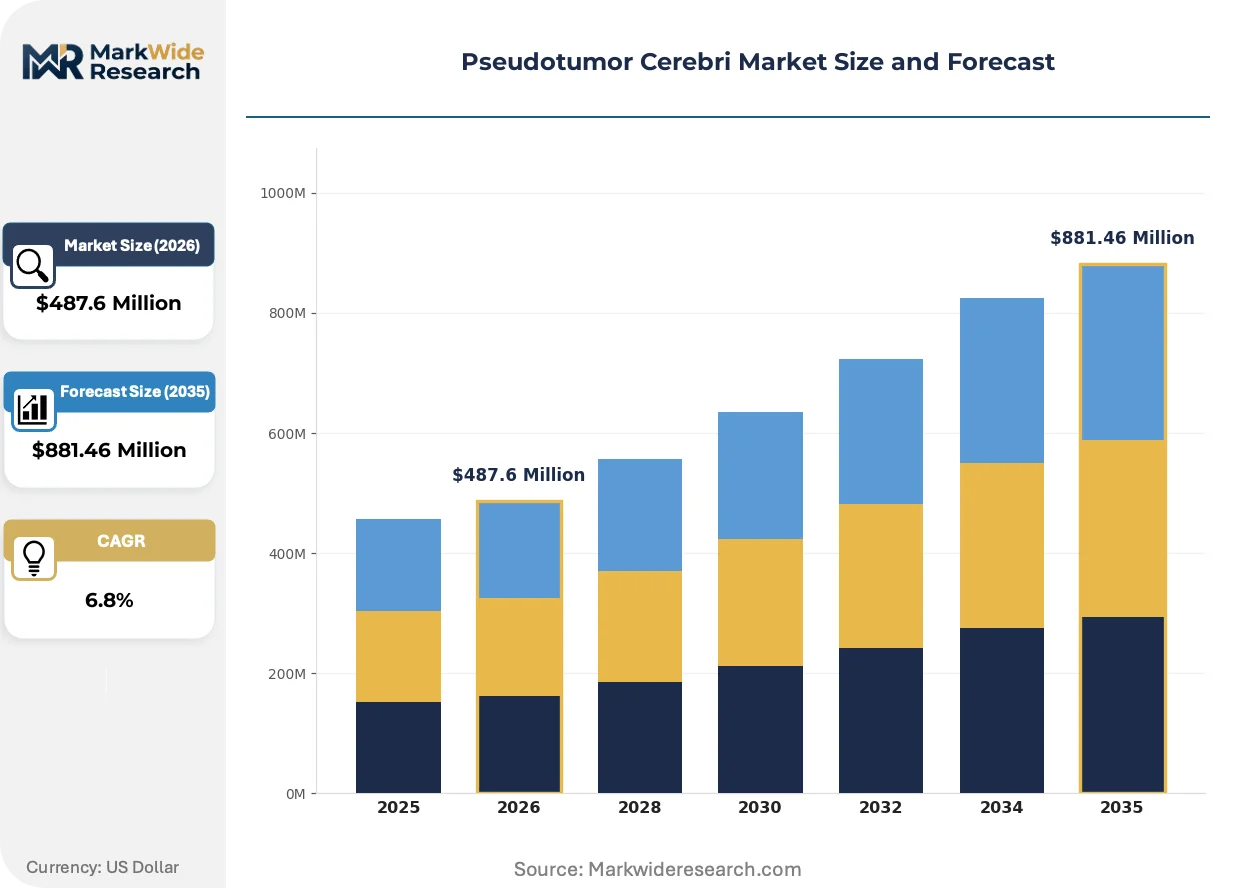
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medications, Surgical Treatments, Diagnostic Devices, Monitoring Equipment Therapy Area: Neurology, Ophthalmology, Pain Management, Critical Care Delivery Mode: Oral, Intravenous, Topical, Invasive Procedures End User: Hospitals, Clinics, Research Institutes, Homecare Settings |
| Companies Covered | Avkare Inc., B. Braun Melsungen AG, Integra LifeSciences Corporation, Johnson & Johnson, Elekta AB, Teva Pharmaceutical Industries Ltd., Beckersmith Medical Inc., Heritage Pharmaceuticals Inc., Ingenus Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pseudotumor Cerebri Market Strategic Shifts
Diagnostic technology convergence with telemedicine infrastructure is redrawing care delivery boundaries, while regulatory incentives reshape therapeutic development economics for this low-prevalence neurological indication.
Spectral-domain optical coherence tomography is hybridizing quantitative retinal nerve fiber layer analysis with artificial intelligence-assisted progression detection. Academic medical centers in the United States are adopting these platforms at accelerating cadence. The technology is compressing subjective clinician assessment cycles and enabling remote monitoring protocols that extend specialist reach beyond physical clinic boundaries.
The FDA's orphan drug designation pathway is accelerating sponsor investment into novel carbonic anhydrase inhibitors and intracranial pressure modulators. Development economics for low-prevalence indications improve through tax credits and market exclusivity provisions. Small-to-mid-cap pharmaceutical sponsors are responding by prioritizing pseudotumor cerebri programs within rare disease portfolios.
Integrated neurology-ophthalmology service lines are consolidating procurement authority under unified department budgets. Equipment vendors face consolidated purchasing committees that bundle diagnostic devices with surgical platforms. This concentration is most visible in United States metropolitan hospital systems where service line restructuring precedes capital allocation decisions.
Pseudotumor Cerebri Market Segmentation
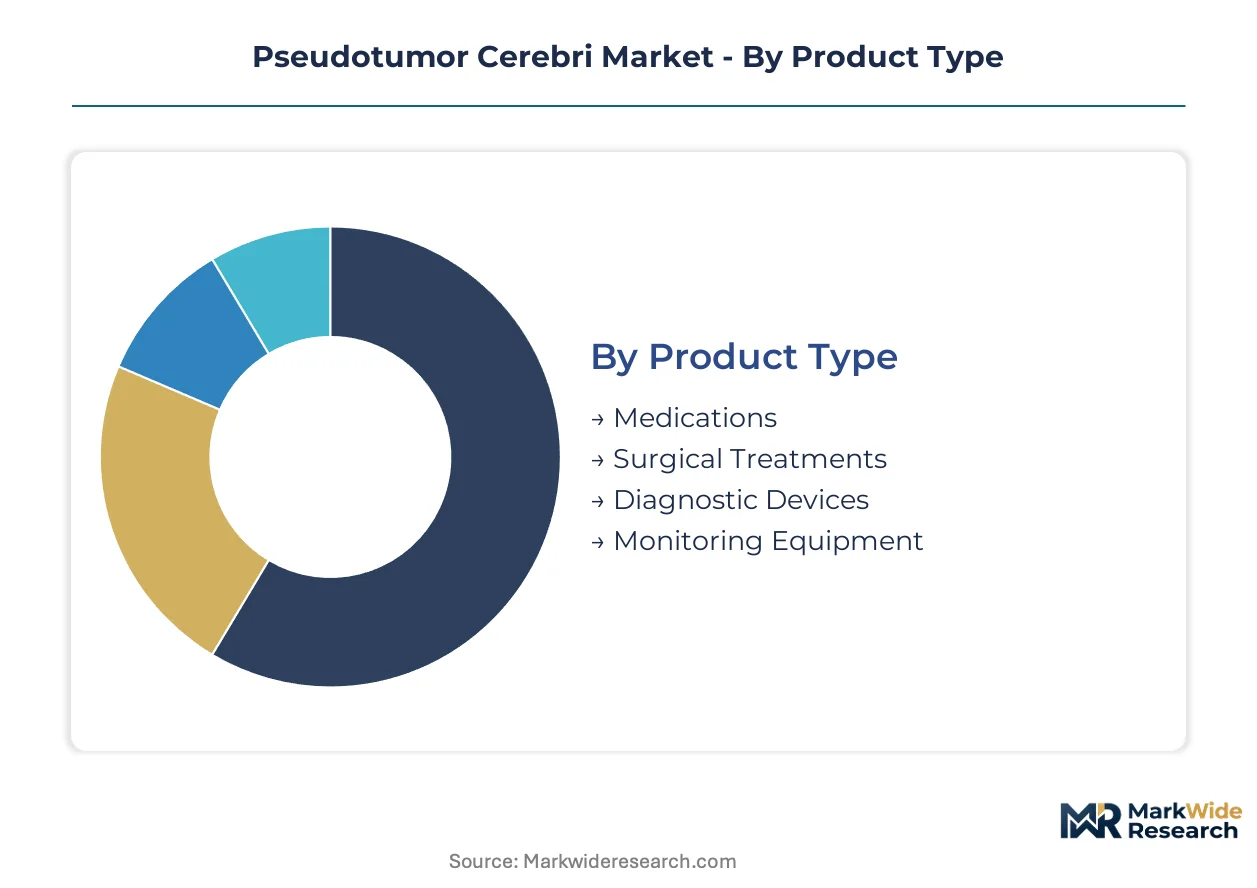
Pseudotumor cerebri care spans diagnostic confirmation, acute pressure reduction, and chronic monitoring phases. Each phase demands distinct equipment and service models that shape procurement priorities across hospital systems.
Product Type:
After-sales service intensity varies sharply across product categories, with surgical implants requiring revision support and diagnostic platforms demanding software maintenance contracts.
- Medications:Carbonic anhydrase inhibitors and diuretics constitute first-line oral therapy. Hospital formularies in the United States concentrate acetazolamide procurement through generic tenders, with supply volatility driving dual-source contracting strategies.
- Surgical Treatments:Cerebrospinal fluid shunt systems and optic nerve sheath fenestration instruments command premium positioning. Academic medical centers in the United States anchor demand where rapid visual decline necessitates immediate intervention.
- Diagnostic Devices:Optical coherence tomography systems standardize papilledema assessment.
- Monitoring Equipment:Intracranial pressure sensors and telemetry systems enable post-intervention surveillance.
By volume, Medications leads. By growth pace, Diagnostic Devices is ahead.
Therapy Area:
Cost tier stratification separates high-acuity surgical intervention from chronic outpatient management, with reimbursement rates determining service line investment priorities.
- Neurology:Lumbar puncture with manometry and intracranial pressure modulation protocols define core diagnostic and therapeutic workflows. Specialized headache centers in the United States concentrate fellowship-trained specialists who drive procedure standardization.
- Ophthalmology:Retinal nerve fiber layer monitoring and vision preservation interventions anchor disease management endpoints. Neuro-ophthalmology departments in academic medical centers deploy optical coherence tomography to compress subjective assessment cycles.
- Pain Management:Headache-focused interventions address refractory symptoms.
- Critical Care:Acute intracranial pressure crises demand rapid escalation protocols.
Neurology captures the largest procedure volume. Ophthalmology is expanding most quickly as monitoring technology displaces manual examination.
Delivery Mode:
Application context determines delivery selection, with ambulatory compatibility increasingly favored for chronic disease populations.
- Oral:Acetazolamide and topiramate tablets dominate maintenance therapy. Prescription volumes in the United States flow through specialized headache centers and academic neurology clinics serving obese women of childbearing age.
- Intravenous:Acute pressure reduction in inpatient settings leverages parenteral formulations.
- Topical:Limited role in current treatment algorithms.
- Invasive Procedures:Shunt placement and optic nerve sheath fenestration address rapid visual decline. Tertiary neurosurgical centers in the United States concentrate surgical volumes where fellowship-trained specialists manage revision burdens.
Oral delivery dominates prescription counts. Invasive Procedures claim the highest per-procedure economics.
End User:
Customer type segmentation reflects care complexity gradients, with infrastructure requirements filtering patient flows across settings.
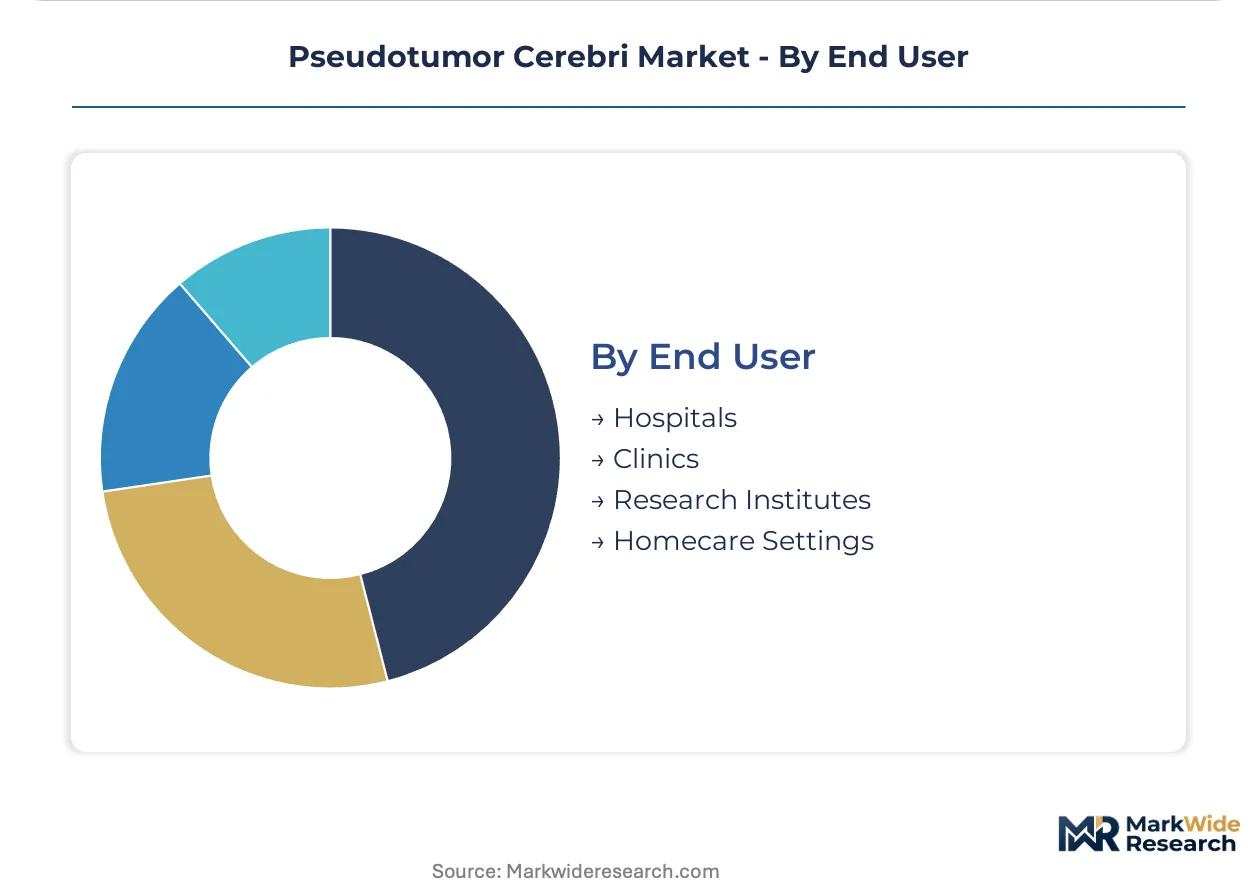
- Hospitals:Integrated neurology-ophthalmology service lines consolidate diagnostic and surgical capabilities. United States metropolitan hospital systems bundle capital equipment procurement under unified department budgets.
- Clinics:Outpatient headache centers manage stable patients on oral therapy.
- Research Institutes:Natural history studies and interventional trials generate evidence for orphan drug designations.
- Homecare Settings:Telemedicine-compatible monitoring technologies extend specialist reach beyond physical clinic boundaries.
Hospitals anchor diagnostic and surgical volume. Homecare Settings are gaining share fastest as remote monitoring protocols mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States Interstate Highway System and transcontinental rail corridors enable rapid patient transport to specialized neuro-ophthalmology centers, cementing the country's central role in pseudotumor cerebri care delivery. Urban academic medical clusters concentrate diagnostic volumes and surgical expertise.
United States
Specialized headache centers in Boston, Baltimore, and San Francisco drive procedure standardization and clinical trial enrollment. The FDA's orphan drug designation pathway accelerates therapeutic development timelines for low-prevalence neurological indications. Neuro-ophthalmology fellowship programs at Johns Hopkins and University of Pennsylvania anchor the specialist workforce pipeline.
Germany
University hospitals in Heidelberg and Tübingen integrate optical coherence tomography into standardized papilledema monitoring protocols. The EMA's parallel framework for orphan medicinal products creates dual-jurisdiction trial efficiency for sponsors pursuing transatlantic development. Baden-Württemberg's medical technology cluster concentrates diagnostic device manufacturing and research consortia.
United Kingdom
NHS England's specialized commissioning frameworks concentrate pseudotumor cerebri care within designated neuro-ophthalmology centers in London and Manchester. The MHRA operates post-Brexit regulatory pathways that maintain alignment with EMA orphan drug incentives. Academic medical centers in Oxford and Cambridge lead natural history studies supporting real-world evidence collection.
Japan
PMDA's Sakigake designation system accelerates review timelines for innovative intracranial pressure modulators targeting rare diseases. Tokyo and Osaka metropolitan areas concentrate neuro-ophthalmology specialists and advanced diagnostic imaging infrastructure. The Ministry of Health, Labour and Welfare's reimbursement frameworks prioritize vision-preserving interventions in working-age populations.
France
ANSM's early access programs enable compassionate use of novel carbonic anhydrase inhibitors prior to formal marketing authorization. The Paris-Saclay medical cluster integrates hospital-based research with pharmaceutical development for rare neurological conditions. Lyon and Marseille academic centers participate in multinational registries tracking long-term visual outcomes.
Pseudotumor Cerebri Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in the supply architecture. The pseudotumor cerebri competitive structure concentrates around three archetypes: pharmaceutical sponsors leveraging generic portfolios, surgical device manufacturers with shunt system expertise, and diagnostic platform vendors integrating artificial intelligence into imaging workflows. Consolidated purchasing committees at United States metropolitan hospital systems favor bundled procurement across these tiers. Vertical integration into adjacent neurology and ophthalmology segments represents the dominant competitive maneuver, alongside strategic partnerships targeting home monitoring technologies.
Among pharmaceutical-focused competitors, Teva Pharmaceutical Industries Ltd. and Heritage Pharmaceuticals Inc. occupy positions within the generic acetazolamide supply tier. Johnson & Johnson and Integra LifeSciences Corporation exemplify the surgical intervention archetype through their respective device portfolios. B. Braun Melsungen AG represents the European-based diversified medical technology competitor with cross-category presence. These named entities anchor broader industry patterns without constituting an exhaustive competitive census.
| Leading Market Players |
|---|
| Avkare Inc. |
| B. Braun Melsungen AG |
| Integra LifeSciences Corporation |
| Johnson & Johnson |
| Elekta AB |
| Teva Pharmaceutical Industries Ltd. |
| Beckersmith Medical Inc. |
| Heritage Pharmaceuticals Inc. |
| Ingenus Pharmaceuticals |
| Others |
Value Chain & Pricing Dynamics
The United States Interstate Highway System and transcontinental rail corridors enable rapid patient transport to specialized neuro-ophthalmology centers, with freight cost dynamics amplifying supply concentration in generic acetazolamide manufacturing while downstream price differentiation separates academic medical center procurement from community hospital contracting.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates branded intracranial pressure modulators from generic carbonic anhydrase inhibitors and commodity diuretic tablets. Price differentiation hinges on FDA orphan drug exclusivity provisions and volume scale in hospital formulary tenders. Cost compression in the generic oral therapy tier is intensifying because API manufacturing concentrates among limited suppliers. Community hospital buyers exhibit highest price sensitivity, while academic medical centers prioritize clinical efficacy over acquisition cost.
Supply Chain Analysis
Contract manufacturing concentration for acetazolamide API rests on facilities in India and China, with finished dosage form production anchored in the United States and Germany. Active pharmaceutical ingredient supply draws from carbon disulfide and ammonia feedstocks, plus specialized chemical intermediates. Single-source vulnerability pervades the generic diuretic tier where qualified API suppliers number fewer than five globally. Distribution runs through wholesale pharmaceutical distributors serving hospital systems and specialty pharmacy channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market occupies early-cycle expansion as optical coherence tomography displaces subjective fundoscopy and FDA orphan drug incentives accelerate therapeutic development timelines.
For Market Incumbents: Build regulatory exclusivity moats through FDA orphan drug designation pathways for novel intracranial pressure modulators. Deepen backward integration into acetazolamide API supply to mitigate shortage risk from concentrated manufacturing. Secure long-term hospital system partnerships that bundle diagnostic platforms with surgical device procurement.
For New Entrants and Emerging Players: Establish a beachhead in home intracranial pressure monitoring devices where telemedicine infrastructure creates ambulatory care white space. Target United States metropolitan headache centers for initial commercial traction. Pursue go-to-market alliances with optical coherence tomography vendors seeking software companion applications.
For Investors and Strategic Acquirers: Specialized diagnostic platform developers with artificial intelligence-enabled retinal nerve fiber layer analysis represent compelling acquisition targets. Long-term viability frames around vision-preserving intervention economics and chronic disease monitoring monetization. Watch FDA breakthrough device designation announcements as inflection indicators for platform valuation resets.
| Strategic Initiative | Industry Significance |
|---|---|
| Orphan Drug Designation Pursuit | FDA tax credits and market exclusivity provisions improve development economics for novel intracranial pressure modulators. |
| Optical Coherence Tomography Platform Integration | Artificial intelligence-assisted progression detection compresses subjective clinician assessment cycles in academic medical centers. |
| Hospital System Partnership Consolidation | Unified neurology-ophthalmology service line budgets bundle diagnostic device procurement with surgical platform acquisition. |
| Home Monitoring Technology Development | Telemedicine-compatible wearable sensors extend specialist reach beyond physical clinic boundaries for chronic patients. |
| EMA Parallel Pathway Execution | European Medicines Agency orphan designation incentives enable dual-jurisdiction trial efficiency for transatlantic development. |
Study Parameters
Initial hypotheses were tested against primary input from neuro-ophthalmology fellowship directors, hospital procurement managers, pharmaceutical regulatory affairs leads, and GPO contracts specialists and refined through secondary validation against FDA orphan drug designations, EMA submissions, ClinicalTrials.gov entries, and hospital equipment procurement databases. Bottom-up prescription volume modeling and top-down therapeutic category sizing were triangulated to reconcile output ranges.
Demand-supply-balance framing anchored the analytical framework across the analysis window, with segmentation dimensions spanning product type, therapy area, delivery mode, and end user. CAGRs were derived from procedure volume trajectories and pricing trend extrapolation. Forecast inputs incorporated optical coherence tomography adoption curves and generic acetazolamide supply stability assumptions.
Sensitivities concentrate around FDA regulatory timeline shifts, API manufacturing disruption, and telemedicine reimbursement policy changes. Quarterly review of orphan drug designation announcements, hospital capital expenditure disclosures, and generic drug shortage alerts is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Macular Edema Market
Ophthalmology
Pediatric Vitrectomy Market
Ophthalmology
Age-Related Macular Degeneration Market
Ophthalmology
Global Ophthalmic Equipment Market
Ophthalmology
Conjunctivitis Market
Ophthalmology
Optometry/Eye Exam Equipment Market
Ophthalmology
Non-Infectious Macular Edema Treatment Market
Ophthalmology
Europe Dry Eye Syndrome Market
Ophthalmology
Uveal Melanoma Market
Ophthalmology
Eye Melanoma Market
Ophthalmology
Choroidal Neovascularization Market
Ophthalmology
Global Ocular Inflammation Treatment Market
Ophthalmology
Eye Care Surgical Market
Ophthalmology
Ophthalmic Lasers Therapeutic Market
Ophthalmology
Corneal Edema Treatment Market
Ophthalmology
Excimer and Femtosecond Ophthalmic Lasers Market