
 Pleural Diseases Therapeutics Market | 2026-2036
Pleural Diseases Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Pleural Diseases Therapeutics Market Analytics
Specialty clinics is collapsing the historical hospital-centric purchasing model for pleural interventions as ambulatory thoracentesis and tunneled pleural catheter placement migrate to lower-acuity settings. Boehringer Ingelheim International GmbH leverages its respiratory franchise to anchor physician education around talc pleurodesis protocols. AbbVie Inc. competes through immunology-linked pipeline assets targeting malignant pleural effusion inflammation pathways. Bristol Myers Squibb differentiates via oncology-immunotherapy combinations under investigation for mesothelioma pleural disease.
Pleural diseases therapeutics encompass pharmacologic agents, interventional devices, and diagnostic-imaging systems designed to manage pathological conditions of the pleural space including pneumothorax, pleural effusion, and mesothelioma, typically employing talc or doxycycline sclerosing agents administered through chest tubes or thoracoscopic delivery to achieve visceral-parietal pleural adhesion. The primary commercial purpose centers on reducing recurrence of air or fluid accumulation while minimizing inpatient length of stay. Pleurodesis agents command the deepest margin pools due to sterile manufacturing requirements and limited generic competition in talc poudrage grades. Drainage devices represent the fastest-growing product category as indwelling pleural catheter technology enables outpatient management of recurrent malignant effusions. Imaging systems remain structurally mature, with incremental innovation concentrated in point-of-care ultrasound integration rather than modality displacement.
FDA orphan drug designation and EMA PRIME eligibility criteria shape clinical development priorities by offering protocol assistance and conditional market access for mesothelioma and rare pleural malignancy indications. The EU MDR recertification timeline pressures device manufacturers to consolidate technical documentation for thoracoscopy instruments and drainage systems. Reimbursement authorities in Japan evaluate pleural intervention coverage through procedure-specific fee schedules that favor minimally invasive techniques over open surgical approaches. Stakeholders must monitor how real-world evidence requirements from these regulators reshape post-market study commitments and pricing negotiations.
Market Dynamics
Hospital procurement of pleurodesis agents and drainage devices is accelerating as thoracic surgery volumes rise and payers pressure shorter inpatient stays. The shift toward ambulatory pleural interventions is restructuring where purchasing decisions occur and which stakeholders control formulary access.
Growth Catalysts
- FDA orphan drug designation:Protocol assistance and conditional market access for mesothelioma indications compress clinical development timelines and reduce regulatory risk for developers targeting rare pleural malignancies.
- Minimally invasive pleural interventions:Tertiary care centers in the United States, Germany, and Japan are driving adoption of thoracoscopic talc poudrage and tunneled catheter placement, expanding addressable procedure volumes.
- EMA PRIME eligibility criteria:Accelerated assessment pathways for priority medicines reshape reimbursement negotiations and early access schemes across European markets.
Market Restraints
- Sterile talc supply concentration:Limited manufacturers of asbestos-free talc meeting poudrage-grade specifications create single-source dependency and batch consistency risks.
- EU MDR recertification timeline:Technical documentation requirements for thoracoscopy instruments and drainage systems pressure smaller device manufacturers to consolidate or exit.
- Doxycycline pleurodesis efficacy ceiling:Sclerosing agent alternatives demonstrate inferior adhesion rates in malignant effusions, constraining therapeutic substitution.
Strategic Opportunities
- Japan procedure-specific fee schedules:Reimbursement differentials favoring minimally invasive techniques over open surgical approaches create margin expansion for outpatient pleural intervention providers.
- Point-of-care ultrasound integration:Convergence of portable imaging with catheter placement protocols enables real-time guidance without fluoroscopy suite dependency.
- Specialty clinic channel development:Ambulatory thoracentesis and tunneled pleural catheter placement migrating to lower-acuity settings opens direct purchasing relationships outside hospital supply chains.
Industry Challenges
- Interventional pulmonology training pipeline:Procedural volume requirements for thoracoscopy competency certification limit qualified operator supply relative to device placement demand.
- Real-world evidence generation infrastructure:Post-market study commitments for conditional approvals require data capture systems that most centers lack, complicating label expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pleural Diseases Therapeutics Market |
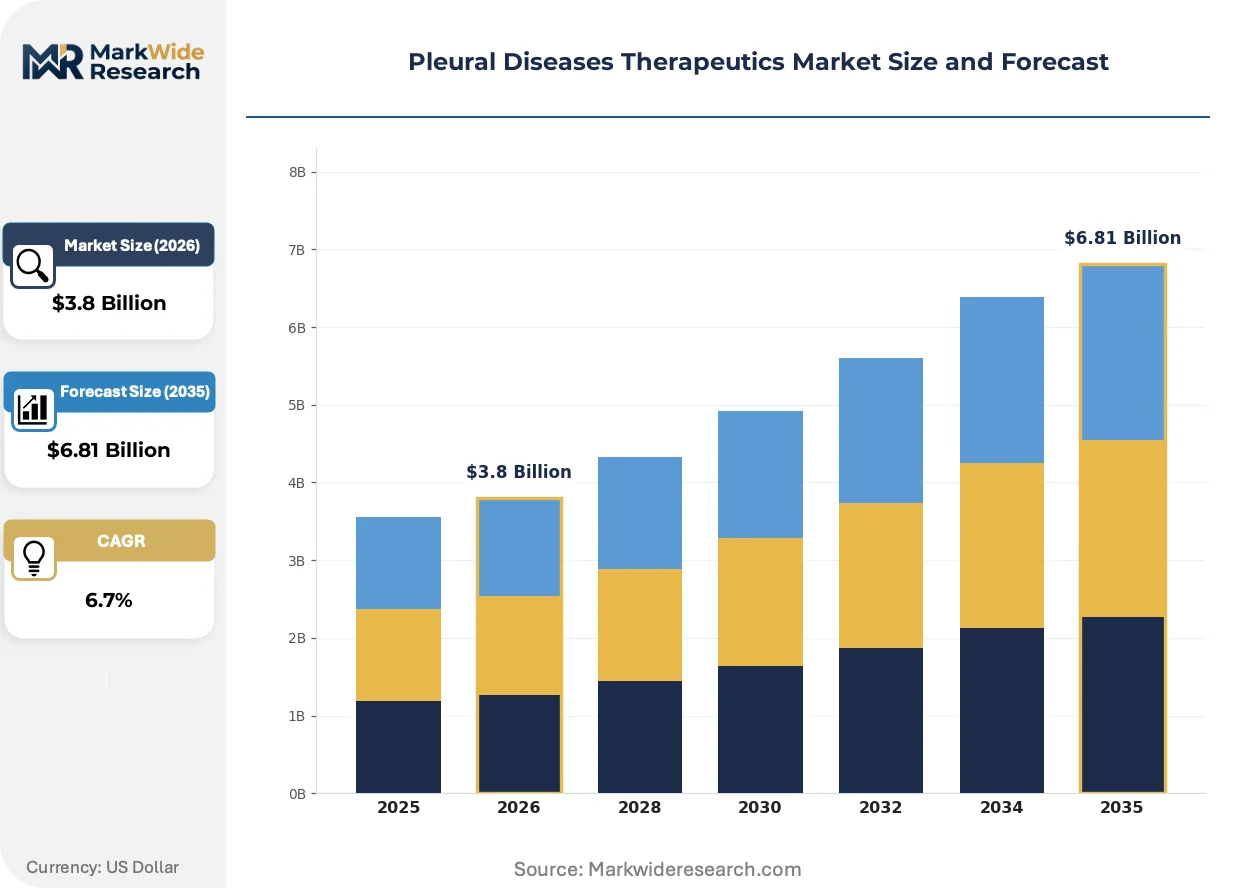
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pleurodesis Agents, Drainage Devices, Imaging Systems, Thoracoscopy Instruments Therapy Area: Pneumothorax, Pleural Effusion, Mesothelioma, Lung Cancer End User: Hospitals, Specialty Clinics, Outpatient Centers, Homecare Settings Delivery Mode: Intravenous, Intramuscular, Intrathecal, Subcutaneous |
| Companies Covered | Boehringer Ingelheim International GmbH, AbbVie Inc., Bristol Myers Squibb, Hoffmann-La Roche Ltd., Sanofi S.A., Merck & Co., Inc., Pfizer Inc., Becton, Dickinson and Company, GlaxoSmithKline plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pleural Diseases Therapeutics Market Evolving Landscape
Thoracic intervention workflows are fragmenting across care settings as technology enables procedure migration and reimbursement reforms accelerate site-of-service arbitrage. Three convergent developments are restructuring competitive positioning.
Indwelling pleural catheter technology is fragmenting the historical inpatient drainage episode. Tunneled catheter systems with integrated vacuum drainage enable home-based malignant effusion management, compressing hospital length-of-stay metrics. Community oncology practices and palliative care networks are adopting these devices faster than academic centers, shifting volume toward ambulatory surgical centers.
EU MDR technical documentation requirements are compressing the device vendor landscape. Thoracoscopy instrument manufacturers face consolidated notified body capacity and extended audit timelines, forcing portfolio rationalization. German and French hospital procurement consortia are responding by pre-qualifying fewer suppliers with complete MDR certification packages, concentrating contract awards.
Site-of-service economics are restructuring purchasing authority. United States payers are expanding prior authorization requirements for inpatient pleurodesis, pushing procedures toward hospital outpatient departments and freestanding ambulatory centers. Interventional pulmonology groups in Texas and Florida are capturing these volumes through joint ventures with specialty surgery centers, bypassing traditional hospital supply agreements.
Pleural Diseases Therapeutics Market Segmentation
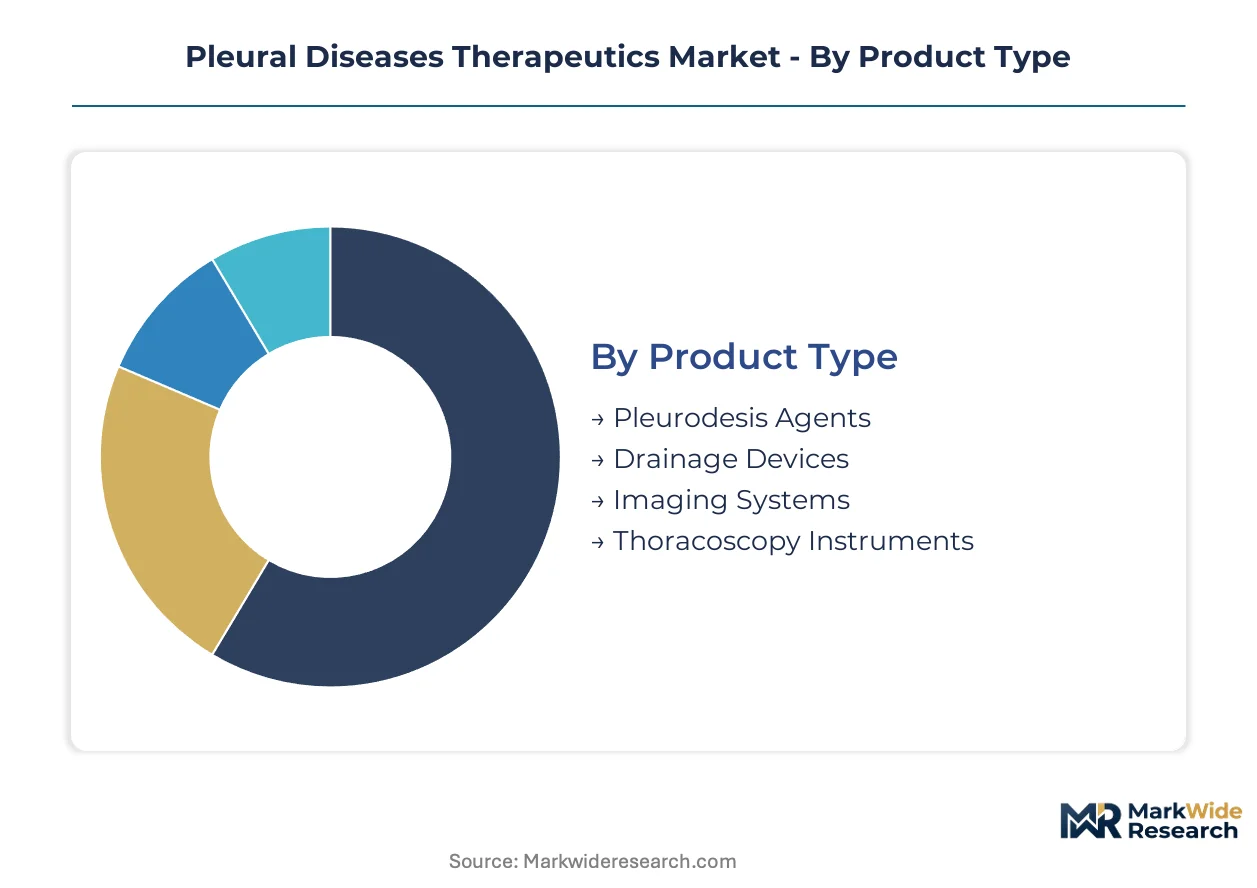
Pleural disease therapeutics fragment across four distinct segmentation dimensions, each carrying different margin profiles and procurement dynamics. Product type and therapy area capture the deepest value pools, while end-user and delivery mode structures determine channel strategy and reimbursement pathways.
Product Type:
Margins concentrate in sterile-manufactured agents with limited generic competition, while device categories compete on placement volume and technical service bundling.
- Pleurodesis Agents:Talc and doxycycline formulations require poudrage-grade sterile manufacturing with asbestos-free certification. Demand concentrates in tertiary thoracic surgery centers across the United States, Germany, and Japan where thoracoscopic delivery protocols dominate procedural workflows.
- Drainage Devices:Indwelling pleural catheter systems with integrated vacuum drainage enable malignant effusion management outside inpatient settings. Specialty clinics in Texas and Florida are capturing placement volumes through joint ventures with ambulatory surgery centers, bypassing traditional hospital procurement.
- Imaging Systems:Point-of-care ultrasound integration with catheter placement protocols drives portable modality demand.
- Thoracoscopy Instruments:EU MDR recertification pressures are compressing the vendor landscape toward consolidated suppliers with complete technical documentation.
The dominant share belongs to Pleurodesis Agents, while Drainage Devices is gaining share fastest through outpatient procedure migration.
Therapy Area:
Volume distribution tracks disease prevalence and recurrence rates, with malignant indications commanding premium pricing due to chronic management requirements.
- Pleural Effusion:Recurrent malignant effusions generate sustained device placement demand through tunneled catheter maintenance protocols. Palliative care networks and community oncology practices in the United States are adopting home-based drainage faster than academic centers.
- Mesothelioma:Orphan indication status unlocks FDA protocol assistance and EMA PRIME eligibility, compressing development timelines for targeted therapeutics. Tertiary centers in Japan leverage procedure-specific fee schedules favoring minimally invasive approaches.
- Pneumothorax:Primary spontaneous cases drive emergency talc pleurodesis volume in hospital settings.
- Lung Cancer:Metastatic pleural involvement creates overlapping therapeutic pathways with malignant effusion management.
Pleural Effusion commands the largest procedure volume, though Mesothelioma carries the steepest pricing power per intervention.
End User:
Site-of-service economics are fragmenting purchasing authority away from centralized hospital supply chains toward point-of-care decision makers.
- Hospitals:Academic medical centers retain complex thoracoscopy volumes and talc poudrage protocols. Inpatient length-of-stay pressures from United States payers are eroding elective pleurodesis margins.
- Specialty Clinics:Interventional pulmonology groups capture ambulatory thoracentesis and tunneled catheter placement through direct purchasing relationships. German and French hospital procurement consortia are pre-qualifying fewer MDR-certified suppliers.
- Outpatient Centers:Freestanding surgical facilities benefit from expanded prior authorization pathways for pleural interventions.
- Homecare Settings:Integrated vacuum drainage systems enable patient-managed malignant effusion care outside clinical facilities.
Hospitals retain the dominant share, yet Specialty Clinics are climbing the fastest as reimbursement reforms accelerate site-of-service arbitrage.
Delivery Mode:
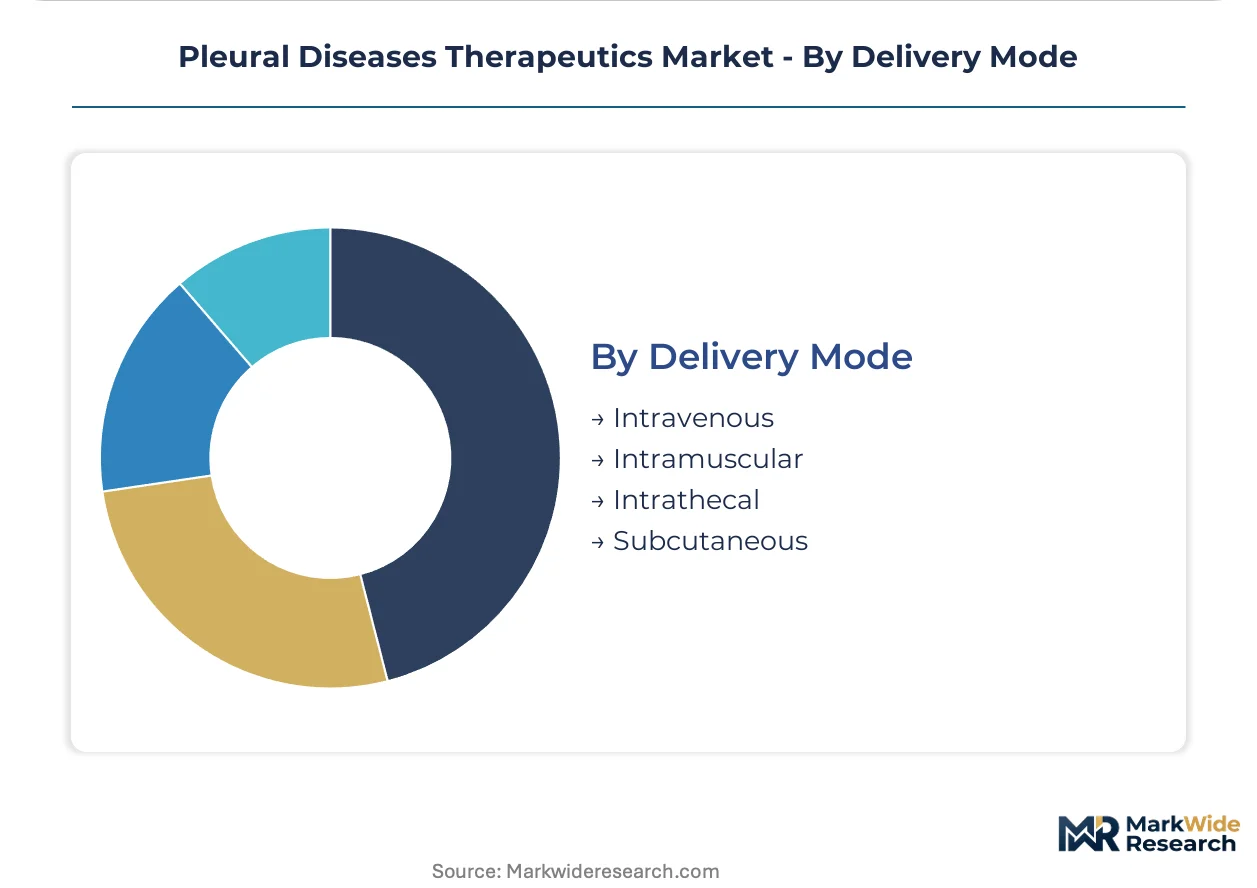
Route selection follows anatomical targeting requirements and procedural setting constraints, with intrapleural administration dominating this therapeutic category.
- Intravenous:Systemic agents for mesothelioma immunotherapy combinations require oncology infusion infrastructure.
- Intramuscular:Limited relevance for pleural-specific therapeutics outside supportive care applications.
- Intrathecal:Specialized access for central nervous system metastases in advanced lung malignancies.
- Subcutaneous:Emerging delivery for sustained-release formulations in development pipelines.
Intrathecal and intravenous routes split the oncology-linked segment, while subcutaneous formulations are expanding most quickly in development portfolios.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers of thoracoscopy instruments and sterile talc formulations export predominantly to hospital procurement consortia across France, Italy, and Spain. This north-south trade corridor channels advanced pleural intervention technologies into Mediterranean markets with accelerating minimally invasive procedure adoption.
United States
Interventional pulmonology groups in Texas and Florida are capturing ambulatory thoracentesis volumes through joint ventures with specialty surgery centers. FDA orphan drug designation for mesothelioma indications compresses clinical development timelines for developers targeting rare pleural malignancies. Tertiary care centers in Houston and Dallas drive adoption of thoracoscopic talc poudrage protocols.
Germany
Hospital procurement consortia in Baden-Württemberg and Bavaria are pre-qualifying fewer suppliers with complete EU MDR certification packages for thoracoscopy instruments. EMA PRIME eligibility criteria reshape reimbursement negotiations and early access schemes for priority medicines. The Mannheim-Heidelberg medical cluster concentrates talc poudrage-grade manufacturing and sterile device assembly operations.
Japan
Procedure-specific fee schedules from METI favor minimally invasive pleural interventions over open surgical approaches, expanding outpatient procedure margins. PMDA accelerated review pathways for orphan indications align with mesothelioma therapeutic development priorities. The Tokyo-Osaka corridor hosts the highest concentration of tertiary thoracic surgery centers performing tunneled catheter placements.
France
ANSM post-market surveillance requirements for pleurodesis agents intensify batch tracking obligations across hospital pharmacy networks. The EU MDR recertification timeline pressures device manufacturers to consolidate technical documentation for drainage systems. Lyon and Marseille academic medical centers anchor malignant pleural effusion research consortiums with standardized talc delivery protocols.
United Kingdom
NICE technology appraisal pathways evaluate pleural intervention cost-effectiveness against inpatient drainage episode benchmarks. The NHS England specialized commissioning framework concentrates complex mesothelioma procedures at designated thoracic surgery centers in London and Manchester. Point-of-care ultrasound integration with catheter placement protocols spreads through regional interventional pulmonology training networks.
Pleural Diseases Therapeutics Market Competitive Landscape
Listed leaders compete with private specialists across regulatory certification and physician education dimensions. The vendor landscape compresses toward consolidated suppliers with complete EU MDR technical documentation and FDA establishment registration. Three archetypes dominate: respiratory franchise holders leveraging existing pulmonology relationships, oncology-immunology developers targeting malignant effusion inflammation pathways, and diversified device manufacturers bundling drainage systems with technical service contracts. Competitive moves concentrate on M&A to capture ambulatory surgery center channel access and strategic partnerships with interventional pulmonology training programs.
Within the respiratory franchise tier, Boehringer Ingelheim International GmbH and GlaxoSmithKline plc exemplify archetypes leveraging established physician education infrastructure. Among oncology-immunology developers, Bristol Myers Squibb occupies a position representing combination therapy investigation for mesothelioma indications. These three entities anchor competitive dynamics around talc pleurodesis protocol standardization and malignant effusion therapeutic positioning.
| Leading Market Players |
|---|
| Boehringer Ingelheim International GmbH |
| AbbVie Inc. |
| Bristol Myers Squibb |
| Hoffmann-La Roche Ltd. |
| Sanofi S.A. |
| Merck & Co., Inc. |
| Pfizer Inc. |
| Becton, Dickinson and Company |
| GlaxoSmithKline plc |
| Others |
Value Network & Pricing Analysis
EU MDR certification gates both sterile talc supplier qualification and price differentiation across thoracoscopy instrument tiers, compressing vendor margins while amplifying premiums for complete technical documentation packages. Hospital procurement consortia in Germany and France exploit this bifurcation to extract volume discounts from certified suppliers while relegating non-compliant manufacturers to spot-market pricing.
Pricing Analysis
Prior-generation talc poudrage formulations trade at commodity-equivalent levels while current-generation thoracoscopic delivery systems command service-bundled premiums and next-generation integrated vacuum drainage platforms capture recurring revenue through catheter maintenance protocols. Pricing stratifies across poudrage-grade certification tiers, with asbestos-free sterile manufacturing and batch consistency documentation driving differentiation. Cost compression in standard-grade doxycycline pleurodesis is intensifying because generic substitution erodes adhesion-rate premiums. Community oncology practices exhibit highest price sensitivity due to capitated reimbursement structures, whereas tertiary thoracic surgery centers prioritize procedural outcome guarantees over unit cost.
Supply Chain Analysis
Asbestos-free talc ore processing capacity in Italy, Germany, and the United States creates a tripartite chokepoint for poudrage-grade sterile manufacturing, with single-source dependencies amplifying batch consistency risks across thoracoscopic delivery workflows. Raw material inputs draw from pharmaceutical-grade talc mining operations, sterile packaging films, and precision-molded catheter polymers. Tariff exposure on Italian-processed talc concentrates supply risk for North American device manufacturers. Distribution runs through hospital procurement consortia in Western Europe and GPO contracts in the United States, with specialty clinics in Texas and Florida emerging as direct purchasing channels outside traditional supply chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Point-of-care ultrasound integration with tunneled catheter placement protocols is transforming pleural intervention workflows into interoperable platform ecosystems, with device-software bundling creating switching costs that lock in ambulatory surgery center volumes.
For Market Incumbents: Fortify talc pleurodesis protocol standardization through physician education infrastructure investments, securing formulary anchoring before biosimilar sclerosing agents erode margin pools. Consolidate EU MDR technical documentation capabilities to pre-empt notified body capacity constraints that threaten competitor recertification timelines. Prioritize backward integration into sterile talc processing to neutralize single-source raw material vulnerabilities. For New Entrants and Emerging Players: Differentiate on home-based drainage ecosystem integration, capturing palliative care network procurement relationships outside hospital-centric supply chains. Target specialty clinic joint ventures in Florida and Texas as the most penetrable channel, where reimbursement differentials favor ambulatory procedure migration. Deploy direct-to-clinic technical service contracts as the primary go-to-market angle, bypassing GPO intermediaries. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across indwelling catheter manufacturing as automated assembly displaces manual production, compressing viable scale thresholds for mid-tier device specialists. Long-term viability centers on platform economics rather than discrete product margins, favoring acquisition targets with integrated software-hardware service bundles. Monitor FDA orphan drug designation velocity for mesothelioma indications as the signal to watch, with accelerated approval pathways indicating ecosystem maturation timing.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Consolidation | Complete certification packages unlock German hospital procurement consortia pre-qualification and contract concentration. |
| Point-of-Care Ultrasound Integration | Portable imaging convergence with catheter protocols reduces fluoroscopy suite dependency and expands ambulatory eligibility. |
| Specialty Clinic Channel Development | Direct purchasing relationships in Texas and Florida bypass traditional hospital supply chains and capture site-of-service arbitrage. |
| FDA Orphan Drug Designation Pursuit | Protocol assistance for mesothelioma indications compresses development timelines and reduces regulatory risk capital requirements. |
| Home-Based Drainage Ecosystem Buildout | Integrated vacuum systems enable patient-managed malignant effusion care outside clinical facilities, extending addressable procedure lifetime value. |
Research Methodology
Operator-level perspectives from interventional pulmonologists, thoracic surgeons, hospital procurement managers, GPO contracts specialists, and palliative care network directors anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) filings, EMA PRIME eligibility databases, hospital procurement records, and CMS Medicare procedure fee schedules. Bottom-up procedure volume estimates and top-down pharmaceutical revenue triangulation converged on segment-level demand assessments.
Sensitivity analysis across sterile talc supply disruption scenarios and reimbursement reform pathways informed the analytical framework. Segmentation dimensions modeled include product type, therapy area, end-user setting, and delivery mode across the projection horizon. CAGRs derived from procedure volume trajectories and pricing elasticity assumptions, with thoracic surgery volume growth and outpatient migration rates serving as primary forecast inputs.
Material uncertainties — sterile talc batch contamination events, EU MDR audit timeline extensions, and Japan procedure fee schedule revisions — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory pathway stability and reimbursement parity between inpatient and ambulatory settings. Practitioners should keep alternative scenarios live as interventional pulmonology training pipeline capacity and real-world evidence infrastructure maturity evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Atrophic Vaginitis Treatment Market
Specialty Medicine
Pleurisy Market
Specialty Medicine
Leukocyte Adhesion Deficiency Management Market
Specialty Medicine
Global Plasma Therapeutics Market
Specialty Medicine
Piriformis Syndrome Market
Specialty Medicine
Soft Tissue Sarcoma Market
Specialty Medicine
Hypothyroidism Market
Specialty Medicine
Immunoglobulin (Igg) Replacement Therapy Market
Specialty Medicine
US Opioid Use Disorder (OUD) Market
Specialty Medicine
Blastomycosis Treatment Market
Specialty Medicine
Global Urea Cycle Disorder Market
Specialty Medicine
Transthyretin Amyloidosis Treatment Market
Specialty Medicine
Global Focal Segmental Glomerulosclerosis Market
Specialty Medicine
Piriformis Syndrome Treatment Market
Specialty Medicine
Psychedelic Medicine Market
Specialty Medicine
Cystic Fibrosis Market