
 Global Ophthalmic Knives Market | 2026-2036
Global Ophthalmic Knives Market Size, Share, and Industry Trends Forecast 2026-2036
Global Ophthalmic Knives Market Foresight
The EU Green Deal's medical device sustainability benchmarks are repositioning procurement criteria across European hospital systems. Alcon leverages its vertical integration in diamond-turned blade manufacturing to sustain premium positioning in refractive surgery suites. MANI Inc. anchors its competitive stance through specialized ceramic-coating expertise for microincision cataract instruments. Bausch + Lomb differentiates via controlled distribution networks spanning ophthalmic clinics and ambulatory surgical centers in North America and Asia-Pacific.
Ophthalmic knives are precision cutting instruments engineered with blade angles between 15 and 30 degrees, manufactured from medical-grade stainless steel, diamond, or ceramic substrates to achieve sub-millimeter incision accuracy in ocular tissue. Their primary commercial purpose centers on enabling minimally invasive anterior and posterior segment procedures while minimizing endothelial cell loss and astigmatic induction. Disposable knives command expanding share in infection-sensitive settings as hospitals phase out reprocessing infrastructure, while titanium-alloy platforms retain dominance in high-volume cataract surgery due to superior edge retention and tactile feedback. Refractive surgery applications represent the fastest-growing segment as femtosecond laser adjunct procedures multiply procedural complexity and blade specificity requirements.
FDA 510(k) clearance pathways and EU MDR Class IIa designation govern blade biocompatibility, sterility assurance, and edge-integrity validation for market access across the United States and European Union. Japan's PMDA enforces additional JIS T 0301 standards for metallic implantable instruments that extend to reusable ophthalmic knife substrates. China's NMPA revised its medical device classification catalog to elevate certain microkeratome blades to higher scrutiny tiers. Stakeholders must monitor evolving reprocessing bans in Germany and France alongside Japan's reimbursement compression for reusable instruments to calibrate portfolio mix between disposable and durable platforms.
Market Dynamics
EU MDR reprocessing validation mandates are forcing hospital systems to dismantle sterilization infrastructure for reusable ophthalmic instruments, permanently altering procurement economics toward single-use platforms.
Growth Catalysts
- Aging Demographics:Cataract surgery volumes in Japan, Germany, and the United States are climbing as populations over 65 expand, sustaining demand for microincision blades and diamond-turned keratome instruments.
- EU MDR Class IIa Designation:Stricter sterility assurance requirements for reusable knives are accelerating hospital transitions to pre-sterilized disposable alternatives in France, Italy, and Spain.
- Femtosecond Laser Adjunct Procedures:Blade specificity requirements are multiplying as refractive surgery suites adopt laser-assisted platforms, creating specialized demand for angled incision instruments.
Market Restraints
- Diamond Substrate Volatility:Synthetic diamond supply concentrates in limited industrial zones, exposing blade manufacturers to input cost swings and qualification delays.
- Japan Reimbursement Compression:METI-directed fee schedule revisions are squeezing margins on reusable instrument platforms, constraining R&D reinvestment cycles.
- Femtosecond Laser Substitution:Corneal flap creation is migrating toward all-laser platforms in premium refractive centers, displacing mechanical microkeratome blade demand.
Strategic Opportunities
- China's NMPA Reclassification:Elevated scrutiny tiers for microkeratome blades create first-mover advantages for manufacturers with pre-qualified sterilization dossiers.
- Ambulatory Surgical Center Expansion:Outpatient ophthalmic clinics in the United States are adopting high-volume disposable contracts, bypassing traditional hospital procurement committees.
- Ceramic-Coating Convergence:Integration of zirconia-based edge retention with titanium-alloy handles is opening premium positioning in microincision cataract surgery.
Industry Challenges
- Edge-Integrity Validation Talent:Shortages of metrology specialists capable of sub-micron blade inspection are extending FDA 510(k) clearance timelines.
- Legacy Reprocessing Infrastructure Stranded Assets:German and French hospital systems face write-downs on sterilization equipment as EU Green Deal sustainability benchmarks tighten.
- ISO 13485 Certification Backlogs:Notified body capacity constraints are delaying quality management system renewals for mid-tier manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Ophthalmic Knives Market |
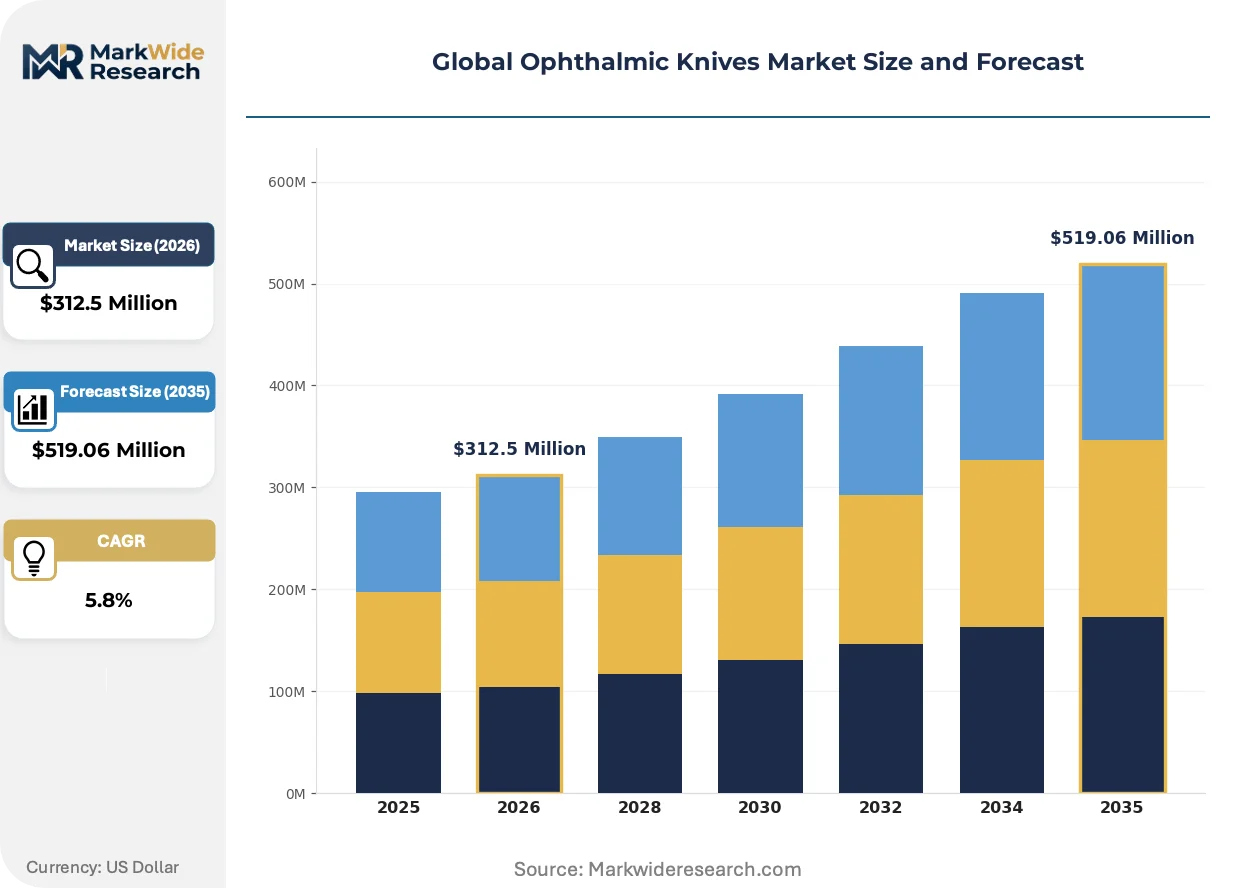
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $519.06 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Knives, Disposable Knives, Reusable Knives, Microkeratomes Material: Stainless Steel, Carbon Steel, Titanium, Plastic End User: Ophthalmic Clinics, Hospitals, Ambulatory Surgical Centers, Research Facilities Application: Cataract Surgery, Glaucoma Surgery, Corneal Surgery, Refractive Surgery |
| Companies Covered | Alcon, Bausch + Lomb, Diamatrix Ltd., Teleflex Incorporated, MANI Inc., Ophtechnics Unlimited, HAI Laboratories, Inc., Paramount Surgimed Ltd., BVI, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Ophthalmic Knives Market Shifts & Advancements
Femtosecond laser integration with manual blade workflows is fragmenting instrument specifications, while regulatory pressure on sterilization assurance compresses the viable product lifecycle for reusable platforms.
Robotic-assisted cataract surgery platforms are automating blade positioning and incision depth control, reducing surgeon variability in anterior segment procedures. Academic medical centers in South Korea and the United States are piloting these systems for standardized outcomes. The technology is automating technician roles in high-volume surgical suites, compressing staffing models toward single-operator configurations.
EU MDR's Unique Device Identification requirements are mandating serialized blade tracking from manufacture to point-of-use, creating compliance costs for legacy product lines. Manufacturers must redesign labeling and data infrastructure to satisfy EUDAMED database integration. Single-use disposable platforms capture advantage here, as their shorter supply chains simplify traceability compared to reusable instruments circulating through multiple sterilization cycles.
Hospital procurement committees are unbundling blade supply from capital equipment contracts, shifting toward direct vendor relationships for consumables. Ambulatory surgical centers in Texas, Florida, and California are leading this disintermediation, negotiating spot pricing for high-volume cataract procedures. The pattern concentrates purchasing power among administrator-led buying groups, marginalizing traditional distributor intermediaries.
Global Ophthalmic Knives Market Segmentation
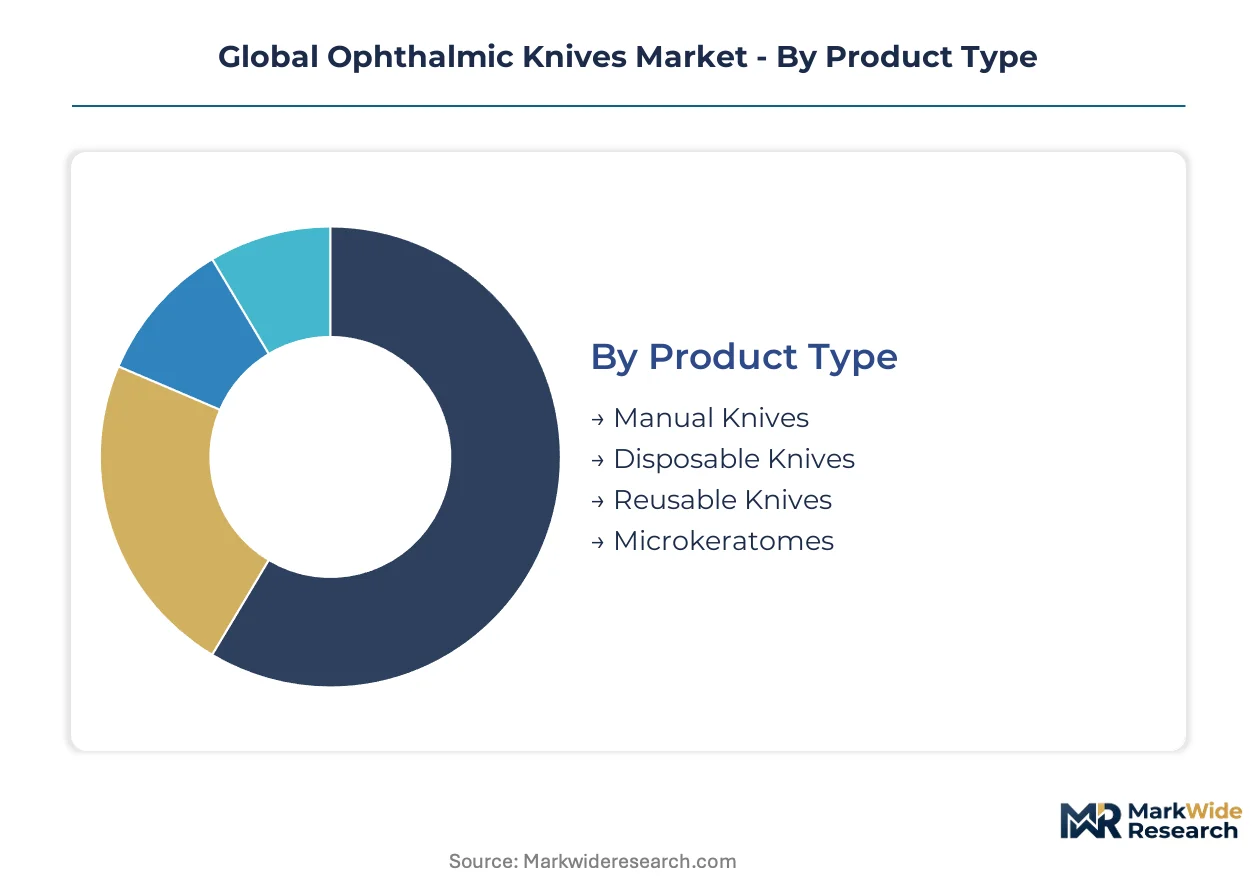
Precision requirements in anterior and posterior segment procedures fragment demand across blade specifications, sterilization protocols, and incision geometries. Procurement patterns diverge sharply between high-volume cataract workflows and specialized refractive suites, with regulatory pressure on reprocessing assurance reshaping platform economics.
Product Type:
Replacement cycles accelerate where EU MDR validation costs exceed amortization savings on reusable platforms, tilting procurement toward pre-sterilized alternatives.
- Disposable Knives:Gamma-irradiated polypropylene handles paired with stainless or diamond blades eliminate sterilization infrastructure. Demand concentrates in German and French hospital systems dismantling central sterile supply departments under EU Green Deal benchmarks.
- Manual Knives:Surgeon-controlled incision instruments with 15-30 degree blade angles remain dominant in high-volume cataract suites across Japan and the United States. Tactile feedback requirements sustain preference over automated alternatives in anterior segment procedures.
- Reusable Knives:Titanium-alloy platforms with diamond-turned edges face stranded asset risk as sterilization equipment write-downs accumulate.
- Microkeratomes:Mechanical flap creation instruments confront displacement from femtosecond laser platforms in premium refractive centers.
Disposable knives sit at the top of the volume ranking, with manual knives climbing the fastest as ambulatory surgical centers bypass hospital procurement committees.
Material:
Cost tiers separate premium ceramic and diamond substrates from commodity stainless configurations, with reimbursement compression in Japan squeezing mid-grade titanium adoption.
- Diamond:Synthetic monocrystalline substrates achieve sub-micron edge retention for refractive incision precision. Supply concentrates in limited industrial zones, exposing manufacturers to qualification delays and input volatility.
- Stainless Steel:Medical-grade 440C and 420 variants dominate high-volume disposable production. Cost structures align with single-use economics in United States ambulatory surgical center contracts.
- Titanium:Biocompatible alloy handles pair with interchangeable blade cartridges in reusable platforms.
- Plastic:Molded polypropylene and polystyrene components reduce per-unit mass for disposable handles.
Stainless steel captures the highest shipment volumes, with diamond substrates expanding most quickly in laser-adjunct refractive procedures.
End User:
Customer type determines purchasing authority structure, with administrator-led buying groups in outpatient settings disintermediating traditional distributor relationships.
- Ambulatory Surgical Centers:High-volume cataract workflows in Texas, Florida, and California negotiate spot pricing for disposable contracts. Direct vendor relationships bypass hospital procurement committee overhead.
- Hospitals:Integrated delivery networks face EU MDR compliance costs on legacy sterilization infrastructure. German and French systems accelerate write-downs on central sterile supply equipment.
- Ophthalmic Clinics:Private practice configurations favor premium blade specificity for refractive procedure differentiation.
- Research Facilities:Academic medical centers pilot robotic-assisted platforms requiring standardized blade geometries.
Ambulatory surgical centers lead volume concentration, with hospitals declining fastest as reprocessing bans proliferate.
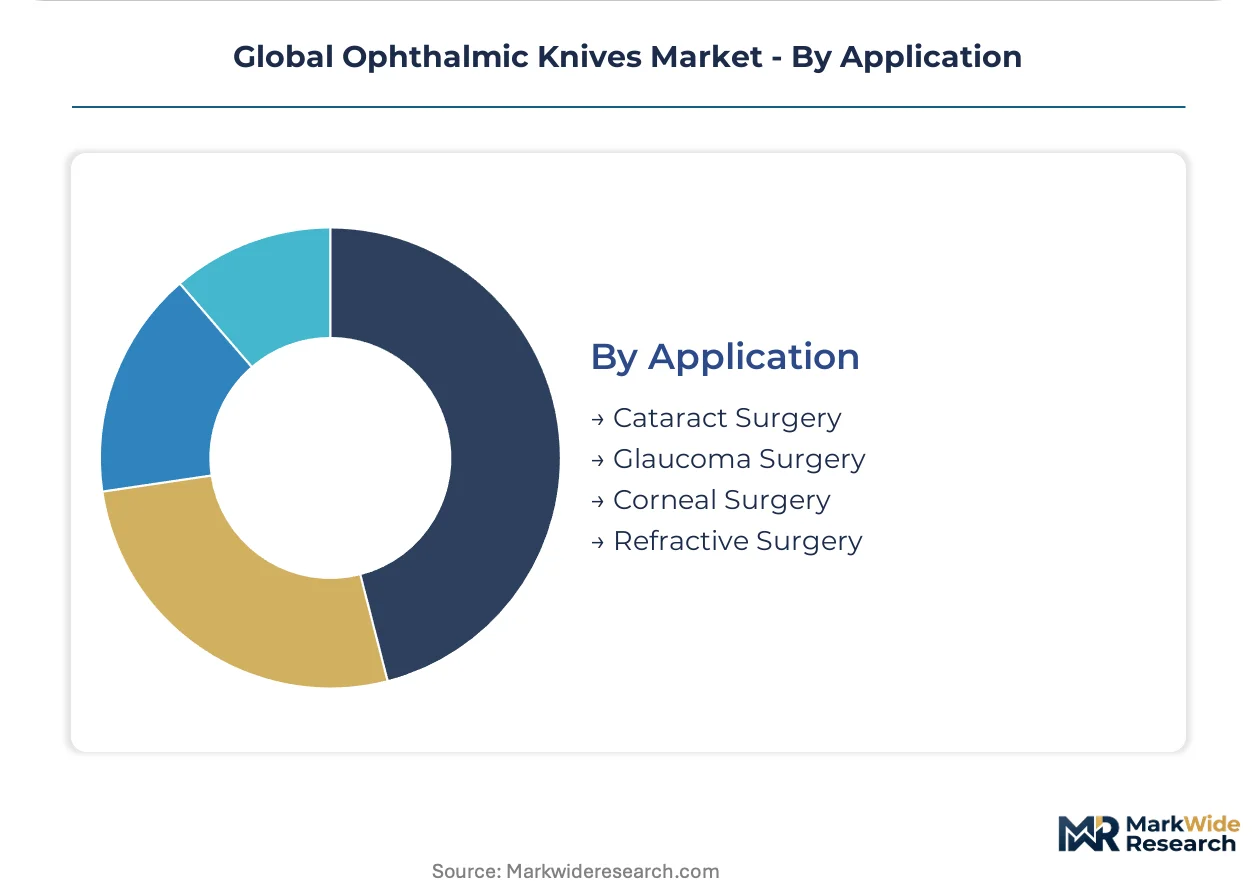
Application:
Procedure complexity dictates blade angle specificity and platform durability requirements, with femtosecond laser integration fragmenting instrument specifications.
- Cataract Surgery:Microincision techniques demand 1.8-2.2mm clear corneal incisions with minimal endothelial cell loss. Aging demographics in Japan, Germany, and the United States sustain procedure volume expansion.
- Refractive Surgery:LASIK and PRK procedures require precise flap creation and stromal bed preparation. Femtosecond laser adjunct adoption multiplies blade specificity requirements in premium suites.
- Glaucoma Surgery:Trabeculectomy and minimally invasive glaucoma surgery utilize specialized blade angles for scleral flap construction.
- Corneal Surgery:Penetrating and lamellar keratoplasty procedures demand donor tissue preparation instruments.
Cataract surgery anchors volume leadership, with refractive surgery gaining share fastest on laser platform proliferation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered precision ophthalmic instrument manufacturing through its optical heritage in Jena and Wetzlar, establishing quality benchmarks that shaped global blade specifications. Japanese and American firms later scaled production, while Chinese and Indian manufacturers now drive volume expansion in disposable segments.
United States
Ambulatory surgical centers in Texas, Florida, and California negotiate direct disposable knife contracts for high-volume cataract workflows. FDA 510(k) clearance pathways govern blade biocompatibility and sterility assurance for market access. The Dallas-Fort Worth metroplex anchors distribution networks serving outpatient ophthalmic clinics across the Sun Belt.
Germany
EU MDR reprocessing validation mandates are dismantling central sterile supply departments in university hospitals across Bavaria and Baden-Württemberg. The EU Green Deal's medical device sustainability benchmarks are accelerating write-downs on legacy sterilization infrastructure. Tuttlingen remains the dominant industrial cluster for precision surgical instrument manufacturing, with manufacturers pivoting toward single-use platforms.
Japan
Aging demographics are expanding cataract surgery volumes in Kanto and Kansai regions, sustaining demand for microincision blades. METI-directed fee schedule revisions are compressing reimbursement for reusable instrument platforms. Nagoya's medical device corridor hosts specialized manufacturers supplying diamond-turned keratome instruments to domestic refractive surgery suites.
China
NMPA reclassification of microkeratome blades to higher scrutiny tiers is elevating compliance barriers for domestic and foreign manufacturers. The country's national pharmaceutical regulator now demands pre-qualified sterilization dossiers for market authorization. Shanghai and Suzhou industrial zones concentrate contract manufacturing operations serving both domestic consumption and export markets.
India
Private ophthalmic clinic chains in Maharashtra and Karnataka are adopting premium blade specificity for refractive procedure differentiation. The country's national pharmaceutical regulator enforces CDSCO medical device rules for imported and domestically manufactured instruments. Ahmedabad's surgical instrument cluster is scaling stainless steel disposable production for Middle East and African export markets.
Global Ophthalmic Knives Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the ophthalmic knives landscape, with integrated manufacturers maintaining captive diamond-turning capabilities while specialist firms outsource substrate fabrication. Market structure tilts toward consolidation at the premium tier, where scale advantages in sterilization validation and regulatory dossier maintenance create defensive moats. Three archetypes dominate: vertically integrated ophthalmic conglomerates, specialized blade substrate manufacturers, and regional disposable contract producers. Competitive moves center on backward integration into synthetic diamond supply and direct contracting with ambulatory surgical center buying groups.
Within the integrated ophthalmic conglomerate tier, Alcon and Bausch + Lomb exemplify scale-driven positioning through in-house production of diamond-turned blades and controlled distribution networks spanning North American and Asia-Pacific surgical suites. MANI Inc. occupies a specialist position, representing Japanese precision manufacturing archetypes with concentrated expertise in ceramic-coating technologies for microincision instruments.
| Leading Market Players |
|---|
| Alcon |
| Bausch + Lomb |
| Diamatrix Ltd. |
| Teleflex Incorporated |
| MANI Inc. |
| Ophtechnics Unlimited |
| HAI Laboratories, Inc. |
| Paramount Surgimed Ltd. |
| BVI |
| Others |
Supply & Pricing Matrix
The EU Green Deal's medical device sustainability benchmarks gate qualified supply and premium-tier pricing access, as manufacturers must absorb sterilization validation costs to serve German and French hospital systems while spot-priced disposable contracts dominate United States ambulatory surgical center procurement.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates diamond-turned ceramic blades from medical-grade stainless configurations and commodity polypropylene handles. Price differentiation rests on EU MDR certification grade and volume scale in direct ASC contracts. Cost compression in the standard tier is intensifying because Japanese reimbursement compression squeezes titanium-alloy platform margins. Ambulatory surgical centers in Texas and Florida exhibit highest price sensitivity, while academic medical centers in South Korea and the United States show lowest sensitivity for robotic-assisted platform compatibility.
Supply Chain Analysis
Dual-sourcing requirements from United States ASC buying groups and Japanese hospital systems mandate multi-supplier qualification for synthetic diamond substrates and ceramic-coating expertise. Geographic supply concentration centers on Germany's Tuttlingen precision cluster, Japan's Nagoya medical device corridor, and China's Shanghai-Suzhou contract manufacturing zones. Raw material dependencies draw from synthetic monocrystalline diamond feedstock, medical-grade 440C stainless steel, and zirconia ceramic powders. Single-source vulnerability in qualified diamond-turning capacity exposes manufacturers to FDA 510(k) clearance delays. Distribution runs through direct vendor relationships with ASC buying groups and traditional distributor networks serving integrated hospital delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, with EU MDR Class IIa reprocessing validation mandates permanently dismantling sterilization infrastructure and forcing procurement economics toward single-use platforms.
For Market Incumbents: To counter femtosecond laser substitution in premium refractive centers, Alcon and Bausch + Lomb should deepen backward integration into synthetic diamond supply to secure qualified substrate access. Capacity addition in Tuttlingen and Nagoya industrial clusters defends margin position against stranded asset risk from sterilization equipment write-downs. Certification investment in China NMPA pre-qualified sterilization dossiers captures first-mover advantage from microkeratome blade reclassification. For New Entrants and Emerging Players: Launch via direct ASC spot-pricing contracts in Texas, Florida, and California to bypass traditional hospital procurement committee overhead. White-space targets include ceramic-coated microincision instruments for cataract workflows and serialized blade tracking systems for EU MDR EUDAMED compliance. The most penetrable segment is United States ambulatory surgical centers adopting high-volume disposable contracts. For Investors and Strategic Acquirers: Roll-up economics work for specialized ceramic-coating substrate manufacturers because ISO 13485 certification backlogs and notified body capacity constraints create defensive moats against mid-tier competition. Long-term viability favors platforms with captive sterilization validation capabilities and direct ASC channel control. The signal to watch is Japan METI fee schedule revisions compressing reusable instrument reimbursement margins.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Sterilization Dossier Pre-Qualification | Accelerates hospital procurement transitions to disposable platforms in Germany and France. |
| Direct ASC Contracting Bypass | Concentrates purchasing power among administrator-led buying groups in Texas and Florida. |
| Synthetic Diamond Backward Integration | Secures qualified substrate supply against input volatility and qualification delays. |
| Ceramic-Coating R&D Convergence | Opens premium positioning in microincision cataract surgery with zirconia edge retention. |
| Serialized Blade Tracking Infrastructure | Satisfies EU MDR Unique Device Identification mandates for EUDAMED database integration. |
Research Methodology
Multiple input streams — primary interviews with ophthalmic surgeons and ASC procurement directors, secondary validation through FDA 510(k) filings and EU MDR notified body records, and trade data from German and Japanese surgical instrument associations — were reconciled through bottom-up and top-down triangulation. Stakeholder consultations included biomedical engineers at academic medical centers, GPO contracts managers, and sterilization validation specialists. Secondary sources encompassed hospital procurement databases, CMS Medicare reimbursement schedules, and PMDA fee schedule revisions.
Data-stream reconciliation anchored volume and value outputs across the projection horizon, with segmentation modeled by product type, material substrate, end-user configuration, application procedure, and regional regulatory cluster. CAGRs were derived from procedure volume trajectories and platform replacement cycle analysis. Industry-specific forecast inputs incorporated femtosecond laser adoption curves and EU MDR compliance cost absorption rates.
Several conditions sit outside the modeled scope, including geopolitical disruption to synthetic diamond supply zones and unannounced regulatory reclassification of additional blade categories. Forecasts reflect documented assumptions regarding reimbursement stability and sterilization infrastructure dismantlement timelines. Deviation in Japan METI fee schedule compression or China NMPA enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
United Kingdom Ophthalmology Devices Market
Ophthalmology
Global Fundus Cameras Market
Ophthalmology
Retinal Vein Occlusion Treatment Market
Ophthalmology
Ophthalmic Drugs and Devices Market
Ophthalmology
Leber Congenital Amaurosis Market
Ophthalmology
Retinal Disorder Treatment Market
Ophthalmology
Ptosis Treatment Market
Ophthalmology
North America Ophthalmic Devices and Drugs Market
Ophthalmology
Asia-Pacific Conjunctivitis Treatment Market
Ophthalmology
Presbyopia Treatment Market
Ophthalmology
Ocular Inserts Market
Ophthalmology
Europe Ophthalmology Market
Ophthalmology
Global Automated Ophthalmic Perimeters Market
Ophthalmology
Australia Ophthalmic Devices Market
Ophthalmology
Thyroid Eye Disease Treatment Market
Ophthalmology
Uveal Melanoma Market