
 Gasoline Gensets Market | 2026-2036
Gasoline Gensets Market Size, Share, and Industry Trends Forecast 2026-2036
Gasoline Gensets Market Analysis
Residential buyers are redrawing demand patterns for gasoline gensets as home-office electrification and outage sensitivity push homeowners toward inverter and standby units. Generac Power Systems anchors North American distribution through dealer networks and service infrastructure. Honda Motor differentiates via portable inverter technology with noise suppression and fuel efficiency. Briggs & Stratton competes on engine manufacturing scale and retail channel penetration across big-box hardware chains.
Gasoline gensets are spark-ignition internal combustion engines coupled with alternators that convert mechanical energy into electrical power, typically operating at 3,000 or 3,600 RPM for 50 Hz or 60 Hz output, with power ratings from under 1 kW to 15 kW for portable units. Their primary purpose is to deliver mobile or emergency alternating current where grid connections are unavailable, unstable, or insufficient for critical loads. Portable gensets occupy the highest unit volume tier due to recreational and light construction use, while standby installations command premium pricing through automatic transfer switch integration and permanent fuel connections. Inverter technology is capturing margin pools as electronic load matching reduces fuel consumption and enables sensitive electronics operation.
The US EPA Tier 4 emissions standards and California Air Resources Board small off-road engine regulations are forcing design changes in carburetion, catalytic aftertreatment, and evaporative emissions control for gasoline gensets sold in North America. The EU F-Gas Regulation and REACH chemical restrictions affect ancillary components including refrigerants in hybrid cooling systems and materials in fuel tanks and hoses. Stakeholders must monitor regulatory divergence between jurisdictions as compliance costs fragment product platforms and determine which engine families remain economically viable across export markets.
Market Dynamics
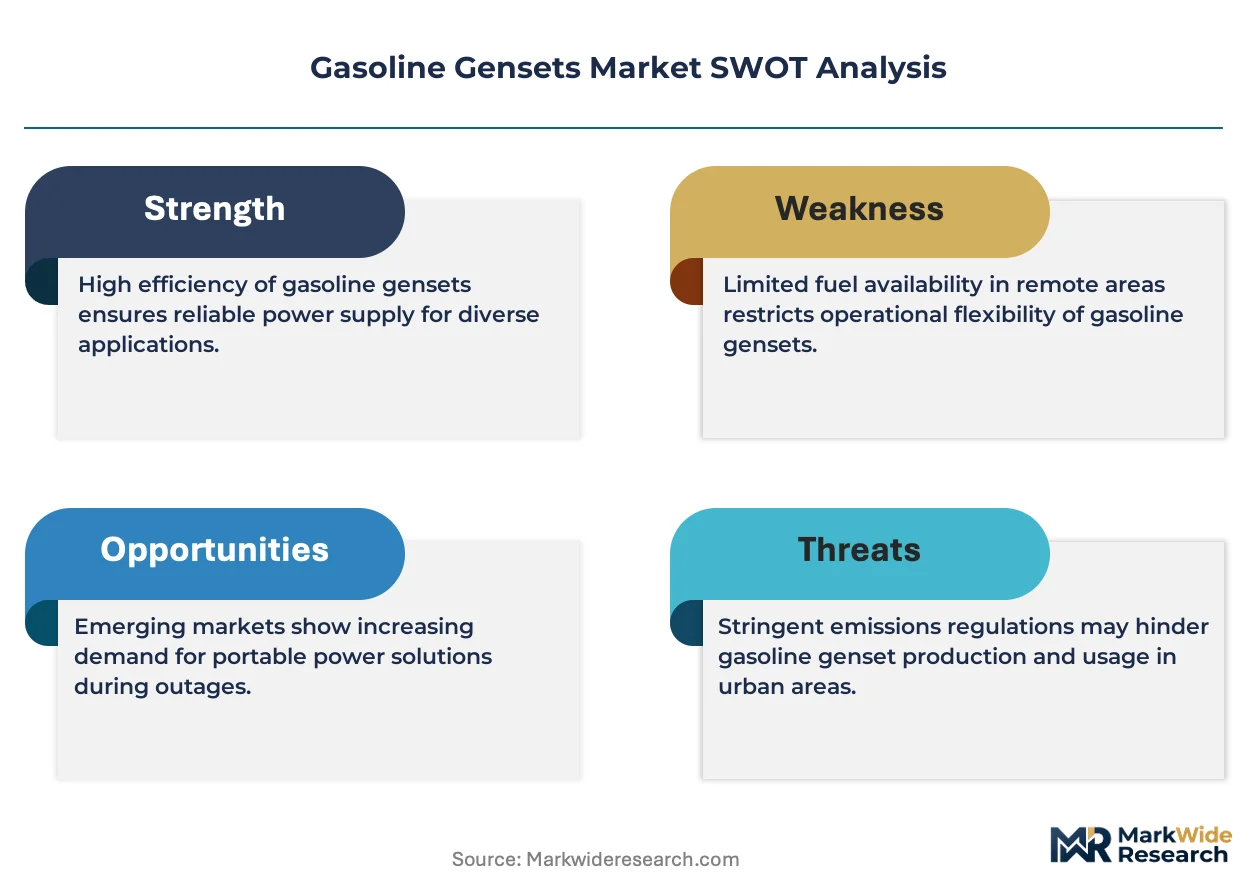
Stringent emissions compliance is fragmenting gasoline genset product platforms as manufacturers redesign carburetion systems, catalytic aftertreatment, and fuel tank vapor recovery to satisfy divergent certification requirements across export jurisdictions.
Growth Catalysts
- Telecom infrastructure electrification:Tower operators across Indonesia, Philippines, and Vietnam are deploying portable gensets for off-grid and backup power as mobile data traffic surges. Grid intermittency in archipelago regions accelerates genset procurement cycles.
- US EPA Tier 4 standards:Certification mandates for small spark-ignition engines are consolidating compliant supplier bases and creating price premiums for certified equipment. Manufacturers with pre-certified engine families capture distributor shelf space.
- Inverter load-matching technology:Electronic fuel injection and variable-speed operation reduce consumption rates for sensitive electronics users. Home-office electrification drives specification upgrades from conventional portable to inverter units.
Market Restraints
- Aluminum and copper price volatility:Alternator windings and engine block castings face input cost pressure from commodity markets. Margin compression limits R&D reinvestment for mid-tier manufacturers.
- Chinese engine supply concentration:Sourcing of small-displacement powerplants clusters in Zhejiang and Chongqing manufacturing corridors. Geopolitical friction or logistics disruption threatens component availability.
- Stationary diesel substitution:Commercial and industrial buyers with continuous runtime requirements favor diesel gensets for fuel efficiency and longevity. Gasoline units face displacement in standby applications above 10 kW.
Strategic Opportunities
- Indonesia's outer island electrification:PLN grid extension lags in Maluku, Papua, and Nusa Tenggara. Distributed genset leasing models address rural commercial demand without capital purchase barriers.
- EU F-Gas Regulation phase-down:Hybrid cooling systems using low-GWP refrigerants create specification differentiation for telecom shelter applications. First-movers secure framework contract eligibility with European tower operators.
- Direct-to-contractor e-commerce:Amazon Business and specialized construction equipment platforms disintermediate traditional dealer networks. Digital fulfillment reduces working capital requirements for inventory-light entrants.
Industry Challenges
- Small-engine calibration expertise:EPA and CARB certification demands specialized emissions testing and durability validation. Talent scarcity in combustion engineering constrains product development timelines.
- Dual-fuel platform complexity:LPG compatibility kits and tri-fuel carburetion systems require additional homologation and field service training. Integration costs erode price competitiveness against single-fuel alternatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gasoline Gensets Market |
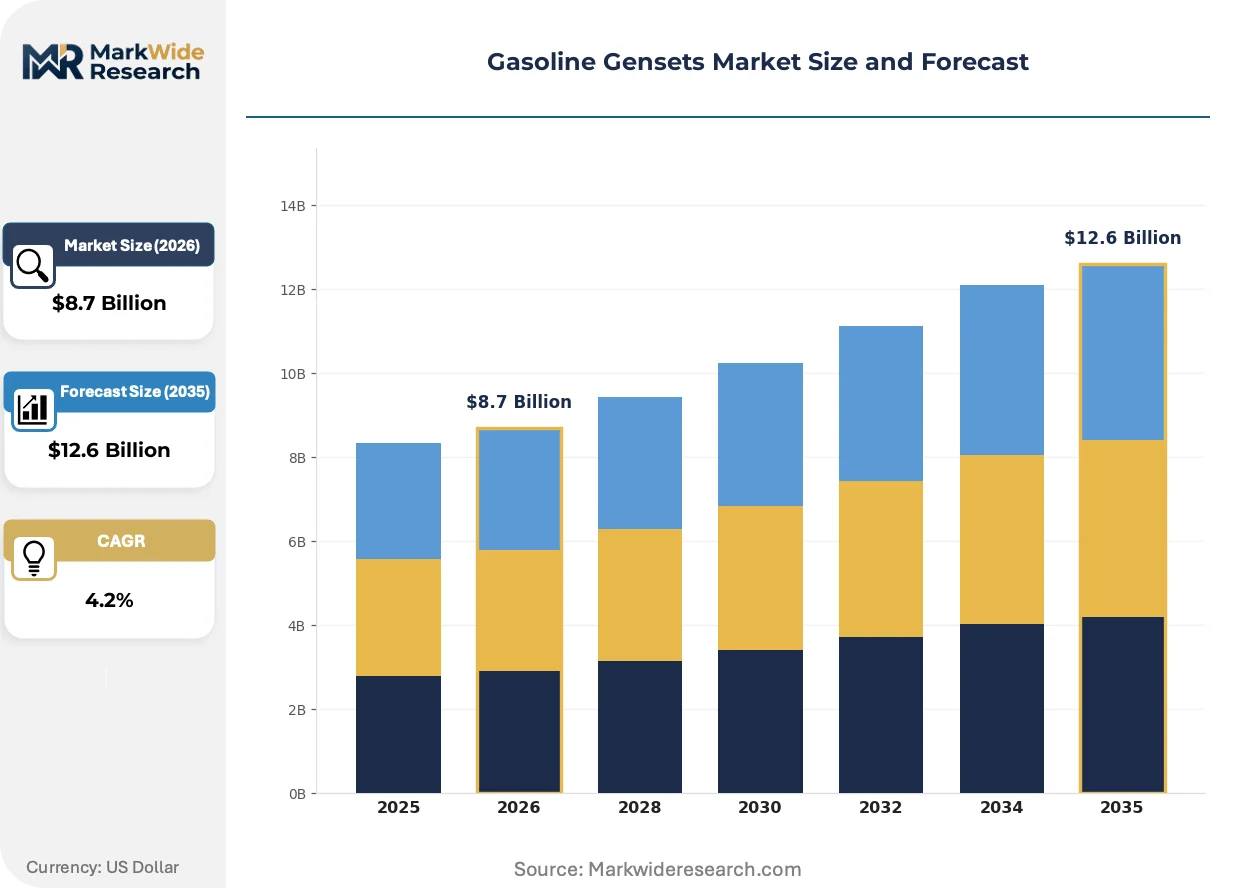
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $12.6 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Standby, Prime, Inverter End User: Residential, Commercial, Industrial, Construction Distribution Channel: Direct Sales, Retail, Online, Wholesale Technology: Conventional, Eco-friendly, Auto-start, Hybrid |
| Companies Covered | Generac Power Systems, Honda Motor, Briggs & Stratton, Yamaha Motor, Champion Power Equipment, Atlas Copco, Cummins, Kohler, FIRMAN Power Equipment, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gasoline Gensets Market Emerging Trajectories
Digital load management and connected monitoring capabilities are redefining genset value propositions as buyers prioritize fuel accountability and predictive maintenance over raw power output specifications.
Smart inverter gensets with Bluetooth-enabled fuel monitoring and automatic idle-down are bifurcating the portable segment. Recreational vehicle owners and residential backup buyers are adopting these units at premium price points. Conventional contractor-grade portables face compression in margin pools as feature differentiation shifts toward electronics integration rather than displacement scaling.
California Air Resources Board small off-road engine regulations are forcing evaporative emissions redesigns. Fuel tank permeation standards and carbon canister integration add component cost and assembly complexity. Manufacturers serving the US West Coast market are responding with California-specific SKUs that carry 15-20% retail price premiums over 49-state equivalents.
Subscription-based power-as-a-service models are emerging in Southeast Asian telecom infrastructure. Tower operators in Indonesia and Philippines are unbundling genset ownership from maintenance and fuel logistics. Equipment vendors retain asset control while contracting for uptime guarantees, shifting balance sheet risk and creating recurring revenue streams.
Gasoline Gensets Market Segmentation
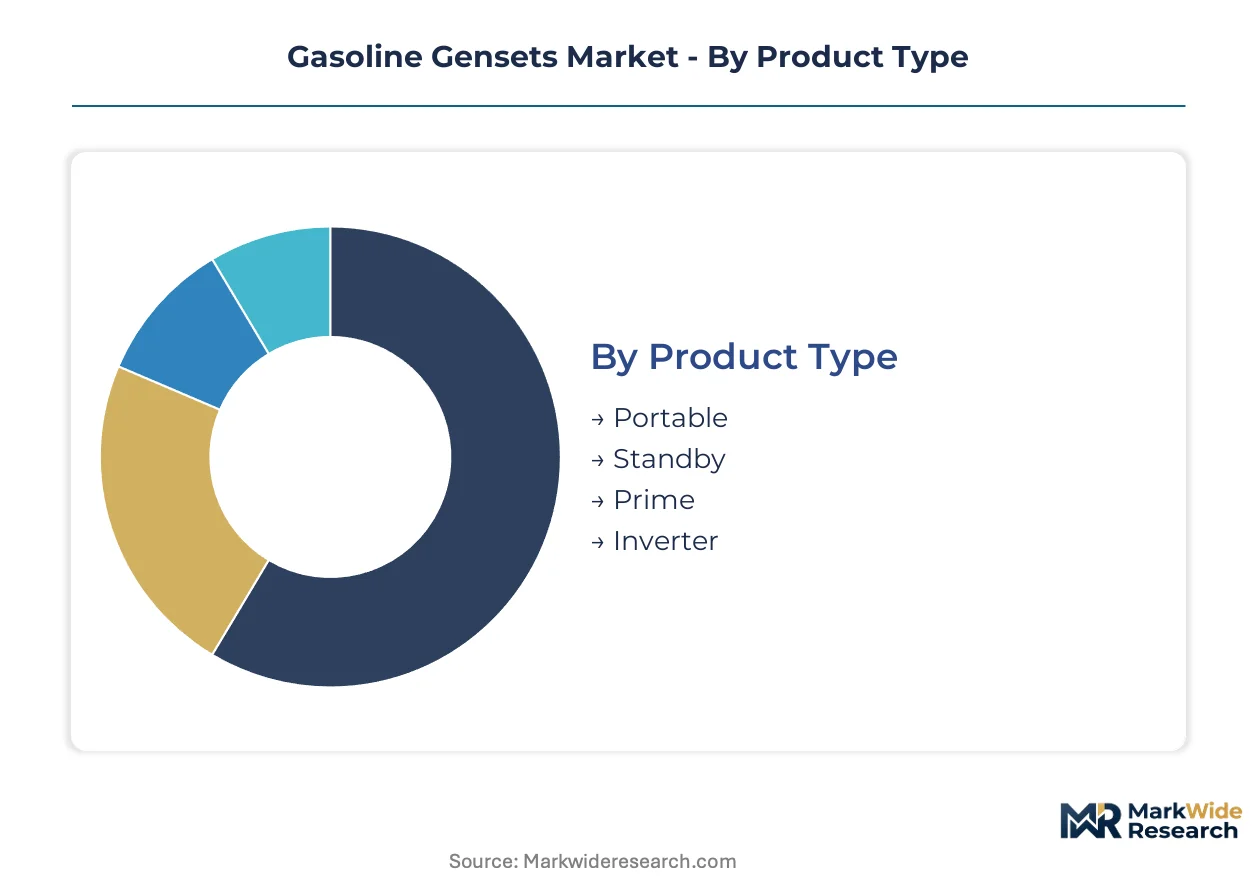
Segmentation in gasoline gensets reveals how product architecture, buyer economics, and channel access intersect. Channel strategy varies sharply across portable versus standby units, while inverter technology commands distinct margin pools through electronics integration.
Product Type:
Portable units flow through retail and e-commerce channels with minimal installation support, while standby systems require dealer networks with electrical contractor relationships.
- Portable:Units below 8 kW dominate unit volume through recreational and light construction applications. Demand concentrates in Indonesia's archipelago regions where PLN grid reliability remains intermittent and tower operators deploy fleets for telecom backup.
- Inverter:Electronic load-matching engines operate at variable speeds to reduce fuel consumption and enable sensitive electronics operation. Home-office electrification in California and Texas is driving specification upgrades from conventional portables, with CARB-compliant models carrying retail premiums.
- Standby:Fixed installations with automatic transfer switches require certified electrical contractors for placement. Dealer network density determines market access.
- Prime:Continuous-duty applications favor diesel alternatives above 10 kW, constraining gasoline share to sub-utility runtime needs.
Portable dominates installed base. Inverter is where expansion concentrates.
End User:
Cost tier stratification separates premium automatic-start residential systems from economy contractor-grade portables.
- Residential:Backup power sensitivity and home-office electrification push buyers toward inverter and standby configurations with noise suppression. Outage frequency in hurricane-prone US states accelerates adoption.
- Commercial:Retail and food service operations require UPS-grade power quality for point-of-sale systems. Runtime economics favor diesel above 15 kW.
- Industrial:Manufacturing facilities with critical process loads specify automatic transfer integration. Gasoline faces displacement where runtime exceeds 500 annual hours.
- Construction:Light commercial building sites drive portable unit procurement through equipment rental channels. Durability specifications prioritize frame construction over electronic features.
Construction commands highest unit velocity. Residential is climbing the fastest on value per unit.
Distribution Channel:
Volume concentration separates high-velocity retail from relationship-driven direct sales with institutional buyers.
- Retail:Big-box hardware chains and farm supply stores stock portable units for immediate pickup. Seasonal demand surges precede hurricane and winter storm seasons.
- Online:Amazon Business and specialized construction platforms are disintermediating traditional dealer networks for contractor procurement. Digital fulfillment reduces working capital for inventory-light entrants.
- Direct Sales:OEM relationships with telecom tower operators and construction fleets bypass distribution markups. Framework contracts lock in multi-year supply agreements.
- Wholesale:Electrical distributors and equipment rental companies aggregate demand from smaller contractors. Credit terms and bulk pricing determine loyalty.
Retail holds greatest unit throughput. Online is gaining share fastest on working capital efficiency.
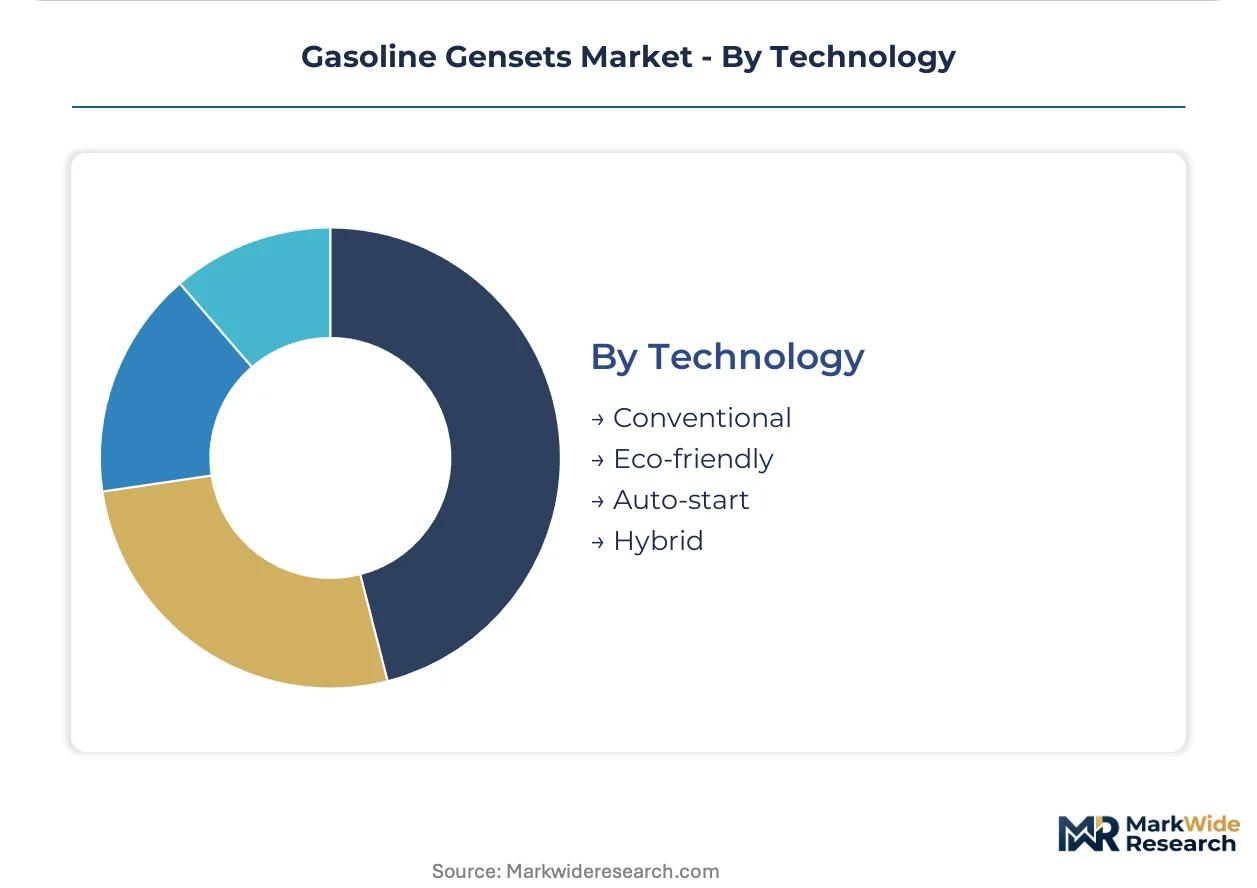
Technology:
Maturity gradients separate legacy carbureted platforms from emerging electronic fuel injection and hybrid architectures.
- Conventional:Fixed-speed carbureted engines dominate contractor-grade portables on first-cost competitiveness. EPA Tier 4 certification is consolidating compliant supplier bases.
- Eco-friendly:Low-emission catalytic aftertreatment and evaporative emissions control add component cost for California ARB compliance. West Coast SKUs carry 15-20% retail premiums.
- Auto-start:Battery-maintained standby systems with automatic transfer switches require permanent fuel connections and electrical integration. Installation complexity limits self-service purchase.
- Hybrid:Battery-genset combinations with solar charging capability address telecom shelter applications. EU F-Gas Regulation phase-down creates specification differentiation for low-GWP refrigerant integration.
Conventional anchors production volume. Hybrid shows steepest expansion trajectory on telecom infrastructure electrification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese manufacturers in Zhejiang and Chongqing supply engine blocks and alternator components to Southeast Asian telecom operators and North American retail distributors. Trade corridors link these production clusters with demand centers in Indonesia's outer islands and hurricane-prone US states.
United States
Backup power procurement accelerates across Texas and Florida as grid instability from extreme weather events drives homeowner specification of inverter and standby units. EPA Tier 4 certification requirements for small spark-ignition engines consolidate compliant supplier bases and create price premiums for certified equipment. Wisconsin anchors engine manufacturing concentration with vertically integrated producers serving dealer networks nationwide.
Indonesia
Telecom tower operators in Maluku, Papua, and Nusa Tenggara deploy portable genset fleets for off-grid and backup power as mobile data traffic surges. PLN grid extension lags in archipelago regions, accelerating genset procurement cycles for rural commercial electrification. Jakarta-based distributors coordinate leasing models that address capital purchase barriers for outer island enterprises.
China
Zhejiang and Chongqing manufacturing corridors concentrate small-displacement powerplant production for export to Southeast Asian and North American markets. Domestic demand concentrates in construction and rural electrification applications. Shanghai and Shenzhen serve as export logistics hubs for containerized genset shipments.
Germany
EU F-Gas Regulation phase-down drives specification differentiation for hybrid cooling systems in telecom shelter applications. REACH chemical restrictions affect fuel tank and hose materials compliance. Bavaria hosts precision engineering clusters developing low-GWP refrigerant integration for European tower operator framework contracts.
Philippines
Mobile network expansion across Visayas and Mindanao requires distributed power solutions where grid reliability remains intermittent. Subscription-based power-as-a-service models emerge as tower operators unbundle genset ownership from maintenance logistics. Cebu and Davao anchor regional distribution for equipment leasing to rural commercial sites.
Gasoline Gensets Market Vendor Landscape
Player mix skews toward diversified power equipment conglomerates with captive engine manufacturing and specialized portable generator fabricators sourcing from Chinese supply bases. Market structure exhibits tiered concentration with premium-tier automatic-start standby systems and economy-grade contractor portables occupying distinct margin pools. Strategic archetypes include vertically integrated engine-alternator assemblers, retail-channel-dependent volume players, and telecom-direct leasing operators. Competitive moves center on California ARB pre-certification for West Coast market access and direct-to-contractor e-commerce platform development.
Among North American power equipment specialists, Generac Power Systems, Honda Motor, and Briggs & Stratton exemplify divergent competitive positioning. Generac represents the vertically integrated standby systems archetype with dealer network density determining market access. Honda occupies the premium portable inverter tier where noise suppression and fuel efficiency command retail premiums. Briggs & Stratton exemplifies engine manufacturing scale leveraged across retail channel penetration. These three anchors illustrate how certification compliance, channel control, and technology differentiation separate margin pools in a fragmented competitive structure.
| Leading Market Players |
|---|
| Generac Power Systems |
| Honda Motor |
| Briggs & Stratton |
| Yamaha Motor |
| Champion Power Equipment |
| Atlas Copco |
| Cummins |
| Kohler |
| FIRMAN Power Equipment |
| Others |
Supply Flow & Price Mechanics
US EPA Tier 4 certification requirements for small spark-ignition engines simultaneously gate supplier qualification and stratify retail price tiers, as compliant engine families command shelf-space premiums while non-certified alternatives face market exclusion. This regulatory filtering concentrates pricing power among pre-certified manufacturers while fragmenting product platforms across export jurisdictions.
Pricing Analysis
Conventional carbureted portable units, inverter-enabled electronic load-matching systems, and California ARB-compliant premium SKUs occupy distinct price bands separated by certification cost and electronics integration. Pricing stratifies across premium, standard, and economy tiers where CARB pre-certification adds 15-20% retail premiums for West Coast market access. Price compression runs through contractor-grade portables as Chinese engine supply concentrates in Zhejiang and Chongqing manufacturing corridors. Construction equipment rental channels exhibit highest price sensitivity, while telecom tower operators prioritize uptime guarantees over unit acquisition cost.
Supply Chain Analysis
Inventory cycles for alternator windings and engine block castings extend lead times when aluminum and copper commodity markets experience volatility. Manufacturing concentrates in China, with Zhejiang and Chongjiang corridors feeding Southeast Asian telecom operators and North American retail distributors. Component sourcing draws from copper wire suppliers in Chile, aluminum smelters in Australia, and precision electronics from South Korea. Single-source vulnerability clusters around small-displacement powerplant families. Distribution runs through dealer networks for standby systems and big-box retail channels for portable units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized emissions testing and combustion engineering talent scarcity constrains product development timelines, compressing competitive windows for certification-compliant engine families. This capability gap separates viable market participants from margin-challenged aspirants.
For Market Incumbents: Shield certified engine family positions by deepening backward integration into carburetion system manufacturing and locking exclusive distributor relationships in hurricane-prone US states. Stationary diesel substitution above 10 kW threatens gasoline standby applications. Prioritize captive supply of catalytic aftertreatment components to defend margin pools against Chinese engine import pressure. For New Entrants and Emerging Players: Differentiate on hybrid cooling system integration for EU telecom shelter applications, where F-Gas Regulation phase-down creates first-mover framework contract eligibility. Indonesia's outer island electrification presents the most penetrable geography, with distributed genset leasing models bypassing capital purchase barriers. Pursue direct-to-contractor e-commerce channels through Amazon Business and specialized construction platforms to disintermediate traditional dealer networks. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across emissions-compliant engine manufacturing as EPA and CARB certification demands specialized testing infrastructure investment. Long-term viability favors vertically integrated assemblers with captive alternator winding capabilities and pre-certified engine platforms. The signal to monitor is California ARB regulatory expansion to additional states, which would amplify compliant equipment pricing premiums.| Strategic Initiative | Industry Significance |
|---|---|
| California ARB Pre-Certification Investment | Secures West Coast market access and 15-20% retail price premiums for compliant SKUs. |
| Hybrid Cooling System Development | Enables EU F-Gas Regulation compliance and framework contract eligibility with European tower operators. |
| Direct-to-Contractor E-Commerce Platform | Reduces working capital requirements and disintermediates traditional dealer networks for portable unit sales. |
| Distributed Genset Leasing Model | Addresses capital purchase barriers in Indonesia's outer islands while retaining asset control. |
| Bluetooth-Enabled Fuel Monitoring Integration | Captures premium portable segment demand from recreational vehicle and residential backup buyers. |
Methodological Framework
Operator-level perspectives from telecom tower maintenance directors, construction equipment rental fleet managers, EPA certification engineers, big-box retail category buyers, and aftermarket service technicians anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation through US EPA certification databases, California ARB evaporative emissions filings, EIA backup power installation records, and customs trade data for engine block imports. Bottom-up unit shipment estimates triangulated against top-down power equipment market sizing.
Sensitivity analysis tested forecast robustness across aluminum and copper price volatility scenarios, EPA enforcement intensity variations, and diesel substitution thresholds. The analytical framework modeled segmentation across product type (portable, inverter, standby), end user (residential, commercial, industrial, construction), distribution channel (retail, online, direct sales, wholesale), and technology tier (conventional, eco-friendly, auto-start, hybrid). CAGRs derived from regression analysis of historical shipment data against macroeconomic indicators and regulatory implementation schedules.
Material uncertainties — commodity price spikes, geopolitical disruption to Chinese engine supply, and regulatory divergence between US and EU jurisdictions — sit outside the modeled envelope. Forecasts reflect documented assumptions about certification timeline adherence and grid reliability trends. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Generators
South America Generator Sets Market
Generators
Dual-Fuel Generator Market
Generators
North America Generator Sets Market
Generators
Asia-Pacific Generator Sets Market
Generators
Gas Generator Market
Generators
Portugal Gas Generator Market
Generators
Residential Gas Generator Market
Generators
South America Portable Generator Market
Generators
Middle-East and Africa Diesel Generator Market
Generators
Power Generator Rental Market
Generators
South America Diesel Generator Market
Generators
Middle-East and Africa Portable Generator Market
Generators
Portable Inverter Generators Market
Generators
Africa Portable Generator Market
Generators
Generator Belt Market
Generators
South Africa Diesel Generator Market