
 Digital Inverter Generator Market | 2026-2036
Digital Inverter Generator Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Inverter Generator Market Insights
Market Context
The premium portable segment is consolidating around quiet-operation and parallel-capability feature sets, while commodity gasoline units face margin compression from generic Asian imports. Honda Motor leverages its proprietary sine-wave inverter technology to sustain pricing power in recreational and residential channels. Cummins anchors the standby tier with integrated transfer-switch systems targeting home backup applications. Champion Power Equipment competes aggressively through broad retail distribution and dual-fuel flexibility across the 2-4 kW class.
Technical Definition and Segment Structure
A digital inverter generator converts raw AC output to DC, then inverts it back to clean sine-wave AC through microprocessor-controlled power modules, achieving total harmonic distortion below 3% and enabling precise voltage regulation for sensitive electronics. The portable category dominates unit volume due to camping, tailgating, and light construction use, though standby systems capture disproportionate value per installation. Gasoline fuels the majority of sub-4 kW sales, yet propane and natural gas segments are expanding fastest in residential standby where fuel storage safety and supply continuity matter. The 2-4 kW power band represents the most contested margin pool, balancing runtime, portability, and price accessibility for mainstream consumers.
Regulatory Frame and Outlook
EPA Tier 4 Final and CARB standards in the United States restrict exhaust emissions from small nonroad engines, compelling redesigns of combustion architectures and favoring inverter platforms with optimized fuel injection. The EU F-Gas Regulation and REACH compliance requirements affect sealed-system components and materials sourcing for units sold into Europe. Stakeholders must monitor evolving state-level zero-emission equipment mandates in California and New York, as these jurisdictions increasingly influence national product planning cycles and R&D allocation decisions.
Market Dynamics
EPA Tier 4 Final emission standards are compressing combustion-engine architectures and forcing manufacturers toward inverter platforms with precision fuel injection and after-treatment systems. This regulatory pressure is redrawing competitive boundaries between legacy generator producers and electronics-centric inverter specialists.
Growth Catalysts
- Grid Instability in Target States:Texas and California utilities face recurring outage events. Residential buyers in these states prioritize standby inverter systems with automatic transfer switches.
- Remote Construction Deployment:Light commercial crews operating off-grid job sites demand portable units with parallel capability and sub-60 dB operation.
- CARB Zero-Emission Equipment Mandates:California's advancing timelines for small off-road engine restrictions are accelerating battery-hybrid inverter development cycles.
Market Restraints
- Semiconductor Supply Concentration:IGBT and MOSFET modules for power inversion depend on Asian foundry capacity. Lead times for these components extend 26-40 weeks.
- Copper and Rare Earth Input Volatility:Stator windings and permanent magnets face price swings tied to commodity extraction constraints.
- Technical Ceiling on Power Density:Air-cooled inverter architectures face thermal management limits above 7 kW continuous output.
Strategic Opportunities
- RV and Marine Channel Expansion:Recreational vehicle OEMs are specifying built-in inverter generators as factory options. This bypasses retail margin erosion.
- Natural Gas Conversion Kits:Residential standby users seek fuel flexibility. Propane and natural gas retrofits open recurring service revenue streams.
- Telecom Tower Backup:Cellular infrastructure operators require extended-runtime units with remote monitoring capability.
Industry Challenges
- Power Electronics Talent Scarcity:Inverter firmware development requires embedded systems engineers with motor control expertise. This skill set pools in automotive and aerospace sectors.
- EPA Certification Timeline Compression:New engine families require 18-24 month validation cycles. Product refresh rates lag consumer electronics expectations.
Report Scope
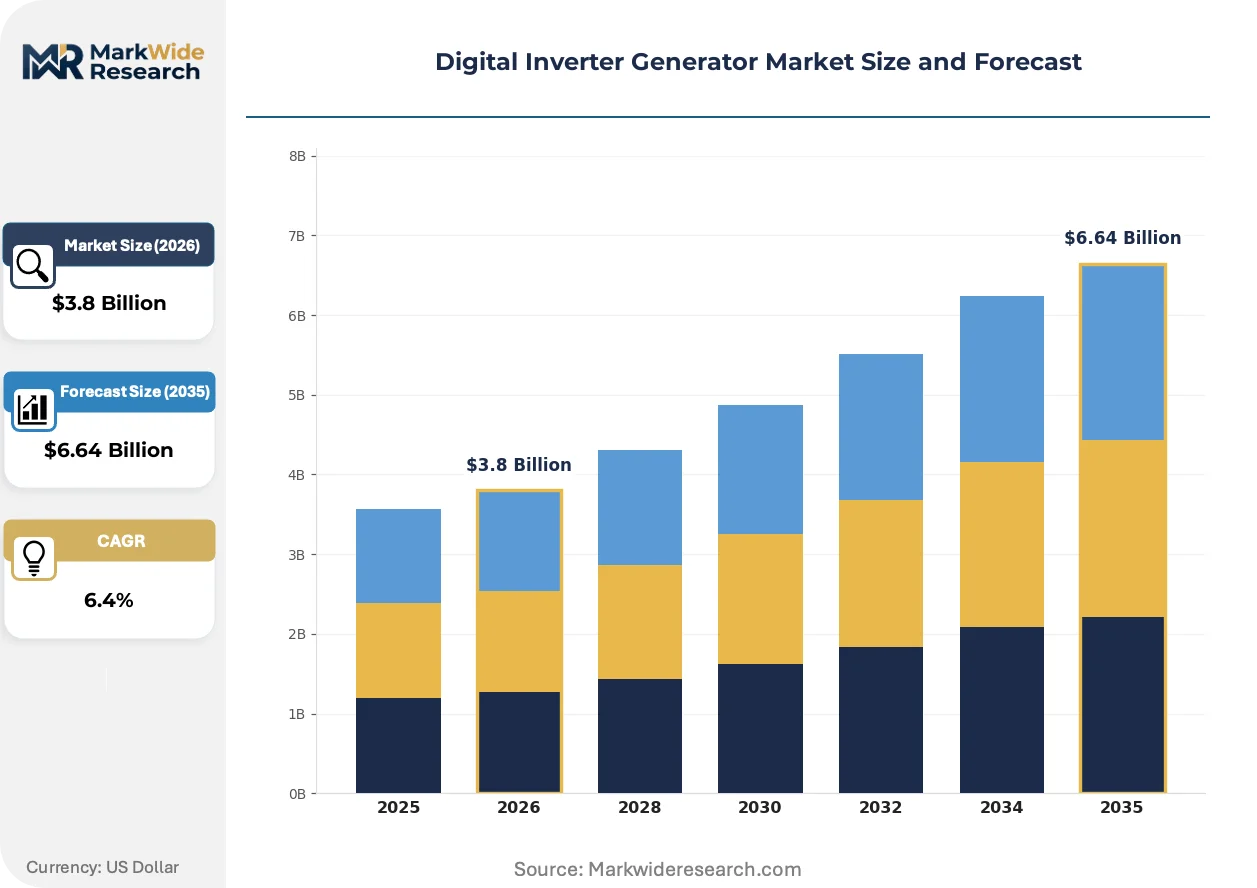
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Inverter Generator Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Portable, Standby, Off-grid, Hybrid Fuel Type: Gasoline, Propane, Diesel, Natural Gas Power Rating: 1-2 kW, 2-4 kW, 4-6 kW, Above 6 kW End User: Residential, Construction, Commercial, Events |
| Companies Covered | Generac Power Systems, Honda Motor, Caterpillar, Cummins, Champion Power Equipment, Briggs & Stratton, Atlas Copco, A-iPower, DuroMax Power Equipment, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Inverter Generator Market Trends and Innovations
Digital inverter generators are absorbing capabilities from adjacent power electronics sectors. Microprocessor control, connectivity modules, and thermal management advances from electric vehicle and solar inverter R&D are migrating into portable and standby units.
Silicon carbide MOSFETs are replacing traditional IGBTs in premium inverter modules. These wide-bandgap semiconductors enable higher switching frequencies and reduced heat sinking requirements. RV OEMs and marine integrators are specifying SiC-based units for weight-sensitive installations. This transition is automating thermal derating calculations that previously required manual engineering review.
EPA Tier 4 Final compliance deadlines are eliminating carbureted engines from the sub-25 hp category. Manufacturers must redesign combustion chambers and add catalytic after-treatment. The 2-4 kW portable segment faces the steepest cost impact as price-sensitive buyers resist premium pricing for fuel-injected architectures. Producers are responding with modular engine families that share emission control components across multiple power ratings.
Buyers are fragmenting across direct-to-consumer e-commerce and specialized dealer channels. Big-box retail captures commodity gasoline units while certified installers dominate standby system sales. The split is most pronounced in Florida and Gulf Coast states where hurricane-driven demand spikes strain inventory planning. Channel-specific SKUs with differentiated warranty terms are proliferating.
Digital Inverter Generator Market Segmentation
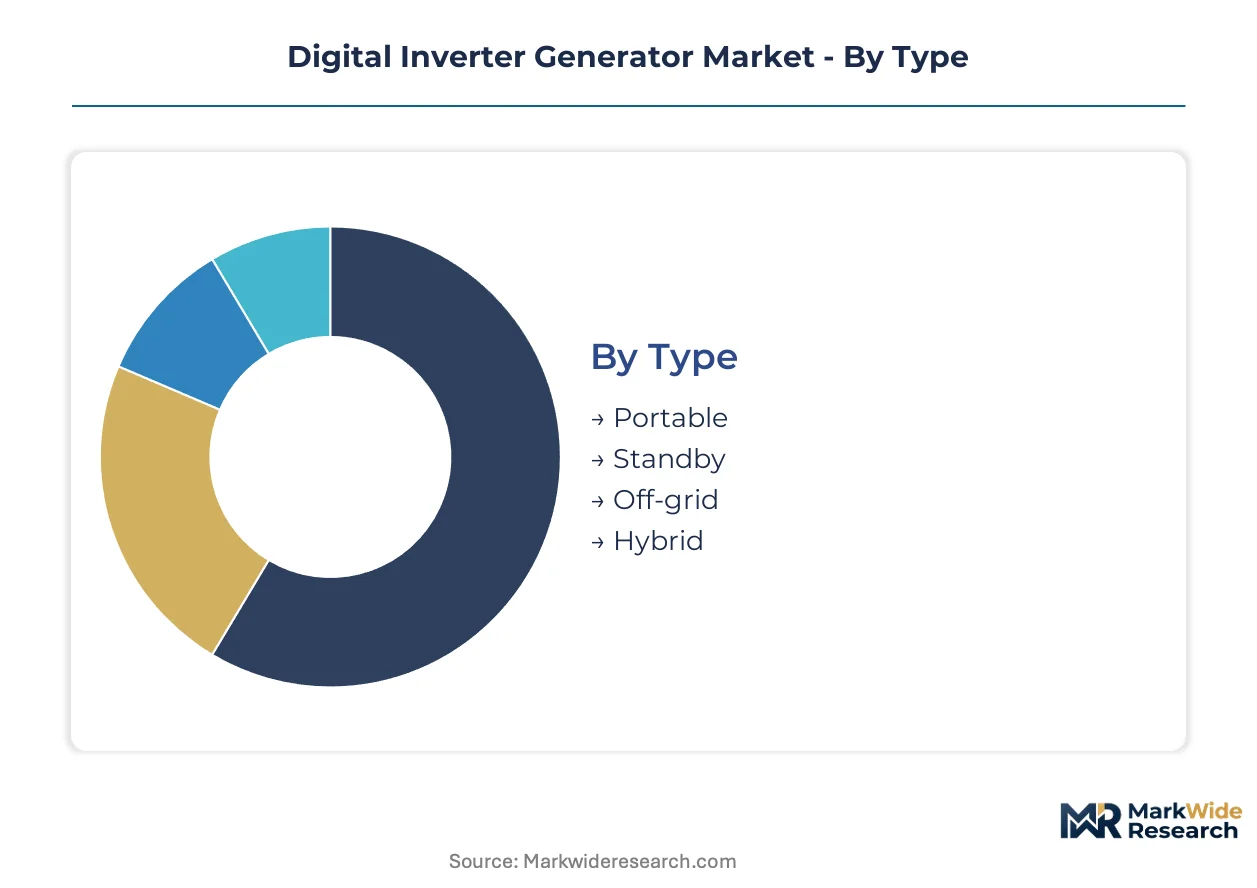
Segmentation in the digital inverter generator market reveals how engineering trade-offs and regulatory pressure concentrate supply in specific configurations. Manufacturers optimize platform architectures around distinct duty cycles and fuel infrastructures, creating divergent margin profiles across each slice.
Type:
Supply concentration clusters around platforms that balance semiconductor content with thermal packaging economics.
- Portable:Units below 75 lbs dominate unit shipments through camping, tailgating, and light contractor channels. Texas and California homeowners facing grid instability are stacking multiple portable units with parallel kits rather than investing in permanent standby installations, stretching inverter module supply.
- Standby:Fixed installations with automatic transfer switches command premium pricing through certified dealer networks. Demand concentrates in hurricane-prone Gulf Coast states and wildfire-affected California counties where extended outages justify permanent fuel connections.
- Off-grid:Remote cabin and telecom tower applications require extended runtime architectures with external fuel tank compatibility.
- Hybrid:Battery-inverter combinations with solar charge controllers are gaining specification in California CARB-compliant zones ahead of small off-road engine phase-outs.
Portable units absorb the bulk of installed capacity; hybrid configurations are expanding most quickly.
Fuel Type:
Cost tier differentiation separates commodity gasoline architectures from specialized gaseous fuel systems requiring certification-heavy fuel train engineering.
- Gasoline:Carbureted engines face EPA Tier 4 Final elimination, forcing EFI redesigns that add $80-120 to bill-of-materials in the sub-4 kW class. Asian contract manufacturers dominate this commoditized segment through big-box retail channels.
- Propane:Cleaner combustion profiles and indefinite fuel storage stability drive adoption in residential standby and food service events. Conversion kit retrofits create recurring service revenue for certified installers in Florida and Texas.
- Diesel:Heavy-duty contractor and agricultural applications favor compression-ignition durability, though particulate after-treatment adds weight and cost.
- Natural Gas:Utility-connected standby systems eliminate fuel logistics entirely. Permitting complexity limits this segment to permanent installations with professional maintenance contracts.
Gasoline retains volume leadership; propane and natural gas are climbing the fastest as emission standards tighten and fuel flexibility becomes a purchase criterion.
Power Rating:
Application-driven sizing creates distinct competitive arenas with different margin and channel characteristics.
- 1-2 kW:Ultralight recreational units prioritize acoustic suppression and compact stowage. RV OEMs are specifying factory-integrated options that bypass retail margin erosion entirely.
- 2-4 kW:The most contested margin pool balances runtime, portability, and price accessibility for mainstream consumers. Champion Power Equipment and Honda Motor compete aggressively here through dual-fuel flexibility versus sine-wave purity positioning.
- 4-6 kW:Light commercial and larger residential loads require parallel-capable or standalone units with enhanced cooling capacity.
- Above 6 kW:Air-cooled inverter architectures hit thermal management ceilings; liquid-cooled designs penetrate commercial standby and construction prime power roles.
The 2-4 kW band commands the largest revenue pool; above 6 kW systems show the steepest expansion trajectory as commercial users replace conventional generators with inverter precision.
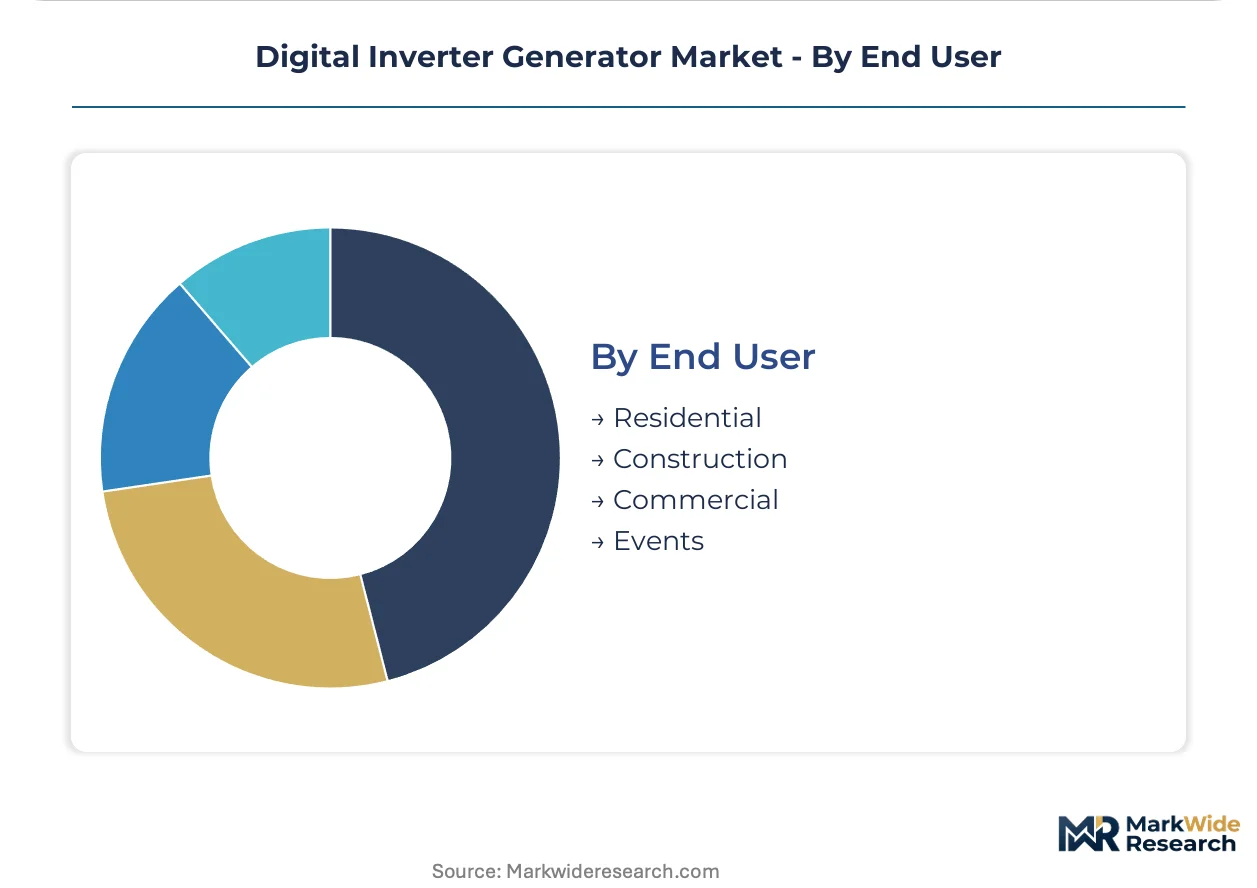
End User:
Customer type determines channel structure, warranty terms, and the balance between retail accessibility and certified installation requirements.
- Residential:Grid instability in Texas and California is shifting purchase patterns from recreational occasional-use toward standby preparedness. Big-box retail captures commodity gasoline sales while electrical contractors dominate transfer-switch-integrated installations.
- Construction:Remote job site crews demand sub-60 dB operation for noise ordinance compliance and parallel capability for equipment scaling. Rental fleet operators are specifying telematics-enabled units for asset tracking.
- Commercial:Retail, hospitality, and healthcare facilities require extended runtime with automatic failover. Fuel storage regulations and fire codes drive specification toward natural gas where utility infrastructure permits.
- Events:Temporary power for outdoor entertainment and catering prioritizes rapid deployment and acoustic discretion. Propane fueling eliminates gasoline vapor hazards in crowded venues.
Residential buyers represent the deepest installed base; construction applications are gaining share fastest as remote work patterns expand off-grid commercial activity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Houston anchors standby generator deployment as Texas utilities struggle with grid reliability following winter storm events and summer peak-load failures.
United States
Texas and California homeowners drive residential standby installations amid recurring outage events. EPA Tier 4 Final standards compress combustion-engine architectures and favor inverter platforms with precision fuel injection. Houston and Dallas-Fort Worth electrical contractors report six-month backlogs for transfer-switch-integrated systems.
Canada
Remote resource extraction camps and northern communities demand portable units with extended runtime and cold-weather starting capability. Environment and Climate Change Canada regulations align with EPA emission frameworks for imported small engines. Alberta oil sands operators specify parallel-capable inverter systems for modular power scaling at drill sites.
Germany
Industrial backup power demand concentrates in manufacturing corridors facing grid instability from renewable intermittency. EU F-Gas Regulation and REACH compliance requirements affect sealed-system components for units sold into the market. Bavarian automotive suppliers specify sine-wave inverter precision for sensitive production line equipment.
Japan
Disaster preparedness culture sustains steady demand for residential and commercial backup systems following earthquake and typhoon events. METI efficiency standards and JIS certification requirements shape product specifications for domestic manufacturers. Osaka-Kobe industrial clusters specify compact inverter units for facility resilience planning.
Australia
Bushfire-prone regions and remote mining operations drive dual demand for residential standby and portable construction units. Australian Design Rules for non-road engines increasingly mirror EPA Tier structures. Western Australia mining camps specify telematics-enabled inverter generators for asset tracking across dispersed sites.
Digital Inverter Generator Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the inverter generator market. Integrated engine-generator manufacturers with foundry and casting capabilities maintain cost advantages in high-volume gasoline segments. Three strategic archetypes dominate: vertically integrated engine specialists, electronics-centric power module designers, and retail-brand assemblers sourcing Asian contract manufacturing. Competitive moves center on modular engine family redesigns for emission compliance and exclusive distribution agreements with big-box retailers and certified installer networks.
Within the premium-tier positioning, Honda Motor exemplifies sine-wave inverter specialization for recreational and residential channels. Champion Power Equipment occupies a position as a retail-distribution and dual-fuel flexibility specialist across the contested 2-4 kW class. Cummins anchors the standby-system tier with integrated transfer-switch architectures targeting home backup applications.
| Leading Market Players |
|---|
| Generac Power Systems |
| Honda Motor |
| Caterpillar |
| Cummins |
| Champion Power Equipment |
| Briggs & Stratton |
| Atlas Copco |
| A-iPower |
| DuroMax Power Equipment |
| Others |
Pricing and Supply Chain Analysis
Captive integration of IGBT and MOSFET module production anchors pricing power for inverter specialists while forcing retail-brand assemblers toward commodity positioning. EPA Tier 4 Final compliance costs concentrate in fuel-injected engine architectures, redrawing margin pools across the 2-4 kW segment where price-sensitive buyers resist premium positioning.
Pricing Analysis
Uptime-based value anchoring dominates standby system pricing, where automatic transfer switch integration commands premium positioning against recreational portable units. Three-tier pricing structure across premium sine-wave purity, standard dual-fuel flexibility, and economy carbureted gasoline segments separates Honda Motor's proprietary inverter technology from Champion Power Equipment's retail-channel positioning. Cost compression in the sub-4 kW gasoline tier intensifies because Asian contract manufacturers flood big-box retail with generic EFI redesigns. Residential standby buyers in Texas and California show lowest price sensitivity, while camping and tailgating consumers in the 1-2 kW class resist fuel-injected premiums.
Supply Chain Analysis
UL and EPA certification gating concentrates qualified supplier pools around established engine-generator manufacturers with validation infrastructure. Manufacturing gravity centers on China for commodity gasoline units, Japan for precision inverter modules, and the United States for standby system assembly serving hurricane-prone markets. Stator windings draw from copper suppliers facing extraction constraints, while permanent magnets rest on rare earth processing concentrated in Asian refining corridors. Single-source vulnerability in wide-bandgap semiconductor foundries threatens SiC MOSFET availability for premium tier production. Distribution runs through certified electrical contractor networks for standby installations and big-box retail for portable recreational sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Semiconductor foundry capacity constraints for power electronics prop pricing power toward inverter specialists with captive module supply or long-term foundry commitments.
For Market Incumbents: Anticipate CARB zero-emission equipment mandates in California accelerating battery-hybrid inverter development cycles, forcing defensive R&D allocation toward silicon carbide thermal management and firmware-controlled fuel injection. Secure backward integration into IGBT module supply or binding capacity reservations with Asian foundries to defend margin position against retail-brand assemblers sourcing generic Asian contract manufacturing. For New Entrants and Emerging Players: EPA Tier 4 Final in the United States opens a window for electronics-centric power module designers lacking legacy carbureted engine exposure to penetrate the 2-4 kW hybrid segment ahead of small off-road engine phase-outs. Target telecom tower backup and RV OEM factory-integration channels where specification bypasses retail margin erosion entirely, using remote monitoring capability as the primary go-to-market wedge. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified industrial conglomerates seeking EPA-certified engine platforms. Long-term viability favors targets with proprietary inverter firmware and established certified installer network relationships over retail-brand assemblers dependent on Asian contract manufacturing. Watch CARB enforcement timelines and foundry capacity expansion announcements as the critical inflection signal for valuation compression or expansion.| Strategic Initiative | Industry Significance |
|---|---|
| SiC MOSFET Module Adoption | Wide-bandgap semiconductors enable higher switching frequencies and reduced thermal derating for weight-sensitive RV and marine installations. |
| Dual-Fuel EFI Engine Family Launch | Modular propane-gasoline architectures share emission control components across multiple power ratings to amortize EPA Tier 4 Final redesign costs. |
| Certified Installer Network Expansion | Exclusive distribution agreements with electrical contractors in Texas and California capture standby system margin pools away from big-box retail. |
| Telematics-Enabled Asset Tracking | Remote monitoring capability addresses cellular infrastructure operator requirements for extended-runtime telecom tower backup applications. |
| Natural Gas Conversion Kit Retrofit Program | Recurring service revenue streams from propane and natural gas retrofits open residential standby fuel flexibility in Florida and Gulf Coast states. |
Research Methodology
Multi-period observation of EPA certification timelines, semiconductor lead time fluctuations, and state-level zero-emission equipment mandate progression anchored the trend analysis, supplemented by interviews with inverter firmware engineers, electrical contractor purchasing managers, RV OEM specification leads, and aftermarket service directors. Secondary validation drew from EPA engine family certification databases, FERC outage event records, customs import data for small nonroad engines, and SEC filings from capital-heavy generator producers. Bottom-up unit shipment modeling triangulated against top-down value estimates across the projection horizon.
Segment-weighting applied differential growth assumptions by power rating band, fuel type compliance trajectory, and end-user channel structure throughout the forecast period. The analytical framework modeled portable, standby, off-grid, and hybrid type segments alongside gasoline, propane, diesel, and natural gas fuel configurations. CAGRs derived from installed base replacement cycles, regulatory compliance deadline impacts, and channel shift elasticity parameters. Forecast inputs incorporated IGBT module availability constraints and state-level grid reliability event frequency as demand drivers.
The model assumes a particular technology adoption path for silicon carbide power electronics; alternative pathways for gallium nitride or advanced IGBT architectures would alter the outlook for thermal management and weight-sensitive applications. Forecasts reflect documented assumptions regarding EPA enforcement consistency and foundry capacity expansion timelines. A model refresh is warranted upon material change in CARB zero-emission equipment mandate acceleration or wide-bandgap semiconductor supply disruption.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Generators
Military Generator Market
Generators
China Generator Sets Market
Generators
Asia-Pacific Generator Sets Market
Generators
Heat Recovery Steam Generator Sales Market
Generators
North America Gasoline Gensets Market
Generators
Marine Gensets Market
Generators
Gasoline Gensets Market
Generators
Global Diesel Gensets Market
Generators
Europe Diesel Generator Market
Generators
South America Diesel Generator Market
Generators
Dual-Fuel Generator Market
Generators
Europe Gas Generator Market
Generators
Onboard Marine Gensets Market
Generators
Gasoline Generator Market
Generators
Silent Generator Market
Generators
Tanzania Diesel Generator Market