
 Halogenerator Market | 2026-2036
Halogenerator Market Size, Share, and Industry Trends Forecast 2026-2036
Halogenerator Market Insights
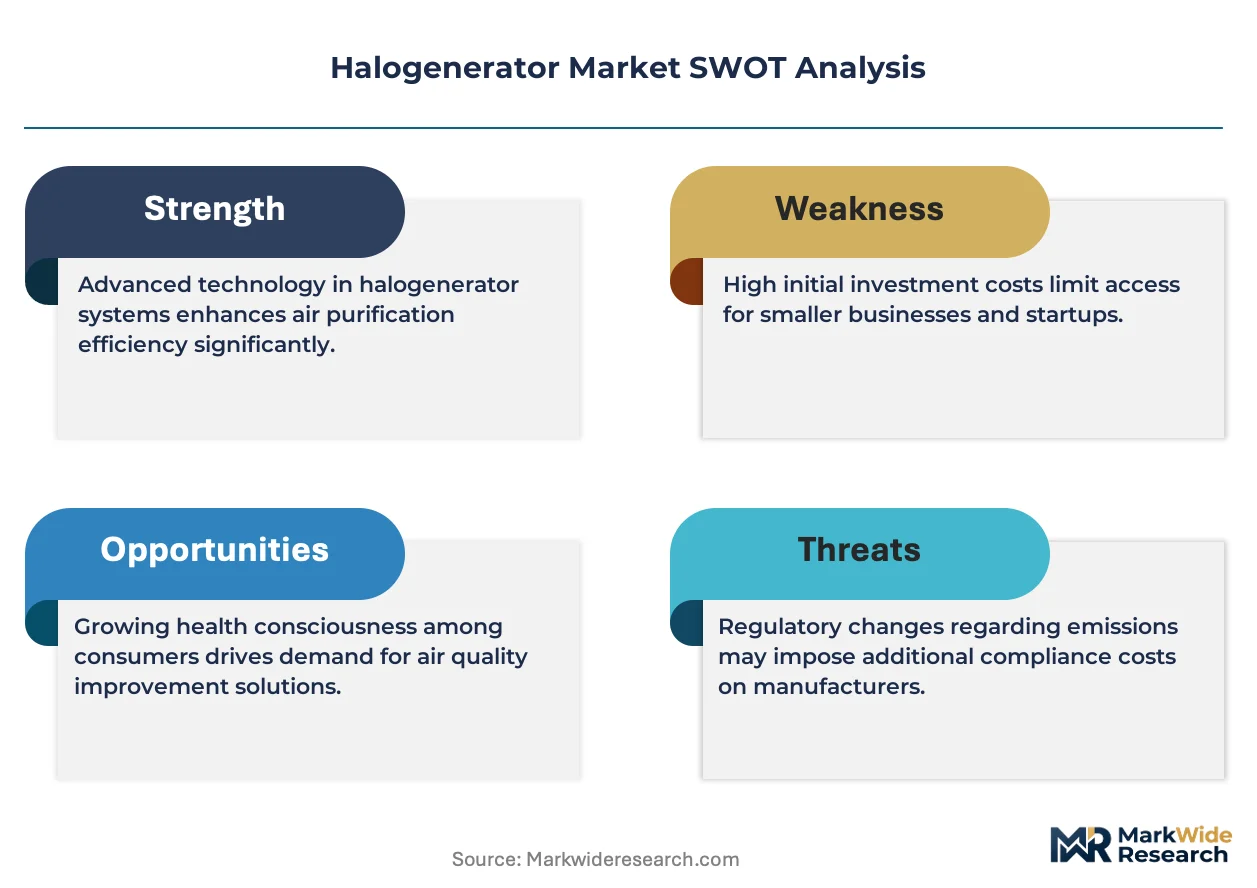
Medical-grade halotherapy certification is reorganizing competitive tiers as buyers prioritize clinical validation over basic salt dispersion. ISO Italia leverages European manufacturing heritage to sustain premium positioning in institutional channels. SaltMed anchors the Central European market with specialized respiratory therapy installations. Halotherapy Solutions competes on automated control integration for wellness center operators seeking reduced staffing overhead.
A halogenerator is an electromechanical device that micronizes pharmaceutical-grade sodium chloride into breathable particles between one and five microns, dispersing them at controlled concentrations for therapeutic inhalation or surface application. The equipment serves commercial wellness operators, medical rehabilitation facilities, and aesthetic clinics seeking non-pharmacological intervention options. Portable units lead volume sales among mobile service providers and boutique wellness startups with limited capital budgets. Wall-mounted systems capture margin pools in hotel spa retrofits where space optimization governs procurement decisions. Dry salt therapy technology dominates the installed base, though ionization technologies are gaining traction among operators targeting differentiation in saturated urban markets.
The FDA classifies certain halogenerator configurations as wellness devices rather than medical equipment, creating a dual-track compliance environment that shapes product development priorities. The EU MDR and REACH frameworks impose substance safety and clinical evidence standards on manufacturers seeking European market access. Stakeholders must monitor evolving classification boundaries between wellness and medical claims as regulatory scrutiny intensifies across major jurisdictions.
Market Dynamics
Medical-grade certification requirements are bifurcating the vendor landscape as institutional buyers demand ISO-validated particle dispersion systems while wellness operators prioritize cost-optimized salt delivery mechanisms.
Growth Catalysts
- EU Medical Device Regulation:MDR classification upgrades are filtering out uncertified manufacturers, creating premium pricing corridors for compliant equipment in German and French rehabilitation centers.
- Respiratory therapy protocols:Pulmonology clinics in the United States are integrating halotherapy into COPD management pathways, expanding reimbursable service categories.
- Hotel spa retrofit wave:Wall-mounted halogenerator installations are accelerating across Dubai and Singapore hospitality assets as wellness amenities become standard competitive fixtures.
Market Restraints
- Pharmaceutical-grade sodium chloride supply:Mining concentration in Pakistan and Ukraine creates input volatility when geopolitical disruptions interrupt bulk salt shipments to European fabricators.
- FDA wellness device classification:The absence of medical-grade pathway clarity blocks institutional reimbursement expansion in the United States, constraining hospital procurement cycles.
- Ionization technology substitution:Himalayan salt cave replication systems compete for wellness center capex budgets without requiring electromechanical micronization equipment.
Strategic Opportunities
- Saudi wellness infrastructure:Vision 2030 hospitality investments are creating demand for turnkey halotherapy installations in Riyadh and Jeddah resort developments.
- Home-use portable segment:Micronization technology convergence with smart home air quality systems is opening direct-to-consumer channels previously inaccessible to commercial equipment vendors.
- REACH substance safety tailwind:European chemical compliance frameworks favor pharmaceutical-grade salt systems over unregulated mineral cave alternatives in aesthetic clinic procurement.
Industry Challenges
- Clinical evidence generation:Randomized controlled trial requirements for MDR Class IIa certification demand 18-24 month validation timelines that strain mid-cap R&D budgets.
- Legacy HVAC integration:Retrofitting controlled particle dispersion into existing climate systems in older hotel properties requires custom engineering that extends installation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Halogenerator Market |
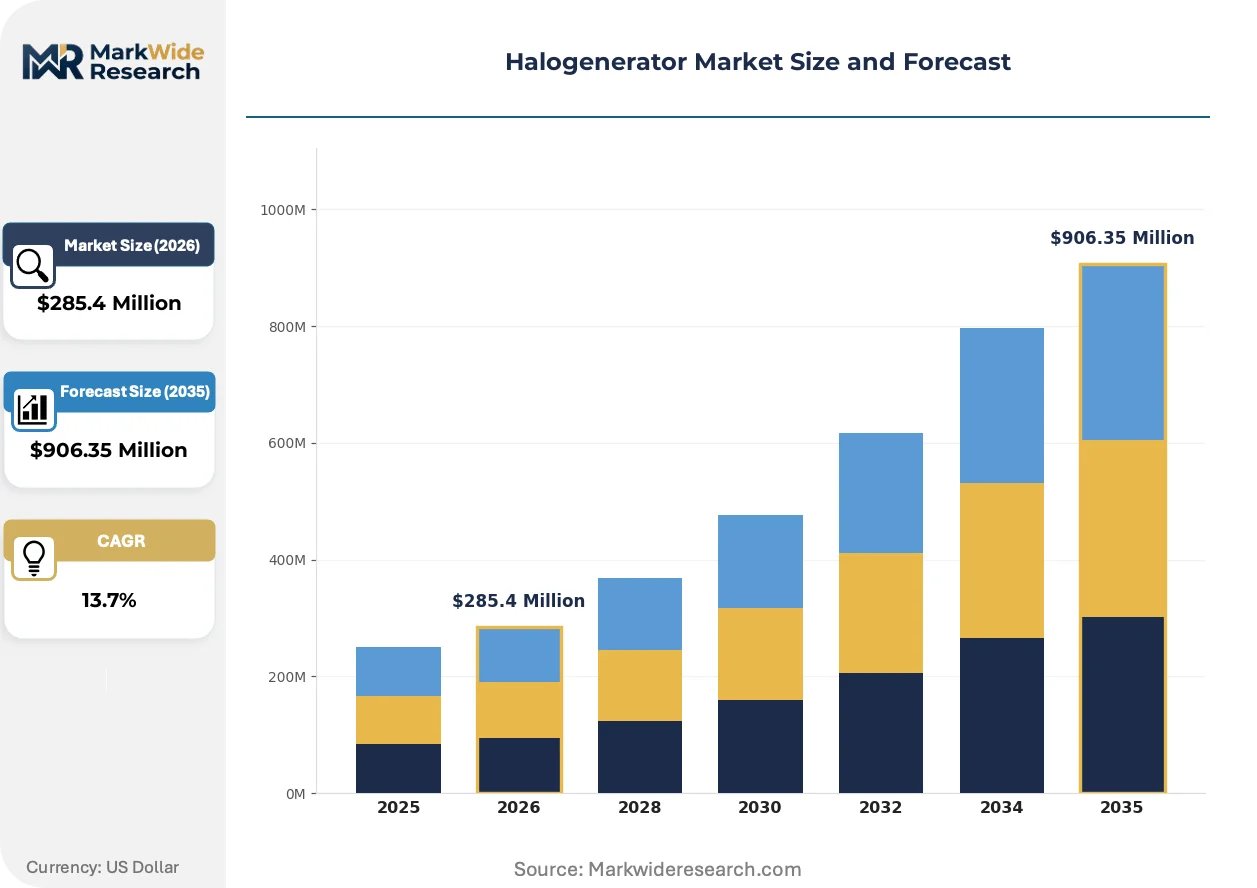
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $906.35 Million |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Units, Wall-Mounted Systems, Commercial Equipment, Industrial Machines End User: Health Clubs, Spas, Hospitals, Wellness Centers Technology: Dry Salt Therapy, Chlorine Free Systems, Ionization Technologies, Automated Controls Application: Respiratory Therapy, Hydrotherapy, Aesthetic Treatments, Aromatherapy |
| Companies Covered | ISO Italia, Stenal, Salt Chamber Inc, Halotherapy Solutions, Halogenerators, The Mark, SaltMed, AlveoTrack, PranaVita, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Halogenerator Market Trends and Innovations
Equipment manufacturers are converging on connected control architectures and modular form factors that reduce installation complexity while enabling remote monitoring capabilities for distributed wellness networks.
Ultrasonic micronization technology is miniaturizing halogenerator footprints from cabinet-scale systems to countertop units without sacrificing particle size precision. Boutique wellness startups in Austin and Melbourne are adopting these compact systems to launch mobile pop-up salt therapy services. The form factor compression is miniaturizing capital barriers for market entry, fragmenting demand across micro-operators previously excluded by equipment costs.
REACH substance safety documentation requirements are mandating pharmaceutical-grade sodium chloride traceability from mine to dispenser. European fabricators must now submit complete supply chain audits to ECHA to maintain market access. German and Austrian rehabilitation clinic procurement committees are prioritizing vendors with full REACH dossier compliance, filtering out competitors dependent on unverified mineral sources.
Wellness center operators are unbundling equipment purchase from maintenance contracts, demanding à-la-carte service tiers based on utilization intensity. Independent spa owners in California and Florida are shifting from bundled five-year agreements to pay-per-session remote monitoring subscriptions. This consumption-pattern shift is compressing vendor recurring revenue visibility while expanding software-enabled service attach rates for control platform providers.
Halogenerator Market Segmentation
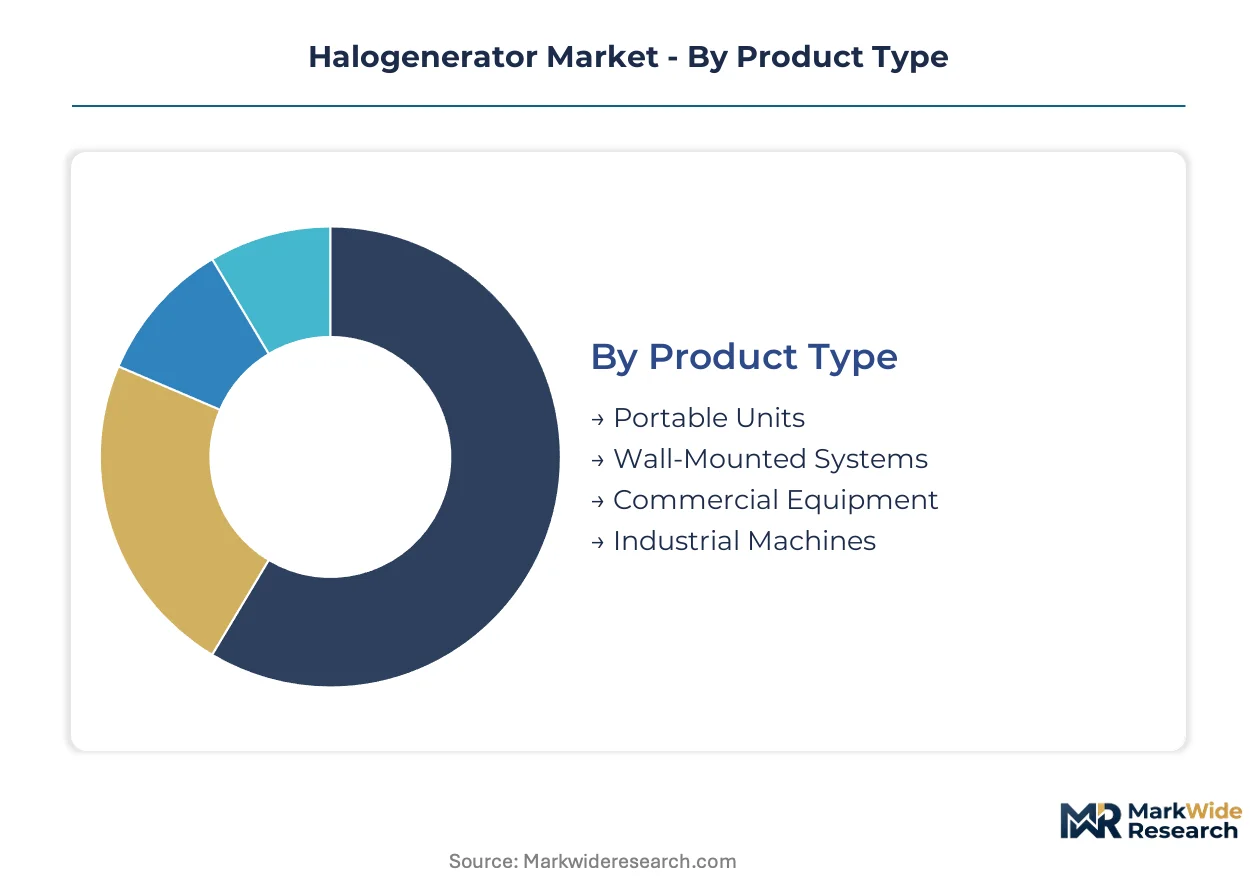
Equipment configuration and buyer sophistication vary sharply across installation contexts. Segmentation reveals where capital intensity, regulatory scrutiny, and operational complexity concentrate value capture.
Product Type:
Domestic demand concentrates in portable and wall-mounted formats for retrofit installations, while export channels favor commercial and industrial systems for greenfield wellness infrastructure.
- Portable Units:Electromechanical salt micronizers housed in mobile casings weighing under 15 kilograms, designed for pop-up services and home-use deployment. Boutique wellness startups in Austin and Melbourne are adopting these systems to launch mobile salt therapy services without fixed-location capital commitments. Compact ultrasonic micronization is compressing unit footprints while preserving one-to-five micron particle precision.
- Wall-Mounted Systems:Fixed-installation equipment integrating with HVAC infrastructure for controlled particle dispersion in enclosed rooms. Hotel spa retrofits across Dubai and Singapore are specifying these units where floor space constraints govern procurement decisions. Wall-mounted configurations command margin premiums in hospitality channels but require custom engineering for legacy climate system integration.
- Commercial Equipment:Cabinet-scale systems serving dedicated halotherapy rooms in wellness centers and rehabilitation facilities.
- Industrial Machines:High-capacity units designed for large-scale salt cave replication and institutional respiratory therapy protocols.
Commercial equipment holds the largest share; momentum sits with portable units.
End User:
Cost tiers separate institutional buyers with certification requirements from wellness operators prioritizing operational simplicity and reduced staffing overhead.
- Health Clubs:Fitness operators installing halotherapy rooms as differentiated member amenities. North American health clubs are expanding installations as post-workout recovery expectations rise, though procurement cycles remain shorter than medical channels.
- Spas:Aesthetic and relaxation service providers integrating salt therapy into treatment menus. German spa operators are driving demand concentration through sustained wellness infrastructure investment and REACH-compliant equipment preferences.
- Hospitals:Pulmonology and rehabilitation departments seeking reimbursable respiratory therapy protocols.
- Wellness Centers:Dedicated facilities offering salt therapy as core service offerings.
Spas hold the largest share; hospitals are climbing the fastest as COPD management pathways expand.
Technology:
Application specificity determines technology selection, with medical protocols demanding validated particle dispersion and wellness operators accepting broader functional ranges.
- Dry Salt Therapy:Electromechanical micronization of pharmaceutical-grade sodium chloride into breathable particles between one and five microns. This technology commands the installed base across commercial and institutional channels, with EU MDR compliance requirements filtering out uncertified manufacturers in German and French rehabilitation centers.
- Automated Controls:Connected architectures enabling remote monitoring, session logging, and integration with facility management systems. California and Florida spa operators are shifting toward pay-per-session remote monitoring subscriptions, compressing vendor recurring revenue visibility while expanding software-enabled service attach rates.
- Chlorine Free Systems:Salt processing configurations eliminating chemical treatment residues for sensitive respiratory applications.
- Ionization Technologies:Alternative particle generation methods gaining traction among operators targeting differentiation in saturated urban markets.
Dry salt therapy holds the largest share; automated controls are gaining share fastest as distributed wellness networks proliferate.
Application:
Volume concentration aligns with clinical validation depth, reimbursable service categories, and consumer willingness to pay for perceived therapeutic outcomes.
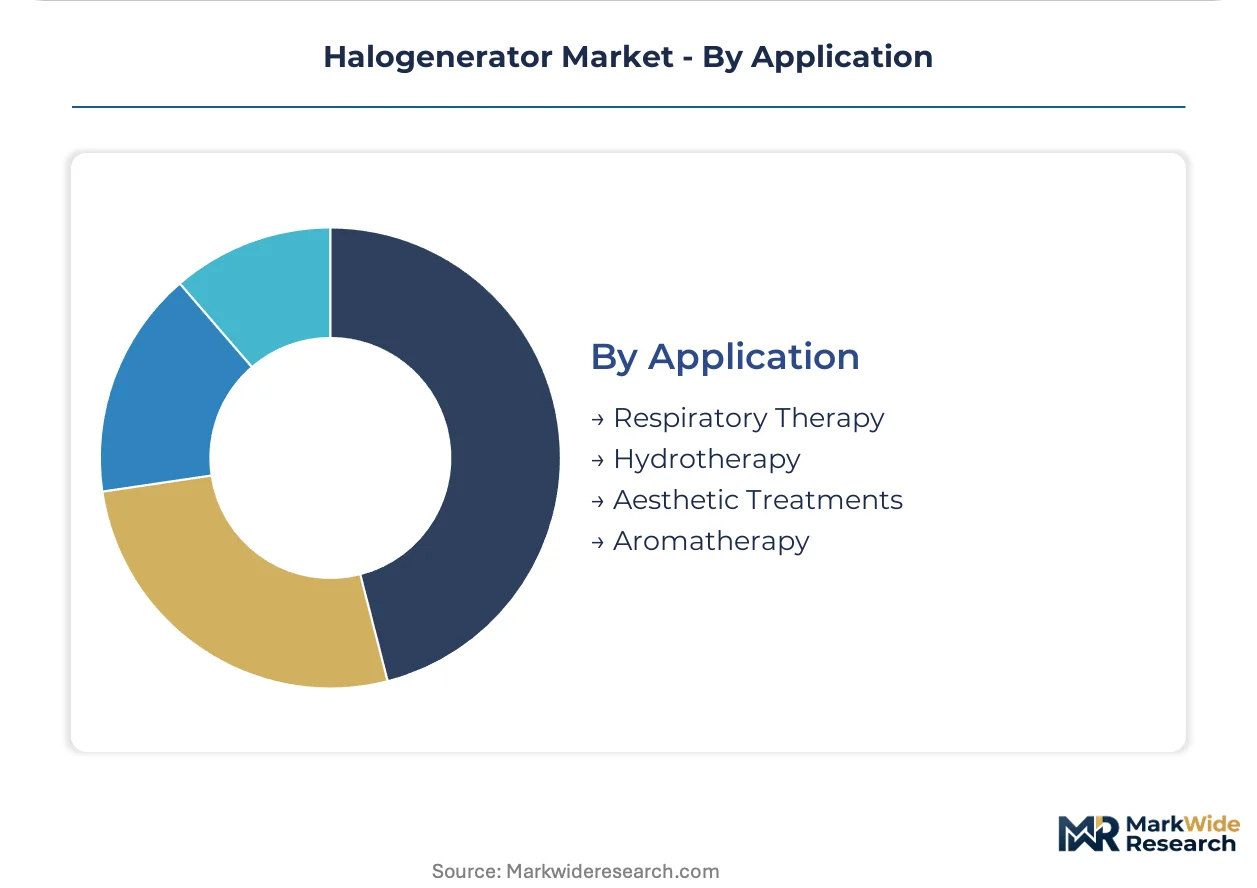
- Respiratory Therapy:Therapeutic inhalation protocols for COPD, asthma, and chronic bronchitis management. United States pulmonology clinics are integrating halotherapy into reimbursable service pathways, though FDA wellness device classification blocks full hospital procurement expansion.
- Aesthetic Treatments:Surface salt application for skin conditions and cosmetic wellness services. European aesthetic clinics are prioritizing REACH-compliant pharmaceutical-grade salt systems over unregulated mineral cave alternatives, creating compliance-driven vendor selection criteria.
- Hydrotherapy:Combined salt and water treatment protocols in spa and rehabilitation settings.
- Aromatherapy:Integrated scent and salt dispersion for relaxation-focused wellness experiences.
Respiratory therapy holds the largest share; aesthetic treatments show steepest expansion trajectory as clinic procurement formalizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical-grade sodium chloride mining concentrates in Pakistan and Ukraine, creating input volatility for European fabricators when geopolitical disruptions interrupt bulk shipments. German and Austrian rehabilitation clinics drive institutional demand through sustained wellness infrastructure investment. Regulatory divergence between FDA wellness classification and EU MDR medical-grade pathways fragments vendor compliance strategies across Atlantic markets.
United States
Pulmonology clinics in Texas and Florida are integrating halotherapy into COPD management pathways, expanding reimbursable respiratory therapy categories. FDA wellness device classification blocks full hospital procurement expansion, constraining institutional adoption despite clinical interest. Austin boutique wellness startups deploy portable ultrasonic units for mobile pop-up salt therapy services.
Germany
Rehabilitation centers in Bavaria and North Rhine-Westphalia prioritize ISO-validated particle dispersion systems for institutional procurement. EU MDR Class IIa certification requirements filter out uncertified manufacturers, creating premium pricing corridors for compliant equipment. REACH substance safety documentation mandates pharmaceutical-grade salt traceability from mine to dispenser.
United Arab Emirates
Vision 2030 hospitality investments in Riyadh and Jeddah resort developments generate demand for turnkey halotherapy installations. MOHAP and SFDA regulatory frameworks shape equipment import requirements for therapeutic wellness assets. Dubai hotel spa retrofits specify wall-mounted systems where floor space constraints govern procurement decisions.
Australia
TGA oversight of therapeutic device claims influences wellness center equipment selection in Melbourne and Sydney metropolitan markets. Boutique operators adopt compact ultrasonic micronization systems to launch mobile services without fixed-location capital commitments. Victorian and New South Wales spa procurement committees prioritize vendors with documented supply chain audit capabilities.
Singapore
Hospitality assets across the city-state accelerate wall-mounted halogenerator installations as wellness amenities become standard competitive fixtures. The Health Sciences Authority monitors classification boundaries between wellness and medical claims for imported therapeutic equipment. Marina Bay and Sentosa resort developments specify integrated HVAC-compatible systems for controlled particle dispersion environments.
Halogenerator Market Competitive Landscape
Concentration sits with mid-cap specialists possessing European manufacturing heritage and MDR compliance capabilities. The vendor landscape bifurcates between institutional-grade fabricators and cost-optimized wellness equipment suppliers. Three archetypes dominate: heritage European manufacturers leveraging certification barriers, North American integrators focused on automated control platforms, and emerging compact technology specialists. Competitive moves center on MDR dossier completion timelines and strategic partnerships with pharmaceutical-grade salt suppliers.
Among heritage European fabricators, ISO Italia anchors premium positioning through institutional channel relationships. SaltMed occupies a position within the Central European specialist tier. Halotherapy Solutions exemplifies the North American automation-focused archetype. These three represent distinct strategic vectors: manufacturing heritage, regional specialization, and control system integration.
| Leading Market Players |
|---|
| ISO Italia |
| Stenal |
| Salt Chamber Inc |
| Halotherapy Solutions |
| Halogenerators |
| The Mark |
| SaltMed |
| AlveoTrack |
| PranaVita |
| Others |
Pricing and Supply Chain Analysis
Capacity utilization at pharmaceutical-grade sodium chloride processing facilities in Pakistan and Ukraine directly governs input cost floors for European fabricators, compressing margin pools for mid-tier equipment manufacturers while amplifying pricing power for vertically integrated producers with captive salt sourcing.
Pricing Analysis
EU MDR Class IIa certification dictates the pricing tier structure across German and French rehabilitation center procurement, separating ISO-validated particle dispersion systems from uncertified wellness-grade alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth, after-sales service bundling, and geographic delivery complexity. Cost compression in the standard tier is intensifying because REACH substance safety documentation requirements are forcing supply chain audit investments that smaller fabricators cannot absorb. Boutique wellness startups in Austin and Melbourne exhibit highest price sensitivity, while Bavarian hospital procurement committees prioritize clinical validation over unit economics.
Supply Chain Analysis
Strait of Hormuz transit underwrites bulk sodium chloride shipments from Pakistani mining operations to European processing facilities, exposing fabricators to geopolitical disruption risk. Manufacturing concentration centers on Germany, Italy, and Poland for electromechanical micronization assembly, with component sourcing drawing from Chinese control system suppliers and Swiss precision machining specialists. Single-source vulnerability concentrates in Ukrainian salt deposits for Central European fabricators lacking alternative pharmaceutical-grade feedstock arrangements. Distribution runs through specialized medical equipment distributors in institutional channels and direct-to-operator e-commerce platforms in wellness segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Early-cycle expansion characterizes this market as COPD management protocol adoption in United States pulmonology clinics and Vision 2030 hospitality investments in Saudi Arabia create dual demand engines with divergent certification requirements.
For Market Incumbents: Secure MDR dossier completion timelines ahead of 2025 regulatory enforcement windows to filter out uncertified competitors in German rehabilitation channels. Anchor backward integration into pharmaceutical-grade sodium chloride sourcing to neutralize Pakistani supply volatility and capture margin compression from REACH audit requirements. ISO Italia and SaltMed exemplify the certification-heritage archetype threatened by ultrasonic micronization miniaturization from compact technology specialists. For New Entrants and Emerging Players: FDA 510(k) fast-track for respiratory therapy indications opens reimbursable service pathways previously blocked by wellness device classification. Target Texas and Florida pulmonology clinic clusters where COPD patient volumes exceed installed halotherapy capacity. Deploy portable ultrasonic units through mobile service subscriptions to bypass fixed-location capital barriers that constrain incumbent channel control. For Investors and Strategic Acquirers: Automated control platform specialists with SaaS-enabled remote monitoring architectures represent the highest-conviction acquisition target archetype as California and Florida operators shift toward pay-per-session consumption models. Long-term viability hinges on software attach rate expansion outpacing hardware margin erosion across the wellness center fragmentation wave. Watch FDA medical-grade pathway clarity as the decisive inflection signal for institutional reimbursement expansion.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Class IIa Certification Completion | Filters uncertified manufacturers from German and French rehabilitation procurement corridors. |
| Backward Integration into Pharmaceutical-Grade Salt Sourcing | Neutralizes Pakistani supply volatility and satisfies REACH traceability mandates. |
| Ultrasonic Micronization Platform Launch | Enables mobile service models for Austin and Melbourne boutique wellness entrants. |
| Remote Monitoring SaaS Development | Captures recurring revenue as California operators abandon bundled maintenance contracts. |
| Saudi Vision 2030 Hospitality Partnership | Positions turnkey installation providers for Riyadh and Jeddah resort development pipelines. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EU MDR notified body decisions, ECHA REACH dossiers, and hospitality procurement databases. Primary interviews engaged equipment manufacturing executives, hospital biomedical engineering directors, wellness center operators, and pharmaceutical-grade salt procurement specialists. Secondary validation drew from customs trade records, SEC equipment supplier filings, and German rehabilitation clinic tender documents. Bottom-up unit economics triangulated against top-down wellness infrastructure investment flows.
Segmentation dimensions modeled include equipment configuration, end-user sophistication tier, technology type, and application specificity across the projection horizon. CAGRs derive from installed base growth rates, replacement cycle compression, and penetration assumptions in respiratory therapy protocols. Forecast inputs incorporate REACH compliance cost pass-through elasticity and FDA classification pathway probability weighting.
Decision-makers should treat outputs as directional under stable geopolitical conditions in Pakistani and Ukrainian salt mining regions; material disruption would warrant model refresh. Practitioners should keep alternative scenarios live as EU MDR enforcement intensity and FDA medical-grade reclassification deliberations evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Generators
United States Portable Generator Market
Generators
North America Portable Generators Market
Generators
South America Gas Generator Market
Generators
Heat Recovery Steam Generator Sales Market
Generators
Onboard Marine Gensets Market
Generators
Portugal Gas Generator Market
Generators
Kuwait Diesel Gensets Market
Generators
Residential Generators Market
Generators
Europe Gas Turbine Market
Generators
Electric Generators Market
Generators
Industrial Generator Market
Generators
Global Diesel Gensets Market
Generators
Power Generator for Military Market
Generators
Wind Power Generators Market
Generators
Wind Turbine Alternator Market
Generators
Reciprocating Power Generating Engine Market