
 South Africa Petroleum Market | 2026-2036
South Africa Petroleum Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Petroleum Market Insights
Buyer concentration among South Africa's mining houses and long-haul transport fleets is hardening as procurement shifts toward term contracts with integrated suppliers. Sasol Limited leverages its synfuels complex in Secunda to secure captive diesel volumes for bulk consumers. Engen Petroleum anchors coastal supply through its Durban refinery and retail network. TotalEnergies South Africa competes via import terminals and strategic stockholding capacity.
Petroleum encompasses crude hydrocarbons and refined products including gasoline, diesel, jet fuel, and fuel oils with specifications governed by SANS standards for sulphur content, cetane number, and distillation curves. Refinery products dominate value generation through fluid catalytic cracking and hydrocracking units that upgrade heavier fractions into high-demand transport fuels. The transportation sector leads end-user consumption through road freight and passenger vehicle dependency, while industrial users represent the fastest-expanding segment as manufacturing capacity utilisation recovers. Chemical feedstocks command premium margins through aromatics and olefins extraction for downstream polymer production.
The Department of Mineral Resources and Energy enforces clean fuels standards aligned with Euro 5 sulphur limits, compelling refinery investment in hydrotreating capacity. SABS certification and NERSA licensing govern product quality and wholesale market access respectively. Stakeholders must monitor import infrastructure development at Richards Bay and Coega against domestic refining rationalisation decisions.
Market Dynamics
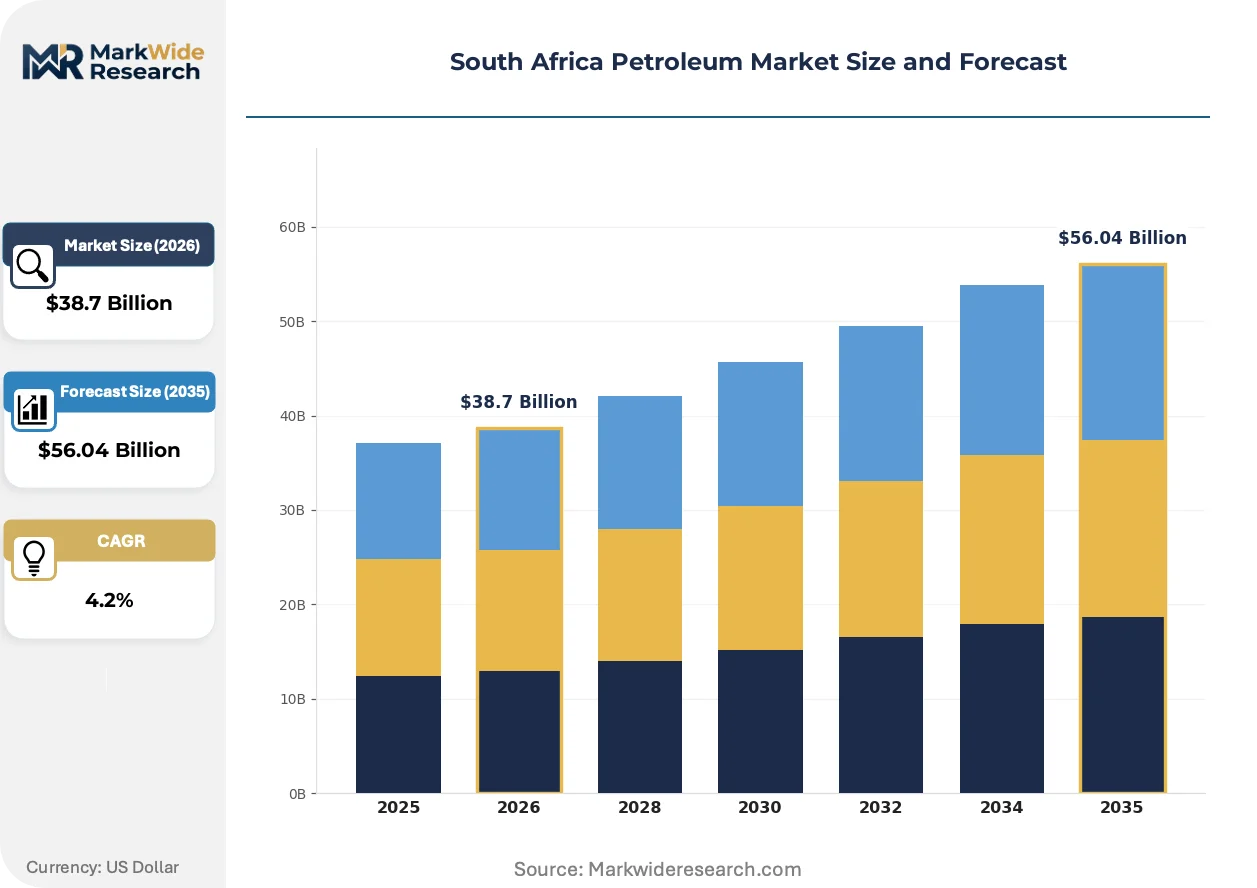
The Department of Mineral Resources and Energy's clean fuels programme is forcing wholesale refinery reinvestment as sulphur specifications tighten toward Euro 5 limits. Mining houses and logistics fleets are consolidating procurement around integrated suppliers with captive synfuels capacity.
Growth Catalysts
- Deep-seated mining expansion:Extraction activity intensifying in the Northern Cape's manganese and iron ore belts is hardening diesel offtake from bulk transport and pit operations. Heavy machinery fleets require consistent high-cetane supply.
- Clean Fuels 2 specification mandate:The DMRE's phased sulphur reduction timeline is accelerating hydrotreater deployment at inland refineries. Upgraded units unlock higher-margin product slate compliance.
- Gauteng industrial corridor concentration:Manufacturing recovery around Johannesburg-Pretoria logistics nodes is compressing demand density for transport fuels and industrial fuel oils.
Market Restraints
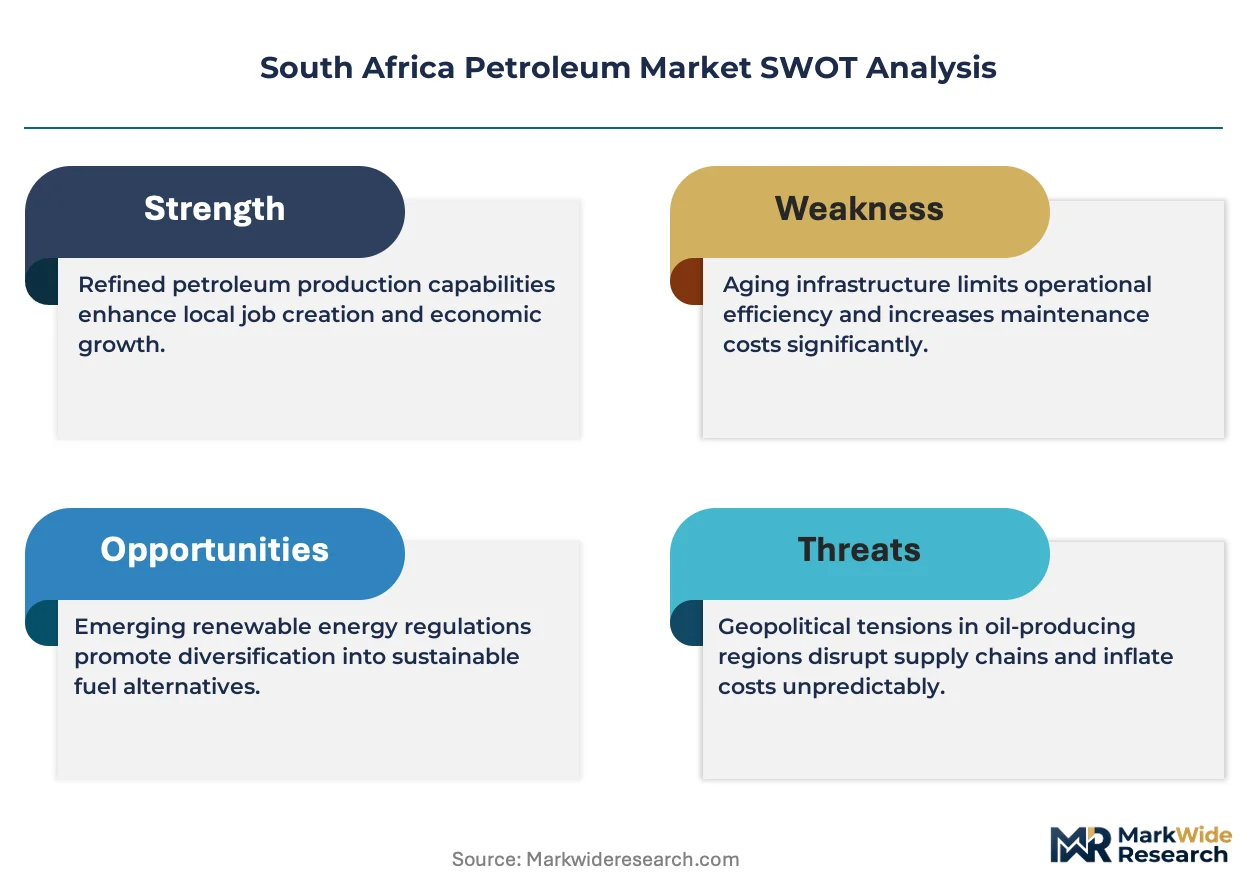
- Crude import dependency:South Africa lacks domestic crude production, exposing refiners to Brent-linked price volatility and currency mismatch against rand-denominated sales.
- Refinery rationalisation risk:Aging coastal processing units face uneconomic upgrade economics against imported product arbitrage, threatening supply security for inland markets.
- Electric mobility substitution:Battery-electric bus pilots in Cape Town and Johannesburg municipal fleets are compressing long-term diesel demand visibility for urban distribution segments.
Strategic Opportunities
- Richards Bay import infrastructure:Deepwater terminal expansion offers alternative supply anchorage if Durban refinery capacity exits, with rail linkages to the Highveld demand hub.
- Synthetic fuels carbon capture integration:Fischer-Tropsch process emissions at Secunda present carbon capture utilisation and storage retrofit potential for low-carbon hydrogen production.
- Industrial cogeneration fuel switching:Petrochemical offgas and fuel oil streams can displace grid electricity for energy-intensive smelters seeking tariff hedge.
Industry Challenges
- Hydrotreater engineering talent scarcity:Specialist process design and catalyst management expertise for ultra-low sulphur unit operation is concentrated among retiring refinery veterans.
- Multi-year certification timelines:SABS product quality approval and NERSA wholesale licensing cycles delay new market entrant stockholding authorisation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Petroleum Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $56.04 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crude Oil, Natural Gas, Refinery Products, Biofuels End User: Transportation Sector, Industrial Users, Residential Users, Commercial Users Application: Energy Generation, Fuel Supply, Chemical Feedstocks, Heating Distribution Channel: Retail Outlets, Direct Supply, Bulk Distribution, Wholesalers |
| Companies Covered | Sasol Limited, TotalEnergies South Africa, Shell South Africa, Engen Petroleum, PetroSA, Astron Energy, BP Southern Africa, Vivo Energy, Natref, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Petroleum Market Trends and Innovations
Refinery technology adaptation and procurement consolidation are compressing traditional supply chain configurations across South Africa's petroleum sector. These shifts are reconfiguring competitive positioning between synfuels producers and coastal importers.
Small-scale modular hydrotreating units are modularizing refinery upgrade pathways for mid-sized processors unable to justify billion-rand grassroots construction. Secunda-based engineering firms are deploying skid-mounted desulphurisation packages for regional fuel terminals. This distributed approach is enabling compliance without full refinery reconstruction.
The DMRE's Clean Fuels 2 regulatory timeline is mandating 10 ppm sulphur limits in transport fuels by phased implementation. Refiners must sequence catalyst replacement and hydrogen supply expansion to maintain throughput during conversion. Diesel product pools face the tightest compliance window given existing high-sulphur cracking unit yields.
Bulk consumers are consolidating term contracting around suppliers with integrated Secunda-Durban supply flexibility. Mining procurement departments are unbundling spot market exposure in favour of volume-commitment structures with price-cap provisions. The Northern Cape extraction belt exhibits the most pronounced shift toward multi-year supply agreements with dedicated logistics allocation.
South Africa Petroleum Market Segmentation
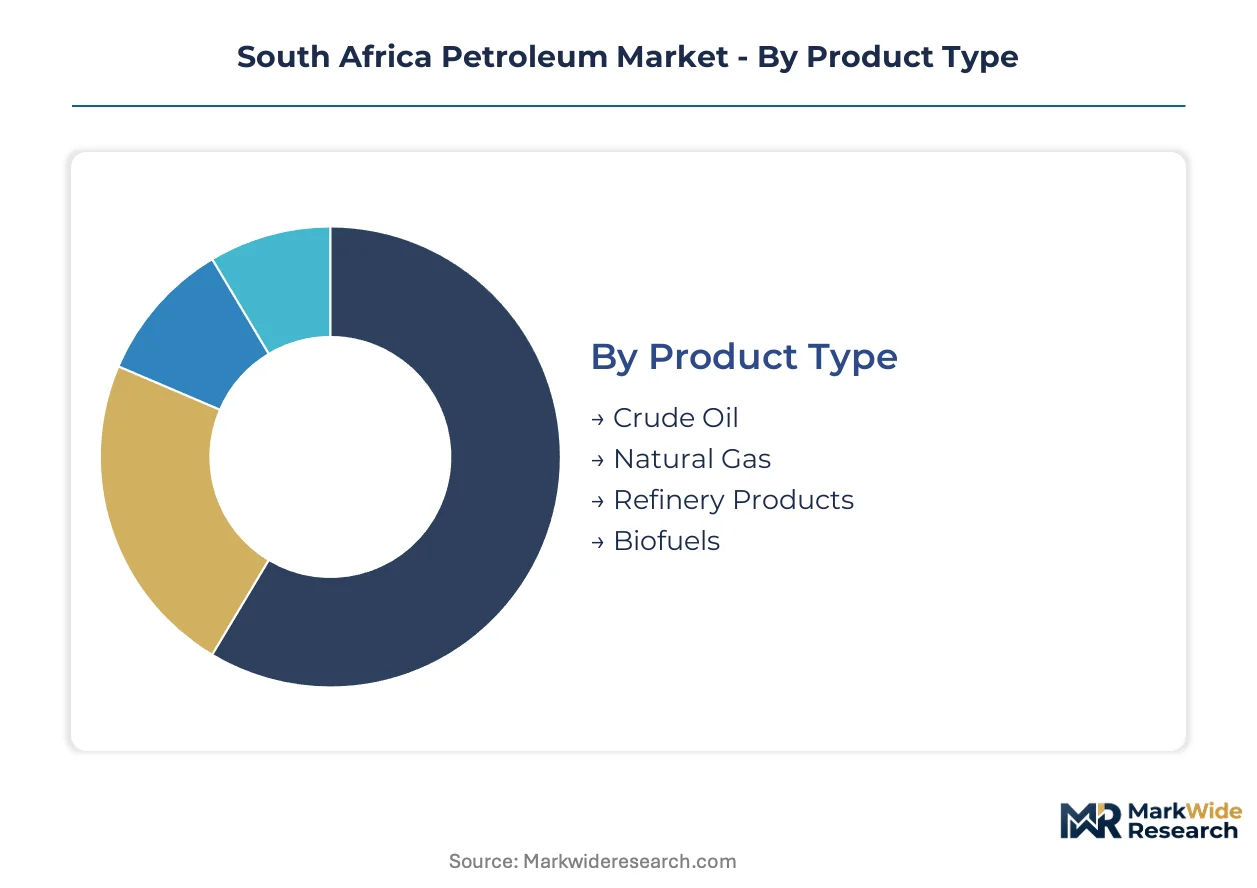
Petroleum market segmentation in South Africa tracks how regulatory specifications, infrastructure access, and end-use concentration fragment value capture across product grades and delivery modes. Understanding these divisions clarifies where DMRE clean fuels compliance costs concentrate and which channels absorb inland supply security risks.
Product Type:
SANS certification requirements vary sharply across product categories, with transport fuels facing the most stringent sulphur specification timelines under Clean Fuels 2 mandates.
- Refinery Products:Fluid catalytic cracking and hydrocracking outputs—gasoline, diesel, jet fuel—dominate value generation through transport fuel sales. Gauteng's industrial corridor around Johannesburg-Pretoria compresses demand density for these upgraded fractions as manufacturing capacity utilisation recovers.
- Crude Oil:Unprocessed Brent-linked feedstock enters exclusively through import terminals at Durban and Richards Bay. Currency mismatch between dollar-denominated procurement and rand-denominated product sales exposes refiners to exchange volatility throughout the processing cycle.
- Natural Gas:Pipeline imports from Mozambique and domestic offshore production supply power generation and industrial heat applications.
- Biofuels:Blending mandates for ethanol and biodiesel remain limited by agricultural feedstock availability and blending infrastructure gaps.
Leading the category by volume: Refinery Products. Expanding most quickly: Biofuels as blending infrastructure develops.
End User:
Customer scale and contract structure determine whether buyers absorb price volatility or transfer risk through term commitments with integrated suppliers.
- Transportation Sector:Road freight fleets, passenger vehicles, and aviation operators consume the majority of refined product output. Northern Cape mining logistics and long-haul corridors drive diesel offtake concentration.
- Industrial Users:Manufacturing, mining operations, and smelters represent the steepest expansion trajectory as energy-intensive production recovers. Petrochemical offgas and fuel oil streams enable grid electricity displacement for tariff-sensitive operations.
- Commercial Users:Retail fuel stations, construction fleets, and agricultural operators purchase through wholesale intermediaries or direct supply agreements.
- Residential Users:LPG and kerosene consumption for heating and cooking concentrates in peri-urban and rural settlements outside piped natural gas coverage.
Dominant volume share: Transportation Sector. Fastest demand growth: Industrial Users as manufacturing utilisation climbs.
Application:
Margin structure diverges between commodity fuel sales and specialty chemical extractions requiring dedicated processing units.
- Fuel Supply:Transport and heating fuel deliveries generate baseline revenue through high-volume, lower-margin transactions. Secunda synfuels and coastal imports compete for inland market share.
- Chemical Feedstocks:Aromatics and olefins extraction from refinery streams commands premium pricing for downstream polymer production. Sasol's Fischer-Tropsch complex anchors domestic supply.
- Energy Generation:Fuel oil and diesel power reciprocating engines and turbines for industrial cogeneration and grid backup.
- Heating:Industrial process heat and residential LPG applications seasonally concentrate demand in winter months.
Highest revenue concentration: Fuel Supply. Margin leadership: Chemical Feedstocks.
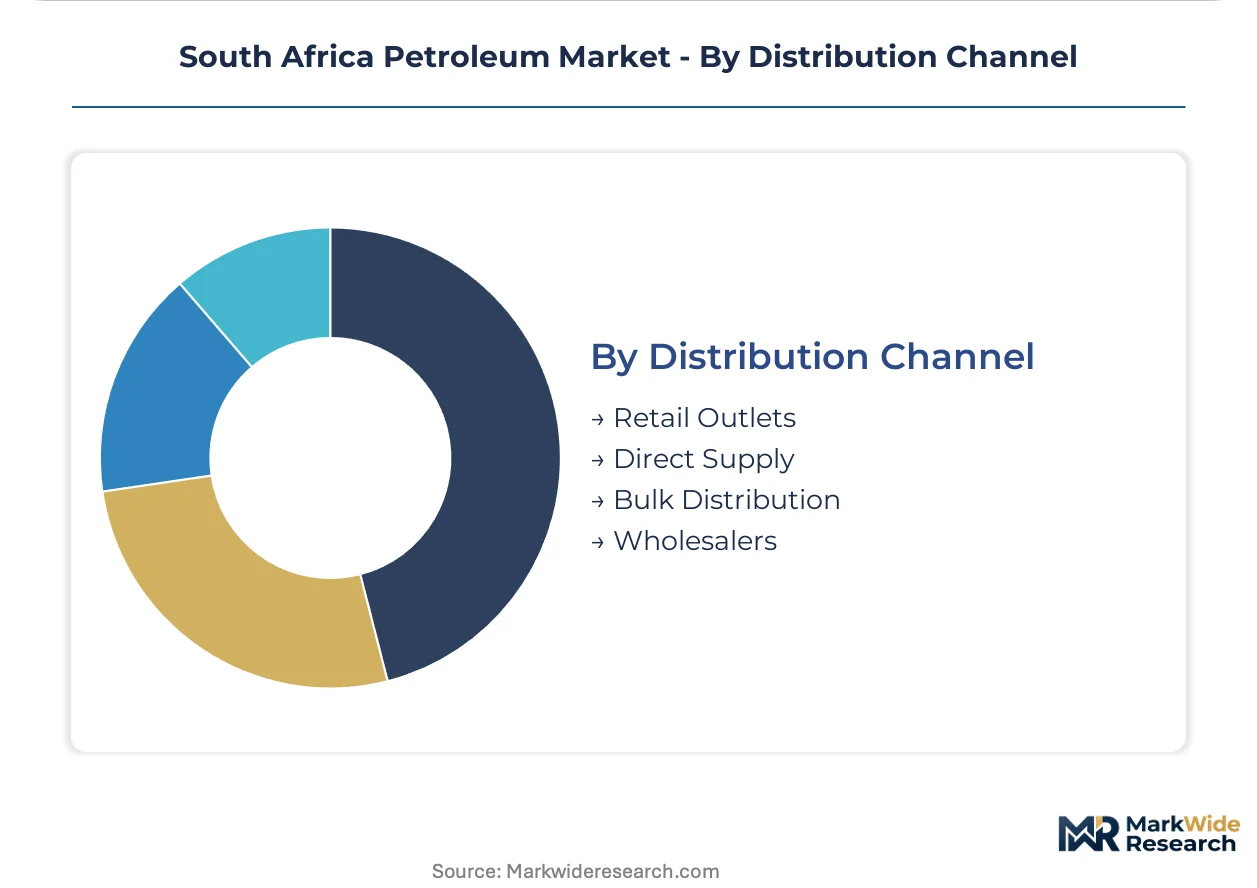
Distribution Channel:
Infrastructure ownership and stockholding authorisation under NERSA licensing separate integrated suppliers from spot-market participants.
- Direct Supply:Mining houses and logistics fleets negotiate multi-year volume commitments with price-cap provisions, bypassing wholesale intermediaries. Northern Cape extraction belts exhibit the most pronounced procurement consolidation.
- Bulk Distribution:Dedicated tanker fleets and rail tank cars move product from Secunda and Durban to inland demand hubs. Richards Bay terminal expansion offers alternative supply anchorage if coastal refinery capacity exits.
- Retail Outlets:Branded service stations and independent forecourts serve fragmented passenger vehicle demand through spot pricing.
- Wholesalers:Licensed stockholders aggregate volumes for resale to smaller commercial and agricultural buyers.
Largest volume flow: Direct Supply. Fastest channel growth: Bulk Distribution as rail linkages expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gauteng's industrial corridor concentrates South African petroleum demand around Johannesburg and Pretoria manufacturing nodes, while coastal refining capacity at Durban and Cape Town faces rationalisation pressure against import arbitrage.
Gauteng Province
Mining logistics fleets and manufacturing operations drive diesel offtake concentration across the Johannesburg-Pretoria corridor. The Department of Mineral Resources and Energy's Clean Fuels 2 programme mandates Euro 5 sulphur compliance, forcing hydrotreater investment at inland refineries. Secunda's Fischer-Tropsch complex anchors synthetic fuel supply to the Highveld demand hub.
KwaZulu-Natal
Durban's import terminal and coastal refinery handle crude receipts for national distribution networks. Transnet's pipeline infrastructure moves refined products inland under NERSA licensing frameworks. Richards Bay deepwater terminal expansion offers alternative supply anchorage if coastal processing capacity exits.
Western Cape
Cape Town's import-dependent supply structure serves regional transport and industrial demand through coastal tanker deliveries. Municipal battery-electric bus pilots compress long-term diesel visibility for urban distribution segments. The Saldanha industrial zone concentrates fuel oil demand for smelter cogeneration applications.
Northern Cape
Manganese and iron ore extraction intensifies across the Kalahari mining belt, hardening diesel procurement from bulk transport and pit machinery fleets. Mining houses consolidate term contracting around integrated suppliers with captive Secunda supply. Kathu and Hotazel logistics nodes exhibit pronounced shift toward multi-year volume commitments.
South Africa Petroleum Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue import-terminal positioning and strategic stockholding capacity. The market structure reflects consolidation around integrated synfuels producers and coastal importers with NERSA wholesale licensing. Three archetypes dominate: Fischer-Tropsch specialists with captive chemical feedstock integration, coastal refiners with import-terminal flexibility, and pure wholesale distributors aggregating volumes for fragmented buyers. Competitive moves center on refinery upgrade sequencing to meet Clean Fuels 2 timelines and procurement consolidation through multi-year term contracts with price-cap provisions.
Among domestic-anchored suppliers, Sasol Limited represents the integrated synfuels archetype through its Secunda complex operations. TotalEnergies South Africa and Engen Petroleum occupy positions spanning import-terminal access and coastal refining capacity. These three exemplify the competitive tension between inland synthetic production and coastal import arbitrage that defines South African petroleum supply configuration.
| Leading Market Players |
|---|
| Sasol Limited |
| TotalEnergies South Africa |
| Shell South Africa |
| Engen Petroleum |
| PetroSA |
| Astron Energy |
| BP Southern Africa |
| Vivo Energy |
| Natref |
| Others |
Pricing and Supply Chain Analysis
Brent crude futures and rand-dollar exchange volatility cascade through South Africa's petroleum value chain, compressing margins at coastal refineries while amplifying pricing power for Secunda's synfuels producers with captive feedstock security. The Department of Mineral Resources and Energy's Clean Fuels 2 sulphur mandates layer compliance cost differentials across product grades, stratifying buyers into term-contract anchoring versus spot-market exposure.
Pricing Analysis
Volume-heavy transport fuel sales generate baseline revenue through lower-margin, high-throughput transactions, while chemical feedstock extractions and specialty industrial fuel oils capture premium returns. Price differentiation hinges on sulphur specification grade and volume-commitment scale, with Euro 5-compliant diesel commanding structural premiums over high-sulphur legacy stock. Cost compression in coastal refinery products is intensifying because import arbitrage erodes domestic processing economics, leaving bulk mining and logistics fleets as the least price-sensitive segment due to term-contract price-cap provisions, while fragmented commercial and agricultural buyers absorb full spot volatility.
Supply Chain Analysis
Direct-to-mine and direct-to-fleet channels handle concentrated demand from Northern Cape extraction belts and Gauteng industrial corridors, bypassing wholesale intermediaries through multi-year volume commitments. Geographic supply concentration centers on South Africa's Secunda synfuels complex, Durban coastal refinery and import terminal, and emerging Richards Bay deepwater anchorage. Raw material dependencies draw from Brent-linked crude imports, Fischer-Tropsch synthesis gas, and hydrocracker hydrogen feedstock. Single-source vulnerability looms around Transnet's pipeline infrastructure to the Highveld demand hub. Distribution runs through dedicated rail tank cars, coastal tanker deliveries, and branded retail forecourts serving fragmented passenger vehicle demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South Africa's petroleum market functions as a cost-of-compliance arena where the Department of Mineral Resources and Energy's Clean Fuels 2 programme erects billion-rand refinery upgrade barriers, entrenching incumbents with capital deployment capacity while screening out undercapitalized challengers.
For Market Incumbents: Extend hydrotreater deployment timelines to synchronize with competitor capacity exits, capturing stranded demand from rationalized coastal refineries. Deepen backward integration into hydrogen supply infrastructure to lock in ultra-low sulphur unit feedstock security against import volatility. Electric mobility pilots in municipal bus fleets threaten long-term diesel offtake; anchor chemical feedstock diversification into polymer-grade aromatics to offset transport fuel compression.
For New Entrants and Emerging Players: Begin with strategic stockholding capacity at Richards Bay terminal expansion zones, exploiting NERSA licensing delays that constrain incumbent wholesale authorization. The most penetrable white space sits in modular skid-mounted desulphurisation packages for regional fuel terminals unable to justify full refinery reconstruction. A go-to-market angle anchored in distributed compliance infrastructure—leasing hydrotreater units to mid-sized processors—circumvents billion-rand grassroots capital requirements while capturing Clean Fuels 2 upgrade spending.
For Investors and Strategic Acquirers: Distressed-cycle entries favor Fischer-Tropsch specialists with integrated chemical feedstock exposure in the Highveld corridor, where captive synfuels capacity insulates against crude import currency mismatch. Long-term viability over a five-to-ten-year window rests on carbon capture retrofit execution at Secunda-scale emissions profiles. The signal to watch is coastal refinery rationalisation announcements, which would trigger inland supply security premiums and revalue pipeline-linked storage assets.
| Strategic Initiative | Industry Significance |
|---|---|
| Hydrotreater Capacity Expansion | Secures Euro 5 compliance timeline ahead of DMRE enforcement windows. |
| Backward Integration into Hydrogen Supply | Locks in feedstock security for ultra-low sulphur diesel production at Secunda. |
| Richards Bay Terminal Stockholding | Creates alternative supply anchorage if Durban refinery capacity exits inland markets. |
| Carbon Capture Retrofit Deployment | Transforms Fischer-Tropsch emissions into low-carbon hydrogen for polymer feedstock. |
| Long-term Mining Supply Agreement | Compresses spot exposure through price-capped volume commitments with Northern Cape extraction belts. |
Research Methodology
Trade flow databases, SABS certification registries, and NERSA wholesale licensing records formed the secondary backbone, cross-referenced against SEC filings from listed energy majors and Transnet infrastructure disclosure documents. Primary fieldwork encompassed structured interviews with refinery operations managers, mining procurement directors at Northern Cape extraction houses, fuel supply specialists at logistics fleet operators, and DMRE regulatory affairs officers. Bottom-up volume modeling across product grades and end-use segments was triangulated against top-down macroeconomic absorption rates.
Historical trendline analysis established baseline consumption patterns across the projection horizon, with growth rates derived from manufacturing capacity utilization recovery trajectories and mining extraction expansion timelines. Segmentation dimensions encompassed product type, end-user category, application purpose, and distribution channel structure, with additional granularity around sulphur specification tiers and synthetic versus imported supply origin. Forecast inputs incorporated Clean Fuels 2 compliance cost curves, refinery rationalisation probability assessments, and electric mobility substitution elasticity for urban distribution segments.
Underlying measurement precision varies by segment; direct supply contracting volumes with disclosed term commitments carry tighter precision than fragmented retail channel estimates. Forecasts reflect assumptions around currency stability, regulatory enforcement timing, and infrastructure investment execution that warrant periodic reassessment. Periodic stress-testing of base assumptions is recommended against crude price volatility bands and refinery closure announcement triggers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Petroleum Products
Oil Refinery Market
Petroleum Products
Petroleum Wax Market
Petroleum Products
Balanos Oil Market
Petroleum Products
Crude Oil Flow Improvers Market
Petroleum Products
Liquefied Petroleum Gas Market
Petroleum Products
Petroleum Benzine Market
Petroleum Products
Oil Storage Sales Market
Petroleum Products
Global Petroleum Pitch Market
Petroleum Products
Quenching Oil Market
Petroleum Products
Pyrolysis Gasoline Market
Petroleum Products
Saudi Arabia Refined Petroleum Products Market
Petroleum Products
Global Petroleum Coke Market
Petroleum Products
Refined Petroleum Products Market
Petroleum Products
Malaysia Refined Petroleum Products Market
Petroleum Products
Europe Ethane Market
Petroleum Products
Performance Oil Sales Market