
 Aerospace Engineering Services Outsourcing Market | 2026-2036
Aerospace Engineering Services Outsourcing Market Size, Share, and Industry Trends Forecast 2026-2036
Aerospace Engineering Services Outsourcing Market Intelligence
Drone manufacturing is realigning aerospace engineering demand as commercial unmanned systems expand beyond defense into logistics and agriculture. Alten Group leverages its European design heritage to anchor certification-intensive programs for urban air mobility platforms. HCLTech competes through offshore development centers that sustain cost advantages in structural analysis and simulation workloads. Capgemini Engineering dominates systems integration outsourcing for connected aircraft programs.
Aerospace engineering services outsourcing covers the contracted provision of specialized technical design, analysis, certification, and manufacturing support functions across aircraft, spacecraft, and unmanned systems lifecycles, typically governed by AS9100 quality standards and specific airworthiness codes. These services reduce fixed R&D overhead while accessing scarce expertise in composite structures, avionics integration, and propulsion thermal management. Design services leads current revenue contribution as OEMs externalize early-stage concept development and digital twin modeling, while testing services represents the fastest-growing category driven by expanded simulation-based certification pathways. The hybrid delivery model captures expanding margin pools by blending onsite program management with offshore technical execution.
FAA airworthiness standards, EASA certification requirements, and AS9100 quality frameworks collectively dictate outsourcing partner eligibility and technical competency thresholds. These regulations shape demand by mandating documented traceability, specialized inspector qualifications, and region-specific compliance architectures that only accredited engineering service providers can fulfill. Stakeholders must monitor evolving sustainability certification criteria and autonomous flight governance as these domains reshape vendor capability requirements.
Market Dynamics
Commercial aviation fleet modernization is compressing engineering cycles and forcing OEMs to externalize design and certification work to accredited partners capable of meeting AS9100 quality mandates.
Growth Catalysts
- FAA Airworthiness Directives:Mandatory compliance updates for aging aircraft fleets are expanding contracted engineering hours for structural modification packages and fatigue analysis.
- Urban Air Mobility Platforms:Electric vertical take-off and landing vehicle development is generating specialized demand for propulsion thermal management and autonomous flight control systems.
- Composite Manufacturing:Carbon fiber-reinforced polymer adoption in next-generation airframes requires outsourced expertise in automated fiber placement and non-destructive inspection protocols.
Market Restraints
- Titanium and Nickel Superalloy Volatility:Aerospace-grade metal price swings compress margins on fixed-price engineering contracts for propulsion component design.
- Indian Engineering Center Concentration:Overreliance on Bangalore and Hyderabad delivery hubs creates geopolitical exposure and talent competition from domestic IT sectors.
- EASA Certification Timeline Rigidity:Extended validation periods for design organization approvals delay revenue recognition and strain working capital for mid-tier service providers.
Strategic Opportunities
- Sustainable Aviation Fuel Certification:EU Green Deal emissions mandates are creating engineering demand for powerplant modification packages and alternative propulsion integration.
- Digital Twin Convergence:Physics-based simulation fused with operational sensor data is opening new service lines for predictive maintenance algorithm development.
- Poland and Romania Delivery Centers:Eastern European engineering talent pools remain underpenetrated relative to India, offering cost arbitrage for European OEM proximity requirements.
Industry Challenges
- AS9100 Auditor Scarcity:Qualified quality management system assessors are concentrated among a handful of certification bodies, creating bottlenecks for supplier qualification.
- Legacy Avionics Integration:ARINC 429 and MIL-STD-1553 protocol expertise is retiring faster than training programs replenish, complicating connected aircraft upgrade programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aerospace Engineering Services Outsourcing Market |
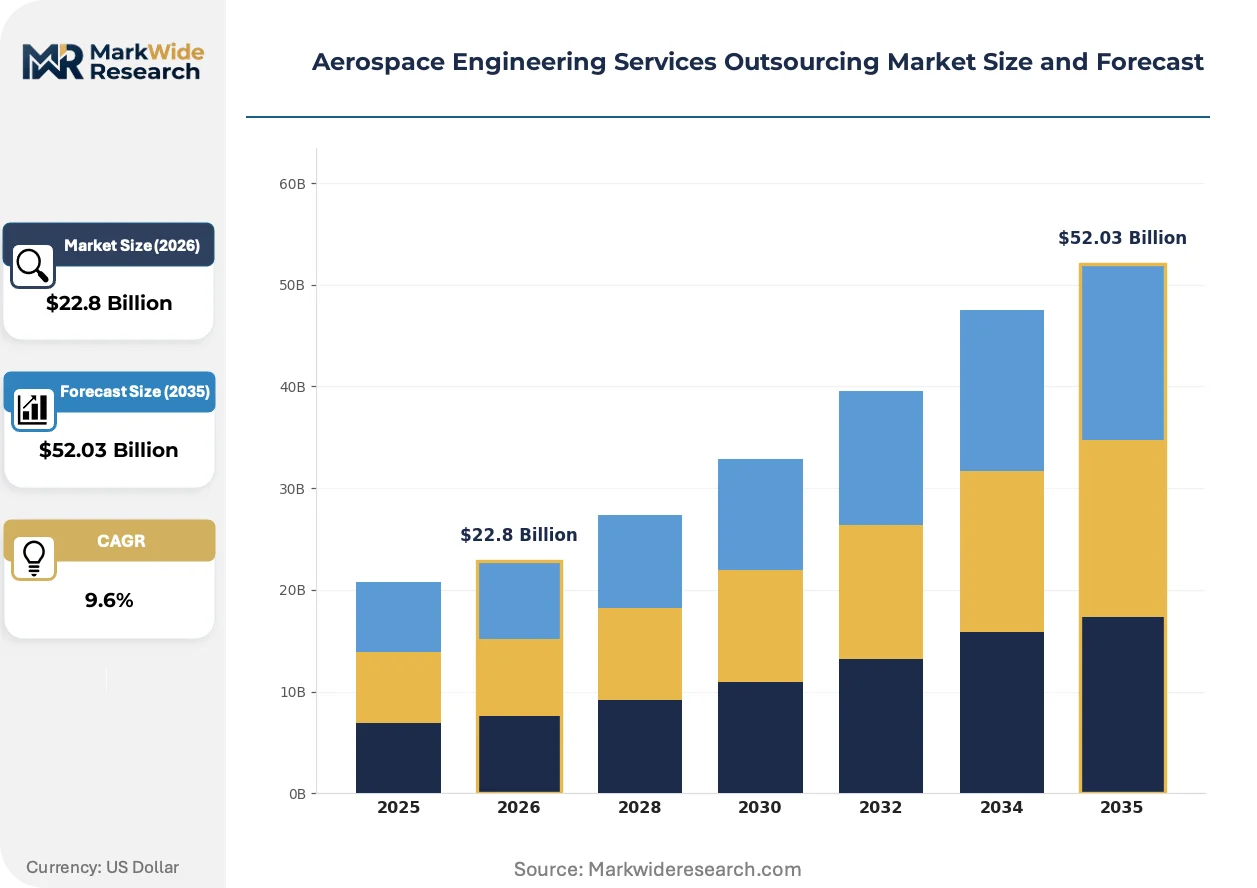
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $52.03 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Design Services, Manufacturing Engineering, Certification Services, Testing Services End User: Commercial Aviation, Military Aviation, Space Exploration, Drone Manufacturers Project Type: New Development, Upgrades, Maintenance, Research Projects Delivery Model: Onsite Support, Offsite Development, Hybrid Model, Remote Services |
| Companies Covered | AKKA Technologies, Altran, Alten Group, QuEST Services, Bertrandt, Capgemini Engineering, L&T Technology Services, Honeywell International, HCLTech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aerospace Engineering Services Outsourcing Market Strategic Shifts & Innovations
Model-based systems engineering is collapsing traditional document-heavy design workflows, compressing certification timelines while demanding new software competencies from established aerospace engineering providers.
Artificial intelligence-assisted generative design is overtaking parametric modeling for structural optimization tasks. Tier 1 suppliers are adopting topology optimization algorithms for bracket and rib configurations, reducing material mass by fifteen to thirty percent on non-critical components. This capability shift is enabling smaller engineering firms to compete on complex geometry development previously requiring specialized finite element expertise.
EASA's proposed regulatory framework for autonomous aircraft operations is mandating formal methods verification for flight control software. European OEMs are restructuring supplier qualification criteria to prioritize partners with DO-178C certification experience. Urban air mobility developers in Germany and France are accelerating recruitment of systems safety engineers to preempt compliance gaps.
Fixed-price engineering contracts with milestone-based payments are displacing time-and-materials arrangements for design services. Commercial aviation procurement teams at major airframers are unbundling digital twin development from physical testing programs, creating specialized vendor tiers. This restructuring is most pronounced in US-based defense subcontracting, where cost-plus incentive fee structures face congressional scrutiny.
Aerospace Engineering Services Outsourcing Market Segmentation
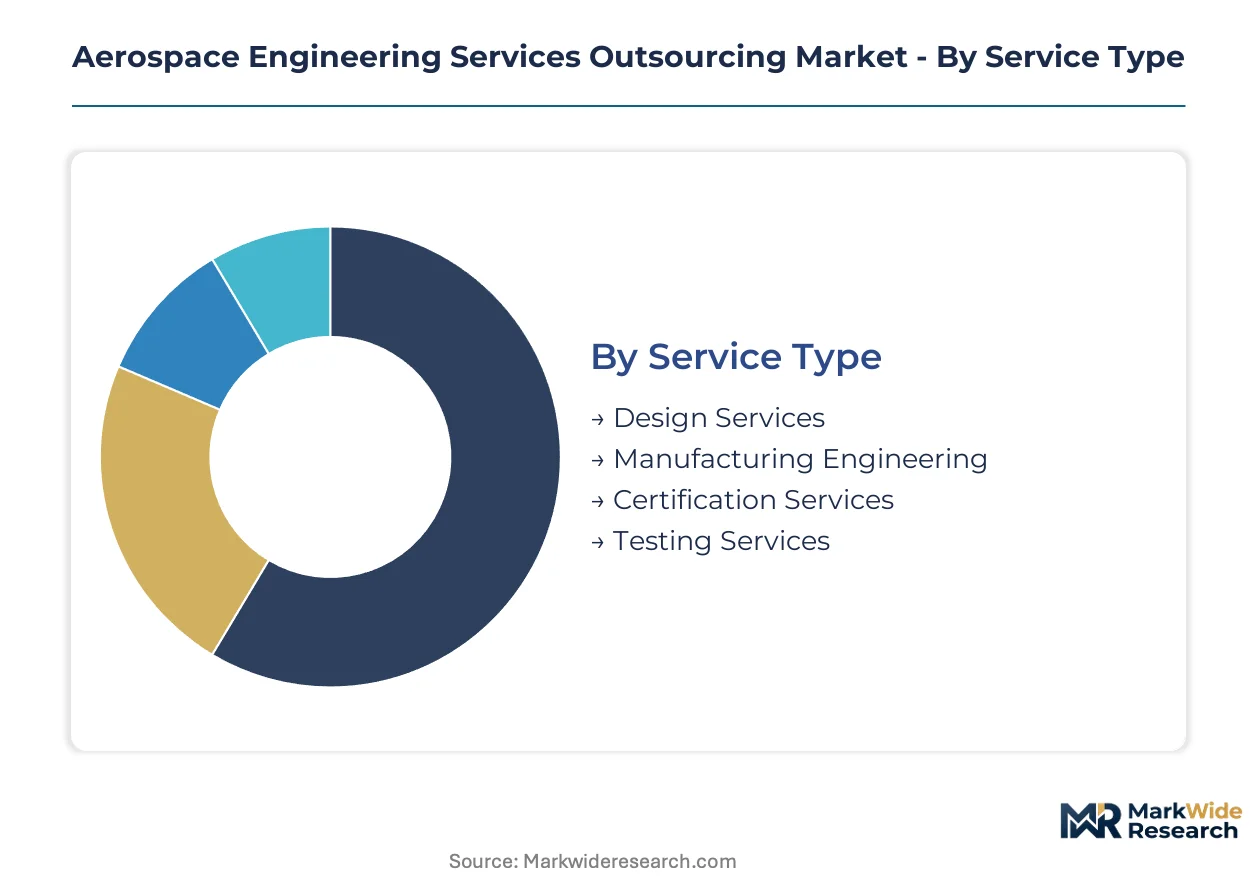
Segmentation in aerospace engineering services outsourcing reveals how certification burdens, delivery economics, and project lifecycle stages reshape vendor selection criteria. Engineering service providers calibrate capability investments around the specific compliance architectures each segment demands.
Service Type:
FAA and EASA certification requirements impose distinct competency thresholds across service categories, with DO-178C software approval and AS9100 quality mandates filtering eligible providers.
- Design Services:Digital twin modeling and early-stage concept development dominate contracted hours as OEMs externalize aerodynamic optimization and structural layout. Airbus and Boeing procurement teams in Toulouse and Seattle concentrate spending here for next-generation narrowbody programs.
- Testing Services:Simulation-based certification pathways and hardware-in-the-loop validation are expanding fastest among urban air mobility developers seeking compressed approval timelines. This segment demands specialized wind tunnel access and electromagnetic interference facilities that few mid-tier vendors possess.
- Manufacturing Engineering:Automated fiber placement programming and tooling design for composite airframes.
- Certification Services:Regulatory documentation packages and compliance traceability for FAA airworthiness directives.
Design Services sits at the top of the volume ranking, with Testing Services climbing the fastest.
End User:
Customer procurement patterns stratify sharply between cost-sensitive commercial programs and mission-assurance military contracts with diverging margin profiles.
- Commercial Aviation:Fleet modernization drives sustained demand for structural modification engineering and avionics retrofit packages. Delta, United, and Lufthansa Technical Operations externalize fatigue analysis and Supplemental Type Certificate preparation to accredited partners.
- Drone Manufacturers:Agricultural spraying and logistics unmanned systems are generating specialized propulsion thermal management and autonomous flight control demand. DJI and Skydio procurement teams prioritize vendors with rapid prototyping capabilities over established aerospace heritage.
- Military Aviation:Defense subcontracting with cost-plus incentive fee structures and ITAR compliance requirements.
- Space Exploration:Launch vehicle reusability engineering and satellite bus platform development for NewSpace operators.
Commercial Aviation commands the largest contract value, while Drone Manufacturers are expanding most quickly.
Project Type:
Revenue recognition timing and working capital intensity vary dramatically across development, upgrade, and sustainment workflows.
- New Development:Clean-sheet aircraft programs require integrated digital thread capabilities spanning requirements management through manufacturing release. Embraer's E2 regional jet and Mitsubishi's SpaceJet accumulated substantial external engineering hours during preliminary design phases.
- Upgrades:Connected aircraft retrofits and cabin reconfiguration programs offer shorter cycle times and more predictable milestone payments. Lufthansa Technik and ST Engineering specialize in these contracted modification packages for aging A320 and 737 fleets.
- Maintenance:Continuing airworthiness management and structural repair documentation for operator engineering departments.
- Research Projects:EU Clean Aviation and NASA Sustainable Flight National Partnership funded technology maturation.
Upgrades generate the steadiest revenue flow, with New Development showing the steepest expansion trajectory.
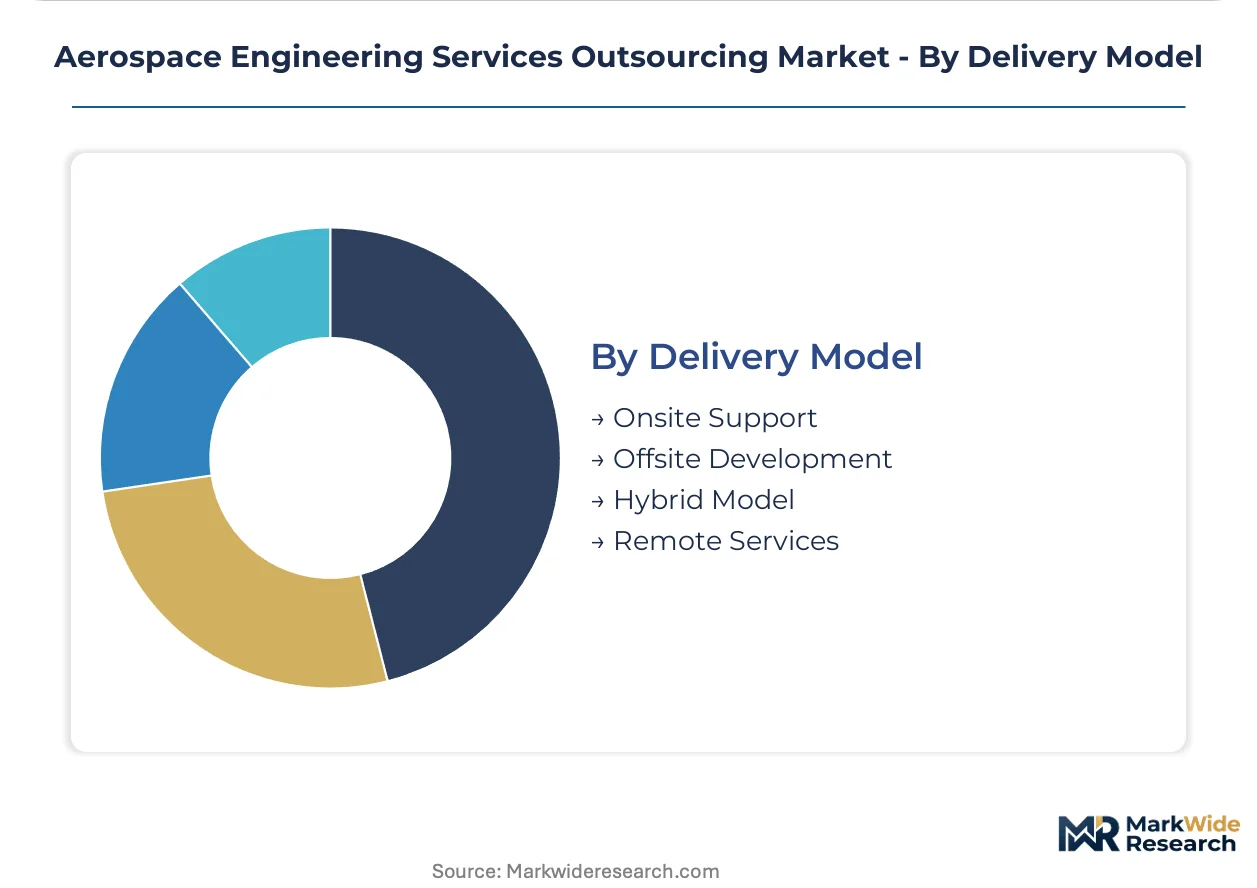
Delivery Model:
Margin capture depends on balancing client proximity for program management against labor arbitrage in technical execution.
- Hybrid Model:Blended onsite engineering management with offshore technical delivery captures expanding margin pools. Alten Group and Capgemini Engineering structure Polish and Indian delivery centers around this architecture for European OEM proximity requirements.
- Onsite Support:Embedded resident engineers at airframer facilities enable real-time design iteration and supplier coordination. This model commands rate premiums but sacrifices scalability.
- Offsite Development:Bangalore and Hyderabad concentrated execution for structural analysis and simulation workloads.
- Remote Services:Cloud-based collaboration tools enabling distributed model-based systems engineering.
Hybrid Model dominates new contract awards, with Remote Services gaining share fastest among digitally mature suppliers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bangalore and Hyderabad anchor engineering delivery concentration for outsourced aerospace design and certification work, with specialized clusters now expanding across Eastern Europe and North American defense corridors to balance cost arbitrage against regulatory proximity requirements.
United States
FAA airworthiness directives for aging commercial fleets sustain contracted structural modification hours, while defense subcontracting concentrates around ITAR-compliant engineering centers in California, Texas, and Washington state. Seattle and Wichita clusters specialize in preliminary design phases for next-generation narrowbody programs.
Germany
EASA certification timelines and formal methods verification for autonomous flight control software reshape supplier qualification criteria. Munich and Hamburg engineering centers concentrate urban air mobility development for electric vertical take-off and landing platforms, with Stuttgart clusters specializing in automotive-aerospace convergence for propulsion thermal management.
India
Bangalore and Hyderabad delivery hubs process structural analysis and simulation workloads for global OEMs, though talent competition from domestic IT sectors intensifies wage pressure. The country's national aerospace regulator aligns with AS9100 quality mandates to sustain eligibility for Boeing and Airbus procurement teams.
Poland
EU Green Deal emissions mandates generate engineering demand for sustainable aviation fuel certification and powerplant modification packages. Warsaw and Krakow engineering centers offer cost arbitrage for European OEM proximity requirements, with Alten Group and Capgemini Engineering anchoring delivery infrastructure.
France
Toulouse procurement teams concentrate spending on digital twin modeling and early-stage concept development for Airbus programs. EASA's proposed autonomous aircraft framework accelerates recruitment of systems safety engineers in Paris-Saclay and Bordeaux clusters to preempt compliance gaps in flight control software verification.
Aerospace Engineering Services Outsourcing Market Key Industry Players
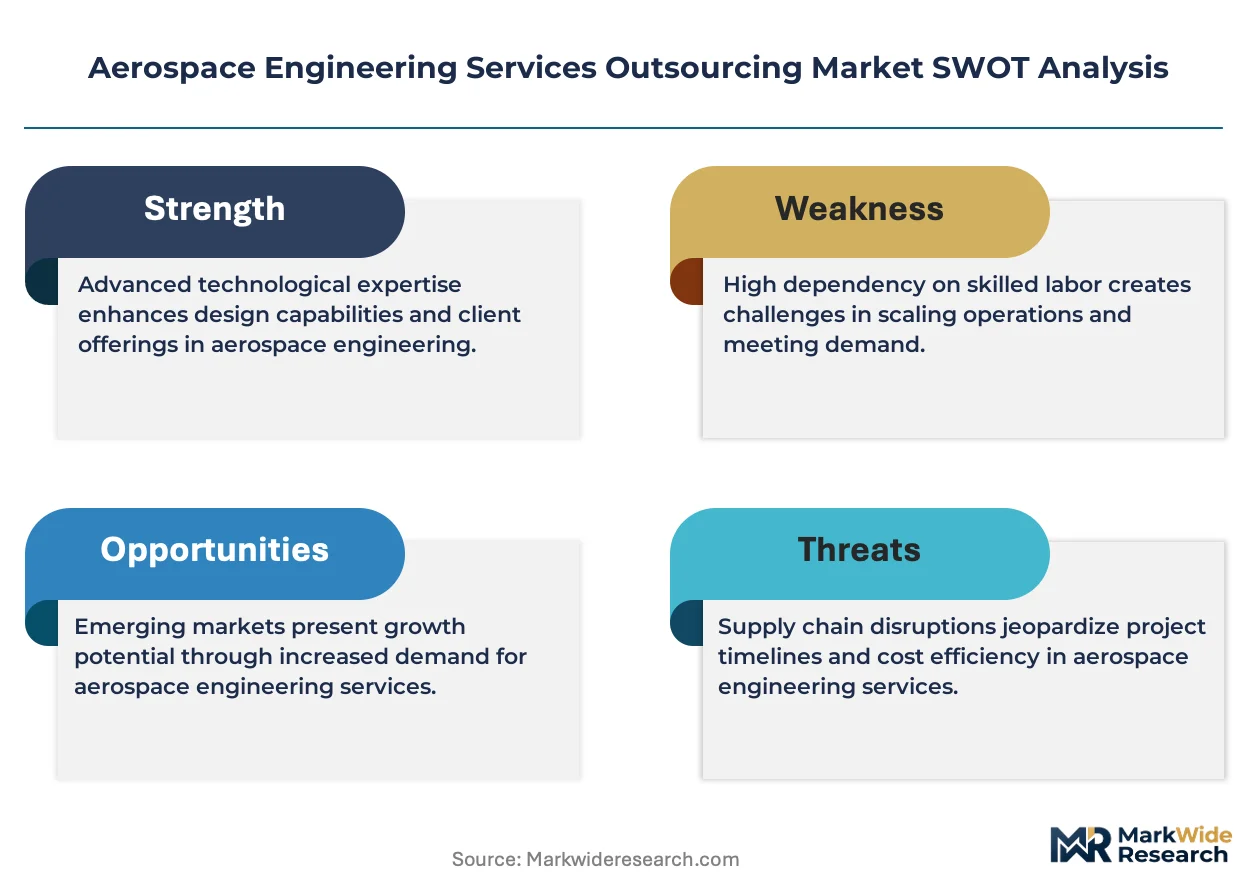
Strategic partnerships dominate the current landscape as engineering service providers blend onsite program management with offshore technical execution to capture expanding margin pools. The vendor base stratifies between diversified technology conglomerates, specialized aerospace engineering firms, and regional delivery specialists. Three archetypes define competitive positioning: certification-intensive European heritage players, scale-driven Indian offshore operators, and hybrid-model integrators with Eastern European delivery footprints. M&A activity and geographic expansion constitute the primary competitive vectors as mid-tier providers seek AS9100 accreditation breadth.
Within the certification-intensive tier, Alten Group and Capgemini Engineering exemplify European design heritage leveraged for regulatory-heavy programs. Among India-based delivery operators, HCLTech occupies a position representing offshore scale advantages in structural analysis workloads. AKKA Technologies anchors the specialized engineering segment with French-rooted aerospace competency. These three company structures illustrate how geographic origin and delivery model architecture determine competitive positioning against FAA and EASA compliance thresholds.
| Leading Market Players |
|---|
| AKKA Technologies |
| Altran |
| Alten Group |
| QuEST Services |
| Bertrandt |
| Capgemini Engineering |
| L&T Technology Services |
| Honeywell International |
| HCLTech |
| Others |
Cost & Logistics Intelligence
Titanium and nickel superalloy volatility cascades through fixed-price engineering contracts as aerospace-grade metal price swings compress margins on propulsion component design work, forcing tiered pricing separation between AS9100-accredited premium providers and standard-tier engineering houses.
Pricing Analysis
Direct-to-OEM discount structures dominate commercial aviation procurement, with airframer procurement teams in Toulouse and Seattle unbundling digital twin development from physical testing programs. Price differentiation rests on certification grade—DO-178C software approval and EASA design organization approval command 25-40% rate premiums over standard structural analysis services. Cost compression in fixed-price milestone contracts is intensifying because titanium and nickel superalloy volatility transfers material risk to engineering service providers. Drone manufacturers exhibit highest price sensitivity, prioritizing rapid prototyping capabilities over established aerospace heritage, while defense subcontracting with cost-plus incentive fee structures shows lowest sensitivity.
Supply Chain Analysis
Regional distribution centers in Bangalore and Hyderabad anchor hub-and-spoke patterns for structural analysis and simulation workloads, with secondary nodes emerging in Warsaw and Krakow for European OEM proximity requirements. Engineering talent supply concentrates in India, Poland, and Romania as cost arbitrage destinations, drawing from carbon fiber-reinforced polymer feedstocks, aerospace-grade titanium billet, and specialized wind tunnel facilities. Single-source vulnerability in AS9100 auditor scarcity creates qualification bottlenecks for mid-tier providers seeking supplier status. Distribution runs through hybrid delivery models blending onsite program management with offshore technical execution.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as FAA airworthiness directives and EASA certification requirements drive demand-shift toward accredited partners with formal methods verification capabilities.
For Market Incumbents: Acquire AS9100-accredited engineering centers in Eastern Europe to preempt talent competition from domestic IT sectors in Bangalore and Hyderabad. Consolidate certification documentation capabilities to defend against emerging Polish and Romanian delivery specialists capturing European OEM proximity requirements. Backward integration into specialized wind tunnel and electromagnetic interference facilities creates captive supply of testing infrastructure that drone manufacturers and urban air mobility developers cannot replicate. For New Entrants and Emerging Players: Enter via sustainable aviation fuel certification services for EU Green Deal emissions mandates, where engineering demand for powerplant modification packages remains underpenetrated relative to established structural analysis segments. Target drone manufacturers in agricultural spraying and logistics unmanned systems as the most penetrable end-user segment, prioritizing rapid prototyping capabilities over legacy aerospace heritage. Position around predictive maintenance algorithm development for digital twin convergence as the go-to-market angle. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-tier providers lack AS9100 accreditation breadth and EASA design organization approvals delay revenue recognition. Long-term viability favors hybrid-model integrators with Eastern European delivery footprints capable of blending cost arbitrage against regulatory proximity requirements. Acquisition target archetype: specialized engineering firms with DO-178C certification experience and existing relationships with urban air mobility developers in Germany and France. Watch EASA's autonomous aircraft regulatory framework as the signal for formal methods verification capability premiums.| Strategic Initiative | Industry Significance |
|---|---|
| AS9100 Accreditation Expansion | Unlocks supplier qualification for Boeing and Airbus procurement teams under FAA and EASA mandates. |
| Eastern European Delivery Center Buildout | Captures cost arbitrage for European OEM proximity requirements in Poland and Romania. |
| Digital Twin Capability Investment | Enables physics-based simulation fused with operational sensor data for predictive maintenance services. |
| Urban Air Mobility Partnership | Secures early positioning in electric vertical take-off and landing platform development for German and French developers. |
| Composite Manufacturing Engineering Acquisition | Adds automated fiber placement programming expertise for carbon fiber-reinforced polymer airframe programs. |
Research Approach
Bottom-up end-use modeling reconciled against top-down supply-side tracking forms the analytical core, combining primary interviews with engineering service provider executives, OEM procurement managers at Airbus and Boeing, regulatory affairs specialists at FAA and EASA, and drone manufacturer technical leads with secondary validation through AS9100 certification body records, EASA design organization approval databases, SEC filings from listed engineering service providers, and customs data on aerospace-grade titanium and nickel superalloy trade flows. Triangulation across these sources validates contracted engineering hour estimates and certification timeline assumptions.
Historical trendline analysis of engineering services outsourcing penetration rates across commercial aviation fleet modernization cycles informs the projection framework, with segmentation modeled across service type, end user, project type, and delivery model dimensions throughout the forecast period. CAGRs derive from regression analysis of accredited engineering center investments, airframer externalization trends, and regulatory burden expansion. Industry-specific forecast inputs include EASA autonomous aircraft framework progression and sustainable aviation fuel certification demand under EU Green Deal mandates.
The model holds under stable FAA and EASA regulatory burden trajectories; deviation in autonomous flight governance timelines or titanium superalloy price volatility would shift engineering service provider margin assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Military Sensors Market
Others
Global Maritime Freight Transport Market
Others
Aluminium Clad Printed Circuit Board Market
Others
South America Automotive LED Lighting Market
Others
Aircraft Switches Market
Others
Bulgur Market
Others
United States Air Furnaces Market
Others
Electric Chainsaw Market
Others
Linear Shaft Market
Others
Printing Machines Market
Others
Nyerereite Market
Others
Smart Home Service Market
Others
Turkey Health and Medical Insurance Market
Others
Infant Fever Stickers Market
Others
Retail Digital Signage Market
Others
Stichtite Market