
 Retail Digital Signage Market | 2026-2036
Retail Digital Signage Market Size, Share, and Industry Trends Forecast 2026-2036
Retail Digital Signage Market Outlook
In-store media networks is reshaping how brands reach shoppers at the point of decision. Samsung Electronics Co. leverages its semiconductor supply chain to control display panel costs across retail formats. LG Electronics anchors its position through OLED brightness innovations suited to window-facing installations. Panasonic Corporation competes on ruggedized outdoor screen durability for gas station and transit shelter networks.
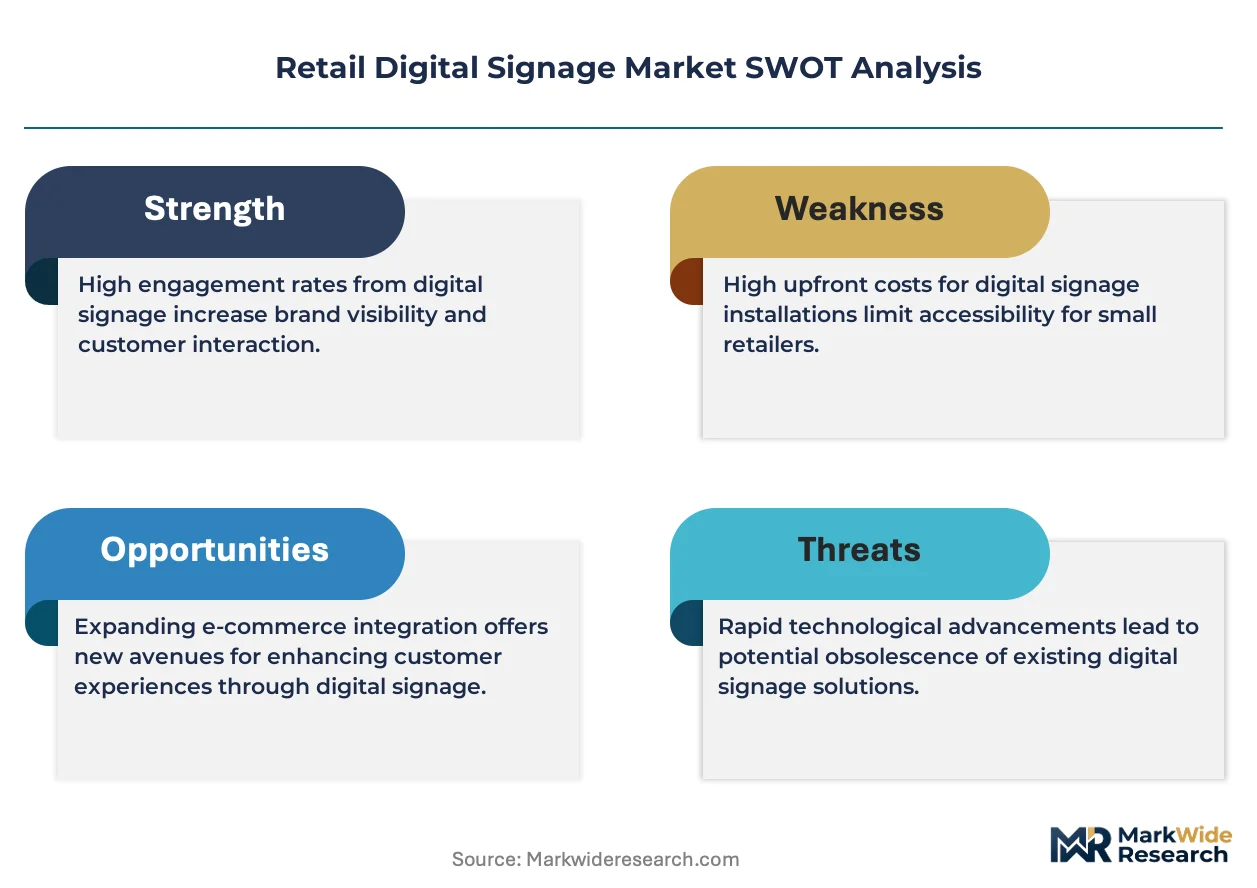
Retail digital signage comprises networked visual display systems—typically LED, LCD, or projection-based—running content management software to deliver targeted messaging in commercial environments. These systems operate at brightness levels exceeding 2,500 nits for daylight-viewable window displays, with edge-lit LED backplanes dominating volume production due to thinner profiles and lower thermal loads. LED displays command the largest installed base among product types, while interactive kiosks generate the fastest expansion as self-service checkout and wayfinding applications multiply. Cloud-based technology deployments are displacing on-premise server architectures, particularly among multi-location retailers seeking centralized content scheduling across hundreds of endpoints.
FCC equipment authorization requirements govern wireless connectivity modules embedded in U.S. digital signage hardware, while the EU Ecodesign Directive and RoHS substance restrictions shape material choices for screens sold across Europe. Retailers must navigate divergent electromagnetic compatibility testing regimes between North American and European certification bodies when sourcing globally. Stakeholders should monitor how energy efficiency labeling mandates in major economies affect total cost-of-ownership calculations for large-format video wall deployments.
Market Dynamics
Cloud-native content management platforms are compressing deployment cycles from months to weeks, forcing hardware vendors to abandon proprietary software stacks and embrace API-first architectures that integrate directly with retailer inventory systems.
Growth Catalysts
- EU Ecodesign Directive:Energy efficiency mandates are accelerating LED backlight replacement cycles across European retail estates, creating refresh demand for compliant display hardware.
- Quick-service restaurant drive-thru lanes:Menu board digitization is expanding screen counts per location from two to six units as dynamic pricing and daypart messaging prove revenue-positive.
- Edge computing architectures:Local processing nodes enable sub-100-millisecond content triggers tied to POS transaction data, unlocking real-time promotional relevance.
Market Restraints
- Indium tin oxide supply concentration:Touchscreen layer production concentrates in East Asian refineries, exposing hardware margins to rare earth price volatility.
- RoHS substance restrictions:Lead-free solder alternatives reduce thermal cycling durability in outdoor installations, shortening warranty-covered lifespans.
- Projection-based systems:Ambient light interference limits deployment to controlled indoor environments, constraining addressable footprint versus direct-view LED.
Strategic Opportunities
- Southeast Asian shopping malls:Deployment rates in Thai and Vietnamese retail centers are accelerating as foreign capital funds mixed-use development.
- CSRD disclosure requirements:European retailers must report scope-three emissions, creating demand for digital signage that replaces printed collateral and demonstrates sustainability metrics.
- Computer vision convergence:Audience measurement cameras integrated with CMS platforms enable impression-based ad sales models for in-store media networks.
Industry Challenges
- Legacy CMS migration:On-premise server architectures resist cloud porting due to customized middleware, forcing parallel system operation during transition windows.
- FCC equipment authorization timelines:Wireless module certification delays product launches by 8-14 weeks, compressing seasonal deployment windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Retail Digital Signage Market |
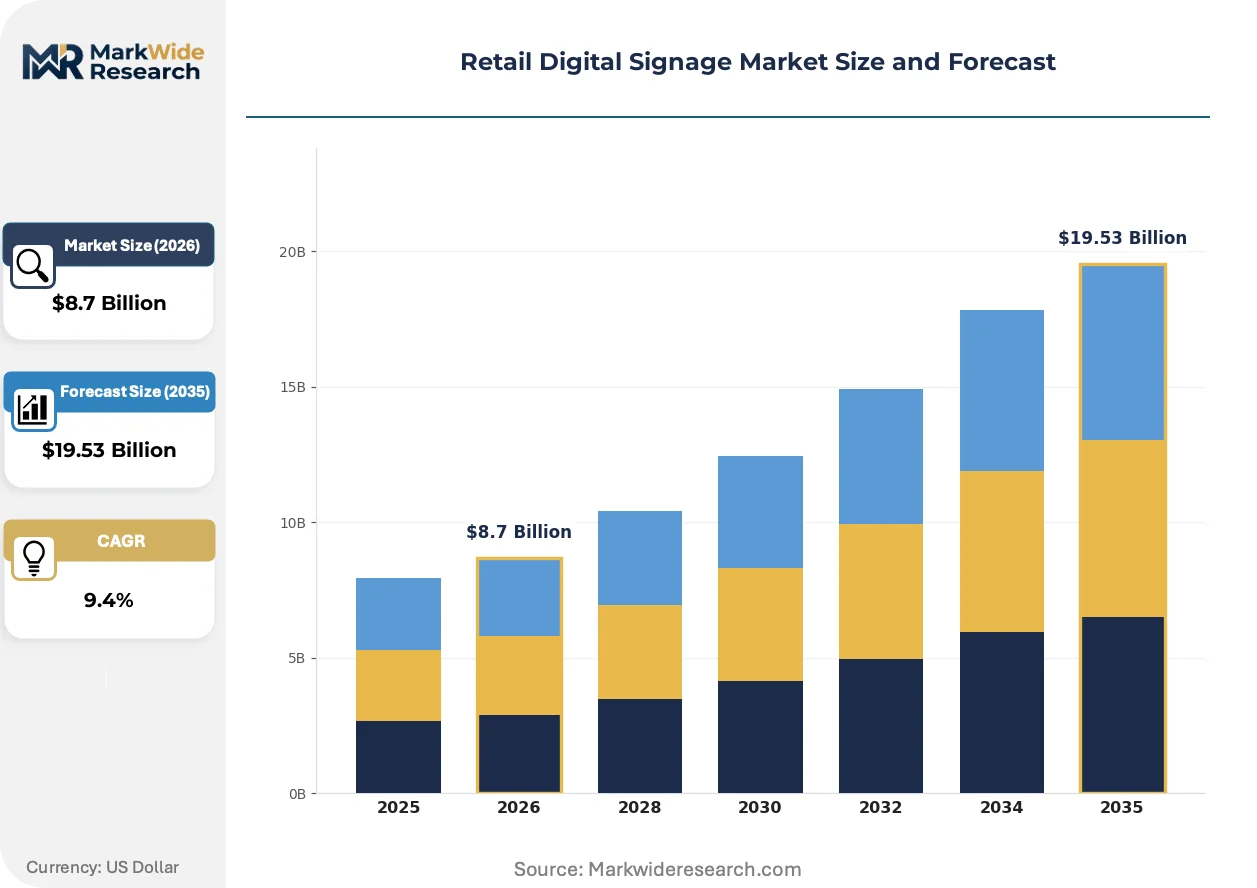
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED Displays, LCD Panels, Projection Systems, Interactive Kiosks End User: Supermarkets, Malls, Restaurants, Healthcare Facilities Technology: Cloud-based, On-premise, IP-based, Digital Media Players Content Type: Advertising, Information, Live Feeds, Social Media |
| Companies Covered | Samsung Electronics Co., LG Electronics, Panasonic Corporation, Sharp Corporation, Sony Group Corporation, Leyard Optoelectronic Co., Ltd., NEC Corporation, Planar Systems Inc., Daktronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Retail Digital Signage Market Strategic Shifts
Display technology roadmaps are bifurcating between ultra-high-brightness outdoor specifications and transparent OLED form factors for premium retail environments.
MicroLED pixel pitch is migrating from stadium and command-center applications into flagship retail installations as manufacturing yields improve and die-transfer costs decline. Luxury department stores in Dubai and Singapore are piloting seamless video walls with sub-1mm pitch for immersive brand storytelling. This migration from commercial-AV to consumer-facing retail is compressing price premiums and forcing LCD manufacturers to defend position through supply chain scale.
REACH substance restrictions are tightening cadmium and mercury thresholds in display backlights, compelling manufacturers to qualify quantum-dot phosphor alternatives. The industrial consequence is extended R&D cycles for new panel introductions as material substitution requires reliability validation. European retailers sourcing hardware face compliance documentation burdens that Asian competitors currently absorb upstream.
Buyer procurement patterns are consolidating vendor relationships from point-solution purchases to multi-year managed service agreements spanning hardware, software, and field maintenance. Grocery chains now demand uptime guarantees with penalty clauses, transferring operational risk to display network operators. This shift is most visible in US and UK markets where labor cost inflation makes in-house technical staffing uneconomical.
Retail Digital Signage Market Segmentation
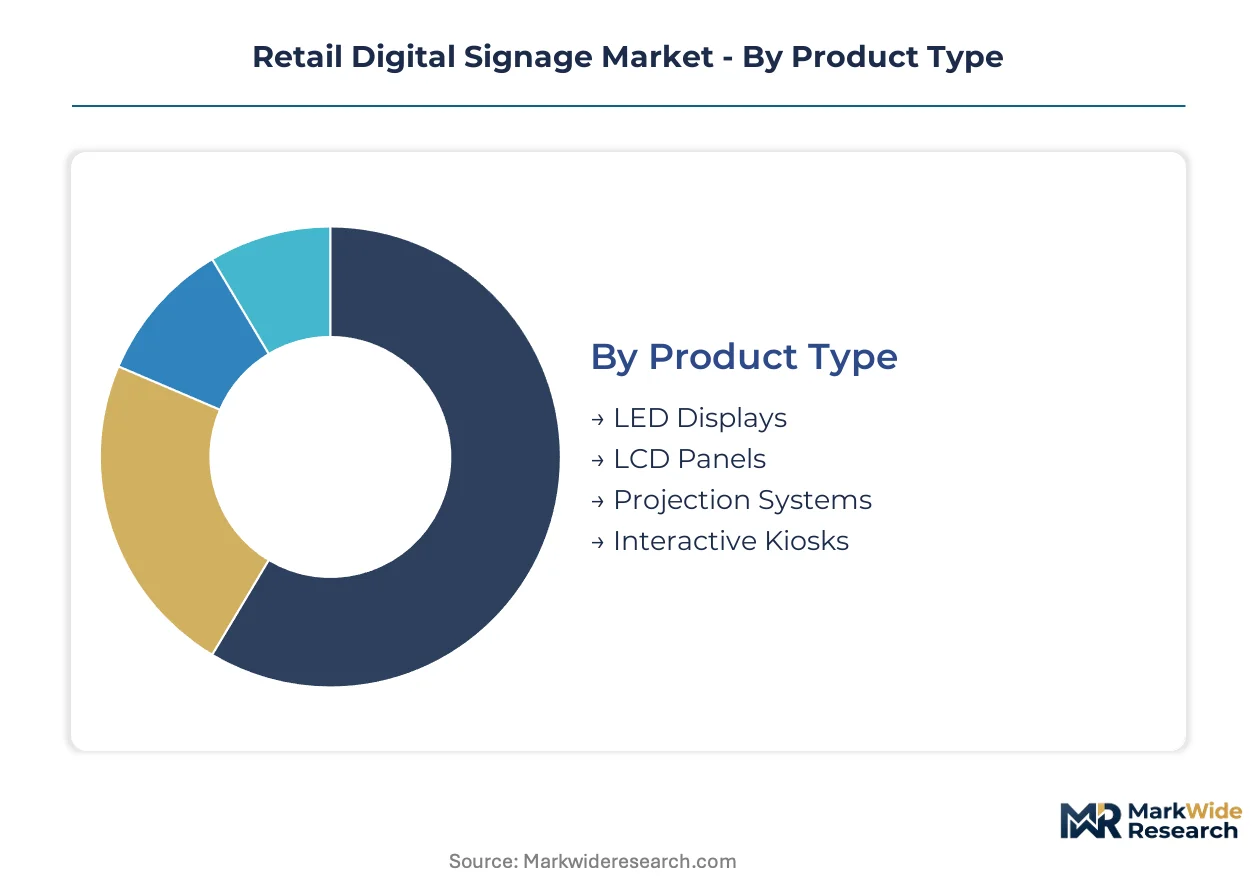
Product architecture, deployment environment, and content delivery mode each create distinct margin profiles and replacement cycles. Vendors must align hardware specifications, software stacks, and service models to the operational tempo of each segment cluster.
Product Type:
Cost tier determines panel technology selection, with brightness specifications and form factor driving unit economics across retail formats.
- LED Displays:Direct-view LED matrices deliver luminance exceeding 2,500 nits for daylight-viewable window installations. Grocery chains and quick-service restaurants deploy these at scale across checkout zones and drive-thru lanes where ambient light interference is severe. LED Displays command the established base. The steepest expansion runs through Interactive Kiosks.
- LCD Panels:Edge-lit LED backplanes dominate volume production due to thinner profiles and lower thermal loads, with OLED brightness innovations suited to premium window-facing installations. Panasonic Corporation competes on ruggedized variants for gas station and transit shelter networks facing thermal cycling stress.
- Projection Systems:Ambient light interference constrains deployment to controlled indoor environments, limiting addressable footprint versus direct-view alternatives in Southeast Asian shopping malls.
- Interactive Kiosks:Self-service checkout and wayfinding applications multiply across supermarket estates, with touchscreen layers exposing hardware margins to rare earth price volatility from East Asian indium tin oxide refineries.
LED Displays anchor installed volumes. Interactive Kiosks gain share fastest as self-service applications multiply.
End User:
Application environment dictates durability specifications, content refresh frequency, and integration depth with operational systems.
- Supermarkets:Checkout zone networks require sub-100-millisecond content triggers tied to POS transaction data, with edge computing architectures unlocking real-time promotional relevance. Cloud-based content management platforms compress deployment cycles from months to weeks.
- Malls:Mixed-use developments in Thailand and Vietnam accelerate deployment rates as foreign capital funds retail center expansion, with seamless video walls piloting sub-1mm pixel pitch for immersive brand storytelling.
- Restaurants:Drive-thru menu board digitization expands screen counts per location from two to six units as dynamic pricing and daypart messaging prove revenue-positive.
- Healthcare Facilities:Wayfinding and queue management applications demand HIPAA-compliant content management with audit trails for patient-facing messaging systems.
Supermarkets represent the fastest-growing trajectory for edge-compute integration. Malls show the steepest expansion in Southeast Asian deployment rates.
Technology:
Maturity of infrastructure determines whether retailers adopt centralized cloud architectures or maintain on-premise control over content distribution.
- Cloud-based:API-first architectures integrate directly with retailer inventory systems, displacing proprietary software stacks as multi-location operators seek centralized scheduling across hundreds of endpoints.
- On-premise:Customized middleware resists cloud porting, forcing parallel system operation during transition windows and extending legacy maintenance obligations.
- IP-based:Networked distribution protocols enable remote device management across dispersed retail estates with standardized firmware update pipelines.
- Digital Media Players:Embedded computing modules drive display intelligence at the edge, supporting computer vision convergence for audience measurement cameras.
Cloud-based deployments are concentrating among multi-location retailers. On-premise retains share in security-sensitive installations.
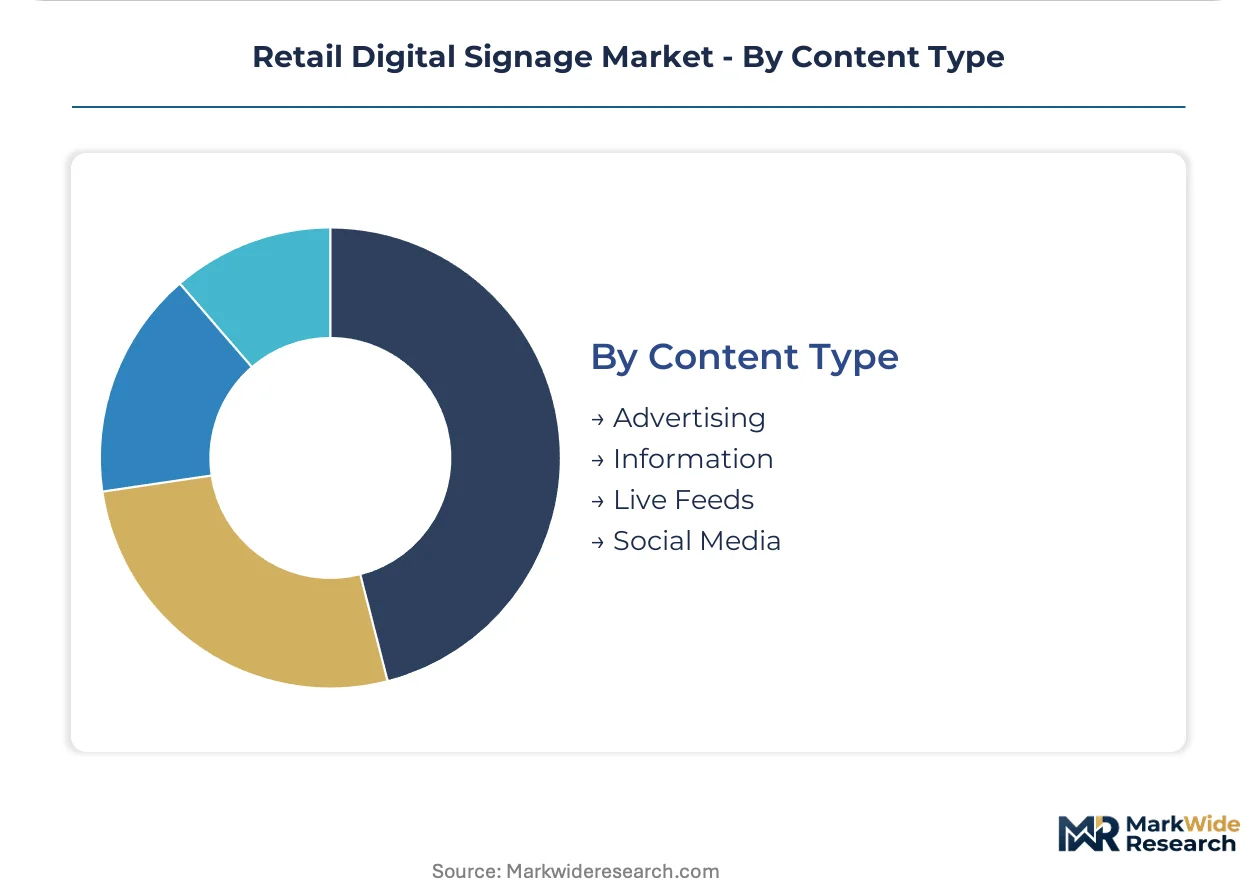
Content Type:
Customer type separates revenue-generating advertising inventory from operational messaging and experiential engagement.
- Advertising:Impression-based ad sales models emerge as computer vision convergence enables audience measurement for in-store media networks, with CSRD disclosure requirements creating demand for digital replacements of printed collateral.
- Information:Inventory-linked promotional swaps tied to real-time stock levels reduce waste from outdated pricing displays across grocery chains.
- Live Feeds:Broadcast integration supports event-driven engagement in flagship retail environments with immersive video wall installations.
- Social Media:User-generated content curation demands moderation pipelines and brand safety protocols for public-facing displays.
Advertising commands revenue concentration. Information displays climb fastest as inventory system integration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Los Angeles-Long Beach complex underwrites North American display hardware import volumes, while Singapore's Changi Logistics Hub serves as the trans-shipment nexus for Southeast Asian retail estates.
United States
Grocery chains and quick-service restaurants deploy screen networks at scale across checkout zones and drive-thru lanes. FCC equipment authorization requirements govern wireless connectivity modules embedded in U.S. digital signage hardware. The Dallas-Fort Worth metroplex anchors deployment velocity for gas station and transit shelter networks.
Germany
Energy efficiency mandates from the EU Ecodesign Directive accelerate LED backlight replacement cycles across European retail estates. REACH substance restrictions tighten cadmium and mercury thresholds in display backlights, compelling manufacturers to qualify quantum-dot phosphor alternatives. The Rhine-Ruhr industrial corridor concentrates hardware distribution infrastructure for Central European markets.
China
Domestic shopping mall development and transit infrastructure expansion drive direct-view LED matrix installations. MIIT certification requirements shape electromagnetic compatibility testing regimes for networked display systems. The Yangtze River Delta manufacturing cluster, centered on Shanghai and Suzhou, controls panel production scale for export markets.
Japan
Luxury department stores pilot seamless video walls with sub-1mm pixel pitch for immersive brand storytelling. METI efficiency standards influence thermal management specifications for indoor installations. The Kanto region surrounding Tokyo anchors flagship retail technology adoption and content management platform development.
Vietnam
Mixed-use retail center expansion accelerates as foreign capital funds development in Ho Chi Minh City and Hanoi. The country's national standards body governs electrical safety certification for imported display hardware. Da Nang's emerging commercial corridor attracts pilot deployments for outdoor screen durability testing in tropical humidity conditions.
Retail Digital Signage Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in panel and semiconductor supply chains. The market structures around three to five dominant conglomerates with captive display manufacturing, surrounded by specialized software vendors and regional installation service providers. Korean and Japanese electronics conglomerates anchor the premium hardware segment; Chinese LED matrix fabricators compete on cost at scale. Competitive moves concentrate on API-first architecture partnerships with retailer inventory systems and multi-year managed service agreements with uptime guarantee clauses.
Within the conglomerate tier, Samsung Electronics Co. and LG Electronics exemplify vertically integrated platform providers with semiconductor supply chain control. Panasonic Corporation occupies a position among diversified industrial electronics groups competing on ruggedized outdoor specifications. These three anchors demonstrate how captive panel production and content management software development concentrate competitive position in enterprise retail deployments.
| Leading Market Players |
|---|
| Samsung Electronics Co. |
| LG Electronics |
| Panasonic Corporation |
| Sharp Corporation |
| Sony Group Corporation |
| Leyard Optoelectronic Co., Ltd. |
| NEC Corporation |
| Planar Systems Inc. |
| Daktronics |
| Others |
Value Chain & Pricing Dynamics
East Asian indium tin oxide refineries concentrate touchscreen layer production, anchoring hardware margins for interactive kiosk manufacturers while downstream margin pools concentrate with managed service operators bundling field maintenance and uptime guarantees.
Pricing Analysis
Volume-discount tiering structures dominate procurement for grocery chains and quick-service restaurant networks, with pricing stratifies across premium, standard, and economy tiers based on brightness specifications and after-sales service bundling. Price differentiation centers on panel certification grade and geographic delivery cost, with outdoor-rated ruggedized displays commanding substantial premiums over indoor edge-lit alternatives. Cost compression in standard-tier LCD panels is intensifying because Chinese LED matrix fabricators are scaling direct-view production for export markets. Quick-service restaurants exhibit highest price sensitivity due to thin operating margins, while luxury department stores remain least sensitive given experiential investment budgets.
Supply Chain Analysis
Supplier-financing facilities with 90-120 day extended payment terms have become standard for Korean and Japanese display conglomerates serving North American retail estates. Panel production concentrates in China, South Korea, and Japan, with the Yangtze River Delta manufacturing cluster controlling semiconductor backplane supply. Raw material dependencies span rare earth phosphors for quantum-dot backlights, indium tin oxide for touch layers, and aluminum substrates for thermal management. Single-source vulnerability in East Asian indium refining exposes margins to commodity price volatility. Distribution runs through the Port of Los Angeles-Long Beach complex for North American deployment and Singapore's Changi Logistics Hub for Southeast Asian retail estates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Retail digital signage is exiting a capital-expenditure trough as grocery chains and quick-service restaurants refresh pandemic-deferred screen networks, with the cyclical recovery underwritten by inventory-system integration mandates driving replacement demand.
For Market Incumbents: Build switching-cost moats through API-first content management architectures that embed deeply into retailer POS and inventory systems. Samsung Electronics Co. and LG Electronics should accelerate cloud-native platform development to capture multi-year managed service contracts with penalty-backed uptime guarantees. Defensive moves must address emerging threat from Chinese LED fabricators scaling sub-1mm pixel pitch microLED production for flagship retail installations. Priority lever rests on backward integration into semiconductor backplane supply to defend margin position against cost-competitive entrants.
For New Entrants and Emerging Players: Vietnamese mixed-use retail center expansion offers the most penetrable geography, with foreign capital funding development in Ho Chi Minh City and Hanoi creating greenfield deployment opportunities. Healthcare facilities represent underserved segment with HIPAA-compliant content management requirements that incumbent platforms have addressed inadequately. Wayfinding and queue management applications in hospital systems offer specialized entry point. Go-to-market angle should emphasize rapid cloud deployment cycles compressing installation timelines from months to weeks.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-based content management platforms as software margins expand relative to hardware-heavy legacy models. Long-term viability favors platform integrators with recurring revenue streams over pure-play hardware manufacturers facing cyclical replacement demand. Acquisition target archetype includes specialized CMS vendors with established API partnerships to major retailer inventory systems. Signal to watch is penetration of computer vision-enabled audience measurement cameras enabling impression-based ad sales models for in-store media networks.
| Strategic Initiative | Industry Significance |
|---|---|
| API-First Platform Integration | Deep embedding into retailer POS systems creates switching costs and recurring revenue lock-in. |
| Managed Service Agreement Expansion | Uptime guarantee contracts transfer operational risk and extend customer lifetime value. |
| MicroLED Manufacturing Scale-Up | Sub-1mm pixel pitch production captures flagship retail experiential budgets from LCD incumbents. |
| Computer Vision Convergence | Audience measurement cameras enable impression-based ad sales for in-store media networks. |
| Southeast Asian Geographic Expansion | Thai and Vietnamese mixed-use developments offer accelerated deployment rates funded by foreign capital. |
Study Parameters
The analysis maps LED display hardware, LCD panel systems, interactive kiosks, and projection technologies, each validated through chief technology officers at grocery chains, quick-service restaurant operations directors, digital signage procurement managers, and cloud platform integration specialists. Primary interviews combined with secondary validation from FCC equipment authorization filings, EU Ecodesign Directive implementation reports, MIIT certification databases, and customs import records at the Port of Los Angeles-Long Beach. Bottom-up unit deployment estimates triangulated against top-down capital expenditure disclosures from major retail conglomerates.
Fixed assumptions across the projection horizon include continued cloud displacement of on-premise architectures, stable rare earth supply from East Asian refineries, and gradual REACH substance restriction tightening without disruptive material bans. Segmentation dimensions modeled span product architecture, deployment environment, end-user vertical, content delivery technology, and regional regulatory cluster. CAGRs derived from logistic diffusion curves fitted to historical replacement cycles and forward deployment pipeline visibility. Industry-specific forecast inputs include quick-service restaurant drive-thru digitization rates and Southeast Asian shopping mall development permits.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese LED fabricators into microLED flagship installations would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
3D Printing Construction Market
Others
Tobacco Packaging Market
Others
Global Compact Wheel Loaders Market
Others
Three Proofing Rugged Tablet Market
Others
Hookah Tobacco Market
Others
Global Injectable Nanomedicine Market
Others
Middle East 3D Printing Construction Market
Others
Construction Fabrics Market
Others
Legal Services Market
Others
Japan Automotive LED Lighting Market
Others
HPHT Diamond Cubic Press Market
Others
Embedded Computer Market
Others
France Smart Home Market
Others
Molecular Spectroscopy Market
Others
Toy Packaging Market
Others
Global Electronic Filters Market