
 Military Sensors Market | 2026-2036
Military Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Military Sensors Market Analysis
US prime contractors is recalibrating production schedules around classified next-generation programs. Lockheed Martin Corporation leverages its Skunk Works division to sustain classified sensor integration programs. BAE Systems plc anchors European supply through its UK and Swedish facilities, competing on sovereign capability requirements.
Military sensors encompass transducers, signal processors, and environmental monitors engineered to detect electromagnetic, acoustic, thermal, or mechanical stimuli across operational wavelengths from ultraviolet through microwave. These devices convert physical phenomena into actionable intelligence for weapons platforms, C4ISR networks, and force protection systems. Radar and infrared modalities dominate procurement volume, while multispectral and hyperspectral technologies capture accelerating investment as datalink bandwidth expands. The surveillance application segment leads installed base, though targeting systems command premium pricing through precision-strike integration.
The US Department of Defense, NATO Standardization Office, and UK's Defence Science and Technology Laboratory collectively shape interoperability mandates, export control thresholds, and electromagnetic compatibility certifications that gate market access. Compliance with ITAR, EAR, and emerging EU defense procurement directives now determines supplier eligibility across allied procurement channels. Stakeholders must monitor fragmentation between AUKUS-aligned technical standards and continental European certification pathways.
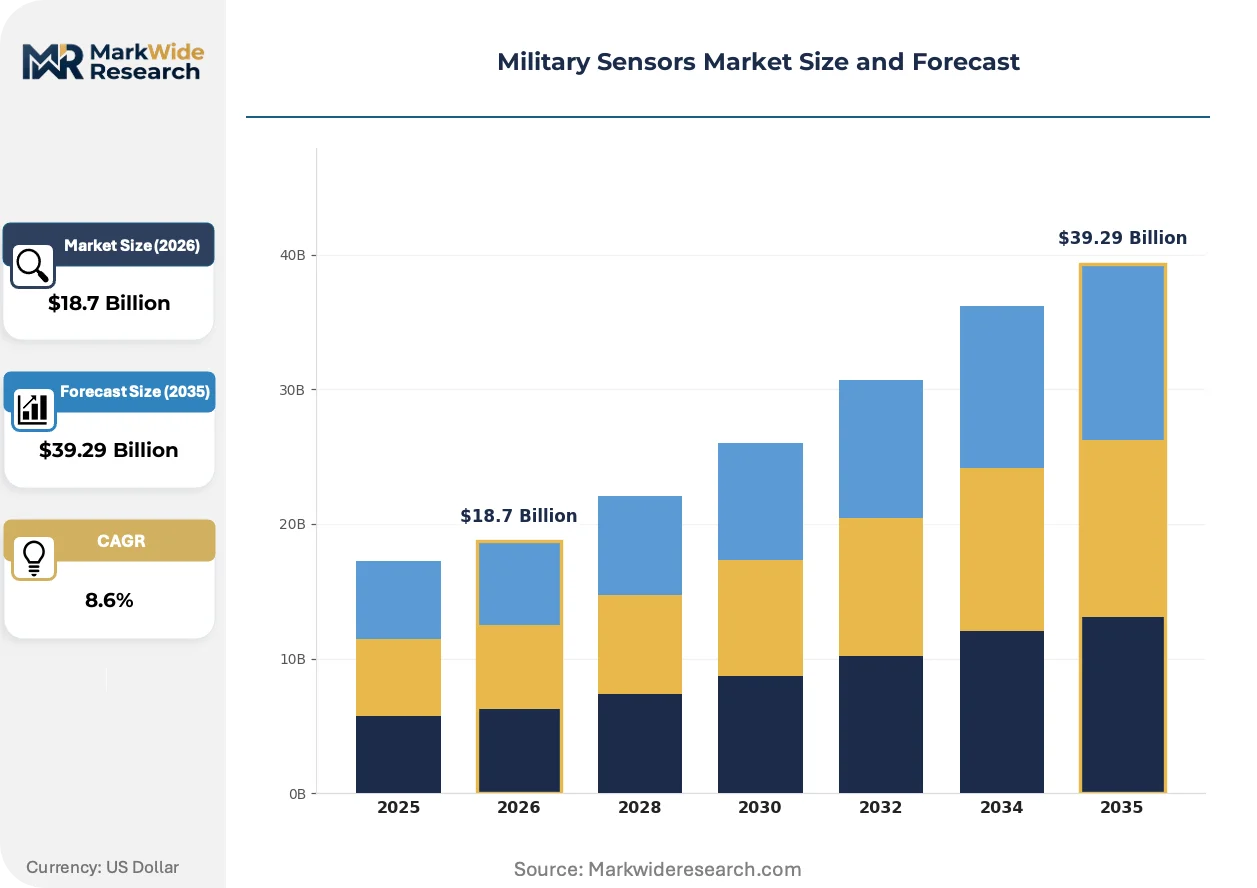
Market Dynamics
The US Department of Defense's Joint All-Domain Command and Control architecture is forcing sensor manufacturers to redesign hardware for seamless interoperability across air, land, sea, space, and cyber domains. This mandate is compressing development cycles while elevating cybersecurity hardening requirements.
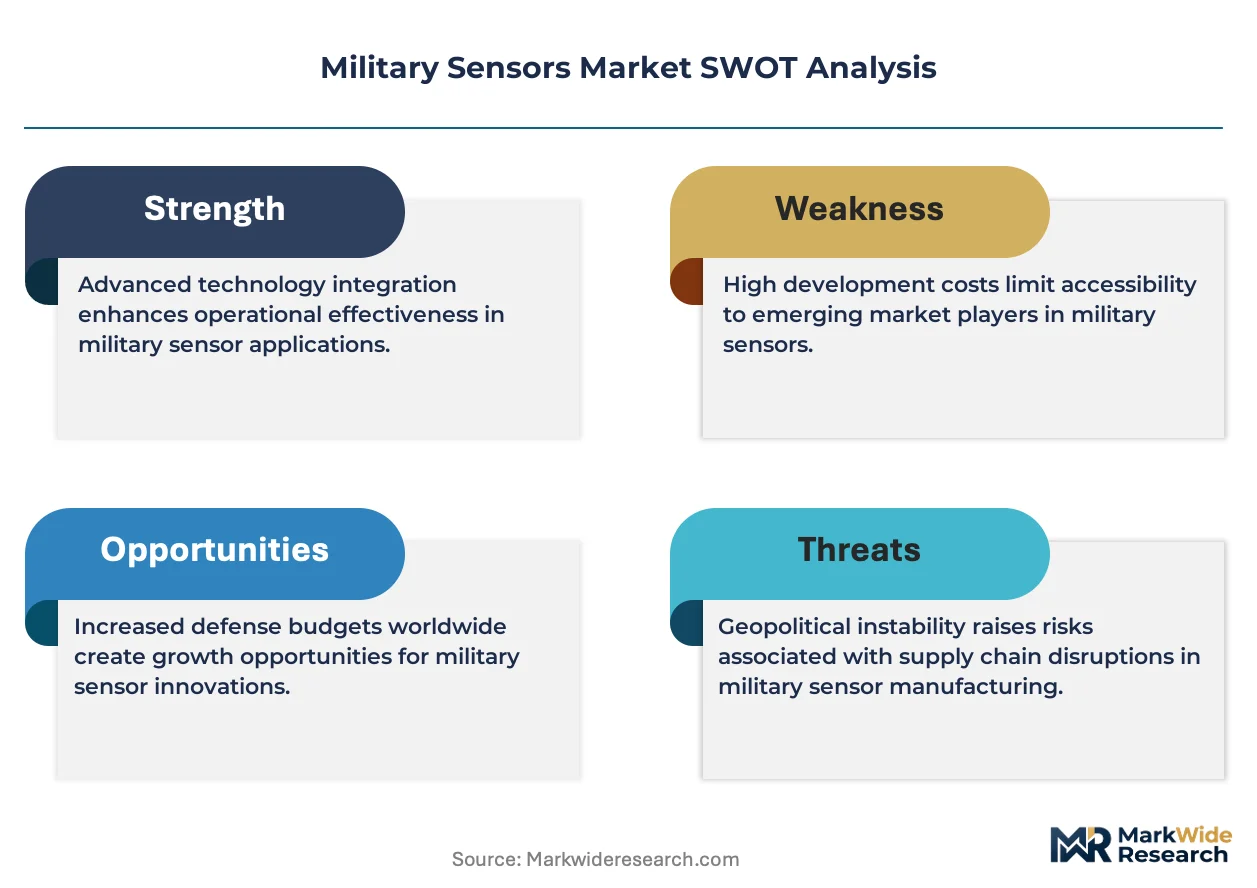
Growth Catalysts
- JADC2 Architecture Mandate:The Pentagon's integrated warfare framework requires sensors with open-systems standards and modular hardware interfaces. Defense primes must retool production lines to meet these specifications.
- Indo-Pacific Theater Priorities:US Pacific Command operations are driving demand for maritime surveillance radars and distributed aperture systems. Island-chain deterrence strategies require persistent sensor coverage across contested waters.
- Hyperspectral Imaging Maturation:Advances in focal plane array manufacturing are reducing unit costs for multispectral payloads. These systems now deploy on tactical unmanned platforms previously limited to electro-optical sensors.
Market Restraints
- ITAR Compliance Burden:US International Traffic in Arms Regulations restrict technology transfer to allied nations. European and AUKUS partners face delays accessing classified sensor architectures.
- Semiconductor Supply Concentration:Advanced analog-to-digital converters and gallium nitride components depend on limited foundry capacity in East Asia. Single-source dependencies create vulnerability for precision-guided munition seekers.
- Electromagnetic Spectrum Saturation:Civilian 5G networks and commercial satellite constellations crowd military frequency allocations. Radar and communications systems face interference in contested environments.
Strategic Opportunities
- AUKUS Technology Pooling:The trilateral security pact between Australia, the United Kingdom, and the United States enables shared development of undersea sensing networks. Sovereign industrial bases gain access to previously restricted architectures.
- Urban Warfare Sensor Packages:Dense environment operations require acoustic gunshot locators, through-wall radar, and chemical detection miniaturized for dismounted soldiers. Special operations forces represent an underserved procurement channel.
- EU Defense Fund Incentives:The European Defence Fund allocates resources for collaborative sensor research among member states. Projects addressing electromagnetic spectrum dominance receive priority funding.
Industry Challenges
- Cleared Workforce Scarcity:Security clearance backlogs extend hiring timelines for software engineers and systems integrators. Classified program access requirements limit talent pools for prime contractors.
- Legacy Platform Integration:Fourth-generation aircraft and surface vessels require sensor upgrades without airframe modifications. Retrofit engineering consumes engineering resources that could deploy on next-generation systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Military Sensors Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $39.29 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Sensor Type: Radar, Lidar, Acoustic, Infrared Application: Surveillance, Targeting, Navigation, Reconnaissance End User: Military, Defense Contractors, Government Agencies, Law Enforcement Technology: Active, Passive, Multispectral, Hyperspectral |
| Companies Covered | Honeywell International Inc., Lockheed Martin Corporation, RTX Corporation, Thales Group, BAE Systems plc, Raytheon Technologies, TE Connectivity Ltd., Kongsberg Gruppen ASA, L3Harris Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Military Sensors Market Emerging Trajectories
Sensor fusion architectures are replacing standalone detection systems. Artificial intelligence at the edge is compressing decision timelines from detection to engagement. These shifts are elevating software and algorithmic content in procurement evaluations.
Quantum sensing modalities are expanding into navigation and timing applications. The US Air Force Research Laboratory and DARPA are field-testing atomic interferometers for GPS-denied environments. These systems enable precision strike without satellite dependency, compressing the electromagnetic signature of advanced platforms.
The EU AI Act establishes risk classification frameworks for autonomous targeting systems. European defense ministries must demonstrate human oversight mechanisms in lethal decision chains. Sensor manufacturers serving NATO markets are embedding circuit-breaker protocols and audit logging to satisfy these mandates.
Allied defense ministries are consolidating sensor procurement through framework agreements rather than platform-specific contracts. The UK's Defence Equipment and Support organization and Australia's Capability Acquisition and Sustainment Group now prioritize common data standards over bespoke specifications. This behavioral shift favors suppliers with modular product architectures and penalizes point-solution vendors.
Military Sensors Market Segmentation
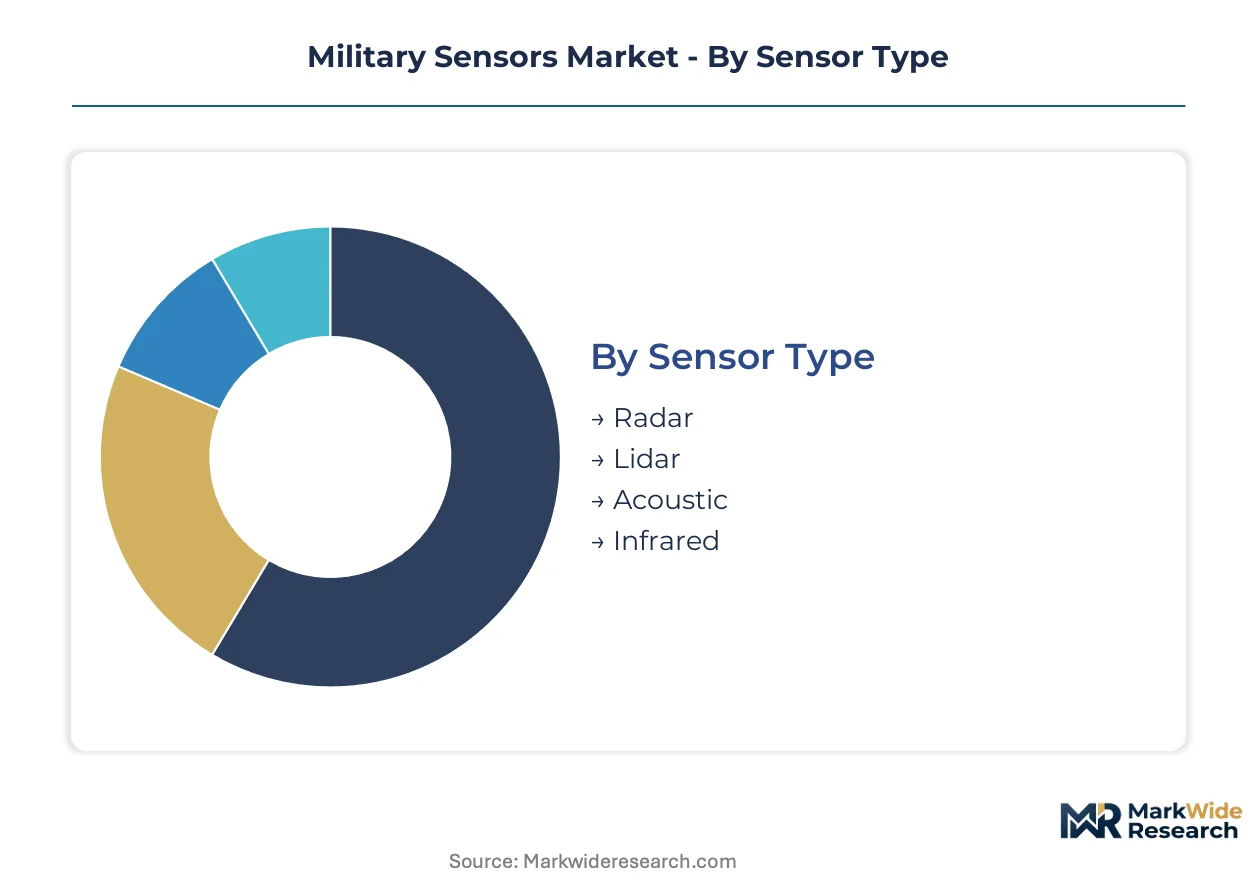
Segmentation in military sensors reveals how procurement pathways diverge across mission requirements and platform constraints. Certification regimes from ITAR to EU defense procurement directives create tiered market access that shapes supplier strategies and customer eligibility.
Sensor Type:
ITAR compliance dominates radar and infrared procurement, while acoustic and lidar systems face lighter export licensing burdens under EAR thresholds. Dual-use designations vary significantly across these modalities.
- Radar:Active electronically scanned arrays and synthetic aperture systems convert electromagnetic returns into track files for fire control and air defense. US Pacific Command drives demand for maritime surveillance variants supporting island-chain deterrence. Gallium nitride component shortages constrain seeker production for precision-guided munitions.
- Infrared:Focal plane arrays detect thermal signatures across short-wave to long-wave bands, enabling passive targeting in contested electromagnetic environments. Staring arrays now deploy on tactical unmanned platforms previously limited to electro-optical payloads. ITAR classification of cooled detector technology restricts allied access.
- Lidar:Laser ranging systems provide three-dimensional mapping for autonomous navigation and obstacle avoidance in GPS-denied conditions.
- Acoustic:Hydrophone arrays and gunshot locators convert pressure waves into bearing estimates for undersea and urban warfare applications.
Leading the category by volume: Radar. Growing fastest: Infrared.
Application:
Cost tiering separates surveillance infrastructure investments from premium targeting system procurements. Surveillance programs optimize for unit economics across distributed networks, while targeting commands price premiums through precision-strike integration.
- Surveillance:Persistent wide-area coverage systems prioritize detection probability over identification confidence, enabling cueing of scarce targeting assets. Distributed aperture architectures reduce single-point vulnerability across contested theaters. Indo-Pacific maritime domain awareness drives investment in over-the-horizon radars.
- Targeting:Fire control sensors achieve sub-meter accuracy for weapon delivery, commanding procurement premiums through kill-chain integration. JADC2 interoperability mandates compress development cycles while elevating cybersecurity hardening requirements. Human-machine interface standards from NATO Standardization Office shape design specifications.
- Navigation:Inertial measurement units and celestial references enable position fixing without satellite dependency. Quantum atomic interferometers from DARPA programs are maturing for GPS-denied environments.
- Reconnaissance:Tactical collection systems emphasize rapid deployment and cross-cueing with national technical means.
Surveillance claims the largest installed base. Targeting captures the steepest expansion trajectory through precision-strike modernization.
End User:
Customer type determines funding stability and specification flexibility. Military end users operate under fixed defense budgets with classified requirements, while defense contractors absorb development risk for platform integration.
- Military:Service branches procure through program offices with milestone decision authority, prioritizing interoperability over proprietary interfaces. US Department of Defense JADC2 architecture mandates open-systems standards across all new sensor acquisitions.
- Defense Contractors:Prime integrators source subsystems for platform incorporation, bearing qualification costs and schedule risk. Lockheed Martin Skunk Works and BAE Systems facilities anchor classified supply chains.
- Government Agencies:Intelligence community users demand specialized collection capabilities outside standard military specifications.
- Law Enforcement:Tactical units require miniaturized packages for urban operations with simplified export licensing.
Military end users dominate procurement volume. Defense contractors represent the fastest-climbing customer segment through platform integration mandates.
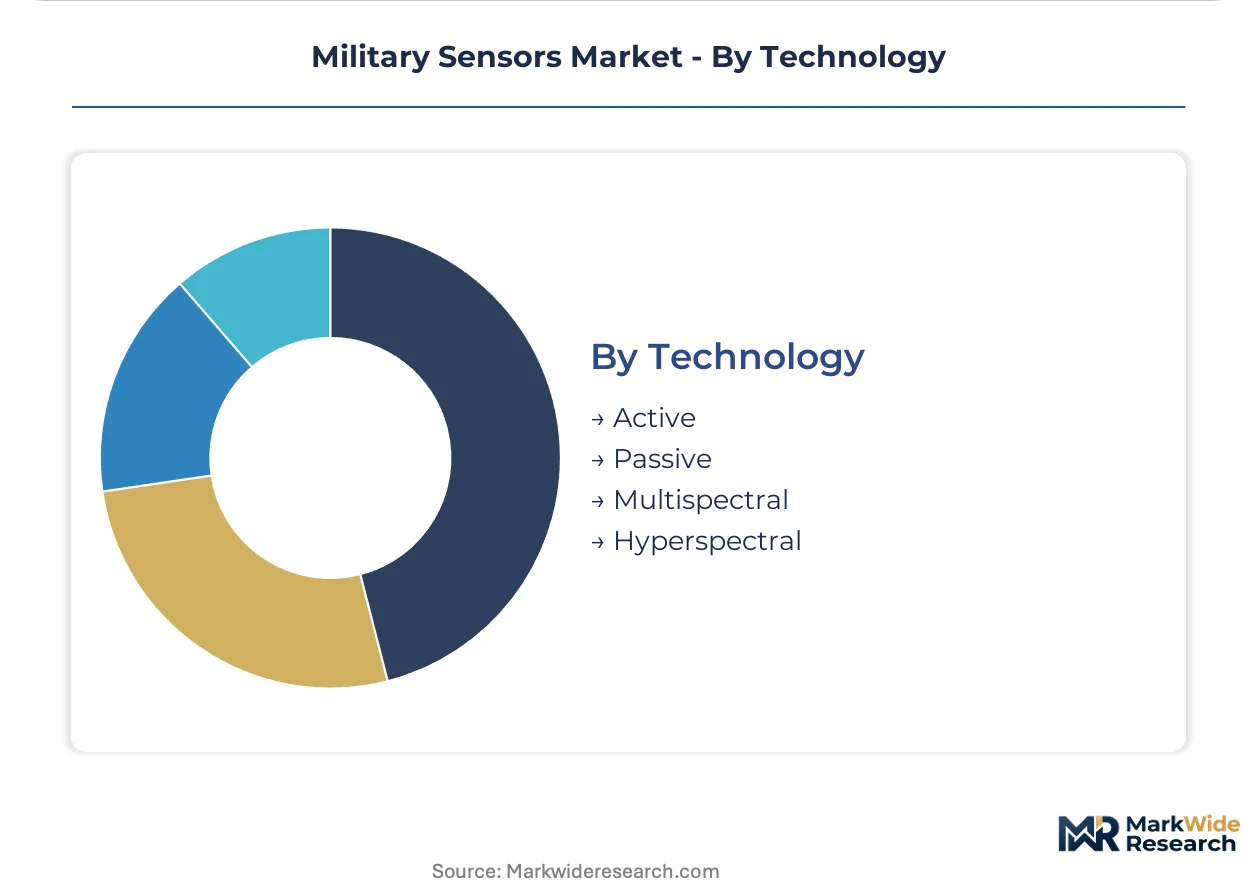
Technology:
Maturity gradients separate established active and passive modalities from emerging multispectral and hyperspectral investments. Legacy architectures face displacement as datalink bandwidth expansion enables sensor fusion at the edge.
- Active:Emit-and-receive systems including radar and lidar provide range and velocity measurements but generate detectable signatures. Electronic protection measures consume increasing processor overhead.
- Passive:Signature-dependent detection avoids emission but requires favorable geometry and environmental conditions. Infrared search and track systems dominate this modality.
- Multispectral:Discrete band imaging across visible through thermal wavelengths enables material discrimination for camouflage penetration. Focal plane array cost reductions now permit tactical deployment.
- Hyperspectral:Continuous spectral sampling identifies chemical signatures and surface compositions previously requiring laboratory analysis. EU AI Act risk classifications constrain autonomous target recognition applications.
Active and passive technologies retain volume leadership. Hyperspectral imaging gains share fastest through focal plane manufacturing advances.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gallium nitride foundry capacity in Taiwan and compound semiconductor substrate production in Japan anchor the geographic distribution of critical sensor components. Defense procurement clusters concentrate where sovereign manufacturing capabilities intersect with classified program access.
United States
The Pentagon's JADC2 architecture and Indo-Pacific theater priorities drive sensor procurement across maritime surveillance and distributed aperture systems. ITAR compliance requirements from the US Department of State restrict technology transfer while shaping domestic supplier eligibility. Lockheed Martin's Skunk Works division in California and RTX Corporation facilities in Massachusetts anchor classified integration programs for next-generation platforms.
United Kingdom
Sovereign capability requirements and AUKUS technology pooling agreements accelerate undersea sensing network development. The UK's Defence Science and Technology Laboratory sets electromagnetic compatibility certifications that gate supplier access to NATO procurement channels. BAE Systems plc operates sensor integration facilities across Bristol and Lancashire, competing on national security-cleared manufacturing capacity.
Germany
EU Defense Fund incentives for collaborative sensor research attract multispectral and hyperspectral technology investments. The country's national defense procurement office mandates CE marking and electromagnetic spectrum dominance standards for platform integration. Industrial clusters in Bavaria and Baden-Württemberg host precision optics manufacturers supplying focal plane arrays for infrared systems.
Australia
AUKUS trilateral security commitments enable access to previously restricted US sensor architectures for undersea and maritime domain awareness. The Capability Acquisition and Sustainment Group prioritizes common data standards over bespoke specifications in framework agreements. Defense technology precincts in South Australia and New South Wales concentrate sovereign submarine sensor development programs.
Japan
METI industrial policy and US-Japan alliance commitments drive domestic production of radar components and infrared focal plane arrays. JIS standards and national security regulations restrict foreign participation in classified sensor programs. Manufacturing concentrations in Nagoya's Chubu region and Kansai's Osaka-Kobe corridor supply precision-guided munition seekers for regional deterrence.
Military Sensors Market Vendor Landscape
Global majors compete with regional champions across classified program access and sovereign manufacturing clearance. The vendor base separates into US primes with Skunk Works-style divisions, European systems integrators with national security credentials, and specialized component suppliers with ITAR-compliant foundry relationships. Three archetypes dominate: vertically integrated platform integrators, sovereign-cleared subsystem specialists, and dual-use technology crossovers from commercial semiconductor markets. Competitive moves concentrate on strategic partnerships for AUKUS technology pooling and portfolio diversification into quantum sensing modalities.
Among US-based defense primes, Lockheed Martin Corporation and RTX Corporation exemplify the vertically integrated archetype with classified program access. European systems integration is anchored by BAE Systems plc and Thales Group, representing sovereign-cleared manufacturing capabilities across UK and French industrial bases. These four entities occupy positions where national security clearance, platform integration authority, and compound semiconductor supply chain access converge.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Lockheed Martin Corporation |
| RTX Corporation |
| Thales Group |
| BAE Systems plc |
| Raytheon Technologies |
| TE Connectivity Ltd. |
| Kongsberg Gruppen ASA |
| L3Harris Technologies |
| Others |
Supply Flow & Price Mechanics
Gallium nitride wafer pricing indices cascade through military sensor supply chains, compressing margins at component tiers while amplifying procurement premiums for ITAR-compliant finished systems. This commodity-cost transmission creates stratified pricing architecture where sovereign-cleared manufacturers capture value that dual-use suppliers forfeit.
Pricing Analysis
Extended warranty and field-service bundling separate prime-contractor pricing from component-vendor quotations, with Lockheed Martin Skunk Works and BAE Systems facilities commanding lifecycle-support premiums. Three-tier pricing structure across ITAR-restricted, EAR-controlled, and commercial-off-the-shelf levels reflects certification-grade differentiation. Cost compression in cooled infrared focal plane arrays intensifies because Taiwanese foundry capacity constraints persist. Defense contractors absorb the least price sensitivity, while government agencies in allied nations face ITAR-driven procurement premiums.
Supply Chain Analysis
Dual-sourcing mandates from the US Department of Defense and NATO Standardization Office require qualified secondary suppliers for gallium nitride substrates, compound semiconductor foundry services, and precision optics. Taiwan, Japan, and the United States anchor critical component manufacturing. Raw material dependencies center on high-purity gallium, sapphire substrates, and specialty gases for epitaxial growth. Single-source vulnerability concentrates in advanced analog-to-digital converter fabrication. Distribution runs through prime-integrator qualification programs rather than open market channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gallium nitride foundry scarcity props sensor pricing across all tiers, constraining volume expansion regardless of procurement demand. This supply ceiling justifies premium positioning for cleared manufacturers with captive semiconductor relationships.
For Market Incumbents: Deploy backward integration into compound semiconductor foundry capacity to secure wafer supply against East Asian concentration risk. Consolidate around JADC2-compliant modular architectures before open-systems mandates obsolete proprietary interfaces. ITAR clearance backlogs threaten talent access; accelerate security-cleared workforce pipelines through university partnerships. For New Entrants and Emerging Players: Launch via sovereign-cleared manufacturing partnerships in AUKUS-aligned jurisdictions to bypass ITAR transfer restrictions. Urban warfare sensor miniaturization for special operations forces represents the most penetrable white space, with through-wall radar and acoustic gunshot locators underserved by prime-contractor portfolios. Target electromagnetic spectrum dominance applications eligible for EU Defense Fund co-development. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier subsystem specialists with ITAR-compliant facilities in the United Kingdom or Australia during AUKUS reorganization windows. Five-to-ten-year viability hinges on quantum sensing modality transitions and sensor-fusion software content expansion. Watch DARPA atomic interferometer field-testing milestones as inflection indicators for GPS-denied navigation market readiness.| Strategic Initiative | Industry Significance |
|---|---|
| JADC2 Architecture Certification | US Department of Defense open-systems mandates gate eligibility for next-generation platform integration. |
| AUKUS Technology Pooling Participation | Trilateral security pact unlocks previously restricted US sensor architectures for UK and Australian sovereign manufacturing. |
| Gallium Nitride Foundry Capacity Expansion | Taiwanese and Japanese substrate supply constraints elevate captive semiconductor production to strategic priority. |
| Quantum Sensing R&D Partnership | US Air Force Research Laboratory atomic interferometer programs signal GPS-denied navigation market formation. |
| EU AI Act Compliance Embedding | Circuit-breaker protocols and audit logging satisfy European autonomous targeting system risk classifications. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with program office acquisition executives, sensor subsystem procurement leads, electromagnetic compatibility certification engineers, and defense prime contractor integration specialists. SEC 10-K disclosures, ITAR license databases, NATO Standardization Office technical standards, and EU Defense Fund award registries provided demand-side validation. Bottom-up platform deployment estimates and top-down defense budget allocation analysis were triangulated against foundry capacity utilization data.
Data-stream reconciliation across shipment volumes, contract award values, and qualification timeline disclosures informed the analytical framework over the projection horizon. Segmentation dimensions modeled encompass sensor modality, application mission profile, end-user funding authority, and sovereign clearance tier. CAGRs were derived from fitted growth curves against historical procurement cycles. JADC2 implementation schedules and Indo-Pacific theater force posture adjustments served as scenario-weighting inputs.
Semiconductor supply disruption, ITAR regulatory reinterpretation, and AUKUS alliance restructuring are the dominant revision risks. Deviation in gallium nitride foundry capacity expansion timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Smart Card Contactless Ticketing Market
Others
Underwater Communication System Market
Others
Canada 3D Printing Construction Market
Others
Asia-Pacific Camping and Caravanning Market
Others
Global Hardware Acceleration Market
Others
Rugged Devices Market
Others
Europe Intercom Devices Market
Others
Flexible PVC Films and Sheets Market
Others
Cathode Battery Material Market
Others
Global Human Augmentation Market
Others
North America Industrial Wearable Devices Market
Others
Diamond Mining Market
Others
Heavy Duty Traps Market
Others
Magnesite Market
Others
Wearable Brain Devices Market
Others
Mobile Computing Devices Market