
 Aircraft Cameras Market | 2026-2036
Aircraft Cameras Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Cameras Market Outlook
Software-defined imaging subscription packages is expanding as a recurring revenue layer that reshapes how camera systems get monetized beyond hardware sales. Collins Aerospace leverages its avionics integration depth to bundle predictive maintenance services with camera deployments. Teledyne FLIR sustains technology leadership in thermal cores through sustained R&D intensity across defense and commercial channels. Kappa optronics GmbH specializes in ruggedized optical modules that withstand extreme altitude pressure differentials and vibration profiles.
Aircraft cameras are electro-optical sensors engineered to capture visible, infrared, or multispectral imagery from airborne platforms, typically operating across spectral bands from near-ultraviolet to long-wave infrared with resolutions exceeding 1080p and frame rates optimized for real-time telemetry. These systems serve flight safety, navigation assistance, surveillance reconnaissance, and aerial documentation purposes in both manned and unmanned aviation environments. Infrared cameras dominate military procurement budgets due to night-vision operational requirements, while thermal imaging cameras capture the fastest growth trajectory driven by expanding UAV surveillance missions. High-definition cameras retain mature positioning in commercial aerial photography where margin pools have compressed amid commoditization of CMOS sensor technology.
FAA airworthiness directives govern camera installation standards on Part 25 aircraft, while EASA CS-25 certification requirements shape product development for European OEM supply chains, and ITAR export controls constrain cross-border transfer of military-grade thermal imaging systems. These regulatory frameworks force manufacturers to maintain parallel certification tracks and restrict market access for non-compliant suppliers. Stakeholders must monitor evolving UAV traffic management integration standards that will determine whether camera systems become mandatory components in detect-and-avoid architectures for autonomous flight corridors.
Market Dynamics
Software-defined imaging architectures are compressing hardware refresh cycles while subscription revenue models restructure supplier-buyer relationships across military and commercial aviation procurement channels.
Growth Catalysts
- UAV Traffic Management Mandates:FAA detect-and-avoid corridor requirements position camera systems as mandatory navigation infrastructure for autonomous flight zones, accelerating fleet retrofit programs.
- ITAR-Controlled Thermal Exports:United States defense procurement restrictions on foreign thermal core transfers concentrate domestic manufacturing incentives and shield domestic suppliers from price-based import competition.
- CMOS Sensor Commoditization:Consumer electronics scale economies in image sensor fabrication drive unit cost reductions that expand addressable market penetration in regional airline and general aviation segments.
Market Restraints
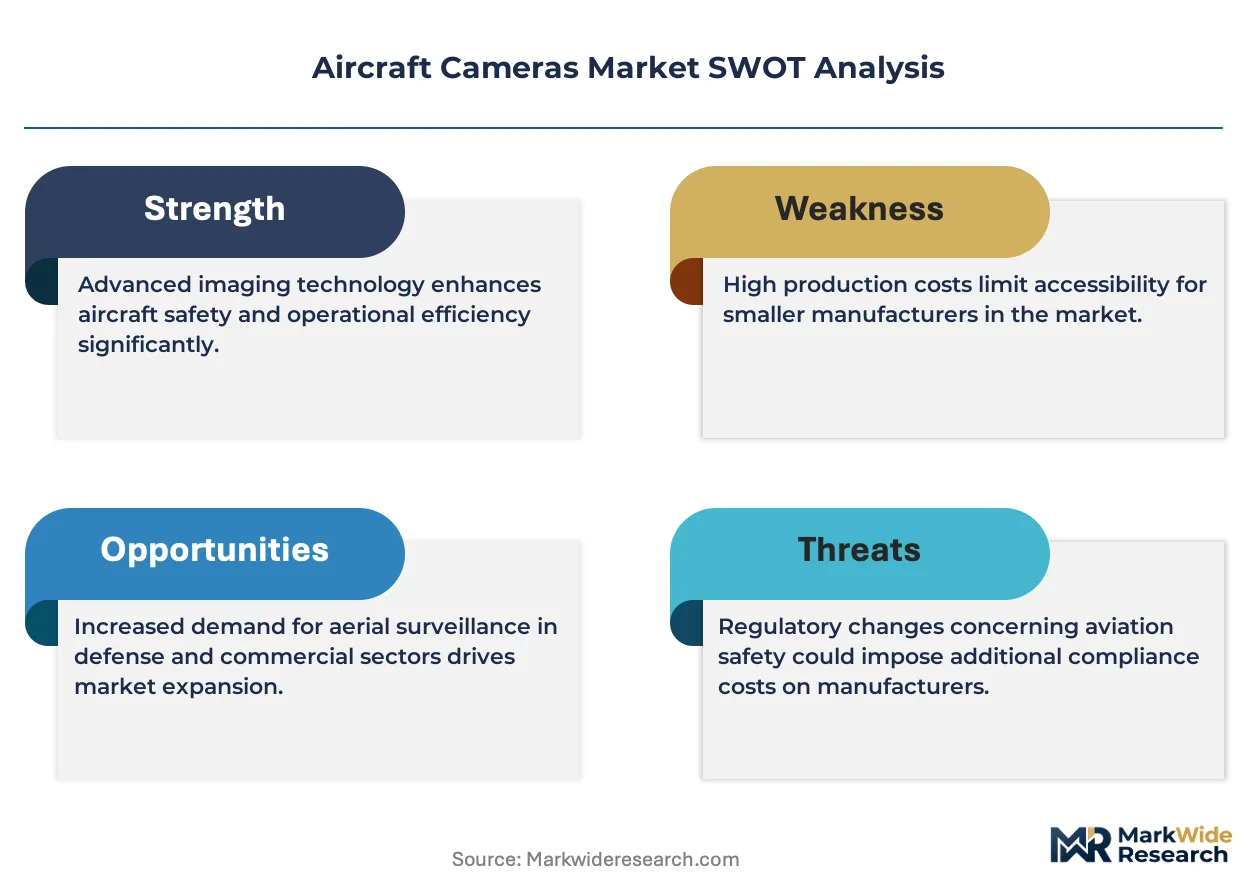
- Germanium Lens Supply Concentration:China controls 67% of global germanium refining capacity for thermal optics, creating input cost volatility and forced substitution to silicon alternatives in mid-wave infrared systems.
- EASA CS-25 Certification Friction:European airworthiness validation timelines for camera modifications extend 18-24 months, compressing product development amortization windows and elevating program risk for non-integrated suppliers.
- Synthetic Aperture Radar Substitution:All-weather radar imaging platforms displace electro-optical systems in maritime surveillance contracts where cloud penetration requirements override resolution preferences.
Strategic Opportunities
- Urban Air Mobility Corridors:Dubai's RTA autonomous aerial taxi infrastructure mandates 360-degree visual sensing suites, creating first-mover installation contracts for camera-integrated detect-and-avoid architectures.
- EU Green Deal Aviation Incentives:CSRD-aligned emissions reporting requirements drive demand for camera-based flight path optimization systems that reduce fuel burn through precision approach guidance.
- Edge AI Convergence:Onboard neural processing units combined with hyperspectral sensors enable real-time material classification for search-and-rescue missions without ground station dependency.
Industry Challenges
- Embedded Software Certification:DO-178C compliance for camera control algorithms demands specialized avionics software engineers, a talent pool concentrated at Collins Aerospace and BAE Systems with limited external availability.
- Legacy Analog Interface Integration:ARINC 818 video protocol adoption conflicts with existing coaxial cable infrastructure in Boeing 737NG and Airbus A320ceo retrofit programs, forcing expensive harness replacements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Cameras Market |
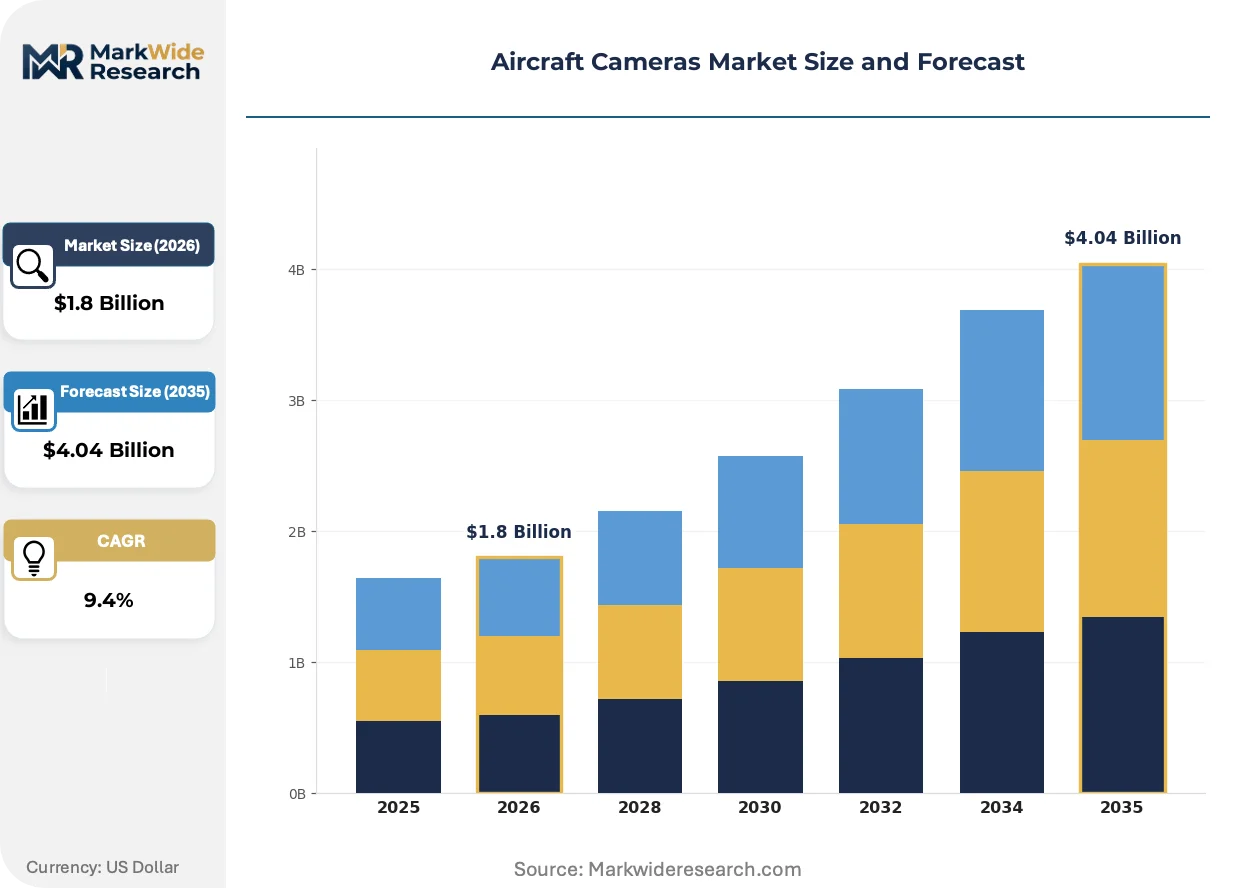
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-Definition Cameras, Infrared Cameras, Thermal Imaging Cameras, Multispectral Cameras Application: Aerial Photography, Surveillance, Agriculture Monitoring, Weather Observation Delivery Mode: On-Premise, Cloud-Based, Integrated Systems, Remote Access End User: Aerospace Companies, Government Agencies, Research Institutions, Private Equity Firms |
| Companies Covered | Collins Aerospace, Teledyne FLIR LLC, Kappa optronics GmbH, AD Aerospace Ltd, L3Harris Technologies, Inc., Elbit Systems Ltd., LATECOERE S.A, Thales Group, Aerial View Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Cameras Market Strategic Shifts
Computational imaging pipelines and edge-native processing architectures are displacing centralized ground-based analysis, redistributing value capture toward sensor-software integrated platforms.
Multispectral sensor fusion is modularizing previously monolithic camera payloads into swappable mission-specific modules. Military UAV operators in United States Special Operations Command now reconfigure spectral bands between flights without airframe modification. This architecture compresses supplier margins on integrated systems while expanding aftermarket attachment revenue for module manufacturers.
EASA's updated CS-25 certification memorandum on electromagnetic interference hardening forces camera manufacturers to redesign shielding architectures for 5G C-band spectrum congestion. Commercial OEM supply chains in Toulouse and Hamburg face 12-18 month requalification delays. Suppliers with pre-certified avionics integration partnerships accelerate market access against standalone component vendors.
Defense procurement offices now unbundle hardware acquisition from predictive maintenance analytics, contracting software subscriptions separately through indefinite-delivery vehicles. This pattern concentrates in United States Navy P-8 Poseidon and MQ-4C Triton programs where Teledyne FLIR and Raytheon compete on algorithmic performance metrics rather than sensor specifications alone. Similar unbundling spreads to European border surveillance agencies under Frontex framework contracts.
Aircraft Cameras Market Segmentation
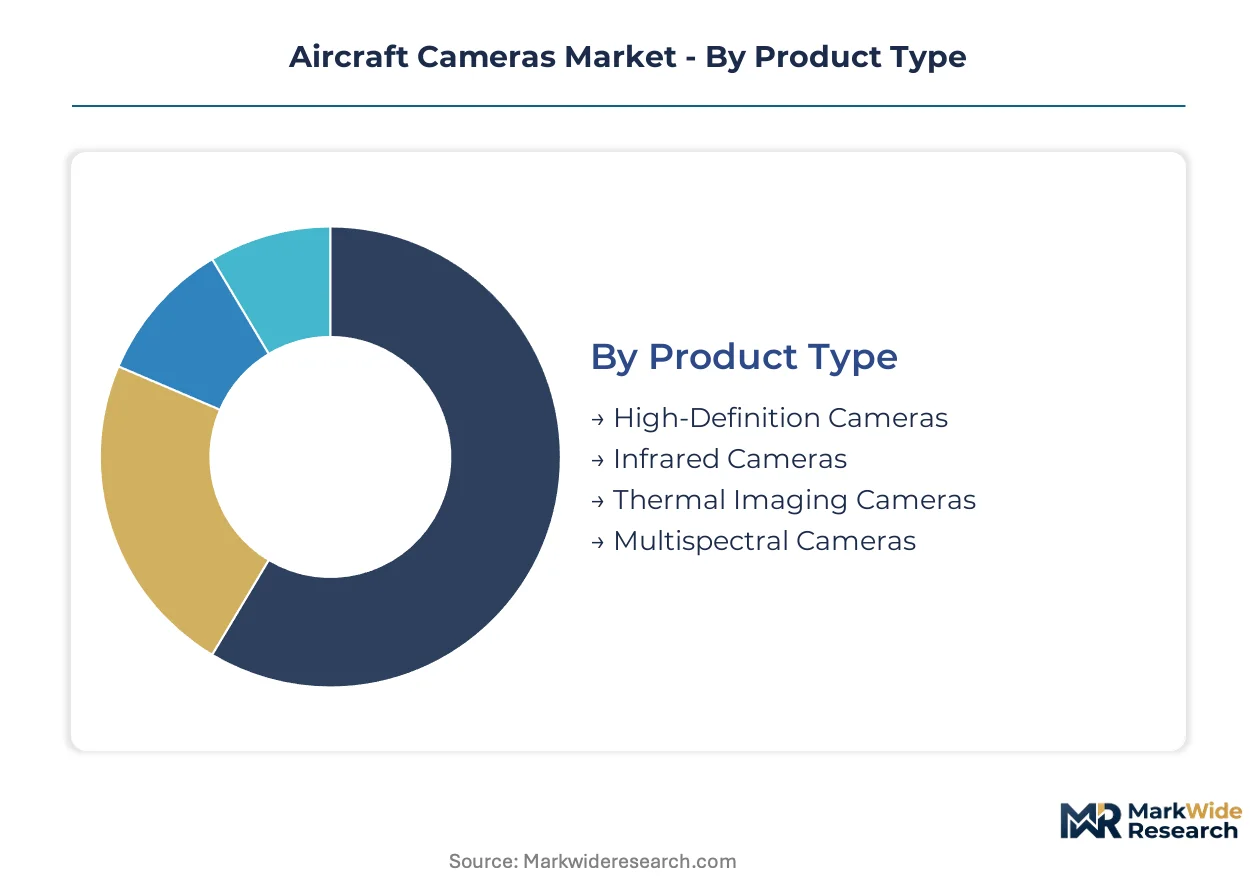
Aircraft camera procurement channels fragment sharply across certification pathways. FAA Part 25, EASA CS-25, and ITAR-controlled defense specifications create incompatible product development tracks that determine supplier eligibility and margin structure.
Product Type:
FAA airworthiness directives and EASA electromagnetic interference standards impose divergent validation burdens across sensor technologies, with thermal cores facing additional ITAR export constraints.
- Infrared Cameras:These systems operate across near-infrared to short-wave infrared spectra, typically employing InGaAs focal plane arrays for night-vision missions. United States Special Operations Command procurement concentrates demand here, driven by unbroken night-vision operational requirements in contested airspace.
- Thermal Imaging Cameras:Long-wave infrared detectors, usually vanadium oxide or amorphous silicon microbolometers, capture heat signatures independent of ambient illumination. German manufacturing clusters in Dresden and Freiburg anchor European supply, though China controls critical germanium refining capacity for objective lenses.
- High-Definition Cameras:CMOS sensors exceeding 1080p resolution dominate commercial aerial photography where EASA CS-25 certification timelines compress supplier margins.
- Multispectral Cameras:Modular architectures combining 4-12 discrete spectral bands enable vegetation index mapping and material classification for precision agriculture.
Thermal imaging cameras sit at the top of the volume ranking, with multispectral cameras climbing the fastest.
Application:
Defense procurement unbundles hardware from analytics subscriptions, while commercial segments demand integrated turnkey systems with predictable total cost of ownership.
- Surveillance:Persistent wide-area motion imagery requires stabilized gimbal mounts and real-time telemetry downlink. United States Navy P-8 Poseidon and MQ-4C Triton programs drive specification standards here, with algorithmic performance metrics displacing raw sensor resolution in contract awards.
- Aerial Photography:High-resolution frame cameras and pushbroom scanners serve commercial mapping and cinematography. Dubai's RTA autonomous aerial taxi infrastructure mandates 360-degree visual sensing suites, expanding addressable market beyond traditional manned aviation.
- Agriculture Monitoring:Normalized difference vegetation index calculations from multispectral payloads guide precision irrigation and fertilizer application.
- Weather Observation:Hyperspectral sensors detect atmospheric water vapor, ice crystal, and aerosol composition for meteorological agencies.
Surveillance commands the largest revenue pool, with agriculture monitoring expanding most quickly as UAV service providers penetrate emerging markets.
Delivery Mode:
Edge-native processing architectures redistribute value capture from ground stations toward onboard neural processing units, compressing latency for time-critical missions.
- Integrated Systems:Camera-avionics fusion through ARINC 818 video protocols demands Collins Aerospace and BAE Systems integration partnerships. DO-178C software certification requirements restrict supplier base to established avionics houses with specialized engineering talent pools.
- Cloud-Based:Software-defined imaging subscription packages enable predictive maintenance analytics and fleet-wide algorithm updates without hardware modification. United States Navy indefinite-delivery vehicles now contract these services separately from sensor procurement.
- On-Premise:Classified military installations and sovereign data requirements mandate air-gapped processing architectures with no external connectivity.
- Remote Access:Satellite relay and beyond-line-of-sight datalinks extend command reach for unmanned platforms operating in denied environments.
Integrated systems retain dominant share, with cloud-based delivery gaining share fastest as defense procurement offices unbundle hardware from software subscriptions.
End User:
Procurement authority fragmentation across civilian and defense channels creates parallel sales organizations with incompatible contract vehicles and security clearance requirements.
- Government Agencies:United States Department of Defense, Frontex, and national border control authorities specify ITAR-controlled thermal cores with multi-year framework contracts. Funding cycles and congressional appropriations timelines introduce demand volatility absent in commercial channels.
- Aerospace Companies:Boeing, Airbus, and tier-one suppliers integrate cameras as original equipment on Part 25 aircraft, with EASA CS-25 and FAA certification requirements governing supplier qualification.
- Research Institutions:NASA, ESA, and university laboratories drive experimental hyperspectral and quantum imaging applications with small-batch procurement and extended qualification tolerance.
- Private Equity Firms:Urban air mobility ventures and drone service operators represent speculative demand with high customer acquisition costs and unproven unit economics.
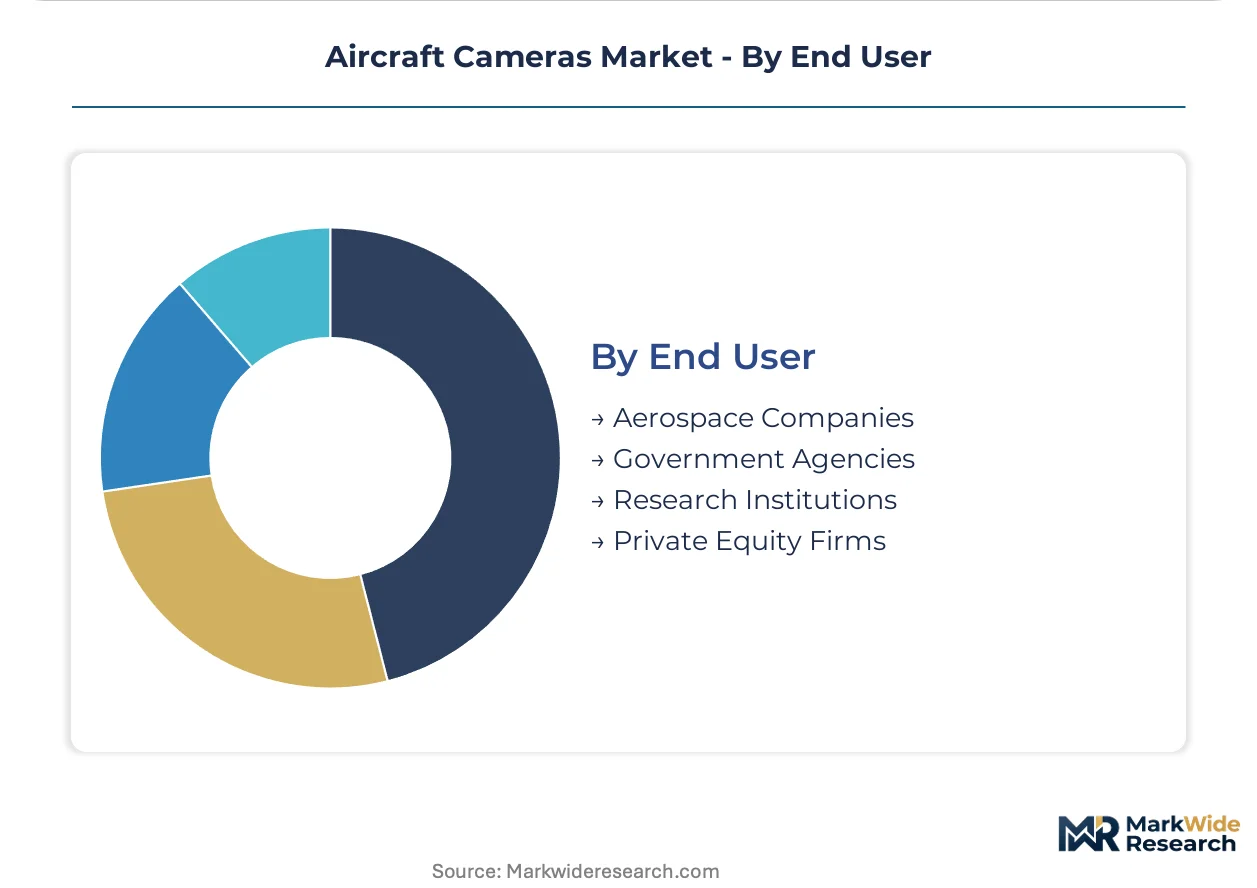
Government agencies anchor volume demand, with aerospace companies showing steepest expansion trajectory as commercial OEM production rates recover.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States military procurement outpaces German commercial aerospace investment, while China's sensor manufacturing scale disrupts traditional supply hierarchies across thermal imaging supply chains.
United States
Special Operations Command night-vision requirements and Navy P-8 Poseidon fleet expansions drive infrared camera procurement. FAA detect-and-avoid corridor mandates for autonomous flight zones accelerate retrofit programs. Tucson and Melbourne aerospace clusters host Teledyne FLIR and L3Harris integration facilities serving defense primes.
Germany
EASA CS-25 certification expertise and precision optics manufacturing anchor European demand. EU Green Deal aviation incentives push camera-based flight path optimization for fuel reduction. Dresden and Freiburg manufacturing clusters specialize in vanadium oxide microbolometer production for thermal cores.
France
Thales Group defense electronics integration and Airbus supply chain proximity concentrate surveillance camera demand. EASA electromagnetic interference hardening requirements force 5G C-band shielding redesigns. Toulouse OEM supply chains face 12-18 month requalification delays for modified camera architectures.
China
UAV export manufacturing scale and domestic thermal imaging consumption expand addressable volumes. The country's national aviation regulator tightens airworthiness standards for civil drone camera installations. Shenzhen and Chengdu electronics clusters dominate CMOS sensor packaging and downstream module assembly.
United Arab Emirates
Dubai RTA autonomous aerial taxi infrastructure mandates 360-degree visual sensing suites for urban air mobility corridors. MOHAP aviation safety oversight extends to camera certification for commercial drone operators. Dubai South aerospace district attracts camera-integrated detect-and-avoid system installers seeking first-mover contracts.
Aircraft Cameras Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with defense procurement favoring integrated avionics houses while commercial aerial photography tolerates component sourcing. The vendor base concentrates around three strategic archetypes: avionics-integrated platform providers, thermal core technology specialists, and ruggedized optical module fabricators. M&A activity targets software-defined imaging capabilities, while capacity expansion concentrates in German precision optics clusters and US defense corridor manufacturing zones.
Among US-based defense-integrated suppliers, Collins Aerospace and L3Harris Technologies, Inc. exemplify the avionics-platform archetype through FAA Part 25 certification depth and predictive maintenance bundling. Kappa optronics GmbH represents the ruggedized-optical-module specialization, occupying a position within German manufacturing clusters that serve extreme-altitude pressure differential requirements. These three anchors demonstrate how certification barriers and supply chain geography determine competitive positioning across incompatible procurement channels.
| Leading Market Players |
|---|
| Collins Aerospace |
| Teledyne FLIR LLC |
| Kappa optronics GmbH |
| AD Aerospace Ltd |
| L3Harris Technologies, Inc. |
| Elbit Systems Ltd. |
| LATECOERE S.A |
| Thales Group |
| Aerial View Systems |
| Others |
Value Chain & Pricing Dynamics
EU Green Deal aviation incentives gate qualified supply for camera-based flight path optimization systems, restricting premium-tier pricing access to manufacturers with EASA CS-25 certification and CSRD-aligned emissions reporting capabilities. Buyers without certified suppliers face 18-24 month requalification delays that compress margin pools and force reliance on undifferentiated commodity CMOS sensors.
Pricing Analysis
Capacity additions in China's CMOS sensor packaging clusters are reshaping price floors for commercial aerial photography tiers, while ITAR-controlled thermal cores retain pricing power through restricted supply. Three-tier pricing structure across military-grade ITAR systems, certified commercial avionics, and commodity UAV modules separates buyers by certification burden and after-sales analytics bundling. Cost compression in high-definition commercial segments intensifies because consumer electronics scale economies flood the market with 1080p+ sensors. Regional airlines and general aviation operators exhibit highest price sensitivity, whereas United States Special Operations Command procurement accepts premium pricing for night-vision operational requirements.
Supply Chain Analysis
Germanium lens supply rests on Chinese specialty metal refiners controlling two-thirds of global processing capacity for thermal optics objective lenses. Raw material dependencies span germanium for long-wave infrared systems, InGaAs focal plane arrays for short-wave infrared, and vanadium oxide microbolometers anchored in Dresden and Freiburg manufacturing clusters. Single-source vulnerability in germanium refining forces mid-wave infrared substitution to silicon alternatives and elevates input cost volatility. Distribution runs through defense prime integration partnerships for military procurement, direct OEM supply contracts for Part 25 aircraft, and modular component channels for UAV service operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aircraft camera procurement arbitrages regulatory cost differentials between EASA CS-25 certification timelines in Europe and FAA Part 25 validation pathways in the United States, with German precision optics clusters offering intermediate positioning for dual-certified suppliers.
For Market Incumbents: Hedge against synthetic aperture radar substitution in maritime surveillance by deepening software-defined imaging subscription revenue and securing predictive maintenance contracts through indefinite-delivery vehicles. Backward integration into vanadium oxide microbolometer production shields margin position from germanium lens supply volatility, while DO-178C certification investment restricts non-integrated competitors from avionics-platform bundling. For New Entrants and Emerging Players: Tier-two UAV service operators in urban air mobility corridors represent the most penetrable channel partner type, with Dubai RTA infrastructure mandates creating first-mover installation contracts for 360-degree visual sensing suites. Agriculture monitoring applications in emerging markets offer white-space expansion with normalized difference vegetation index calculations, accessible through hyperspectral module manufacturing without full airframe integration. For Investors and Strategic Acquirers: Roll-up economics work for ruggedized optical module specialists because EASA electromagnetic interference hardening requirements and 5G C-band shielding redesigns fragment supplier bases into sub-scale certification holders. Long-term viability centers on software-defined imaging capabilities with recurring revenue attachment, with acquisition target archetypes spanning edge AI convergence plays and predictive maintenance algorithm developers. Watch FAA detect-and-avoid corridor mandate implementation timelines as the inflection indicator for autonomous flight infrastructure deployment.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Imaging Subscription Launch | Recurring revenue bundling with Collins Aerospace predictive maintenance services reshapes supplier-buyer contracts. |
| EASA CS-25 Dual Certification Investment | Parallel FAA and European validation tracks unlock Boeing and Airbus supply chain access against standalone vendors. |
| Germanium Alternative Lens Development | Silicon-based mid-wave infrared systems reduce dependency on Chinese refining capacity for thermal optics. |
| Edge AI Neural Processing Integration | Onboard material classification for search-and-rescue eliminates ground station latency and dependency. |
| Urban Air Mobility Corridor Partnership | Dubai RTA infrastructure mandates create captive demand for detect-and-avoid camera architectures. |
Study Parameters
Multiple input streams — primary interviews with avionics integration engineers, defense procurement officers, and UAV fleet operators, plus secondary validation through FAA airworthiness directives, EASA certification memoranda, and ITAR export control filings — were reconciled through bottom-up and top-down triangulation. Primary fieldwork captured specification requirements from United States Navy P-8 Poseidon program managers, Frontex border surveillance technical leads, and commercial OEM procurement teams at Toulouse and Hamburg. Secondary sources encompassed SEC 10-K filings from defense primes, customs data on germanium and InGaAs focal plane array trade flows, and electromagnetic interference testing documentation from 5G C-band shielding redesigns.
Data-stream reconciliation anchored volume and value outputs across product type, application, delivery mode, and end user dimensions, with additional segmentation by certification pathway and regional regulatory cluster. CAGRs were derived from installation base expansion modeling, fleet retrofit program timelines, and autonomous flight infrastructure deployment schedules. Industry-specific forecast inputs incorporated UAV traffic management mandate implementation progress and ITAR-controlled thermal core procurement restrictions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to germanium supply disruption, EASA requalification timeline extensions, and synthetic aperture radar technology advancement. Forecasts reflect documented assumptions on certification pathway convergence and defense procurement unbundling patterns. A small set of named triggers — FAA detect-and-avoid mandate acceleration, Chinese export restriction escalation, and edge AI processing cost curves — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Global B2B Enterprise and Industrial Wearables Market
Others
North America Flexographic Printing Market
Others
Finished Leather Market
Others
China Packaging Primers Market
Others
Asia-Pacific Telecom Transformers Market
Others
Drum Motor Market
Others
Middle East and Africa Medium Voltage Switchgear Market
Others
Aerospace Software Testing Market
Others
GCC Shisha Tobacco Market
Others
Global Phablets and Superphones Market
Others
Metal Ore Mining Market
Others
High-Performance Films Market
Others
Global Mobile Gambling Market
Others
Signal Transformer Market
Others
Turkey Health and Medical Insurance Market
Others
Global Electronic Filters Market