
 United States Air Furnaces Market | 2026-2036
United States Air Furnaces Market Size, Share, and Industry Trends Forecast 2026-2036
United States Air Furnaces Market Analytics
Domestic foundry capacity for heat exchanger castings is decoupling from assembly plant locations across the Ohio River Valley. Carrier Global Corporation leverages captive steel-forming operations to stabilize input costs. Lennox International Inc. anchors its premium position through proprietary variable-speed blower architectures. Trane Technologies plc competes on commercial-scale modular furnace systems for multi-site property managers.
United States air furnaces are forced-air heating appliances that combust natural gas, liquid propane, fuel oil, or electrical resistance elements to generate thermal energy distributed through ductwork, with residential units typically rated between 40,000 and 120,000 BTU per hour and achieving Annual Fuel Utilization Efficiency ratings of 80% to 98.5%. Gas-fired units dominate the installed base due to existing pipeline infrastructure and lower operating costs per therm, while electric segments accelerate in jurisdictions with aggressive building electrification codes. Smart control systems capture expanding margin pools as utilities deploy demand-response programs requiring two-way communication between grid operators and household thermal equipment.
DOE furnace efficiency standards, EPA Clean Air Act emissions limits, and regional utility rebate programs administered by state public utility commissions collectively determine product certification requirements and market access conditions. NHTSA does not regulate this equipment class, though OSHA workplace ventilation standards influence commercial and industrial specification practices. Stakeholders must monitor state-level building code adoptions and utility decarbonization timelines to anticipate shifts in allowable fuel types and control system interoperability mandates.
Market Dynamics
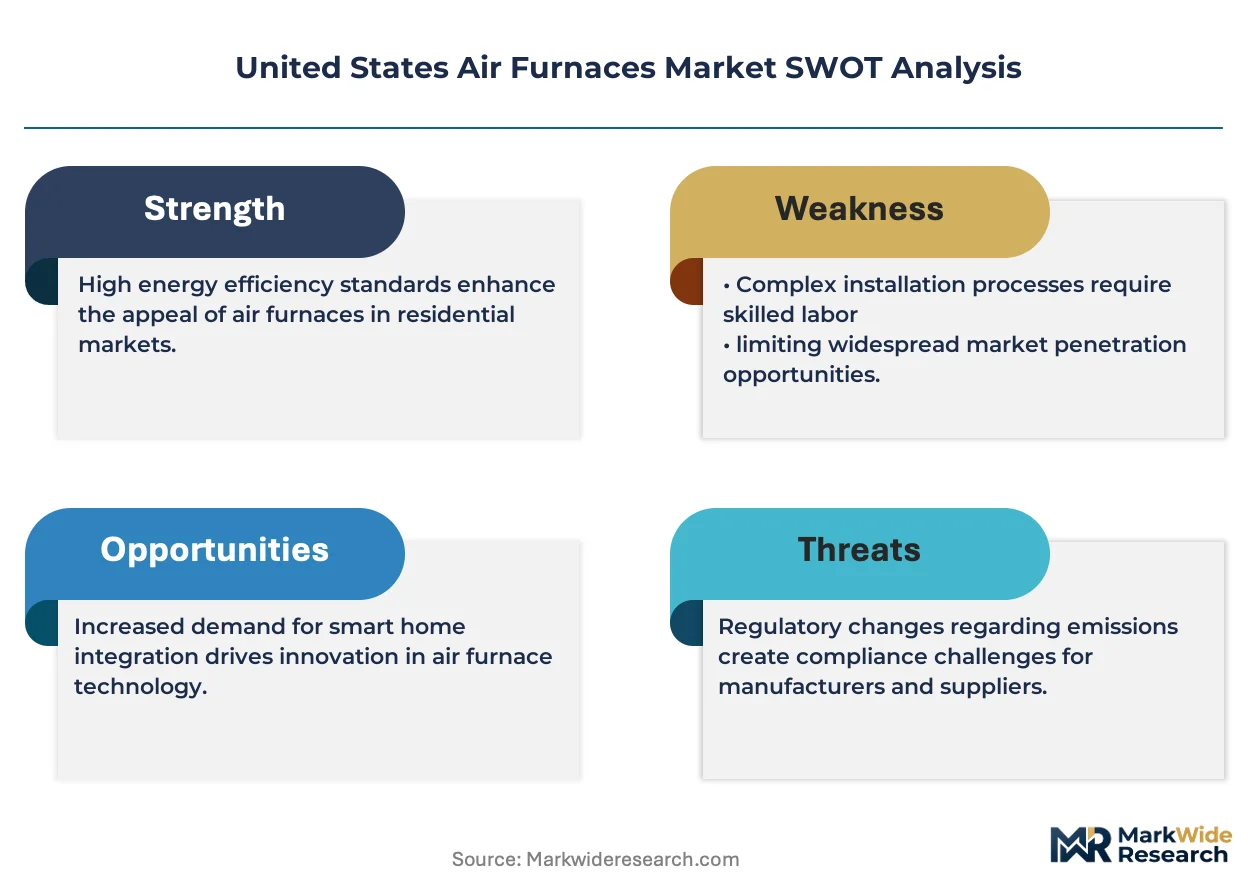
DOE furnace efficiency standards and EPA Clean Air Act emissions limits are compressing product development cycles while accelerating capital redeployment toward condensing combustion architectures and smart control integration.
Growth Catalysts
- Building Electrification Codes:California and Washington state mandates for heat pump readiness are preserving gas furnace retrofit demand in jurisdictions where full electrification faces infrastructure constraints.
- Texas Residential Construction:Permitting velocity in Houston and Dallas-Fort Worth metro corridors is compressing replacement cycles for mid-efficiency equipment in new single-family subdivisions.
- Utility Demand-Response Programs:FERC Order 2222 compliance timelines are compelling two-way communication capabilities in residential control systems across ISO-NE and PJM territories.
Market Restraints
- Heat Exchanger Steel Volatility:Cold-rolled coil pricing swings tied to Nucor and Cleveland-Cliffs production adjustments are compressing margin stability for assembly plants.
- Ohio River Valley Foundry Concentration:Ductile iron casting capacity clustering around Pittsburgh and Cincinnati creates single-source vulnerability for heat exchanger components.
- Heat Pump Substitution:Cold-climate heat pump performance improvements in Minnesota and Wisconsin are eroding gas furnace share in northern tier states.
Strategic Opportunities
- IRA Tax Credits:Section 25C efficiency incentives are expanding addressable market for 95%+ AFUE condensing units in Midwest replacement channels.
- Commercial Modular Systems:Multi-site property managers in Florida and Arizona are standardizing on scalable furnace architectures for portfolio-wide energy management.
- Propane Rural Segments:Appalachian and Ozark regions lacking natural gas pipeline access represent underpenetrated terrain for high-efficiency LP conversion kits.
Industry Challenges
- EPA Certification Timelines:New source performance standard testing protocols are extending product launch windows by 8-14 months for modified burner designs.
- Control System Integration:Legacy thermostat wiring incompatibility with Wi-Fi enabled demand-response modules is forcing costly electrical upgrades in pre-2010 housing stock.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Air Furnaces Market |
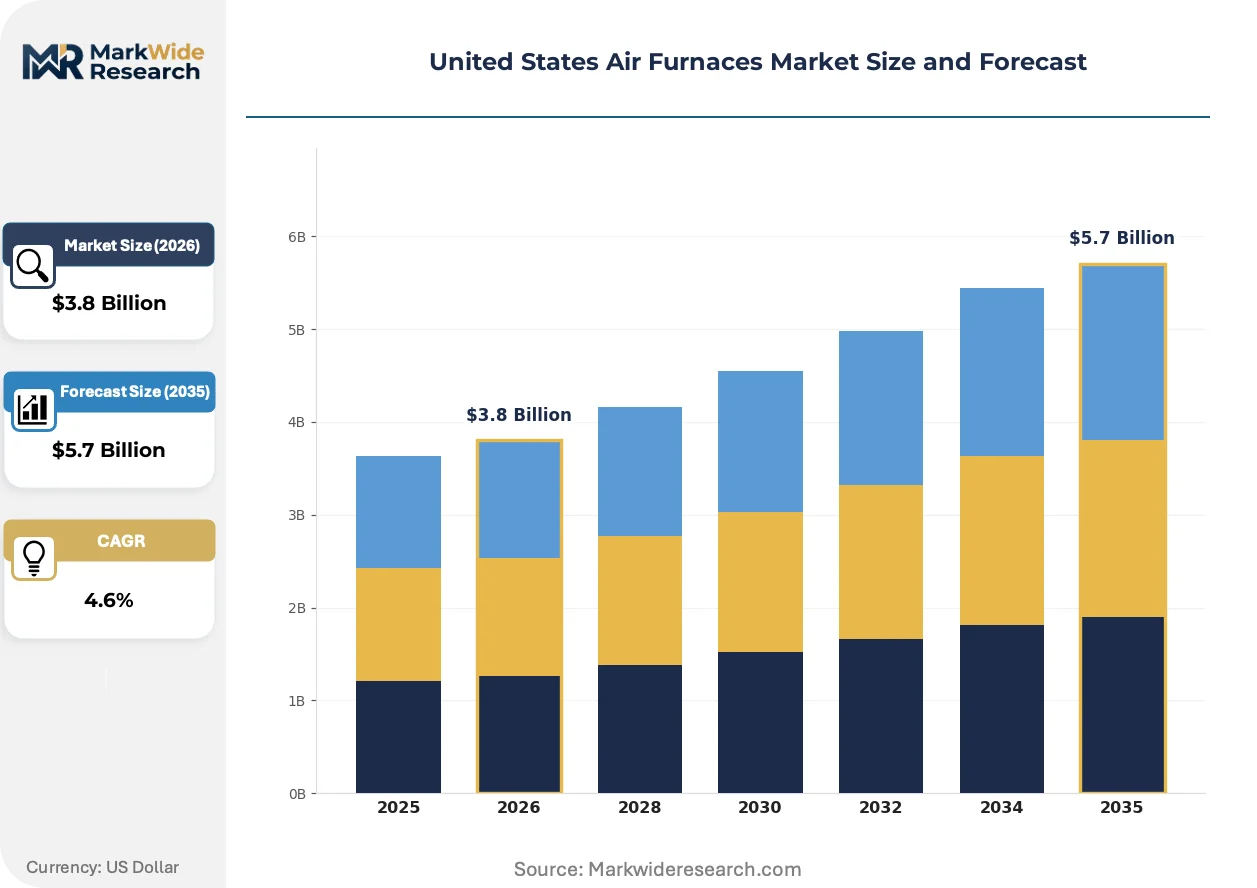
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gas Fired, Electric, Oil Fired, Dual Fuel End User: Residential, Commercial, Industrial, Government Installation Type: Indoor, Outdoor, Wall Mounted, Standalone Control System: Manual, Programmable, Smart, Remote |
| Companies Covered | Carrier Global Corporation, Lennox International Inc., Trane Technologies plc, Daikin Industries, Ltd., Rheem Manufacturing Company, Johnson Controls, Inc., Goodman Manufacturing, Nortek Global HVAC, American Standard Heating & Air Conditioning, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Air Furnaces Market Evolving Landscape
Condensing combustion technology and modulating burner control are compressing the efficiency gap between entry-level and premium furnace tiers while redistributing margin pools toward sensor and software components.
Modulating gas valves paired with variable-speed ECM blower motors are overtaking single-stage fixed-speed architectures in mid-market residential segments. HVAC contractors in Colorado and Utah are specifying these systems for high-altitude installations where combustion efficiency degradation is acute. The technology is overtaking conventional fixed-output designs by enabling 40:1 turndown ratios that match thermal output to real-time load conditions.
EPA New Source Performance Standards for residential furnaces are mandating nitrogen oxides emissions below 40 nanograms per joule of heat output. Manufacturers are responding with staged combustion air injection and flame retention head redesigns. The standards are compressing product development timelines most severely for oil-fired equipment in Northeastern states where residual fuel sulfur content complicates burner tuning.
Homebuyers in Texas and Florida are prioritizing smart thermostat compatibility and utility rebate eligibility over raw equipment efficiency ratings. Builders are responding by pre-wiring homes for demand-response participation and specifying furnaces with embedded communication modules. The shift is visible most acutely in master-planned communities where utility partnerships bundle installation incentives with multi-year service agreements.
United States Air Furnaces Market Segmentation
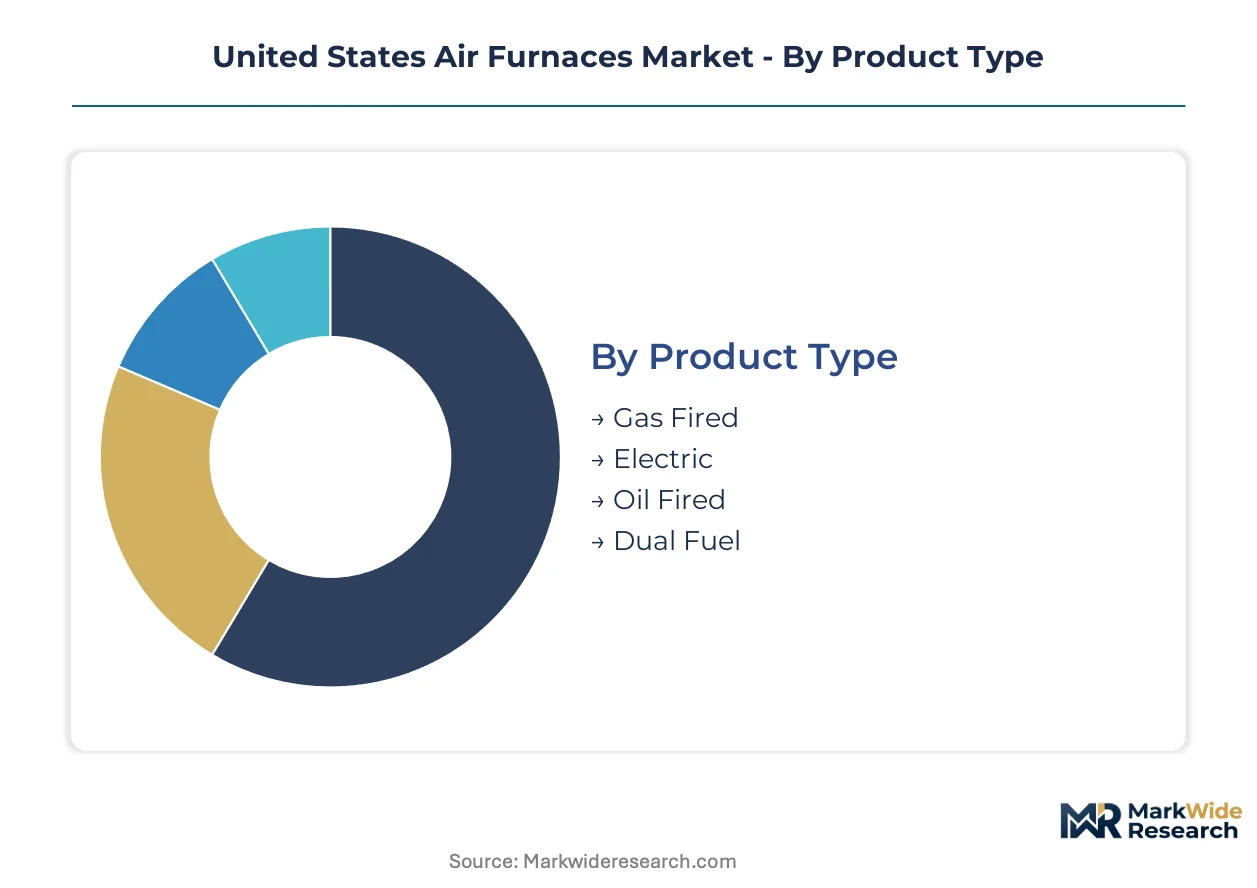
Equipment replacement cycles in Texas and Florida subdivisions create distinct demand profiles across fuel types and control architectures. Segmentation reveals how DOE efficiency mandates and utility rebate structures concentrate volume in specific product configurations while penalizing legacy technologies.
Product Type:
Upgrade decisions pivot on existing fuel infrastructure availability and regional electrification timelines, with replacement urgency highest where pipeline networks are entrenched.
- Gas Fired:Natural gas combustion systems dominate the installed base through existing distribution infrastructure and lower operating costs per therm. Demand concentrates in Southeast and Southwest states where heat pump conversions lag and pipeline networks remain dense, with Texas residential construction driving mid-efficiency unit turnover.
- Electric:Resistance heating elements and electric heat pump hybrids accelerate in jurisdictions with aggressive building electrification codes. California and Washington state mandates preserve retrofit demand where full electrification faces infrastructure constraints, though cold-climate performance limitations constrain northern tier penetration.
- Oil Fired:Residual fuel systems persist in Northeastern rural markets lacking natural gas pipeline access.
- Dual Fuel:Hybrid configurations combining gas combustion with electric heat pump backup address load-balancing requirements in variable climates.
Volume placements concentrate in Gas Fired; the faster expansion belongs to Electric.
End User:
Cost tier differentiation separates specification practices across customer types, with capital availability and payback horizons driving technology selection.
- Residential:Single-family and multi-family dwellings account for the majority of unit placements, with replacement cycles compressed by Texas and Florida permitting velocity. Homebuyers prioritize smart thermostat compatibility and utility rebate eligibility over raw efficiency ratings, shifting builder specifications toward demand-response-ready configurations.
- Commercial:Multi-site property managers in Florida and Arizona standardize on scalable furnace architectures for portfolio-wide energy management. Modular systems enable centralized monitoring across distributed retail and hospitality locations, with FERC Order 2222 compliance driving two-way communication requirements.
- Industrial:Manufacturing facilities and warehouses specify high-capacity units with extended duty cycles.
- Government:Federal and municipal buildings face procurement mandates favoring domestic assembly and efficiency certification thresholds.
Residential captures the dominant share of unit volume; Commercial shows the steepest expansion trajectory as property managers consolidate supplier relationships.
Installation Type:
Application constraints dictate physical configuration, with space limitations and climate exposure determining indoor versus outdoor placement.
- Indoor:Basement and utility closet placements dominate in northern climates where freeze protection is essential. Pre-2010 housing stock forces costly electrical upgrades for smart control compatibility, compressing retrofit economics in legacy subdivisions.
- Outdoor:Packaged units serve commercial applications and residential markets with limited interior mechanical space. Florida and Arizona installations prioritize weather-resistant enclosures for extended equipment life in high-humidity environments.
- Wall Mounted:Compact configurations address space-constrained multi-family construction in urban corridors.
- Standalone:Modular external units serve industrial and agricultural buildings with minimal existing ductwork.
Indoor placements retain the volume concentration; Outdoor configurations are climbing the fastest as commercial construction favors packaged systems.
Control System:
Margin pools redistribute toward sensor and software components as utilities deploy demand-response programs requiring grid-interactive thermal equipment.
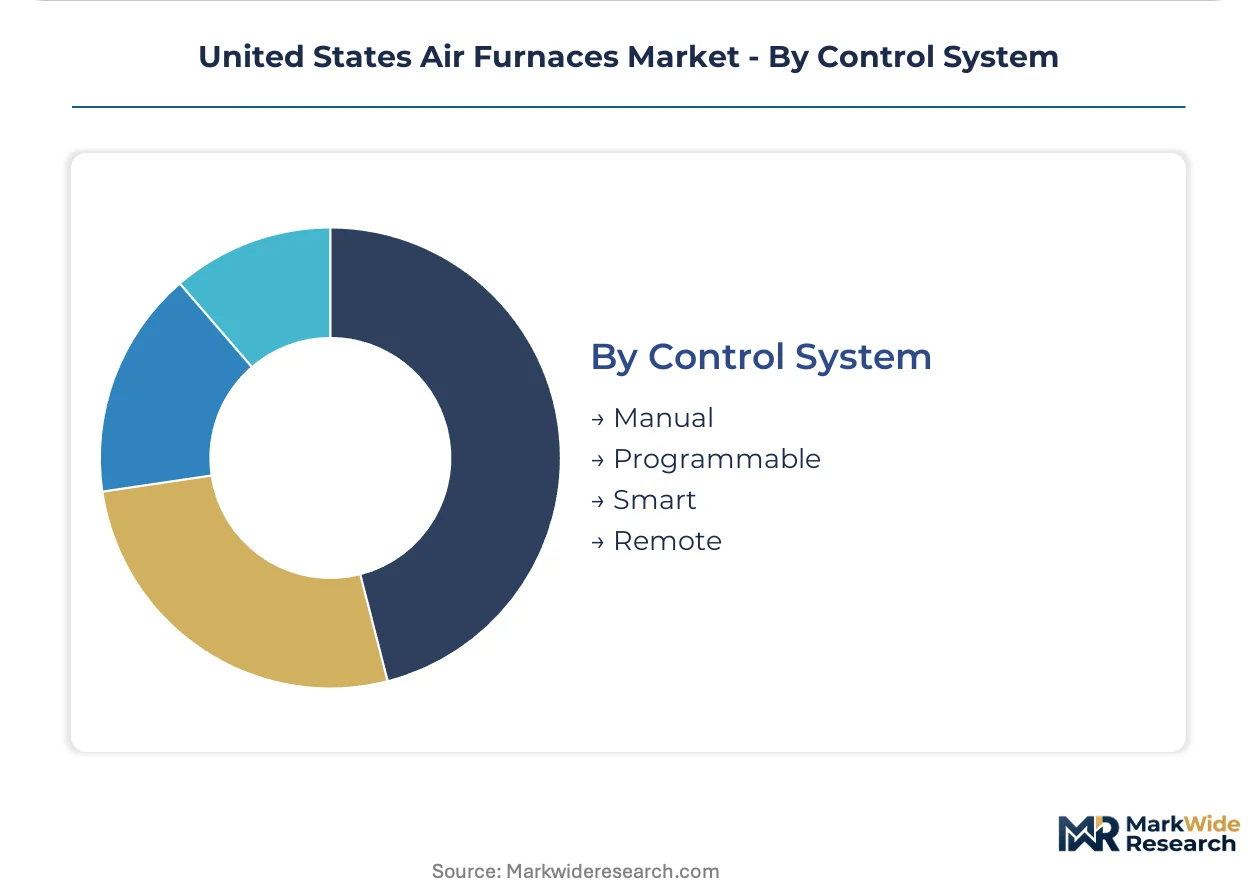
- Smart:Wi-Fi enabled modules with two-way communication capabilities are overtaking conventional architectures in new construction. ISO-NE and PJM territories mandate FERC Order 2222 compliance timelines, compelling embedded communication modules for residential participation in grid stabilization programs.
- Programmable:Schedule-based temperature setbacks retain share in cost-sensitive replacement channels where electrical infrastructure upgrades are prohibitive.
- Manual:Basic electromechanical thermostats persist in rental housing and rural markets with limited broadband penetration.
- Remote:Cloud-connected systems enabling off-site monitoring serve commercial property managers with distributed portfolios.
Smart controls command the premium tier volume; Remote capabilities are gaining share fastest among multi-site operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Steel-forming operations and ductile iron foundries cluster along the Ohio River Valley, anchoring component supply for assembly plants distributed across the Southeast and Southwest where replacement demand concentrates.
Southeast
Florida master-planned communities and Georgia suburban corridors drive equipment turnover in new residential construction. EPA emissions limits and state utility commission rebate programs shape product specifications toward demand-response-ready configurations. Atlanta serves as a distribution hub linking Ohio River Valley foundry output to Florida installation contractors.
Southwest
Texas permitting velocity in Houston and Dallas-Fort Worth compresses replacement cycles for mid-efficiency gas-fired units. DOE furnace standards and IRA Section 25C tax credits influence builder specifications toward 95%+ AFUE condensing architectures. San Antonio mechanical contractors report rising specification rates for smart control compatibility in new subdivisions.
Midwest
Ohio, Indiana, and Illinois replacement channels respond to cold-climate performance demands and aging housing stock electrical infrastructure constraints. FERC Order 2222 compliance timelines across PJM territories mandate two-way communication capabilities in residential control systems. Pittsburgh and Cincinnati foundry clusters supply heat exchanger castings to regional assembly plants.
Pacific Northwest
Washington state building electrification codes preserve gas furnace retrofit demand where full electrification faces infrastructure constraints. State public utility commissions administer rebate programs favoring high-efficiency condensing units over resistance heating. Seattle-area HVAC contractors report specification shifts toward heat pump hybrid configurations.
Mountain West
Colorado and Utah high-altitude installations drive demand for modulating burner control systems addressing combustion efficiency degradation. Rocky Mountain regions lacking natural gas pipeline access sustain propane conversion kit demand. Denver mechanical engineers specify variable-speed ECM blower motors for altitude-compensated thermal output.
United States Air Furnaces Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue smart control integration and modular commercial architectures. The vendor base organizes around three archetypes: integrated manufacturers with captive component operations, assembly specialists sourcing from regional foundries, and technology licensors focusing on control system software. Competitive moves concentrate on strategic partnerships for demand-response program compliance and portfolio diversification into heat pump hybrids.
Within the integrated-manufacturer tier, Carrier Global Corporation and Lennox International Inc. exemplify archetypes combining captive steel-forming with proprietary blower architectures. Trane Technologies plc occupies a position emphasizing commercial-scale modular systems. These three entities anchor competitive positioning around distinct vectors: input cost stabilization, premium variable-speed technology, and multi-site property manager relationships respectively.
| Leading Market Players |
|---|
| Carrier Global Corporation |
| Lennox International Inc. |
| Trane Technologies plc |
| Daikin Industries, Ltd. |
| Rheem Manufacturing Company |
| Johnson Controls, Inc. |
| Goodman Manufacturing |
| Nortek Global HVAC |
| American Standard Heating & Air Conditioning |
| Others |
Value Network & Pricing Analysis
EPA New Source Performance Standards for nitrogen oxides emissions below 40 nanograms per joule gate both qualified supply and premium-tier pricing access, compressing product development timelines for modified burner designs while elevating certification costs for manufacturers seeking 95%+ AFUE condensing unit positioning. DOE furnace efficiency standards and IRA Section 25C tax credit eligibility further stratify the market, with compliant architectures commanding material premiums over legacy mid-efficiency configurations in replacement channels.
Pricing Analysis
Warranty and extended service bundling separate premium manufacturer offerings from unbundled contractor-sourced installations, with Carrier and Lennox leveraging captive service networks to justify tiered pricing structures across premium, standard, and economy levels. Price differentiation rests on AFUE certification thresholds and smart control compatibility rather than raw thermal output, with utility rebate eligibility in Texas and Florida compressing buyer price sensitivity among new construction segments while cost-sensitive replacement channels in Midwest legacy housing stock prioritize programmable over Wi-Fi-enabled architectures. Pricing pressure stems from cold-rolled coil volatility tied to Nucor and Cleveland-Cliffs production adjustments, squeezing margin stability for assembly-dependent specialists.
Supply Chain Analysis
Warehouse distribution through Atlanta and Dallas-Fort Worth regional centers feeds installation contractors across Southeast and Southwest corridors, with hub-and-spoke patterns optimizing last-mile delivery for Texas permitting velocity. Geographic supply concentration centers on Ohio River Valley foundry clusters around Pittsburgh and Cincinnati for ductile iron heat exchanger castings, while captive steel-forming operations at integrated manufacturers anchor input cost stabilization. Raw material dependencies span cold-rolled coil, ductile iron feedstock, and ECM blower motor electronics, with single-source vulnerability in foundry capacity creating structural risk for assembly plants lacking backward integration into component production. Distribution runs through mechanical contractor networks and HVAC wholesaler channels serving residential and commercial end-users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Foundry capacity concentration in the Ohio River Valley props pricing for heat exchanger components, constraining supply elasticity and elevating procurement leverage for vertically integrated incumbents over assembly-dependent competitors.
For Market Incumbents: Lock in captive foundry relationships or steel-forming operations to defend margin position against cold-rolled coil volatility and single-source casting vulnerability. Prioritize certification investment for EPA New Source Performance Standards compliance to compress competitor product launch windows, while channel control through preferred contractor networks in Texas and Florida master-planned communities limits emerging entrant access to high-velocity new construction segments. For New Entrants and Emerging Players: Direct-to-contractor digital platforms offering demand-response-ready control system retrofit kits represent the most penetrable route into Midwest replacement channels constrained by legacy thermostat wiring incompatibility. Target propane rural segments in Appalachian and Ozark regions lacking natural gas pipeline access, where high-efficiency LP conversion kits face limited incumbent focus and utility electrification timelines preserve gas equipment demand. For Investors and Strategic Acquirers: FERC Order 2222 compliance timeline acceleration across ISO-NE and PJM territories is the leading indicator that smart control integration capabilities will separate acquisition-worthy targets from stranded asset risks. Over the projection horizon, prioritize vertically integrated mid-cap specialists with captive steel-forming or foundry relationships and embedded communication module IP, watching for state-level building code adoption shifts toward heat pump readiness as signals of gas furnace retrofit demand preservation or erosion.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Foundry Acquisition | Secures heat exchanger casting supply against Ohio River Valley concentration risk. |
| Smart Control Module Development | Enables FERC Order 2222 compliance for ISO-NE and PJM utility program participation. |
| Propane Conversion Kit Expansion | Addresses underpenetrated Appalachian and Ozark rural markets lacking pipeline access. |
| Demand-Response Platform Partnership | Bundles installation incentives with multi-year service agreements in Texas master-planned communities. |
| Condensing Architecture Scale-Up | Captures IRA Section 25C tax credit eligibility for 95%+ AFUE Midwest replacement channels. |
Research Methodology
Document review covered DOE furnace efficiency standard filings, EPA Clean Air Act emissions rulemakings, and FERC Order 2222 implementation timelines, complemented by interviews with HVAC mechanical contractors, public utility commission rebate program administrators, residential builder procurement directors, and foundry operations managers. Secondary validation drew from EIA residential energy consumption surveys, state-level building code adoption databases, and SEC 10-K disclosures from integrated manufacturers. Bottom-up unit placement estimates triangulated against top-down construction permitting velocity data across Texas and Florida metro corridors.
Segmentation outputs across fuel type, end user, installation configuration, and control system architecture informed volume and value projections over the modeling period. Analytical framework incorporated replacement cycle dynamics tied to housing stock vintage, utility decarbonization timeline assumptions, and cold-climate heat pump performance improvement trajectories. CAGRs derived from historical equipment shipment patterns cross-referenced with regional construction forecast inputs and efficiency mandate compliance cost curves.
The model holds under steady EPA and DOE regulatory enforcement and stable natural gas infrastructure investment; deviation in federal efficiency standard rollback or accelerated heat pump subsidy expansion would shift replacement channel demand composition. Forecasts reflect documented assumptions regarding foundry capacity utilization and steel input cost trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Managed Testing Services Market
Others
Delumper Market
Others
Animal Feed Alternative Protein Market
Others
AI in Precision Medicine Market
Others
Green Technologies Market
Others
Global Cosmetovigilance Market
Others
Bio-Based Leather Market
Others
Security Bottles Market
Others
Nuclear Power Cables Market
Others
High-Performance Films Market
Others
Turkey Health and Medical Insurance Market
Others
Durian Fruit Market
Others
Global Virtual Keyboard Market
Others
Fiber to the X (Fttx) Tester Market
Others
ASEAN Smart Homes Market
Others
Liquid-Cooled Heat Sink Market