
 Aluminium Clad Printed Circuit Board Market | 2026-2036
Aluminium Clad Printed Circuit Board Market Size, Share, and Industry Trends Forecast 2026-2036
Aluminium Clad Printed Circuit Board Market Analytics
Automotive electronics procurement is expanding across tier-one lighting suppliers and EV power module integrators, fragmenting what was once a concentrated LED-luminaire buyer base. TTM Technologies leverages captive aluminium lamination capacity to anchor North American supply for electric vehicle inverters. Amitron specializes in quick-turn prototypes for aerospace thermal management, occupying a niche where qualification cycles extend eighteen to thirty-six months. Varioprint AG competes through ISO-certified production lines serving German industrial automation OEMs with strict traceability requirements.
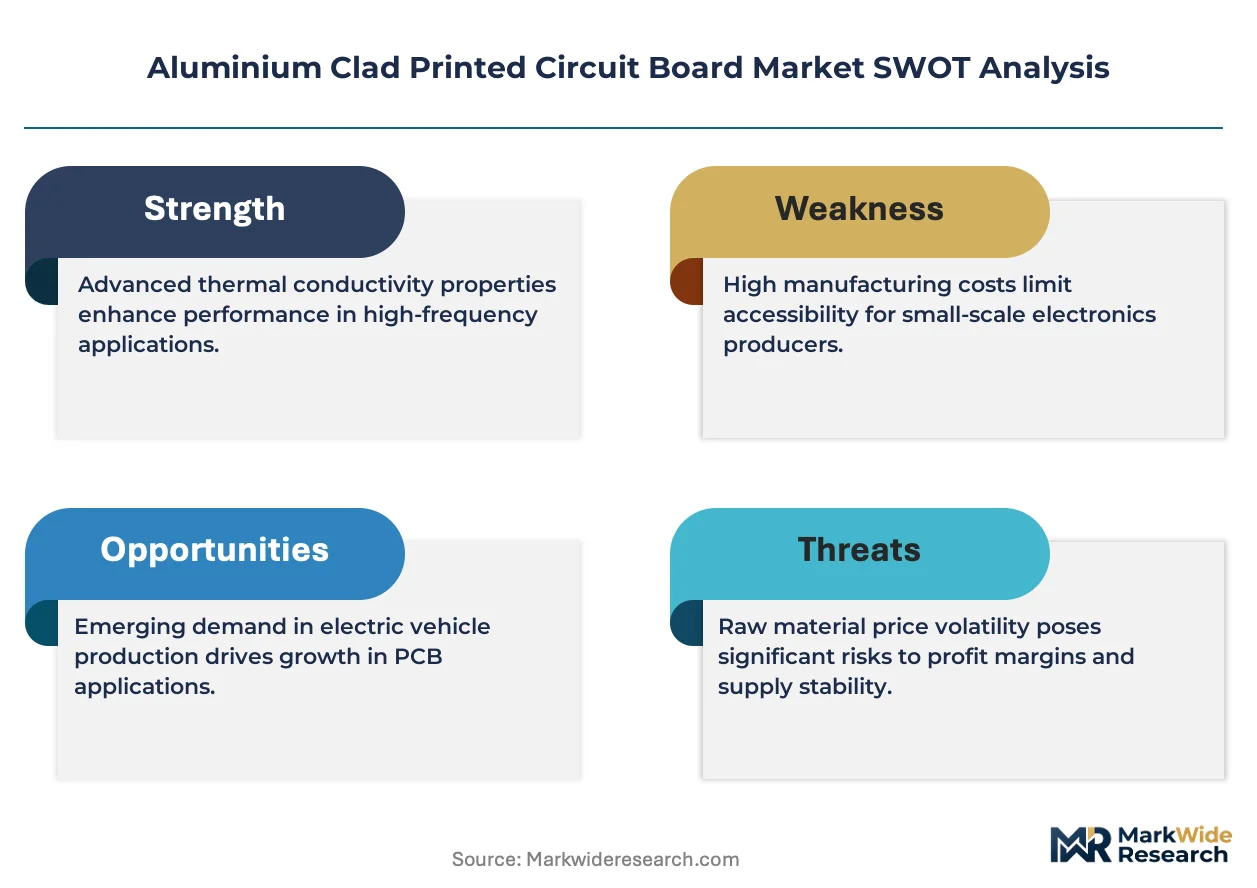
An aluminium clad printed circuit board consists of a thermally conductive aluminium base layer bonded to a copper circuit layer through a dielectric prepreg, typically achieving thermal conductivity between 1.0 and 3.0 W/mK depending on dielectric formulation. This construction draws heat away from high-power components in LED arrays, motor drives, and DC-DC converters where conventional FR-4 substrates would fail through thermal degradation. Single-sided configurations dominate volume production for cost-sensitive LED retrofit lamps, while multi-layer variants capture margin pools in telecommunications base stations where signal integrity and heat dissipation must coexist. Flexible aluminium-backed circuits remain embryonic but attract development investment from medical device manufacturers seeking conformable thermal solutions for wearable phototherapy equipment.
The US EPA regulates hexavalent chromium in aluminium surface conversion coatings under Clean Air Act provisions, pushing fabricators toward trivalent chrome or chrome-free pretreatment chemistries. China's GB standards for electronic product pollution control, administered by SAMR, mandate substance disclosure thresholds that affect dielectric adhesive formulations imported from Japanese and Korean chemical suppliers. The EU Ecodesign Directive, enforced through national market surveillance authorities, sets minimum efficacy requirements for LED modules that indirectly specify thermal interface performance. Stakeholders must monitor how impending revisions to automotive EMC standards in major manufacturing jurisdictions redefine the dielectric thickness versus thermal conductivity trade-off in power module substrates.
Market Dynamics
Automotive electrification programs are redrawing procurement specifications for power module substrates, forcing fabricators to recalibrate dielectric thermal conductivity against electromagnetic compatibility thresholds.
Growth Catalysts
- China's MIIT energy-efficiency mandates:Power electronics suppliers must source thermally conductive substrates for motor drives and inverters, tightening dielectric performance standards across domestic supply chains.
- LED retrofit lamp volume:Single-sided aluminium-backed boards capture cost-sensitive consumer lighting replacement cycles in residential and commercial retrofit channels.
- Copper-aluminium bonding advances:Improved dielectric prepreg formulations enable thinner thermal interfaces without voltage breakdown, expanding addressable applications in telecommunications base stations.
Market Restraints
- Dielectric adhesive import dependency:Japanese and Korean chemical suppliers control proprietary high-thermal-conductivity resin formulations, exposing fabricators to currency and logistics volatility.
- EU RoHS hazardous substance limits:Restrictions on lead and hexavalent chromium in surface conversion coatings force costly chemistry transitions at aluminium pretreatment lines.
- Ceramic substrate substitution:Direct-bonded copper on alumina and silicon nitride alternatives capture margin in ultra-high-power EV inverters above 200 kW.
Strategic Opportunities
- Medical wearable phototherapy:Flexible aluminium-backed circuits for conformable thermal management remain underdeveloped, attracting R&D investment from device manufacturers seeking conformal heat spreading.
- India's LED streetlighting procurement:Municipal bulk purchasing programs under the country's energy efficiency bureau create volume demand for cost-optimized single-sided boards.
- GaN power semiconductor integration:Gallium nitride switch deployment in compact chargers is electrifying demand for thin, high-thermal-conductivity substrates that manage localized heat flux.
Industry Challenges
- Automotive EMC qualification timelines:OEM power module validation cycles extend eighteen to thirty-six months, freezing design wins and straining working capital for mid-cap fabricators.
- Multi-layer registration precision:Aligning copper circuit layers across aluminium core thickness variations demands capital-intensive laser drilling and optical inspection equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aluminium Clad Printed Circuit Board Market |
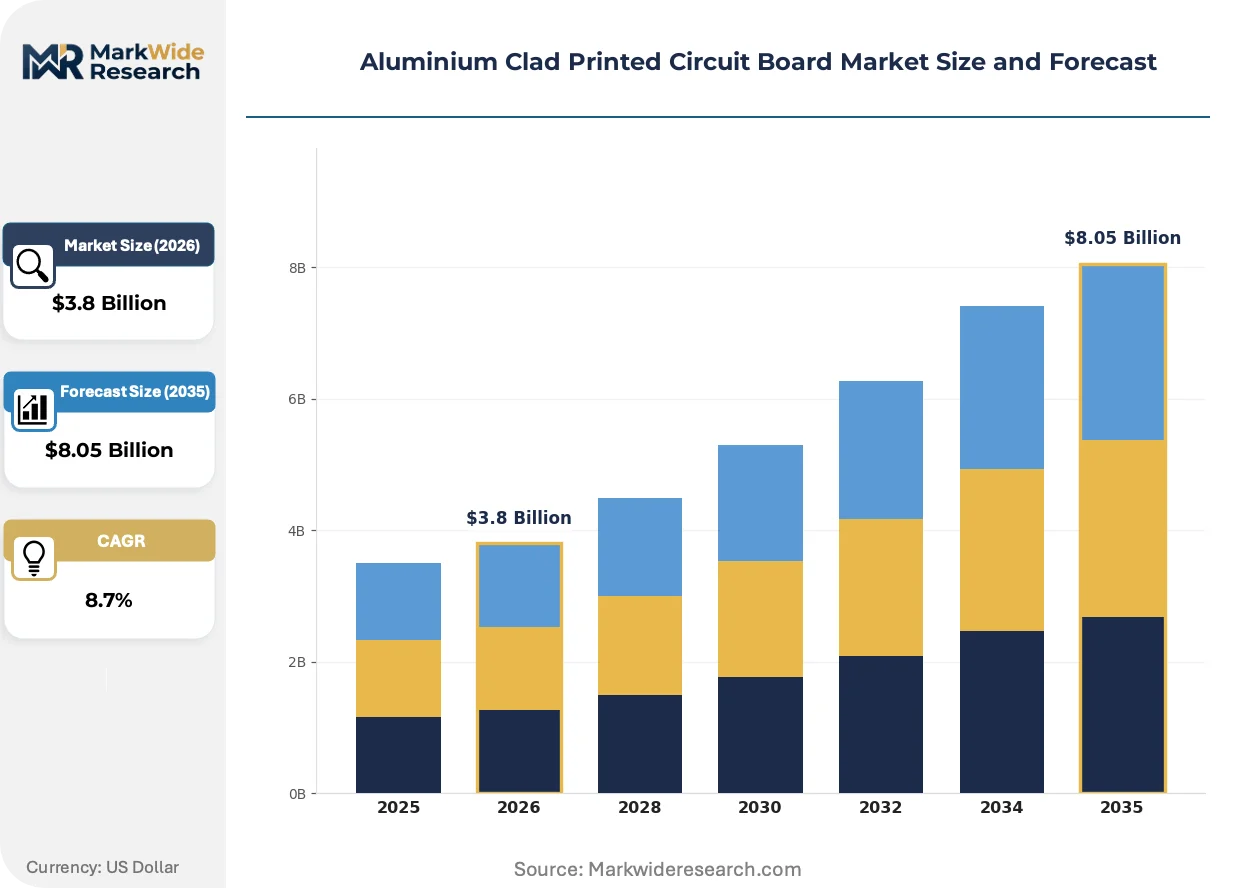
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Sided, Double-Sided, Multi-Layer, Flexible Application: LED Lighting, Power Electronics, Automotive Electronics, Industrial Equipment End User: Consumer Electronics, Telecommunications, Aerospace, Medical Devices Technology: Surface Mount Technology, Through-Hole Technology, Hybrid Technology, Embedded Technology |
| Companies Covered | TTM Technologies Inc., Amitron, San Francisco Circuits, Best Technology, Varioprint AG, Millennium Circuits Limited, Advanced Circuits, LT Circuit, Uniwell Electronic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aluminium Clad Printed Circuit Board Market Evolving Landscape
Material science breakthroughs and regulatory chemistry restrictions are converging to redefine substrate construction methods, thermal performance benchmarks, and qualification protocols.
Polyimide-ceramic hybrid dielectrics are electrifying thermal management possibilities in high-frequency power electronics. Defence and aerospace contractors are qualifying these laminates for radar power supplies. The technology is compressing the traditional trade-off between signal integrity and heat dissipation in multi-layer configurations.
REACH candidate list expansions are pressuring European fabricators to eliminate brominated flame retardants from dielectric adhesives. German industrial automation OEMs now mandate full material disclosure through SCIP database entries. Board suppliers are responding with phosphorus-nitrogen intumescent formulations that maintain UL94 V-0 ratings.
Consolidated supplier portals are replacing fragmented distributor networks for tier-one automotive lighting programs. Tier-two module integrators in Guangdong Province now transact directly with lamination houses for volume LED substrate contracts. This disintermediation is most pronounced in East Asian manufacturing clusters where procurement teams co-locate with fabrication facilities.
Aluminium Clad Printed Circuit Board Market Segmentation
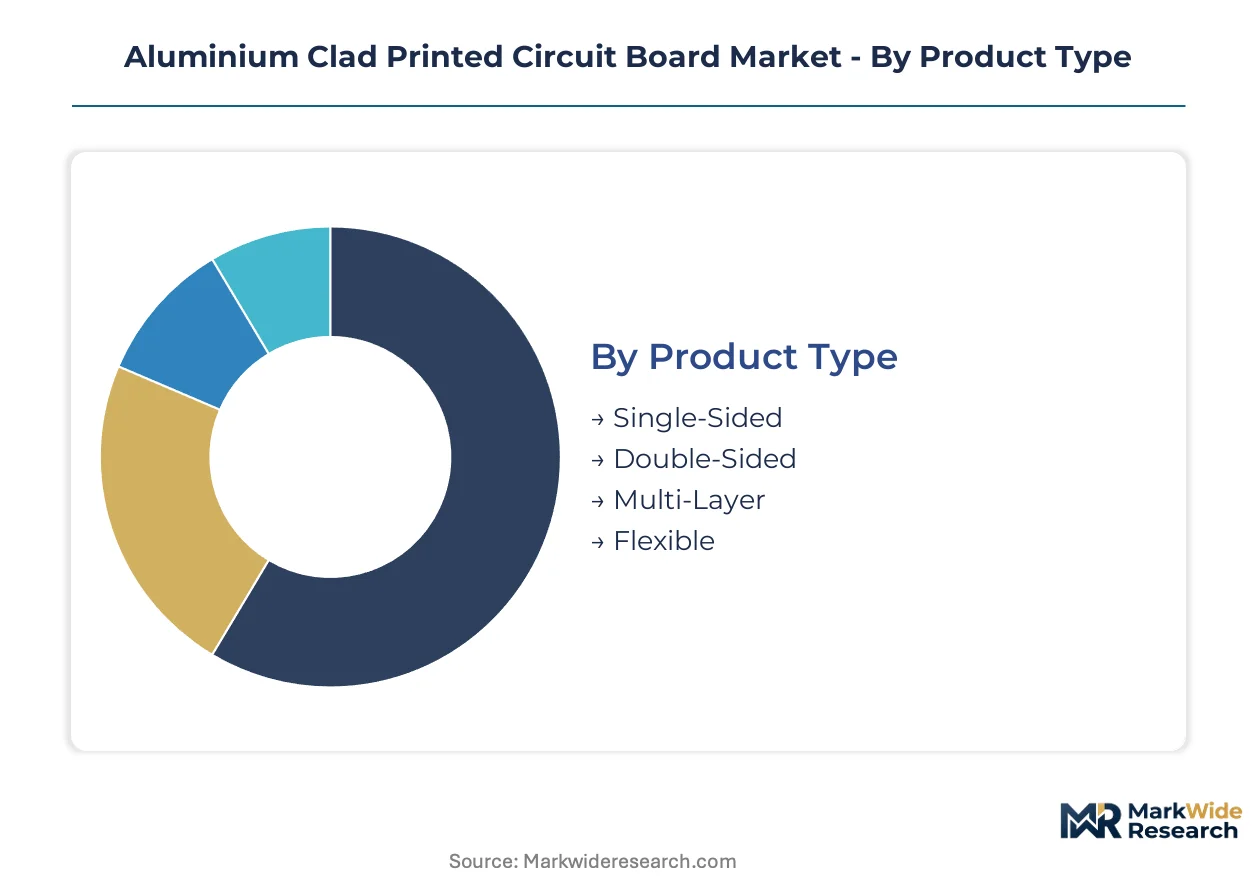
Aluminium clad printed circuit board procurement splits across thermal performance tiers, manufacturing complexity levels, and qualification rigor standards. Fabricators configure dielectric thickness, layer count, and surface finish specifications to match heat flux requirements and electromagnetic compatibility thresholds in target applications.
Product Type:
Standardization dominates at the high-volume end of this spectrum, while multi-layer and flexible variants demand extensive customization cycles.
- Single-Sided:One copper circuit layer bonded to aluminium base through dielectric prepreg, optimized for cost-sensitive LED retrofit lamps and linear lighting fixtures. Procurement concentrates with Guangdong Province fabricators serving residential and commercial retrofit channels where thermal management requirements remain modest.
- Multi-Layer:Aluminium core sandwiched between multiple copper circuit layers with buried vias, enabling signal integrity alongside heat dissipation in telecommunications base stations. Demand clusters with tier-one automotive lighting suppliers qualifying these substrates for ADAS power modules under extended EMC validation timelines.
- Double-Sided:Copper circuits on both faces of aluminium core, bridging thermal performance and circuit density for industrial motor drives.
- Flexible:Thin aluminium foil bonded to polyimide dielectric, permitting conformable thermal spreading for wearable medical phototherapy devices.
Leading the category by volume: Single-Sided. Growing fastest: Multi-Layer.
Application:
Cost tiers separate retrofit lighting from automotive power modules, with industrial equipment occupying a mid-tier qualification position.
- LED Lighting:Single-sided aluminium-backed boards in retrofit lamps, streetlighting housings, and commercial luminaires. India's municipal bulk procurement programs under the Bureau of Energy Efficiency generate volume demand for cost-optimized substrates with standard 1.0-1.5 W/mK thermal conductivity.
- Automotive Electronics:Power module substrates for electric vehicle inverters, onboard chargers, and LED headlamp drivers. TTM Technologies anchors North American supply through captive aluminium lamination capacity, while tier-two integrators in Taiwan's PCB corridor manage dielectric thermal conductivity against EMC thresholds.
- Power Electronics:Motor drives, DC-DC converters, and renewable energy inverters requiring thermal conductivity above 2.0 W/mK.
- Industrial Equipment:Factory automation controllers and robotics power stages with moderate thermal loads and extended operating lifespans.
Volume leader: LED Lighting. Steepest expansion trajectory: Automotive Electronics.
End User:
Customer type determines qualification burden, with aerospace and medical demanding longest certification cycles.
- Consumer Electronics:Compact chargers and appliance power supplies driving demand for thin, high-thermal-conductivity substrates. Gallium nitride semiconductor deployment is compressing form factors and intensifying localized heat flux management requirements.
- Aerospace:Radar power supplies and avionics thermal management requiring polyimide-ceramic hybrid dielectrics. Amitron specializes in quick-turn prototypes where qualification cycles extend eighteen to thirty-six months.
- Telecommunications:Base station power amplifiers and 5G infrastructure with simultaneous signal integrity and thermal dissipation needs.
- Medical Devices:Wearable phototherapy equipment and diagnostic imaging systems seeking conformable thermal solutions.
Dominant by procurement volume: Consumer Electronics. Expanding most quickly: Aerospace.
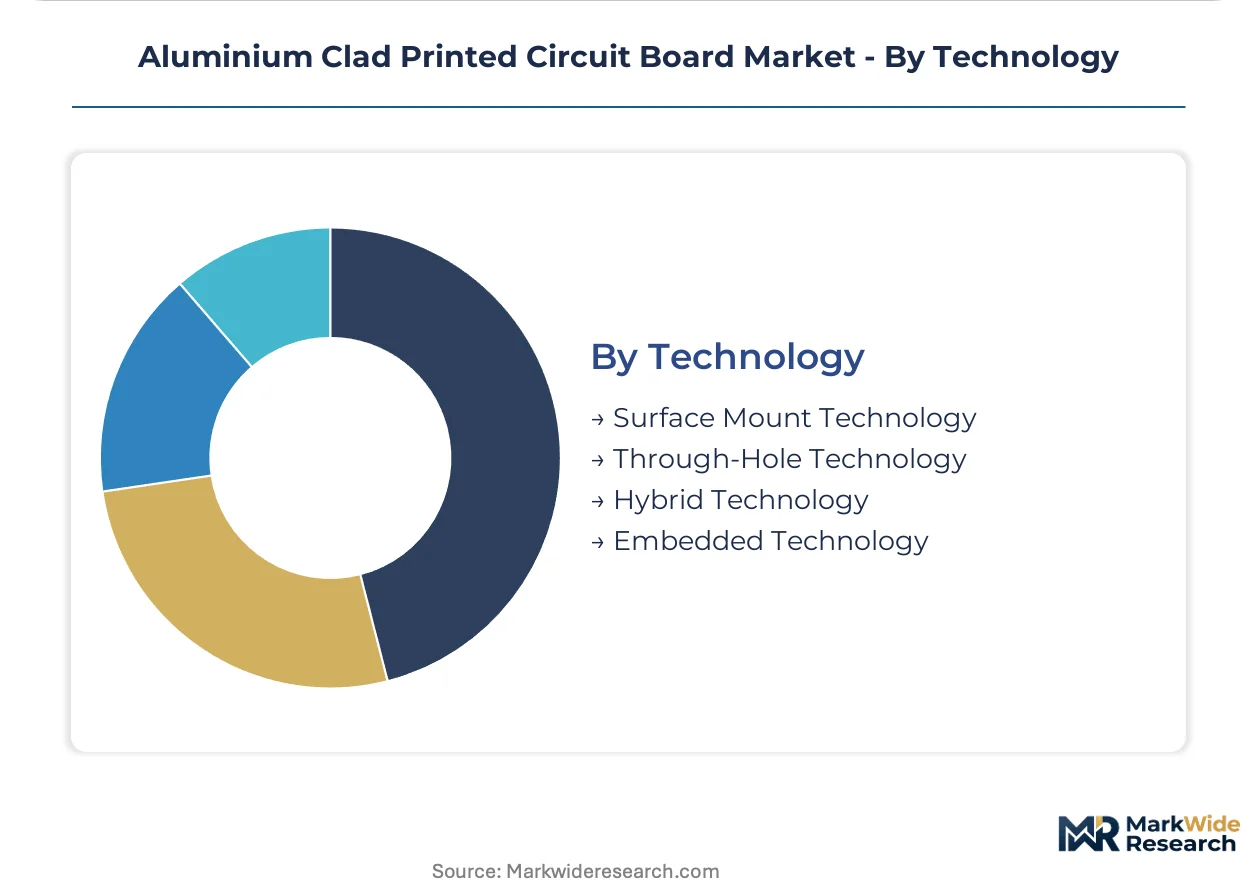
Technology:
Mounting technology maturity correlates with automation levels and assembly cost structures across manufacturing geographies.
- Surface Mount Technology:Dominant assembly method for LED arrays and compact power electronics, enabling automated placement of thermal interface components. Guangdong Province fabricators have scaled SMT lines specifically for aluminium-backed substrate processing.
- Through-Hole Technology:Retained for high-reliability industrial and automotive applications requiring mechanical component anchoring. German industrial automation OEMs mandate through-hole power devices on Varioprint AG ISO-certified production lines with full SCIP database material disclosure.
- Hybrid Technology:Combines surface mount and through-hole methods for mixed-signal power modules.
- Embedded Technology:Passive components buried within dielectric layers, emerging in high-frequency telecommunications substrates.
Volume leadership: Surface Mount Technology. Gaining share fastest: Hybrid Technology.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bauxite refining corridors in Henan Province and Shandong Province supply the aluminium substrate feedstock that underpins East Asian PCB fabrication. These raw-material localities anchor thermal management substrate production for automotive electrification and LED retrofit programs worldwide.
China
Guangdong Province hosts the densest concentration of aluminium-backed PCB fabricators serving LED streetlighting and consumer electronics. MIIT energy-efficiency mandates for motor drives and power inverters tighten dielectric performance standards across domestic supply chains. Shenzhen and Dongguan manufacturing clusters process standard 1.0-1.5 W/mK substrates for cost-optimized luminaire exports.
United States
TTM Technologies anchors North American supply through captive aluminium lamination capacity for electric vehicle inverters. EPA Clean Air Act provisions on hexavalent chromium push fabricators toward trivalent chrome or chrome-free pretreatment chemistries. Automotive electronics procurement concentrates with tier-one lighting suppliers and EV power module integrators in Michigan and California manufacturing corridors.
Germany
Varioprint AG operates ISO-certified production lines serving industrial automation OEMs with strict traceability requirements. REACH candidate list expansions pressure fabricators to eliminate brominated flame retardants from dielectric adhesives. Bavaria-based suppliers maintain SCIP database material disclosure for phosphorus-nitrogen intumescent formulations.
Taiwan
The island's printed circuit board corridor manages dielectric thermal conductivity against EMC thresholds for automotive power modules. Tier-two module integrators transact directly with lamination houses for volume LED substrate contracts. Taipei and Taoyuan manufacturing clusters specialize in multi-layer configurations for telecommunications base stations.
India
Municipal bulk purchasing programs under the Bureau of Energy Efficiency generate volume demand for cost-optimized single-sided boards. LED streetlighting procurement concentrates with domestic fabricators serving residential and commercial retrofit channels. Maharashtra and Gujarat manufacturing hubs scale SMT lines specifically for aluminium-backed substrate processing.
Aluminium Clad Printed Circuit Board Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue flexible and medical-grade substrate specializations. The vendor base organizes around three maturity tiers: volume fabricators with captive lamination, quick-turn prototype specialists, and ISO-certified precision suppliers. Two dominant competitive moves define current positioning: backward integration into aluminium pretreatment chemistries and geographic co-location with automotive OEM validation centers. Consolidated supplier portals disintermediate traditional distributor networks in East Asian procurement corridors.
Among North American fabricators, TTM Technologies Inc. and Amitron exemplify contrasting archetypes. TTM Technologies occupies a position tied to captive aluminium lamination infrastructure. Amitron sits within the quick-turn prototype tier where qualification cycles extend eighteen to thirty-six months. Varioprint AG represents the ISO-certified precision supplier archetype serving European industrial automation with full material disclosure protocols.
| Leading Market Players |
|---|
| TTM Technologies Inc. |
| Amitron |
| San Francisco Circuits |
| Best Technology |
| Varioprint AG |
| Millennium Circuits Limited |
| Advanced Circuits |
| LT Circuit |
| Uniwell Electronic |
| Others |
Value Network & Pricing Analysis
Certification-grade divergence between automotive-qualified multi-layer substrates and commodity single-sided boards manifests in both pricing power and supply chain configuration. Premium tiers capture extended EMC validation cycles and captive lamination capacity, while cost-optimized tiers feed from distributed Guangdong fabricators serving LED retrofit channels.
Pricing Analysis
Warranty and qualification-bundling separates automotive-grade multi-layer supply from unbundled commodity single-sided procurement. Three-tier pricing structure across automotive-qualified, industrial-certified, and economy LED tiers reflects dielectric thermal conductivity ratings and EMC validation depth. Cost compression in economy tiers intensifies because Guangdong fabricators compete on volume scale for municipal streetlighting contracts. Consumer electronics buyers exhibit highest price sensitivity, while aerospace and medical device procurement tolerates premium positioning for eighteen-to-thirty-six month qualification cycles.
Supply Chain Analysis
Workforce availability constraints in Shenzhen and Dongguan manufacturing clusters shape fabrication capacity allocation across thermal performance tiers. Supply concentrates in China, Taiwan, and Germany, with bauxite refining in Henan and Shandong provinces feeding aluminium substrate feedstock. Dielectric prepreg formulations draw from Japanese and Korean chemical suppliers, creating single-source vulnerability for high-thermal-conductivity resin. Distribution runs through consolidated supplier portals that disintermediate traditional distributor networks in East Asian procurement corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in a substrate technology-transition phase where polyimide-ceramic hybrid dielectrics displace conventional prepreg formulations in high-frequency power electronics. Gallium nitride semiconductor deployment accelerates demand compression for thinner thermal interfaces.
For Market Incumbents: Anchor North American supply through captive aluminium lamination infrastructure as TTM Technologies demonstrates, while deepening backward integration into chrome-free pretreatment chemistries to preempt EPA regulatory shifts. Defend against ceramic substrate substitution in ultra-high-power EV inverters by qualifying polyimide-ceramic hybrid laminates for radar and telecommunications base station applications.
For New Entrants and Emerging Players: Direct-to-device-manufacturer digital procurement platforms offer the lowest-friction entry path into flexible aluminium-backed circuit supply for wearable medical phototherapy. Target India's municipal LED streetlighting procurement under Bureau of Energy Efficiency programs, where cost-optimized single-sided board specifications favor new capacity without legacy qualification burdens. Pursue quick-turn prototype positioning in aerospace thermal management where Amitron's eighteen-to-thirty-six month cycle model proves replicable.
For Investors and Strategic Acquirers: Re-rating potential sits with ISO-certified precision suppliers given REACH candidate list expansions and SCIP database disclosure mandates that elevate compliance infrastructure value. Long-term viability through the technology-transition window favors fabricators with multi-layer registration precision and automotive EMC validation relationships. Watch GaN power semiconductor integration rates as the inflection signal for thin-substrate demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminium Pretreatment | Captive chrome-free chemistry capacity preempts EPA Clean Air Act enforcement shifts. |
| Polyimide-Ceramic Hybrid Dielectric Qualification | Defence and aerospace contractor approvals compress signal-integrity-versus-thermal trade-offs. |
| Consolidated Supplier Portal Deployment | Direct lamination-house transactions in Guangdong disintermediate legacy distributor networks. |
| Automotive EMC Validation Center Co-location | Proximity to OEM power module qualification cycles accelerates design win capture. |
| Flexible Substrate R&D Investment | Medical device manufacturer partnerships for conformable phototherapy equipment open white-space. |
Research Methodology
Trade association filings, customs documentation, and SEC regulatory disclosures formed the secondary backbone for this analysis. Primary interviews with PCB fabrication plant managers, automotive Tier 1 procurement leads, dielectric adhesive R&D directors, and medical device thermal engineers combined with secondary validation. Bottom-up fabrication capacity estimates and top-down end-use demand aggregation enabled cross-verification across the analysis window.
Historical trendline analysis of aluminium-backed substrate shipments by thermal conductivity tier informed projection modeling. Segmentation dimensions included product type, application, end user, and mounting technology complexity across the projection horizon. CAGRs derived from curve-fitting approaches applied to qualification-corrected capacity expansion timelines. GaN semiconductor deployment rates and MIIT energy-efficiency mandate implementation served as industry-specific forecast inputs.
The model holds under stable dielectric resin supply and continued automotive electrification program execution; deviation in ceramic substrate substitution pace or REACH regulatory acceleration would shift trajectory assumptions. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Middle East Location-Based Services Market
Others
Industrial Air Purifiers Market
Others
Asia Pacific Automotive LED Lighting Market
Others
North America Flexographic Printing Market
Others
Disposable Non Woven Sponge Market
Others
Aerospace Tester Market
Others
South Korea Intellectual Property Market
Others
Manometers Market
Others
Small Office Home Office (SOHO) Servers Market
Others
Hypersensitivity Market
Others
Smart Home Solutions Market
Others
Gym Wipes Market
Others
Food Technology Market
Others
CAR T Cell Therapy Market
Others
Folding Mobile Phone Market
Others
Global Drug Discovery Informatics Market