
 Infant Fever Stickers Market | 2026-2036
Infant Fever Stickers Market Size, Share, and Industry Trends Forecast 2026-2036
Infant Fever Stickers Market Analysis
Multi-pack bundling of disposable stickers with digital thermometers is broadening buyer choice across retail pharmacy and online channels. Medline Industries leverages its hospital supply chain to sustain volume leadership in institutional procurement. Pigeon Corporation anchors its position through specialized distribution across Asian maternity retail networks. Tempagenix LLC differentiates via technology leadership in liquid crystal display formulations for temperature-readout accuracy.
Infant fever stickers are adhesive skin-applied indicators containing thermochromic liquid crystals or chemical dot matrices that change color to display body temperature within a calibrated range, typically manufactured through precision coating of responsive substrates onto hypoallergenic backings for non-invasive pediatric temperature monitoring. The product-type dimension shows disposable stickers capturing the dominant margin pool due to recurring purchase frequency, while digital stickers represent the fastest-growing configuration as Bluetooth-enabled models integrate with parental smartphone ecosystems. Material-grade segmentation reveals biodegradable substrates gaining traction among environmentally positioned brands, though PVC and adhesive film variants still occupy the bulk manufacturing base for cost-sensitive markets.
FDA biocompatibility requirements under ISO 10993 and EMA medical device regulations shape adhesive formulation standards and market access protocols for skin-contact pediatric products. The EU Green Deal chemical restriction frameworks are forcing material substitutions away from certain phthalate-containing adhesives across European supply chains. Stakeholders must monitor evolving pediatric-specific labeling mandates from Health Canada and TGA as these regulators tighten age-graded safety claims for home-use diagnostic devices.
Market Dynamics
Biocompatibility mandates from FDA and EMA are forcing adhesive reformulation across pediatric skin-contact devices, compressing margin pools for legacy PVC-based manufacturers while opening pathways for substrate innovators.
Growth Catalysts
- Bluetooth-enabled digital stickers:Smartphone ecosystem integration drives parental preference for continuous temperature logging without wake disruption.
- EU Green Deal chemical restrictions:Phthalate-free adhesive mandates accelerate biodegradable substrate adoption among European contract manufacturers.
- Millennial home healthcare:Non-invasive monitoring preference concentrates demand in direct-to-consumer pharmacy channels.
Market Restraints
- Thermochromic liquid crystal supply:Cholesteric ester precursor concentration in Japanese specialty chemical houses creates input cost volatility.
- ISO 10993 certification timelines:Extended biocompatibility testing protocols delay new adhesive platform commercialization by 18-24 months.
- Digital thermometer substitution:Low-cost infrared ear and temporal artery devices capture price-sensitive segments in mass retail.
Strategic Opportunities
- Indian maternity clinic networks:Underpenetrated institutional procurement in tier-2 cities offers volume scaling for disposable sticker formats.
- Hospital-at-home reimbursement:CMS and analogous national health frameworks expand eligible monitoring device categories.
- NFC-thermochromic convergence:Near-field communication chips embedded in liquid crystal substrates enable tap-to-log functionality.
Industry Challenges
- Pediatric dermatological testing capacity:Qualified clinical sites for infant skin irritation trials create bottlenecks in product pipeline velocity.
- Legacy ERP integration:Hospital procurement systems require custom API development for Bluetooth sticker data streams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Infant Fever Stickers Market |
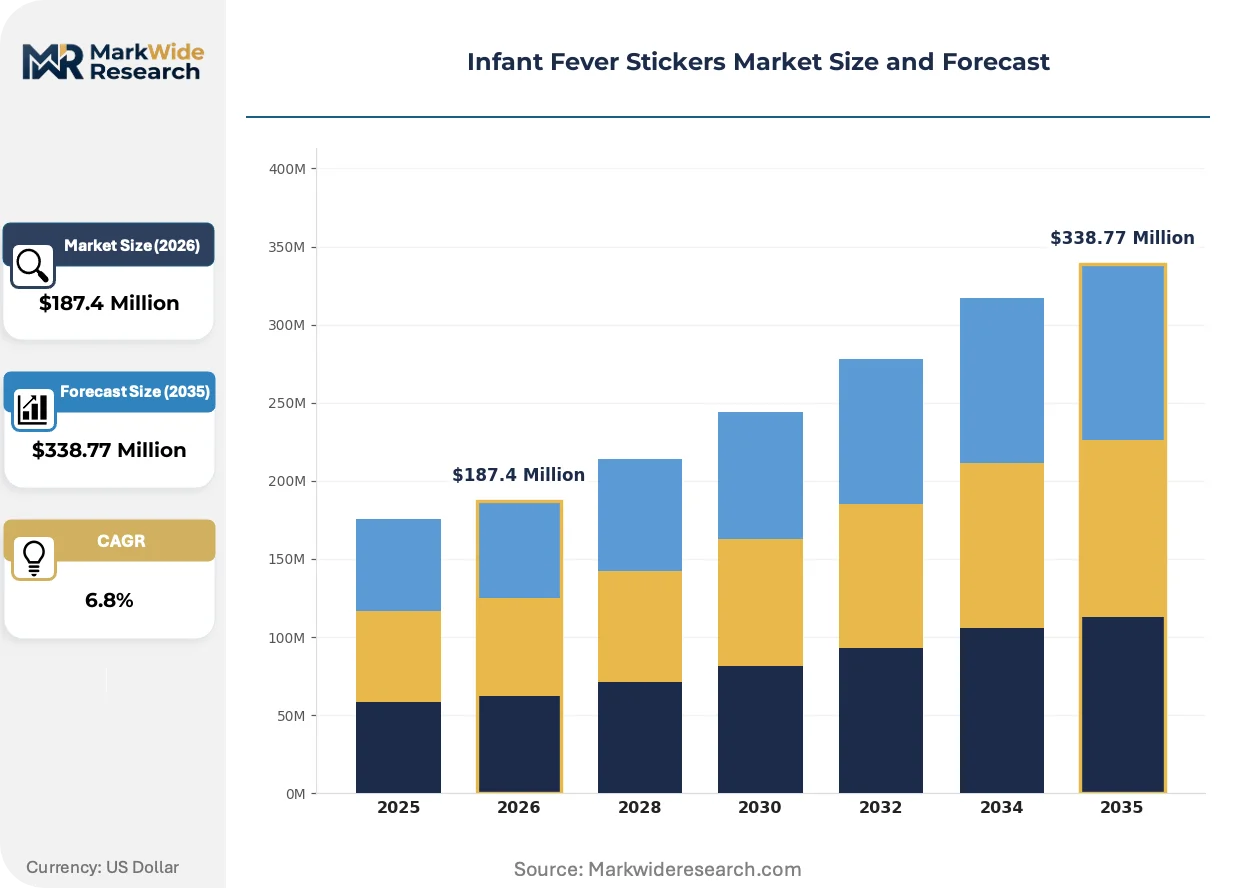
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Stickers, Traditional Stickers, Multi-use Stickers, Disposable Stickers Material: Biodegradable, PVC, Adhesive Film, Non-woven Fabric Target Age Group: Newborns, Infants, Toddlers, Pre-schoolers Distribution Channel: Pharmacies, Online Retail, Hospitals, Supermarkets |
| Companies Covered | Medline Industries, Pigeon Corporation, AMG Medical Inc, Carex Health Brands, Tempagenix LLC, FeverMates, Rumble Tuff, LCR Hallcrest LLC, Apothecary Products LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Infant Fever Stickers Market Emerging Trajectories
Material science advances and connectivity integration are fragmenting the traditional disposable sticker value chain into specialized component layers.
Printed electronics on flexible polymer substrates is modularizing temperature sensing from display readout. Pediatric device OEMs are adopting chip-on-flex architectures at accelerating cadence. This separation of sensing and display functions is modularizing supplier tiers and compressing time-to-market for private-label entrants.
REACH Annex XVII restrictions on skin-contact adhesives are forcing substitution of conventional acrylics for medical-grade silicone formulations. German and French contract manufacturers face reformulation costs and validation cycles. Premium sticker lines targeting Northern European pharmacy chains absorb compliance premiums through certified biodegradable positioning.
Subscription replenishment models are displacing single-unit pharmacy purchases among digitally native parents. Direct-to-consumer channels capture recurring revenue through calibrated sticker packs paired with app-based fever tracking. This behavioral shift concentrates lifetime value in United States and United Kingdom urban markets where telehealth integration is deepest.
Infant Fever Stickers Market Segmentation
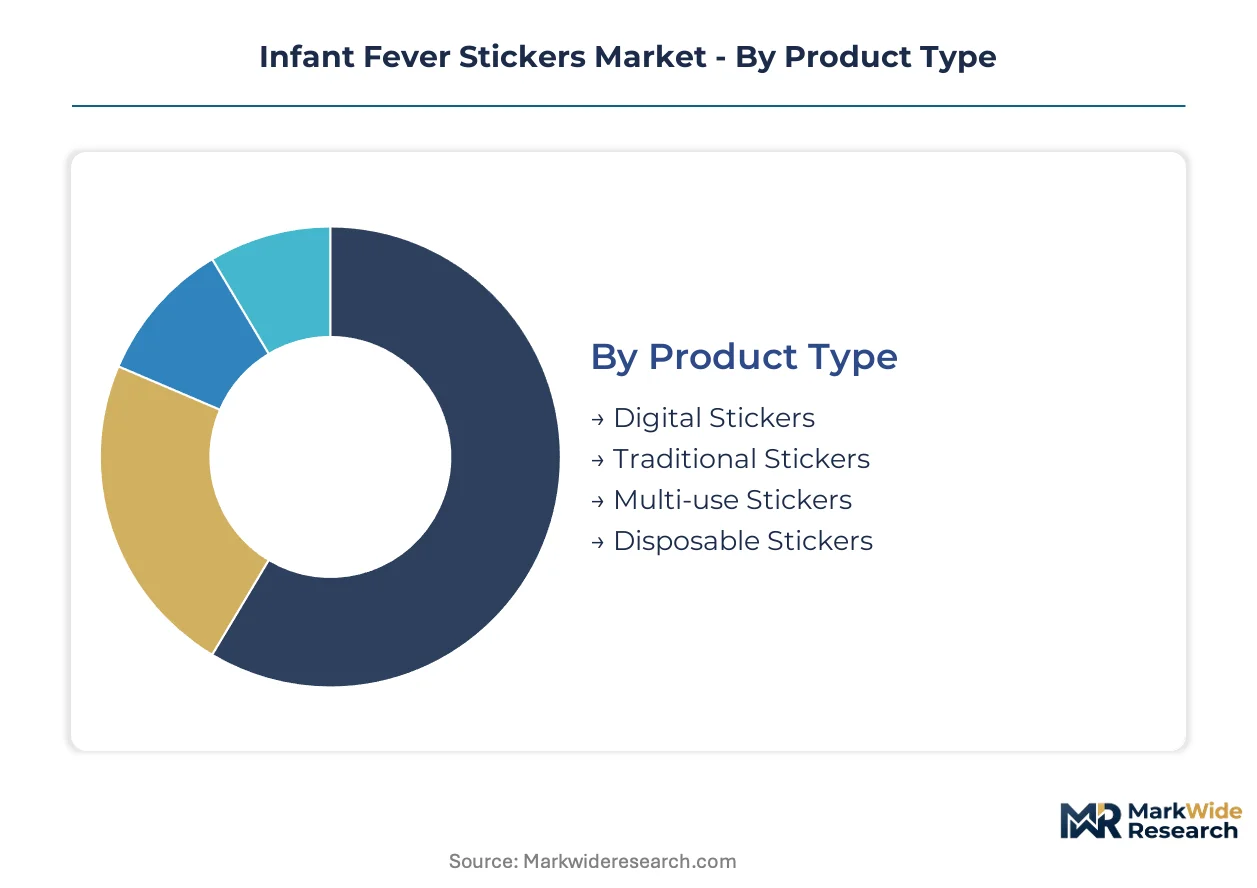
Segmentation in infant fever stickers determines both regulatory pathway complexity and margin architecture. FDA ISO 10993 biocompatibility requirements apply differentially across adhesive substrates and target age groups, while distribution channel selection shapes whether products compete on clinical certification or consumer convenience.
Product Type:
Certification burdens stratify sharply across this dimension—Bluetooth-enabled formats trigger FCC and FDA device classification, while passive thermochromic stickers face lighter cosmetic-grade oversight.
- Digital Stickers:Bluetooth-enabled sensors paired with liquid crystal or thermistor arrays transmit continuous temperature data to parental smartphones. Demand concentrates in United States urban markets where millennial parents prioritize uninterrupted sleep monitoring and telehealth integration drives reimbursement discussions.
- Disposable Stickers:Single-use thermochromic liquid crystal strips on hypoallergenic backings dominate pharmacy volume through recurring purchase cycles. German and Japanese hospital procurement systems anchor institutional demand for calibrated batch consistency.
- Traditional Stickers:Passive chemical dot matrices without connectivity serve price-sensitive segments in emerging markets.
- Multi-use Stickers:Rechargeable sensor platforms with replaceable adhesive layers target premium home healthcare segments.
Disposable stickers sit at the top of the volume ranking, with digital stickers climbing the fastest.
Material:
Cost tier architecture separates premium biodegradable positioning from commodity PVC manufacturing, with ECHA REACH compliance costs widening the spread.
- Biodegradable:Plant-derived substrates and medical-grade silicone adhesives command certification premiums in Northern European pharmacy chains. EU Green Deal chemical restrictions are accelerating contract manufacturer migration from legacy acrylic formulations.
- PVC:Conventional adhesive films with phthalate plasticizers retain cost-sensitive market share in mass retail and developing economies. EMA biocompatibility mandates are compressing margin pools as reformulation investments compound.
- Adhesive Film:Acrylic-based medical tapes with ISO 10993-5 cytotoxicity clearance serve mid-tier hospital contracts.
- Non-woven Fabric:Breathable cellulose backings reduce dermatological irritation incidents in neonatal intensive care applications.
PVC occupies the largest production base, though biodegradable substrates are expanding most quickly.
Target Age Group:
Application intensity varies by physiological development—newborn skin permeability demands the strictest adhesive safety profiles.
- Newborns:Products require neonatal-specific ISO 10993-10 irritation testing and hypoallergenic silicone formulations. United States NICU procurement and Japanese maternity hospital networks concentrate demand for calibrated accuracy in thermoregulation-critical first weeks.
- Infants:Six-month to twelve-month applications balance sensitivity with durability for emerging mobility. Parental anxiety around fever spikes drives direct-to-consumer subscription replenishment in United Kingdom and United States markets.
- Toddlers:Active-movement-resistant adhesive engineering becomes critical for reliable skin contact.
- Pre-schoolers:Verbal temperature reporting capability reduces sticker dependency, shifting demand toward confirmation-use scenarios.
Infant-targeted products command the volume lead, with newborn-specific formats gaining share fastest on clinical precision requirements.
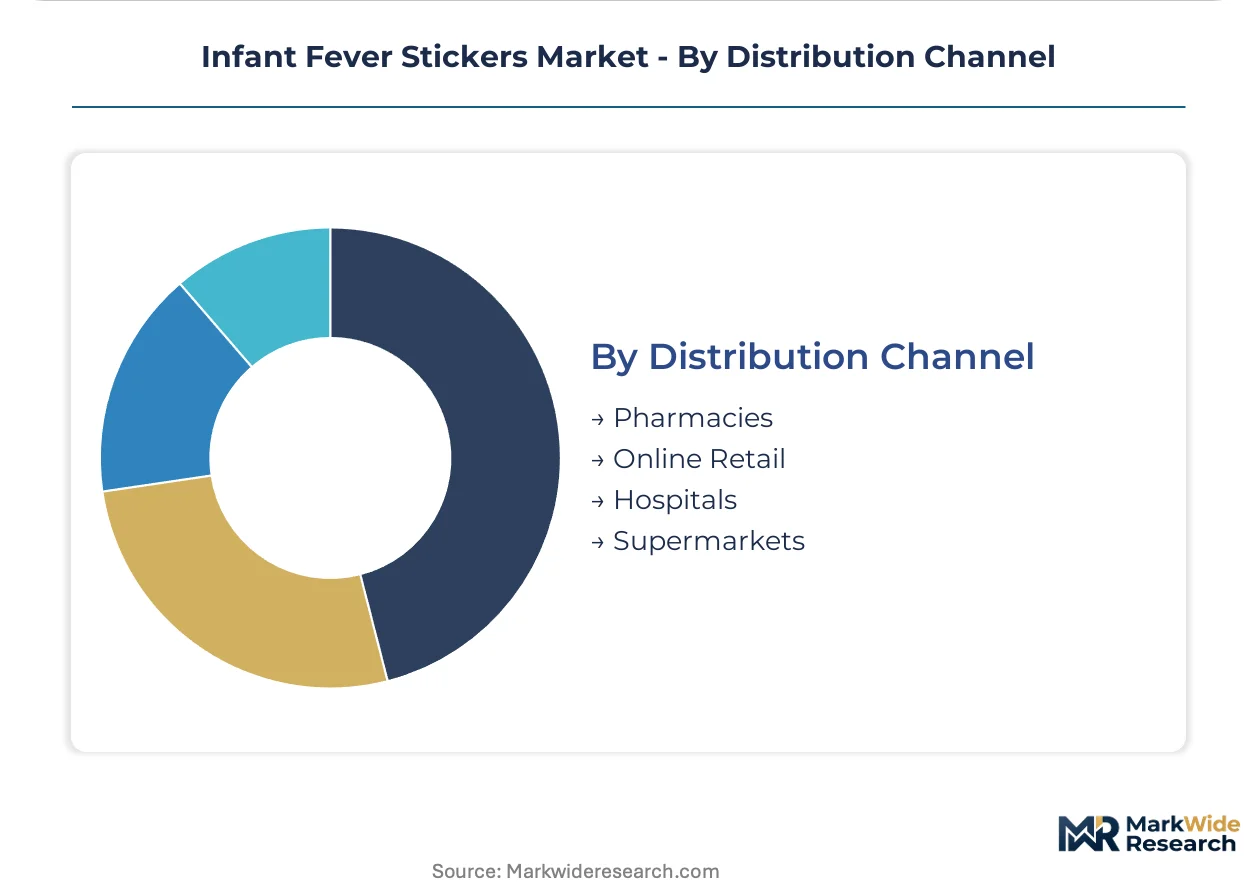
Distribution Channel:
Customer type fragmentation separates institutional procurement discipline from consumer impulse purchasing patterns.
- Pharmacies:Certified pharmacy networks in Germany and Japan require documented cold-chain handling and batch traceability. Professional counseling attachment rates sustain premium pricing against supermarket alternatives.
- Online Retail:Direct-to-consumer platforms capture subscription replenishment models paired with app-based fever tracking. United States and United Kingdom urban markets show deepest telehealth integration driving recurring revenue concentration.
- Hospitals:Group purchasing organization contracts demand volume discounts and ERP-compatible data formats.
- Supermarkets:Mass retail placement competes on price visibility for emergency purchase occasions.
Pharmacies retain the top volume position, with online retail channels showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The infant fever sticker industry traces its commercial origins to Japanese maternity care innovation in the 1980s, where PMDA-registered liquid crystal formulations first gained traction in neonatal wards. German and United States manufacturers subsequently scaled production for hospital procurement systems, establishing the current tri-regional concentration.
United States
Millennial parental preference for smartphone-integrated monitoring concentrates demand in urban direct-to-consumer channels. FDA ISO 10993 biocompatibility mandates shape adhesive formulation standards for skin-contact pediatric devices. Boston and San Francisco Bay Area telehealth clusters drive subscription replenishment model adoption among digitally native parents.
Germany
Hospital procurement systems anchored by group purchasing organizations sustain institutional volume for calibrated disposable formats. ECHA REACH Annex XVII restrictions on phthalate-containing adhesives accelerate medical-grade silicone substitution. Bavarian contract manufacturers face reformulation validation cycles as EU Green Deal chemical frameworks tighten.
Japan
Specialized maternity retail networks concentrate demand for precision-temperature neonatal products. PMDA medical device regulations enforce stringent batch consistency requirements for thermochromic liquid crystal calibration. Tokyo-Osaka industrial corridors host cholesteric ester precursor supply concentration, creating input cost sensitivity.
United Kingdom
Pharmacy-certified counseling attachment rates sustain premium positioning against supermarket alternatives. MHRA pediatric labeling mandates for home-use diagnostic devices tighten age-graded safety claim protocols. London and Manchester urban markets show deepest telehealth integration driving app-based fever tracking adoption.
India
Tier-2 city maternity clinic networks present underpenetrated institutional procurement opportunities for disposable sticker formats. CDSCO medical device registration timelines create market access friction for imported adhesive platforms. Maharashtra and Karnataka pharmaceutical manufacturing clusters incubate domestic contract manufacturing capacity.
Infant Fever Stickers Market Vendor Landscape
Premium-margin players sit above commodity-margin players across material-grade and connectivity dimensions, with biodegradable substrate innovators and Bluetooth-enabled format developers commanding pricing power over legacy PVC-based disposable manufacturers. The vendor base stratifies into three tiers: hospital supply chain incumbents with group purchasing organization relationships, specialized maternity retail distributors with pharmacy network access, and direct-to-consumer technology entrants with app ecosystem integration. Dominant competitive moves include strategic partnerships with telehealth platforms for reimbursement pathway development and portfolio diversification into subscription replenishment models.
Within the hospital supply chain tier, Medline Industries leverages its institutional procurement relationships to anchor volume positioning. Pigeon Corporation exemplifies the specialized maternity retail distributor archetype through its Asian pharmacy network concentration. Tempagenix LLC occupies the technology leadership position among liquid crystal formulation specialists. These three entities represent distinct competitive vectors: scale-driven supply chain integration, regional distribution depth, and materials science specialization respectively.
| Leading Market Players |
|---|
| Medline Industries |
| Pigeon Corporation |
| AMG Medical Inc |
| Carex Health Brands |
| Tempagenix LLC |
| FeverMates |
| Rumble Tuff |
| LCR Hallcrest LLC |
| Apothecary Products LLC |
| Others |
Supply Flow & Price Mechanics
Cholesteric ester precursor costs from Japanese specialty chemical houses cascade through liquid crystal substrate pricing tiers, compressing margins for commodity PVC-based disposables while amplifying premium capture for medical-grade silicone alternatives in Northern European pharmacy chains.
Pricing Analysis
Subscription-based replenishment paired with app ecosystems commands premium positioning against single-unit pharmacy transactions. Price differentiation hinges on ISO 10993-5 cytotoxicity certification grade and Bluetooth connectivity integration. Pricing pressure stems from low-cost infrared thermometer substitution in mass retail channels. Price-sensitive segments concentrate in supermarket emergency purchases, while hospital procurement systems exhibit lowest sensitivity due to clinical accuracy requirements.
Supply Chain Analysis
ISO 10993 biocompatibility certification gates entry for adhesive formulation suppliers, concentrating qualified substrate production in Germany, Japan, and United States medical-grade polymer corridors. Raw material dependencies center on cholesteric ester precursors, medical-grade silicone adhesives, and flexible polymer substrates. Single-source vulnerability in Japanese specialty chemical houses for liquid crystal inputs creates supply risk. Distribution runs through hospital group purchasing organizations, certified pharmacy networks, and direct-to-consumer platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where FDA and EMA biocompatibility tightening continuously elevates compliance barriers and reshapes competitive viability.
For Market Incumbents: Anticipate adhesive reformulation cost spikes from REACH Annex XVII phthalate restrictions by securing medical-grade silicone supply contracts now. Backward integration into cholesteric ester precursor sourcing mitigates Japanese supply concentration risk. Channel control through telehealth platform partnerships defends against direct-to-consumer technology entrants. For New Entrants and Emerging Players: EU Green Deal chemical restrictions in Germany and France open a window for biodegradable substrate specialists to capture pharmacy certification premiums. White-space targets include Indian tier-2 maternity clinic networks and NFC-thermochromic convergence formats. Go-to-market through subscription app ecosystems bypasses entrenched hospital supply chain incumbents. For Investors and Strategic Acquirers: Roll-up economics work for biodegradable adhesive specialists because ECHA compliance costs are fragmenting European contract manufacturing capacity. Long-term viability centers on material science platforms with dual FDA-EMA clearance pathways. Watch pediatric dermatological testing capacity bottlenecks as inflection signal for pipeline velocity constraints.| Strategic Initiative | Industry Significance |
|---|---|
| Biocompatibility Certification Investment | FDA ISO 10993 clearance opens hospital procurement channels and commands pricing premiums. |
| Telehealth Platform Partnership | CMS reimbursement pathway development anchors subscription revenue in United States urban markets. |
| Biodegradable Substrate Migration | EU Green Deal compliance positions brands for Northern European pharmacy chain placement. |
| NFC-Thermochromic Convergence | Near-field communication integration enables tap-to-log functionality for millennial parent segments. |
| Indian Clinic Network Expansion | CDSCO registration navigates market access friction for underpenetrated institutional procurement. |
Methodological Framework
Direct dialogue with pediatric device OEMs, hospital procurement managers, GPO contracts specialists, and adhesive formulation chemists grounded qualitative insights, cross-referenced against FDA 510(k) filings, EMA medical device registrations, hospital procurement databases, and customs trade records for thermochromic materials. Bottom-up and top-down triangulation validated volume estimates across adhesive substrate tiers and distribution channels.
Top-down macroeconomic sizing intersected with bottom-up segment-level modeling across product type, material grade, target age group, and distribution channel dimensions throughout the forecast period. CAGRs derived from regression analysis against pediatric outpatient volume trajectories and millennial home healthcare adoption curves, with Bluetooth-enabled format penetration serving as primary growth elasticity input alongside biocompatibility certification timeline assumptions.
Revisions become necessary when FDA or EMA pediatric-specific labeling mandates materialize, when cholesteric ester precursor supply disruptions occur, or when hospital-at-home reimbursement categories expand beyond current CMS frameworks. A model refresh is warranted upon material change in telehealth platform integration depth or EU chemical restriction enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Diamond Mining Market
Others
Gem Faceting Machine Market
Others
Calendered Polyvinyl Chloride Flexible Films Market
Others
Japan Coal Market
Others
Three Proofing Rugged Tablet Market
Others
Software Synthesizers Market
Others
Powder Coating Equipment Market
Others
IoT Testing Market
Others
Global Microcontroller Embedded Systems Market
Others
Military Sensors Software Market
Others
Cloud DVR Market
Others
Connected Homes Market
Others
India Battery E-Commerce Market
Others
Asia Pacific Cloud Infrastructure Testing Services Market
Others
South America Automotive LED Lighting Market
Others
Electric Pallet Jack Truck Market