
 Electric Chainsaw Market | 2026-2036
Electric Chainsaw Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Chainsaw Market Analytics
Professional landscaping companies are unwinding the historical dominance of homeowner purchases in electric chainsaw procurement. STIHL leverages its dealer network to sustain service-level differentiation against mass-market rivals. Makita anchors its position through battery platform interoperability across its outdoor power tool range. Husqvarna competes on professional-grade build tolerances that tolerate daily commercial workloads.
An electric chainsaw converts electrical energy into reciprocating chain motion through a brushless or brushed DC motor driving a sprocket and guide bar assembly, with cutting speeds typically ranging from 10 to 30 meters per second depending on motor wattage and chain pitch. Battery-powered chainsaws are capturing the fastest expansion as lithium-ion cell energy density improves and commercial users abandon gasoline engine maintenance burdens. Corded variants retain margin pools in stationary workshop and firewood preparation settings where mobility constraints do not apply. Pole chainsaws occupy a specialized niche in utility vegetation management where overhead reach requirements exclude standard form factors.
EPA emissions standards for small spark-ignition engines and OSHA workplace noise exposure limits are redirecting commercial buyers toward electric alternatives that eliminate exhaust compliance and reduce hearing protection burdens. The EU Green Deal machinery decarbonization timelines and REACH substance restrictions on battery materials are reshaping supplier qualification requirements across the value chain. Stakeholders must monitor solid-state battery commercialization timelines and charger infrastructure standardization to time platform investments.
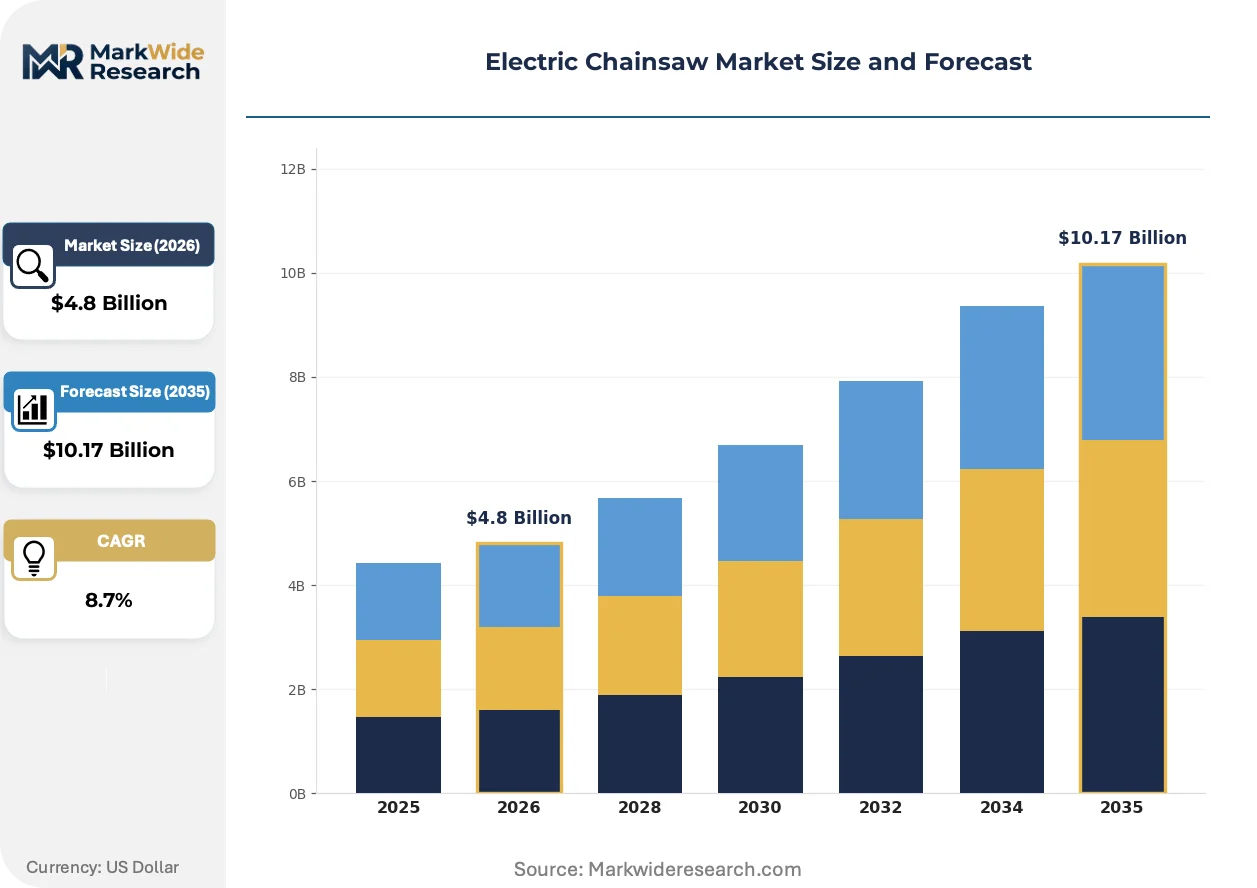
Market Dynamics
Landscaping cooperatives and municipal fleets are accelerating the displacement of gasoline equipment through binding procurement rules that prioritize brushless motor platforms and shared battery ecosystems across tool categories.
Growth Catalysts
- EU Green Deal machinery decarbonization timelines:Municipalities in Germany and the Netherlands now mandate zero-emission equipment for public contracts, forcing commercial landscapers to electrify chainsaw inventories ahead of schedule.
- OSHA workplace noise exposure limits:Commercial operators in the United States face stricter enforcement of hearing conservation programs, making electric chainsaws the compliant default for crews working near residential boundaries or in extended shifts.
- Lithium-ion cell energy density improvements:Cell chemistry advances from 250 to 300 watt-hours per kilogram are extending runtime per charge to match gasoline tank endurance for typical felling and bucking cycles.
Market Restraints
- Cobalt and lithium carbonate price volatility:Battery pack costs remain tethered to mining concentration in the Democratic Republic of Congo and Chilean salar brine operations, creating margin pressure when commodity spikes coincide with procurement cycles.
- Brushless motor controller supply concentration:Power semiconductor fabrication for high-efficiency motor drives clusters in Taiwanese foundries, exposing OEMs to geopolitical disruption risk and extended lead times during capacity crunches.
- Gasoline engine persistence in remote forestry:Absence of charging infrastructure in backcountry harvesting zones preserves internal combustion dominance for wildfire suppression and remote timber operations where battery logistics fail.
Strategic Opportunities
- India's urban greening mandates under Smart Cities Mission:Municipal corporations in Bengaluru and Pune are tendering for electric maintenance equipment as air quality enforcement tightens around parks and roadside vegetation corridors.
- Solid-state battery commercialization:Silicon-anode and ceramic-electrolyte cell architectures promise 40% energy density gains over conventional lithium-ion, enabling professional-grade runtime without weight penalties that currently limit commercial adoption.
- Platform interoperability as competitive moat:OEMs that secure backward compatibility across generations of battery packs can capture locked-in commercial fleets that resist switching costs associated with stranded charger and cell investments.
Industry Challenges
- Certification timeline compression under EU Machinery Regulation:Manufacturers face overlapping conformity assessment requirements for CE marking, electromagnetic compatibility, and battery safety standards that delay product launches by 8-14 months.
- Service technician skill gaps for power electronics diagnostics:Traditional small-engine repair networks lack training in inverter board troubleshooting and battery management system calibration, creating aftermarket service deserts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Chainsaw Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Corded Chainsaws, Battery-Powered Chainsaws, Pole Chainsaws, Mini Chainsaws End User: Homeowners, Landscaping Companies, Tree Service Providers, Construction Firms Power Rating: 500-1000 Watts, 1001-1500 Watts, 1501-2000 Watts, Above 2000 Watts Application: Tree Pruning, Wood Cutting, Land Clearing, Firewood Preparation |
| Companies Covered | Husqvarna, STIHL, Makita, Stanley Black & Decker, Techtronic Industries, Robert Bosch, Echo, Oregon Tools, Zhejiang Zomax Garden Machinery, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Chainsaw Market Evolving Landscape
Equipment architecture is splitting between integrated battery systems and modular platform designs, with procurement rules and total-cost accounting driving divergent investment patterns across buyer segments.
Brushless permanent magnet motor topology is bifurcating the product hierarchy into sealed-unit homeowner tools and field-serviceable professional platforms. Landscapers operating fleet-scale inventories favor motors with replaceable stator assemblies and accessible hall sensors. This technical stratification is compressing the mid-market segment that previously bridged consumer and commercial categories.
REACH substance restrictions on battery materials are forcing cell suppliers to eliminate cobalt-rich cathode chemistries and certain fluorinated electrolyte additives. OEM qualification cycles for alternative lithium-iron-phosphate and nickel-manganese-cobalt reduced-cobalt formulations are extending supplier onboarding timelines. European forestry cooperatives are responding by consolidating procurement around pre-qualified cell vendors with established compliance documentation.
Rental and subscription service models are displacing outright equipment purchases among mid-sized landscaping contractors. Husqvarna Fleet Services and comparable telematics-enabled programs bundle tool access, maintenance, and battery refresh into per-hour billing. This consumption-pattern shift is most visible in Germany and Scandinavia where capital-light operating structures align with cooperative ownership models and seasonal cash flow volatility.
Electric Chainsaw Market Segmentation
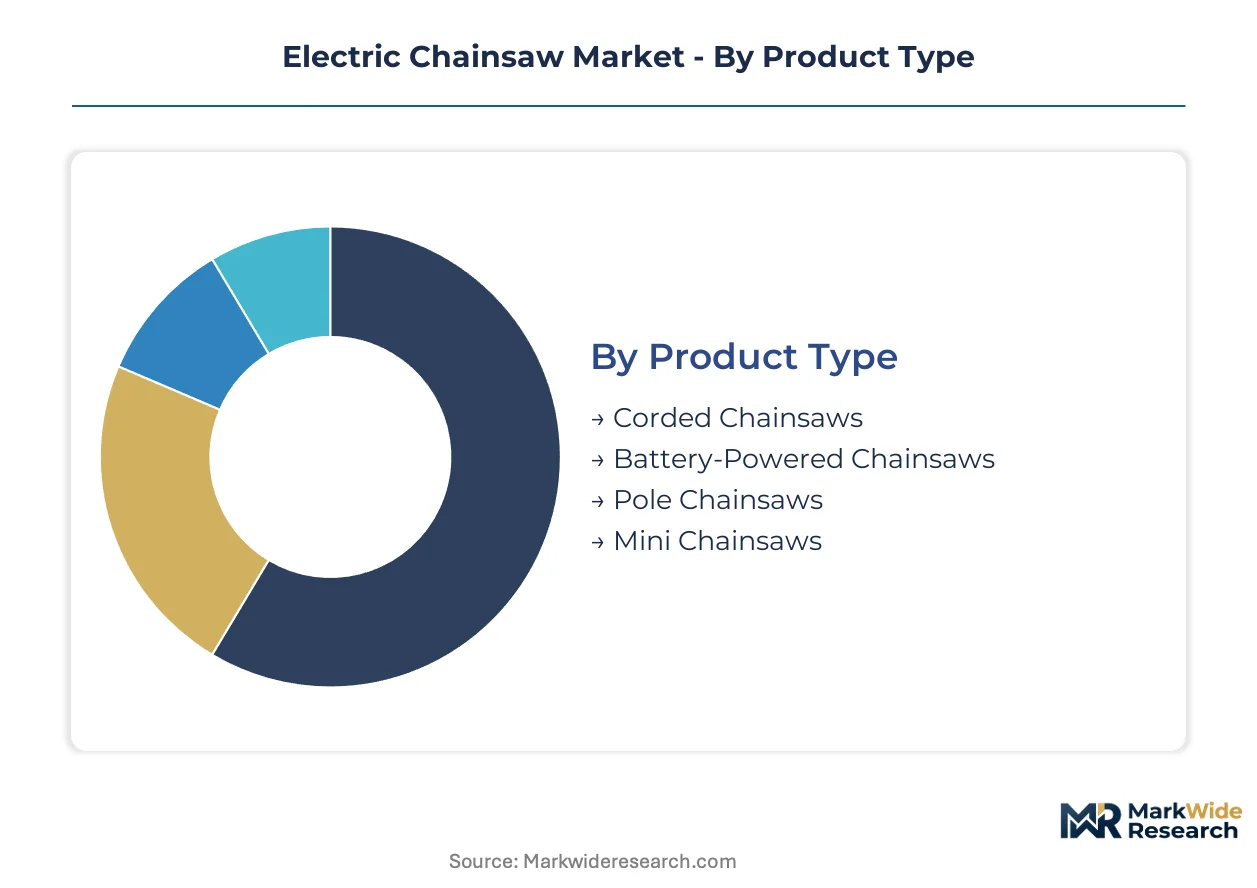
Electric chainsaw procurement patterns diverge sharply across user profiles and use intensities. Segment boundaries determine motor specification, battery platform investment, and service infrastructure requirements.
Product Type:
Battery-powered platforms face the most intense substitution pressure from next-generation solid-state architectures that promise to erase runtime gaps with gasoline equivalents.
- Corded Chainsaws:These units draw continuous AC power through tethered connections, eliminating battery weight and thermal management constraints. Demand clusters in stationary workshop environments across Germany and the Netherlands where firewood preparation and lumber milling operations prioritize uninterrupted runtime over mobility. EPA emissions compliance costs for small-engine alternatives reinforce corded positioning in commercial settings with reliable grid access.
- Battery-Powered Chainsaws:Lithium-ion cell packs deliver cordless operation through brushless DC motor drives with energy densities now exceeding 250 watt-hours per kilogram. Landscaping companies in Scandinavian municipalities are consolidating procurement around shared battery ecosystems that interchange across trimmers, blowers, and chainsaws to maximize fleet utilization rates.
- Pole Chainsaws:Telescoping shaft configurations extend cutting reach for overhead vegetation management without ladder deployment. Utility vegetation contractors in the United States specify these units for distribution line clearance where OSHA fall protection requirements elevate powered-reach solutions.
- Mini Chainsaws:Compact 4-6 inch bar lengths target light pruning and craft woodworking applications with single-hand operation. Hobbyist segments in Japan favor these units for bonsai maintenance and precision garden sculpting.
Battery-powered chainsaws retain volume leadership; mini chainsaws hold the steepest expansion curve.
End User:
Cost tier stratification separates capital-intensive fleet operators from intermittent residential purchasers with divergent total-cost-of-ownership calculations.
- Homeowners:Intermittent users with seasonal demand spikes prioritize acquisition price over runtime endurance and serviceability. German retail channels report strongest attachment rates for integrated battery systems with simplified maintenance requirements.
- Landscaping Companies:Commercial fleet operators amortize equipment across hundreds of annual operating hours and demand modular battery platforms with field-replaceable components. These buyers in the Netherlands now face municipal contract mandates for zero-emission equipment under EU Green Deal procurement rules.
- Tree Service Providers:Arborist specialists require professional-grade torque delivery for hardwood felling and storm damage response. OSHA noise exposure enforcement in the United States is redirecting urban crews toward electric alternatives that reduce hearing conservation program burdens.
- Construction Firms:Site preparation and demolition timber processing drives demand for high-wattage units with reinforced drive sprockets. Indian infrastructure contractors under Smart Cities Mission air quality mandates are tendering electric equipment for urban corridor maintenance.
Landscaping companies command the largest procurement volumes; tree service providers are gaining share fastest through regulatory-driven fleet conversions.
Power Rating:
Application intensity determines wattage thresholds, with commercial felling operations demanding sustained output that residential pruning rarely requires.
- 500-1000 Watts:Entry-level output range suits light pruning, hobby woodworking, and occasional firewood cutting with bars under 14 inches. Homeowners in Japan dominate this segment for garden maintenance tasks.
- 1001-1500 Watts:Mid-range platforms balance weight and cutting speed for routine landscaping maintenance and moderate hardwood processing. German forestry cooperatives specify these units for boundary vegetation management near residential noise-sensitive zones.
- 1501-2000 Watts:Professional-grade torque delivery handles sustained bucking cycles and medium-diameter felling without thermal derating. Landscaping fleets in Scandinavia concentrate procurement here for seasonal peak workload coverage.
- Above 2000 Watts:Maximum power density targets commercial timber harvesting and emergency storm response where gasoline displacement remains technically challenging. Battery thermal management and cell discharge rates constrain adoption despite improving energy density.
The 1001-1500 watt band retains volume leadership; above-2000-watt platforms are climbing the fastest as cell chemistry advances erode gasoline performance advantages.
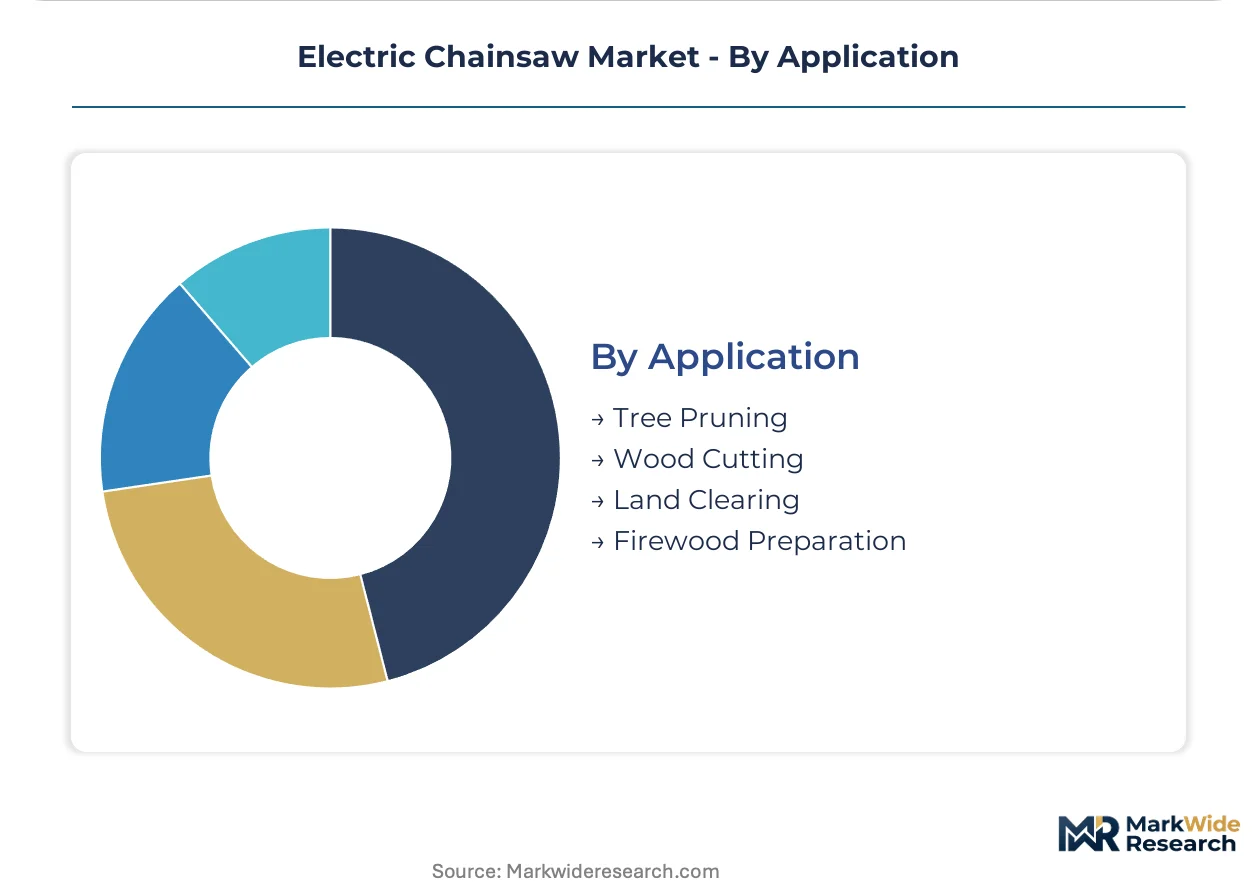
Application:
Task-specific duty cycles differentiate intermittent pruning demand from continuous production environments with opposing equipment specifications.
- Tree Pruning:Precision cutting with frequent positional adjustments favors lightweight, maneuverable platforms with top-handle configurations. Arborist contractors in the United States specify these for urban canopy maintenance under OSHA-compliant noise thresholds.
- Wood Cutting:Sustained ripping and cross-cutting operations demand high sustained wattage with efficient chip ejection systems. German sawmill workshops maintain corded dominance here for stationary production reliability.
- Land Clearing:Heavy-duty brush and sapling removal requires impact-resistant construction and rapid chain replacement capability. Infrastructure developers in India deploy these units for Smart Cities corridor preparation under tightening particulate emissions enforcement.
- Firewood Preparation:Seasonal bulk processing of harvested timber into stove-length sections prioritizes runtime endurance over cutting speed. Corded units retain strong positioning in Central European markets with reliable winter grid access.
Tree pruning retains volume leadership; land clearing holds the steepest expansion trajectory as infrastructure electrification accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial landscaping fleets concentrate procurement in jurisdictions with binding zero-emission mandates. Municipal contract rules and workplace noise enforcement redirect capital toward electric platforms.
Germany
Forestry cooperatives near residential boundaries prioritize low-noise equipment to satisfy local ordinance enforcement. EU Green Deal machinery decarbonization timelines bind municipal procurement to zero-emission standards. The Baden-Württemberg and Bavaria clusters host equipment distributors serving cooperative purchasing pools.
United States
OSHA workplace noise exposure limits tighten enforcement for crews operating near suburban property lines. Commercial arborists face hearing conservation program compliance costs that electric alternatives reduce. Pacific Northwest utility vegetation contractors specify pole chainsaws for distribution line clearance under fall protection regulations.
Netherlands
Municipal landscaping fleets accelerate gasoline displacement through procurement rules favoring shared battery ecosystems. EU REACH substance restrictions on battery materials reshape supplier qualification requirements. The Randstad urban corridor concentrates fleet operators tendering for park and roadside maintenance contracts.
India
Smart Cities Mission urban greening mandates drive municipal tendering for electric maintenance equipment in Bengaluru and Pune. Central Pollution Control Board air quality enforcement tightens around vegetation corridors. Infrastructure contractors in Maharashtra deploy land-clearing units for corridor preparation under particulate emissions rules.
Japan
Hobbyist segments favor compact mini chainsaws for precision garden sculpting and bonsai maintenance. METI efficiency standards shape battery platform development timelines. The Kanto and Kansai metropolitan clusters concentrate specialty retailers serving precision agriculture and residential gardening demand.
Electric Chainsaw Market Competitive Landscape
Player mix skews toward diversified outdoor power equipment manufacturers with established dealer networks. The vendor base concentrates around three to five integrated groups controlling battery platform ecosystems and service infrastructure. Strategic archetypes separate dealer-network builders from mass-market battery platform specialists and professional-grade durability fabricators. Competitive moves center on shared battery ecosystem expansion and fleet telematics service bundling.
Among European-origin integrated manufacturers, Husqvarna, STIHL, and Robert Bosch occupy positions spanning professional and consumer tiers. These entities exemplify the dealer-network archetype that sustains service-level differentiation against direct-to-market rivals. Makita represents the battery platform interoperability strategy, anchoring fleet-scale procurement through cross-tool compatibility. Stanley Black & Decker sits within the mass-market consolidation vector, leveraging portfolio breadth across homeowner and light commercial segments.
| Leading Market Players |
|---|
| Husqvarna |
| STIHL |
| Makita |
| Stanley Black & Decker |
| Techtronic Industries |
| Robert Bosch |
| Echo |
| Oregon Tools |
| Zhejiang Zomax Garden Machinery |
| Others |
Value Network & Pricing Analysis
Foundry-scale semiconductor fabrication for brushless motor controllers concentrates in Taiwanese facilities, creating dual leverage over OEM cost structures and supplier bargaining power that cascades through battery pack and finished equipment pricing tiers.
Pricing Analysis
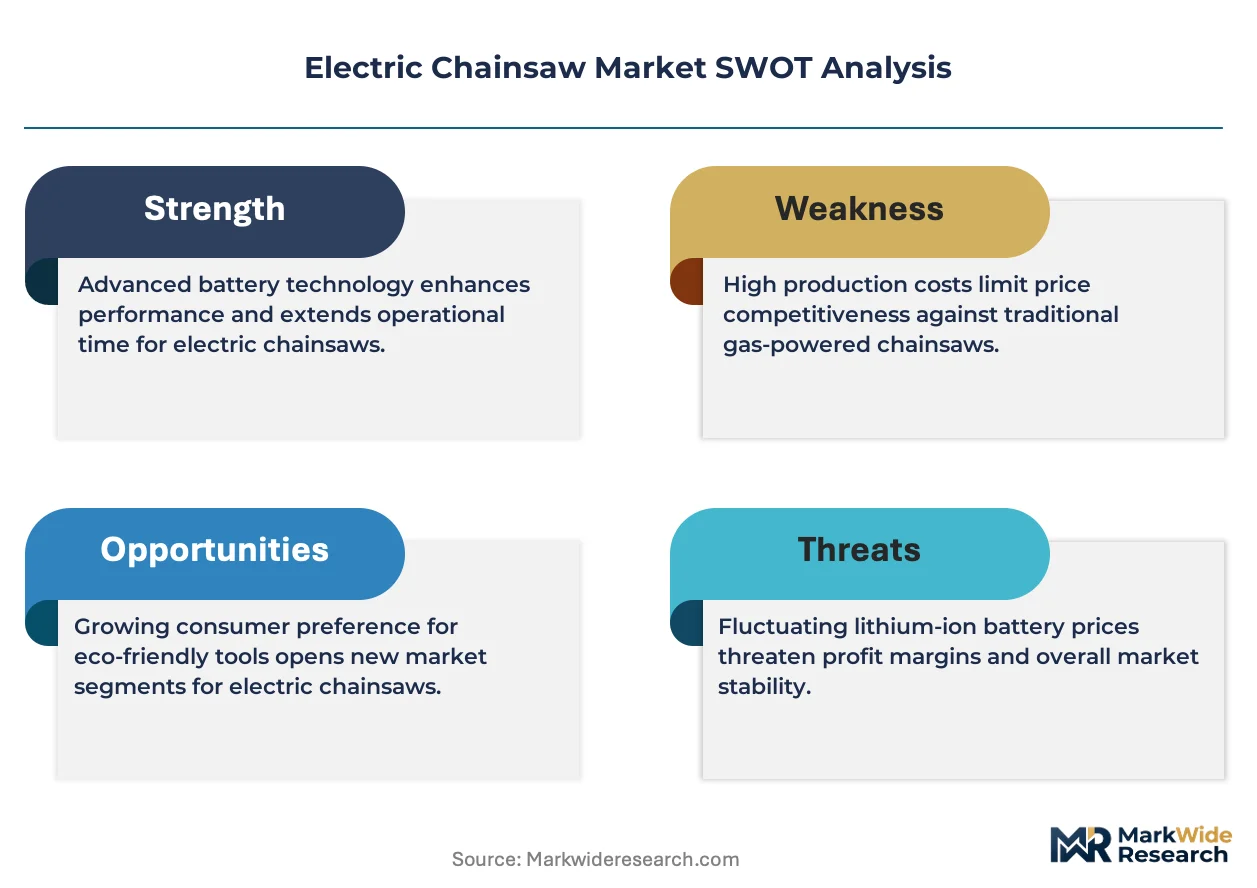
Cost-plus contracts with lithium carbonate indexation dominate battery procurement agreements between OEMs and cell suppliers, with Chilean salar brine price volatility passing through to pack costs within 90-day adjustment windows. Three-tier pricing structure across premium, standard, and economy levels separates professional-grade brushless platforms with field-serviceable components from sealed homeowner units and entry-level brushed-motor alternatives. Price differentiation rests on UL/CE certification tier and volume scale, with fleet procurement above 500 units unlocking 15-20 point discounts. Cost compression in the economy tier is intensifying because Chinese OEMs are flooding European distribution channels with unbranded lithium-ion platforms. Homeowners exhibit highest price sensitivity, while landscaping cooperatives prioritize total-cost-of-ownership calculations that amortize battery ecosystem investments across multi-tool fleets.
Supply Chain Analysis
Inventory lead times for power semiconductors and battery management ICs now stretch 26-40 weeks, forcing OEMs to hold 90-day finished goods buffers that compress working capital efficiency. Cell chemistry supply concentrates in China, South Korea, and Japan, with cylindrical 21700 and 18650 formats drawing from common cathode precursor streams. Raw material dependencies span cobalt hydroxide from the Democratic Republic of Congo, lithium carbonate from Chilean salar operations, and electrolyte salts from Japanese specialty chemical producers. Single-source vulnerability in Taiwanese foundry capacity for automotive-grade MOSFETs exposes motor controller supply to geopolitical disruption risk. Distribution runs through dealer networks in Germany and the Netherlands, direct-to-contractor platforms in Scandinavia, and industrial distributors in the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards regulatory entrenchment as the primary defensive moat, with EU Green Deal machinery decarbonization timelines and OSHA noise enforcement creating switching costs that lock commercial fleets into pre-qualified supplier relationships.
For Market Incumbents: Secure backward integration into battery cell assembly or cathode precursor processing to insulate margins from cobalt and lithium carbonate volatility. Anchor fleet-scale procurement through platform interoperability investments that maximize switching costs for landscaping cooperatives consolidating around shared battery ecosystems. Defend against emerging Chinese OEMs by accelerating dealer network density in German and Dutch municipal corridors where procurement rules favor established compliance documentation.
For New Entrants and Emerging Players: Aftermarket service deserts for power electronics diagnostics present the most penetrable white-space, with traditional small-engine repair networks lacking inverter board troubleshooting capabilities. Target tree service providers in the United States where OSHA noise enforcement is redirecting urban crews toward electric alternatives faster than incumbent service infrastructure can adapt. Pursue telematics-enabled rental subscription models that bundle tool access, maintenance, and battery refresh into per-hour billing, replicating Husqvarna Fleet Services structures without legacy channel conflicts.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors OEMs with solid-state battery qualification partnerships and established REACH compliance documentation that will compress supplier onboarding timelines for next-generation cell architectures. Long-term viability hinges on capturing platform lock-in effects as commercial fleets consolidate procurement around shared battery ecosystems that interchange across tool categories. Acquisition target archetype: regional distributors with dense dealer networks in EU Green Deal-mandated municipal corridors. The signal to watch is silicon-anode cell pilot production announcements from tier-one suppliers, which would indicate 40% energy density gains capable of eroding gasoline runtime advantages in professional-grade applications.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery Platform Interoperability Expansion | Locks commercial fleets into shared ecosystems that maximize utilization rates across trimmers, blowers, and chainsaws. |
| Backward Integration into Cell Assembly | Insulates OEM margins from Chilean lithium carbonate and DRC cobalt hydroxide price volatility. |
| Telematics-Enabled Rental Subscription Launch | Captures capital-light landscaping contractors through per-hour billing aligned with seasonal cash flow patterns. |
| Solid-State Battery Qualification Partnership | Positions OEMs for 40% energy density gains that erase runtime gaps with gasoline equivalents. |
| Dealer Network Density Expansion | Defends service-level differentiation against direct-to-market Chinese OEMs in EU-mandated municipal corridors. |
Research Methodology
A spread of perspectives from landscaping fleet managers, municipal procurement officers, dealer network operators, and aftermarket service technicians converged on the working assumptions underlying demand segmentation and price sensitivity calibrations. Primary fieldwork combined structured interviews with equipment distributors in Germany, the Netherlands, and the United States with secondary validation against EU Green Deal implementation timelines, OSHA enforcement guidance documents, and REACH substance restriction updates. Trade data from Eurostat and U.S. Census Bureau customs records provided import volume triangulation against bottom-up OEM shipment disclosures and top-down equipment stock estimates.
Segmentation dimensions modeled include product architecture (corded, battery-powered, pole, mini), end-user profile (homeowner, landscaping company, tree service provider, construction firm), power rating tier, and application intensity (pruning, wood cutting, land clearing, firewood preparation). CAGRs were derived from equipment stock replacement cycles, municipal procurement rule phase-in schedules, and cell chemistry energy density improvement curves across the projection horizon. Forecast inputs incorporated brushless motor penetration rates, shared battery ecosystem adoption thresholds, and solid-state battery commercialization timelines.
Forecasts assume regulatory continuity in EU Green Deal machinery decarbonization timelines and OSHA workplace noise enforcement; material policy shifts would require re-modeling demand acceleration or deceleration scenarios. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
APAC Smart Home Market
Others
China Smart Home Market
Others
Vegetable Carbon Market
Others
Global Military Lighting Market
Others
Nanomedicine for Drug Delivery Market
Others
Wearable Translator Market
Others
Global Military and Aerospace Sensors Market
Others
Global Computer Peripherals Market
Others
Document Camera Market
Others
US Mobile MRI Services Market
Others
Security Envelopes Market
Others
Electrical Calibration Equipment Market
Others
Inorganic Tin Chemicals Market
Others
Thailand Travel Retail Market
Others
Wingboards Market
Others
Ceramic Machinery Market