
 South America Automotive LED Lighting Market | 2026-2036
South America Automotive LED Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
South America Automotive LED Lighting Market Insights
A capital-intensity divergence between integrated chip-scale LED producers and module assemblers is reorganizing competitive tiers across the supply base. KOITO MANUFACTURING CO., LTD. leverages captive semiconductor packaging lines to sustain margin capture on matrix-beam headlamp systems. HELLA GmbH & Co. KGaA anchors its position through thermal-management IP and localized calibration centers in Brazil. OSRAM GmbH competes via phosphor-conversion architectures optimized for Mercosur voltage fluctuations and ambient heat loads.
Automotive LED lighting denotes solid-state illumination systems employing gallium-nitride emitters mounted on metal-core printed circuit boards, operating at junction temperatures below 150°C through active or passive thermal dissipation, primarily to enhance vehicle visibility, reduce energy draw from alternators, and enable adaptive beam-pattern control. Headlights occupy the dominant value share given complexity in adaptive driving-beam modules and laser-assisted long-range projection, while interior lighting segments differentiate through RGB ambient systems and surface-mount OLED panels targeting premium electric vehicle cabins. Aftermarket providers face structural pressure as OEMs extend standard LED fitment into economy passenger car trims, compressing retrofit volume pools.
Brazil's ANVISA enforces photobiological safety testing aligned with IEC 62471, while Mercosur technical regulations mandate electromagnetic compatibility certification for LED driver circuits, collectively raising compliance costs for non-integrated importers. Argentina's national automotive regulator adds homologation layers for adaptive front-lighting system activation speeds, shaping R&D priorities for suppliers serving dual-jurisdiction programs. Stakeholders must monitor convergence between Brazilian Inovação Verde incentives and evolving CONMETRO efficiency benchmarks to calibrate capital allocation across manufacturing and import strategies.
Market Dynamics
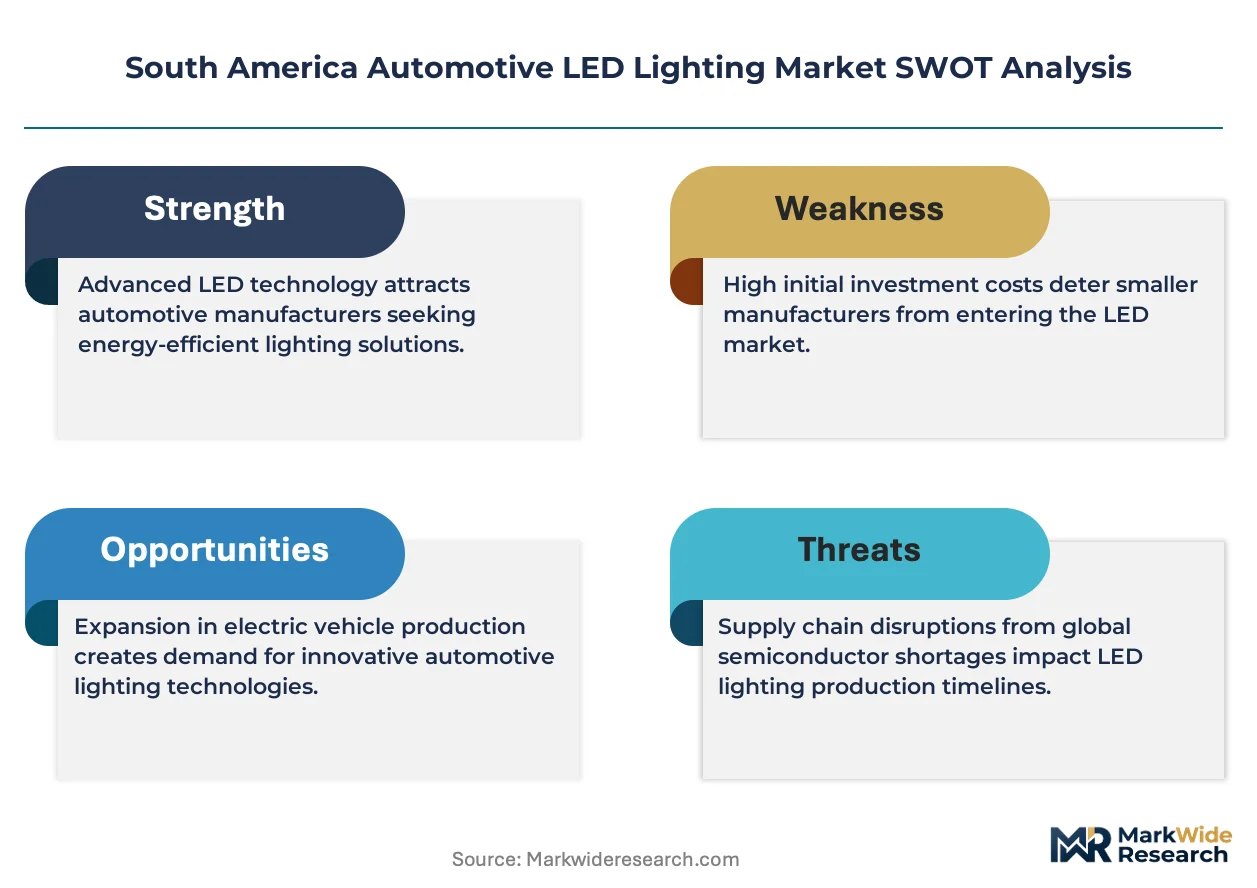
ANVISA photobiological safety mandates and Mercosur electromagnetic compatibility standards are forcing module-level redesigns across Brazilian and Argentine assembly lines, compressing supplier qualification timelines while elevating thermal-management specifications.
Growth Catalysts
- ANVISA IEC 62471 alignment:Brazil's mandatory photobiological testing accelerates chip-scale packaging investments by domestic module assemblers seeking faster homologation cycles.
- Matrix-beam headlamp demand:São Paulo-based electric vehicle assemblers specify adaptive driving-beam systems for both domestic certification and regional Mercosur export programs.
- Phosphor-conversion architectures:Voltage-stabilized LED designs optimized for Brazilian grid fluctuations penetrate economy passenger car trims previously served by halogen retrofit channels.
Market Restraints
- Gallium-nitride substrate volatility:Concentrated sourcing from East Asian foundries exposes Brazilian packagers to input cost swings and extended lead times for high-brightness emitters.
- Dual-jurisdiction homologation:Argentina's national automotive regulator imposes additional adaptive front-lighting activation-speed layers atop Mercosur baseline requirements, duplicating engineering validation.
- Halogen residual fitment:Legacy incandescent systems persist in Argentine commercial vehicle segments where total cost-of-ownership calculations delay LED conversion despite efficiency gains.
Strategic Opportunities
- RGB ambient cabin systems:Premium electric vehicle programs in Brazil's southeastern manufacturing corridor specify surface-mount OLED panels for differentiated interior lighting configurations.
- CONMETRO efficiency benchmarks:Brazilian federal efficiency standards create procurement preference windows for suppliers demonstrating luminous efficacy above regulatory minima.
- Aftermarket service bundling:Authorized dealer networks in Argentina integrate LED driver circuit diagnostics with scheduled maintenance, capturing retrofit volume displaced by OEM standard fitment.
Industry Challenges
- Thermal simulation expertise:Metal-core printed circuit board layout specialists capable of junction-temperature modeling below 150°C thresholds remain concentrated in São Paulo and Porto Alegre engineering clusters.
- Electromagnetic compatibility certification timelines:Mercosur LED driver circuit testing protocols extend product launch schedules by four to six months for non-integrated importers lacking captive laboratory access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Automotive LED Lighting Market |
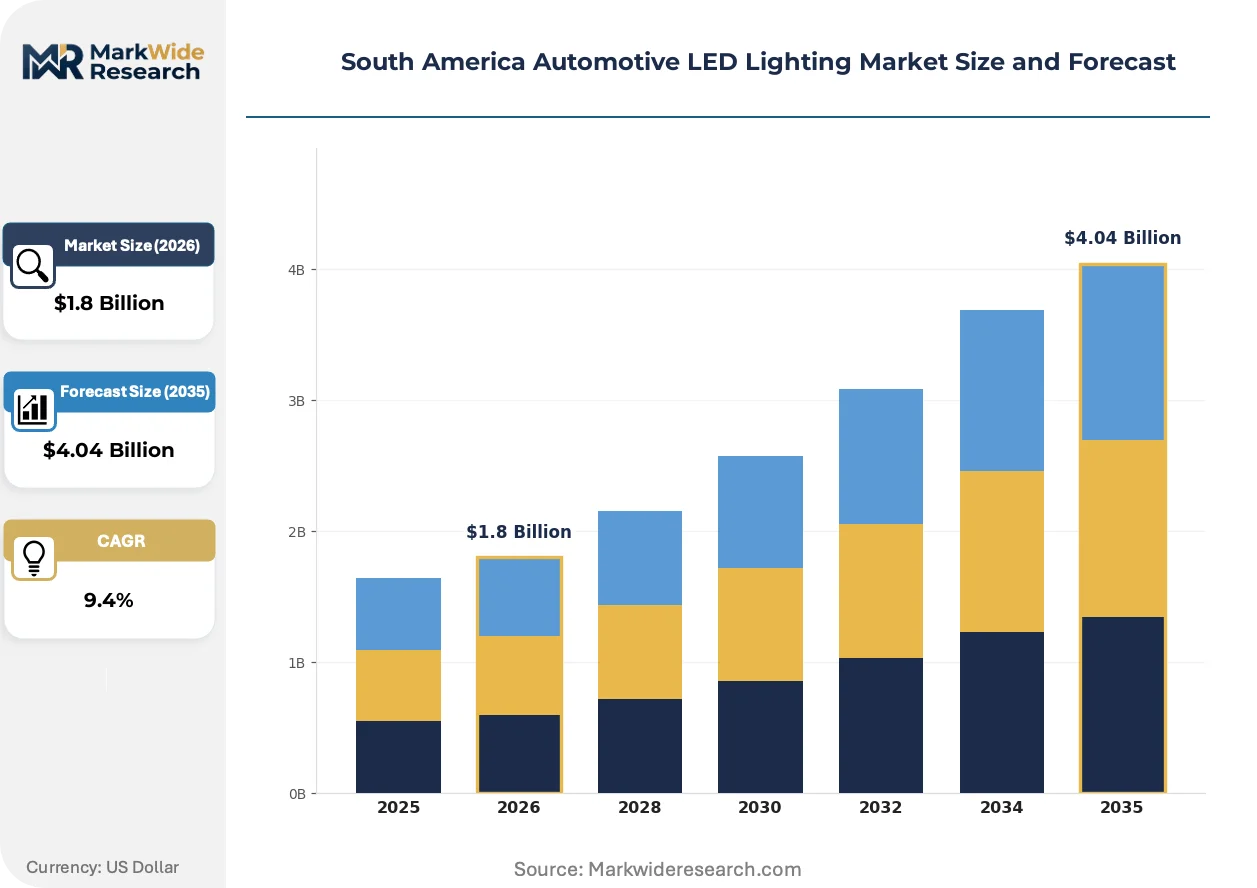
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Headlights, Taillights, Fog Lights, Interior Lights Technology: Halogen, Xenon, OLED, Laser Vehicle Type: Passenger Cars, Commercial Vehicles, Motorcycles, Electric Vehicles Customer Type: OEMs, Aftermarket Providers, Vehicle Assemblers, Tier-1 Suppliers |
| Companies Covered | KOITO MANUFACTURING CO., LTD., HELLA GmbH & Co. KGaA, OSRAM GmbH, Stanley Electric Co., Ltd., Marelli Holdings Co., Ltd., Valeo, Hyundai Mobis, ASX Iluminação, NAOEVO Lighting, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Automotive LED Lighting Market Trends and Innovations
Chip-scale packaging architectures and adaptive beam-pattern algorithms are compressing headlamp module footprints while elevating software content in South American supplier portfolios.
Matrix-beam LED arrays with individually addressable pixels is miniaturizing optical engine dimensions for adaptive driving-beam applications. São Paulo-based assemblers specify these systems for mid-range electric vehicle trims previously limited to static low-beam configurations. The technology is miniaturizing housing volumes by forty percent versus projector-module predecessors while enabling real-time glare-free zone masking.
ANVISA enforcement of IEC 62471 photobiological safety testing tightens documentation requirements for LED source submissions. Brazilian module importers now face extended laboratory queue times for blue-light hazard assessments. Domestic packagers with captive testing capabilities capture accelerated approval pathways for matrix-beam and laser-assisted projection programs.
Fleet procurement departments in Brazil's southeastern corridor consolidate lighting system sourcing under multi-year platform agreements. Direct contracts with semiconductor packagers displace traditional tier-one distributor relationships for high-volume electric vehicle programs. Argentine commercial vehicle operators lag this consolidation, maintaining spot-buy patterns through regional parts importers.
South America Automotive LED Lighting Market Segmentation
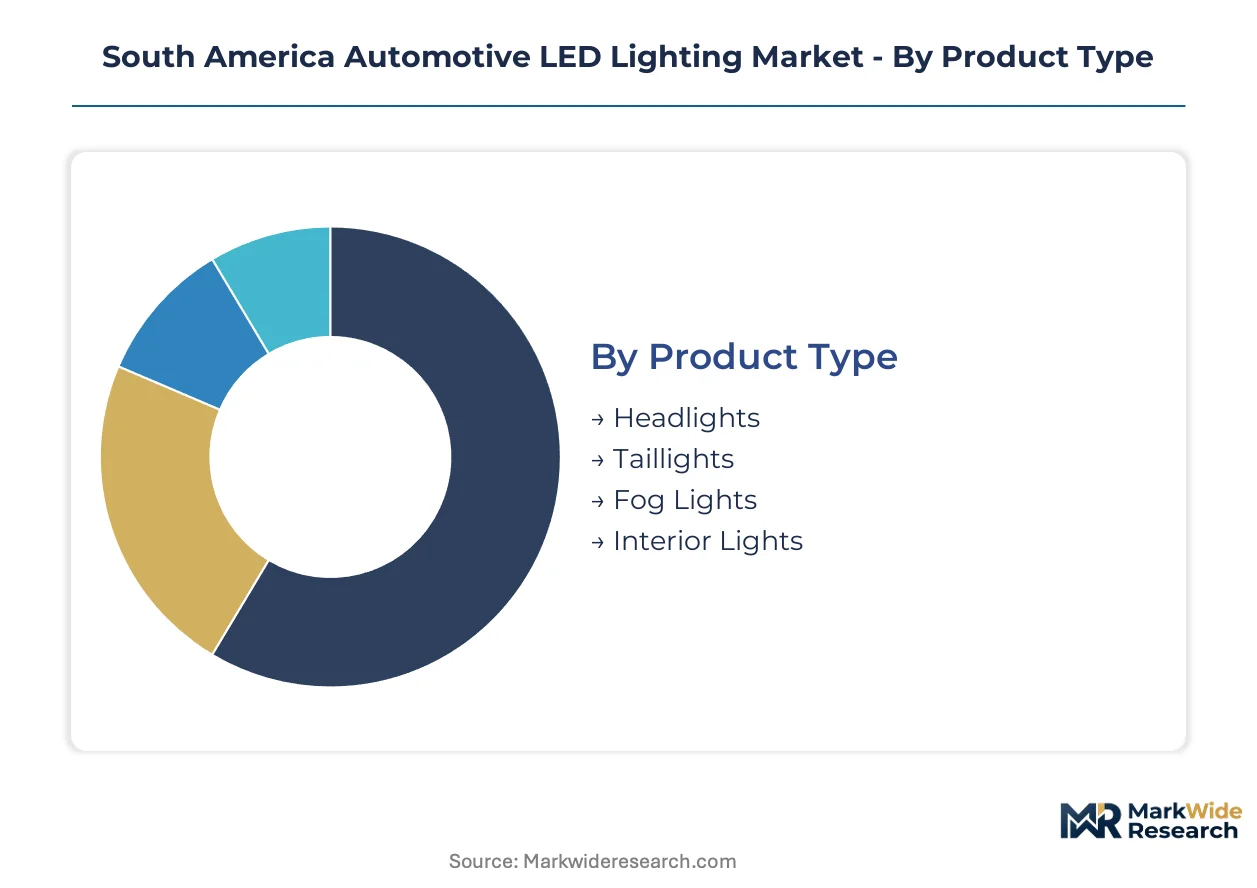
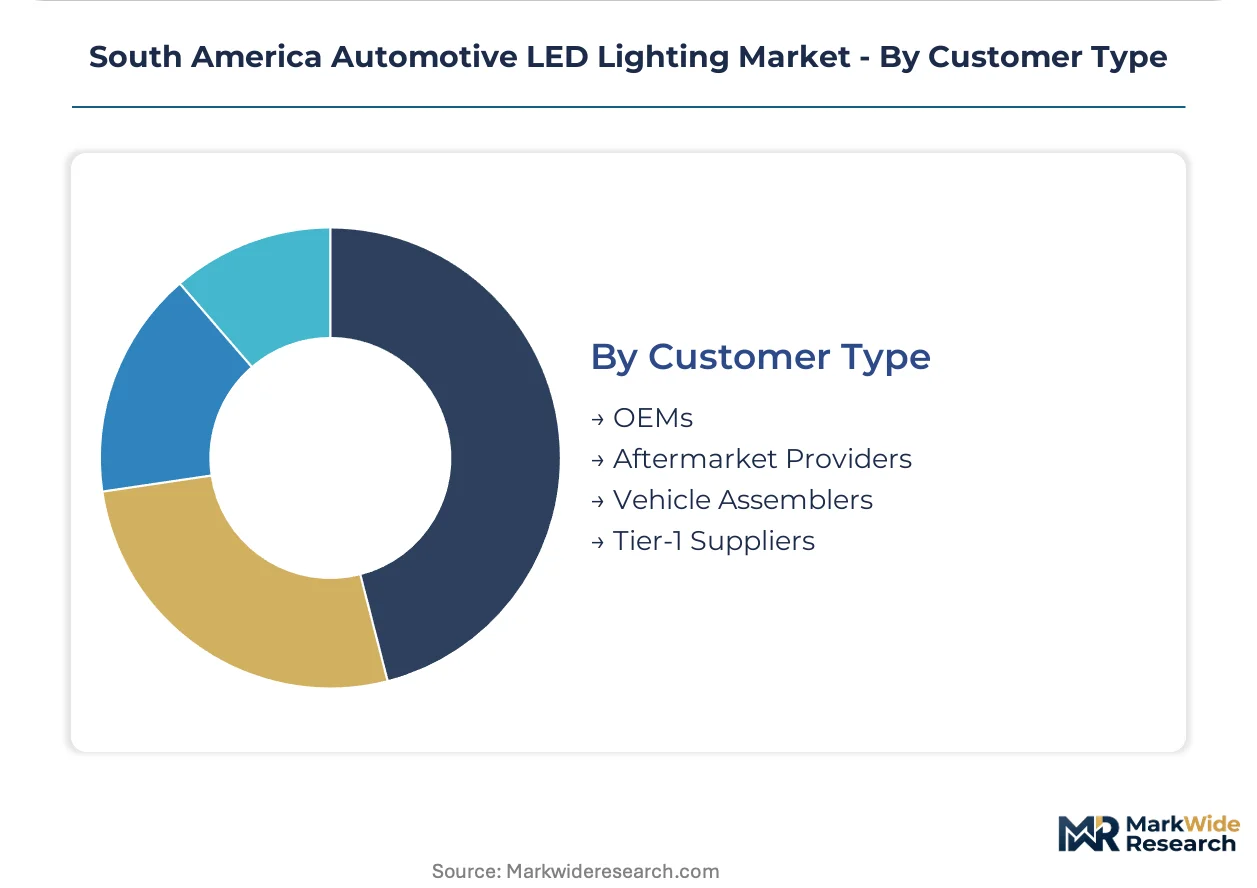
Segmentation in South America automotive LED lighting reveals divergent channel economics across product types and customer tiers. OEM direct procurement concentrates in São Paulo's manufacturing corridor, while aftermarket flows through Argentine distributor networks serving legacy fleet retrofits.
Product Type:
Channel mix varies sharply by product complexity, with matrix-beam headlamp systems flowing exclusively through OEM-Tier-1 direct contracts while interior ambient modules split across authorized dealer networks and independent retrofit channels.
- Headlights:Adaptive driving-beam arrays with individually addressable pixels dominate value capture. São Paulo-based electric vehicle assemblers specify these systems for Mercosur export certification, compressing supplier qualification timelines under ANVISA photobiological mandates.
- Interior Lights:RGB ambient systems and surface-mount OLED panels target premium electric vehicle cabins. Brazilian southeastern manufacturing programs source these through captive semiconductor packagers with in-house thermal simulation capabilities.
- Taillights:Sequential LED signatures penetrate mid-range passenger car trims previously limited to static incandescent configurations.
- Fog Lights:Compact projector modules serve Argentine commercial vehicle segments where total cost-of-ownership calculations delay full LED conversion.
By volume, Interior Lights leads through economy passenger car standard fitment. By growth pace, Headlights is ahead.
Technology:
Cost tier stratification separates legacy incumbent technologies from emerging solid-state architectures, with phosphor-conversion LED designs displacing halogen in Brazilian grid-stabilized applications while laser-assisted projection remains confined to premium OEM programs.
- Halogen:Residual incumbent technology persisting in Argentine commercial vehicle segments. Fleet procurement departments delay conversion despite efficiency penalties, maintaining spot-buy patterns through regional parts importers.
- OLED:Thin-film organic emitters enable conformal surface lighting for dashboard and door-panel integration. Brazilian premium electric vehicle cabins specify these for differentiated ambient configurations.
- Xenon:High-intensity discharge systems retain niche presence in aftermarket retrofit channels serving legacy luxury platforms.
- Laser:Diode-pumped phosphor architectures extend long-range projection for adaptive driving-beam applications. ANVISA documentation requirements constrain import volumes to domestic packagers with captive testing capabilities.
By installed base, Halogen retains plurality share. By displacement velocity, OLED is climbing the fastest.
Vehicle Type:
Application severity drives specification divergence, with electric vehicle platforms mandating full LED fitment for alternator load reduction while commercial vehicle operators in Argentina prioritize durability over efficiency gains.
- Electric Vehicles:Battery-electric platforms specify complete LED exterior and interior systems to minimize auxiliary power draw. São Paulo-based assemblers source matrix-beam headlamps through multi-year platform agreements with semiconductor packagers.
- Passenger Cars:Mid-range trims adopt phosphor-conversion headlamp designs as OEMs extend standard LED fitment downward from premium configurations.
- Commercial Vehicles:Heavy-duty operators in Argentina maintain halogen residual fitment where total cost-of-ownership calculations outweigh efficiency mandates.
- Motorcycles:Compact single-beam LED modules penetrate Brazilian urban commuter segments through aftermarket retrofit channels.
By unit volume, Passenger Cars dominates production. By specification intensity, Electric Vehicles is gaining share fastest.
Customer Type:
Margin concentration aligns with supply chain position, with Tier-1 suppliers capturing thermal-management IP value while aftermarket providers face structural compression as OEM standard fitment displaces retrofit demand.
- OEMs:Vehicle manufacturers consolidate lighting system sourcing under direct semiconductor packager contracts. Brazilian southeastern corridor programs displace traditional distributor relationships for high-volume electric vehicle platforms.
- Tier-1 Suppliers:Module assemblers with captive laboratory access capture accelerated ANVISA approval pathways. Thermal simulation expertise concentrates in São Paulo and Porto Alegre engineering clusters.
- Vehicle Assemblers:São Paulo-based operations specify adaptive driving-beam systems for dual-jurisdiction Brazilian-Argentine export programs.
- Aftermarket Providers:Authorized dealer networks in Argentina integrate LED driver circuit diagnostics with scheduled maintenance to capture residual retrofit volume.
By revenue concentration, OEMs leads procurement value. By margin pressure exposure, Aftermarket Providers faces the steepest structural compression.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Argentine fleet buyers exhibit acute price sensitivity, delaying LED conversion in commercial segments, while Brazilian electric vehicle assemblers absorb premium pricing for matrix-beam systems without volume elasticity.
Brazil
São Paulo-based electric vehicle manufacturers drive specification intensity for adaptive driving-beam headlamps. ANVISA enforces IEC 62471 photobiological safety testing, compressing homologation timelines for domestic packagers. The southeastern manufacturing corridor concentrates thermal-management engineering clusters in São Paulo and Porto Alegre.
Argentina
Commercial vehicle operators maintain halogen residual fitment where total cost-of-ownership calculations outweigh efficiency mandates. The national automotive regulator imposes additional adaptive front-lighting activation-speed requirements atop Mercosur baselines. Buenos Aires-based fleet procurement departments sustain spot-buy patterns through regional parts importers.
Chile
Copper mining fleet operators specify heavy-duty LED work lighting for open-pit extraction vehicles. The country's national mining regulator mandates visibility standards for nighttime haulage operations. Antofagasta-based equipment lessors consolidate lighting system procurement under multi-year platform agreements.
Colombia
Andean urban transit authorities specify LED interior systems for bus rapid transit fleet modernization. The national transport ministry enforces energy efficiency benchmarks for public vehicle procurement. Bogotá-based assemblers source compact projector modules through authorized dealer networks.
South America Automotive LED Lighting Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with captive semiconductor packaging capabilities determining margin capture on matrix-beam systems. The vendor base separates into three strategic archetypes: Japanese and German multinationals with thermal-management IP, Korean and Italian module assemblers with regional calibration centers, and domestic Brazilian packagers with ANVISA-fast-track laboratory access. Competitive moves concentrate on backward integration into gallium-nitride substrate sourcing and geographic expansion through São Paulo engineering cluster establishment.
Within the integrated multinational tier, KOITO MANUFACTURING CO., LTD. and HELLA GmbH & Co. KGaA exemplify divergent thermal-management strategies, while OSRAM GmbH occupies a position emphasizing phosphor-conversion architectures. These three entities anchor the premium specification segment serving Brazilian electric vehicle programs, with each representing distinct approaches to Mercosur voltage stabilization and ambient heat-load engineering.
| Leading Market Players |
|---|
| KOITO MANUFACTURING CO., LTD. |
| HELLA GmbH & Co. KGaA |
| OSRAM GmbH |
| Stanley Electric Co., Ltd. |
| Marelli Holdings Co., Ltd. |
| Valeo |
| Hyundai Mobis |
| ASX Iluminação |
| NAOEVO Lighting |
| Others |
Pricing and Supply Chain Analysis
Sixteen-week lead times for gallium-nitride substrates from East Asian foundries concentrate pricing power among integrated packagers with captive semiconductor lines, forcing Brazilian module assemblers into premium sourcing positions or extended inventory carries.
Pricing Analysis
After-sales service bundling drives lifetime value as authorized dealer networks in Argentina integrate LED driver diagnostics with scheduled maintenance contracts. Three-tier pricing structure across premium matrix-beam, standard phosphor-conversion, and economy passenger car trims reflects certification grade differentiation. Cost compression in economy segments intensifies because OEM standard fitment displaces retrofit volume. Fleet procurement departments in Argentina exhibit acute price sensitivity, while São Paulo-based electric vehicle assemblers absorb premium matrix-beam pricing without volume elasticity.
Supply Chain Analysis
East Asian gallium-nitride foundry concentration anchors upstream chokepoints, with Taiwanese and South Korean substrate suppliers commanding allocation priority during capacity constraints. Brazilian module assemblers draw from Chinese phosphor-conversion architectures, Japanese thermal-management components, and domestic metal-core printed circuit board fabrication. Single-source vulnerability persists for high-brightness emitters subject to geopolitical export controls. Distribution runs through São Paulo engineering clusters serving OEM direct contracts and Buenos Aires-based regional parts importers serving aftermarket channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as São Paulo-based electric vehicle assemblers consolidate lighting system sourcing under multi-year platform agreements, displacing traditional tier-one distributor relationships.
For Market Incumbents: Secure thermal-management IP through localized calibration center expansion in Brazil's southeastern corridor. Deepen backward integration into gallium-nitride substrate sourcing to mitigate East Asian foundry allocation risk. ANVISA photobiological testing mandates compress homologation timelines, rewarding domestic packagers with captive laboratory access. For New Entrants and Emerging Players: Aftermarket diagnostic service gaps in Argentine commercial vehicle segments offer white-space entry points where legacy halogen fleets delay LED conversion. Target Buenos Aires-based fleet operators through spot-buy pattern disruption and authorized dealer network partnerships. Bundle LED driver circuit maintenance with existing service contracts to bypass OEM standard fitment displacement. For Investors and Strategic Acquirers: Carve-out targets emerge from multinational automotive lighting parents seeking portfolio rationalization outside core geographies. Long-term viability hinges on Mercosur regulatory convergence and electric vehicle platform standardization. Monitor ANVISA-Mercosur regulatory harmonization progress as the inflection signal for capital deployment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into GaN Substrates | Captive sourcing from Taiwanese foundries insulates Brazilian packagers from allocation volatility. |
| ANVISA Fast-Track Laboratory Certification | Domestic testing capabilities accelerate matrix-beam homologation cycles versus importer queues. |
| São Paulo Engineering Cluster Expansion | Localized thermal simulation expertise supports junction-temperature modeling below 150°C thresholds. |
| Aftermarket Service Bundling | Authorized dealer networks in Argentina capture retrofit volume through diagnostic-maintenance integration. |
| Phosphor-Conversion Voltage Stabilization | Grid-optimized designs penetrate economy trims previously served by halogen retrofit channels. |
Research Methodology
Operator-level perspectives from Tier 1 supplier procurement managers, OEM platform engineers, aftermarket distributors, and ANVISA regulatory affairs specialists anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation through vehicle production databases, Mercosur technical regulation filings, and customs import records. Bottom-up segment sizing triangulated against top-down macroeconomic anchors across the analysis window.
Sensitivity analysis tested forecast robustness across voltage fluctuation scenarios, gallium-nitride price volatility bands, and regulatory timeline compression assumptions. The analytical framework modeled segmentation across vehicle class, propulsion architecture, content per vehicle, and regional production cluster. CAGRs derived from installed base evolution, replacement cycle dynamics, and technology displacement curves specific to adaptive driving-beam adoption trajectories.
Material uncertainties — gallium-nitride substrate allocation disruptions, Argentine-Brazilian regulatory divergence, and commercial vehicle total cost-of-ownership recalculations — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding electric vehicle platform standardization and ANVISA enforcement consistency. Practitioners should keep alternative scenarios live as Mercosur electromagnetic compatibility certification timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Pediatric Measuring Devices Market
Others
Dry Washer Market
Others
India 3D Printing Construction Market
Others
Connected TV Market
Others
Latin America Domestic CEP Market
Others
Global Luxury High End Furniture Market
Others
Qatar Smartphone Market
Others
Agitation System Market
Others
Mexico Retail Market
Others
Remanufacturing-as-a-Service (RaaS) Market
Others
Global Bio-Based Chemicals Market
Others
Global Multi-Access Edge Computing Market
Others
Germany 3D Printing Construction Market
Others
Education and Learning Analytics Market
Others
Middle East and Africa Medium Voltage Switchgear Market
Others
Metal Air Battery Market