
 Stichtite Market | 2026-2036
Stichtite Market Size, Share, and Industry Trends Forecast 2026-2036
Stichtite Market Outlook
Collector demand is collapsing the historical dominance of jewelry manufacturers as the primary buyer archetype for premium-grade material. Gemrock Australia leverages its Tasmanian deposit access to sustain supply continuity for specimen-grade output. Tasmanian Gemstone Mining anchors its position through direct relationships with museum and private collectors. Shepherd Mining competes via specialized cutting and polishing capabilities that differentiate finished stones from raw export competitors.
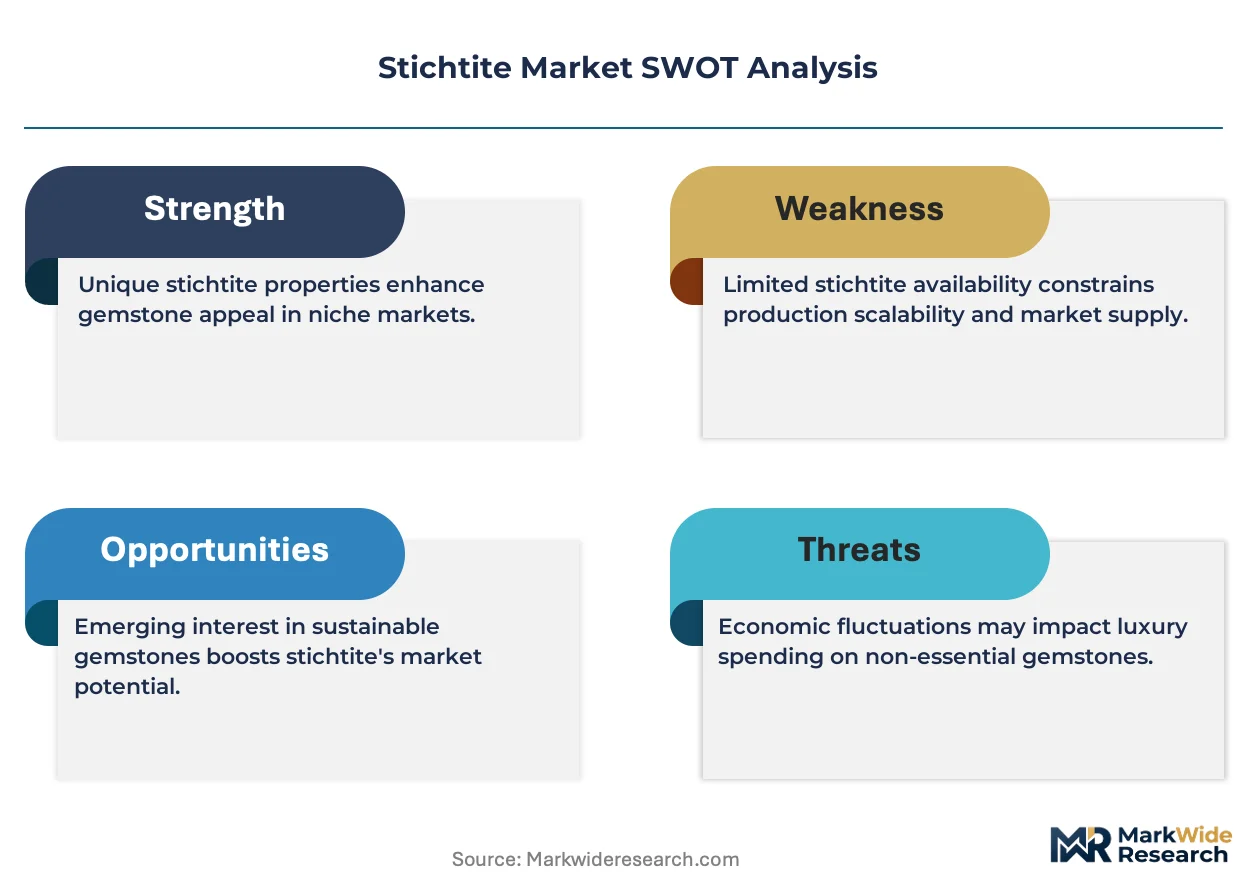
Stichtite is a hydrated magnesium chromium carbonate mineral, typically occurring in association with serpentine and displaying distinctive purple to pink coloration with Mohs hardness of 1.5–2.0, which limits its use to protected ornamental applications. The mineral serves primarily as a lapidary material for cabochons, decorative inlays, and metaphysical healing products where aesthetic rarity commands premium positioning. Raw Stichtite dominates volume flows while Stichtite Powder captures expanding margins from wellness product manufacturers seeking consistent material feedstock. The Jewelry application segment retains established value pools though Healing Products represents the fastest-growing consumption channel as alternative wellness markets deepen mineral ingredient sourcing.
Australia's state mineral heritage frameworks and Environment Protection Authority site-specific approvals constrain extraction rates and shape deposit access priorities. The country's national gemstone export certification requirements administered through federal trade authorities further structure market participation thresholds. Stakeholders must monitor evolving heritage designation expansions that could restrict new mining tenements across the Dundas mineral field region.
Market Dynamics
Collector demand for rare mineral specimens is accelerating faster than traditional jewelry consumption, reshaping extraction priorities and pricing hierarchies across Australian deposit zones. This behavioral shift concentrates value capture among operators with direct museum and private collector relationships.
Growth Catalysts
- Wellness Product Manufacturing:Alternative healing markets are deepening mineral ingredient sourcing for metaphysical applications, creating consistent feedstock demand for Stichtite Powder.
- Australian Heritage Mineral Frameworks:Tasmania and Western Australia's deposit protections limit raw extraction volumes, artificially constraining supply and elevating scarcity premiums for specimen-grade material.
- Lapidary Specialization:Advanced cabochon cutting and polishing capabilities differentiate finished stones from raw export competitors, capturing margin expansion in ornamental applications.
Market Restraints
- Mohs Hardness Limitation:The mineral's 1.5–2.0 hardness rating restricts applications to protected ornamental uses, excluding wear-resistant jewelry categories.
- Deposit Geographic Concentration:Australia's Dundas mineral field and Tasmanian sites represent the primary high-grade sources, creating supply vulnerability to state-level heritage designation expansions.
- Serpentine Association Dependency:Stichtite's typical occurrence alongside serpentine complicates pure-mineral recovery and elevates processing costs.
Strategic Opportunities
- Healing Products Channel Expansion:Metaphysical wellness retail networks represent underpenetrated distribution infrastructure for finished cabochons and carved specimens.
- Digital Collector Marketplaces:Specialized mineral auction platforms are displacing traditional dealer networks for specimen-grade transactions.
- Federal Export Certification Alignment:Australia's national gemstone export requirements administered through federal trade authorities create compliance-based barriers that favor established tenement holders.
Industry Challenges
- Heritage Tenement Approval Timelines:Environment Protection Authority site-specific approvals extend extraction authorization cycles, freezing capital deployment.
- Specimen Grading Standardization:Absence of unified quality frameworks for collector-grade material creates pricing opacity and transaction friction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stichtite Market |
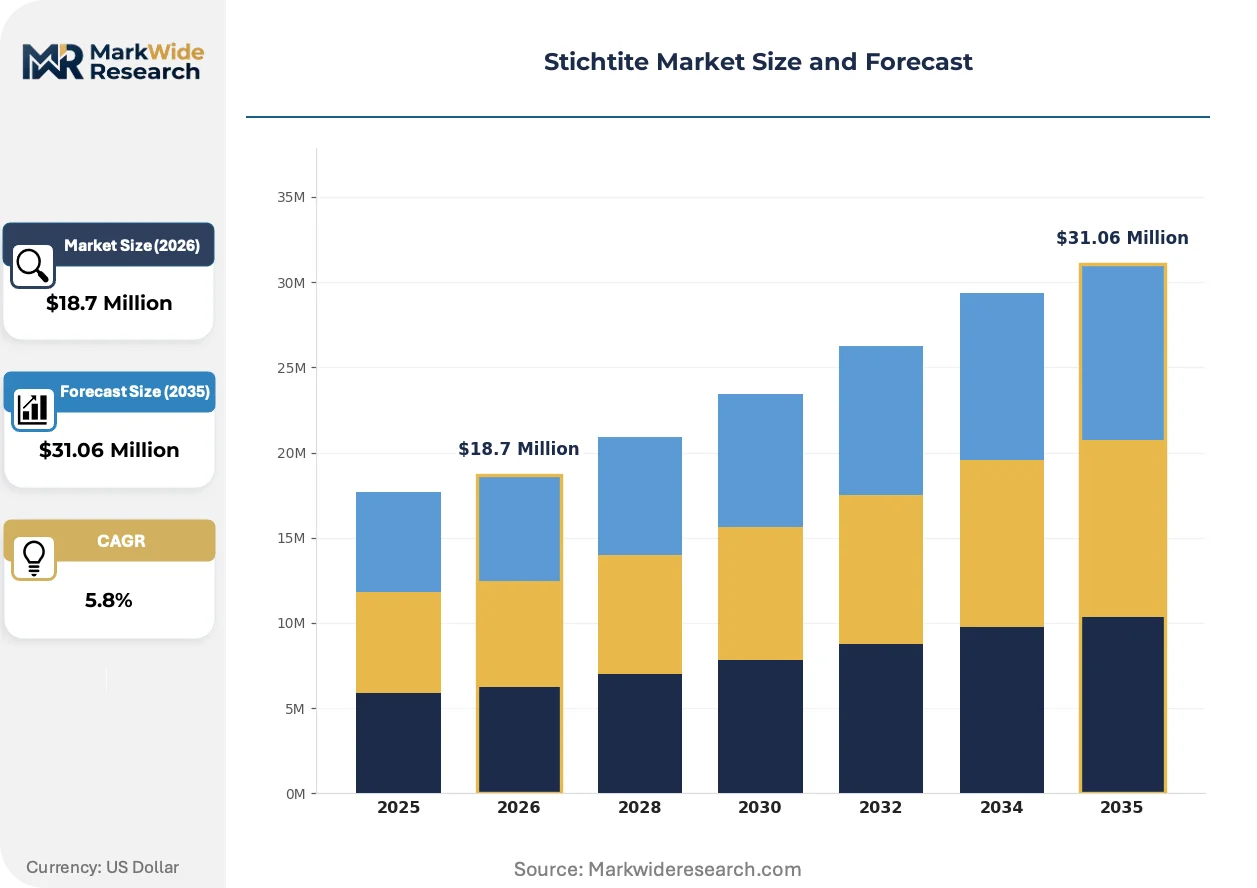
| Market Size in 2026 | $18.7 Million |
| Market Size in 2035 | $31.06 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Raw Stichtite, Processed Stichtite, Stichtite Powder, Stichtite Stones Application: Jewelry, Decorative Items, Construction Materials, Healing Products End User: Artisans, Retailers, Manufacturers, Collectors Distribution Channel: Online Retail, Direct Sales, Specialty Stores, Trade Shows |
| Companies Covered | Gemrock Australia, Tasmanian Gemstone Mining, Stichtite Hill Mining, Australian Mineral Exports, Shepherd Mining, Dundas Mineral Field, Bottrill Minerals, Macquarie Minerals, Serpentine Hill Resources, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stichtite Market Strategic Shifts
Processing technology and distribution infrastructure are actively fragmenting the historical unity of raw export and finished goods markets. These developments are creating distinct competitive arenas with divergent capability requirements.
Advanced stabilization and resin-infusion techniques are bifurcating the lapidary supply base. High-end cabochon producers are adopting vacuum-pressure stabilization to expand workable material volumes. This technology is enabling softer rough to enter jewelry-grade finishing pipelines while compressing margins for untreated specimen purists.
Tasmania's state mineral heritage frameworks are tightening extraction permit conditions under Environment Protection Authority oversight. These constraints are elevating tenement security values and pushing operators toward heritage-compliant site rehabilitation bonds. Small-scale miners are responding by consolidating claims to spread compliance costs.
Museum and private collector procurement is consolidating through specialized mineral shows and invitation-only preview events. Traditional wholesale dealer networks are losing volume to direct miner-collector relationships. This pattern is most visible in Australian and North American collector communities where provenance documentation commands premium positioning.
Stichtite Market Segmentation
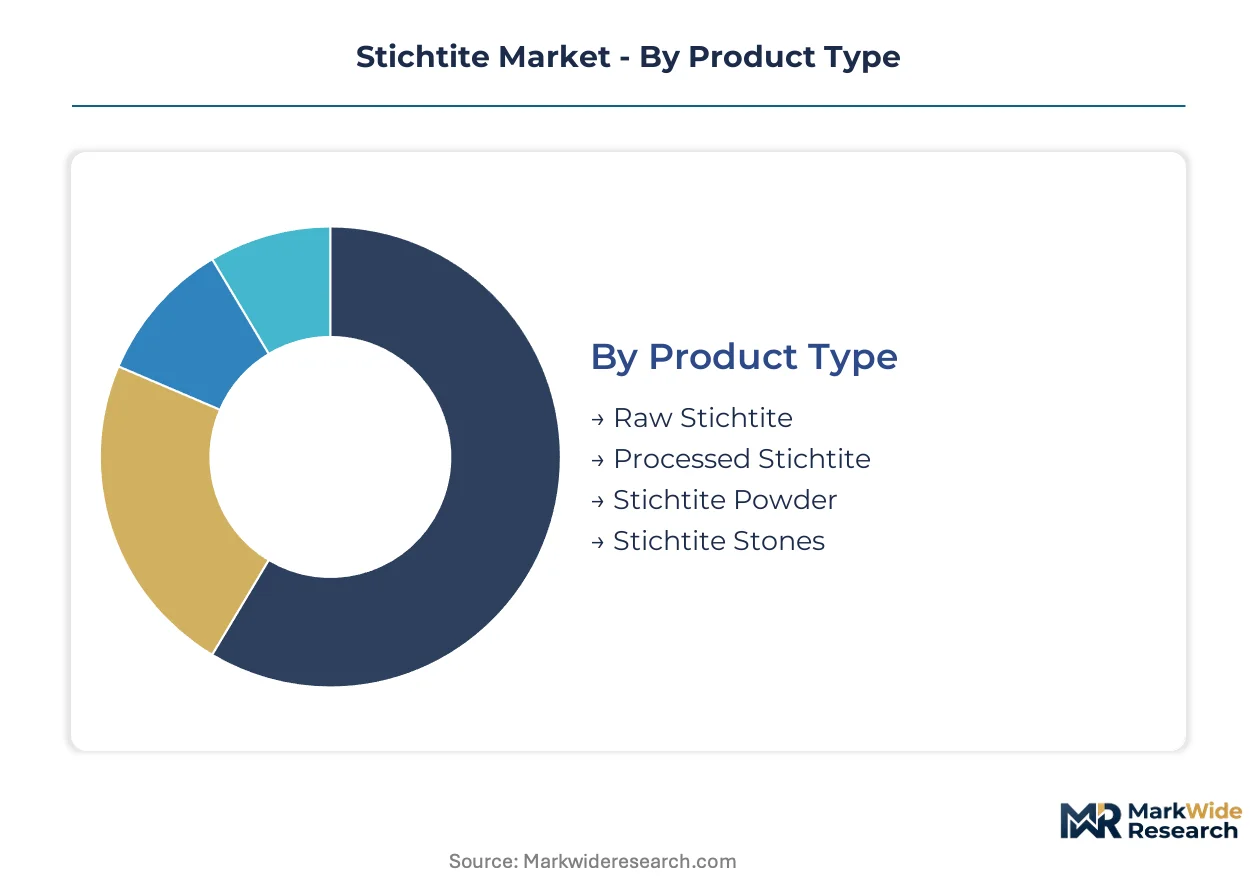
Stichtite's extreme softness and geographic concentration in Australian heritage zones fragment value capture across distinct processing stages and buyer archetypes. Segmentation reveals how raw material constraints propagate through distribution channels and end-use applications.
Product Type:
Australian heritage frameworks constrain domestic extraction volumes while export-led demand concentrates in processed and powder forms for international wellness and lapidary markets.
- Raw Stichtite:Unprocessed rough material extracted from Tasmanian and Western Australian deposits, typically associated with serpentine host rock. Collector demand in North America and Europe absorbs premium specimen-grade output, though heritage permit limitations restrict volume scalability.
- Processed Stichtite:Stabilized and cut material prepared for ornamental applications through vacuum-pressure resin infusion. Lapidary specialists in Australia and the United States command margin premiums through advanced cabochon finishing capabilities that differentiate finished stones from raw competitors.
- Stichtite Powder:Finely milled material serving metaphysical wellness product manufacturers seeking consistent feedstock for crystal healing formulations and decorative inlay compounds.
- Stichtite Stones:Carved decorative objects and display specimens produced for museum acquisition and private collector markets, where provenance documentation from Dundas mineral field or Tasmanian origins commands positioning premiums.
Raw Stichtite commands the established base. The steepest expansion runs through Stichtite Powder.
Application:
Cost tier differentiation separates protected ornamental uses from volume wellness applications, with hardness limitations excluding wear-intensive categories regardless of price positioning.
- Jewelry:Cabochon-set pieces in protected settings such as pendants and brooches, where Mohs hardness of 1.5–2.0 precludes ring or bracelet applications. Australian lapidaries supply domestic retailers while specialized cutters serve North American and European wholesale channels.
- Decorative Items:Inlay work, bookends, and display objects leveraging the mineral's distinctive purple-pink coloration against serpentine matrix. Tasmanian producers dominate this segment through heritage-compliant extraction tenements.
- Construction Materials:Limited architectural inlay and decorative surfacing applications requiring stabilization treatment to prevent abrasion damage in high-contact installations.
- Healing Products:Metaphysical retail networks distribute raw specimens, carved forms, and powder-based formulations through wellness channels in Australia, Canada, and the United States.
Jewelry retains the revenue concentration. Healing Products is climbing the fastest as alternative wellness markets deepen mineral ingredient sourcing.
End User:
Customer type fragmentation splits volume procurement between institutional collectors and dispersed artisan fabricators with diverging specification requirements.
- Artisans:Independent lapidary workers and jewelry makers purchasing small-lot rough material through specialty suppliers and direct miner relationships.
- Retailers:Metaphysical shops, museum stores, and gemstone dealers sourcing finished cabochons and carved specimens for consumer resale.
- Manufacturers:Wellness product companies and decorative inlay producers requiring consistent powder and stabilized material feedstock at scale.
- Collectors:Private individuals and institutional museums acquiring specimen-grade material with documented provenance from specific Australian deposits.
Collectors command premium positioning through direct miner relationships. Manufacturers are gaining share fastest as wellness product volume requirements expand.
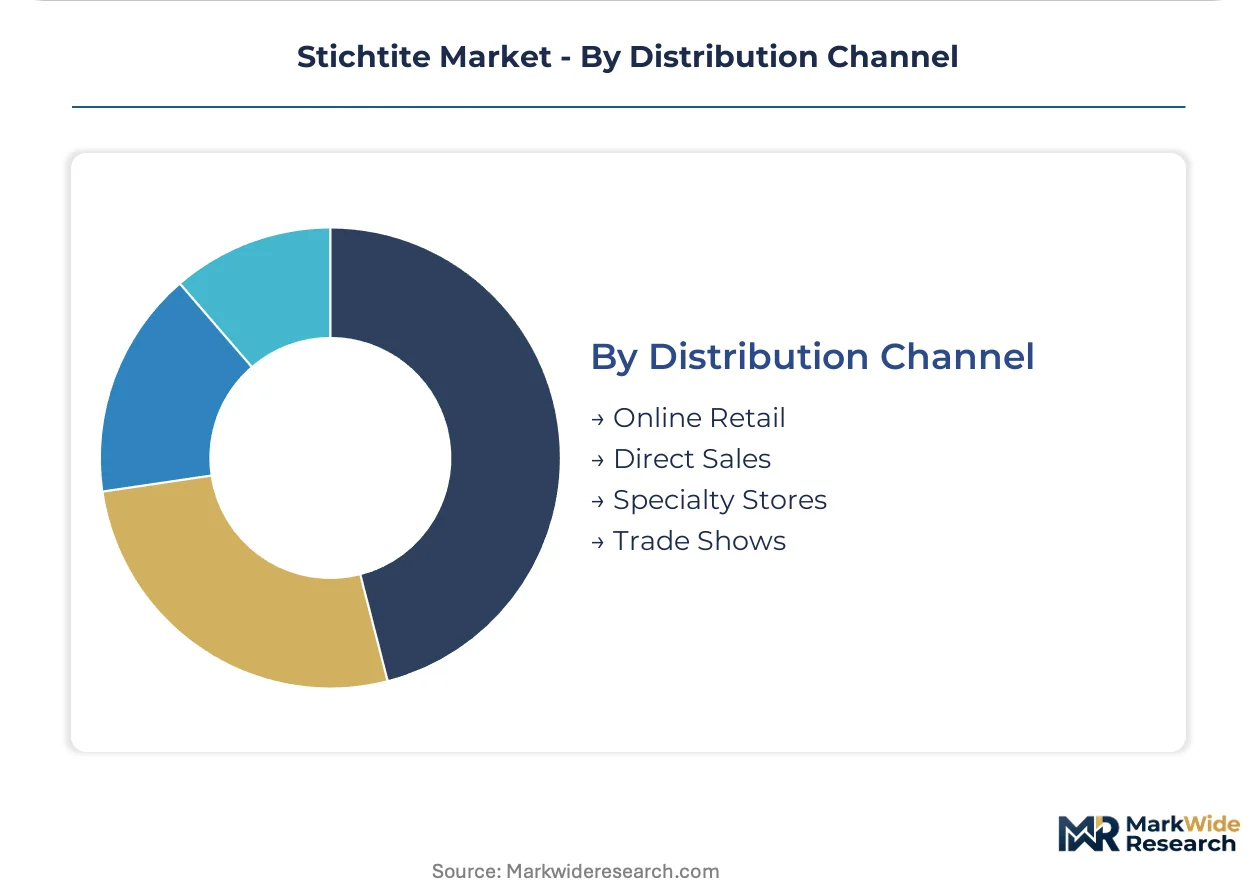
Distribution Channel:
Supply concentration in Australian heritage zones shapes channel economics, with direct sales capturing collector premiums and digital platforms displacing traditional dealer intermediaries.
- Online Retail:Specialized mineral marketplaces and wellness e-commerce platforms connecting Australian producers to North American and European end users, reducing traditional wholesale markups.
- Direct Sales:Miner-to-collector transactions at invitation-only preview events and museum procurement programs, where provenance documentation from Tasmanian or Dundas field origins supports pricing premiums.
- Specialty Stores:Metaphysical retailers and lapidary supply shops serving artisan fabricators with small-lot rough and finished cabochon inventory.
- Trade Shows:Tucson Gem and Mineral Show and regional Australian exhibitions where specimen-grade material changes hands through established dealer networks.
Direct Sales commands the established base. Online Retail is expanding most quickly as digital collector marketplaces displace traditional intermediaries.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Burnie in northwest Tasmania anchors Australian stichtite export logistics, with dedicated mineral handling infrastructure connecting Dundas field production to Asian and North American collector markets. This maritime asset underwrites the geography's centrality despite extraction volume constraints.
Australia
Collector demand from North American museums and private buyers absorbs premium Tasmanian specimen output. The Environment Protection Authority administers site-specific extraction permits under Tasmania's Mineral Resources Development Act. The Dundas mineral field in Western Australia concentrates high-grade deposit activity where heritage-compliant operators maintain tenement security through rehabilitation bonds.
United States
Metaphysical wellness retailers in Arizona and Colorado drive powder and carved specimen procurement for crystal healing formulations. The Federal Trade Commission monitors gemstone marketing claims under its Jewelry Guides enforcement framework. Tucson's annual Gem and Mineral Show serves as the primary North American specimen trading venue where Australian provenance commands positioning premiums.
Canada
Vancouver-based lapidary specialists source stabilized rough for cabochon finishing serving domestic jewelry channels. Health Canada regulates mineral-based wellness product ingredient disclosures through its Natural Health Products Directorate. The Pacific Northwest collector corridor linking British Columbia to Washington State deepens direct miner relationships bypassing traditional dealer networks.
United Kingdom
London auction houses and Oxford museum acquisition programs anchor European specimen demand for documented Tasmanian material. The British Geological Survey maintains mineral heritage classification standards influencing institutional procurement criteria. The Cotswolds lapidary cluster processes small-lot rough through specialized cutting workshops serving heritage jewelry makers.
Germany
Stuttgart-area metaphysical distributors import Australian powder for crystal healing product manufacturing serving Central European wellness markets. ECHA's REACH framework governs mineral substance registration requirements for imported lapidary materials. The Idar-Oberstein gemstone cutting tradition accommodates soft-stone specialization for protected ornamental applications.
Stichtite Market Competitive Environment
Concentration sits with heritage-tenement holders possessing direct Environment Protection Authority approvals. The vendor base spans fewer than ten active extraction operators across Tasmania and Western Australia, creating tiered supply access where tenement security duration separates strategic positioning. Two archetypes dominate: deposit-control specialists leveraging state mineral heritage relationships, and lapidary-integrated processors capturing margin through finished goods differentiation. Competitive moves center on tenement consolidation to spread compliance costs and direct-to-collector digital channel development.
Among Tasmanian deposit operators, Gemrock Australia and Tasmanian Gemstone Mining occupy positions within the heritage-access archetype, leveraging state-level extraction permits to sustain specimen-grade output continuity. Shepherd Mining exemplifies the lapidary-integration vector, differentiating through specialized cutting capabilities that elevate finished stones above raw export competitors. Stichtite Hill Mining and Bottrill Minerals represent smaller-scale tenement holders consolidating claims to distribute Environment Protection Authority compliance burdens.
| Leading Market Players |
|---|
| Gemrock Australia |
| Tasmanian Gemstone Mining |
| Stichtite Hill Mining |
| Australian Mineral Exports |
| Shepherd Mining |
| Dundas Mineral Field |
| Bottrill Minerals |
| Macquarie Minerals |
| Serpentine Hill Resources |
| Others |
Value Chain & Pricing Dynamics
Ninety-day extraction permit cycles from Tasmania's Environment Protection Authority compress inventory turnover and amplify pricing power for heritage-tenement holders with secured Dundas field access. Supply scarcity from state-level mineral protections feeds directly into specimen-grade premiums, while powder feedstock contracts stabilize margins for wellness product manufacturers.
Pricing Analysis
Three-tier pricing structure across museum-grade specimens, lapidary-standard stabilized rough, and bulk powder feedstock segments the market. Price differentiation separates documented Tasmanian provenance from Western Australian material, with vacuum-pressure stabilization adding margin capture for finished cabochon producers. Pricing pressure stems from Environment Protection Authority compliance cost inflation spreading across consolidated tenements. Artisan buyers exhibit highest price sensitivity, while institutional collectors absorb scarcity premiums for specimen-grade output with museum acquisition documentation.
Supply Chain Analysis
Container availability constraints on the Burnie-to-Hong Kong trade lane elevate inbound logistics costs for Australian exporters serving Asian collector markets. Supply concentrates in Tasmania and Western Australia, with Dundas mineral field deposits and Tasmanian heritage zones anchoring raw material flows. Processing draws from serpentine host rock association, vacuum-pressure stabilization equipment, and resin infusion compounds. Single-source vulnerability runs through Environment Protection Authority permit concentration. Distribution runs through direct miner-collector relationships, specialized mineral auction platforms, and metaphysical wellness retail networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Collector demand acceleration and wellness product manufacturing expansion are disrupting traditional jewelry-centric value capture, with Australia's heritage mineral frameworks acting as the regulatory inflection constraining scalable supply response.
For Market Incumbents: Secure tenement consolidation across adjacent Dundas field claims to distribute Environment Protection Authority rehabilitation bond burdens. Lock in direct digital marketplace relationships with North American museum procurement officers before specialized auction platforms consolidate collector access. Heritage permit security duration separates strategic positioning from commodity raw exporters.
For New Entrants and Emerging Players: Anchor in German and Canadian metaphysical wellness distribution networks where Australian powder feedstock penetration remains underdeveloped. Target carved specimen fabrication for museum store retail channels, bypassing established lapidary specialist intermediaries. Pursue white-label supply agreements with crystal healing product manufacturers seeking consistent material certification.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified mining parents with non-core Tasmanian gemstone assets held for heritage compliance portfolio balance. Long-term viability hinges on wellness product channel depth rather than jewelry market cyclicality. Monitor Environment Protection Authority permit queue length as the signal indicating tenement scarcity inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Tenement Consolidation | Spreads Tasmania's Environment Protection Authority compliance costs across larger claim portfolios. |
| Direct Digital Marketplace Development | Bypasses traditional mineral dealer networks for specimen-grade collector transactions. |
| Vacuum-Pressure Stabilization Investment | Expands workable rough volumes for jewelry-grade cabochon finishing pipelines. |
| Wellness Product Channel Partnership | Secures long-term powder feedstock offtake from German and Canadian metaphysical distributors. |
| Museum Provenance Documentation Program | Commands scarcity premiums through Tasmanian and Dundas field origin certification. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with lapidary specialists, museum acquisition curators, metaphysical wellness product manufacturers, and Environment Protection Authority compliance officers. Secondary validation drew from Australian Mineral Resources Development Act filings, federal gemstone export certification records, customs trade data, and Dundas mineral field geological surveys. Bottom-up tenement analysis and top-down collector market sizing were triangulated against wellness product manufacturing feedstock demand estimates.
Across the analysis window, projections incorporate product type segmentation by raw, processed, powder, and carved specimen forms; application segmentation across jewelry, decorative items, and healing products; and end user segmentation distinguishing artisan, retailer, manufacturer, and collector archetypes. CAGRs were derived from heritage permit issuance trajectories and wellness channel penetration curves. Forecast inputs include Environment Protection Authority approval timeline elasticity and digital marketplace transaction velocity.
Decision-makers should treat outputs as directional under sustained heritage designation expansion and wellness product regulatory stability assumptions; material deviation would warrant model refresh. Specific risk factors encompass Tasmania state-level mining policy shifts and Health Canada ingredient disclosure tightening. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Storm Surge Barriers Market
Others
5G Tester Market
Others
Global B2B Enterprise and Industrial Wearables Market
Others
Underwater Light Market
Others
Small Office Home Office (SOHO) Servers Market
Others
Hookah Tobacco Market
Others
Embedded Computer Market
Others
Tripod Market
Others
Folding Mobile Phone Market
Others
Middle East and Africa Surface Analysis Market
Others
Exosome Technologies Market
Others
Versatile Video Coding Market
Others
Propanil Market
Others
Industrial Personal Computer Market
Others
Global Learning Analytics Market
Others
Europe Travel Retail Market