
 Aerospace Engineering Services Market | 2026-2036
Aerospace Engineering Services Market Size, Share, and Industry Trends Forecast 2026-2036
Aerospace Engineering Services Market Analytics
Modular service bundling is broadening buyer choice as OEMs unbundle legacy turnkey contracts into discrete design, testing, and certification modules. Collins Aerospace leverages its vertical integration across avionics and aerostructures to sustain engineering margins on complex integration programs. Quest Global anchors its position through deep specialization in flight physics and structural analysis for tier-one suppliers.
Aerospace engineering services encompass the technical design, analysis, verification, and certification support applied to aircraft, spacecraft, and unmanned systems, spanning disciplines from computational fluid dynamics and finite element modeling to systems integration and airworthiness compliance. The primary purpose is to reduce development risk, accelerate certification timelines, and transfer specialized expertise from external partners to OEM engineering teams. Design services command the largest revenue pool given their centrality to new aircraft programs, while certification work carries the highest margins due to regulatory complexity and limited supplier pools. Testing services are expanding fastest as digital twin adoption pushes physical validation toward later development stages.
FAA airworthiness standards, EASA certification specifications, and ISO 9100 quality frameworks govern market access and shape service provider qualification requirements across major aviation jurisdictions. These regulatory layers elevate barriers for uncredentialed entrants while creating sustained demand for compliance-oriented engineering work. Stakeholders must weigh the trade-off between building captive certification capabilities and outsourcing to accredited specialists as program complexity and regulatory scope continue to expand.
Market Dynamics
Airframers are unbundling monolithic engineering contracts into discrete modules, forcing service providers to compete on specialized capability depth rather than turnkey scale. This fragmentation is concentrating margin in certification and flight-physics niches while commoditizing routine design work.
Growth Catalysts
- FAA Airworthiness Directives:Tightening documentation mandates for aging fleet retrofits sustain demand for accredited DER services across structural repair and avionics upgrade programs.
- Artemis Program Requirements:NASA's lunar return timeline accelerates demand for propulsion thermal analysis and human-rating certification expertise in the United States.
- Digital Twin Adoption:Physics-based simulation platforms compress physical test cycles, expanding outsourcing of model validation and correlation work to specialized engineering houses.
Market Restraints
- Specialized Talent Scarcity:Finite pools of cleared stress engineers and DER-qualified analysts in Wichita, Seattle, and Toulouse constrain capacity expansion regardless of contract backlog.
- Certification Timeline Rigidity:EASA's frozen certification specifications for novel propulsion architectures delay revenue recognition on electric and hydrogen aircraft programs.
- Input Cost Volatility:High-performance computing cluster pricing and ANSYS, Dassault Systèmes software licensing fees escalate fixed cost bases for simulation-heavy service providers.
Strategic Opportunities
- Urban Air Mobility Certification:FAA's Powered Lift rulemaking creates first-mover advantage for engineering firms building eVTOL flight-test and human-factors capabilities.
- India Defense Offset Localization:Ministry of Defence indigenization mandates for fighter and transport programs open engineering partnerships with Hindustan Aeronautics and private sector tier-one suppliers.
- Sustainable Aviation Fuel Pathway Analysis:Combustion simulation and emissions modeling converge as airlines seek external validation of SAF blend performance for fleet renewal planning.
Industry Challenges
- Security Clearance Bottlenecks:ITAR and classified program access delays stretch onboarding timelines for defense-adjacent engineering teams beyond twelve months.
- Legacy System Integration:Boeing and Airbus proprietary CAD environments and configuration management tools fragment toolchains, forcing costly dual-platform staffing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aerospace Engineering Services Market |
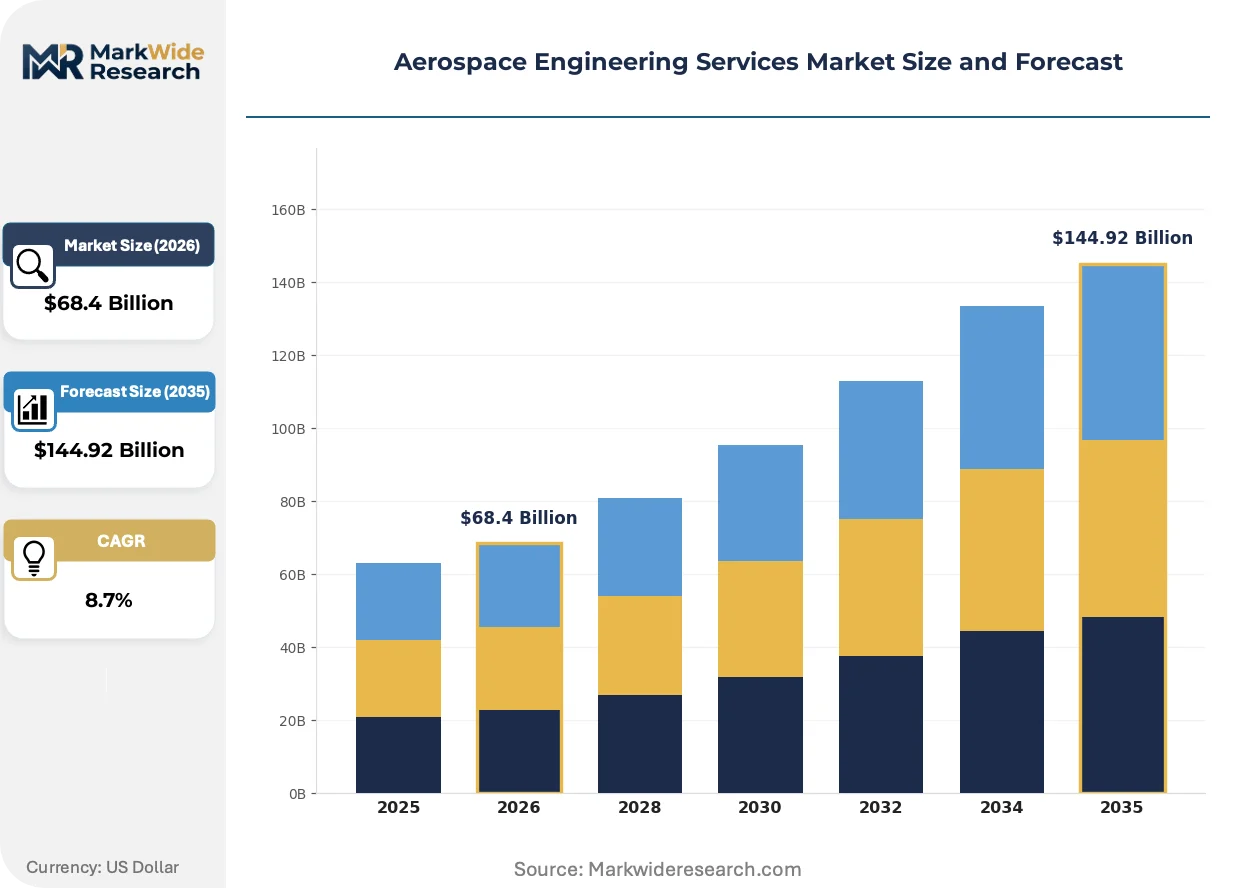
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $144.92 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Design, Testing, Consulting, Certification End User: Commercial Aircraft, Military Aviation, Space Exploration, UAVs Technology: Aerodynamics, Structural Analysis, Avionics, Propulsion Application: Flight Simulation, Maintenance, Safety Analysis, Compliance |
| Companies Covered | Collins Aerospace, Alten Group, BAE Systems, Honeywell International, L&T Technology Services, Quest Global, CYIENT, Safran Engineering Services, Capgemini, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aerospace Engineering Services Market Evolving Landscape
Computational methods are displacing physical prototyping across aerostructures and propulsion, compressing development timelines while elevating the value of simulation correlation expertise. Three forces are reshaping how engineering services are scoped, priced, and delivered.
Generative design algorithms are automating topology optimization for additive-manufactured brackets and ducting, reducing iteration cycles from weeks to hours. Tier-one suppliers at Spirit AeroSystems and GKN Aerospace deploy these tools on next-generation narrowbody programs. The technology is automating load-path analysis previously performed by senior stress engineers, reallocating human expertise toward validation and edge-case resolution.
EASA's CS-25 Amendment 26 tightens damage tolerance and fatigue requirements for composite primary structures, mandating expanded test matrices and statistical substantiation. European airframers face extended certification timelines for carbon-fiber wing and fuselage designs. Suppliers in Germany, France, and Italy are building captive non-destructive inspection and structural health monitoring capabilities to retain program access.
Fixed-price module contracts are displacing time-and-materials arrangements for design and analysis work, transferring development risk to engineering service providers. Boeing's supplier development organization and Airbus' engineering procurement teams pilot outcome-based pricing on discrete work packages. This compression is most visible in aerostructures detail design, where Indian and Eastern European providers compete on guaranteed deliverable pricing.
Aerospace Engineering Services Market Segmentation
Engineering service procurement in aerospace hinges on risk allocation between OEMs and external partners. Buyers segment contracts by technical complexity, regulatory exposure, and program phase to optimize specialist deployment.
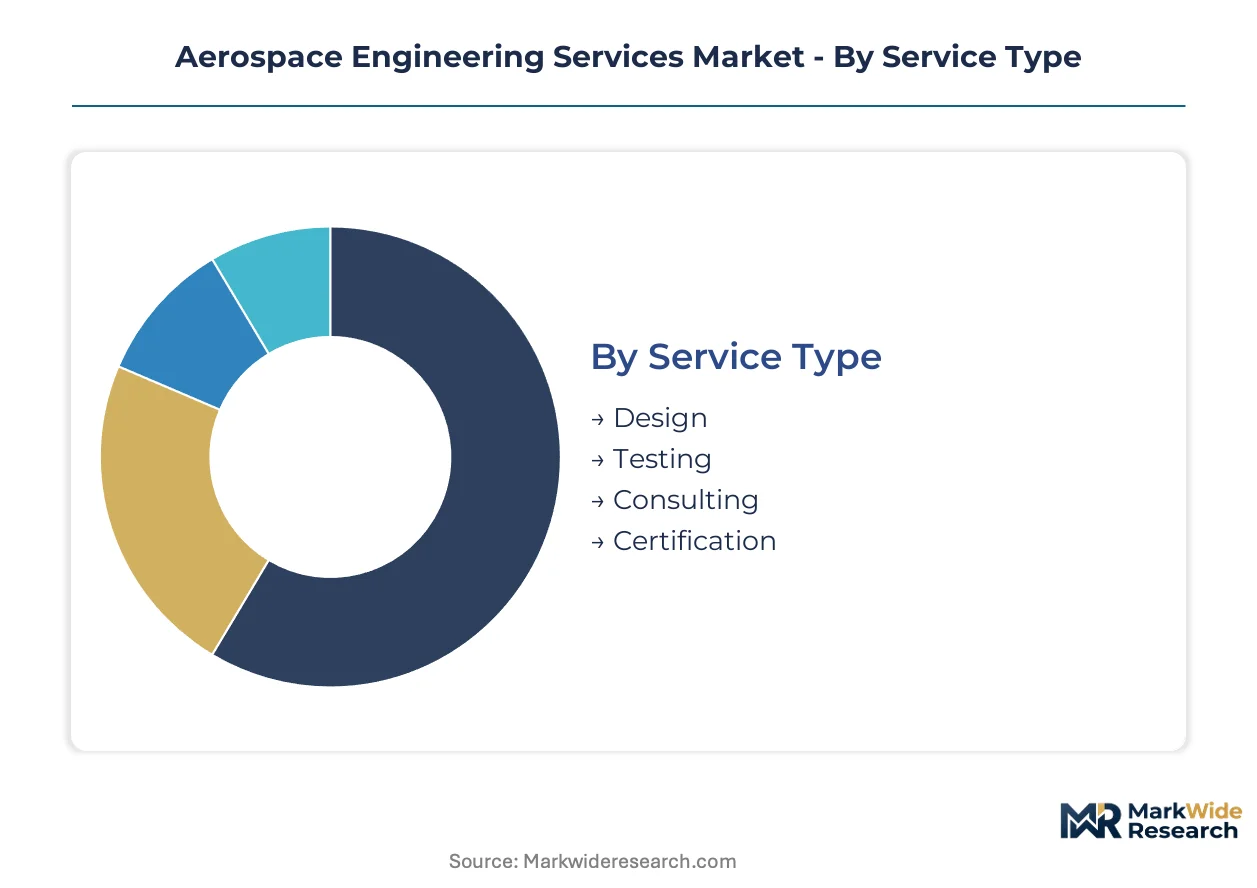
Service Type:
Cost tier determines outsourcing depth, with high-margin regulatory work retained by accredited specialists while routine analysis faces commoditization pressure.
- Design:Conceptual and detailed engineering for airframes, propulsion systems, and subsystems. Demand concentrates at Boeing and Airbus supplier development teams in Wichita and Toulouse as airframers unbundle legacy turnkey contracts into discrete work packages.
- Certification:Airworthiness substantiation, DER sign-off, and regulatory documentation for FAA and EASA compliance. FAA airworthiness directives on aging fleet retrofits sustain premium pricing for cleared analysts in Seattle and Derby regardless of contract backlog.
- Testing:Physical validation, environmental qualification, and flight-test support. Digital twin adoption pushes physical validation toward later development stages, expanding outsourcing of model correlation work.
- Consulting:Program management, technical advisory, and process optimization for engineering organizations. Indian and Eastern European providers compete on fixed-price deliverables for aerostructures detail design.
Volume sits with Design; growth tilts toward Certification.
End User:
Application maturity shapes service mix, with established platforms demanding sustainment engineering while developmental programs require integrated design-certification support.
- Commercial Aircraft:Narrowbody and widebody programs drive the largest contract value. Boeing's 737 MAX recovery and Airbus A320 family ramp sustain demand for aerostructures and systems integration specialists in the United States and France.
- Space Exploration:Lunar return timelines and satellite constellation deployments accelerate propulsion thermal analysis requirements. NASA's Artemis program sustains deep benches of human-rating certification expertise in Huntsville and Houston.
- Military Aviation:Fighter, transport, and rotorcraft programs governed by ITAR and classified access requirements. Security clearance bottlenecks stretch onboarding timelines beyond twelve months for defense-adjacent engineering teams.
- UAVs:Unmanned system design for military and commercial applications. FAA's Powered Lift rulemaking creates first-mover advantage for engineering firms building eVTOL flight-test capabilities.
Commercial Aircraft commands current volume; Space Exploration is climbing the fastest.
Technology:
Technical capability depth determines supplier qualification, with flight physics and structural analysis requiring accredited analysts while avionics integration faces toolchain fragmentation.
- Structural Analysis:Finite element modeling, damage tolerance assessment, and fatigue life prediction for metallic and composite structures. EASA's CS-25 Amendment 26 tightens composite primary structure requirements, mandating expanded test matrices for carbon-fiber wing designs.
- Propulsion:Thermal analysis, combustion simulation, and emissions modeling for turbine and novel architectures. Sustainable aviation fuel pathway analysis converges as airlines seek external validation of blend performance for fleet renewal planning.
- Aerodynamics:Computational fluid dynamics, wind tunnel correlation, and flight-envelope expansion. Generative design algorithms automate topology optimization, reallocating human expertise toward validation and edge-case resolution.
- Avionics:Systems integration, software certification, and hardware-software verification. Boeing and Airbus proprietary CAD environments fragment toolchains, forcing costly dual-platform staffing for integration specialists.
Structural Analysis anchors revenue; Propulsion is gaining share fastest.
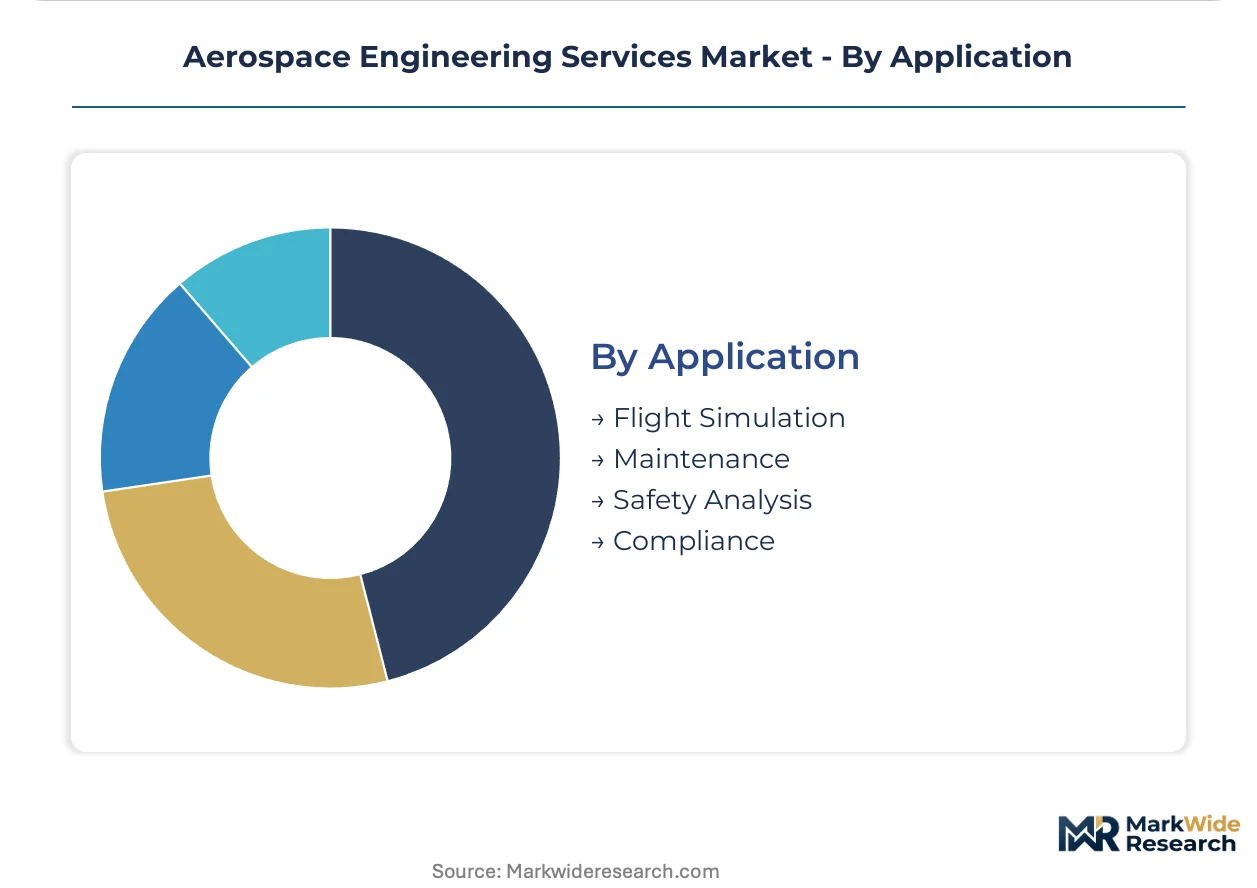
Application:
Regulatory exposure defines margin structure, with compliance-oriented work carrying pricing premiums due to limited supplier pools and liability concentration.
- Compliance:Certification documentation, regulatory interface, and continued airworthiness management. EASA certification specifications for novel propulsion architectures delay revenue recognition on electric and hydrogen aircraft programs.
- Safety Analysis:Fault tree assessment, failure mode analysis, and system safety engineering for human-rated systems. Human-factors expertise concentrates in Dallas-Fort Worth and Munich for next-generation cockpit programs.
- Flight Simulation:Model development, pilot-in-the-loop testing, and training device qualification. Physics-based simulation platforms compress physical test cycles, elevating correlation expertise value.
- Maintenance:Repair design, damage assessment, and fleet sustainment engineering. Aging aircraft directives sustain demand for structural repair substantiation across North American and European MRO networks.
Compliance generates premium pricing; Safety Analysis shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering service consumption concentrates where airframers and propulsion OEMs maintain design headquarters, while production capability disperses across cost-optimized engineering clusters. The United States captures the largest contract value through Boeing's supplier ecosystem and NASA's Artemis program. France, Germany, the United Kingdom, and India anchor specialized capability pools that feed into transnational program teams.
United States
Boeing's 737 MAX recovery and supplier development organization in Wichita sustain demand for aerostructures specialists. FAA airworthiness directives on aging commercial fleets sustain premium pricing for DER-qualified analysts in Seattle and Derby-adjacent engineering offices. NASA's lunar return timeline accelerates propulsion thermal analysis requirements at Marshall Space Flight Center in Huntsville.
France
Airbus engineering procurement teams in Toulouse unbundle legacy turnkey contracts into discrete design and certification modules. EASA's CS-25 Amendment 26 tightens composite primary structure requirements, mandating expanded test matrices for carbon-fiber wing designs at Saint-Nazaire and Nantes manufacturing clusters. Safran Engineering Services anchors propulsion certification expertise in Paris-Saclay.
Germany
MTU Aero Engines and Rolls-Royce Deutschland sustain demand for combustion simulation and emissions modeling in Munich and Dahlewitz. The country's national aviation regulator enforces stringent documentation standards for novel propulsion architectures, delaying revenue recognition on electric and hydrogen aircraft programs. Hamburg's aerostructures cluster builds captive non-destructive inspection capabilities for A320 family programs.
United Kingdom
BAE Systems' military aviation programs govern ITAR-adjacent engineering work from Lancashire and Bristol engineering centers. The UK Civil Aviation Authority interfaces with EASA on post-Brexit certification reciprocity, creating documentation complexity for trans-Atlantic programs. Derby's Rolls-Royce headquarters concentrates gas turbine thermal analysis expertise for narrowbody engine programs.
India
Ministry of Defence indigenization mandates for fighter and transport programs open engineering partnerships with Hindustan Aeronautics and private sector tier-one suppliers. L&T Technology Services and CYIENT compete on fixed-price deliverables for aerostructures detail design from Bangalore and Hyderabad delivery centers. The country's national quality regulator enforces ISO 9100 frameworks for aerospace supplier qualification.
Aerospace Engineering Services Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across a tiered vendor structure. Large integrated suppliers leverage vertical integration across avionics and aerostructures to sustain margins on complex integration programs. Three archetypes dominate: full-service conglomerates with captive certification capabilities, regional engineering specialists with cost-optimized delivery models, and niche flight-physics boutiques with accredited analyst pools. M&A activity concentrates on acquiring cleared engineering teams and DER qualifications, while strategic partnerships target digital twin and generative design capability gaps.
Within the full-service conglomerate tier, Collins Aerospace and Honeywell International exemplify diversified suppliers with in-house certification authority. Among regional engineering specialists, Alten Group and L&T Technology Services occupy positions spanning European and Indian delivery footprints. Quest Global anchors the flight-physics specialist archetype through structural analysis and aerodynamics expertise for tier-one supplier programs. These three named entities represent the competitive spectrum without exhausting the vendor landscape.
| Leading Market Players |
|---|
| Collins Aerospace |
| Alten Group |
| BAE Systems |
| Honeywell International |
| L&T Technology Services |
| Quest Global |
| CYIENT |
| Safran Engineering Services |
| Capgemini |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up engineering specialists dominate mid-market structural analysis, concentrating supply among DER-accredited analyst pools in Wichita and Toulouse while enforcing fixed-price discipline on commoditized design modules. This ownership pattern tightens margin capture in certification niches and accelerates cost-down pressure on routine aerostructures work.
Pricing Analysis
Cost-down pressure on routine design modules accelerates as Boeing and Airbus procurement teams mandate fixed-price deliverables for aerostructures detail work. Three-tier pricing structure across premium, standard, and economy levels separates FAA DER sign-off services from uncredentialed analysis and offshore commodity engineering. Price differentiation rests on certification tier and geographic delivery cost, with cleared analysts in Seattle commanding premiums against Eastern European competitors. Tier-one suppliers show highest price sensitivity on volume design work, while OEMs accept premium pricing for human-rating certification.
Supply Chain Analysis
Cleared stress engineer availability in Derby, Wichita, and Toulouse constrains capacity expansion regardless of contract backlog. Supply concentrates in the United States, France, and India, with propulsion thermal analysis anchored at Marshall Space Flight Center and aerostructures detail design migrating to Bangalore delivery centers. Raw material dependencies include high-performance computing clusters, ANSYS and Dassault Systèmes software licenses, and composite test specimens. Single-source vulnerability around ITAR-cleared analyst pools in defense-adjacent programs elevates onboarding risk. Distribution runs through airframer supplier development organizations and tier-one procurement teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a supply-constrained environment where finite pools of DER-qualified analysts and ITAR-cleared engineers prop pricing power regardless of demand cyclicality.
For Market Incumbents: Lock in captive certification capabilities through accelerated DER qualification pipelines in Huntsville and Derby, insulating against margin erosion from Indian and Eastern European fixed-price competitors. Consolidate flight-physics boutiques in Toulouse and Munich to deepen aerodynamics and structural analysis moats. Prioritize NASA Artemis program positioning to capture human-rating certification revenue. For New Entrants and Emerging Players: Tier-two supplier engineering procurement teams represent the most penetrable channel for eVTOL flight-test capabilities under FAA Powered Lift rulemaking. Urban air mobility certification support and SAF pathway analysis offer white-space expansion with limited incumbent saturation. Pursue fixed-price module contracts for aerostructures detail design to establish delivery credibility before climbing into higher-margin regulatory work. For Investors and Strategic Acquirers: Distressed-cycle entries favor ITAR-cleared engineering boutiques in Wichita and Seattle with established Boeing or Lockheed Martin program access. Long-term viability over the next decade hinges on digital twin and generative design capability integration. Watch for FAA rulemaking acceleration on novel propulsion architectures as inflection signal for certification service demand.| Strategic Initiative | Industry Significance |
|---|---|
| DER Qualification Pipeline Expansion | Builds captive certification authority in Huntsville and Derby to defend premium pricing. |
| Digital Twin Capability Acquisition | Captures model validation and correlation work shifting from physical to virtual testing. |
| eVTOL Flight-Test Infrastructure Buildout | Positions for FAA Powered Lift certification demand in Dallas-Fort Worth corridor. |
| India Defense Offset Partnership | Opens engineering contracts with Hindustan Aeronautics under Ministry of Defence mandates. |
| SAF Combustion Simulation Investment | Validates blend performance for airline fleet renewal planning and emissions compliance. |
Research Methodology
Document review covered FAA airworthiness directives, EASA certification specifications, NASA procurement disclosures, and supplier development organization RFPs, complemented by interviews with engineering procurement directors at Boeing and Airbus, DER-qualified analysts in Seattle and Toulouse, and program managers at Marshall Space Flight Center. Secondary validation drew from SEC 10-K filings of listed engineering services providers, ISO 9100 audit records, and customs data on aerospace software licensing. Bottom-up contract value aggregation and top-down market sizing triangulated segment-level estimates.
Segmentation outputs across service type, end user, technology, and application dimensions were modeled over the projection horizon, with CAGRs derived from historical contract value trajectories and program pipeline visibility. Inputs included Artemis program timeline acceleration, CS-25 Amendment 26 implementation schedules, and digital twin adoption curves at tier-one suppliers. The analytical framework weighted regulatory complexity indices against cost-optimized delivery center expansion.
Caveats apply where FAA rulemaking delays on novel propulsion architectures or EASA certification specification freezes could materially shift the outlook for electric and hydrogen aircraft program revenue recognition. ITAR clearance bottlenecks stretching beyond twelve months may constrain defense-adjacent capacity expansion assumptions. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Engineering Services
Engineering Services Outsourcing Market
Engineering Services
US Engineering, Procurement, and Construction Management (EPCM) Market
Engineering Services
Bridge Inspection Services Market
Engineering Services
Metal Fabrication Service Market
Engineering Services
Bridge Inspection System Market
Engineering Services
Foundation Repair Services Market
Engineering Services
Asia Pacific Engineering, Procurement, and Construction Management (EPCM) Market
Engineering Services
Asia-Pacific Seismic Services Market
Engineering Services
Seismic Services Market
Engineering Services
Architectural Services Market
Engineering Services
Europe Engineering Research and Development (ER&D) Services Market
Engineering Services
Middle East Seismic Services Market
Engineering Services
Outsourcing Civil Engineering Services Market
Engineering Services
United States (US) MEP Services Market
Engineering Services
China Engineering, Procurement, and Construction Management (EPCM) Market
Engineering Services
Engineering Design Service Market