
 Smart Home Service Market | 2026-2036
Smart Home Service Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Home Service Market Analytics
UL 2900 cybersecurity certification is rotating as the primary gating standard for smart home service providers seeking enterprise and insurance-channel placement. Vivint Smart Home leverages its vertically integrated installation workforce to control end-to-end service quality. ADT sustains brand recognition in monitored security, though its pivot toward broader home automation remains incomplete. Schneider Electric anchors its position through deep building-management expertise that extends into residential energy services.
Smart home service denotes the recurring delivery of integrated monitoring, automation, and energy optimization functions through connected device networks, typically requiring continuous cloud connectivity and over-the-air firmware management to maintain operational integrity. The primary commercial purpose centers on converting capital hardware expenditures into predictable subscription revenue while reducing household energy consumption and insurance risk profiles. Home security retains the largest revenue pool among service types, yet energy management commands superior margins where utility rebate programs apply. IoT solutions underpin baseline connectivity, while AI integration represents the fastest-expanding technology layer as predictive maintenance and anomaly detection capabilities mature. Residential customers still generate the majority of installations, though property managers exhibit steeper growth trajectories as multifamily portfolios standardize on platform-managed units.
FCC Part 15 governs radio frequency emissions from connected devices in the United States, while the EU AI Act imposes risk-classification obligations on automated decision systems affecting building access and energy allocation. GDPR and state-level privacy statutes in California and Virginia constrain how behavioral data from smart home systems may be monetized or shared with third parties. Stakeholders must weigh certification investments against the fragmentation of regional compliance requirements as they scale platform architectures across jurisdictions.
Market Dynamics
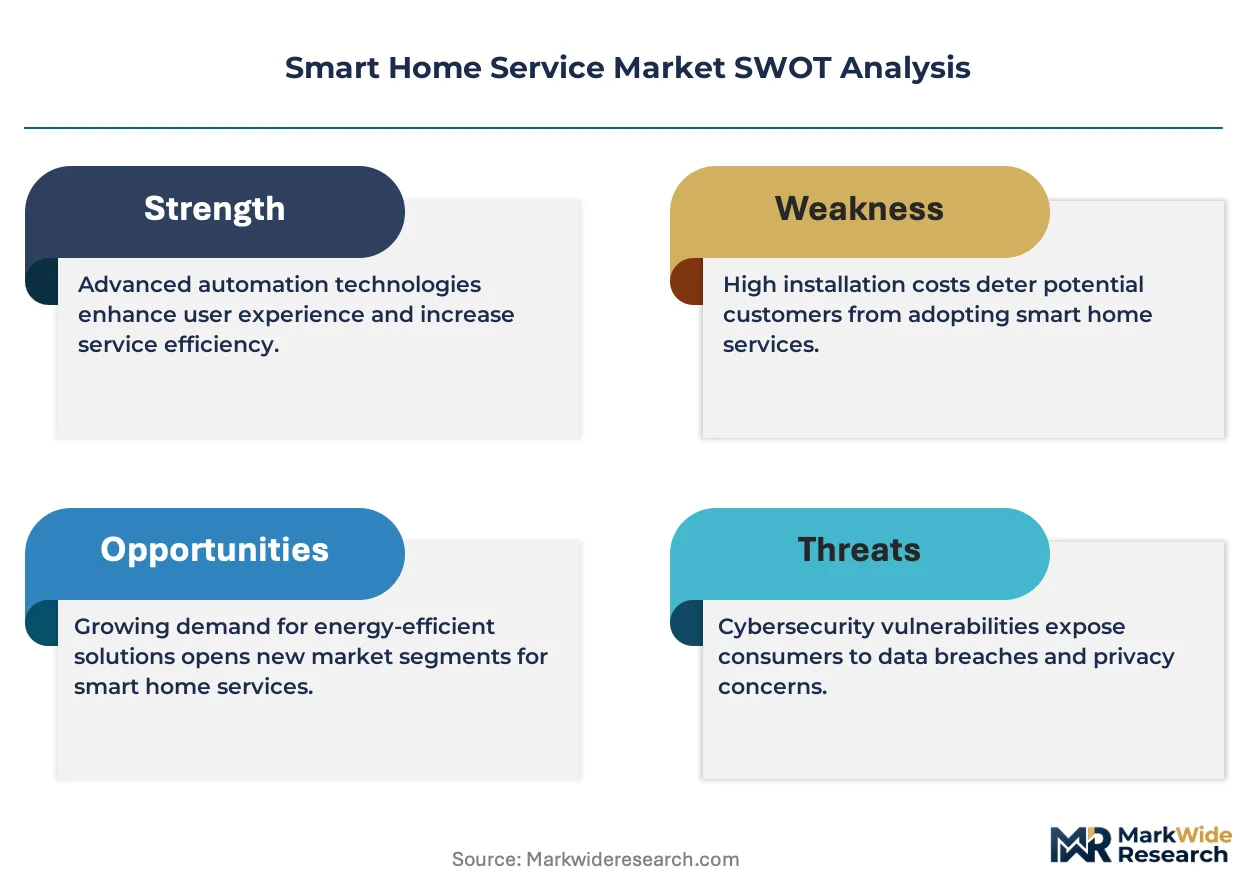
The smart home service market is restructuring around the collision of utility-led energy mandates and institutional rental portfolio digitization, forcing vendors to rebuild platforms for multi-tenant management rather than single-family customization.
Growth Catalysts
- EU AI Act compliance:Risk-classification obligations for automated building systems are creating qualified vendor shortages that favor early certifiers in European deployments.
- Smart metering mandates:Germany's utility-led rollout is bundling energy optimization services with hardware installation, accelerating subscription conversion rates.
- Property manager digitization:Institutional multifamily portfolios are standardizing on platform-managed units, generating recurring revenue pools that dwarf residential customer lifetime values.
Market Restraints
- Silicon supply concentration:Semiconductor fabrication for edge-computing devices remains concentrated in East Asian foundries, exposing service providers to input cost volatility and allocation constraints.
- GDPR monetization friction:Behavioral data from connected home systems faces strict processing limitations, compressing ancillary revenue streams that subsidize hardware subsidies.
- Legacy HVAC integration:Pneumatic and analog climate control systems in pre-2000 housing stock resist retrofit without full replacement, limiting addressable unit penetration.
Strategic Opportunities
- Insurance channel integration:UL 2900 certification is unlocking placement with property and casualty carriers seeking risk-score data from monitored environments.
- AI-driven predictive maintenance:Convergence of anomaly detection algorithms with over-the-air firmware management is enabling outcome-based service contracts for critical building systems.
- Sub-metering in multifamily:Regulatory tailwinds for individual unit billing in rental housing are creating white space for energy-as-a-service providers in underpenetrated secondary German cities.
Industry Challenges
- Cybersecurity certification timelines:UL 2900 and IEC 62443 assessment cycles extend 14-18 months, delaying product launches and freezing development roadmaps.
- Interoperability protocol fragmentation:Matter, Zigbee, Z-Wave, and proprietary mesh networks require parallel engineering tracks, inflating R&D overhead without guaranteed standard dominance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Home Service Market |
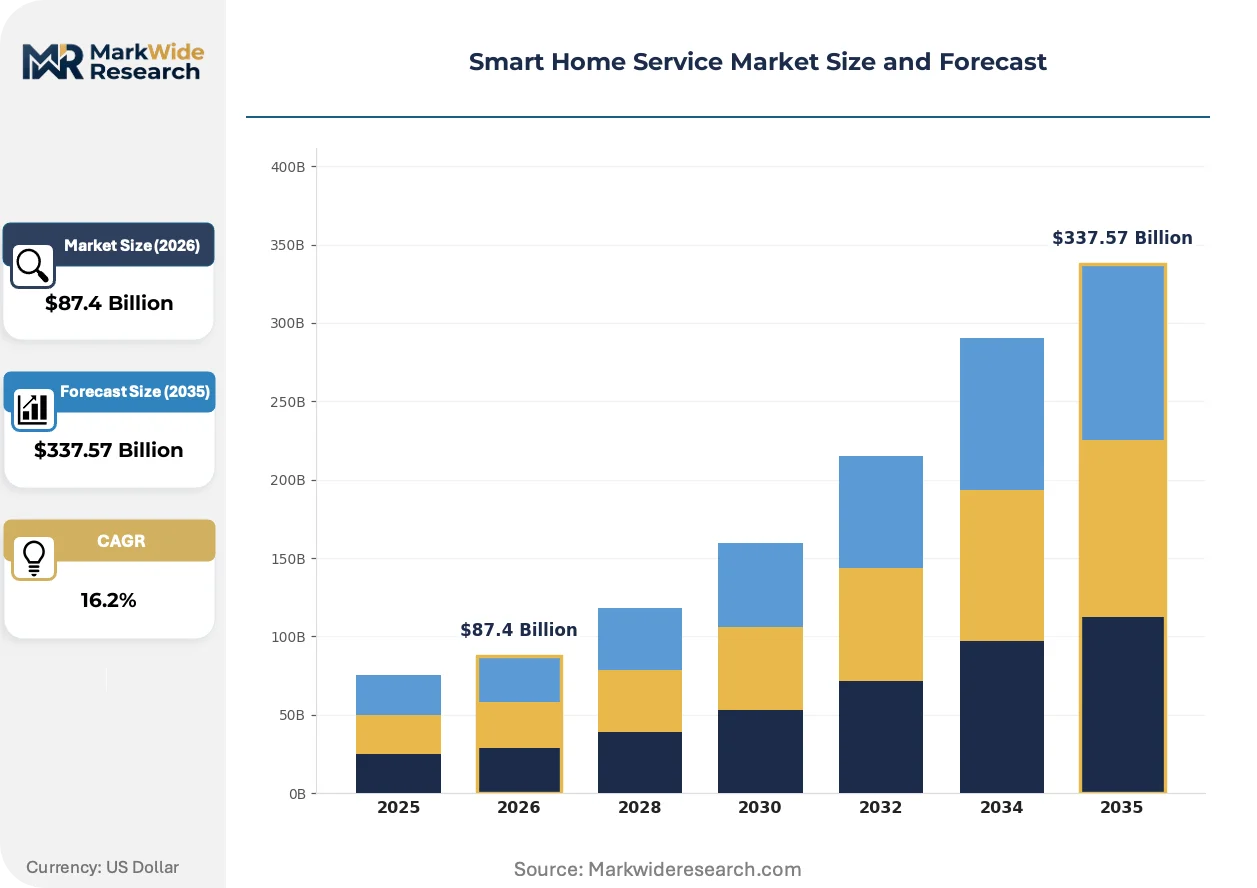
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $337.57 Billion |
| CAGR (2026 – 2036) | 16.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Home Security, Energy Management, Home Automation, Maintenance Services Technology: IoT Solutions, Cloud Computing, AI Integration, Voice Assistants Customer Type: Residential, Commercial, Rental Properties, Property Managers Installation Type: DIY Install, Professional Install, Remote Monitoring, Upgrades |
| Companies Covered | Vivint Smart Home, ADT, Comcast Corporation, Alarm.com Holdings, Johnson Controls, Control4, Schneider Electric, Ingersoll Rand, Protection One Alarm Monitoring, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Home Service Market Evolving Landscape
Artificial intelligence integration is compressing the service layer from reactive monitoring to predictive intervention, while regulatory compliance is becoming a product feature rather than a back-office cost.
Edge-based machine learning inference is supplanting cloud-dependent processing for latency-sensitive functions like occupancy detection and anomaly classification. Property managers operating thousand-unit portfolios are adopting these architectures fastest, driven by insurance premium reductions and bandwidth cost containment. The shift is compressing vendor margins on data-center infrastructure while elevating hardware BOM costs.
GDPR and the EU AI Act are imposing joint-controllership obligations on smart home platforms that automate access decisions or energy allocation. Industrial consequence includes mandatory algorithmic impact assessments and audit trails for building management systems. German utility-led deployments face the strictest interpretation, with some operators segregating EU data processing entirely to satisfy regulator demands.
Buyer procurement is consolidating around platform-managed service contracts that bundle hardware, installation, monitoring, and maintenance into per-unit monthly fees. The traditional channel of retail device sales followed by third-party installation is losing share to vertically integrated providers in multifamily new construction. This pattern is most visible in institutional rental portfolios across North America and Northern Europe, where standardization overrides consumer preference.
Smart Home Service Market Segmentation
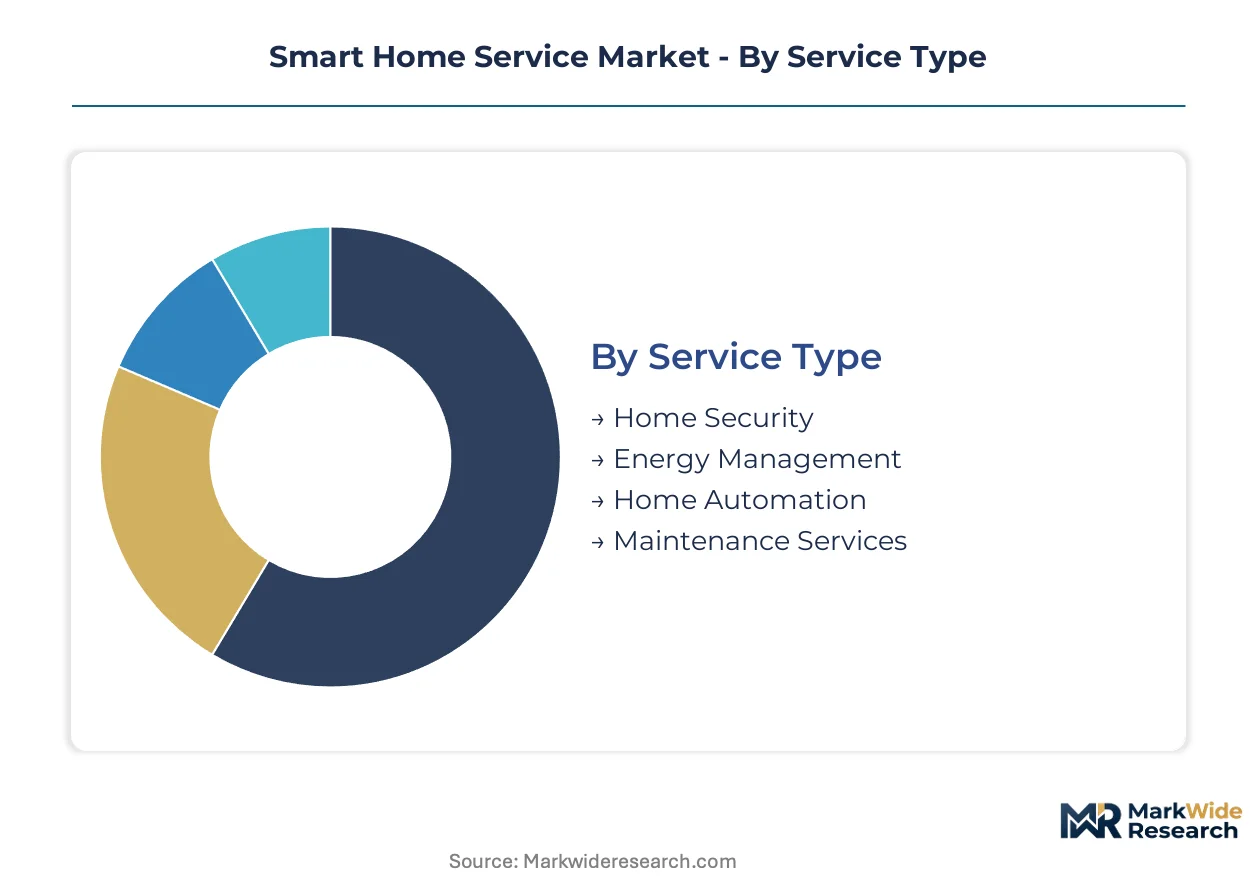
Segmentation in smart home services reveals how regulatory compliance costs and customer procurement patterns reshape vendor economics. The market fragments across four critical dimensions where certification requirements and installation complexity determine margin structures and competitive defensibility.
Service Type:
FCC Part 15 and GDPR impose divergent compliance burdens across service categories, with monitored functions facing stricter radio frequency and data processing obligations than passive automation.
- Home Security:Continuous monitoring of intrusion, fire, and environmental hazards through sensor networks and central station dispatch. Demand concentrates in institutional rental portfolios across Germany and the United States, where insurance premium reductions justify subscription premiums. UL 2900 certification has become a mandatory gating standard for carrier channel placement.
- Energy Management:Real-time consumption optimization, load shifting, and utility tariff arbitrage through connected thermostats and sub-metering infrastructure. German utility-led mandates in secondary cities like Leipzig and Dortmund are accelerating bundling with smart meter rollouts, creating the steepest subscription conversion trajectories.
- Home Automation:Coordinated control of lighting, shading, and entertainment systems through centralized platforms.
- Maintenance Services:Predictive intervention for HVAC, plumbing, and appliance systems using anomaly detection algorithms.
Home Security handles the majority of throughput; Energy Management is the fastest mover on share.
Technology:
Cost tier differentiation separates capital-intensive edge deployments from cloud-dependent architectures, with AI integration commanding premium pricing where outcome-based contracts apply.
- IoT Solutions:Baseline connectivity protocols enabling device interoperability and data telemetry. Massive installed base in residential retrofits across Virginia and California sub-markets, though margin compression from protocol fragmentation limits vendor profitability.
- AI Integration:Predictive maintenance, occupancy inference, and anomaly classification through machine learning models. Property managers operating thousand-unit portfolios in Dallas and Atlanta are adopting edge-based inference fastest, driven by bandwidth cost containment and insurance risk scoring.
- Cloud Computing:Centralized data processing, firmware distribution, and remote diagnostics infrastructure.
- Voice Assistants:Natural language interfaces for device control and service management.
IoT Solutions carries the largest installed base; AI Integration is expanding most quickly among enterprise buyers.
Customer Type:
Application urgency varies sharply, with rental property digitization timelines compressing procurement cycles relative to discretionary residential adoption.
- Property Managers:Institutional operators of multifamily portfolios standardizing on platform-managed units. Revenue concentration in REITs and institutional owners across Berlin, Munich, and Hamburg, where EU AI Act compliance requirements favor early-certifying vendors with segregated EU data processing.
- Residential:Individual homeowners purchasing subscription services for single-family dwellings. Volume leadership persists in suburban markets outside Houston and Phoenix, though customer lifetime values lag commercial segments by substantial margins.
- Commercial:Small business and retail environments requiring integrated security and energy optimization.
- Rental Properties:Individual landlord-owned units seeking standardized service tiers.
Residential maintains volume dominance; Property Managers are climbing the fastest as institutional capital flows into build-to-rent development.
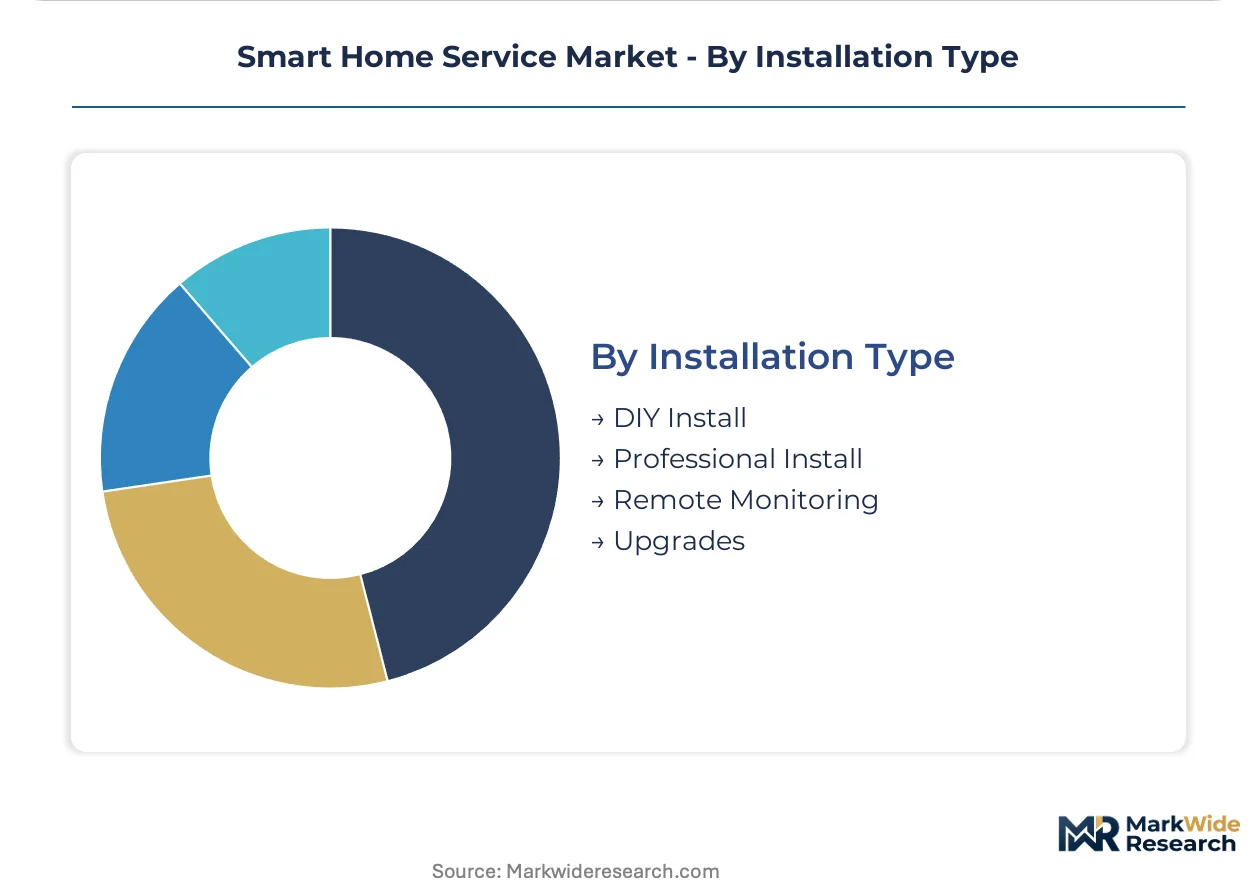
Installation Type:
Supply concentration in trained technician networks creates regional bottlenecks, with professional installation margins expanding where building codes mandate certified electrical work.
- Professional Install:Certified technician deployment of hardware, network configuration, and system commissioning. Demand clusters in pre-2000 housing stock across Chicago and Boston, where legacy HVAC integration complexity resists DIY approaches and mandates full system replacement.
- Remote Monitoring:Continuous oversight of system health, threat verification, and firmware management from centralized operations centers. German deployments under GDPR joint-controllership obligations require segregated EU processing, elevating vendor infrastructure costs while reducing bandwidth dependencies.
- DIY Install:Consumer self-configuration of plug-and-play device ecosystems.
- Upgrades:Expansion and modernization of existing smart home infrastructure.
Professional Install handles the majority of revenue; Remote Monitoring is gaining share fastest as property managers prioritize operational leverage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Property managers in Germany, institutional landlords in the United States, and utility operators across Northern Europe concentrate procurement volumes for platform-managed smart home services. This buyer-archetype clustering shapes regional deployment patterns and compliance investment priorities.
Germany
Utility-led smart metering mandates in Leipzig and Dortmund accelerate service bundling with hardware installation. The EU AI Act imposes strict risk-classification obligations on automated building access and energy allocation systems. Berlin's institutional rental portfolios standardize on GDPR-compliant platforms with segregated EU data processing.
United States
FCC Part 15 governs radio frequency emissions from connected devices while state-level privacy statutes in California and Virginia constrain behavioral data monetization. UL 2900 cybersecurity certification unlocks placement with property and casualty carriers in Dallas and Atlanta. Houston and Phoenix suburban markets sustain residential volume leadership.
United Kingdom
GDPR joint-controllership obligations reshape vendor qualification criteria for automated decision systems in building management. London's build-to-rent developments consolidate procurement around platform-managed service contracts. Manchester and Birmingham multifamily portfolios exhibit accelerating digitization timelines.
France
CNIL enforcement of GDPR provisions creates compliance friction for behavioral data processing from connected home systems. Paris institutional landlords prioritize vendors with demonstrated EU AI Act certification. Lyon and Marseille secondary markets present underpenetrated opportunities for energy-as-a-service providers.
Canada
Health Canada and PMRA frameworks intersect with provincial privacy statutes governing smart home data collection. Toronto and Vancouver institutional rental portfolios standardize on certified installation networks. Montreal's pre-2000 housing stock drives demand for professional HVAC integration and full system replacement.
Smart Home Service Market Competitive Landscape
Player mix skews toward vertically integrated service providers with captive installation workforces and certified monitoring infrastructure. Market structure concentrates around three tiers: premium platform operators with full-stack capabilities, mid-market specialists in single service verticals, and regional installers competing on price. Dominant competitive moves include UL 2900 certification pursuit for insurance channel access and backward integration into edge-computing hardware design.
Within the premium platform tier, Vivint Smart Home and ADT exemplify contrasting strategic positions. Vivint leverages its captive installation workforce to control end-to-end service quality and subscription conversion. ADT sustains brand recognition in monitored security while extending toward broader home automation capabilities. Schneider Electric anchors the building-management extension archetype, translating deep energy services expertise into residential platform architectures.
| Leading Market Players |
|---|
| Vivint Smart Home |
| ADT |
| Comcast Corporation |
| Alarm.com Holdings |
| Johnson Controls |
| Control4 |
| Schneider Electric |
| Ingersoll Rand |
| Protection One Alarm Monitoring |
| Others |
Value Network & Pricing Analysis
Fourteen-to-eighteen-month UL 2900 certification cycles concentrate pricing power with early-certifying vendors while compressing margins for late entrants competing on hardware subsidies. Inventory buffers for edge-computing semiconductors stretch 90-120 days across German and North American distribution hubs, tethering service pricing to foundry allocation volatility.
Pricing Analysis
Cost-plus contracts indexed to semiconductor spot markets dominate enterprise procurement for thousand-unit property manager deployments. Three-tier pricing structure across premium certified-installation, standard self-service, and economy hardware-only levels separates UL 2900-compliant platforms from uncertified competitors. Pricing pressure stems from GDPR-mandated data segregation elevating EU infrastructure costs for joint-controllership obligations. Residential subscribers in Houston and Phoenix exhibit highest price sensitivity, while institutional REITs in Berlin and Dallas accept premium tiers for insurance channel integration.
Supply Chain Analysis
Ninety-day inventory cycles for edge-AI chipsets expose service providers to allocation constraints from Taiwan and South Korea foundries. Component sourcing draws from Chinese sensor manufacturers, German HVAC integration specialists, and Vietnamese final assembly for consumer-grade hardware. Single-source vulnerability concentrates in 7nm and 5nm edge inference processors. Distribution runs through vertically integrated installation workforces in North America and certified technician networks across Northern Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power shifts toward institutional property managers consolidating procurement across thousand-unit portfolios, fragmenting vendor pricing autonomy. This consolidation favors platforms with captive installation capacity and segregated EU data infrastructure.
For Market Incumbents: Compound UL 2900 certification advantages by backward integration into edge-computing hardware design, insulating against foundry allocation volatility. Lock in multi-year platform-managed service contracts with REITs in Dallas and Atlanta before GDPR joint-controllership obligations harden vendor qualification criteria. Prioritize segregated EU data processing investments to defend position in German utility-led deployments.
For New Entrants and Emerging Players: Anchor in sub-metering energy-as-a-service for secondary German cities like Leipzig and Dortmund, where utility mandates create white space without incumbent saturation. Target pre-2000 housing stock in Chicago and Montreal requiring professional HVAC integration that resists DIY competition. Pursue Matter protocol certification as go-to-market angle to bypass Zigbee and Z-Wave fragmentation overhead.
For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue infrastructure play because property manager digitization converts capital expenditures into predictable per-unit subscriptions. Acquisition target archetype: mid-market specialists with captive installation networks and pending UL 2900 certification. Watch for inflection when EU AI Act enforcement triggers qualified vendor shortages in Berlin and Munich institutional portfolios.
| Strategic Initiative | Industry Significance |
|---|---|
| UL 2900 Certification Pursuit | Unlocks placement with property and casualty carriers in Dallas and Atlanta seeking risk-score data. |
| Backward Integration into Edge Hardware | Reduces dependency on Taiwan and South Korea foundry allocation for latency-sensitive inference chips. |
| Segregated EU Data Infrastructure | Satisfies GDPR joint-controllership obligations for German utility-led smart metering mandates. |
| Platform-Managed Service Contracts | Bundles hardware, installation, and monitoring into per-unit fees for REITs in Berlin and Hamburg. |
| Matter Protocol Standardization | Eliminates parallel engineering tracks for Zigbee and Z-Wave, compressing R&D overhead. |
Research Methodology
Cross-validation between primary interviews with smart home platform executives and secondary validation from FCC Part 15 filings anchors the qualitative findings. Stakeholder consultations included property manager procurement directors, UL certification assessors, German utility smart metering program leads, and insurance carrier risk officers. Secondary sources comprised SEC 10-K disclosures from listed service providers, EMA and EU AI Act regulatory documentation, and customs data on edge-computing semiconductor imports. Bottom-up unit economics triangulated against top-down market sizing across service type, technology layer, and customer archetype.
Sensitivity analysis tested forecast robustness across semiconductor price volatility scenarios and GDPR enforcement intensity variations. Segmentation dimensions modeled include service category, technology integration depth, customer procurement scale, and installation complexity tier. CAGRs derived from installed base expansion rates, subscription renewal patterns, and hardware replacement cycles. Edge-AI adoption curves and utility mandate compliance timelines served as industry-specific demand drivers.
Material uncertainties — foundry allocation constraints, EU AI Act enforcement timing, and insurance channel certification requirements — sit outside the modeled envelope. Forecasts reflect assumptions on regulatory stability and technology standardization momentum. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
High Frequency Vibrator Market
Others
Coalescing Filter Market
Others
Europe Astrology Market
Others
Rotary Union Market
Others
Fibert Market
Others
Global Recruitment and Staffing Market
Others
Industrial Gauges Market
Others
Turkey Health and Medical Insurance Market
Others
Disposable Non Woven Sponge Market
Others
Japan Indoor LBS Market
Others
China Online Gambling Market
Others
United States Indoor LBS Market
Others
Double Card Mobile Phone Market
Others
US Cat Food Market
Others
US Legal Services Market
Others
Global Animal Feed Protein Ingredients Market