
 Printing Machines Market | 2026-2036
Printing Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Printing Machines Market Outlook
E-commerce fulfillment centers are bifurcating demand away from traditional commercial print shops toward on-demand packaging and short-run label operations. HP Inc. leverages thermal inkjet architectures to serve high-velocity fulfillment lines, while Canon Inc. sustains dominance in commercial photo and document segments through aqueous ink formulations. Koenig & Bauer AG anchors specialized sheet-fed and web offset systems for security and currency printing.
Printing machines are electromechanical systems engineered to transfer ink or toner onto substrates including paper, film, textile, and metal at speeds ranging from 15 to 1,000+ meters per minute, with resolution specifications typically spanning 300 to 2,400 dpi depending on end-use precision requirements. Inkjet printers lead unit shipments across desktop and wide-format categories, while digital printers command premium positioning in packaging due to variable-data capabilities and reduced makeready waste. Laser printers occupy mature volume segments in office and enterprise environments, whereas 3D printers represent the fastest-expanding value pool as manufacturers adopt additive tooling for jigs, fixtures, and end-use components.
The EPA regulates volatile organic compound emissions from commercial printing operations under Clean Air Act standards, while REACH restricts hazardous substances in inks and coatings sold across Europe, compelling reformulation investments. The EU Green Deal and F-Gas Regulation are reshaping dryer and curing system specifications, pushing OEMs toward LED-UV and infrared technologies. Stakeholders must monitor how energy-efficiency mandates and substrate recyclability requirements alter capital equipment specifications and retrofit demand.
Market Dynamics
E-commerce fulfillment centers are fragmenting demand away from traditional commercial print shops toward on-demand packaging and short-run label operations, compressing equipment procurement cycles and reshaping vendor relationships.
Growth Catalysts
- E-commerce fulfillment expansion:Third-party logistics operators in Germany and the Netherlands are scaling digital label system deployments to support same-day delivery promises.
- REACH compliance:European ink reformulation mandates are accelerating capital replacement cycles as converters retire solvent-based systems for water-based alternatives.
- LED-UV curing:Energy-efficiency specifications under the EU Green Deal are pulling adoption of low-temperature drying systems across packaging converters.
Market Restraints
- Substrate cost volatility:Fluctuating pulp and polymer resin prices compress margin visibility for packaging converters operating on fixed-price contracts.
- Precision component concentration:German and Japanese suppliers dominate high-resolution printhead manufacturing, creating single-source vulnerability for OEMs.
- Digital-to-offset substitution ceiling:Long-run corrugated and publication segments retain cost advantages for web offset systems above 50,000 impressions.
Strategic Opportunities
- India packaging modernization:Domestic food and pharmaceutical manufacturers are upgrading from flexographic to digital systems for variable-data serialization compliance.
- Textile direct-to-garment convergence:Hybrid inkjet-dye sublimation systems are opening short-run apparel decoration for online custom merchandise platforms.
- BIS energy labeling:Indian Bureau of Standards efficiency ratings for industrial equipment are creating first-mover advantage for OEMs with certified low-power architectures.
Industry Challenges
- Mechatronics talent scarcity:Maintenance of precision registration systems requires scarce expertise in servo control and vibration dampening.
- Legacy RIP integration:Prepress workflow unification across offset and digital assets demands costly middleware development for hybrid print environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Printing Machines Market |
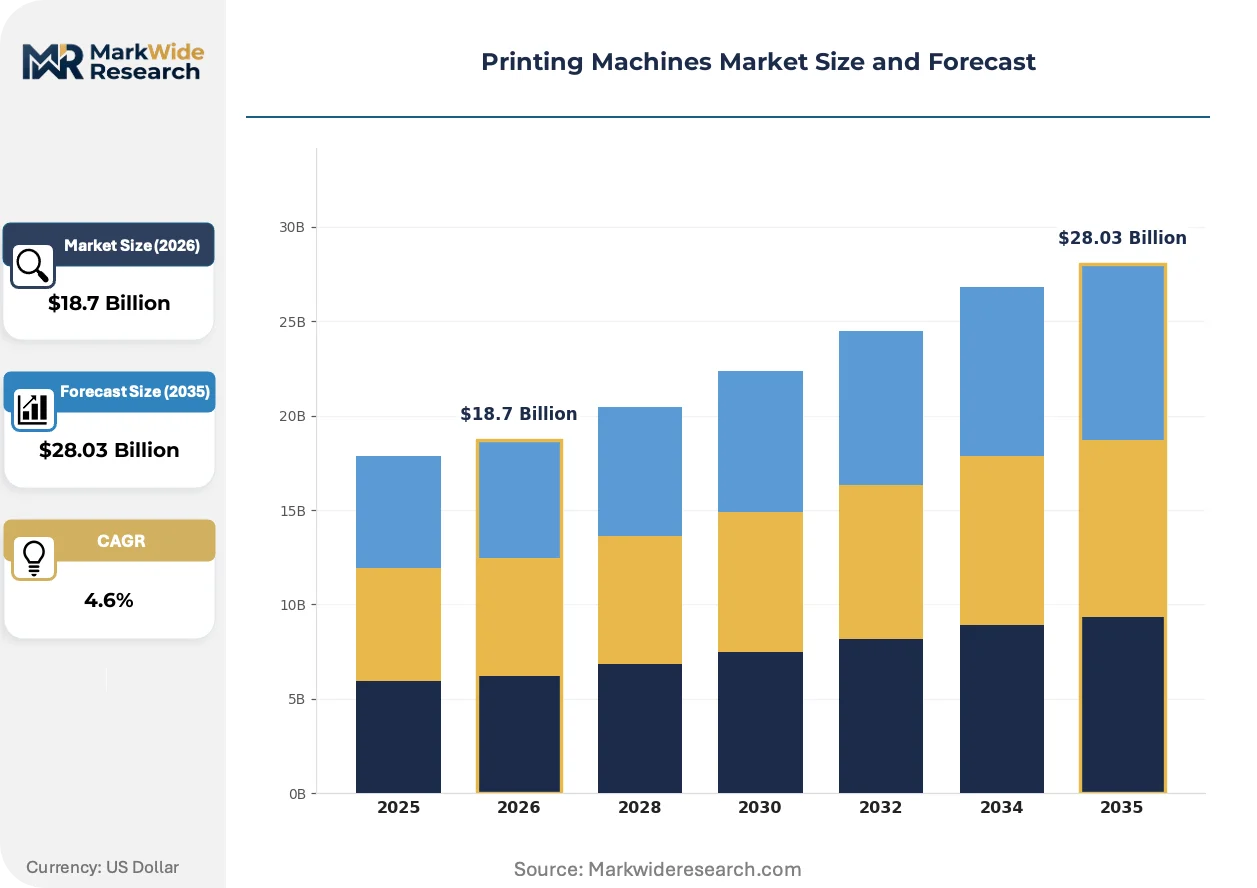
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.03 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inkjet Printers, Laser Printers, 3D Printers, Digital Printers Application: Commercial Printing, Labeling, Packaging, Textile Printing Technology: Offset Printing, Flexography, Screen Printing, Gravure Printing End User: Publishing Houses, Advertising Agencies, E-Commerce, Manufacturers |
| Companies Covered | HP Inc., Canon Inc., Ricoh Company Ltd., Xerox Holdings Corporation, Heidelberger Druckmaschinen AG, Bobst Group SA, Koenig & Bauer AG, Seiko Epson Corporation, Fujifilm Holdings Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Printing Machines Market Strategic Shifts
Active developments across curing technology, regulatory compliance architecture, and procurement models are compressing equipment replacement cycles and reconfiguring vendor-buyer power dynamics.
Thermal inkjet printhead architectures are fragmenting the high-velocity fulfillment segment. E-commerce sortation facilities in Germany and the United States are adopting single-pass arrays for real-time shipping label generation. This capability is fragmenting demand away from centralized print operations toward distributed edge-printing nodes within warehouse footprints.
The EU F-Gas Regulation is forcing refrigerant-based dryer retrofits across commercial heatset web installations. Equipment owners in France and Italy face accelerated depreciation schedules for gas-dependent curing systems. Packaging converters are responding by specifying infrared and LED-UV alternatives in new capital requests.
Equipment-as-a-service contracting is displacing traditional capital purchase models among mid-volume commercial printers. Usage-based billing with bundled maintenance and consumable provisioning is penetrating the Benelux and Nordic markets. This shift is most visible among marketing services providers with seasonal volume volatility.
Printing Machines Market Segmentation
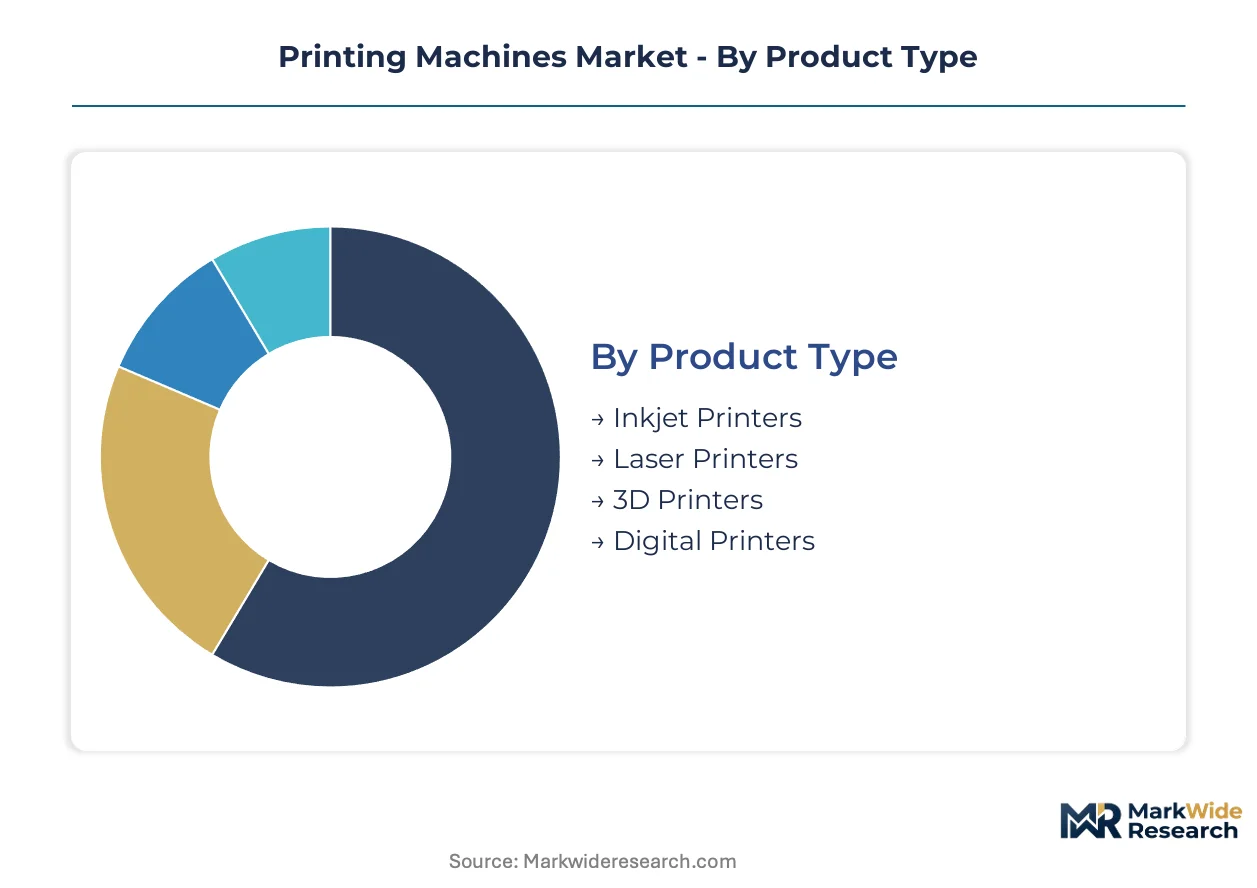
Segmentation in printing machines reveals divergent equipment specifications across end-use intensity levels. High-velocity fulfillment operations demand thermal inkjet architectures with minimal makeready, while security printing requires gravure-level precision at web offset speeds.
Product Type:
Domestic demand concentrates in desktop and office systems across Germany, Japan, and the United States, whereas export-led growth flows from Chinese and Vietnamese manufacturing of wide-format and industrial units.
- Inkjet Printers:Thermal and piezoelectric printhead technologies deposit aqueous, solvent, or UV-curable inks onto porous and non-porous substrates. E-commerce fulfillment centers in the Netherlands deploy single-pass arrays for real-time shipping label generation at sortation velocities exceeding 150 meters per minute.
- Digital Printers:Electrophotographic and inkjet platforms enable variable-data printing with zero plate costs, serving pharmaceutical serialization mandates in India and short-run packaging converters in Italy. REACH-compliant water-based formulations are displacing solvent systems across European installations.
- Laser Printers:Xerographic engines with organic photoconductor drums and dry toner fusing dominate enterprise document workflows.
- 3D Printers:Fused deposition modeling and selective laser sintering systems produce jigs, fixtures, and end-use polymer components for automotive tooling shops.
Laser printers command the established base. The steepest expansion runs through digital printers.
Application:
Cost tier separation is pronounced: packaging and labeling systems carry 3-5x capital intensity versus commercial printing equipment, with correspondingly longer depreciation schedules and service contract attach rates.
- Packaging:Corrugated, folding carton, and flexible film printing systems handle substrates from 80gsm paperboard to 400-micron PE films. German converters serving FMCG brands are retrofitting LED-UV curing to meet EU Green Deal energy specifications.
- Labeling:Pressure-sensitive and shrink-sleeve decoration systems print at 50-200 meters per minute with registration tolerances below 0.1 millimeters. Third-party logistics operators in Germany scale digital label deployments to support same-day delivery commitments.
- Commercial Printing:Marketing collateral, direct mail, and transactional document production.
- Textile Printing:Direct-to-garment and dye-sublimation systems for apparel decoration.
Commercial printing retains the installed base. The steepest expansion trajectory belongs to labeling.
Technology:
Volume concentration favors offset for runs above 50,000 impressions, while digital and flexographic systems capture shorter runs with faster changeover.
- Offset Printing:Lithographic transfer from aluminum plates to rubber blankets achieves 175+ line screen resolution on coated stocks. Heidelberg and Koenig & Bauer anchor precision engineering clusters sustaining German export dominance in sheet-fed and web offset systems.
- Flexography:Photopolymer plate relief printing on corrugated and flexible packaging substrates. Indian food manufacturers upgrade from flexographic to digital systems for variable-data serialization compliance with FSSAI track-and-trace mandates.
- Screen Printing:Stencil-based ink deposition for glass, metal, and textile substrates.
- Gravure Printing:Engraved cylinder intaglio for high-volume publication and decorative laminates.
Offset printing holds the established base. The steepest expansion runs through flexography.
End User:
Customer type determines procurement modality: manufacturers and e-commerce operators favor equipment-as-a-service contracting, while publishing houses and advertising agencies retain traditional capital purchase models.
- E-Commerce:Fulfillment centers and third-party logistics operators require edge-printing nodes for on-demand packaging and shipping documentation. Usage-based billing with bundled maintenance penetrates the Benelux and Nordic markets among seasonal-volume marketing services providers.
- Manufacturers:Automotive, electronics, and consumer goods producers deploy additive systems for tooling and direct part production. BIS energy labeling for industrial equipment creates first-mover positioning for OEMs with certified low-power architectures in India.
- Publishing Houses:Newspaper, magazine, and book production operations.
- Advertising Agencies:Marketing services and creative production studios.
Publishing houses command the established base. The steepest expansion runs through e-commerce.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision engineering clusters around Heidelberg and Koenig & Bauer anchor high-resolution printhead manufacturing and export-oriented production systems. Supply concentrates in Japan's mechatronics corridors and China's wide-format assembly bases, with demand fragmentation accelerating across fulfillment networks.
Germany
Third-party logistics operators scale digital label deployments to support same-day delivery commitments. The EU F-Gas Regulation accelerates refrigerant-based dryer retrofits across commercial heatset web installations. Precision engineering clusters around Heidelberg and Koenig & Bauer sustain export-oriented sheet-fed and web offset production.
United States
E-commerce sortation facilities adopt single-pass thermal inkjet arrays for real-time shipping label generation. EPA Clean Air Act standards regulate volatile organic compound emissions from commercial printing operations. Edge-printing nodes fragment demand away from centralized print operations within warehouse footprints.
China
Domestic manufacturing of wide-format and industrial units drives export-led growth across Southeast Asian markets. MIIT energy-efficiency standards and dual carbon goals reshape dryer and curing system specifications. Yangtze River Delta assembly bases concentrate inkjet printer unit shipments for desktop and wide-format categories.
India
Food and pharmaceutical manufacturers upgrade from flexographic to digital systems for FSSAI variable-data serialization compliance. BIS energy labeling for industrial equipment creates first-mover positioning for OEMs with certified low-power architectures. Maharashtra and Gujarat packaging converters drive capital replacement cycles for water-based ink alternatives.
Japan
Mechatronics expertise in servo control and vibration dampening sustains high-resolution printhead manufacturing dominance. METI industrial standards and JIS certification requirements maintain quality benchmarks for precision registration systems. Chubu and Kansai corridors anchor photoconductor drum and dry toner fusing technology production.
Printing Machines Market Competitive Environment
Concentration sits with diversified technology conglomerates and precision engineering specialists. The vendor base spans three tiers: integrated electronics manufacturers with thermal inkjet architectures, specialized sheet-fed and web offset fabricators, and emerging additive system providers. Strategic moves center on equipment-as-a-service contracting penetration and LED-UV curing technology licensing.
Within the diversified technology tier, HP Inc. and Canon Inc. exemplify integrated electronics manufacturers with broad portfolio coverage. Heidelberger Druckmaschinen AG occupies a position among precision engineering specialists focused on commercial and security printing systems. These three anchors represent divergent competitive vectors: high-velocity fulfillment scaling, aqueous ink formulation dominance, and precision sheet-fed engineering heritage respectively.
| Leading Market Players |
|---|
| HP Inc. |
| Canon Inc. |
| Ricoh Company Ltd. |
| Xerox Holdings Corporation |
| Heidelberger Druckmaschinen AG |
| Bobst Group SA |
| Koenig & Bauer AG |
| Seiko Epson Corporation |
| Fujifilm Holdings Corporation |
| Others |
Value Chain & Pricing Dynamics
EU F-Gas Regulation compliance gates both equipment qualification and price stratification across European installations, forcing converters to absorb LED-UV retrofit premiums or accept depreciated asset valuations on gas-dependent curing systems.
Pricing Analysis
REACH dictates the pricing tier structure across European printing equipment markets, separating certified water-based ink systems from legacy solvent platforms facing accelerated depreciation. Three-tier pricing structure across premium, standard, and economy levels reflects energy-efficiency certification, after-sales service bundling, and geographic proximity to technical support hubs. Cost compression in mid-volume commercial segments is intensifying because equipment-as-a-service contracting compresses upfront capital recognition. Small-format commercial printers exhibit highest price sensitivity, while security printing operations show lowest sensitivity due to precision registration requirements and regulatory compliance mandates.
Supply Chain Analysis
Strait of Malacca transit underwrites photopolymer plate and specialty ink shipments from Japanese chemical manufacturers to Southeast Asian packaging converters. High-resolution printhead manufacturing concentrates in Germany and Japan, while wide-format assembly bases cluster in China's Yangtze River Delta. Supply chain risk centers on single-source vulnerability for piezoelectric printhead ceramics and precision servo motors. Distribution runs through OEM-direct channels for enterprise systems and authorized dealer networks for mid-volume commercial installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service contract attach rates and consumable replenishment programs are expanding faster than hardware unit shipments, particularly among e-commerce fulfillment operators with seasonal volume volatility.
For Market Incumbents: Secure aftermarket service revenue streams through predictive maintenance platforms and remote diagnostics capabilities. Digital-native entrants threaten traditional capital sales models with usage-based billing penetration in Benelux and Nordic markets. Capacity addition in India's Maharashtra and Gujarat industrial corridors captures packaging modernization demand. Certification investment in BIS energy labeling creates first-mover positioning against unverified competitors. For New Entrants and Emerging Players: Anchor in India's pharmaceutical serialization compliance segment, where FSSAI track-and-trace mandates drive flexographic-to-digital conversion. Short-run corrugated packaging for regional food manufacturers represents the most penetrable application white-space. Equipment-as-a-service contracting with bundled consumable provisioning offers the strongest go-to-market angle against capital-constrained mid-volume converters. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across thermal inkjet fulfillment segments as single-pass architectures reduce per-unit infrastructure requirements. Long-term viability favors OEMs with recurring revenue depth exceeding fifty percent of total mix. Acquisition targets should demonstrate installed base density in e-commerce logistics corridors. The signal to watch is same-day delivery promise expansion driving edge-printing node deployment velocity.| Strategic Initiative | Industry Significance |
|---|---|
| LED-UV Curing Technology Licensing | EU Green Deal energy specifications pull adoption across German and Italian packaging converters. |
| Equipment-as-a-Service Platform Launch | Usage-based billing penetrates Benelux marketing services providers with seasonal volume patterns. |
| Backward Integration into Printhead Manufacturing | Captive supply of piezoelectric ceramics reduces single-source vulnerability for precision components. |
| India Packaging Modernization Partnership | FSSAI serialization compliance drives flexographic-to-digital conversion in Maharashtra industrial clusters. |
| Predictive Maintenance Software Development | Remote diagnostics capabilities secure recurring revenue streams from e-commerce fulfillment operators. |
Study Parameters
A spread of perspectives from plant engineers at packaging converters, procurement leads at third-party logistics operators, aftermarket service heads at OEMs, and regulatory affairs specialists at ink formulation companies converged on the working assumptions. Primary interviews combined with secondary validation from SEC filings of diversified technology manufacturers, ECHA REACH substance registration databases, EU F-Gas Regulation implementation reports, and customs trade data for printing machinery imports. Bottom-up equipment shipment tallies triangulated against top-down end-use demand estimates across e-commerce, pharmaceutical, and food manufacturing verticals.
Segmentation dimensions modeled span product type, application, technology, and end-user category across the analysis window. Product type captures inkjet, digital, laser, and additive system architectures. Application tracks packaging, labeling, commercial printing, and textile decoration intensity levels. Technology distinguishes offset, flexographic, screen, and gravure process capabilities. End-user segmentation separates e-commerce fulfillment operators, manufacturers, publishing houses, and advertising agencies. CAGRs derived from installed base evolution, replacement cycle compression, and penetration rate assumptions for variable-data printing capabilities.
Decision-makers should treat outputs as directional under assumptions of sustained e-commerce fulfillment expansion and REACH compliance enforcement continuity; material deviation in substrate cost volatility or printhead supply disruption would warrant model refresh. Practitioners should keep alternative scenarios live as LED-UV curing adoption curves and equipment-as-a-service contracting penetration rates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Dental Ceramics Market
Others
Residential Electrical Conduit Market
Others
Advanced Fiber-Based Gasket Market
Others
Solar Animal Repellent Market
Others
Aerospace and Defense Fiber Optic Cables Market
Others
Solar Animal Repeller Market
Others
Ceramic Machinery Market
Others
Brazil Lime Market
Others
Vegan Confectionery Market
Others
Global Contactless Biometrics Technology Market
Others
Water and Waste Water Treatment Chemicals Market
Others
3D Printing Construction Market
Others
Billet Market
Others
North America Astrology Market
Others
PCB Laminate Market
Others
Lined Tank Market