
 Nyerereite Market | 2026-2036
Nyerereite Market Size, Share, and Industry Trends Forecast 2026-2036
Nyerereite Market Analytics
East African artisanal mining cooperatives is pivoting toward traceable supply chains for rare carbonatite-derived minerals. Weinrich Minerals Company leverages its established dealer network to sustain premium specimen flows from Tanzanian source localities. Zeolyst International anchors industrial offtake through synthetic analog production that bypasses natural scarcity constraints. Clariant competes in adjacent zeolite markets with processing expertise transferable to carbonate mineral refinement.
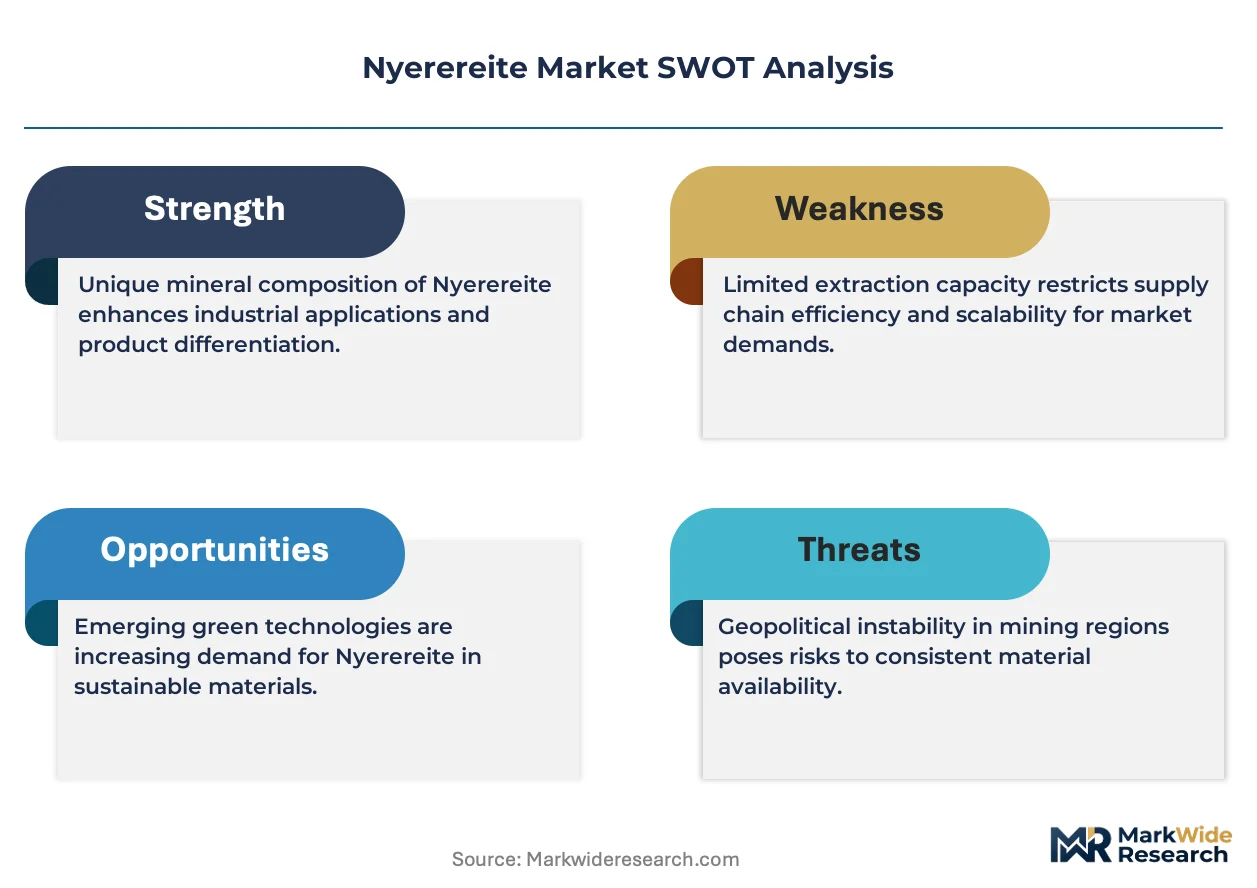
Nyerereite is a rare sodium calcium carbonate mineral (Na₂Ca(CO₃)₂), typically forming ephemeral white to gray phenocrysts in natrocarbonatite lavas with rapid alteration to gaylussite upon atmospheric exposure; its primary commercial purpose lies in specialty geological reference collections, research material procurement, and niche industrial catalyst precursors. Nyerereite Crystals command the highest margin pool due to unaltered specimen rarity and museum-grade certification requirements, while Synthetic Nyerereite represents the fastest-growing category as laboratories and catalyst manufacturers seek reproducible composition without volcanic sourcing volatility. Nyerereite Powder occupies a mature, price-sensitive position serving educational and analytical reagent markets where substitution tolerance runs higher.
Tanzania's Mining Commission, Kenya's Ministry of Petroleum and Mining, and ISO 17025 accreditation frameworks collectively shape market access through export licensing, environmental impact thresholds, and specimen authenticity verification protocols that disqualify uncertified material from institutional procurement channels. Stakeholders must monitor evolving East African Community harmonized mining codes and build dual sourcing strategies spanning natural specimen networks and controlled synthetic production before regulatory fragmentation hardens supply asymmetries.
Market Dynamics
East African artisanal mining cooperatives is pivoting toward traceable supply chains for rare carbonatite-derived minerals. Stricter extraction permitting under Kenya's Mining Act revisions is constraining raw material availability and reshaping competitive positioning across collector and research procurement channels.
Growth Catalysts
- ISO 17025 accreditation frameworks:Specimen authenticity verification protocols are disqualifying uncertified material from institutional procurement channels, creating certified-supplier premiums.
- Synthetic analog production:Laboratories and catalyst manufacturers seek reproducible composition without volcanic sourcing volatility, expanding addressable demand beyond natural specimen constraints.
- Tanzania's Arusha region:Proximity to the type locality at Ol Doinyo Lengai volcano supports direct collector and research procurement with minimized logistics friction.
Market Restraints
- Volcanic eruption dependency:Natural nyerereite forms only in natrocarbonatite lava effusions from Ol Doinyo Lengai, creating single-point-of-failure supply concentration.
- Atmospheric alteration:Rapid conversion to gaylussite upon exposure limits unaltered specimen recovery windows and degrades museum-grade inventory.
- Kenyan export licensing:Tanzania's Mining Commission harmonization delays with Kenya's Ministry of Petroleum and Mining create cross-border documentation bottlenecks.
Strategic Opportunities
- Kenyan Rift Valley expansion:Underexplored carbonatite complexes near Homa Bay and Rangwa present prospective source diversification beyond Tanzania's volcanic monopoly.
- Catalyst precursor applications:Sodium calcium carbonate chemistry offers niche industrial offtake in specialty chemical synthesis where synthetic reproducibility outweighs natural provenance.
- East African Community harmonized mining codes:Pending regulatory alignment would streamline multi-country sourcing networks and reduce permit fragmentation costs.
Industry Challenges
- Specimen stabilization expertise:Shortage of trained mineralogists capable of rapid collection and hermetic sealing before atmospheric degradation erodes recoverable inventory value.
- Dual-track certification complexity:Laboratories must maintain parallel quality systems for natural specimen provenance and synthetic batch reproducibility, straining analytical capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nyerereite Market |
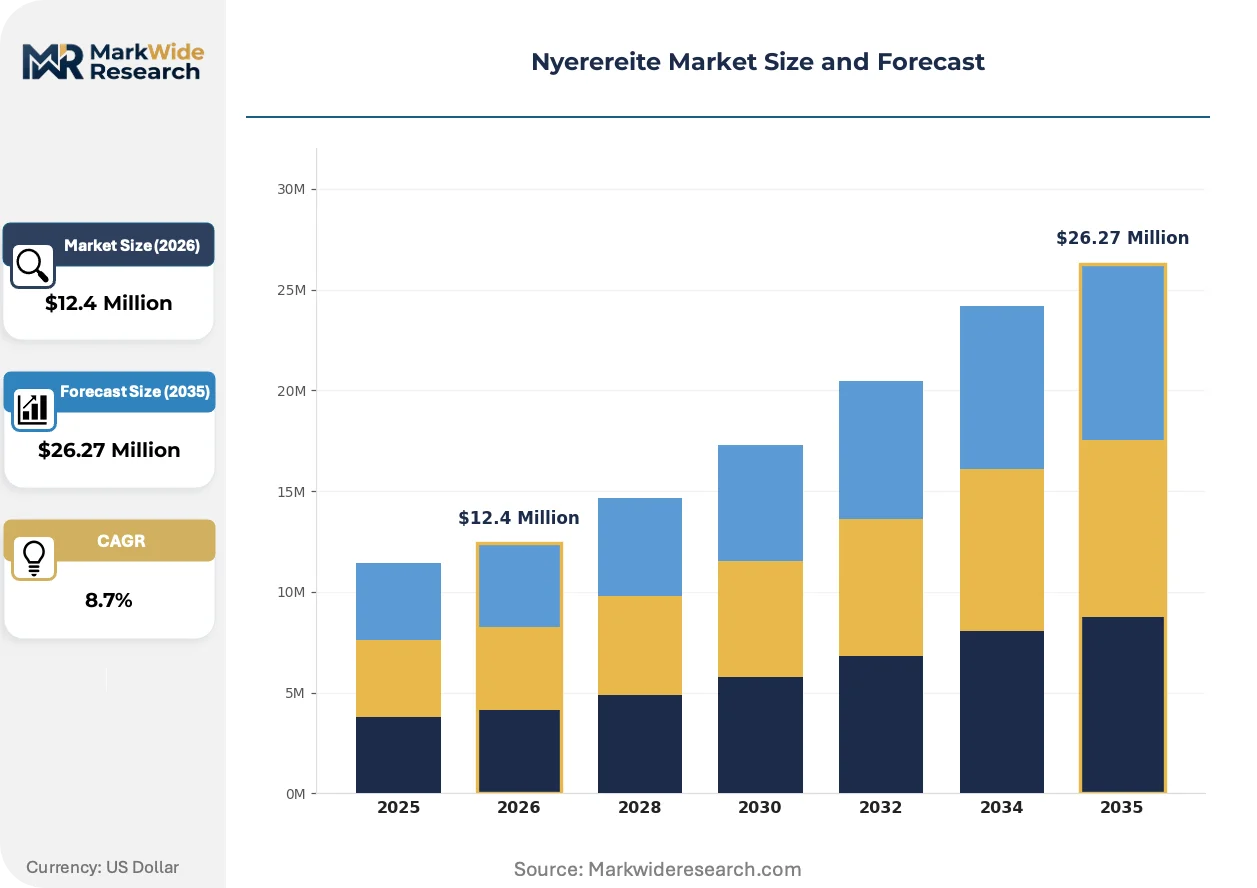
| Market Size in 2026 | $12.4 Million |
| Market Size in 2035 | $26.27 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nyerereite Crystals, Nyerereite Powder, Synthetic Nyerereite, Nyerereite Granules Application: Agriculture, Construction, Manufacturing, Chemical Processing End User: Fertility Management, Mineral Suppliers, Construction Companies, Chemical Industries Packaging Type: Bags, Drums, Containers, Bulk |
| Companies Covered | Weinrich Minerals Company, R&M Minerals, John Betts Fine Minerals, Allminerals LLC, Zeolyst International, Zeocem, Gordes Zeolite, Clariant, IDA-ORE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nyerereite Market Evolving Landscape
Synthetic production methods are actively reshaping supply security for research and industrial end-uses. Three developments are compressing traditional collector-market dominance while opening adjacent commercial pathways.
Cryogenic stabilization protocols are overtaking conventional hermetic sealing for field-collected specimens. Research institutions in Germany and Japan are adopting liquid nitrogen quenching within hours of eruption notification. This technique preserves unaltered crystal structure for museum-grade certification, extending viable recovery windows from hours to weeks and compressing price premiums for degraded material.
REACH substance registration requirements in Europe are forcing synthetic producers to disclose full compositional characterization. ECHA's evolving guidance on inorganic carbonate salts is compelling Zeolyst International and comparable suppliers to invest in analytical documentation beyond basic purity metrics. Industrial catalyst manufacturers are responding by consolidating supplier relationships with REACH-compliant entities, marginalizing uncertified natural specimen traders.
Collector procurement is fragmenting across direct-source dealer networks and academic consignment platforms. Weinrich Minerals Company and established East African dealers are disintermediating traditional auction houses for high-value specimens. This channel shift is most visible in North American institutional acquisitions, where provenance documentation and rapid specimen turnover now outweigh price discovery through centralized marketplaces.
Nyerereite Market Segmentation
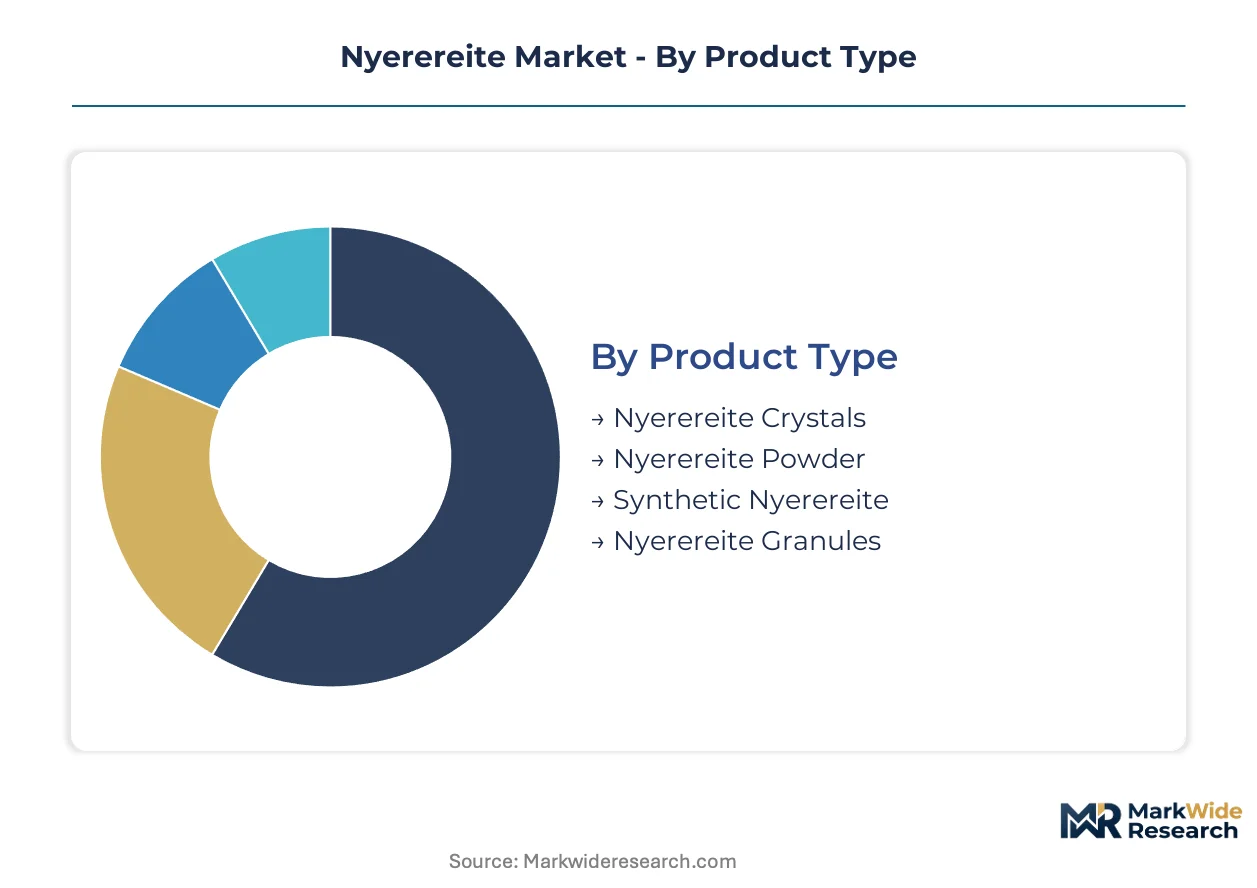
Nyerereite's extreme scarcity and rapid atmospheric alteration create sharp segmentation boundaries between preservation-intensive specimen forms and industrial-processable variants. Product differentiation tracks directly against degradation risk, while end-use applications split between collector-driven premium channels and volume chemical offtake.
Product Type:
Standalone preservation systems dominate the high-value tier, with embedded processing applications driving industrial volume.
- Nyerereite Crystals:Unaltered phenocrysts from Ol Doinyo Lengai natrocarbonatite lavas require immediate hermetic sealing or cryogenic quenching to prevent gaylussite conversion. Museum-grade certification under ISO 17025 protocols commands substantial premiums from German and Japanese research institutions.
- Synthetic Nyerereite:Laboratory-produced sodium calcium carbonate bypasses volcanic sourcing volatility through controlled precipitation methods. Catalyst manufacturers and analytical reagent suppliers in Europe favor this reproducible composition as REACH registration requirements harden.
- Nyerereite Powder:Milled material serves educational and analytical markets where atmospheric exposure tolerance runs higher.
- Nyerereite Granules:Sized particulate for controlled-release applications in specialty chemical synthesis.
Volume placements concentrate in Synthetic Nyerereite; the faster expansion belongs to Nyerereite Crystals as cryogenic stabilization extends recoverable inventory windows.
Application:
Cost tier stratification separates premium research allocation from commodity chemical consumption.
- Chemical Processing:Sodium calcium carbonate chemistry provides precursor material for specialty synthesis where compositional precision outweighs natural provenance. Industrial catalyst manufacturers consolidate supplier relationships with REACH-compliant synthetic producers.
- Agriculture:Carbonate-derived soil amendments from East African carbonatite complexes serve fertility management programs in Tanzania's Arusha corridor.
- Construction:Limited uptake in cement chemistry research and alkaline aggregate studies.
- Manufacturing:Niche incorporation into refractory material testing and ceramic glaze formulation.
Revenue concentration sits with Chemical Processing; Agriculture claims the steepest expansion trajectory as Kenyan Rift Valley sourcing networks mature.
End User:
Customer type fragmentation splits between institutional procurement with documentation requirements and industrial buyers prioritizing batch consistency.
- Mineral Suppliers:Specialty dealers like Weinrich Minerals Company sustain premium specimen flows through direct-source networks in Tanzania, disintermediating traditional auction channels for North American institutional acquisitions.
- Chemical Industries:Catalyst manufacturers and reagent producers drive synthetic offtake, consolidating around suppliers with full ECHA compositional disclosure.
- Fertility Management:Agricultural cooperatives in East Africa source carbonatite-derived inputs for regional soil amendment programs.
- Construction Companies:Limited demand from materials research divisions and geotechnical testing laboratories.
Procurement volume aggregates at Chemical Industries; Mineral Suppliers capture the fastest share gains as direct-source dealer networks expand.
Packaging Type:
Supply concentration in hermetic formats reflects the mineral's preservation-critical handling requirements.
- Containers:Sealed vessel systems with inert atmosphere maintenance serve museum-grade specimen transport from Ol Doinyo Lengai to German and Japanese research institutions.
- Bulk:Loose material handling for synthetic production batches and industrial chemical processing where atmospheric exposure poses minimal degradation risk.
- Drums:Intermediate containment for milled powder and granule shipments to analytical reagent distributors.
- Bags:Standard flexible packaging for lower-grade educational material and agricultural applications.
Shipment value concentrates in Containers; Bulk formats gain share fastest as synthetic production scales beyond natural specimen constraints.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ol Doinyo Lengai volcano in northern Tanzania anchors the geography as the sole natural source of unaltered nyerereite phenocrysts. Collector and research procurement concentrates in East African corridors with direct access to carbonatite lava flows. Cross-border regulatory friction between Tanzania and Kenya shapes supply chain configuration.
Tanzania
Arusha region hosts the type locality at Ol Doinyo Lengai, where proximity to eruption events enables rapid specimen recovery before atmospheric alteration. Tanzania's Mining Commission enforces export licensing for carbonatite-derived minerals under revised 2023 extraction codes. Cryogenic stabilization facilities in Arusha city now extend viable collection windows from hours to weeks.
Kenya
Homa Bay and Rangwa carbonatite complexes offer prospective diversification beyond Tanzania's volcanic monopoly for collector networks. Kenya's Ministry of Petroleum and Mining imposes stricter environmental impact thresholds under Mining Act revisions that constrain raw material availability. Nairobi-based mineral dealers are building traceable supply chains to satisfy ISO 17025 accreditation requirements.
Germany
Research institutions in Munich and Frankfurt drive museum-grade specimen demand with hermetic transport specifications. ECHA's REACH substance registration requirements for inorganic carbonate salts compel full compositional disclosure from suppliers. Cryogenic quenching protocols developed at German universities now preserve unaltered crystal structure for extended certification windows.
Japan
Tokyo and Osaka mineralogical museums anchor institutional acquisition budgets for rare carbonate reference collections. METI standards for analytical reagent purity influence procurement specifications for synthetic sodium calcium carbonate. Direct-source dealer networks now disintermediate traditional auction channels for North American and European institutional buyers.
United States
Specialty mineral dealers in Tucson and Denver sustain premium specimen flows through established East African sourcing relationships. EPA guidelines for chemical precursor handling shape laboratory procurement of synthetic carbonate materials. Research universities in California and Massachusetts consolidate supplier relationships around REACH-compliant synthetic producers.
Nyerereite Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue synthetic analog production to bypass volcanic sourcing constraints. The vendor base splits between specialty mineral dealers with direct-source networks and industrial chemical suppliers with controlled precipitation capabilities. Three archetypes dominate: traceable supply chain operators, synthetic reproducibility specialists, and museum-grade certification handlers. Competitive moves concentrate on geographic expansion into underexplored carbonatite complexes and technology licensing for cryogenic stabilization protocols.
Among specialty mineral dealers, Weinrich Minerals Company and John Betts Fine Minerals represent the direct-source archetype with established networks in Tanzania. Zeolyst International occupies a position exemplifying synthetic production scale for industrial catalyst applications. Clariant sits within the adjacent zeolite processing tier with expertise transferable to carbonate mineral refinement. These three anchors illustrate the market's bifurcation between natural specimen rarity and synthetic reproducibility.
| Leading Market Players |
|---|
| Weinrich Minerals Company |
| R&M Minerals |
| John Betts Fine Minerals |
| Allminerals LLC |
| Zeolyst International |
| Zeocem |
| Gordes Zeolite |
| Clariant |
| IDA-ORE |
| Others |
Value Network & Pricing Analysis
Research institutions in Germany and Japan anchor the dominant pricing model through hermetic transport specifications and museum-grade certification requirements. Their procurement concentration around ISO 17025-accredited suppliers creates substantial premiums for unaltered specimens while compressing margins for degraded inventory.
Pricing Analysis
Warranty-backed cryogenic stabilization now bundles with premium specimen sales, while standard hermetic sealing remains unbundled for mid-tier transactions. Three-tier pricing structure across museum-grade certified, field-stabilized, and degraded-altered tiers tracks directly against alteration risk and certification completeness. Price differentiation hinges on ISO 17025 accreditation status and provenance documentation depth. Cost compression in the powder and granule segments is intensifying because synthetic producers achieve REACH-compliant batch reproducibility at scale. Chemical processing buyers exhibit highest price sensitivity, whereas mineral suppliers serving institutional collectors demonstrate lowest sensitivity.
Supply Chain Analysis
Single-source vulnerability sits with Ol Doinyo Lengai volcano in Tanzania, where natrocarbonatite lava effusions provide the sole natural source of unaltered nyerereite phenocrysts. Geographic supply concentration centers on Tanzania, Kenya, and Germany, with the latter hosting cryogenic quenching facilities that extend recoverable inventory windows. Raw material dependencies rest on volcanic eruption timing, atmospheric exposure windows, and hermetic sealing infrastructure. Supply chain risk stems from regulatory restriction, specifically export licensing bottlenecks between Tanzania's Mining Commission and Kenya's Ministry of Petroleum and Mining. Distribution runs through direct-source dealer networks disintermediating traditional auction channels for North American and European institutional buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a consolidation play where REACH registration requirements and ISO 17025 accreditation thresholds force uncertified traders toward exit or acquisition.
For Market Incumbents: Cement supply security through backward integration into cryogenic stabilization infrastructure at Arusha collection points. Deepen provenance documentation systems to defend against synthetic substitution threats from Zeolyst International and comparable REACH-compliant producers. Channel control through direct-source dealer networks represents the critical lever for margin preservation. For New Entrants and Emerging Players: Synthetic production technology offers the most penetrable wedge for laboratory and catalyst manufacturer procurement channels. White-space targets include Kenyan Rift Valley carbonatite complexes near Homa Bay and Rangwa for source diversification, plus European industrial offtake seeking ECHA-compliant compositional disclosure. A go-to-market angle anchored to batch reproducibility certificates bypasses volcanic sourcing volatility entirely. For Investors and Strategic Acquirers: The window for entry favors vertically integrated specialists with captive cryogenic infrastructure and dual-track certification capabilities. Long-term viability rests on synthetic production scale combined with traceable natural specimen networks. The signal to watch is East African Community harmonized mining code implementation as inflection indicator for multi-country sourcing cost structures.| Strategic Initiative | Industry Significance |
|---|---|
| Cryogenic Stabilization Infrastructure Buildout | Extends recoverable inventory windows from hours to weeks for German and Japanese museums. |
| REACH Registration Completion | Unlocks European catalyst manufacturer procurement channels for synthetic producers. |
| Direct-Source Dealer Network Expansion | Disintermediates auction houses for North American institutional acquisitions. |
| Kenyan Rift Valley Prospecting | Diversifies supply beyond Tanzania's volcanic monopoly toward Homa Bay carbonatites. |
| ISO 17025 Accreditation Investment | Qualifies material for institutional procurement channels that exclude uncertified traders. |
Research Methodology
Independent corroboration across mineralogical museum curators, specialty mineral dealers, carbonatite geologists, and synthetic chemistry producers underwrites the qualitative findings. Primary interviews with Tanzania Mining Commission officials, Kenya Ministry of Petroleum and Mining licensing officers, and ECHA registration specialists combined with secondary validation from customs export records, geological survey publications, and ISO accreditation databases. Bottom-up specimen flow tracking and top-down market sizing triangulate volume estimates.
Rate-of-change decomposition across product type, application, end user, and packaging format dimensions structures the analytical framework. CAGRs derive from segment-level growth trajectory blending and cross-referencing against synthetic production capacity announcements and volcanic eruption frequency patterns. Modeled inputs include cryogenic stabilization adoption curves, REACH registration completion timelines, and East African Community regulatory harmonization progress.
Several conditions sit outside the modeled scope, including unscheduled volcanic eruptions, abrupt export moratoriums, and breakthroughs in atmospheric alteration prevention chemistry. Forecasts reflect documented assumptions about synthetic substitution rates and certification penetration curves. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Viral Vector Contract Development and Manufacturing Organization (CDMO) Market
Others
Semiconductor Gas Filters Market
Others
UK Real Estate Hospitality Market
Others
Smart-Connected Power Plug Socket Market
Others
5G Devices Market
Others
Magnetic Stripe Readers Market
Others
Subtilisin Market
Others
Industrial Hooters Market
Others
Dried Fruit Extracts Market
Others
Global Virtual Keyboard Market
Others
Interference Mitigation Filters Market
Others
Global Application Testing Services Market
Others
Asia-Pacific Eyelash Serum Market
Others
Dandelion Market
Others
Wearable Solar Devices Market
Others
Sprockets Market