
 Aircraft Switches Market | 2026-2036
Aircraft Switches Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Switches Market Analysis
EU Aviation Safety Agency airworthiness mandates for enhanced cockpit human-machine interface standards is restructuring the cost-of-entry calculus for switch manufacturers seeking European OEM qualification. Honeywell International Inc leverages its integrated avionics platform to bundle switch products with flight control systems, sustaining channel control across major airframe programs. Safran SA anchors its position through specialized electromechanical architectures designed for Airbus platforms, while TE Connectivity Corporation competes on connector-to-switch integration that reduces installation complexity.
Aircraft switches are electromechanical or solid-state devices engineered to complete, interrupt, or redirect electrical circuits within airframe systems, typically rated for operational lifecycles exceeding 100,000 actuations and temperatures ranging from -55°C to 125°C per MIL-STD-810 requirements; they serve as primary command interfaces between flight crews and avionics, environmental, or propulsion subsystems. Toggle switches retain dominant share in legacy military platforms where mechanical reliability outweighs weight penalties, yet electronic switch technology represents the fastest-expanding segment as fly-by-wire architectures proliferate across civil aviation. Hybrid technology configurations concentrate margin pools where manufacturers combine tactile mechanical feedback with digital output signaling to satisfy dual-redundancy requirements without full optical conversion costs.
The Federal Aviation Administration governs TSO-C112 certification for cockpit controls, while the European Union Aviation Safety Agency enforces CS-25 airworthiness criteria that dictate switch placement accessibility and failure-mode redundancy; both frameworks compel manufacturers to maintain dual-qualified production lines, inflating fixed costs but creating regulatory moats against unqualified entrants. China's Civil Aviation Administration and its GB standards for indigenous commercial aircraft programs add a third compliance layer as COMAC C919 production scales. Stakeholders must monitor divergence between FAA and EASA human factors standards, as incompatible ergonomic requirements threaten to fragment switch platform commonality across transatlantic programs.
Market Dynamics
Fly-by-wire architecture mandates from the FAA are forcing electromechanical switch suppliers to redesign product portfolios for digital signal compatibility, compressing development cycles and elevating qualification barriers.
Growth Catalysts
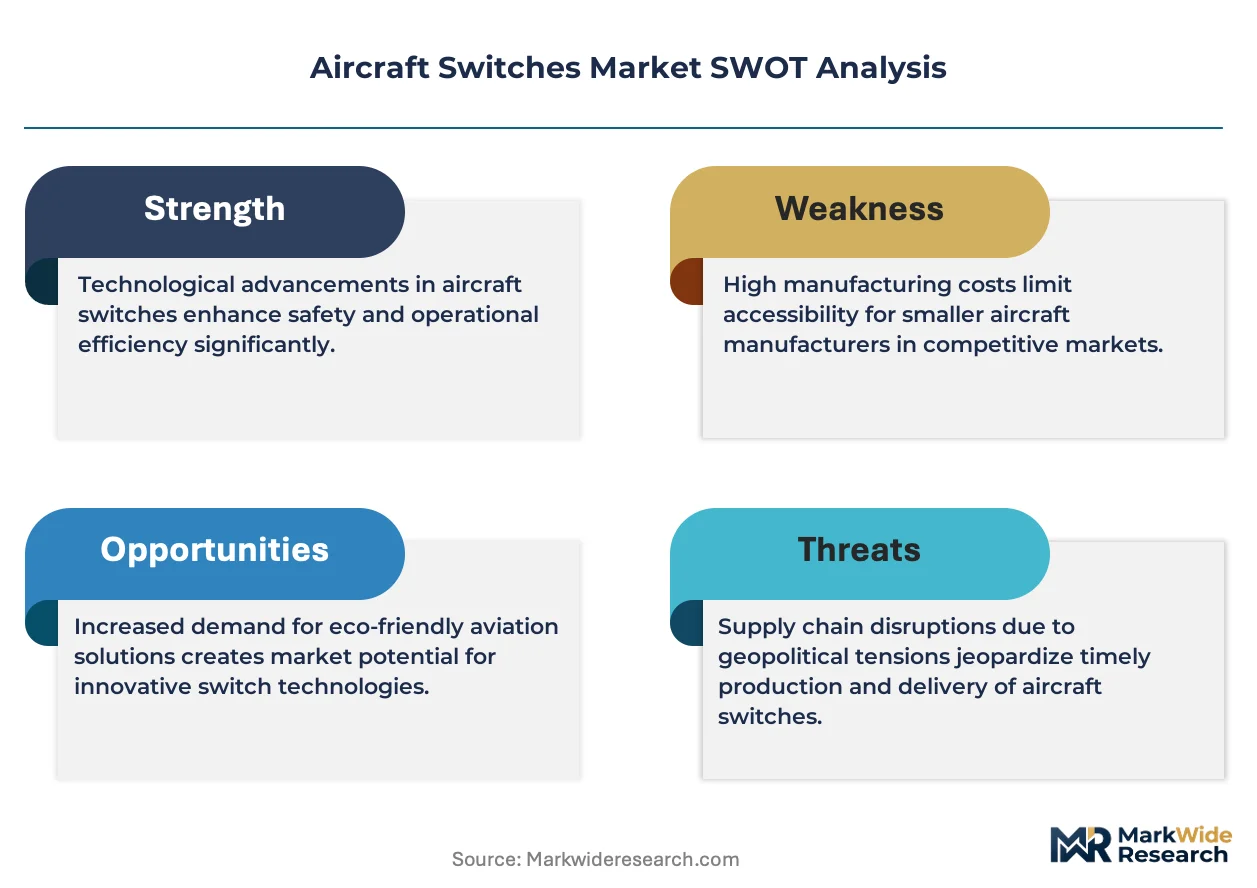
- TSO-C112 Certification Pathways:FAA cockpit control mandates create captive demand for qualified switchgear across Boeing and Airbus supply chains.
- COMAC C919 Production Ramp:China's indigenous commercial aircraft program requires certified switch suppliers for flight deck and cabin systems.
- Solid-State Switch Technology:Optical and hall-effect architectures replace mechanical contacts in next-generation avionics, extending operational lifecycles.
Market Restraints
- Dual-Qualified Production Lines:FAA and EASA incompatible ergonomic standards force manufacturers to maintain separate tooling, inflating fixed cost structures.
- Precious Metal Input Volatility:Palladium and gold contact plating exposes margins to commodity price swings in electromechanical switch production.
- Supply Concentration in US Tier-One:Boeing and Lockheed Martin procurement consolidation limits channel access for mid-tier switch vendors.
Strategic Opportunities
- Urban Air Mobility Platforms:eVTOL manufacturers in Germany and the United States require lightweight, redundant switch architectures for piloted and autonomous flight modes.
- Aftermarket Retrofit Channels:Legacy military fleet modernization programs create demand for MIL-STD-810 qualified drop-in replacements.
- Hybrid Tactile-Digital Convergence:Combining mechanical feedback with digital output signaling captures margin pools between full electromechanical and solid-state extremes.
Industry Challenges
- Human Factors Engineering Talent Scarcity:FAA and EASA divergent cockpit accessibility standards require specialized ergonomics expertise that concentrates at Honeywell and Safran.
- DO-178C Software Certification Timelines:Electronic switch firmware qualification for fly-by-wire systems extends development cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Switches Market |
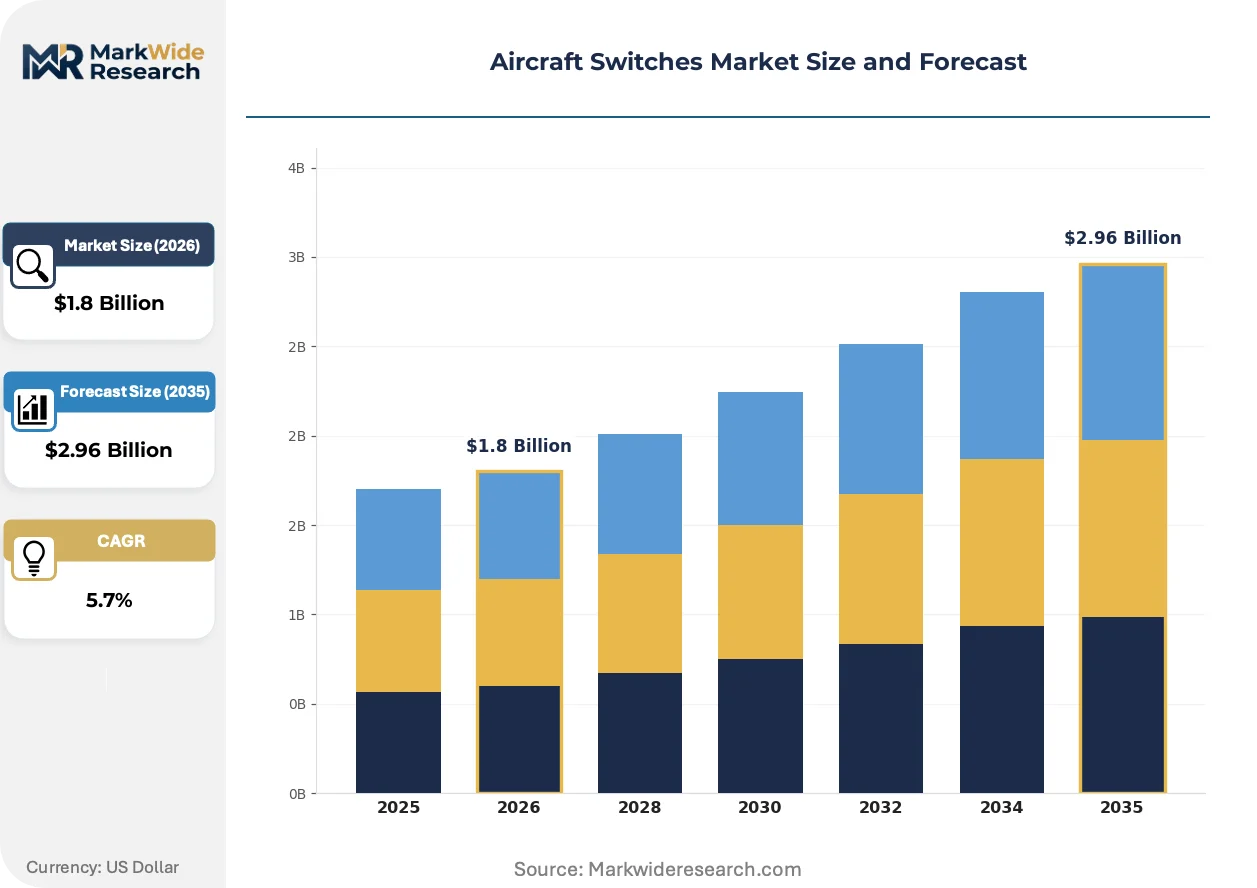
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Toggle Switches, Push Button Switches, Rotary Switches, Rocker Switches Technology: Mechanical, Electronic, Optical, Hybrid End User: Civil Aviation, Military Aviation, MRO Services, OEMs Installation Type: Panel Mounted, Surface Mounted, Flush Mounted, Built-in |
| Companies Covered | Eaton Corporation plc, AMETEK Inc, Honeywell International Inc, ITT Inc, Curtiss-Wright Corporation, Safran SA, TE Connectivity Corporation, Meggitt PLC, RTX Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Switches Market Emerging Trajectories
Aviation switch technology is bifurcating between legacy mechanical reliability and solid-state miniaturization, with hybrid architectures capturing intermediate applications.
Photonic switching technology is decentralizing cockpit control signal distribution by replacing copper wiring with fiber-optic pathways. Regional jet manufacturers in Brazil and Canada are adopting these systems for weight reduction. The shift is decentralizing avionics architecture away from centralized switch panels toward distributed control nodes.
EU Aviation Safety Agency CS-25 airworthiness criteria now mandate redundant failure modes for all flight-critical cockpit controls. This compels manufacturers to engineer dual-channel switch outputs without single points of failure. Airbus A320neo and A350 programs are driving first adoption, with suppliers redesigning electromechanical platforms for digital redundancy.
Airline procurement teams are consolidating switch purchasing through avionics platform integrators rather than direct component sourcing. This channel compression favors vendors bundled with Honeywell or Collins Aerospace flight control systems. The pattern is most pronounced in North American and European flag carrier fleet renewals.
Aircraft Switches Market Segmentation
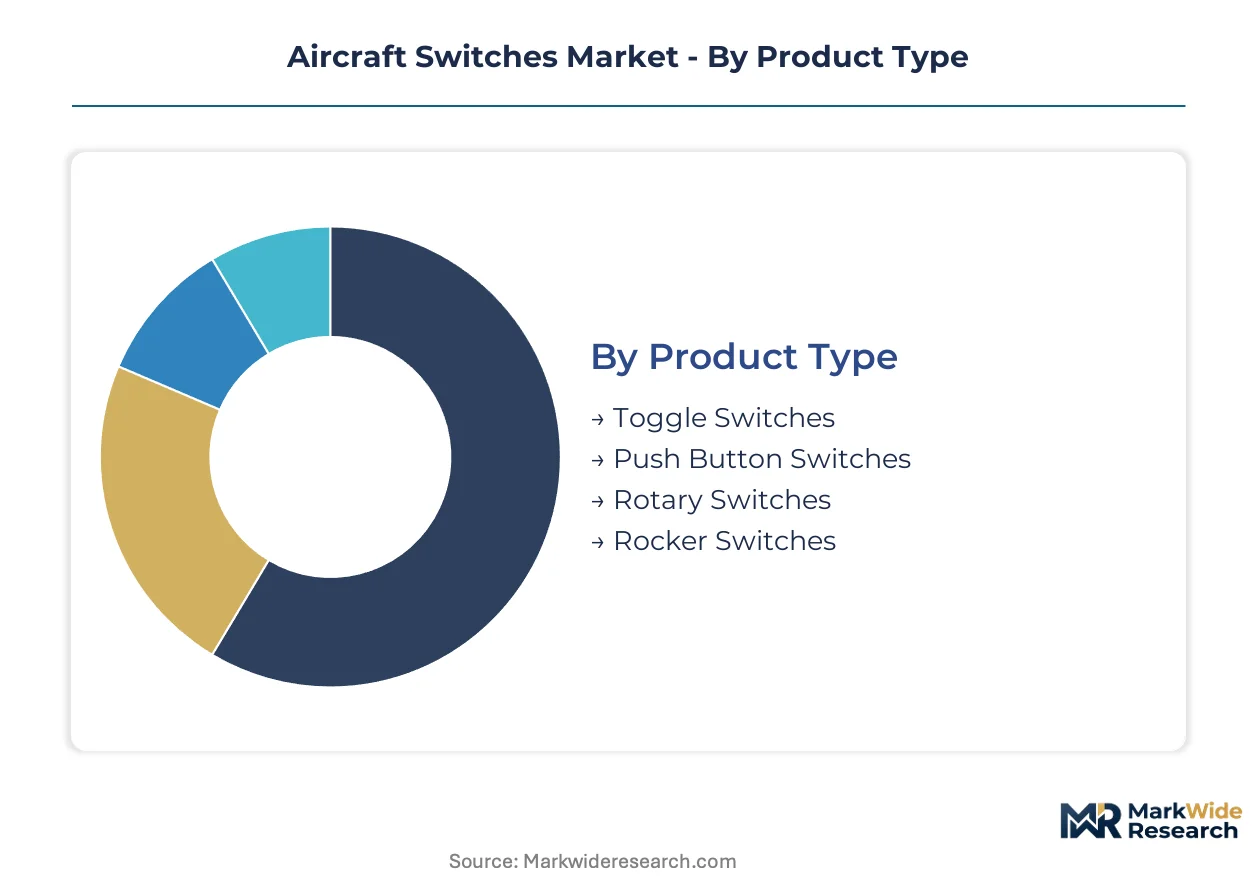
Segmentation in aircraft switches reveals how procurement patterns split between legacy platform sustainment and next-generation avionics integration. Buyers prioritize different performance thresholds depending on whether they serve military retrofits, civil OEM line-fit, or aftermarket MRO channels.
Product Type:
Cost tier separates buyers seeking commodity replacements from those procuring mission-critical flight deck controls.
- Toggle Switches:Mechanical lever-actuated devices with positive detent feedback, typically rated for 100,000+ cycles per MIL-STD-810. Demand concentrates in United States military platforms where mechanical redundancy outweighs weight penalties; F-15 and C-130 fleet sustainment programs drive procurement volumes.
- Push Button Switches:Momentary or latching actuators with tactile dome or mechanical contact mechanisms. Airbus A320neo and Boeing 737 MAX flight decks specify these for crew-alerting functions; EASA CS-25 human factors mandates are elevating qualification complexity for European-qualified suppliers.
- Rotary Switches:Multi-position selectors for mode selection in avionics subsystems.
- Rocker Switches:Bistable actuators common in cabin management and environmental control panels.
Toggle switches lead volumes today; push button switches are gaining share fastest.
Technology:
Application maturity determines whether buyers accept qualification risk on solid-state architectures or default to proven electromechanical platforms.
- Mechanical:Contact-based switching with physical metal-to-metal closure, operating across -55°C to 125°C temperature ranges. Legacy military and regional jet programs in Brazil and Canada specify these for field-repairability; qualification heritage reduces FAA certification timelines.
- Electronic:Solid-state architectures employing hall-effect or capacitive sensing without moving contacts. Fly-by-wire programs at Airbus and Boeing are displacing mechanical alternatives; DO-178C software certification extends development cycles 18-24 months.
- Optical:Photonic signal transmission eliminating electromagnetic interference susceptibility.
- Hybrid:Configurations combining tactile mechanical feedback with digital output signaling for dual-redundancy requirements.
Mechanical platforms dominate installed base; electronic architectures show steepest expansion trajectory.
End User:
Customer procurement authority shapes whether switch suppliers sell direct to airframers or through avionics integrators.
- Civil Aviation:Commercial airline and business jet operators requiring TSO-C112 certified cockpit controls. Fleet modernization at United States and European flag carriers is compressing supplier qualification windows; channel consolidation through Honeywell and Collins Aerospace limits direct component access.
- Military Aviation:Defense platforms prioritizing mechanical reliability and battlefield serviceability. United States Department of Defense procurement through Lockheed Martin and Boeing Defense anchors demand; MIL-STD-810 environmental qualification is mandatory.
- MRO Services:Aftermarket maintenance, repair, and overhaul providers sourcing drop-in replacements.
- OEMs:Original equipment manufacturers integrating switches at airframe production.
Civil aviation generates largest revenue pool; military aviation maintains most stable procurement cadence.
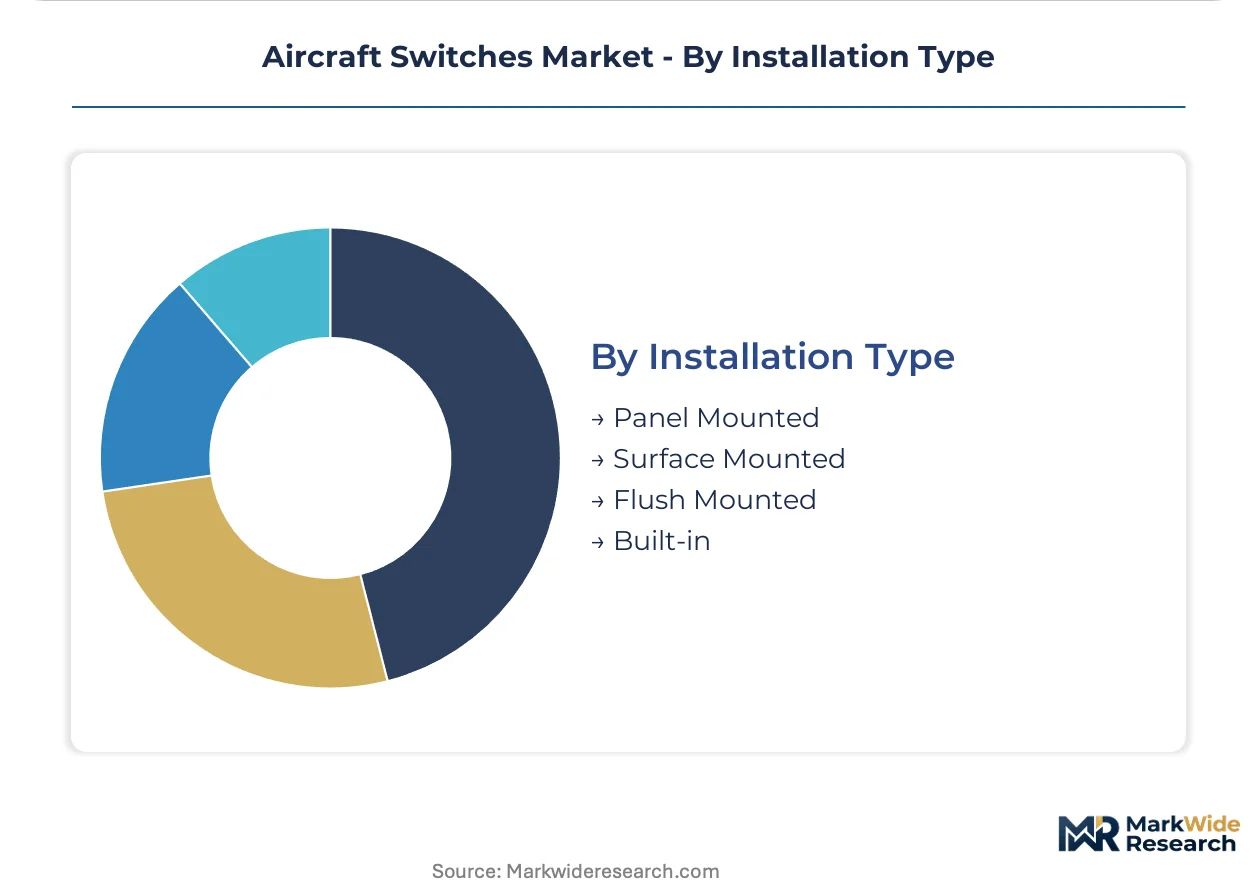
Installation Type:
Volume scale differentiates between high-unit aftermarket replacements and low-unit OEM line-fit programs.
- Panel Mounted:Switches secured through threaded bushings or snap-fit bezels in cockpit instrument panels. COMAC C919 and Airbus A350 production lines in China and France specify these for flight-critical applications; accessibility requirements per EASA CS-25 dictate minimum spacing standards.
- Surface Mounted:Low-profile actuators for space-constrained cabin control stations. Regional jet OEMs in Canada and Brazil adopt these for weight reduction; simplified wiring reduces installation labor hours.
- Flush Mounted:Seamless integration with modern cockpit aesthetic requirements.
- Built-in:Custom-integrated switch modules embedded within larger control assemblies.
Panel mounted configurations anchor OEM demand; surface mounted variants are climbing fastest in regional jet applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled aerospace engineering talent concentrates in the United States, France, and Germany, anchoring design and certification capabilities for flight-critical switchgear. These workforce clusters support OEM supply chains while regulatory divergence between FAA and EASA shapes regional procurement patterns.
United States
Boeing's commercial and defense programs in Washington State and South Carolina drive sustained demand for MIL-STD-810 qualified electromechanical switches. FAA TSO-C112 certification mandates create captive procurement channels for domestic suppliers. The Greater Seattle aerospace cluster hosts tier-one avionics integrators consolidating switch purchasing through platform-level contracts.
France
Airbus final assembly lines in Toulouse and Hamburg-bound component flows anchor European demand for EASA CS-25 certified cockpit controls. EU Aviation Safety Agency human factors standards mandate redundant failure modes, elevating qualification complexity. The Occitanie region hosts specialized electromechanical suppliers serving A320neo and A350 programs.
Germany
eVTOL developers in Munich and Stuttgart require lightweight switch architectures for urban air mobility platforms. The country's national aviation regulator enforces stringent ergonomic accessibility standards for piloted and autonomous flight modes. Bavaria's aerospace engineering corridor concentrates design talent for next-generation solid-state switching technologies.
China
COMAC C919 production scaling in Shanghai creates indigenous demand for certified flight deck and cabin switch systems. GB standards administered by the Civil Aviation Administration impose third compliance layers beyond FAA and EASA frameworks. The Yangtze River Delta hosts emerging domestic suppliers qualifying for narrowbody program integration.
United Kingdom
Defense procurement through BAE Systems and Rolls-Royce sustains demand for mechanical reliability in legacy military platforms. The country's national aerospace regulator maintains alignment with EASA airworthiness criteria post-Brexit. The Midlands manufacturing belt concentrates precision electromechanical fabrication for battlefield-serviceable switchgear.
Aircraft Switches Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across the aircraft switches landscape. The market structure tilts toward consolidation at the tier-one avionics platform level, where channel control determines component access. Three archetypes dominate: integrated flight control system bundlers, specialized electromechanical architects, and connector-to-switch integrators. Competitive moves center on strategic partnerships with airframers and portfolio diversification into solid-state architectures.
Among diversified conglomerates, Eaton Corporation plc and Honeywell International Inc exemplify the integrated platform bundler archetype, leveraging avionics system control to capture switch procurement decisions. Safran SA and TE Connectivity Corporation occupy positions as specialized architects and integrators respectively, with the former concentrated on Airbus-aligned electromechanical designs and the latter competing on installation complexity reduction. AMETEK Inc represents the precision instrumentation specialist tier serving military qualification requirements.
| Leading Market Players |
|---|
| Eaton Corporation plc |
| AMETEK Inc |
| Honeywell International Inc |
| ITT Inc |
| Curtiss-Wright Corporation |
| Safran SA |
| TE Connectivity Corporation |
| Meggitt PLC |
| RTX Corporation |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up electromechanical specialists have consolidated tier-two switch manufacturing in the United States and France, tightening pricing discipline through captive supply of precious-metal contact plating while forcing unintegrated competitors toward spot-market palladium exposure.
Pricing Analysis
The bundled-vs-unbundled service split separates Honeywell and Collins Aerospace platform integrators from standalone component vendors. Three-tier pricing structure across TSO-C112 certified flight-critical, CS-25 qualified commercial, and MIL-STD-810 military grades reflects certification investment amortization. Cost compression in unbundled electromechanical tiers is intensifying because COMAC C919 qualification timelines stretch supplier cash conversion cycles. MRO aftermarket buyers exhibit highest price sensitivity; fly-by-wire OEM line-fit customers prioritize qualification heritage over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Japanese and South Korean suppliers of high-reliability hall-effect sensors for solid-state architectures. Manufacturing concentrates in the United States, France, and China, with Toulouse and Seattle anchoring Airbus and Boeing final assembly demand. Raw material dependencies include palladium contact plating, gold wire bonding, and aerospace-grade thermoset housings. Tariff exposure on Chinese-sourced connector subassemblies threatens margin stability. Distribution runs through tier-one avionics integrators rather than direct airframe procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The aircraft switches market functions as a regulatory compounder where FAA TSO-C112 and EASA CS-25 certification mandates perpetually refresh captive demand across fleet modernization cycles.
For Market Incumbents: Extend platform bundling advantages by embedding switch products within Honeywell and Collins Aerospace flight control system contracts, neutralizing standalone component competitors. Deepen backward integration into precious-metal contact plating to buffer palladium price volatility. Prioritize DO-178C software certification investment to capture fly-by-wire displacement of mechanical architectures.
For New Entrants and Emerging Players: Capture aftermarket retrofit white space in United States military fleet sustainment programs where MIL-STD-810 qualification barriers are lower than civil FAA pathways. Target COMAC C919 supplier qualification in Shanghai as the most penetrable geography given indigenous sourcing mandates. Pursue urban air mobility switch architectures for German eVTOL developers as an uncontested application segment.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier electromechanical specialists lacking fly-by-wire electronic switch portfolios. Long-term viability hinges on dual-certification capability across FAA and EASA frameworks. Watch for divergence between FAA and EASA human factors standards as the signal indicating regulatory fragmentation risk or consolidation opportunity.
| Strategic Initiative | Industry Significance |
|---|---|
| DO-178C Software Certification Investment | Electronic switch firmware qualification extends development cycles but locks in fly-by-wire platform positions at Airbus and Boeing. |
| Dual-Qualified Production Line Expansion | Simultaneous FAA TSO-C112 and EASA CS-25 certification capability captures transatlantic program commonality. |
| Precious Metal Backward Integration | In-house palladium plating capacity insulates margins from commodity volatility in electromechanical switch production. |
| Urban Air Mobility Partnership | eVTOL switch architecture development with Lilium or Joby Aviation opens uncontested autonomous flight mode applications. |
| COMAC C919 Supplier Qualification | CAAC GB standards compliance positions vendors for China's indigenous narrowbody production scaling. |
Methodological Framework
Bottom-up airframe production modeling reconciled against top-down avionics platform tracking forms the analytical core of this study. Primary interviews with flight control system engineers, tier-one procurement managers, MRO aftermarket specialists, and regulatory certification consultants were validated against secondary sources including FAA TSO filings, EASA certification databases, COMAC supplier disclosures, and MIL-STD-810 qualification records. Supply-side triangulation across electromechanical and solid-state switch manufacturers was cross-referenced against Boeing and Airbus delivery schedules.
Historical trendline analysis of toggle, push-button, and electronic switch procurement patterns informed projection frameworks across the analysis window. Segmentation dimensions modeled include product type, technology architecture, end-user procurement authority, and installation configuration. CAGRs were derived from weighted average of airframe delivery forecasts and technology displacement curves, with specific inputs from fly-by-wire adoption rates and fleet modernization program announcements.
Regulatory divergence between FAA and EASA, COMAC production schedule delays, and palladium price volatility are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions regarding certification timeline continuity and platform bundling persistence. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Europe Indoor Air Purification Market
Others
Global Optical Coordinate Measuring Machine Market
Others
Air Separation Module Kit Market
Others
Czech Republic Market
Others
Communication Base Station Body Market
Others
Digital Mortgage Software Market
Others
Football Sportswear Market
Others
Military Image Intensifier Market
Others
TWS Micro-Battery Market
Others
China Automotive LED Lighting Market
Others
Gas Radiators Market
Others
Aircraft Cameras Market
Others
Fibert Market
Others
Halogen Free Flame Retardant Bopet Films Market
Others
Medical Simulation Market
Others
Aircraft Exterior Lighting Market