
 Linear Shaft Market | 2026-2036
Linear Shaft Market Size, Share, and Industry Trends Forecast 2026-2036
Linear Shaft Market Analytics
Precision grinding and CNC machining labor availability is collapsing across major production hubs, forcing shaft manufacturers to automate finishing operations or relocate capacity. THK Co. Ltd leverages captive heat-treatment facilities to insulate its output from subcontractor bottlenecks in Japan. NSK Ltd anchors its European position through Schneeberger-aligned distributor networks in Switzerland and Germany. Hiwin Corporation dominates Taiwan's domestic automation supply chain while extending shaft fabrication into linear guide assemblies.
A linear shaft is a cylindrical precision component, typically ground to tolerances within ISO h6 or g6 fits, that provides axial guidance for bearings, bushings, and linear motion systems in machinery and automation equipment. Solid shafts in hardened chrome steel retain the largest installed base across legacy machine-tool retrofits, though hollow shafts are displacing them in high-speed robotics gantries where reduced rotating mass improves acceleration response. Stainless steel variants command premium positioning in semiconductor cleanrooms and food-processing lines where FDA and EFSA contact rules apply, while aluminum shafts are gaining share in aerospace actuation systems governed by AS9100 traceability requirements.
Japan's METI enforces JIS B 1191 dimensional standards for linear motion components, while the EU Machinery Directive and CE marking mandate fatigue-life documentation for shafts deployed in collaborative robot cells. China's SAMR now requires GB-standard material certificates for imported precision shafts used in domestic automotive assembly lines. Buyers must monitor how carbon-border adjustment mechanisms and evolving ISO 14001 supply-chain audits reshape sourcing economics between Asian and European fabrication centers.
Market Dynamics
Precision grinding labor shortages across Germany and Japan are forcing shaft fabricators to automate finishing operations or relocate capacity, while China's MIIT carbon-neutrality mandates accelerate demand for lightweight aluminum shafts in industrial equipment retrofits.
Growth Catalysts
- MIIT Carbon-Neutrality Mandates:China's Ministry of Industry and Information Technology emissions rules for industrial equipment are accelerating demand for aluminum shafts that reduce gantry mass and motor energy consumption in automation systems.
- Robotics Integrator Concentration:South Korean robotics integrators clustered around Seoul-Incheon manufacturing corridors are expanding linear shaft procurement for high-speed pick-and-place gantries serving electronics assembly.
- Semiconductor Cleanroom Expansion:FDA and EFSA contact-material rules are pulling stainless steel shaft variants into food-processing and pharmaceutical packaging lines requiring washdown compatibility.
Market Restraints
- Chrome Steel Input Volatility:Hardened chrome steel rod pricing fluctuates with ferrochrome supply disruptions from South African smelter concentration, compressing margin predictability for ground shaft producers.
- Heat-Treatment Bottleneck:Japan's captive heat-treatment capacity constraints limit subcontractor availability for precision shaft hardening, forcing OEMs to absorb extended lead times or invest in in-house furnaces.
- Hollow Shaft Substitution Ceiling:Solid chrome steel shafts retain specification lock-in across legacy machine-tool retrofits where spindle inertia requirements block hollow shaft adoption despite weight advantages.
Strategic Opportunities
- Aerospace Actuation Systems:AS9100-traceable aluminum shafts are penetrating aircraft flight-control actuation where mass reduction directly improves fuel efficiency and payload capacity.
- EU Green Deal Industrial Retrofit:The European Union's Green Deal machinery-upgrade incentives are creating pull for energy-efficient linear motion systems in automotive stamping and assembly lines.
- Linear Guide Assembly Integration:Shaft fabricators with captive linear guide production capabilities can capture value upstream from distributors by supplying pre-integrated motion subassemblies to automation OEMs.
Industry Challenges
- Precision Grinding Skill Collapse:Master grinder apprenticeship pipelines in Germany and Japan have failed to replace retiring technicians, forcing reliance on less precise CNC grinding or imported finished shafts.
- Multi-Standard Certification Burden:Simultaneous compliance with JIS B 1191, EU Machinery Directive fatigue-life documentation, and China's GB-standard material certificates fragments quality-system resources for multinational suppliers.
- Carbon-Border Adjustment Exposure:Evolving EU carbon-border adjustment mechanisms threaten to penalize Asian-sourced shafts unless suppliers can document ISO 14001-aligned supply-chain emissions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Linear Shaft Market |
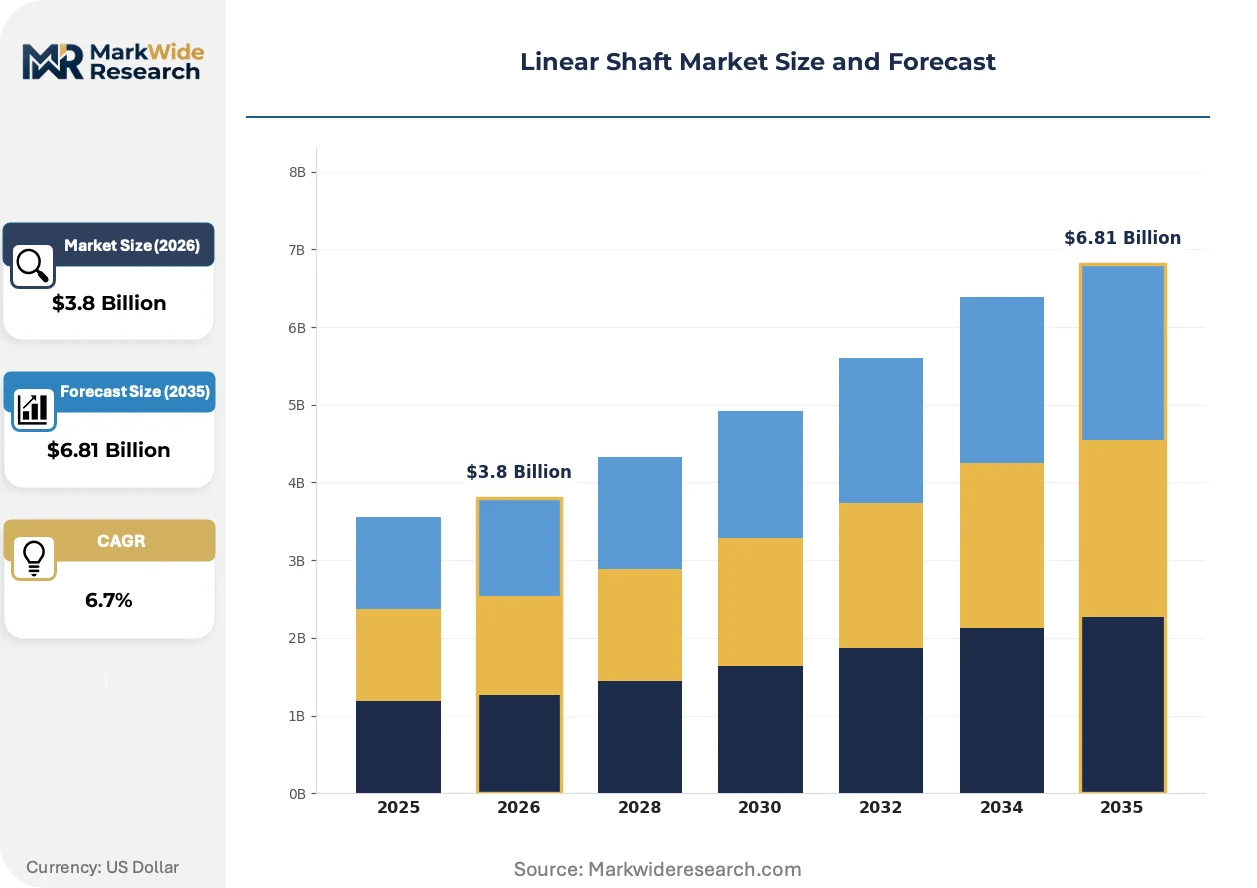
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hollow Shaft, Solid Shaft, Metric Shaft, Custom Shaft Material: Steel, Aluminum, Stainless Steel, Plastic End User: Aerospace, Robotics, Automotive, Manufacturing Application: Linear Motion, Actuation, Positioning, Guiding |
| Companies Covered | THK Co. Ltd, NSK Ltd, Hiwin Corporation, Schneeberger Group, Bosch Rexroth AG, Thomson Industries Inc., Nippon Bearing Co. Ltd, HepcoMotion Inc., UMBRAGROUP, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Linear Shaft Market Evolving Landscape
Hollow shaft geometries, regulatory material traceability mandates, and buyer consolidation around integrated motion suppliers are restructuring how linear shafts are specified, sourced, and priced across automation supply chains.
Ceramic-coated aluminum shafts are displacing chrome steel in high-speed robotics gantries where reduced rotating mass improves acceleration response and servo motor sizing. Automotive battery assembly integrators in South Korea and Germany are specifying these variants for pick-and-place modules operating above 3 m/s. The shift is compressing demand for traditional solid steel shafts in applications where dynamic performance outweighs absolute rigidity.
The EU Machinery Directive now mandates fatigue-life documentation for shafts deployed in collaborative robot cells, requiring manufacturers to maintain test records traceable to EN ISO 12100 risk assessments. This documentation burden favors suppliers with captive testing laboratories over smaller fabricators relying on third-party validation. German automotive OEMs are responding by consolidating procurement around Schneeberger-aligned distributors capable of bundling certification packages with volume supply agreements.
Buyer concentration around integrated motion system suppliers is fragmenting traditional shaft distributor networks as robotics OEMs demand pre-assembled linear guide-shaft-ball screw modules rather than discrete components. THK and NSK are capturing this value by extending shaft fabrication into complete actuator assemblies. The pattern is most visible in Japan and Taiwan, where domestic automation supply chains favor single-source subsystem procurement over component-level sourcing.
Linear Shaft Market Segmentation
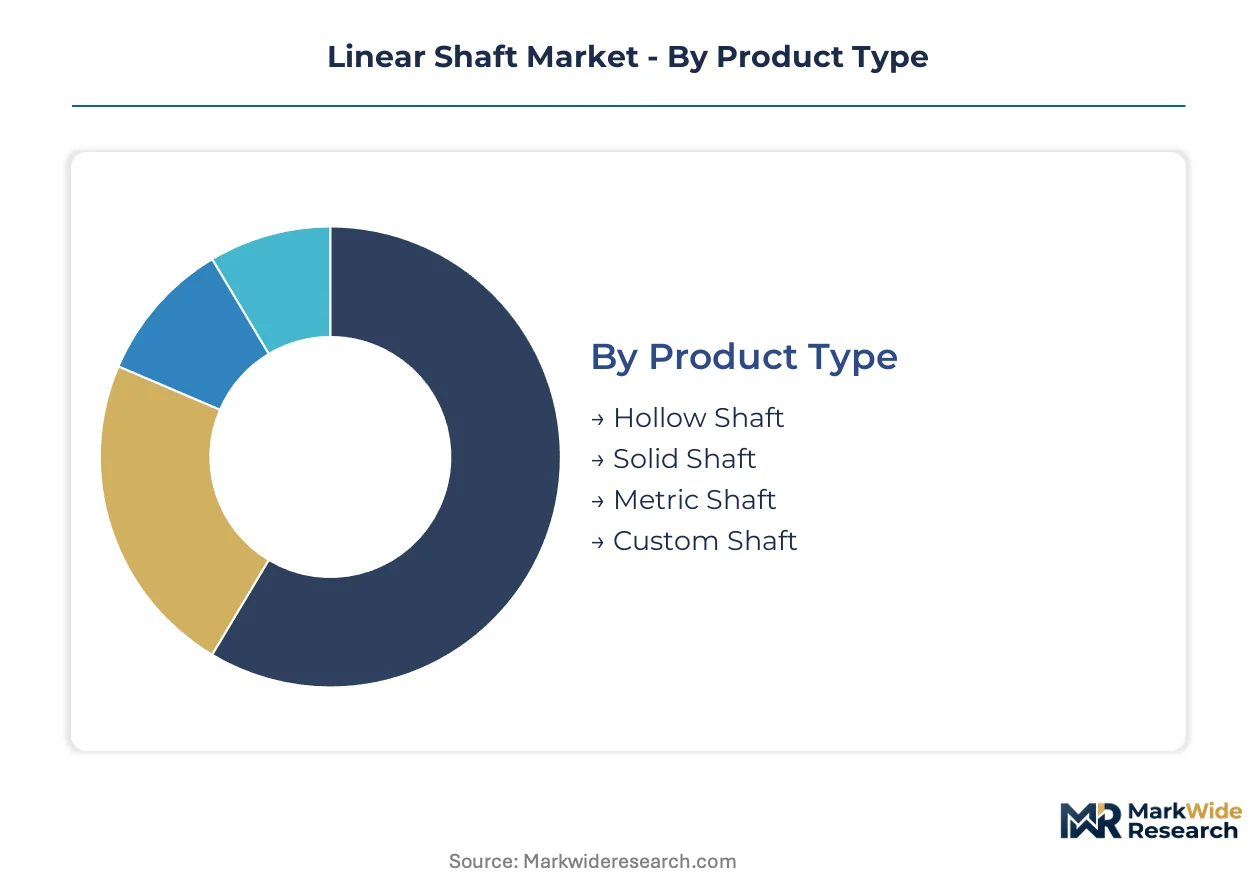
Linear shaft procurement splits across four dimensions that determine specification, certification burden, and margin structure. Product geometry and material selection trigger distinct regulatory pathways, while end-use verticals impose divergent performance and traceability requirements.
Product Type:
Regulatory differentiation hinges on hollow versus solid construction, with fatigue-life documentation mandates from the EU Machinery Directive applying differentially based on mass and rotational dynamics.
- Hollow Shaft:Tubular geometry reduces rotating mass by 40-60% versus solid equivalents, enabling acceleration rates above 3 m/s in Seoul-Incheon electronics assembly gantries. South Korean robotics integrators specify these variants for high-speed pick-and-place modules where servo motor downsizing cuts energy consumption.
- Solid Shaft:Chrome steel rods ground to ISO h6 tolerances retain specification lock-in across German and Japanese machine-tool retrofits where spindle inertia requirements block hollow adoption. Legacy equipment refurbishment in Bavaria and Baden-Württemberg consumes the bulk of current throughput.
- Metric Shaft:DIN-standard dimensions dominate European automation supply chains, with JIS B 1191 alignment required for Japanese OEM qualification.
- Custom Shaft:Non-standard lengths and surface treatments serve semiconductor cleanroom OEMs requiring AS9100-traceable aluminum configurations.
Solid shafts handle the majority of throughput; hollow shafts are climbing the fastest on share.
Material:
Cost tier stratification separates commodity steel from aerospace-grade aluminum, with carbon-border exposure reshaping sourcing economics between Asian and European fabrication centers.
- Steel:Hardened chrome steel retains the largest installed base, though ferrochrome supply disruptions from South African smelter concentration compress margin predictability for ground shaft producers serving automotive stamping lines.
- Aluminum:Ceramic-coated variants displace steel in high-speed robotics where reduced mass improves acceleration response. China's MIIT carbon-neutrality mandates accelerate demand for lightweight shafts that cut gantry motor energy consumption in automation retrofits.
- Stainless Steel:FDA and EFSA contact-material compliance positions these shafts in pharmaceutical packaging and food-processing washdown environments.
- Plastic:Polymer shafts serve low-load laboratory automation where magnetic neutrality and chemical resistance outweigh rigidity requirements.
Steel maintains volume dominance; aluminum is expanding most quickly on share.
End User:
Application maturity varies sharply, with aerospace traceability requirements and automotive volume scale imposing divergent supplier qualification burdens.
- Aerospace:AS9100-traceable aluminum shafts penetrate flight-control actuation where mass reduction improves fuel efficiency. FAA and EASA certification documentation favors suppliers with captive testing laboratories.
- Robotics:Collaborative robot cells require fatigue-life documentation traceable to EN ISO 12100 risk assessments, consolidating procurement around distributors capable of bundling certification packages.
- Automotive:Battery assembly integrators in Germany and South Korea specify ceramic-coated shafts for modules operating above 3 m/s.
- Manufacturing:General automation consumes standardized chrome steel shafts through distributor networks aligned with Schneeberger and THK.
Manufacturing handles the majority of throughput; aerospace is gaining share fastest.
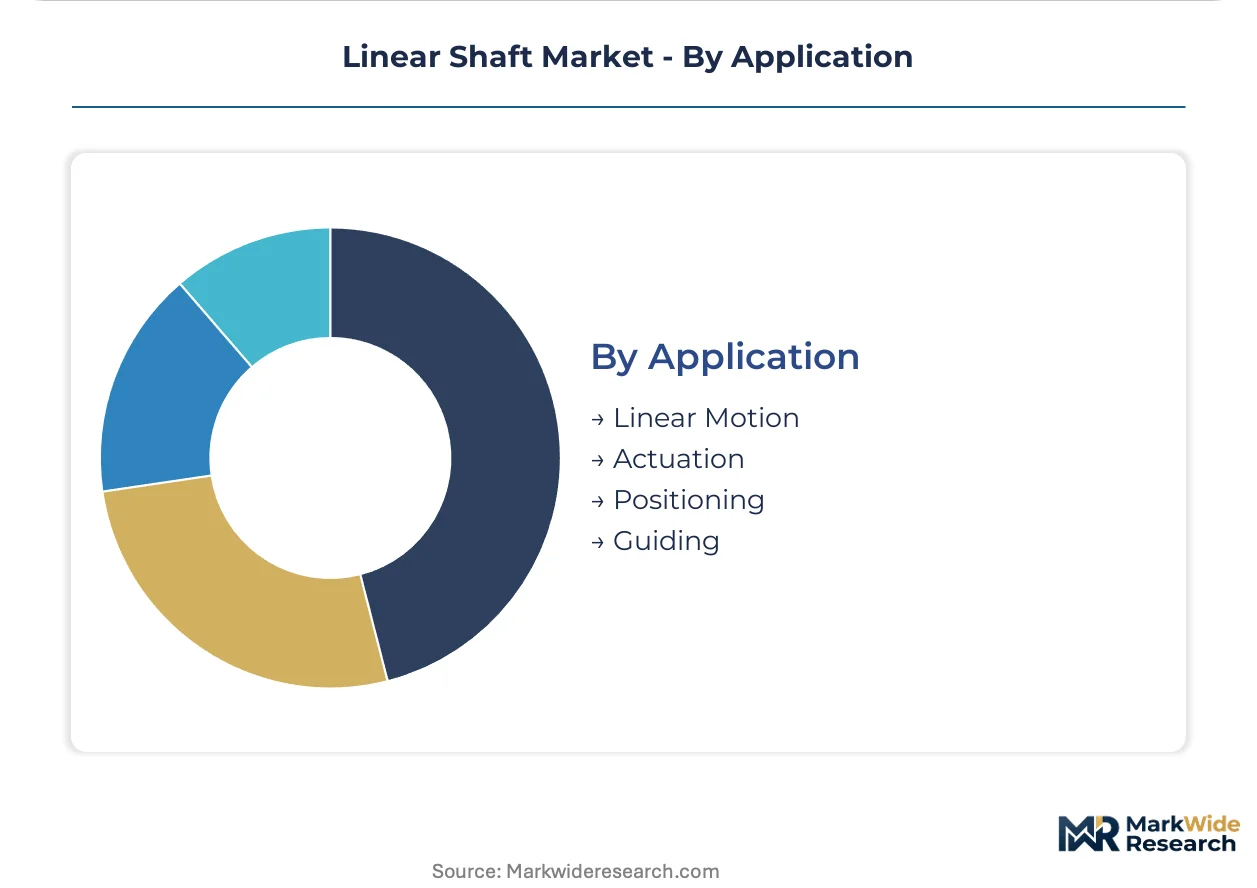
Application:
Customer type fragmentation separates integrated motion system buyers from component-level procurement, with pre-assembly demands reshaping traditional distributor relationships.
- Linear Motion:Bearing guidance systems for gantry robots and Cartesian coordinate machines, with hollow shaft substitution accelerating in Seoul-Incheon electronics corridors.
- Actuation:Flight-control and industrial valve applications where aluminum shafts reduce actuator mass in aerospace and process industries.
- Positioning:CNC machine-tool axes requiring ISO h6 or g6 ground tolerances, with precision grinder labor shortages in Germany forcing automation or relocation.
- Guiding:Rail and bushing alignment in packaging and material handling, typically specified through linear guide assembly integrators.
Linear motion handles the majority of throughput; actuation is the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIIT carbon-neutrality mandates anchor China's industrial equipment retrofit agenda, reshaping procurement patterns for lightweight motion components across East Asian manufacturing corridors.
Germany
Precision grinder labor shortages in Bavaria and Baden-Württemberg constrain OEM output for machine-tool retrofits. The EU Machinery Directive mandates fatigue-life documentation for collaborative robot shafts, consolidating procurement around Schneeberger-aligned distributors. Stuttgart automotive stamping lines absorb standardized chrome steel throughput despite hollow shaft substitution pressure elsewhere.
Japan
METI enforces JIS B 1191 dimensional standards that qualify suppliers for domestic automation OEMs. Captive heat-treatment bottlenecks limit subcontractor availability, forcing fabricators to automate finishing or absorb extended lead times. Nagoya-area precision manufacturers anchor the country's linear motion supply chain for robotics integrators.
China
MIIT emissions rules accelerate aluminum shaft demand for gantry mass reduction in automation retrofits. SAMR requires GB-standard material certificates for imported precision shafts used in domestic automotive assembly. Yangtze River Delta electronics corridors concentrate procurement for high-speed pick-and-place modules.
South Korea
Robotics integrators clustered around Seoul-Incheon manufacturing corridors represent the fastest-expanding buyer segment for linear shaft procurement. MFDS-aligned contact-material rules pull stainless variants into pharmaceutical packaging applications. Battery assembly integrators specify ceramic-coated shafts for modules operating above 3 m/s.
United States
FAA certification documentation for AS9100-traceable aluminum shafts penetrates aerospace actuation systems where mass reduction improves fuel efficiency. FDA contact-material rules position stainless steel variants in food-processing washdown environments. Pacific Northwest semiconductor cleanroom expansion drives custom shaft specifications for non-standard lengths and surface treatments.
Linear Shaft Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with precision grinding mastery separating premium-tier suppliers from volume fabricators. The market structure consolidates around integrated motion system suppliers while fragmenting across component-level specialists. Three archetypes dominate: captive heat-treatment operators insulating output from subcontractor bottlenecks, distributor-aligned certification bundlers capturing EU Machinery Directive compliance value, and linear guide assembly integrators capturing upstream motion subassembly demand. Competitive moves center on backward integration into heat-treatment capacity and geographic expansion through Schneeberger-aligned distribution networks.
Among Japanese fabricators, THK Co. Ltd and NSK Ltd exemplify the integrated motion system archetype, with THK leveraging captive facilities and NSK anchoring European positioning through Swiss and German distributor relationships. Hiwin Corporation represents the Taiwan-based automation supply chain specialist extending shaft fabrication into complete linear guide assemblies. These three occupy positions reflecting divergent strategic responses to precision grinding labor scarcity and regulatory documentation burdens across JIS, EU, and GB standard regimes.
| Leading Market Players |
|---|
| THK Co. Ltd |
| NSK Ltd |
| Hiwin Corporation |
| Schneeberger Group |
| Bosch Rexroth AG |
| Thomson Industries Inc. |
| Nippon Bearing Co. Ltd |
| HepcoMotion Inc. |
| UMBRAGROUP |
| Others |
Value Network & Pricing Analysis
JIS B 1191 compliance gates both supplier qualification and price differentiation in the linear shaft market, with Japanese OEMs paying premiums for certified fabricators while uncertified Asian suppliers compete on raw material cost alone. This regulatory threshold fragments pricing power across certification tiers.
Pricing Analysis
Japanese and German buyers face 15-25% premiums over Southeast Asian procurement for equivalent chrome steel specifications due to captive heat-treatment and grinder labor scarcity. Three-tier pricing structure across premium, standard, and economy levels separates AS9100-traceable aerospace shafts from DIN-standard automation grades and uncertified commodity rods. Cost compression in economy-tier steel shafts is intensifying because ferrochrome supply disruptions from South African smelter concentration force margin absorption. Automotive battery assembly integrators show least price sensitivity due to certification bundling requirements, while general manufacturing distributors face severe margin pressure from spot-market competition.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for precision-ground shafts requiring temperature-controlled transport to prevent dimensional drift. Supply concentrates in Japan, Germany, and Taiwan, with China expanding aluminum shaft capacity under MIIT carbon-neutrality mandates. Raw material dependencies center on South African ferrochrome for hardened steel grades, Swiss grinding wheel abrasives, and Japanese heat-treatment furnace equipment. Single-source vulnerability around Nagoya-area captive heat-treatment facilities threatens extended lead times during capacity crunches. Distribution runs through Schneeberger-aligned technical distributors in Europe and direct OEM relationships in East Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision grinding labor collapse across Germany and Japan fragments manufacturing capacity into defendable niches, creating entry points for automated finishing specialists and regional certification bundlers.
For Market Incumbents: Consolidate procurement relationships around Seoul-Incheon robotics clusters where hollow shaft demand accelerates fastest. Backward integration into captive heat-treatment capacity insulates output from Nagoya subcontractor bottlenecks. Invest in EN ISO 12100 fatigue-life testing laboratories to capture EU Machinery Directive compliance value from smaller fabricators lacking documentation capabilities. For New Entrants and Emerging Players: Lead with ceramic-coated aluminum shaft production targeting South Korean battery assembly integrators operating pick-and-place modules above 3 m/s. Aerospace actuation systems present the most penetrable white space, with AS9100 traceability requirements filtering out commodity suppliers. Partner with Yangtze River Delta electronics corridors for rapid qualification against MIIT emissions rules. For Investors and Strategic Acquirers: EU carbon-border adjustment mechanism implementation reshapes the acquisition landscape, privileging suppliers with ISO 14001-aligned supply-chain documentation over Asian competitors facing tariff exposure. Long-term viability centers on integrated motion system suppliers extending shaft fabrication into linear guide assemblies. Watch for SAMR enforcement patterns on GB-standard material certificates as the inflection signal for China-import substitution opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Heat-Treatment Capacity Addition | Insulates Japanese fabricators from Nagoya subcontractor bottlenecks during precision shaft hardening surges. |
| AS9100 Certification Investment | Opens aerospace actuation procurement where FAA documentation requirements filter commodity competitors. |
| Schneeberger Distribution Alignment | Captures EU Machinery Directive compliance bundling value across Stuttgart automotive stamping lines. |
| Ceramic Coating Process Development | Enables aluminum shaft displacement of chrome steel in Seoul-Incheon high-speed robotics gantries. |
| Linear Guide Assembly Integration | Captures upstream motion subassembly demand from Taiwan and Japan automation OEMs consolidating suppliers. |
Research Methodology
Cross-validation between primary interviews with precision grinding shop floor managers and secondary validation through METI production surveys anchors the qualitative findings. Stakeholder engagement included maintenance directors at German automotive stamping facilities, OEM procurement teams at South Korean robotics integrators, aftermarket service heads at Japanese machine-tool retrofitters, and technical R&D directors at Taiwanese linear guide manufacturers. Secondary sources comprised JIS B 1191 certification registries, EU Machinery Directive fatigue-life documentation filings, SAMR GB-standard import records, and SEC 10-K disclosures from listed motion component suppliers. Bottom-up shaft fabrication capacity estimates triangulated against top-down automation equipment production forecasts.
Sensitivity analysis tested forecast robustness across alternative scenarios for ferrochrome supply disruption duration and MIIT carbon-neutrality enforcement intensity. The analytical framework modeled volume and value outputs across product geometry, material grade, end-use vertical, and application type dimensions throughout the projection horizon. CAGRs derived from regression against industrial automation capital expenditure cycles and semiconductor cleanroom construction pipelines. Industry-specific inputs included precision grinder apprenticeship graduation rates from German and Japanese labor ministries and Yangtze River Delta electronics corridor investment permits.
Forecasts assume regulatory continuity in JIS B 1191, EU Machinery Directive, and SAMR GB-standard regimes; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Global Learning Analytics Market
Others
Ambient Assisted Living and Smart Home Market
Others
Commercial Aircraft Angle of Attack Sensors Market
Others
Lightweight Compact Wheel Loader Market
Others
Global Laser Defense Eyewear Market
Others
Advanced Fiber-Based Gasket Market
Others
Wingboards Market
Others
Coconut Activated Carbon Market
Others
Cryogenic Storage Tanks Market
Others
Italy Feed Additives Market
Others
Digital Audio Decoders Market
Others
Latin America Domestic CEP Market
Others
Global Healthcare/Medical Simulation Market
Others
5G Enabled Healthcare Services Market
Others
Wearable Solar Devices Market
Others
Roasted Wheat Market