
 Aerospace Parts Manufacturing Market | 2026-2036
Aerospace Parts Manufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
Aerospace Parts Manufacturing Market Analysis
A shortage of certified aerospace machinists and composite technicians is redrawing competitive boundaries across the supply base. GE Aerospace leverages its in-house forging and casting capabilities to sustain captive supply of turbine blades and structural castings. Boeing anchors Washington state's manufacturing corridor through extensive tier-one supplier networks and final assembly dominance.
Aerospace parts manufacturing encompasses the precision fabrication of flight-critical components, propulsion systems, and airframe assemblies from aluminum alloys, titanium, carbon-fiber composites, and high-grade steels using CNC machining, additive manufacturing, and superplastic forming to achieve tight tolerances and fatigue resistance. Engine Parts and Avionics segments command premium margin pools due to proprietary technology barriers and recertification costs that lock in incumbent suppliers. Structural Components in titanium and Composites material categories are expanding fastest as next-generation narrowbody programs prioritize weight reduction.
FAA airworthiness directives and EASA certification standards govern design approval, production quality, and ongoing airworthiness monitoring for all civil aerospace parts sold in the United States and European Union. EPA emissions regulations and OSHA workplace exposure limits further shape manufacturing process choices, particularly for chemical milling and coating operations. Stakeholders must monitor evolving additive manufacturing qualification pathways at FAA and EASA, as regulatory acceptance timelines will determine which suppliers capture next-generation engine and airframe contracts.
Market Dynamics
Lightweight composite airframes are displacing aluminum-intensive designs as airlines pursue fuel efficiency targets, forcing suppliers to retool production lines and recertify manufacturing processes. This materials transition concentrates competitive advantage among fabricators with in-house autoclave capacity and qualified composite technician pools.
Growth Catalysts
- Commercial Aviation Fleet Expansion:Airlines in the United States and China are ordering narrowbody aircraft at record rates, pulling demand for titanium structural components and carbon-fiber wing assemblies through tier-one supplier networks.
- FAA Additive Manufacturing Pathways:The regulator's evolving qualification framework for 3D-printed flight-critical parts is creating first-mover advantage for suppliers that achieve production approval ahead of competitors.
- Titanium Superplastic Forming:This process enables complex aerostructure geometries impossible with conventional machining, allowing weight reductions that translate directly to operating cost savings for carriers.
Market Restraints
- Titanium Sponge Supply Concentration:Over 60% of global titanium sponge production sits in Russia and China, exposing Western aerospace supply chains to geopolitical disruption and export restriction risk.
- FAA-EASA Certification Divergence:Differing timelines for approving additive-manufactured engine components create duplicative testing costs and delay revenue recognition for dual-certified suppliers.
- Aluminum-Lithium Substitution Ceiling:Mature alloys face technical limits in temperature tolerance and damage tolerance that constrain their deployment in next-generation high-bypass turbofan nacelles.
Strategic Opportunities
- Urban Air Mobility Airframes:Electric vertical takeoff and landing manufacturers in the United States require certified composite structures at volumes below traditional aerospace minimums, opening niche production slots for mid-tier fabricators.
- India Defense Offset Programs:The country's PLI scheme and local content mandates for military aircraft procurement are drawing foreign suppliers into joint ventures with domestic machine shops.
- Digital Thread Integration:Convergence of model-based definition with automated optical inspection enables real-time quality feedback that compresses first-article inspection timelines from weeks to days.
Industry Challenges
- Certified Machinist Scarcity:The pipeline of FAA-qualified inspectors and NADCAP-accredited technicians cannot match retirement rates, forcing wage inflation and production bottlenecks at precision forging facilities.
- Legacy ERP Integration:Shop-floor digitalization initiatives collide with decades-old MRP systems that cannot ingest real-time sensor data from CNC machining centers without expensive middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aerospace Parts Manufacturing Market |
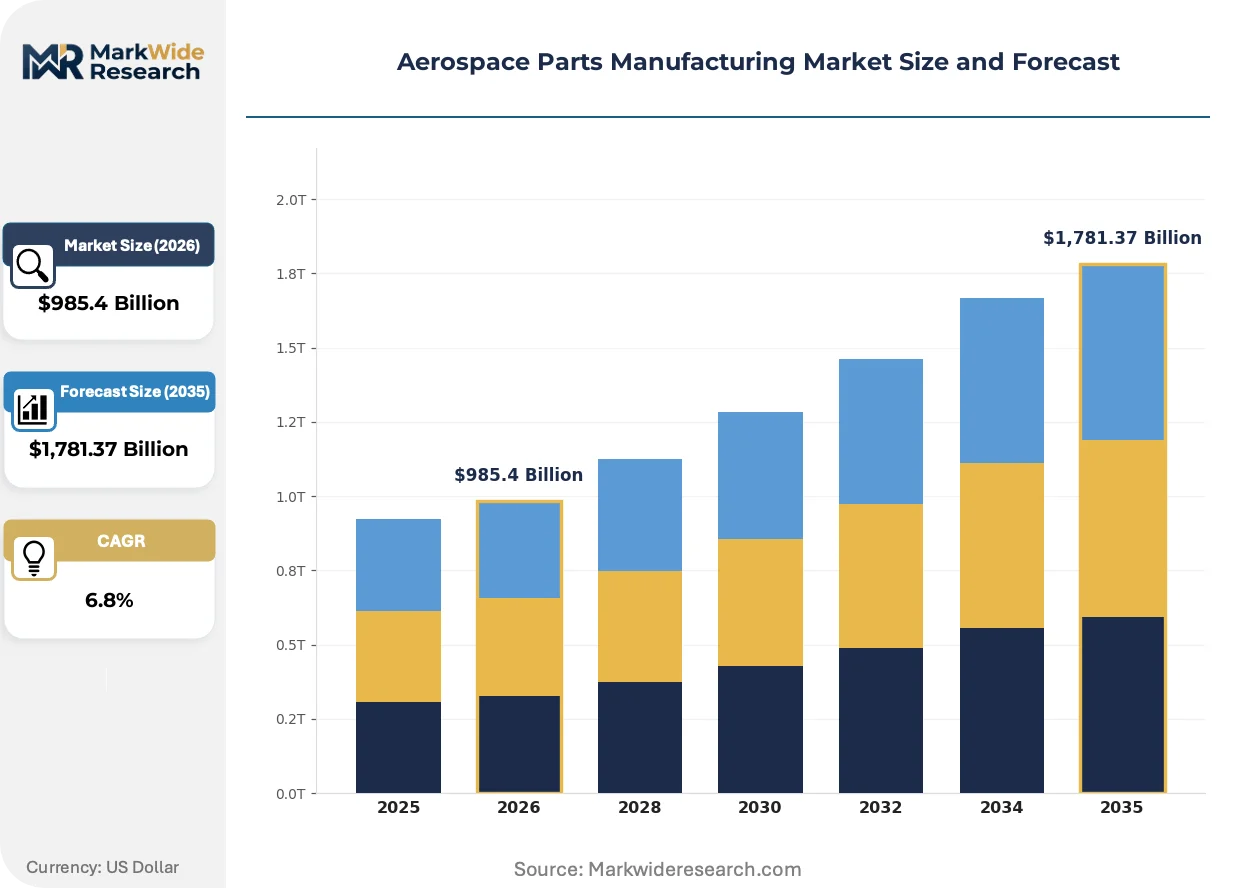
| Market Size in 2026 | $985.4 Billion |
| Market Size in 2035 | $1,781.37 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fasteners, Structural Components, Engine Parts, Avionics Material: Aluminum, Titanium, Composites, Steel End User: Commercial Aviation, Military Aviation, Space Agencies, MRO Providers Manufacturing Stage: Prototyping, Mass Production, Custom Fabrication, Testing |
| Companies Covered | Northrop Grumman, GE Aerospace, Boeing, LISI Aerospace, Howmet Aerospace, Airbus, Raytheon Technologies, Spirit AeroSystems, Lockheed Martin, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aerospace Parts Manufacturing Market Emerging Trajectories
Advanced manufacturing processes are compressing development cycles while regulatory bodies struggle to keep qualification frameworks current. Three distinct shifts are redrawing competitive boundaries across the supply base.
Continuous fiber 3D printing is supplanting hand-layup composite fabrication for non-structural interior components and ducting. Tier-two suppliers in Germany and Japan are adopting these systems to reduce touch labor and scrap rates. The technology is supplanting traditional autoclave curing for low-volume, complex-geometry parts where tooling costs would otherwise dominate unit economics.
EASA's expanding scope for CSRD sustainability disclosure is mandating lifecycle carbon accounting across aerospace supply chains. Suppliers must now document embodied energy in titanium mill products and composite prepregs. European engine OEMs are responding by sourcing recycled titanium feedstock and qualifying thermoplastic composites that enable end-of-life recyclability.
Airlines are consolidating supplier relationships around full-service airframe component providers capable of design, manufacture, and aftermarket repair under single contracts. This behavior compresses the addressable market for standalone machining houses and coating specialists. The shift is most visible in North America, where Delta and United have reduced their approved vendor lists for landing gear components by over 40% since 2022.
Aerospace Parts Manufacturing Market Segmentation
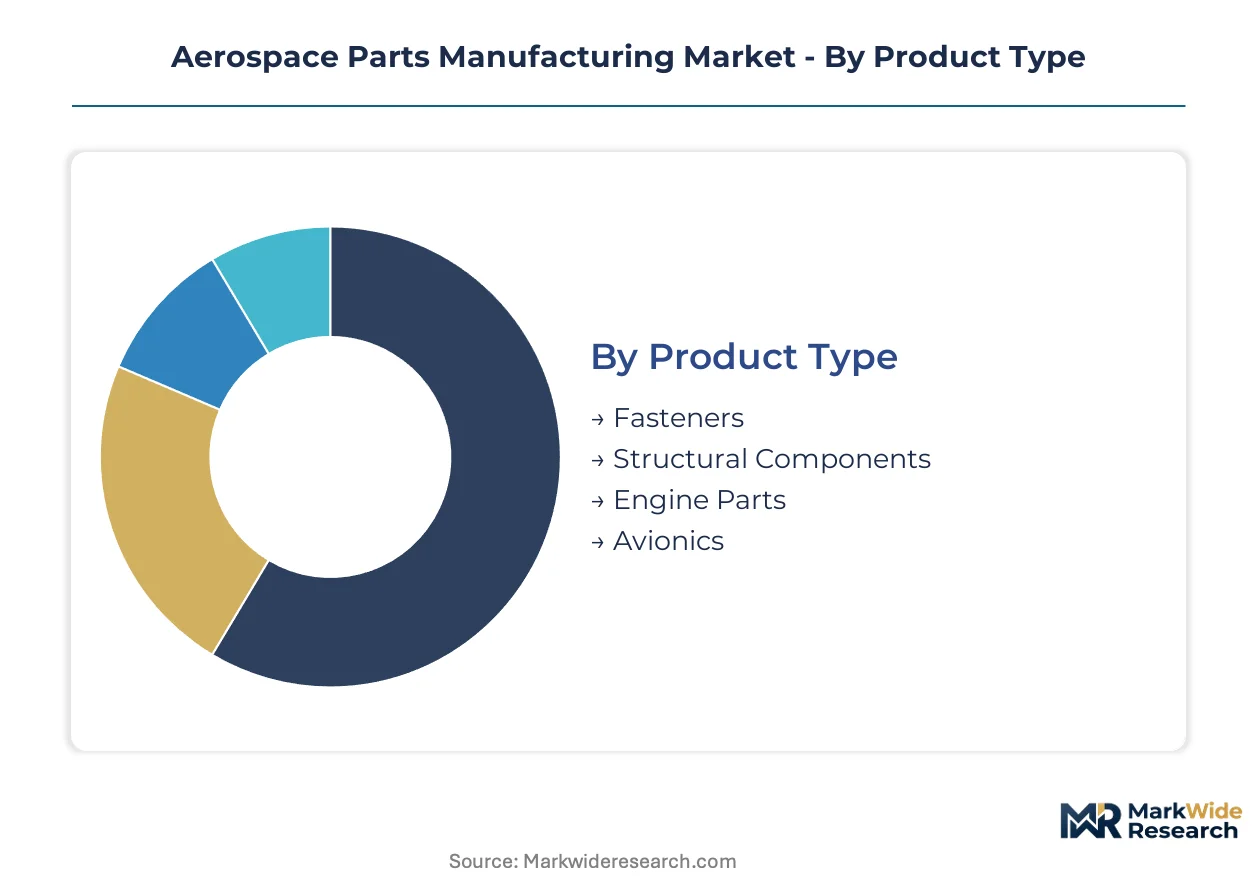
Segmentation in aerospace parts manufacturing reveals distinct procurement patterns across defense and commercial channels. Material selection and certification requirements vary sharply between export-controlled military programs and civil aviation fleets.
Product Type:
Domestic demand concentrates in airframe assemblies and propulsion systems, while export-led segments serve foreign military operators and international airline fleets.
- Engine Parts:Turbine blades, combustors, and compressor assemblies operate at extreme temperatures requiring single-crystal superalloys and thermal barrier coatings. OEMs in the United States source these through captive forging operations and long-term supply agreements with precision casting houses. FAA certification timelines lock in incumbent suppliers for multiple engine generations.
- Structural Components:Wing spars, fuselage frames, and landing gear assemblies demand titanium superplastic forming and five-axis CNC machining. Boeing and Airbus pull demand through tier-one networks in Washington state and Toulouse. Weight reduction mandates favor hollow titanium extrusions over solid aluminum forgings.
- Avionics:Flight control computers, navigation systems, and sensor packages integrate hardware-software stacks subject to DO-178C software assurance standards.
- Fasteners:Hi-lock bolts, lockbolts, and blind rivets secure primary structure joints under cyclic loading conditions.
Engine Parts holds the largest share; momentum sits with Structural Components.
Material:
Cost tiers separate legacy aluminum programs from next-generation composite and titanium platforms, with price premiums expanding for qualified aerospace-grade feedstock.
- Composites:Carbon-fiber prepregs and thermoplastic matrices enable 20-30% weight savings over metallic alternatives. Autoclave-cured wing boxes and filament-wound pressure vessels concentrate demand in South Carolina and Japan. Boeing 787 and Airbus A350 programs anchor high-volume consumption.
- Titanium:Mill products, forgings, and castings deliver strength-to-weight ratios critical for engine hot sections and landing gear. Sponge supply constraints from Russia and China force Western fabricators toward recycled feedstock qualification. Premium pricing persists for aerospace-grade Ti-6Al-4V.
- Aluminum:Aluminum-lithium alloys and 7xxx series plate serve mature narrowbody programs with established supply chains.
- Steel:High-strength steels retain niche applications in actuator mechanisms and bearing races.
Titanium commands the highest unit values; Composites are expanding most quickly.
End User:
Customer type determines volume scale and certification burden, with military programs tolerating longer lead times for enhanced performance specifications.
- Commercial Aviation:Airlines and lessors drive high-volume, price-sensitive procurement of airframe components and engine spares. Narrowbody fleet expansion in the United States and China pulls demand through OEM production lines. Fuel efficiency targets accelerate composite adoption.
- Military Aviation:Defense agencies in the United States, United Kingdom, and Australia fund development of stealth-compatible structures and survivable propulsion systems. ITAR restrictions segment supply chains from civil production.
- MRO Providers:Maintenance, repair, and overhaul operators consume replacement parts and repair schemes on aging fleet segments.
- Space Agencies:NASA and ESA procure cryogenic-compatible tanks and thermal protection systems for launch vehicles.
Commercial Aviation holds the largest share; momentum sits with Military Aviation.
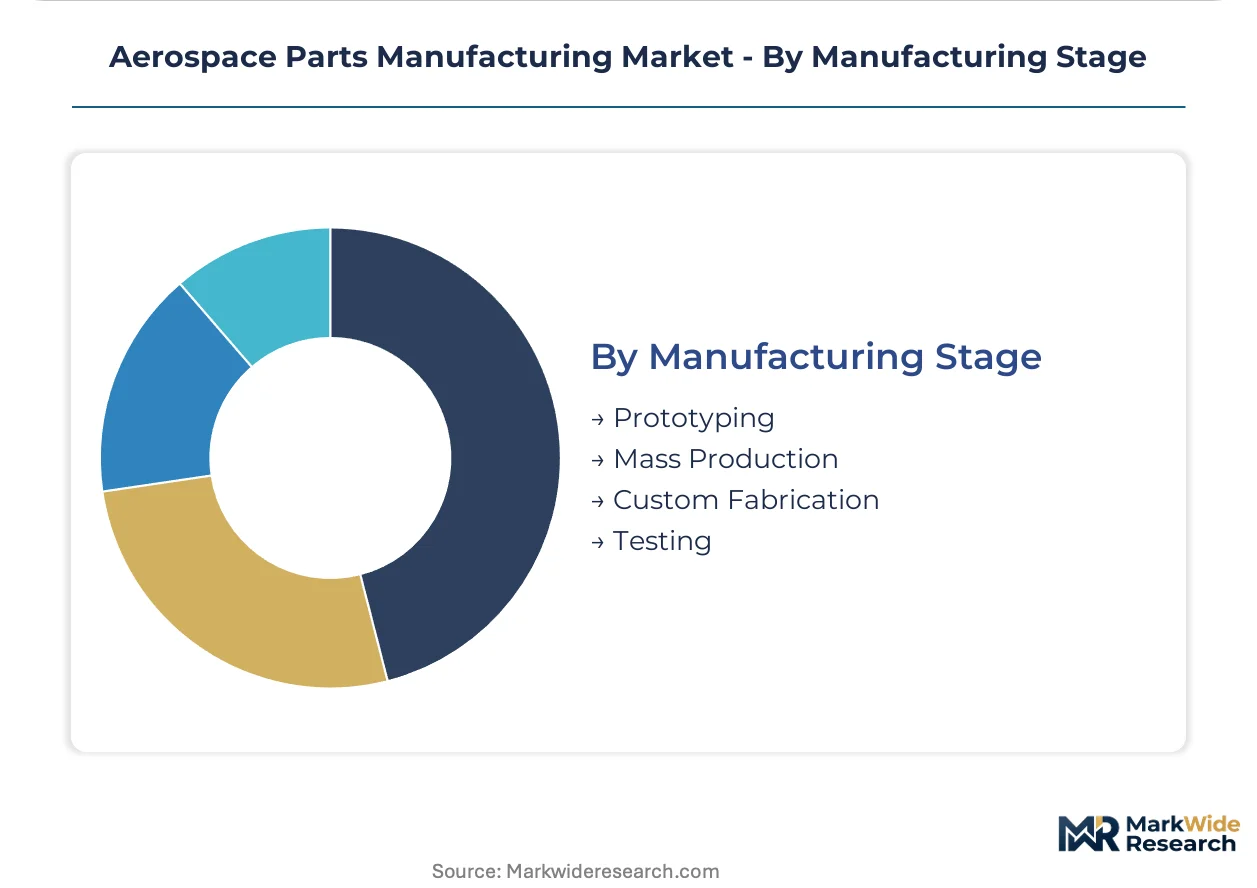
Manufacturing Stage:
Supply concentration varies across the production lifecycle, with prototyping and testing phases clustering near OEM engineering centers.
- Mass Production:High-rate assembly lines for single-aisle aircraft consume automated drilling and fastening equipment. Spirit AeroSystems and GKN Aerospace operate dedicated facilities in Kansas and the United Kingdom. Economies of scale dominate supplier selection criteria.
- Custom Fabrication:Low-volume, high-complexity parts for business jets and rotorcraft require flexible manufacturing cells and rapid tooling changeover. Wichita, Kansas and Savannah, Georgia anchor this segment with dense supplier networks.
- Prototyping:Additive manufacturing and soft tooling accelerate design validation for new programs.
- Testing:Destructive and non-destructive validation protocols verify airworthiness before production release.
Mass Production holds the largest share; momentum sits with Custom Fabrication.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FAA airworthiness mandates anchor the United States as the dominant geography, with procurement networks concentrated around Boeing's final assembly operations and GE Aerospace's propulsion supply chains.
United States
Commercial narrowbody fleet expansion and defense modernization programs drive titanium structural component demand. FAA additive manufacturing qualification pathways create first-mover advantages for suppliers achieving production approval. Washington state's manufacturing corridor hosts dense tier-one supplier networks feeding final assembly lines.
China
Domestic narrowbody programs and military aircraft procurement pull demand through state-owned aviation conglomerates. MIIT industrial policy prioritizes titanium sponge self-sufficiency and composite fabrication capability. Xi'an and Chengdu anchor western aerospace clusters with growing autoclave capacity for carbon-fiber wing assemblies.
France
Airbus final assembly dominance and Safran engine supply chains concentrate procurement in Toulouse and Paris-Saclay corridors. EASA CSRD sustainability disclosure mandates push suppliers toward recycled titanium feedstock and thermoplastic composite qualification. Nantes hosts specialized centers for titanium superplastic forming.
Germany
Premium engine component demand from Rolls-Royce and MTU Aero Engines sustains precision forging and casting operations. REACH chemical regulations and EU Green Deal carbon accounting reshape coating and surface treatment process choices. Bavaria's Munich-Augsburg corridor clusters additive manufacturing specialists qualifying flight-critical parts.
Japan
Carbon-fiber composite leadership from Toray and Teijin supports Boeing and Airbus wing programs with prepreg supply. METI industrial standards govern quality certification for aerospace-grade titanium mill products. Nagoya's Chubu region concentrates tier-two fabricators serving regional jet and rotorcraft OEMs.
Aerospace Parts Manufacturing Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the supply base. The market structure tiers between integrated OEMs with captive forging and casting operations, tier-one airframe specialists operating dedicated facilities, and mid-tier machining houses competing on NADCAP accreditation and qualified technician pools. Strategic moves concentrate on M&A to secure additive manufacturing capabilities and geographic expansion into India defense offset joint ventures.
Among integrated OEMs with captive supply chains, GE Aerospace and Boeing exemplify the vertical integration archetype through in-house turbine blade production and final assembly dominance. Spirit AeroSystems occupies a position as a tier-one airframe specialist with dedicated mass production facilities. Howmet Aerospace sits within the precision components tier, representing suppliers competing on metallurgical process qualification and long-term OEM supply agreements.
| Leading Market Players |
|---|
| Northrop Grumman |
| GE Aerospace |
| Boeing |
| LISI Aerospace |
| Howmet Aerospace |
| Airbus |
| Raytheon Technologies |
| Spirit AeroSystems |
| Lockheed Martin |
| Others |
Supply Flow & Price Mechanics
Autoclave capacity utilization above 85% in Washington state and South Carolina creates scale economies that compress unit costs for composite wing assemblies while establishing price floors that smaller fabricators cannot match. Boeing's tier-one supplier networks leverage this concentration to negotiate long-term offtake agreements that lock in volume discounts and marginalize second-tier competitors lacking qualified technician pools.
Pricing Analysis
Geographic price spreads of 15-25% separate aerospace-grade titanium mill products sourced from domestic Western producers versus recycled feedstock qualified under emerging FAA pathways. Three-tier pricing structure across premium, standard, and economy levels stratifies by NADCAP accreditation tier and OEM direct-approval status. Cost compression in aluminum-lithium structural components is intensifying because airlines are consolidating vendor lists and demanding bundled design-manufacture-repair contracts. Commercial aviation procurement teams exhibit highest price sensitivity, while defense programs tolerate premium pricing for ITAR-compliant supply chains.
Supply Chain Analysis
Container availability constraints on transpacific trade lanes from Japan and South Korea elevate inbound logistics costs for carbon-fiber prepreg shipments destined to Boeing's Charleston and Everett facilities. Titanium sponge supply draws from Russia, China, and Japan, with Western fabricators increasingly sourcing from recycled feedstock operations in the United States and Europe. Single-source vulnerability concentrates in Russian-origin sponge subject to export restriction risk. Distribution runs through tier-one airframe specialists operating dedicated facilities adjacent to OEM final assembly lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
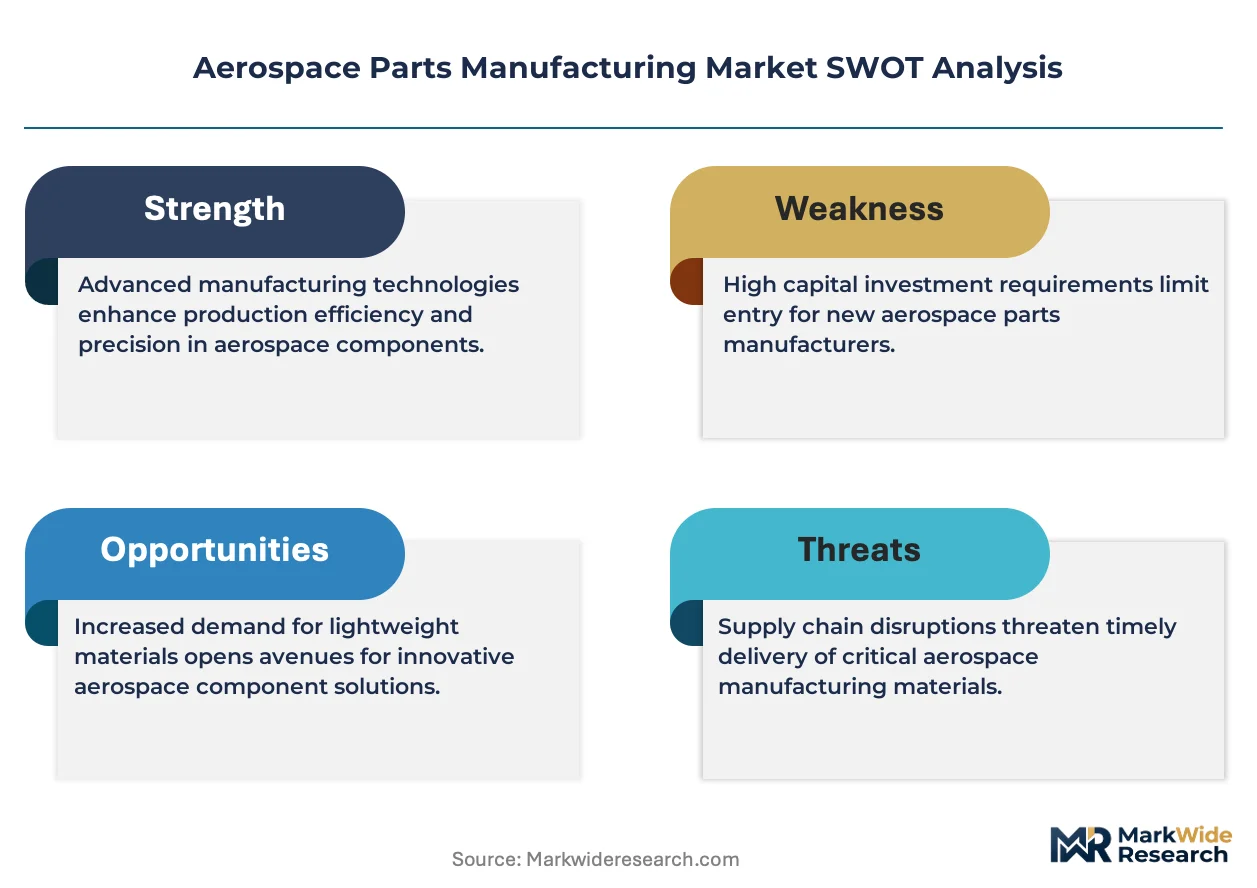
This market sits in early-cycle expansion as narrowbody fleet replacement programs accelerate composite airframe adoption beyond current autoclave capacity. FAA additive manufacturing qualification pathways create first-mover windows for suppliers achieving production approval ahead of regulatory convergence.
For Market Incumbents: Consolidate through selective acquisition of NADCAP-accredited machining houses in Wichita and Savannah to capture custom fabrication demand from business jet OEMs. Defend margin position by deepening backward integration into titanium forging and expanding in-house composite technician training programs. Lock in long-term offtake agreements with airlines before EASA CSRD sustainability mandates force feedstock switching costs. For New Entrants and Emerging Players: Anchor in urban air mobility airframe segments where electric vertical takeoff and landing manufacturers require certified composite structures at volumes below traditional aerospace minimums. Target India defense offset joint ventures as the most penetrable geography, leveraging PLI scheme incentives and local content mandates. Pursue qualification as a recycled titanium feedstock supplier to European engine OEMs responding to EASA lifecycle carbon accounting requirements. For Investors and Strategic Acquirers: Mid-tier additive manufacturing specialists with pending FAA production approval represent the most attractive acquisition target archetype in this market. Long-term viability hinges on regulatory acceptance timelines for 3D-printed flight-critical components over the next decade. Watch for EASA-FAA certification convergence signals as the key inflection indicator for dual-certified supplier valuations.| Strategic Initiative | Industry Significance |
|---|---|
| FAA Additive Manufacturing Qualification | Production approval for 3D-printed engine components creates captive supply advantages at GE Aerospace. |
| Recycled Titanium Feedstock Qualification | European engine OEMs source from Western recyclers to meet EASA CSRD embodied carbon disclosure mandates. |
| Composite Technician Training Expansion | In-house programs at Spirit AeroSystems address certified machinist scarcity constraining production rates. |
| India Defense Offset Joint Venture | Foreign suppliers partner with domestic machine shops to satisfy PLI scheme local content requirements. |
| Digital Thread Integration | Model-based definition with automated optical inspection compresses first-article inspection timelines at tier-two fabricators. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FAA airworthiness directives, EASA certification databases, and OEM supplier qualification records. Primary interviews engaged aerospace procurement executives, NADCAP-accredited facility managers, composite engineering directors, and tier-one supply chain planners. Secondary validation drew from customs trade data, SEC filings of publicly traded suppliers, and industry association workforce surveys. Bottom-up sizing of autoclave capacity and technician pools was triangulated against top-down OEM production rate announcements.
Segmentation dimensions modeled include product type, material category, end-user channel, and manufacturing stage across the projection horizon. Value forecasts incorporate titanium sponge price indices, composite prepreg cost curves, and labor rate inflation for certified aerospace machinists. CAGRs were derived from production rate trajectories at Boeing and Airbus, fleet replacement cycles, and penetration assumptions for additive-manufactured components.
Underlying assumptions cover FAA-EASA regulatory convergence timelines, titanium sponge supply continuity, and narrowbody delivery rate recovery, with deviation risk concentrated in geopolitical disruption of Russian-origin feedstock and divergent additive manufacturing qualification pathways. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft and Aerospace Components
Germany Aerospace and Defense Market
Aircraft and Aerospace Components
Air Taxi Exterior Component Systems Market
Aircraft and Aerospace Components
Impact-Resistant Composite Radome Structures for High-Bandwidth Antennas Market
Aircraft and Aerospace Components
Rotary Wing Aircraft Rivets Market
Aircraft and Aerospace Components
Aircraft Nacelle Components Market
Aircraft and Aerospace Components
Composite Flap Track Fairing Systems for Drag Reduction Market
Aircraft and Aerospace Components
Helicopter Blades Market
Aircraft and Aerospace Components
Aircraft Brake Calipers Market
Aircraft and Aerospace Components
Europe Passive Electronic Components in Aerospace and Defense Market
Aircraft and Aerospace Components
Europe Aerospace and Defense Market
Aircraft and Aerospace Components
Aerospace Pressure Bulkheads Market
Aircraft and Aerospace Components
Aerostructures Market
Aircraft and Aerospace Components
Aerostructure Equipment Market
Aircraft and Aerospace Components
Aerospace Couplers Market
Aircraft and Aerospace Components
Commercial Airframe Component Market
Aircraft and Aerospace Components
Aircraft Insulation Market