
 Autonomous Navigation Processing Unit Market | 2026-2036
Autonomous Navigation Processing Unit Market Size, Share, and Industry Trends Forecast 2026-2036
Autonomous Navigation Processing Unit Market Analysis
China is fragmenting as domestic foundries and module assemblers scale capacity for automotive-grade navigation processors. Moog Inc. leverages decades of precision motion control heritage to anchor its position in aerospace-grade processing units. Honeywell International Inc. competes across dual-use defense and commercial aviation channels with radiation-hardened architectures. Thales Group specializes in maritime and rail autonomy stacks, sustaining European sovereignty in safety-critical navigation firmware.
An autonomous navigation processing unit integrates sensor fusion algorithms, real-time kinematic positioning, and path-planning compute into a single embedded subsystem typically operating on sub-50-watt thermal envelopes with ASIL-D or equivalent functional safety ratings. Its primary purpose is to execute localization, mapping, and trajectory optimization decisions without human intervention across dynamic environments. Embedded Systems dominate current procurement volumes, though Software Solutions capture expanding margin pools as OEMs decouple hardware from over-the-air updatable perception stacks. Machine Learning and Sensor Fusion represent the fastest-growing technology pairing, while Lidar Integration remains concentrated in premium autonomous vehicle and urban drone programs where centimetric accuracy justifies sensor cost.
The U.S. FAA and NHTSA maintain divergent certification timelines for airborne versus ground autonomy, creating compliance complexity for vendors serving both domains. EASA in Europe and China's MIIT are converging on updated GB standards for functional safety documentation, reshaping market access requirements for non-domestic suppliers. Stakeholders must monitor how regulatory fragmentation between FAA airworthiness directives and NHTSA automated driving system guidance affects platform architecture choices and geographic deployment sequencing.
Market Dynamics
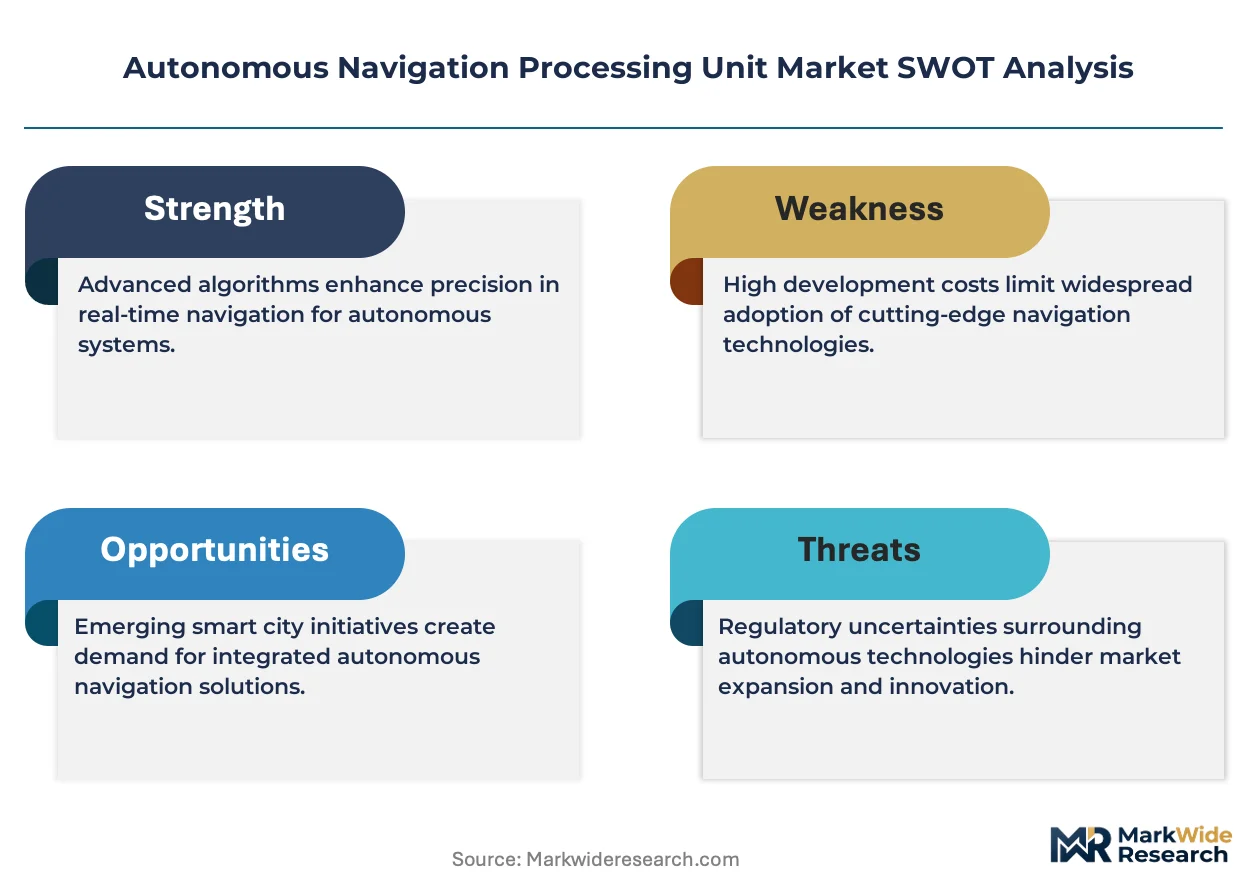
Automotive OEMs are decoupling hardware from perception stacks, forcing processor vendors to defend margin pools through software-defined differentiation rather than silicon integration alone.
Growth Catalysts
- EU AI Act compliance mandates:Functional safety documentation requirements for real-time path planning systems are accelerating hardware validation cycles among European automotive suppliers.
- Urban drone programs:Centimetric localization demands in last-mile aerial logistics are expanding procurement volumes for lidar-integrated navigation subsystems.
- Defense procurement programs:Dual-use radiation-hardened architectures are anchoring demand in Germany, the United States, and China through sovereign capability investments.
Market Restraints
- Automotive-grade silicon foundry concentration:Taiwan and South Korea facilities control advanced node access for ASIL-D rated processors, creating supply vulnerability.
- FAA-NHTSA certification divergence:Airworthiness directive timelines for airborne autonomy lag ground vehicle automated driving system guidance by 18-24 months, fragmenting platform architecture choices.
- Sensor fusion algorithm substitution:Open-source SLAM frameworks are compressing proprietary software margins for mid-tier navigation stack vendors.
Strategic Opportunities
- India's PLI scheme for automotive electronics:Module assembly incentives are attracting navigation processor packaging investments outside traditional East Asian hubs.
- Rail autonomy firmware:European maritime and freight rail operators are procuring safety-critical navigation stacks with sovereign data residency requirements.
- Edge AI and thermal envelope convergence:Sub-50-watt embedded subsystems combining machine learning inference with real-time kinematic positioning are opening industrial robotics applications.
Industry Challenges
- Functional safety engineer scarcity:ASIL-D certification expertise concentrates among semiconductor veterans from aerospace and automotive brake-system backgrounds, constraining vendor scaling.
- Over-the-air update liability:Decoupled perception stacks create ambiguous responsibility boundaries between hardware suppliers and software integrators during post-deployment failure events.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Autonomous Navigation Processing Unit Market |
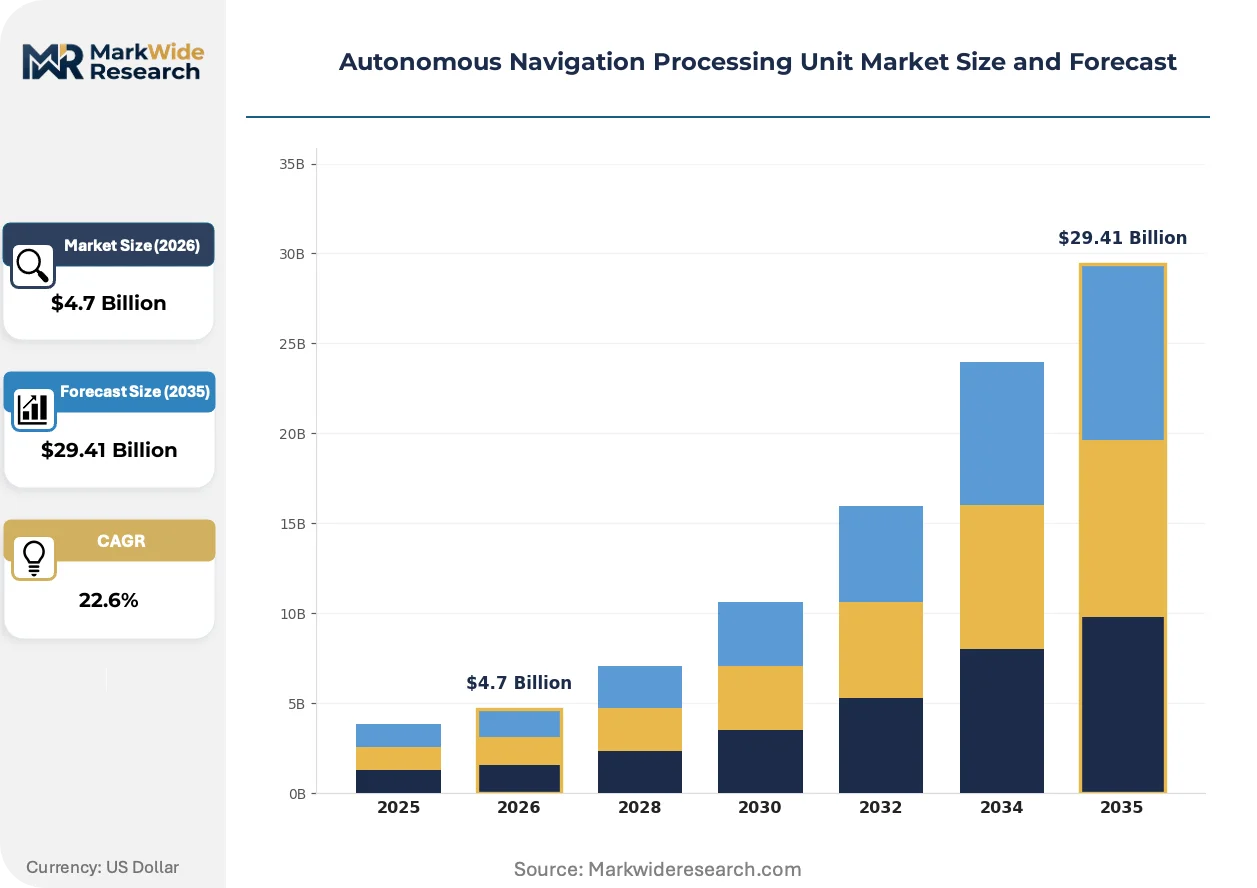
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $29.41 Billion |
| CAGR (2026 – 2036) | 22.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Embedded Systems, Software Solutions, Hardware Modules, Development Kits End User: Automotive OEMs, Robotics Manufacturers, Aerospace Companies, Research Institutions Technology: Machine Learning, Sensor Fusion, Computer Vision, Lidar Integration Application: Autonomous Vehicles, Drones, Industrial Automation, Maritime Navigation |
| Companies Covered | Moog Inc., Honeywell International Inc., Northrop Grumman Corporation, General Dynamics Corporation, Thales Group, L3Harris Technologies Inc., ABB, Raytheon Technologies Corporation, Safran, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Autonomous Navigation Processing Unit Market Emerging Trajectories
Neuromorphic compute architectures and spiking neural network implementations are compressing power-performance tradeoffs for edge-deployed navigation systems. Vendors are repositioning around algorithm-hardware co-design rather than discrete component supply.
Spiking neural network accelerators are executing sensor fusion at sub-10 millisecond latencies for dynamic obstacle avoidance. Automotive Tier-1s in Germany and Japan are qualifying these devices for Level 4 urban pilot programs. Discrete DSP-based signal processing chains are rendering obsolete as unified neuromorphic substrates absorb timing-critical perception workloads.
EASA and China's MIIT are converging on updated GB standards for functional safety documentation, creating partial regulatory alignment absent from FAA frameworks. Non-domestic suppliers must maintain parallel certification tracks for European and Chinese market access. Urban air mobility startups are prioritizing EASA certification paths to exploit this convergence.
Defense contractors and commercial aviation suppliers are consolidating procurement through dual-use qualification programs, collapsing traditional channel separation. Honeywell and Thales are restructuring sales organizations around integrated defense-civil account teams. This consolidation is most visible in Germany and France, where national sovereignty requirements favor vendors with established security clearance infrastructure.
Autonomous Navigation Processing Unit Market Segmentation
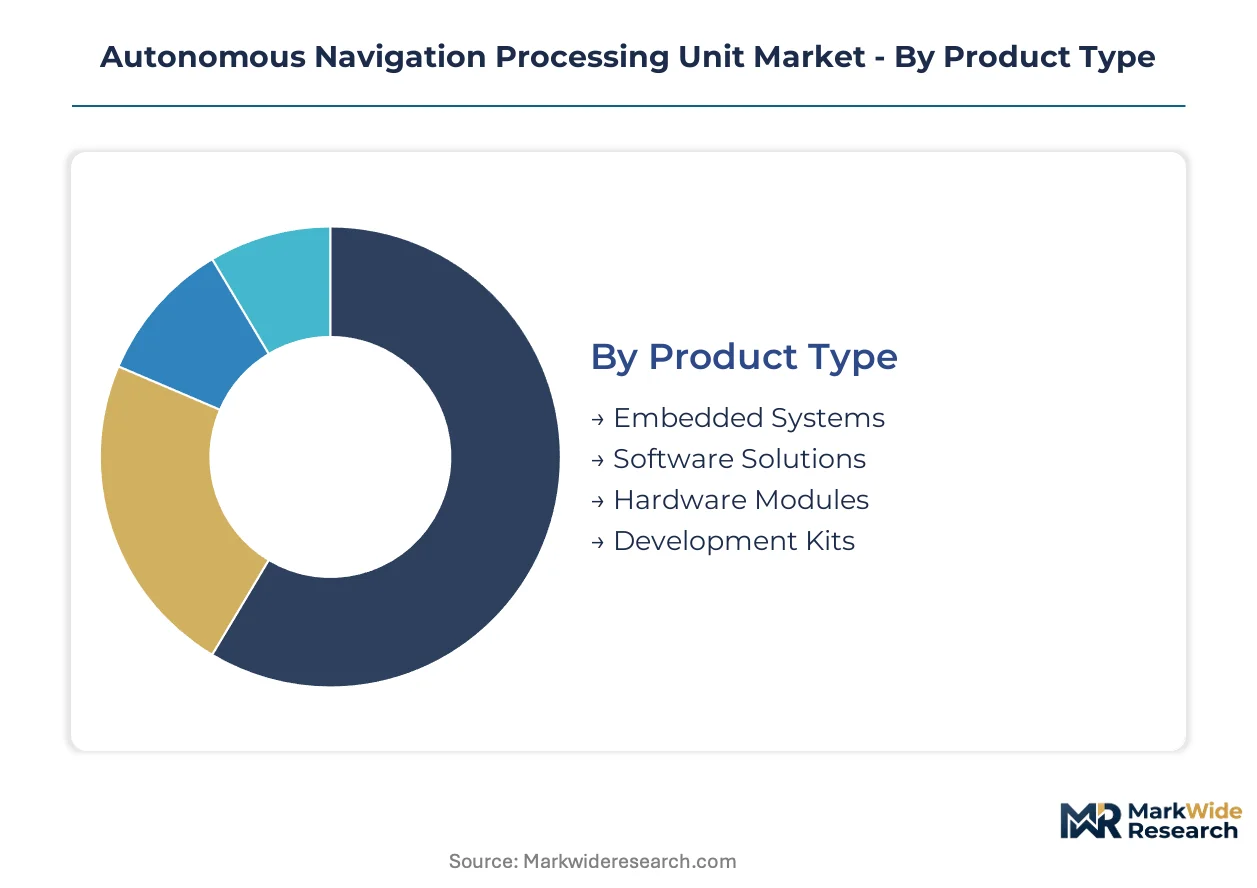
Autonomous navigation processing unit segmentation reveals how compute architectures fragment across thermal envelopes, safety certification tiers, and software-hardware decoupling strategies. Procurement patterns diverge sharply between automotive volume programs and aerospace qualification cycles.
Product Type:
Cost tier determines procurement channel access, with premium ASIL-D rated units commanding qualification timelines that exclude budget-constrained developers.
- Embedded Systems:These sub-50-watt subsystems integrate sensor fusion, real-time kinematic positioning, and path-planning compute into single ASIL-D rated packages. Automotive OEMs in Germany and the United States concentrate procurement here for Level 3 and Level 4 pilot programs, though Taiwan and South Korea foundry concentration creates supply vulnerability for advanced node access.
- Software Solutions:Decoupled perception stacks enable over-the-air updatable algorithms without hardware replacement. Expanding margin pools attract vendors defending position through software-defined differentiation rather than silicon integration alone, though liability boundaries between hardware suppliers and integrators remain ambiguous during post-deployment failures.
- Hardware Modules:Discrete processing boards for integration into larger avionics or industrial control systems.
- Development Kits:Prototyping platforms with reduced certification overhead for algorithm validation.
Embedded Systems holds installed capacity. Software Solutions is rotating up the share rankings.
End User:
Application maturity separates volume purchasers from qualification-heavy adopters with divergent procurement cycles.
- Automotive OEMs:Level 3 and Level 4 autonomy programs are expanding fastest among this category, with EU AI Act compliance mandates accelerating hardware validation cycles. Real-time path planning documentation requirements tighten functional safety protocols for European suppliers.
- Aerospace Companies:Radiation-hardened architectures anchor demand through sovereign capability investments in Germany, the United States, and China. FAA-NHTSA certification divergence creates compliance complexity for vendors serving both airborne and ground domains simultaneously.
- Robotics Manufacturers:Industrial automation integrators sourcing sub-50-watt edge AI subsystems.
- Research Institutions:Academic and government labs procuring development platforms for algorithm advancement.
Automotive OEMs capture procurement volume growth. Aerospace Companies maintains the steepest expansion trajectory for dual-use qualification programs.
Technology:
Compute paradigm shifts are compressing power-performance tradeoffs and displacing discrete signal processing chains.
- Machine Learning:Neuromorphic architectures and spiking neural network implementations execute sensor fusion at sub-10 millisecond latencies for dynamic obstacle avoidance. German and Japanese automotive Tier-1s are qualifying these devices for Level 4 urban pilot programs.
- Sensor Fusion:Unified timing-critical perception workloads are rendering discrete DSP-based signal processing chains obsolete. Open-source SLAM frameworks compress proprietary software margins for mid-tier navigation stack vendors.
- Computer Vision:Camera-centric localization for cost-constrained autonomy stacks.
- Lidar Integration:Centimetric accuracy demands in last-mile aerial logistics and premium autonomous vehicle programs justify sensor cost concentration.
Sensor Fusion dominates current deployment. Machine Learning is climbing the fastest in qualification pipelines.
Application:
Geography clusters around regulatory sandbox availability and defense procurement concentration.
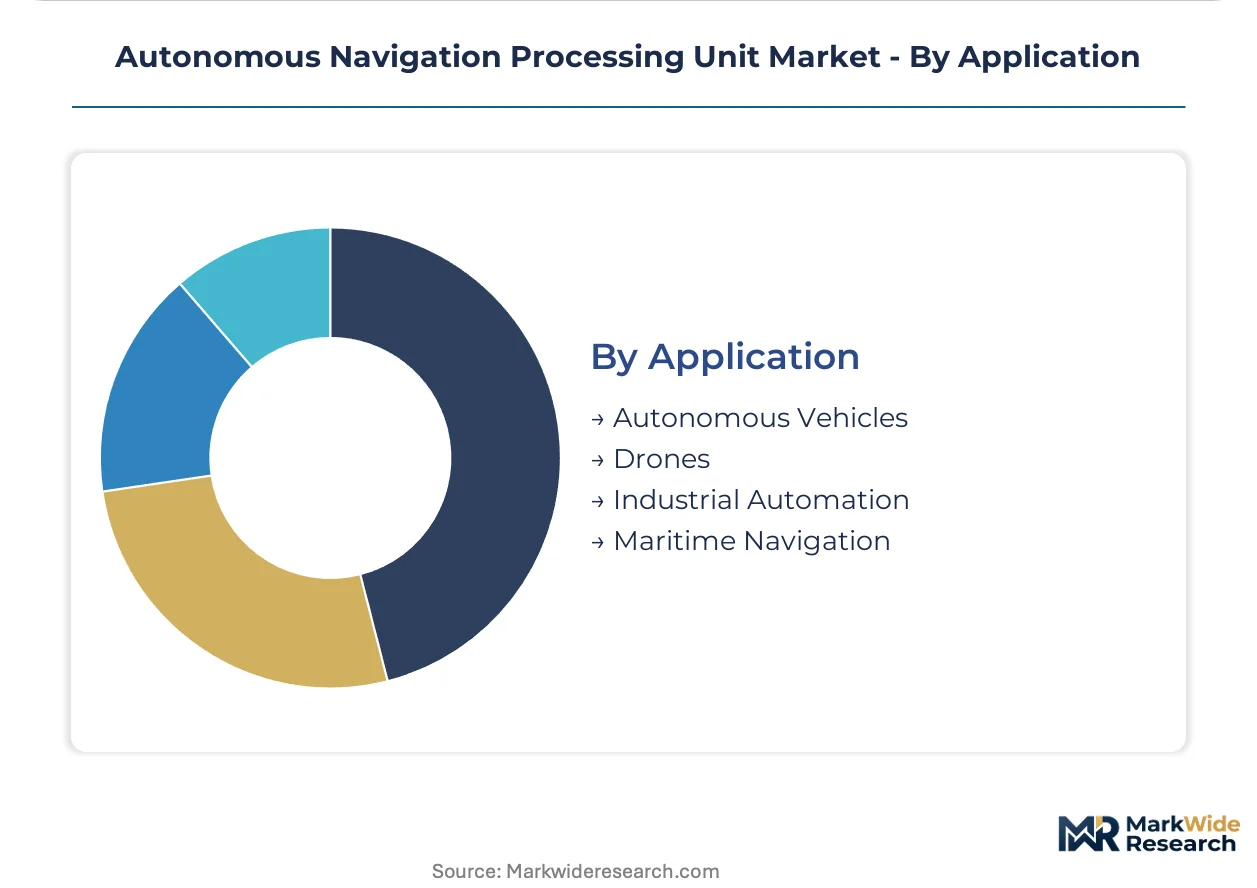
- Autonomous Vehicles:Ground-based mobility platforms face NHTSA automated driving system guidance timelines that lag airborne certification by 18-24 months, fragmenting platform architecture choices for dual-domain vendors.
- Drones:Urban air mobility programs prioritize EASA certification paths to exploit regulatory convergence with China's MIIT on updated GB standards for functional safety documentation.
- Industrial Automation:Edge AI and thermal envelope convergence opens robotics applications with real-time kinematic positioning requirements.
- Maritime Navigation:European maritime operators procure safety-critical navigation stacks with sovereign data residency requirements, sustaining regional firmware sovereignty.
Autonomous Vehicles anchors revenue scale. Drones is gaining share fastest in procurement volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
NHTSA automated driving system guidance anchors the United States as the dominant geography, while EASA and China's MIIT drive regulatory convergence across European and Asian qualification pathways. Geographic procurement clusters around defense procurement programs, automotive OEM pilot deployments, and sovereign capability investments.
United States
Defense procurement programs and FAA airworthiness directives anchor demand for radiation-hardened architectures. NHTSA testing protocols for automated driving systems create compliance complexity for dual-domain vendors serving both airborne and ground autonomy. The Southwest defense corridor concentrates dual-use qualification programs with established security clearance infrastructure.
Germany
Automotive OEM Level 3 and Level 4 pilot programs drive the fastest procurement volume expansion among European markets. EU AI Act compliance mandates accelerate hardware validation cycles for real-time path planning documentation. Bavaria and Baden-Württemberg host automotive Tier-1 qualification pipelines for neuromorphic compute architectures.
China
Domestic foundries and module assemblers scale capacity for automotive-grade navigation processors, fragmenting supply concentration. MIIT convergence with EASA on updated GB standards for functional safety documentation reshapes market access requirements. Yangtze River Delta clusters anchor sovereign capability investments in defense and commercial aviation channels.
Japan
Automotive Tier-1s qualify spiking neural network accelerators for Level 4 urban pilot programs, driving machine learning technology adoption. METI industrial policy supports edge AI and thermal envelope convergence for robotics applications. Kanto and Kansai industrial corridors concentrate precision motion control heritage and sensor fusion algorithm development.
India
PLI scheme incentives for automotive electronics attract navigation processor packaging investments outside traditional East Asian foundry hubs. Module assembly capacity expansion targets cost-tier procurement channels for industrial automation integrators. Gujarat and Maharashtra emerge as alternative packaging locations for sub-50-watt embedded subsystems.
Autonomous Navigation Processing Unit Market Vendor Landscape
Aerospace-grade specialists and automotive-scale fabricators split the market between qualification-heavy defense procurement and volume-driven OEM programs. Vendor positioning stratifies across three archetypes: radiation-hardened defense contractors, precision motion control heritage players, and software-defined differentiation challengers. Consolidation pressures intensify as dual-use qualification programs collapse traditional channel separation between civil and defense accounts. M&A activity and strategic partnerships dominate competitive moves as vendors seek integrated defense-civil account capabilities.
Within the aerospace-grade tier, Moog Inc., Honeywell International Inc., and Thales Group exemplify archetype positioning through established precision control and safety-critical firmware legacies. Moog occupies a heritage-anchored position in precision motion control systems. Honeywell sits within the dual-use qualification nexus spanning radiation-hardened architectures. Thales represents European sovereignty in maritime and rail autonomy stacks with security-cleared infrastructure. These three entities illustrate how vendor restructuring around integrated account teams responds to procurement consolidation in Germany and France.
| Leading Market Players |
|---|
| Moog Inc. |
| Honeywell International Inc. |
| Northrop Grumman Corporation |
| General Dynamics Corporation |
| Thales Group |
| L3Harris Technologies Inc. |
| ABB |
| Raytheon Technologies Corporation |
| Safran |
| Others |
Supply Flow & Price Mechanics
Yangtze River Delta foundry capacity expansion in automotive-grade navigation processors is compressing margins for mid-tier embedded systems while concentrating pricing power among ASIL-D certified suppliers. Taiwan and South Korea facilities control advanced node access, creating tiered cost structures that ripple through OEM procurement negotiations.
Pricing Analysis
Geographic price spreads between German automotive Tier-1 contracts and Indian module assembly channels exceed three-to-one for equivalent thermal envelope specifications. Three-tier pricing structure across premium ASIL-D, standard automotive-grade, and economy industrial-tier processors differentiates by certification level and volume scale. Pricing pressure stems from open-source SLAM framework substitution eroding proprietary software margins. Robotics manufacturers exhibit highest price sensitivity, while aerospace companies absorbing radiation-hardened architectures show lowest elasticity.
Supply Chain Analysis
Export-control regimes restricting advanced lithography equipment flows to Chinese domestic foundries are fragmenting supply concentration across Taiwan, South Korea, and emerging Indian packaging hubs. Silicon wafers, automotive-grade substrate materials, and neuromorphic accelerator IP cores constitute critical input dependencies. Single-source vulnerability concentrates in Taiwan's leading-edge node capacity for sub-50-watt embedded subsystems. Distribution runs through dual-use defense procurement channels and automotive Tier-1 direct contracts, with limited spot-market liquidity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The autonomous navigation processing unit market is recovering from qualification-cycle compression as Level 3 and Level 4 automotive pilot programs reaccelerate capital deployment. Defense procurement programs provide countercyclical demand anchoring during automotive OEM budget pauses.
For Market Incumbents: Build certification moats through accelerated ASIL-D and FAA airworthiness qualification pipelines before EU AI Act documentation mandates tighten. Consolidate software-defined differentiation through algorithm-hardware co-design investments that compress spiking neural network latency benchmarks. Open-source SLAM commoditization threatens mid-tier navigation stack margins; anchor defense-civil account teams in Germany and France where sovereign capability investments favor security-cleared vendors. Priority rests on neuromorphic compute architecture R&D partnerships with Japanese automotive Tier-1s. For New Entrants and Emerging Players: Build out India's PLI scheme module assembly capacity as an alternative packaging location outside Taiwan-South Korea concentration. Rail autonomy firmware in Europe offers most penetrable white-space, with maritime navigation stacks following close behind. Target industrial robotics integrators seeking sub-50-watt edge AI subsystems with real-time kinematic positioning. Go-to-market leverage centers on thermal envelope convergence demonstrations for machine learning inference workloads. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors dual-use qualification specialists with established security clearance infrastructure and radiation-hardened architecture heritage. Long-term viability across the projection horizon hinges on regulatory convergence exploitation between EASA and China's MIIT on functional safety documentation standards. Acquisition target archetype: precision motion control heritage players with aerospace-grade firmware legacies lacking automotive-scale volume channels. Signal to watch: FAA-NHTSA certification timeline divergence compression indicating dual-domain vendor consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Algorithm-Hardware Co-Design Investment | Neuromorphic substrate integration compresses power-performance tradeoffs for German Tier-1 qualification pipelines. |
| Dual-Use Qualification Program Expansion | Defense-civil account consolidation collapses traditional channel separation in France and Germany procurement. |
| India PLI Scheme Module Assembly Entry | Packaging capacity diversification reduces Taiwan foundry concentration vulnerability for automotive-grade processors. |
| EASA-MIIT Regulatory Convergence Exploitation | Updated GB standards alignment opens parallel certification tracks for European and Chinese market access. |
| Open-Source SLAM Framework Neutralization | Proprietary sensor fusion differentiation defends margin pools against algorithm substitution pressure. |
Methodological Framework
Cross-validation between primary interviews with automotive platform engineers, defense procurement officers, semiconductor foundry planning leads, and avionics certification specialists anchors the qualitative findings. Secondary validation draws from FAA airworthiness directive filings, NHTSA automated driving system guidance documents, EASA certification databases, and MIIT GB standards updates. Bottom-up triangulation across embedded systems procurement volumes and top-down macroeconomic scenario modeling ensures segmentation integrity.
Calibration against historical qualification cycle timelines and automotive OEM pilot program announcement patterns shapes the analytical framework. Segmentation dimensions span product type, end user archetype, compute paradigm, and application domain with regional regulatory cluster overlays. CAGRs derive from installed capacity buildout trajectories and technology substitution elasticity estimates. Neuromorphic accelerator adoption curves and thermal envelope convergence thresholds constitute industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion moves by Chinese domestic foundries or accelerated FAA-NHTSA harmonization would shift outcomes. Material shifts in EU AI Act enforcement stringency or Taiwan semiconductor export control escalations would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Navigation & Surveillance
Anti-Jamming Market
Communication Navigation & Surveillance
Inertial Systems Market
Communication Navigation & Surveillance
Spain Satellite Communications Market
Communication Navigation & Surveillance
Surface Radars Market
Communication Navigation & Surveillance
EMEA Mission Critical Wireless Communications Market
Communication Navigation & Surveillance
Tactical Radio Market
Communication Navigation & Surveillance
Weapon Locating Radar Market
Communication Navigation & Surveillance
GNSS Smart Antenna Market
Communication Navigation & Surveillance
Global Military Communications Market
Communication Navigation & Surveillance
Asia-Pacific Inertial Systems Market
Communication Navigation & Surveillance
Advanced Antenna System Market
Communication Navigation & Surveillance
Through the Wall Radar Market
Communication Navigation & Surveillance
Autonomous Navigation System Market
Communication Navigation & Surveillance
Naval Tactical Communication Market
Communication Navigation & Surveillance
Integrated 3D Radar Market
Communication Navigation & Surveillance
3D Radar Market